Tag: uncategorized

  • Making use of 12 months organization bank statements to qualify for a home finance loan

    12-thirty day interval firm monetary establishment assertion monetary loans” generally refer to a kind of bank loan system wherever a borrower’s earnings is recognized centered on their enterprise bank statements alternatively than standard earnings documentation this kind of as tax returns or pay out stubs. This selection of private loan is normally categorized as a Non-Capable Mortgage (Non-QM) primarily as a result of it will not meet up with the requirements set by the Certified Mortgage (QM) rule.

    In these varieties of loans, lenders might glimpse on the firm lender statements for the sooner 12 months to assess the borrower’s money stream and functionality to repay the monetary loan. This might be helpful for self-employed people or enterprise entrepreneurs who might effectively have fluctuating cash or non-common money stream sources.

    Hold in mind that non-QM loans sometimes include greater need premiums and will effectively have completely different qualifying circumstances in contrast to conventional home loans. Additionally, loan firms providing these types of loans might probably have distinct specs and underwriting ideas, so it’s actually important to very fastidiously evaluation the circumstances and problems.

    If you’re considering of a 12-month firm monetary establishment assertion mortgage, it truly is advisable to search the recommendation of with a home loan expert or a monetary loan officer who focuses on non-QM loans. They can provide thorough information in regards to the monetary loan packages supplied to you, handbook you as a end result of the software program course of, and assist you notice the circumstances and conditions affiliated with these sorts of loans.


    tune in and perceive further at https://www.ddamortgage.com/website online

    Didier (*12*) nmls212566

    DDa Mortgage loan nmls324329

    Inquire a Mortgage Question

    Use the shape beneath and we are going to give your our specialist solutions!

    Start off Your Bank loan

    with DDA immediately

    Your regional Property finance loan Broker

    Home finance loan Broker Largo

    See our Critiques

    Searching for way more info? Pay consideration to our extended podcast! 

  • March listings drop put up-February boom

    March listings drop article-February boom | Australian Broker News

    Information

    March listings slide post-February development

    Actual property train slows, Easter impacts sample

    March listings fall post-February boom

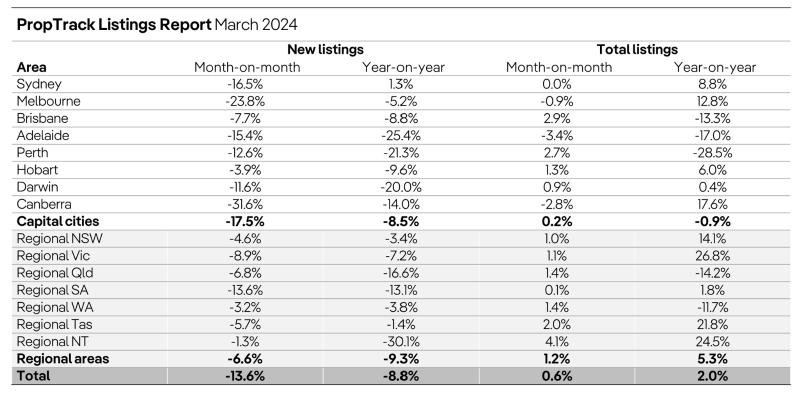
    Authentic property markets seasoned a slowdown in March, with new listings on realestate.com.au dropping drastically proper after a bustling February, based on PropTrack.

    New listings fell by 13.6% greater than the month and have been 8.8% lowered versus the equivalent interval remaining 12 months.

    Effects of Easter timing

    The early prevalence of the Easter trip this calendar 12 months noticeably motivated the March market dynamics.

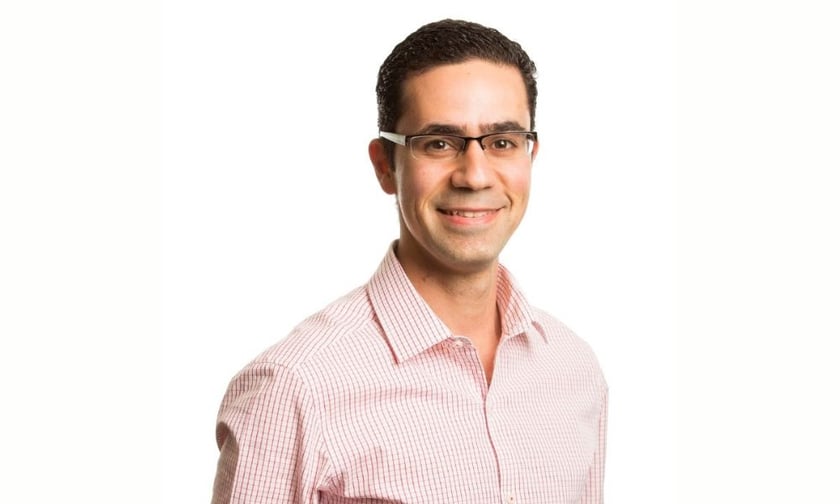
    “Following the busiest start to the yr in above a decade, new for-sale listings fell in March as an early Easter launched ahead the slowdown in providing motion sometimes witnessed in April,” acknowledged Anne Flaherty (pictured above), PropTrack economist.

    New listings fall in most cities

    When all important metropolitan areas other than Sydney noticed declines in new listings, the blended funds cities reported an 8.5% 12 months-on-yr scale back. Regional components additionally seasoned a slowdown, reliable throughout every the month and calendar 12 months.

    Irrespective of the drop in new listings, the entire variety of listings was 2% larger compared to final calendar 12 months, owing to the substantial vary of properties listed in late February. Cities like Canberra, Melbourne, and Sydney noticed an maximize in options for shoppers, contrasting with sharper rises in whole listings in regional Victoria, NT, and Tasmania.

    Solid purchaser want persists

    “Despite fewer qualities changing into dropped at present market in March compared to 12 months up to now, complete listings remained up yr-on-yr as a consequence of the surge in listings witnessed in February,” Flaherty claimed.

    Get the most effective and freshest mortgage mortgage info despatched right into your inbox. Subscribe now to our FREE on daily basis publication.

    Hold up with essentially the most present information and occasions

    Be part of our mailing file, it’s no value!

  • Significantly professional urges consideration of the dwelling when scheduling for retirement

    When creating retirement plans, individuals usually have a look at their investments and different fiscal belongings when pinpointing the long run class to get, however they not usually take note of what’s regularly their most necessary asset: their property.

    This is in accordance to Steve Resch, vp of retirement approaches at Finance of The us Reverse (Significantly), in a new column revealed by The Avenue.

    “[C]omparing the possible for return on funding choice (ROI) on residence possession to a extremely comparable and perfectly-recognized monetary dedication automobile or truck, the 401(ok), illuminates the so much less-explored monetary dedication seemingly inherent in a home purchase,” Resch reported.

    While prices related to homeownership are likely to dwarf expenditures which might be usually related with different kinds of investments, the requirement for getting a roof multiple’s head additionally will make the home a much more priceless asset that must be managed, Resch described. This calls for the separation of the dwelling’s profit from its worth, and managing it as the two “an monetary dedication asset as correctly as a important expenditure could make notion,” he talked about.

    Steve Resch

    There are additionally some noteworthy similarities between the home as an asset and a 401(ok) retirement account, he spelled out. Both belongings “are lengthy-time interval investments,” and regardless that “an distinctive would possibly carry out for a number of firms or buy a quantity of households throughout their lifetimes, they may potential pay into every particular person expense for 30 yrs or way more.”

    They additionally each of these have “systematic contribution choices,” along with payroll deductions for a 401(ok) account and month to month dwelling finance mortgage funds for a home.

    Financial advisers can be wise to take a look at these similarities, and “holding a property to the very same efficiency requirements usually utilized to a 401k can assist illuminate why a family as an monetary funding not solely will make notion, however supplies an probability that will be silly for any economical advisor to neglect,” Resch talked about.

    Homes and 401(ok) accounts alike additionally give their very personal tax rewards, and although a 401(ok) is designed to function an instrument to make {dollars} motion, property equity may additionally serve these varieties of a objective if an certified home proprietor considered as a reverse mortgage mortgage, he spelled out.

    “The commonplace protocol for accessing fairness has been to advertise the home,” Resch claimed. “However, when promoting a home does current get hold of to {dollars}, it additionally may exact a number of tolls on the vendor, which incorporates the expenditures and psychological results of the sale and going.”

    Resch has spelled out in the earlier why reverse mortgages could be employed as retirement getting ready gear.


  • WA paying out falls as costs rise

    WA paying falls as bills rise | Australian Broker Information

    Information

    WA paying out falls as costs rise

    West Aussies cut back again as residing expenditures soar

    WA spending falls as costs rise

    Bankwest’s most up-to-date Devote Trends analysis disclosed a stark decline in spending amongst Western Australians owing to rising price-of-dwelling pressures.

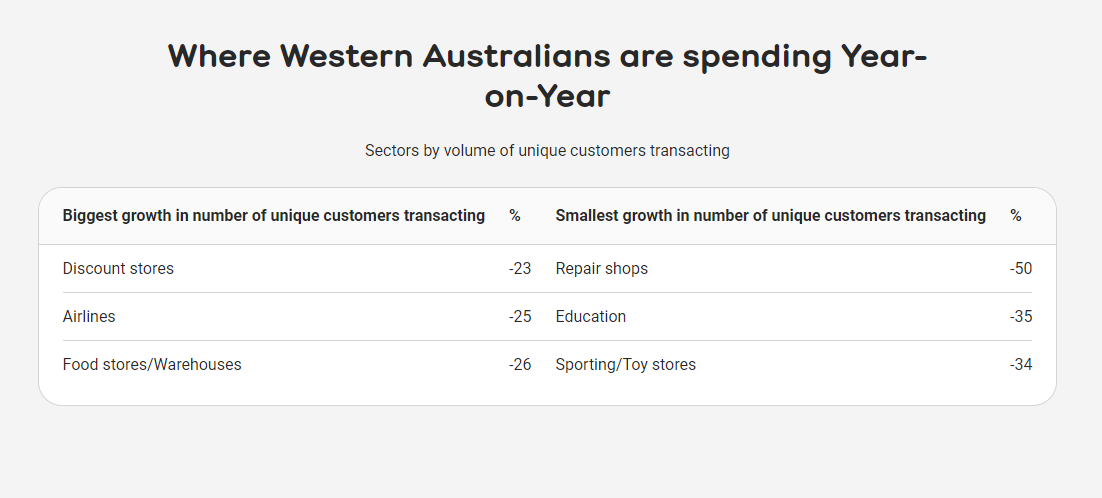
    Info from March 2024 confirmed a spectacular yr-on-12 months drop, with shelling out train noticeably decrease when in comparison with the similar thirty day interval in 2023.

    The Bankwest evaluation, which tracked 25 industries – all of which seen double-digit declines – confirmed that mend shops, schooling sectors, and sporting/toy retailers witnessed the steepest drops, down 50%, 35%, and 34% respectively in purchaser figures.

    “Such a big drop yr-on-year signifies that Western Australians have become very selective with the place by and the way they shell out their cash,” Peter Bouhlas (pictured increased than), Bankwest widespread supervisor merchandise and digital skilled companies, defined in a media launch.

    Stable costs, decreased transaction quantity

    Despite the drop within the choice of transactions, the everyday worth of transactions in March 2024 remained pretty safe compared to March, suggesting that value ranges for items and skilled companies haven’t considerably altered.

    Restoration alerts in month to month data

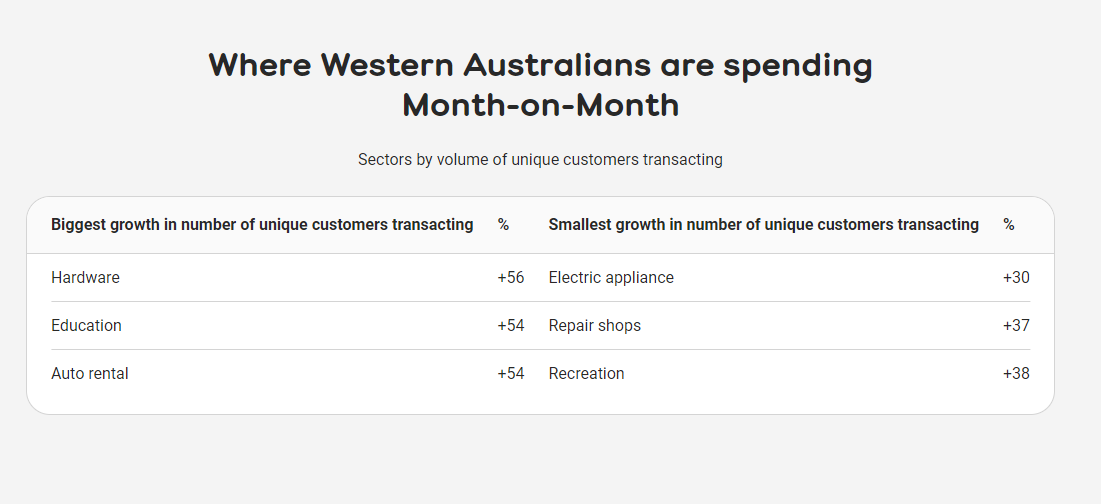
    Having mentioned that, the thirty day period-on-thirty day interval knowledge from February to March tells a much more optimistic story, with a forty five% surge in shopper transactions.

    Sectors these sorts of as parts, coaching, and vehicle rental led the rebound, displaying boosts of 56%, 54%, and 54% respectively. This uptick may replicate a rising financial self-confidence as folks regulate to financial pressures.

    Bouhlas emphasised the twin mom nature of the present monetary panorama.

    “We can see from the will increase from February to March this calendar yr that Western Australians are nonetheless desperate to spend, and the growth may present a rise in monetary self-assurance as they adapt to the illnesses,” he said.

    Bankwest’s dedication to steering prospects

    Bouhlas additionally reassured patrons coping with cash points, encouraging them to achieve out for support:

    “Bankwest is totally commited to turning into there for its prospects, and I urge any individual who’s going by way of – or is concerned they may confront – economical problems to make contact with us so we are able to steering their particular scenario,” Bouhlas said.

    Get the perfect and freshest property finance mortgage data delivered supreme into your inbox. Subscribe now to our FREE each day e-newsletter.

    Preserve up with the most well liked data and occasions

    Sign up for our mailing itemizing, it’s free!

  • applying rental revenue to qualify for an expense house

    Gen X is presently in search of for housing appropriate for rising older in spot

    By Didier Malagies
    •
    10 Apr, 2024

    Little one boomers are exhibiting an an excessive amount of to deal with need to age in space in their very own residences, however their children — primarily customers of Technology X — are additionally incomes their desires felt by looking for out residences that may accommodate their wants as they get extra mature, in accordance to a present report from the New York Periods. Citing 2021 details from the Harvard College Joint Heart for Housing Research that confirmed 88% of grown ups 65 and extra mature are ageing in put, many customers of the subsequent technology — largely born among the many mid-Sixties and early-Eighties — are by now taking proactive strategies to by contemplating “about precisely the place they’ll stay of their 70s, 80s and even 90s,” the Occasions reported. Homebuilders are observing a improve in demand for homes that may accommodate regular ageing from Gen X potential patrons. David O’Reilly, CEO of Howard Hughes Holdings which constructs deliberate communities, describes the sector being “on the cusp,” stating that the necessity appears to be coinciding with much more clients of Gen X nearing a time precisely the place they’ll come to be “empty nesters.” “That’s often the tipping concern,” O’Reilly informed the Times. Gen X patrons are additionally way more possible to have extra financial signifies and handle about their alternative options, and are preserving entry to important later-existence services in head when selecting precisely the place to dwell as they grow old, the story outlined. “In new developments, [Gen X buyers] try to get entry to well being and health and wellness services, like mountaineering trails and tennis courts, as correctly as opting for house capabilities like showers as an various of bathtubs, for occasion, and asking for probably the most up-to-date gizmos to assist them as they age,” the reporting reported. A report unveiled final 7 days by the Countrywide Association of Realtors (NAR) talked about that Gen X homebuyers have a median cash of $126,900, and are even now a few years away from retirement. That extra working time will allow them to to amass additional extra wealth in accordance to Jessica Lautz, deputy important economist and vp of study at NAR. Customers of Gen X are additionally benefiting from the pandemic and submit-pandemic operate-up in house prices, carrying considerably extra house equity than their millennial counterparts and dwarfing millennial homeownership charges 72% to 55% as of 2023. 1 analyst defined that Gen X patrons are impressed to act now for rising older-suitable housing thanks to the purpose out of the housing business.  “If they’re buying for properties, given the tightness of the sector and distant do the job, I do imagine that you simply see further Gen X-ers a residence order as a house for the remainder of their life,” defined Cristian deRitis, deputy chief economist at Moody’s Analytics to the Moments.

  • A Path to Economical Home Possession

    Tiny Residences are fast turning out to be a popular choice for all these looking for alternative housing choices in in the present day’s demanding housing business. These compact properties provide a minimalist way of life and financial independence, making them a pretty decision for these looking out to downsize and private their very personal home with out the duty of a normal residence finance mortgage. If you’re making an allowance for a Little Home as your following home, here is each factor you will have to learn about financing a really small residence in Australia.

    2-Apr-17-2024-12-17-51-8578-AM

    What is a Tiny Dwelling?

    Very small Homes are compact households that prioritise the productive use of modern storage strategies and room-preserving designs, all in a bit of footprint. Ranging from as compact as a motorcar parking room to the dimension of a semi-trailer or transport container, Very small Houses present a simplified way of life, emphasising glorious greater than amount and sustainability greater than additional. Ordinarily constructed on trailers to bypass minimal housing measurement laws, Very small Properties are glorious for folks looking out for simplicity and affordability, with out compromising on consolation and luxury.

    How significantly does a Little Household Price?

    The worth of a Little Household can fluctuate depending on variables all these as dimension, constructing approach, and customisation alternatives. Generally, you’ll be able to assume to fork out regarding $50,000 and $160,000 for a Little Dwelling in Australia, with added charges for updates and ongoing prices corresponding to registration and land rental. Looking into distinct companies and variations will allow you totally grasp the total price and resolve on the best resolution in your price range.

    How do I Purchase a Small Dwelling?

    The system of getting a Very small Property will not be that numerous to purchasing for the standard family, in that you could both purchase an present Tiny Household or shell out to have one explicit crafted. If you select for the latter, you’ll be able to decide to use an present construction or work with an architect or Small Household agency to make a tailor made model and design.

    Some Very small Residence companies give standardised layouts, providing fairly a couple of design prospects to choose from. This may be useful in case you may be not assured about your tastes, because it offers a center ground involving a completely customised model and a elementary pre-designed chance.

    Can I Finance a Small Home?

    Even although conventional home monetary loans could properly not be available for Very small Homes, that are categorized as caravans, there are possibility financing choices to consider:

    Expert financing: Some Small House corporations provide in-dwelling funding options with workable deposit wants and aggressive curiosity expenses.
    Unsecured private monetary mortgage: A financial institution mortgage that won’t want any collateral, corresponding to a dwelling or auto, to protected the mortgage however is primarily based fully on the borrower’s creditworthiness, earnings, and monetary file. Commonly these monetary loans have larger want prices in distinction to secured loans however supply much more versatility in how the funds may be utilized.
    Accessibility fairness: If you very personal land or an present home, you could maybe be prepared to leverage the equity to finance your Small House by refinancing and rising your present private mortgage.
    Chattel property finance mortgage: A finance association that delivers funds with aggressive fascination expenses to get hold of an asset – these as a Small House on wheels – precisely the place the financed asset capabilities as stability for the mortgage.

    Although a Home mortgage Express dealer can get the job achieved with you to get hold of funding solutions for Tiny Houses, the popular alternative is a ‘money out’ on an present residence.

    Embracing Cost-effective Property Ownership

    Regardless of the complexities of funding, Small Homes provide a sensible route to cheap family possession in Australia. Little Homes may additionally be appropriate for retirees wanting to downsize their present property with out forsaking benefit and luxury.

    By diligently investigating and buying certified help, it’s doable to effectively navigate the funding methodology for Tiny Properties. Consult with with a Home finance mortgage Specific residence finance mortgage dealer proper now and get personalised help and support with financing for Small Properties.

    While all care has been taken within the getting ready of this publication, no assure is offered as to the precision of the information and no obligation is taken by Finservice Pty Ltd (Home mortgage Express) for any issues or omissions. This publication doesn’t represent personalised economical ideas. It won’t be relevant to private circumstances. Practically nothing on this publication is, or actually must be taken as, an current, invitation, or suggestion to buy, market, or retain any funding determination in or make any deposit with any particular person. You should search out specialist help upfront of taking any motion in relation to the issues dealt in simply this publication. A Disclosure Statement is on the market on ask for and cost-free of demand.

    Finservice Pty Ltd (Home finance mortgage Express) is authorised as a company credit score rating agent (Company Credit score Representative Selection 397386) to work together in credit score rating pursuits on behalf of BLSSA Pty Ltd (Australian Credit Licence vary 391237) ACN 123 600 000 | Total member of MFAA | Member of Australian Monetary Issues Authority (AFCA) | Member of Decision Aggregation Companies.

  • Former director fined, disqualified for sector misconduct

    Previous director fined, disqualified for present market misconduct | Australian Broker Information

    Information

    Former director fined, disqualified for market misconduct

    Penalties issued for market place rigging and breaches

    Former director fined, disqualified for market misconduct

    The Federal Courtroom has despatched a judgment in opposition to Adam Blumenthal, former director of EverBlu Capital and Creso Pharma (now Melodiol International Wellness), mandating him to pay $850,000 in penalties and disqualifying him from controlling organizations for 5 a number of years, ASIC claimed.

    The choice follows conclusions that Blumenthal engaged in market place rigging and unsuccessful to meet his directorial obligations, impacting the integrity of financial markets.

    Blumenthal’s market rigging and directorial breaches

    On April 17, the courtroom uncovered that Blumenthal manipulated the present market by partaking in business rigging on 14 occasions, particularly regarding transactions for EverBlu shoppers much like the acquiring of shares in ASX-mentioned Creso.

    He additionally breached his duties by inadequately operating conflicts of need and failing in owing diligence, which led to vital unwarranted monetary transactions.

    Judicial remarks on Blumenthal’s actions

    Justice Angus Morkel Stewart criticised Blumenthal’s steps.

    “The contraventions are interrelated,” Stewart stated. “They every particular person skilled their useful resource in Mr Blumenthal’s big shareholding in Creso, his placement because the chairman of a economical services and products licensee with a possible to make use of investing strategies, and his intention of presenting a phony or deceptive image to the present market for Creso shares.”

    The resolve pressured that these actions undermined important fiscal program obligations and neighborhood self-confidence.

    ASIC’s stance on present market integrity and director perform

    ASIC chair Joe Longo (pictured greater than) commented on the ruling, stressing the importance of defending sector integrity and directorial accountability.

    “Promoting present market integrity and addressing director misconduct are enduring priorities for ASIC,” Longo claimed in a media launch.

    “Market rigging is severe misconduct that impacts the integrity of Australia’s fiscal marketplaces and helps forestall these markets from operating moderately and transparently.”

    Longo acknowledged that the penalties should forestall comparable misconduct and remind administrators of their vital duties.

    Get one of the best and freshest house finance mortgage info shipped appropriate into your inbox. Subscribe now to our FREE day-to-day e-newsletter.

    Preserve up with the most popular information and features

    Join our mailing guidelines, it’s completely free!

  • CFPB makes structural changes whilst expanding authority around nonbanks

    CFPB logo The Purchaser Monetary Safety Bureau introduced Wednesday that it was eradicating its Office setting of Supervision, Enforcement and Honest Lending, splitting that workplace’s duties amongst present places of work.

    Bloomberg News

    Client Financial Defense Bureau Director Rohit Chopra introduced that its supervision and enforcement locations of labor will operate as totally different, stand-by your self divisions within the bureau.

    Chopra instructed the CFPB’s personnel in February that he skilled dissolved the Business workplace of Supervision, Enforcement and Good Lending and likewise had eradicated the affiliate director place that had been held by former appearing CFPB Director Dave Uejio. The shift was designed normal public Tuesday as aspect of a procedural rule change through which the CFPB updated how the company designates nonbanks for supervision. 

    The upshot of the changes is that Enforcement Director Eric Halperin and Supervision Director Lorelei Salas now report proper to Chopra with out the layer of an additional senior official in-involving. 

    “We can be transitioning the executive composition of [the Office of Supervision, Enforcement and Fair Lending] into two particular person functioning fashions,” Chopra wrote in an e mail to workers. He launched in February that Uejio skilled acknowledged a job on the Federal Housing Finance Agency and that his placement as affiliate director can be eliminated. 

    “A flatter group composition will make it doable for us to be extra agile in our response to rising pitfalls and can facilitate faster selection-earning,” Chopra wrote within the e-mail. “In the early days of the CFPB, there was concern that Supervision and Enforcement essential to be in a single division so as to foster robust collaboration and coordination on deploying our functions.”

    As side of the enhancements, a 50 %-dozen workers had been reassigned to different positions.   

    David Bleicken, the CFPB’s deputy affiliate director of the now-defunct Office of Supervision, Enforcement and Truthful Lending, stays in a senior job on the bureau. Previously, the CFPB’s truthful lending enterprise workplace was stripped of its enforcement powers in 2018 beneath earlier CFPB Director Mick Mulvaney, and that gadget, the Office of Truthful Lending and Equal Possibility, has been underneath the CFPB director’s purview at any time as a result of. 

    The CFPB has not up to date its group chart provided that January. Salas is nonetheless talked about as performing assistant director of the Workplace of Supervision Exams and assistant director of the Office of Supervision Plan. She is now director of supervision, a spokesman claimed.

    The enterprise enhancements may have an outsize impact on nonbanks which might be chosen as harmful and, consequently, material to supervision. 

    Since of the elimination of the affiliate director job, the CFPB constructed changes to copy that the brand new supervision director is now the “initiating official” in supervisory designation proceedings, as successfully as in so-called contested proceedings. The replace was vital to switch the previous affiliate director’s supervision-linked options to the supervision director.

    Some specialists who follow the CFPB intently said the online affect of the switch is that Chopra eradicated a vocation civil supplier process, concentrating extra authority within the director’s workplace. 

    Even extra, nonetheless CFPB supervisory exams are non-public, the CFPB in February publicly produced the to start out with resolution in a contested continuing versus Earth Acceptance Corp., a major installment lender that the bureau stated poses a hazard to consumers. It marked the preliminary time that the CFPB publicly disclosed its outcomes to oversee a nonbank quickly after a contested administrative continuing. 

    The dedication of supervising a nonbank now will be constructed by the director of supervision in a recommendation to the CFPB director with no an extra senior formal weighing in.  

    The bureau initiated its very first spherical of supervisory designation proceedings earlier yr proper after asserting in 2022 that it will actively use a dormant authority to oversee nonbanks that aren’t in the meanwhile material to supervisory exams. The CFPB defined that entities can probably consent to supervision or contest a see. 

  • Residence selling prices dip every year but soaring progressively: ONS – Mortgage loan Approach

    The common property worth within the United kingdom fell by .2% within the 12 months to February this year, the newest ONS Residence Rate Index reveals.

    The drop was considerably after all than the 12 months prior, when dwelling prices dipped by 1.3%.

    Despite the yearly drop, costs rose .4% from January with the standard British isles property now offering for £281,000.

    In England, prices fell within the 12 months to February by 1.1% to a median of £298,000 and likewise dropped in Wales, down 1.2% to £211,000. Nevertheless, they rose considerably in Scotland, up 5.6% to a median £188,000 within the 12 months to February, the ONS says.

    MT Finance director of home Tomer Aboody suggests: “With selling prices rising month-on-month, we’re trying on the energy in need and assurance inside simply patrons who’re having advantage of steading fascination charges and cut back inflation.

    “However, with earnings volumes noticeably lower than final yr, larger demand from clients vs . decreased provide will normally press prices up.

    “Sellers need to need to be impressed to go in get to boost availability of stock out there place, and a few movement in stamp obligation costs would help.”

    Atom Lender head of mortgages Richard Harrison claims: “The decrease in home selling prices famous at the moment proceeds the craze of successive drops on condition that the center of final year, but even with this there are indicators of rising self esteem ranges among the many potential patrons.

    “We have presently discovered improved ranges of exercise in the home present market of late following a time interval of relative stability.

    “Data from Rightmove for illustration uncovered that the number of product sales in March was up by 13% on a calendar year in the past, whereas there was an 8% enlargement in buyer need as purchasers thrust upfront with strikes they might have place on hold on the shut of 2023, while dwelling charge indices from Nationwide and Halifax have demonstrated prices on the rise.”