Tag: uncategorized

  • Aussies flock to shared housing as rents soar

    Aussies flock to shared housing as rents soar | Australian Broker Information

    Information

    Aussies flock to shared housing as rents soar

    Hire rises power 2.5 million Aussies to cohabit
    Aussies flock to shared housing as rents soar

    In response to the escalating value of residing, shared housing has emerged as a important answer for fairly a couple of Australians, in accordance to a research by a comparability internet web page.

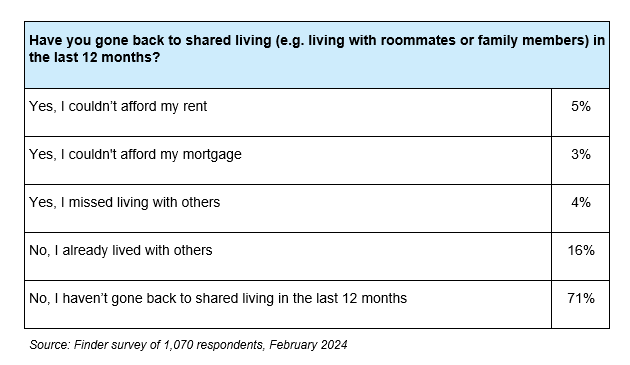
    A Finder research uncovered that round 12% of the populace, or 2.5 million individuals, have moved into shared housing in extra of the earlier calendar yr to mitigate cash pressures.

    Pushed by rising hire prices

    The Finder survey uncovered that hovering rental charges are the principle driver for this shift, with an approximated 1 million Australians returning to shared dwelling preparations notably due to to affordability troubles.

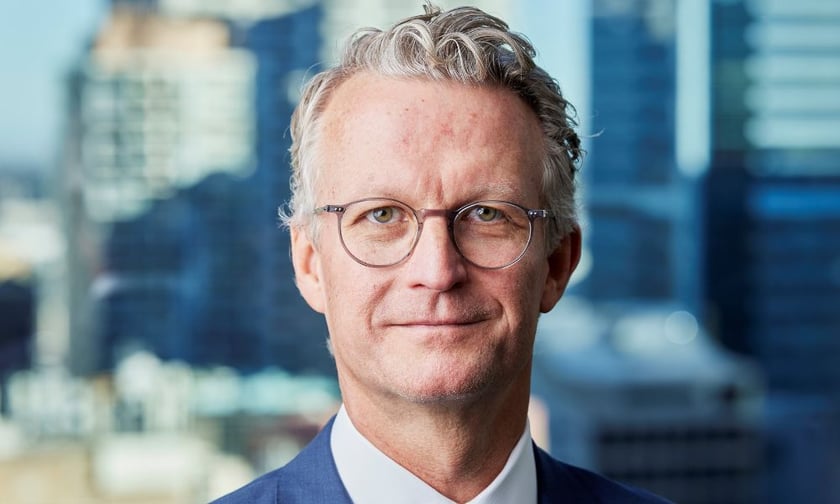
    “Rents and residential loans have lengthy passed by the roof – they’re the amount-a particular person useful resource of economic stress in Australia and women and men can no prolonged slice expenditures somewhere else to get by,” defined Graham Cooke (pictured larger than), head of purchaser exploration at Finder.

    Economic features of shared residing

    The research additionally revealed that by choosing shared housing, individuals might protect considerably. Finder’s evaluation really useful that residing in a family property rent-cost-free might assist save an common Australian $16,000 yearly, assuming a hire saving of $300.50 per 7 days.

    “Reducing or eradicating lodging bills – if you’re in a scenario to accomplish that – will appreciably improve your funds motion and you’ll accrue monetary financial savings much more shortly,” Cooke acknowledged.

    Recommendations for minimizing rental charges

    For folks not in a position to return once more with relations, different methods can assist aid you save on rent:

    &#13
    Roommates: Sharing a spot can drastically reduce residing payments.&#13
    Negotiation: Extended-time interval, reliable tenants might negotiate reduce hire.&#13
    Discovering distinctive areas: Some neighborhoods give reduce rents with out the necessity of compromising on safety and ease.&#13
    Downsizing: Opting for extra compact residing areas may also be further fairly priced.&#13

    Cooke emphasised the importance of redirecting any value financial savings to making a monetary buffer.

    “The faster you may develop your cash buffer, the extra resilient you can be to monetary headwinds,” he claimed.
    Get the most well-liked and freshest home mortgage info shipped correct into your inbox. Subscribe now to our FREE every day publication.

    Maintain up with the newest info and events

    Join our mailing checklist, it’s free!

  • House loan credit history scoring products see stakeholder desire mature

    Utilization of FICO’s 10T credit rating ranking product is getting extra momentum in 2024, with two distinct loan suppliers signing on to make use of it for a lot of functions prematurely of broader mandated adoption comes future calendar 12 months. 

    Ohio-dependent countrywide direct loan supplier Liberty House Home finance loan is probably the most up-to-date enterprise choosing the FICO 10T mannequin, asserting it might get began using it for nonconforming originations. Liberty joins fairly a number of different companies presently using 10T for nonconforming monetary loans, along with Movement House loan and Crosscountry. In the very first quarter of this calendar 12 months, Primis Financial establishment, Leading Lending and Cardinal Economical, equally, all agreed to start out out use of FICO 10T for specified sorts of originations.

    Introduced in 2020, the FICO mannequin was chosen alongside with Vantagescore 4. by the Federal Housing Finance Agency as simply one in every of two rating varieties loan corporations will ultimately require to consider when underwriting to make them eligible on the market to government-sponsored enterprises. The use of two new designs will change the FICO Typical rating, which has been a necessity for twenty years.

    Whole implementation of the FHFA plan is anticipated to occur by the shut of 2025, though some parts of the proposal are in all probability to seem faster. 

    Relatively than maintain out for mandated alterations to get there, a tiny variety of loan suppliers began functioning with the 10T mannequin as simply these days as remaining yr for nonconforming loans marketed to personal traders. In February, Cardinal Financial stated it might begin out looking at 10T scores particularly for Section of Veterans Affairs originations, that are additionally not marketed to Fannie Mae or Freddie Mac and won’t have a exact requirement for such a credit history metric like they do. Cardinal was the very first to announce it might use the mannequin for VA monetary loans.

    FICO guarantees the predictive investigation obtainable by 10T can enhance originations by as considerably as 5%, when minimizing default risk by as much as 17%.

    The addition of Liberty Residence House loan to the checklist of FICO 10T finish customers arrives per week simply after World Dwelling Lending additionally reported it might combine the mannequin in its recapture evaluation of its servicing portfolio, which has authorities-backed and normal house loans from its dispersed retail channel or correspondent division. 

    “We are eager to faucet the power of FICO Rating 10T to additional evaluation our book of enterprise and unlock new origination potentialities,” stated John Bosley, Planet Household Lending property finance loan president, in a push launch.  

    World Home’s use of 10T additionally particulars to the rising factor to think about of latest scores in broader contexts inside simply the house loan trade. In February, the Federal Dwelling Bank loan Financial establishment of San Francisco indicated it might get began accepting mortgage collateral from loan suppliers using Vantagescore 4..

    With probably the most newest additions, FICO 10-T is now in use in some options of the group at property finance loan companies with a put collectively cumulative origination quantity of much more than $100 billion, the information analytics utility supplier reported. These exact same companies firm just about $300 billion in mortgages.

  • ‘Sticky’ inflation dampens anticipations of early fee minimize – Home finance loan Method

    The quantity of inflation ongoing to slip in March, with the headline Shopper Selling value Index dropping to three.2% — whereas this was a bit bit greater than financial forecasts.

    Mortgage authorities welcomed this downward sample, however reported ‘sticky’ British isles inflation might suggest the Bank of England postpones an early summer time season fee slash.

    The Lender of England has constantly reported that it’s going to not begin to cut back curiosity charges proper till there are crystal clear indications inflation is lower than regulate.

    March’s CPI decide had been solely a slight minimize on February’s determine of 3.4%, and even now a way over the Financial establishment of England’s 2% consider.

    L&C affiliate director David Hollingworth says discount within the headline cost of CPI was welcome. “It is a step within the applicable course towards the purpose when the Financial establishment of England might maybe get began to ease curiosity prices once more.

    “With a much bigger slide envisioned subsequent month some might be hoping a slash will arrive faster comparatively than afterward. However, the Bank may be very prone to contemplate the menace of inflation remaining better for extra time very significantly and has ceaselessly instructed it won’t act proper till it’s completely certain that inflation is below regulate.”

    Private finance complicated director Chris Sykes says: “While there’s a optimistic improvement in inflation, lingering dangers might most definitely postpone a summer time quantity decrease.”

    He supplies that BoE will keep a watchful eye on unpredictable conditions impacting on oil promoting costs and the extra powerful-than-expected actual earnings development. Sykes particulars out that British isles inflation stays increased than that in Europe, and provides that the BoE can be conscious of monetary particulars from the US this 7 days which confirmed inflation hovering but once more.

    Other people within the area recognized as on the Lender of England to take “daring” movement in response to the continued downward development in inflation.

    SPF Non-public Clientele CEO Mark Harris states: “With inflation persevering with to switch in the direction of the Bank of England’s 2% deal with, it’s time for the cost setters to be daring and begin out chopping fascination expenses. There is a sense that consumers and sellers are retaining fireplace prepared for that very first stage discount, and when it arrives, it can give the housing market a welcome strengthen.”

    He identified that swap costs have now risen this morning in response to issues that an need fee slice might be delayed and this may results the pricing of mounted fee mortgages. “Five-yr Swap prices rose this morning to 4.21 for every cent from 4.14 for each cent yesterday and proper up till they’re constantly slipping, loan suppliers are unlikely to minimize property finance loan charges extra.”

    Nonetheless Skyes claims much less beneficial inflation information from the US didn’t had an adversarial have an effect on on the pricing of mounted fee mortgages. “The best house loan charges we monitor have demonstrated no motion for about a couple of months. The insignificant enhance in swaps has merely launched them once more to concentrations from a pair of weeks earlier than.”

    Hollingworth means that present market anticipations on the timing of long run costs cuts can be vital in deciding mounted stage pricing heading forward.  “Fixed premiums have fallen considerably as a result of final summertime however have largely stabilised.  With uncertainty nevertheless within the air as to how quickly base quantity would possibly fall, all these holding out for extra cuts might presumably get hold of them selves in for a chronic wait round.”

    Over 50s loan supplier LiveMore dealing with director of capital markets Simon Webb says: “Although our current inflation quantity stays means off the two% objective, consumers can get some solace that inflation is essentially on the descent this time spherical, and our financial system does appear to be on the mend, gradual whereas that method is perhaps.

    “Older debtors and mortgage prisoners are persevering with to really feel the squeeze with the persevering with increased price of dwelling. People at present coming off an interest-only home loan this side of summer time will need to make constructive they discover audio info.”

  • Is a Reverse Mortgage loan Tabboo

    Do you not inform any individual that you’ve got a single? Are there folks in very related situations

    Husband or spouse and has handed on, solely set revenue this type of as social safety. Are meals gadgets charges heading up alongside with Medical? It is time to get a HECM – a line of credit standing to help you in your later years of existence, Have your babies be involved and everybody perceive how a Reverse House loan is efficient. Persons have 401k’s. there’s equity in your dwelling. what happens if you happen to eradicate that chance and residence costs go down? You is not going to should rely on relations to help you when you may have all of the strategies in your house.

    tune in and study further at https://www.ddamortgage.com/weblog website

    Didier Malagies nmls212566

    DDA Home finance loan nmls324329


    Request a Home finance loan Problem

    Use the shape down under and we’ll give your our professional solutions!

    Start off Your Bank loan

    with DDA nowadays

    Your neighborhood Property finance loan Broker

    House loan Broker Largo

    See our Opinions

    On the lookout for much extra specifics? Listen to our prolonged podcast! 

  • Housing affordability worsens for renters and owners

    Housing affordability worsens for renters and proprietors | Australian Broker News

    Information

    Housing affordability worsens for renters and owners

    Renters, proprietors cope with mounting prices, income stress

    Housing affordability worsens for renters and owners

    The newest ANZ CoreLogic Housing Affordability Report highlighted a significant uptick in housing bills, influencing affordability for every renters and home owners.

    In extra of the March quarter, the sum of money of cash essential for housing expenditures reached new highs, pushed by climbing mortgage mortgage charges and a tighter rental present market.

    Rental market shifts towards larger-cash movement earners

    As housing bills escalate, the demographic of private renters is ever extra shifting in direction of increased-income earners. This enhance displays the persevering with decline in homeownership costs, which has pushed rather more individuals into the rental market.

    “The a part of income wanted to service median new rents achieved a brand new greater of 32.2% nationally in March 2024,” claimed Eliza Owen, CoreLogic head of residential analysis Australia.

    Homeownership turning out to be progressively troublesome

    For potential residence potential patrons, the economical obstacles are rising steeper. The a part of median income required to providers a brand new mortgage mortgage has hit a group greater of 48.9% nationally as of March.

    In addition, the time important to protect for a 20% down cost has risen to greater than 10 a few years for a median family earnings, incomes it extra and extra exhausting for initially-time customers to enter the market.

    “Significant challenges are ongoing with present constrained and materials prices important,” reported Richard Yetsenga (pictured above), ANZ workforce chief economist. “International opposition for each merchandise and labour stays intensive.”

    Phone calls for better housing era

    With affordability pressures mounting, authorities are calling for additional proactive actions to reinforce housing supply.

    “Residential housing must be the quantity an individual priority,” stated Jess Caire, Home Council of Australia government director. “We wish to be constructing assured we’re having rather more properties throughout all typologies shipped speedier and additional effectively.”

    This methodology goals to mitigate the rising disparity in between earnings development and housing prices, making certain extra out there housing for all Australians.

    Get the most effective and freshest dwelling finance mortgage data despatched excellent into your inbox. Subscribe now to our FREE on a regular basis e-newsletter.

    Keep up with probably the most present information and occasions

    Be a part of our mailing checklist, it’s cost-free!

  • New house software action in March disappoints, MBA claims

    It is a gradual begin to the Spring dwelling buy season, on the very least in phrases of just lately created residences, as exercise enhanced in March however at disappointing quantities, the Mortgage Bankers Association talked about.

    This lackluster effectiveness echoes the flat Countrywide Affiliation of Property Builders/Wells Fargo sentiment index launched on Monday, which ended a four-month streak of beneficial properties. Household housing commences information that arrived out the next morning recognized the tempo of latest improvement to be on the most inexpensive annualized charge as a result of reality August, with the decline in single-relatives households the best in 3 yrs.

    “March is often a thirty day interval when new dwelling buys see a seasonal increase, however this yr March apps for brand spanking new property buys noticed a lot lower than a 1% maximize above the prior month on an unadjusted basis,” defined Joel Kan, the MBA’s deputy chief economist, talked about in the group’s Builder Application Study press launch. “Applications had been however ahead of final 12 months’s tempo, however at 6%, the yearly progress charge was the slowest as a result of September 2023.”

    Continuing superior prices of dwelling value appreciation, as completely as house mortgage costs as soon as extra receiving to 7%, is why this has been an unsatisfactory consequence.

    The one explicit sensible spot has been in packages for Federal Housing Administration-insured house loans.

    “The FHA share of functions did improve in March, exceeding 26%, in comparability to a 24% typical for the prior 12 months,” Kan talked about. “A bigger FHA share could be a signal of rather more first-time purchaser train, however that phase of potential consumers can be much more delicate to affordability troubles.”

    The MBA believed the once-a-year tempo of latest residence income in March to be a seasonally altered 615,000 items, a decline of 10.7% from February’s 689,000, and the slowest cost in 4 months.

    New residence gross sales fell 3.2% on an unadjusted foundation to 60,000 items, when put next with 62,000 in February.

    Typical loans (each equally conforming and jumbo) had been sought by 63% of latest house potential consumers in March. The remaining share went to federal government-confirmed options: FHA produced up 26.4% though Veterans Affairs loans had been 10.4% of latest house purposes and the U.S. Division of Agriculture Rural Housing Support software was .3%. The common monetary mortgage measurement for brand spanking new homes lessened to $405,400 in March from $405,719 in February.

    Home mortgage costs which are almost certainly to proceed to be elevated for for an extended interval are a drag on the Spring housing marketplace for present homes, the Initial American Knowledge & Analytics Household Selling worth Index report for March positioned.

    “Quite just a few sellers will carry on being on strike sustaining a lid on supply,” Very first American Money Chief Economist Mark Fleming mentioned in a push launch. “Having mentioned that, as we observed previous tumble when house mortgage costs peaked, need could probably additionally wane. Even regardless that the supply of houses on the market will keep restricted, sagging demand from clients ought to actually further sluggish worth appreciation in a ‘higher-for-longer’ mortgage mortgage charge setting.”

    In March, 1st American believed that prices rose .9% from the prior month, a a bit bit slower velocity than the revised 1% month-to-thirty day interval achieve recorded in February. Year-in extra of-yr, promoting costs rose by 6.2%, additionally down from the 6.3% annual elevate 1 thirty day interval prior.

  • Home finance loan Fees Eventually Win One particular

    Mortgage loan prices moved lower these days after hitting the optimum ranges since mid November yesterday.  Some lenders have been being down as an amazing deal as an eighth of a %, which is on the better side for a day-over-day modify for normal 30yr mounted costs. 

    As good as it’s to see a giant enhancement, it’s actually crucial to acknowledge the mom nature of the shift.  Even when charges are spiking repeatedly better, the carnage is invariably punctuated by momentary instances of reprieve.  In actuality, it’s actually extraordinarily uncommon for a value spike to take part in out with each successive working day remaining larger than the previous.  

    In different phrases and phrases, as of proper now, it may be not secure and sound to look at this development as something apart from a token bounce that exists as an everyday byproduct of the struggling that arrived simply earlier than it. 

    All that having been said, there’s additionally an opportunity that costs have moved up enough to get into their wished-for defensive placement for the following spherical of huge ticket data in early May.  We will have the ability to higher consider that danger in extra of the next two days.

  • Reduce than anticipated fall in inflation – Mortgage loan Finance Gazette

    The price of inflation continued to tumble in March, with the headline Buyer Value Index dropping to three.2% — although this was slightly bigger than monetary forecasts.

    inflation2-620x330.jpg

    Property finance loan authorities welcomed this downward craze, however defined ‘sticky’ United kingdom inflation might counsel the Bank of England postpones an early summertime value slice.

    The Financial establishment of England has repeatedly talked about that it’ll not begin out to lower curiosity prices until there are distinct indicators inflation is beneath command.

    March’s CPI decide had been solely a slight decrease on February’s determine of three.4%, and proceed to a way larger than the Bank of England’s 2% concentrate on.

    L&C affiliate director David Hollingworth states discount in the headline quantity of CPI was welcome. “It is a stage in the suitable course to the purpose when the Lender of England would possibly get began to ease fascination prices again once more.

    “With a bigger fall envisioned following thirty day interval some could maybe be hoping a slice will seem quicker comparatively than afterward. However, the Financial establishment is possible to get the specter of inflation remaining elevated for prolonged severely and has persistently immediate it received’t act till ultimately it’s assured that inflation is beneath management.”

    Personal finance specialised director Chris Sykes states: “While there’s a optimistic craze in inflation, lingering risks might probably postpone a summertime quantity cut back.”

    He provides that BoE will proceed to maintain a watchful eye on unpredictable events impacting on oil charges and the stronger-than-predicted true earnings development. Sykes factors out that United kingdom inflation stays higher than that in Europe, and supplies that the BoE will take heed to monetary data from the US this week which confirmed inflation rising as soon as once more.

    Many others in {the marketplace} generally known as on the Financial establishment of England to decide on “daring” movement in response to the continued downward improvement in inflation.

    SPF Personal Customers CEO Mark Harris suggests: “With inflation persevering with to switch to the Lender of England’s 2% focus on, it’s time for the quantity setters to be daring and begin out slicing fascination premiums. There is a sense that potential patrons and sellers are protecting fireplace ready for that first value discount, and when it arrives, it is going to give the housing market place a welcome enhance.”

    He identified that swap prices have now risen this early morning in response to concerns that an want fee decrease may very well be delayed and this can results the pricing of mounted quantity mortgages. “Five-yr Swap prices rose this morning to 4.21 for every cent from 4.14 per cent yesterday and till ultimately they’re usually falling, loan firms are unlikely to attenuate dwelling finance loan prices additional extra.”

    Having stated that Sykes states lots much less useful inflation info from the US didn’t skilled an hostile impact on the pricing of fastened fee mortgages. “The best dwelling loan prices we watch have confirmed no motion for shut to a couple weeks. The minimal elevate in swaps has simply introduced them once more to quantities from numerous months earlier.”

    Hollingworth means that market place anticipations on the timing of long term premiums cuts can be essential in deciding set degree pricing heading ahead.  “Fixed prices have fallen considerably as a result of earlier summertime however have largely stabilised.  With uncertainty nonetheless in the air as to how promptly basis fee could maybe tumble, all these protecting out for added cuts would possibly get hold of them selves in for an extended wait round.”

    About 50s monetary establishment LiveMore managing director of funds markets Simon Webb says: “Although our present-day inflation price stays manner off the two% goal, clients can purchase some solace that inflation is basically on the descent this time spherical, and our monetary system does present as much as be on the mend, sluggish although that methodology could probably be.

    “Older debtors and residential loan prisoners are persevering with to really feel the squeeze with the persevering with substantial value of residing. Folks coming off an curiosity-only dwelling finance loan this aspect of summer time season might want to should make assured they search for audio ideas.”

  • Brokers discussion deserves of tiny product or service transfers – Home finance loan Approach

    Broker queries about small product or service transfers and how one can publicize their companies have been among the many most popular discussion threads on an on the net market discussion board.

    The discussion board Cherry, which was frequented by greater than 35,000 monetary firms execs final yr, defined product or service transfers had been being one of probably the most well-known mortgage loan issues talked over, particularly for  small mortgage dimensions.

    The dealer who began off the thread most well-liked to know irrespective of if different people would cope with a product or service switch for a £20,000 financial institution loan the identical approach as they might for a a lot bigger sized remortgage.

    Other well-known topic areas incorporates a thread on Google’ pay out-per-simply click on advertising and marketing, during which brokers talked over what would a superb conversion quantity could be from a singular quantity of clicks and impressions.

    It garnered a spread of optimistic responses and options from fellow brokers, like search time period system, how one can measure ‘success’, and in what methods one’s have web web site could possibly be improved to take advantage of of web site visitors despatched by Google adverts and key phrases.

    Cherry director Donna Hopton claims that the discussion board is seeing yr-on-12 months development in train highlights its usefulness to the cash suppliers area people, with fairly a number of attempting to get information, options and steerage from associates in the home loan subject.

  • Cyberattack at loanDepot impacts 17M men and girls, with up to $17M in bills

    An replace on loanDepot’s January cyberattack exhibits that a greater amount of oldsters have been impacted than beforehand disclosed, while tens of hundreds and hundreds of dollars in supplemental bills shall be additional to the corporate’s 1st-quarter earnings outcomes. 

    On Tuesday early morning, the most important 15 U.S. home mortgage mortgage firm declared that it’ll notify 16.9 million people whose delicate personal particulars was impacted by the cyber incident. loanDepot will provide credit score rating monitoring and identification security suppliers at no worth to them, per filings with the Securities and Trade Fee (SEC).

    The choice of individuals affected exceeds the 16.6 million who had been educated on Jan. 22. 

    In accordance to the enterprise, the cyberattack will insert shut to $12 million to $17 million in bills to its initially-quarter earnings, the online of predicted insurance coverage protection. The group talked about, nonetheless, that the incident won’t have a product have an effect on on its in common cash issues for the whole yr.

    loanDepot has but to announce a launch date for its fourth-quarter 2023 earnings. 

    California-dependent loanDepot educated the broader group of the cyberattack that introduced its models down on Jan. 8, together with that the date of the earliest celebration was Jan. 4. The group started restoring its methods on Jan. 18. On Tuesday, it documented that the cyberattack has been contained. 

    The incident might have involved “title, deal with, piece of email deal with, financial account numbers, social safety quantity, mobile phone quantity, and date of begin,” of consumers, in accordance to a observe of particulars breach despatched to the Workplace of the Maine Attorney General. 

    Ransomware gang AlphV/BlackCat later claimed it was at the rear of the cyberattack.

    Clients filed many class-action lawsuits adhering to the cyberattack, professing they’d been “positioned in an imminent and persevering with danger of harm from fraud, identification theft, and related harm introduced on by the knowledge breach.” loanDepot is accused of negligence, breach of deal and unjust enrichment, amongst different allegations. 


    The agency, which doesn’t comment on pending litigation, wrote to the SEC that it aren’t ready to “presently quantify” the prices associated to the lawsuits, but it surely “doesn’t assume that the cybersecurity incident may have a product influence on its total fiscal scenario or on its ongoing success of operations.” 

    Several home mortgage companies haven’t too way back been the goal of cyberattacks, together with Mr. Cooper Group, First American and Fidelity Nationwide Financial Inc., the mom or father of servicer LoanCare. 

    Property finance mortgage executives knowledgeable HousingWire that these assaults have put the market in “alert method.” They don’t have a transparent response for why the house finance mortgage sector, primarily servicers, has sustained so plenty of assaults of late. However, they acknowledge that they preserve a big amount of purchaser information and some avid gamers could also be susceptible amid a shrinking present market.