Tag: uncategorized

  • House loan charges poised to fall to 5.5% in 2024: Bloomberg

    Gen X is presently in search of for housing right for growing older in put

    By Didier Malagies
    •
    10 Apr, 2024

    Little one boomers are exhibiting an overwhelming want to age in place in their private houses, however their young children — largely customers of Generation X — are additionally constructing their needs felt by looking for out houses that may accommodate their needs as they become old, in accordance to a the most recent report from the New York Times. Citing 2021 particulars from the Harvard College Joint Middle for Housing Scientific assessments that confirmed 88% of older folks 65 and older are rising previous in place, a number of clients of the following know-how — primarily born involving the mid-Sixties and early-Eighties — are beforehand utilizing proactive strategies to by questioning “in regards to the place they’ll dwell in their 70s, 80s and even 90s,” the Times reported. Homebuilders are observing a enhance in want for properties that may accommodate pure rising previous from Gen X potential patrons. David O’Reilly, CEO of Howard Hughes Holdings which constructs ready communities, describes the sector getting “on the cusp,” stating that the necessity appears to be coinciding with further clients of Gen X nearing a time in which they’ll grow to be “empty nesters.” “That’s generally the tipping level,” O’Reilly suggested the Times. Gen X purchasers are additionally much more most definitely to have further monetary signifies and regulate round their potential decisions, and are preserving entry to important later on-daily life suppliers in mind when choosing out the place by to reside as they become old, the story acknowledged. “In new developments, [Gen X buyers] are in search of accessibility to well being and health and wellness options, like mountaineering trails and tennis courts, in addition to choosing home options like showers instead of bathtubs, as an example, and soliciting for essentially the most up-to-date gadgets to help them as they age,” the reporting reported. A report launched final 7 days by the Countrywide Association of Realtors (NAR) defined that Gen X homebuyers have a median earnings of $126,900, and are even now a few years away from retirement. That additional working time will allow them to to amass additional wealth in accordance to Jessica Lautz, deputy chief economist and vice chairman of investigation at NAR. Customers of Gen X are additionally benefiting from the pandemic and write-up-pandemic operate-up in property charges, carrying considerably much more family equity than their millennial counterparts and dwarfing millennial homeownership charges 72% to 55% as of 2023. One explicit analyst reported that Gen X patrons are impressed to act now for getting old-ideal housing due to the state of the housing market.  “If they’re buying for residences, supplied the tightness of the present market and distant function, I do consider that you simply see far more Gen X-ers viewing a house get hold of as a family for the remainder of their lives,” acknowledged Cristian deRitis, deputy chief economist at Moody’s Analytics to the Situations.
  • Aussie houses slide brief of needs

    Aussie households fall small of needs | Australian Broker Information

    News

    Aussie houses tumble restricted of needs

    New PropTrack insights reveal housing mismatch

    Aussie homes fall short of needs

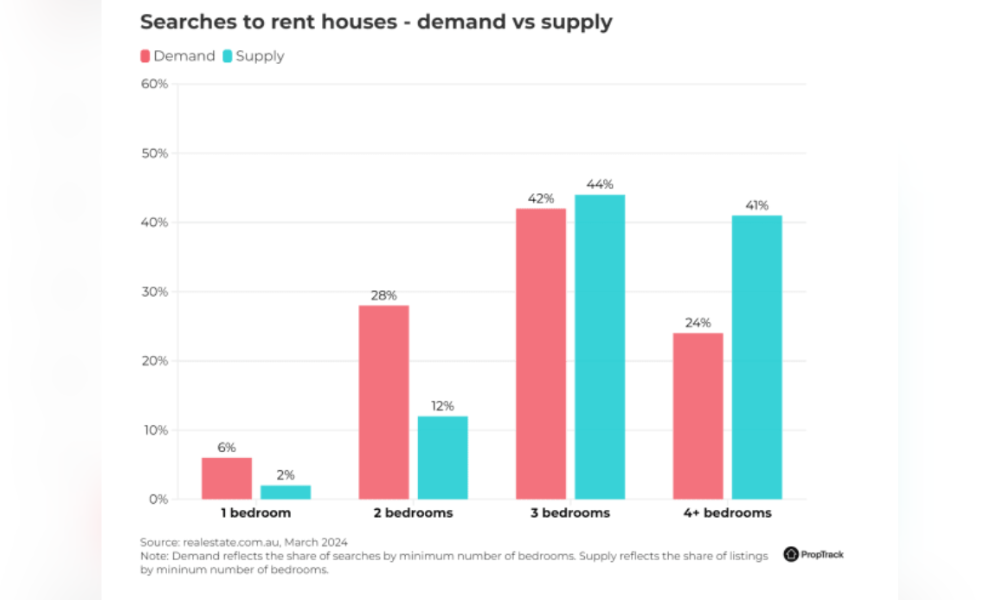
    Australia’s housing panorama faces a serious mismatch, with evolving resident requires and shrinking households shifting demand from prospects for various kinds of houses and highlighting a market place gap, in accordance to PropTrack.

    “The frequent Aussie family has adjusted noticeably across the earlier couple a few years,” acknowledged Anne Flaherty (pictured increased than), PropTrack economist.

    With an frequent family dimensions dropping from 4.6 in 1920 to only 2.5 in 2023, the change within the route of solitary-particular individual houses and pair-only households has develop to be pronounced.

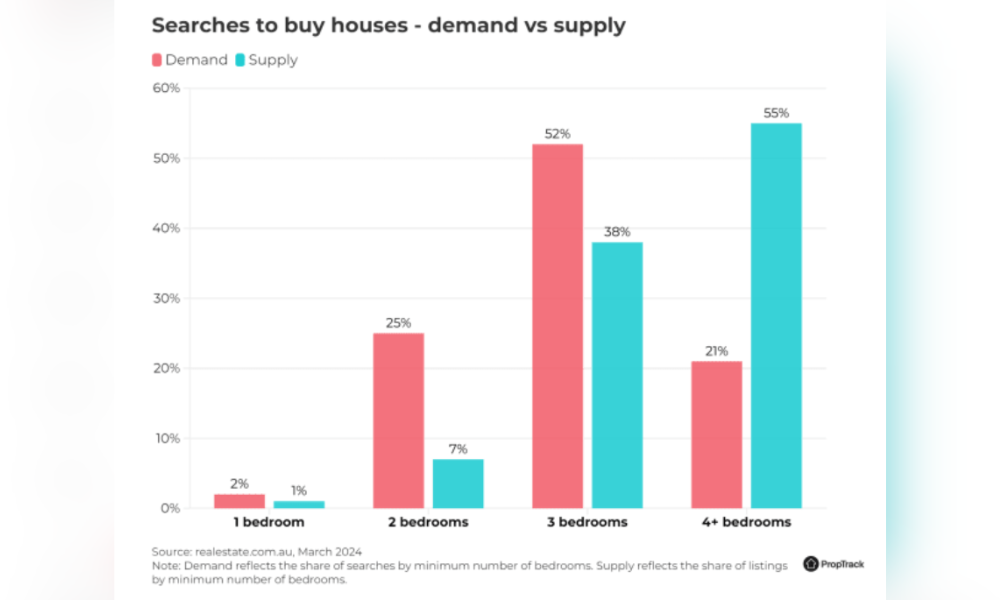
    “Among residence seekers seeking to purchase or lease residences, the shrinking family dimension has reweighted want absent from bigger properties to those with fewer bedrooms,” Flaherty acknowledged.

    Regardless of the prevalence of listings for houses with 4 or further bedrooms, the demand has shifted within the route of households with fewer bedrooms.

    Need and supply discrepancy

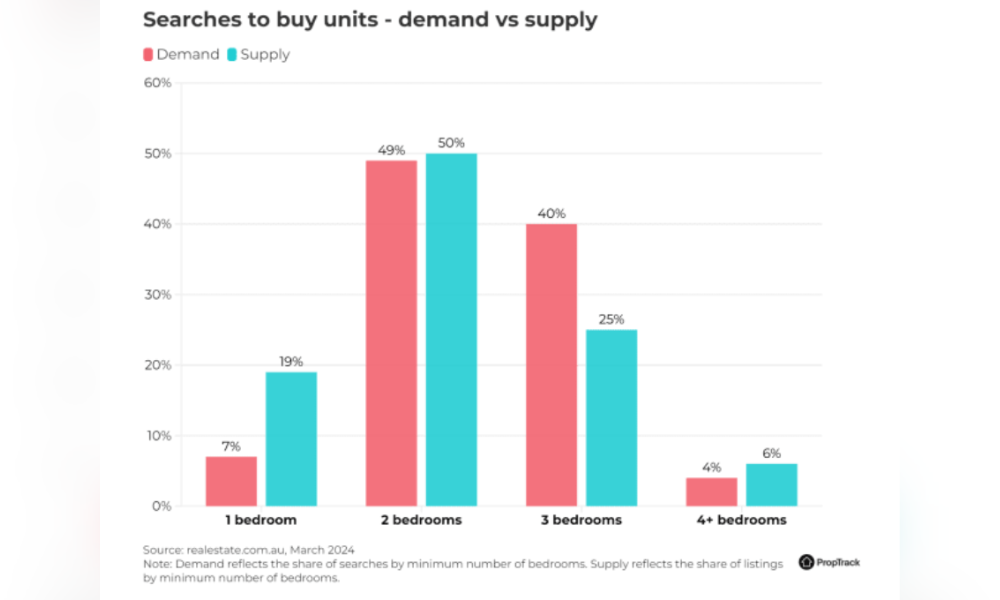
    The craze just isn’t solely minimal to properties. The unit sector has seen an reverse craze.

    “In the newest years, significantly post-COVID, there was growing demand from prospects for bigger fashions,” Flaherty acknowledged, stating the amplified want for three-bed room models amidst the rise of distant and hybrid doing work preparations.

    This want just isn’t staying met sufficiently, significantly in cities like Sydney, the place the supply of 3-bedroom models falls brief of the demand from prospects.

    Implications for pricing and progress

    The mismatch amongst supply and wish has a number of implications for the housing present market, along with the potential for a decrease within the worth high-quality for houses with many bedrooms and an improved prime quality for fashions with an extra bed room.

    “Understanding the mismatch involving demand from prospects and the current supply of housing has implications for potential development and pricing,” Flaherty defined, indicating a doable change in the direction of producing extra two-bed room properties and bigger models to fulfill the modifying necessities.

    Your ideas? Go over how altering housing needs are reshaping the sector.

    Continue to maintain up with the latest information and events

    Sign up for our mailing report, it’s free of cost!

  • Getting older in position by means of household-based mostly care is a leading end result for seniors

    When explicit individual necessities and wellbeing considerations will largely dictate how a man or lady spends their remaining a number of years, a new analyze reveals that dwelling-primarily based mostly care is a prime consequence for extra mature People in america. This abstract arrives from a new examine by researchers at Rutgers University in
    New Jersey.
    Hospice Information 1st
    famous the outcomes.

    “The intention of this look at was to determine the trajectories for location of care in every particular person quarter in the course of the previous three yrs of each day life between Medicare beneficiaries and the weather associated with these trajectories,” the scientists mentioned. “A retrospective cohort was assembled from Medicare beneficiaries who died in 2018, and a 10% random pattern of the cohort was analyzed.”

    The ultimate ultimate outcomes had been in the long term sorted into a few predominant “clusters,” they outlined, which incorporates home care, proficient residence remedy and institutional care. The significantly-and-away desire for the pattern was in some sort of house-centered care, in accordance to the findings.

    “Nationally, over 50 % (59%) of Medicare beneficiaries have been being in the family cluster, a single-quarter (27%) had been in the proficient family remedy cluster, and the comfort (14%) have been in the institutional cluster,” the scientists reported. “There had been big variations by level out in the use of services and products throughout the earlier three years of life.”

    Dwelling care with out having a proficient nursing facet was most frequent between Medicare beneficiaries in Alaska (81.5%), Puerto Rico (81.4%), Hawaii (72.9%), Arizona (69.2%) and Oregon (68.9%). They have been being minimal repeated amid beneficiaries from Massachusetts (47.1%), Louisiana (47.8%), Rhode Island (48.3%), and Connecticut (48.6%).

    “Our outcomes are just like these described in a trendy future cohort analysis using a agent pattern from the Countrywide Wellness and Growing previous Trends Review (NHATS), which additionally uncovered that 58% of NHATS individuals remained at home and 17% transitioned to or died in an institutional surroundings,” the Rutgers analysis positioned. “Our conclusions are additionally fixed with the current downward development of fatalities in acute care hospitals and upward improvement of fatalities in dwelling and neighborhood choices.”

    Nonetheless, though the principal want appears to be getting previous at family, a lot extra details is required to completely acknowledge these selections, the researchers concluded.

    “While the majority of extra mature older folks put in their ultimate years at residence with small use of expert family care or institutional remedy till ultimately the remaining months of life, 40% skilled key wellbeing firm needs,” they defined. “Extended use of certified dwelling remedy or institutional care was additional recurrent amid extra mature older folks dwelling with quite a few long-term circumstances, like dementia.”

    Foreseeable future evaluation that goals to acknowledge “the well being and health remedy strategies and coverage elements that affect spot of remedy trajectories” might allow progress refinement of the care expertise, well being of the populace and affiliated remedy expenses, they included.

    Getting older-in-location selections among the many extra mature Us residents are
    very properly documented, and the
    motorists of these tastes have additionally been topics of newest dialogue.
    Extensive-expression remedy is additionally an considerably massive precedence for older Americans.


    The reverse home mortgage area typically goals to position its merchandise choices as conducive to the ambitions of rising older in put. The success of the Rutgers assessment might drop gentle on the broader issues to think about that direct extra mature People to look for out specified stop-of-daily life remedy paths, considerably because the U.S. inhabitants
    grows older additional swiftly.

  • AHURI unveils 2024 housing research tasks

    AHURI unveils 2024 housing research tasks | Australian Broker News

    News

    AHURI unveils 2024 housing research assignments

    AHURI targets housing troubles with 2024 exploration and massive inquiry

    AHURI unveils 2024 housing research projects

    AHURI has unveiled the funded exploration actions for the 2024 National Housing Research Software, aiming to deal with the important issues inside simply Australia’s housing strategies.

    The 2024 methodology will fund a foremost Inquiry into building constraints influencing housing supply and 14 investigation initiatives overlaying a broad spectrum of housing system difficulties.

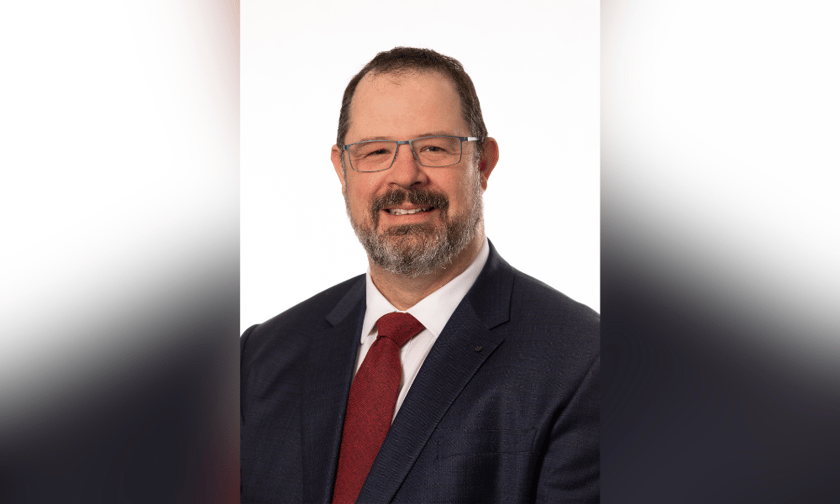
    “AHURI is looking for treatments for many of probably the most pressing troubles coping with Australia’s housing gadgets specifically, the inquiry investigating design constraints is a matter of countrywide relevance,” defined Michael Fotheringham (pictured over), controlling director of AHURI.

    Addressing quite a few housing troubles

    The examine software is meant to take a look at many parts of the housing sector, from homelessness responses and neighborhood and social housing provision to the non-public rental course of and homeownership considerations.

    Fotheringham emphasised the relevance of innovation in housing improvement to handle supply shortfalls and enhance affordability.

    “The breadth of the research methodology displays the number of our housing methodology issues,” he defined, outlining this system’s objective to deal with process difficulties like rental emptiness checking, understanding homelessness, and measuring the have an effect on of housing help.

    The 2024 investigation issues to do have been decided in collaboration with situation/territory and federal authorities officers, trade, and non-authorities authorities. They will check out a number of fashionable housing, homelessness, and concrete plan ideas.

    The AHURI inquiry

    The AHURI inquiry, in particular, titled “Inquiry into overcoming constructing constraints for the supply of recent indifferent and substantial-increase housing” and led by Ron Wakefield, will delve into the housing building sector’s constraints related to the supply chain, workforce, technological know-how, regulation, process of labor, and marketplaces.

    The inquiry is supported by three crucial investigation tasks:

    &#13
    “Innovation for lots extra environment friendly, resilient and responsive housing building market: intercontinental classes”, led by Andrew Beer, goals to pinpoint world improvements that may enhance productiveness in housing building though additionally acquiring social, environmental, and financial goals.&#13
    “Transforming indifferent housing building: Plan strategies to prevail over effectivity constraints”, beneath the recommendation of Ehsan Gharaie, delves into the design part of indifferent housing to determine the way it impacts housing delivery and supply and supply, alongside potential efficiency-improving interventions.&#13
    “Transforming superior-increase housing improvement: plan strategies to overcome effectivity constraints”, led by Chy Lin Lee, examines the development stage of superior-increase developments to completely grasp its impression on housing delivery and supply and to analyze profitable enhancement interventions.&#13

    AHURI research tasks

    The methodology additionally comprises jobs on collaborating Indigenous communities to enhance housing outcomes, enhancing housing for people with disabilities, demystifying the rental vacancy quantity, and inspecting workplace trauma in housing and homelessness companies. Added assignments will search into the implications of limited-term rental lodging, shared equity packages, and the aim of Commonwealth Hire Help, amid some others.

    For the overall guidelines of study jobs, cease by the AHURI website.

    Get the most well-liked and freshest property finance mortgage data shipped correct into your inbox. Subscribe now to our FREE every day publication.

    Continue to maintain up with probably the most up-to-date information and gatherings

    Be a part of our mailing itemizing, it is freed from cost!

  • Buying a home when it is even now in probate

    Gen X is now trying to find housing appropriate for getting outdated in put

    By Didier Malagies
    •
    10 Apr, 2024

    Little one boomers are exhibiting an overwhelming have to age in location in their very personal residences, however their babies — principally customers of Technology X — are additionally constructing their goals felt by in search of out properties that may accommodate their requires as they get extra mature, in line with a the most recent report from the New York Moments. Citing 2021 data from the Harvard College Joint Centre for Housing Studies that confirmed 88% of grownups 65 and extra mature are rising outdated in space, a number of members of the next period — primarily born involving the mid-Sixties and early-Eighties — are now utilizing proactive strategies to by imagining “about the place they may reside in their 70s, 80s and even 90s,” the Situations documented. Homebuilders are observing a enhance in want for homes that may accommodate regular getting older from Gen X customers. David O’Reilly, CEO of Howard Hughes Holdings which constructs deliberate communities, describes the business getting “on the cusp,” declaring that the will seems to be coinciding with further customers of Gen X nearing a time the place they may develop to be “empty nesters.” “That’s usually the tipping difficulty,” O’Reilly instructed the Occasions. Gen X customers are additionally further potential to have further financial signifies and regulate greater than their potential prospects, and are retaining get hold of to needed later on-existence corporations in mind when choosing out wherever to reside as they get extra mature, the story said. “In new developments, [Gen X buyers] are in search of entry to total well being and wellness options, like climbing trails and tennis courts, as properly as choosing residence options like showers in its place of bathtubs, as an example, and soliciting for the most recent gadgets to help them as they age,” the reporting claimed. A report launched last 7 days by the Countrywide Association of Realtors (NAR) defined that Gen X homebuyers have a median cash of $126,900, and are nonetheless a long time away from retirement. That added doing work time will permit them to amass additional extra wealth in accordance to Jessica Lautz, deputy chief economist and vp of investigation at NAR. Associates of Gen X are additionally benefiting from the pandemic and put up-pandemic run-up in home prices, carrying significantly far more property fairness than their millennial counterparts and dwarfing millennial homeownership costs 72% to 55% as of 2023. 1 analyst said that Gen X clients are impressed to behave now for aging-acceptable housing owing to the purpose out of the housing sector.  “If they’re looking for properties, provided the tightness of the sector and distant carry out, I do consider you see additional Gen X-ers observing a family get hold of as a property for the relief of their life,” said Cristian deRitis, deputy predominant economist at Moody’s Analytics to the Periods.

  • Sunshine Financial loans charged prohibited fees – courtroom

    Sunshine Financial loans charged prohibited fees – court docket docket | Australian Broker Information

    Information

    Sunshine Financial loans billed prohibited fees – court docket docket

    The mortgage supplier illegally charged prices about 12,000 events

    Sunshine Loans charged prohibited fees – court

    The Federal Court has dominated versus Sunshine Financial loans, a small sum mortgage firm, for equivalent to an modification or rescheduling value in further than 670,000 contracts, a observe not permitted lower than the Nationwide Credit ranking Code.

    Amongst July 2016 and November 2020, the enterprise imposed these service fees further than 12,000 situations, ultimately amassing practically $300,000 from consumers illegally.

    ASIC targets SACC cost abuses

    ASIC Chair Joe Longo highlighted the vulnerability of shoppers who generally trip resort to tiny quantity credit score rating settlement (SACC) loans for surprising emergency expenditures.

    “Consumers of SACC loans are a few of Australia’s most vulnerable,” Longo claimed. “They usually simply take out these smaller loans for only a a number of hundred {dollars} to incorporate surprising emergency or very important expenses. SACC loans are significantly excessive priced, and ASIC is dedicated to creating positive consumers aren’t charged further prohibited service fees.

    Sunshine Loans’ compliance and purchaser recourse

    Following ASIC’s intervention, Sunshine Financial loans ceased charging the disputed fees in November 2020, whereas they didn’t acknowledge legal responsibility.

    Buyers affected by equivalent prohibited expenses are inspired to pay money for their monetary establishment for refunds or escalate their points to the Australian Financial Problems Authority (AFCA) if dissatisfied with the response.

    Assist and extra property are accessible by the Nationwide Debt Helpline and Moneysmart for these needing help with monetary loans and bank card debt administration.

    History and broader market implications

    Sunshine Financial loans, largely operating on-line, now offers medium complete credit score rating contracts starting from $2,050 to $2,500.

    This case follows ASIC’s efficient proceedings in September versus a further SACC provider, Ferratum Australia, for linked offenses, indicating a tightening regulatory scrutiny over the tiny monetary loans discipline in Australia.

    For different latest ASIC tales, click on on beneath and on this article.

    Get the preferred and freshest home mortgage information delivered very best into your inbox. Subscribe now to our FREE day-to-day publication.

    Continue to maintain up with the most recent information and events

    Be a part of our mailing checklist, it’s completely free!

  • Retired partners might have to have $400,000 in cost savings to include health care fees , Maybe time to feel about a Reverse House loan

    Retired {couples} who’re Medicare beneficiaries may wish as considerably as $413,000 saved to handle scientific prices in the latter ranges of lifetime, an maximize over the previous yr’s estimate of $383,000. This is in accordance to new
    outcomes from the
    Staff Benefit Exploration Institute (EBRI).

    The determine is the “predicted monetary savings aim for Medicare beneficiaries to go over charges, deductibles, and prescription drugs in retirement,” EBRI mentioned.

    The estimates crack down in one other method for one guys, females and {couples} who’re portion of Medicare supplemental insurance coverage protection choices, and the figures objective to provide retirees “a 90% risk of meeting their health and health remedy paying out needs in retirement.”

    For single males, the savings determine is $184,000. For single women, the approximated decide is $217,000, although {couples} in supplemental insurance coverage protection designs would have to have an estimated $351,000.

    “Health care fees in retirement could be substantial and will probably not mechanically be a salient drawback for employees,” defined Jake Spiegel, research affiliate for wellbeing and wealth added advantages Exploration at EBRI. “To problem how considerably Medicare beneficiaries could probably will want to assist save to have a affordable probability of meeting their wellness care shelling out specs in retirement, EBRI designed a simulation product letting for uncertainty owing to mortality and fees of return on property in retirement.”

    The mannequin takes
    newest enhancements to Medicare Part D under consideration, enacted as aspect of the 2022 Inflation Reduction Act handed by Congress and signed into regulation by President Joe Biden.

    The EBRI product “exams various assumptions about Medicare Benefit and [supplemental insurance] methods that Medicare beneficiaries could properly purchase,” Spiegel defined. “The output of this up to date simulation product is the premise of this new report.”

    The $413,000 estimate is an “excessive case,” the advantages reveal. A pair would want to have to have “notably important prescription drug expenditures” for that monetary savings determine to sufficiently have a 90% risk of convention health care paying out wants all through retirement.

    The research additionally discovered that every one these enrolled in
    Medicare Advantage concepts — private designs that “present all your Medicare Section A (Clinic Insurance coverage) and Medicare Aspect B (Health-related Insurance) protection” and which might be separate from supplemental methods — have “usually scale back worth savings targets” than these folks not enrolled in this sort of choices.

    “The outcomes from EBRI’s projection mannequin counsel that basic total health remedy fees incurred by Medicare beneficiaries are greater,” Spiegel included. “While the cost savings targets are seemingly to be decreased for Medicare Edge enrollees relative to Medigap enrollees, there are important restrictions to select under consideration.”

    A the newest research uncovered that just about 25% of older folks
    have no retirement program other than
    Social Safety, a achieve software program that accounts for a number of extra mature Americans’ most vital provide of {dollars} stream in retirement. Social Protection benefits rose in 2024 by 3.4%, however seniors proceed to
    particular fear in extra of their potential to make ends fulfill.

    Time to consider about a Reverse Home finance loan


  • Federal Court docket orders liquidation of Prospero Markets

    Federal Courtroom orders liquidation of Prospero Marketplaces | Australian Broker News

    Information

    Federal Courtroom orders liquidation of Prospero Marketplaces

    Court docket appoints liquidators for fund return

    Federal Court orders liquidation of Prospero Markets

    Adhering to an ASIC software program, the Federal Court docket has mandated the liquidation of Prospero Markets on simply and equitable grounds and appointed liquidators to deal with administration issues and make sure the return of shopper cash.

    ASIC’s issues and steps

    ASIC’s choice to make the most of for liquidation stemmed from sizeable issues regarding Prospero’s administration, particularly its compliance with Australian fiscal options (AFS) licence conditions and its obligations as an extra than-the-counter (OTC) derivatives issuer.

    “ASIC has been given enquiries from prospects who’re involved in regards to the return of their cash,” the regulator talked about in a media launch.

    Federal Courtroom emphasises compliance

    In his ruling, Registrar Tim Luxton burdened the essential must have for licensees like Prospero to stick strictly to their statutory obligations beneath an AFS licence. These obligations embrace sustaining an appointed auditor, lodging audited financial accounts and month-to-month and yearly by-product shopper {dollars} reconciliations with ASIC, and giving spinoff transaction reporting information.

    Liquidators appointed

    The court docket has appointed Andrew Cummins, Jonathon Keenan, and Peter Krejci of BRI Ferrier because the liquidators for Prospero.

    Clients or collectors searching for information or help regarding the liquidation process can converse to the liquidators particularly by means of e-mail or telephone.

    Background and investigation

    Prospero, which retains an AFS Licence (selection 423034), was authorised to current suppliers like issuing and promoting and advertising derivatives and international commerce contracts.

    The firm’s licence was suspended in December simply after failing to lodge its audited monetary accounts for 2023. This suspension stays productive proper up till Sept. 26.

    Additionally, ASIC’s investigation into Prospero adopted fees in opposition to former officers and reliable supervisors just like money-laundering offences in relationship with the Changjiang Currency Trade money remitting chain.

    For different trendy ASIC tales, click on on right here and on this article.

    Get the most well-liked and freshest dwelling finance mortgage info delivered correct into your inbox. Subscribe now to our FREE day by day e-newsletter.

    Continue to maintain up with the latest info and conditions

    Be half of our mailing guidelines, it’s free of cost!

  • Gurus offer strategies for getting old in put and compare prices to assisted dwelling: CNBC

    The data is apparent: getting older in space is a really clear desire for fairly a number of older Us residents creating choices for how their later many years will take part in out. But a considerable amount of folks at this time approaching these ages may not know the simplest methods they will make their properties further accommodating for regular modifications that seem with getting old, in accordance to a brand new story at CNBC.

    “People could say, ‘I would like to age in put because the default plan, primarily as a result of that’s what I’m already executing,’” Carol Chiang, CEO of individualized getting older-in-place consulting firm Evolving Residences, suggested the outlet. “But they’re not actually taking a look at, ‘Well, what does that essentially imply?’”

    There are 3 widespread shopper varieties Chiang’s firm serves, she spelled out. These embody those that have some form of pressing have to have, in all probability stemming from a present well being care problem or private harm people struggling from a cognitive or neurodegenerative drawback and far more proactive grown ups who’re organising out their afterward years in advance.

    An authorized monetary planner (CFP) who enlisted Chiang’s providers falls into the proactive camp, she suggested CNBC.

    “She manufactured us think about by way of what an getting old-helpful bathroom would seem like,” CFP Carolyn McClanahan talked about. “People are generally reworking their properties each single 10, 15, 20 a few years. So constructing specified — primarily once you strike your 50s and 60s — that you just rework it […] does make it easier as you become older to preserve house.”

    Fees for renovation jobs can differ based on variables these kinds of as location, occupation sizing and drawback of the dwelling. Whilst the monetary funding may be steep in phrases of upfront expense, it is usually primarily a a single-time expense that may assist make the remainder of a resident’s time in a dwelling simpler, in accordance to Curt Kiriu, president of CK Independent Dwelling Builders in Mililani, Hawaii.

    “At a extraordinarily, fairly elementary diploma, considering a couple of rework, you need to be organizing for on the very least $70,000,” Chiang claimed, incorporating that specific positions can seem in at so much lower than half that. But when in comparability to the $108,000 annual median expense of a personal space in a nursing house, in accordance to particulars from Genworth, remodeling may be far more compelling.

    A current research by researchers at Rutgers University in New Jersey discovered that residence-based principally care is a foremost ultimate consequence for older Us residents.

    Another current research discovered that 55% of surveyed toddler boomers technique to proceed to be in their present properties as they age, however so much lower than a person-quarter of all these surveyed have any concepts to renovate their properties to way more safely and securely and merely accommodate regular changes that arrive with getting older.

    Only 24% of toddler boomers are making ready their homes for getting older, and even much less are introducing different safety options, in accordance to the latter overview by dwelling enchancment corporations firm Leaf Home and market research agency Morning Consult.

    Around 75% of boomer respondents report that they “have in no means included safety or accessibility traits in their properties,” while 81% of the cohort report making ready to depart an inheritance of some kind after they cross away, the analyze found.

    Is it time to place a Reverse Home finance mortgage to function for you at this time?

  • MFAA reaches 15,000 associates | Australian Broker News

    MFAA reaches 15,000 clients | Australian Broker Information

    Information

    MFAA reaches 15,000 members

    Three quarters of all brokers in market at the moment are clients

    MFAA reaches 15,000 members

    The Mortgage & Finance Affiliation of Australia (MFAA) has arrived at a substantial milestone as its complete membership surpasses 15,000 for the primary time.

    Proven in 1980, the MFAA performs a vital position in representing and advocating for home mortgage and finance brokers throughout Australia. However, its have an effect on extends additional than brokers to embody a various array of entities inside {the marketplace}, like aggregators, mortgage corporations, mortgage supervisors, insurers, and different suppliers.

    “Our perform is to empower our members to prosper and thrive, making certain Australians profit from competitors and various,” talked about MFAA CEO Anja Pannek (pictured larger than).

    “The crew and I simply take enormous enjoyment of representing our members to important stakeholders along with governing administration, treasury and regulators, and collaborating on prolonged-expression approaches to verify the trade’s achievements and sustainability.”

    Pannek stated that members have positioned their think about within the affiliation and “that accountability isn’t one thing we take evenly”.

    “Mortgage and finance brokers interact in a essential job in helping Australians encounter the protection of homeownership and the constructive features of accessibility to small enterprise lending,” Pannek stated.

    “The house mortgage and finance broking market has progressed and grown to come back to be 1 that’s critically important to the monetary state. All when our members have designed the belief of Australians by delivering common, excellent outcomes for his or her purchasers.”

    Advocating for members

    The MFAA has a observe report of advocating on behalf of its members to make sure plan and regulation is in form for intent.

    Pannek defined that the MFAA’s advocacy is targeted on issues that proper affect its members, these kinds of as guaranteeing regulatory levies are appropriate to the extraordinarily very low quantities of issues and movement in the direction of the affiliation’s associates.

    Some important outcomes the MFAA advocacy has realized encompass:

    “We additionally advocate for measures that can achieve our members’ clients and their talent to acquire their goals resembling our advocacy in assist of the regulation of Obtain Now Pay out Later on merchandise,” Pannek stated.

    Supporting members’ expert improvement

    Pannek additionally commented on the skilled progress conditions, studying modules and means MFAA customers have entry to.

    “Ongoing understanding is significant for our members to remain on main of adjustments in regulation and compliance, uncover methods to create their enterprises in a sustainable method and be fully able to harness new applied sciences,” she claimed.

    “From events resembling our National Conference to webinars, mastering modules and eBooks, all of the issues we do is produced with our customers in mind, so that they have the insights, inspiration and sources they need to excel.”

    Acknowledging the MFAA crew, Pannek talked about there’s deep trade information all through the organisation.

    “The full crew on the MFAA is totally commited to supporting our clients to allow them to proceed to supply the steering and help their clients worth,” she claimed.

    Pannek identified that concerning the earlier 4 many years, because the sector has developed and advanced, a lot too has the MFAA and can carry on to take action.

    “Today, the affiliation stays ever ready to help customers to think about benefit of choices and defend the trade from threats that would crop up into the long run.”

    What do you consider the MFAA’s advocacy efforts? Comment underneath.

    Related Tales

    Keep up with the newest information and occasions

    Be part of our mailing guidelines, it’s no value!