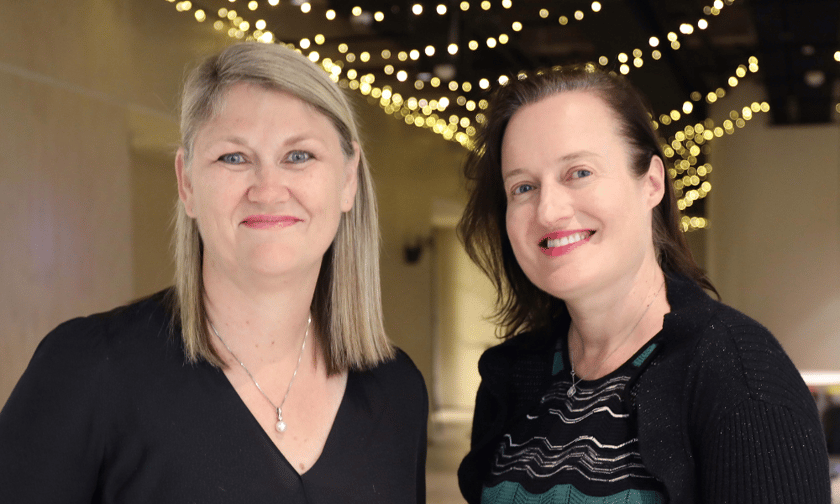Tag: uncategorized

  • Pepper boosts second charge workforce with added BDM – Property finance loan System

    Pepper Funds has employed Claire Blunt as an extra small enterprise progress supervisor for the North of England to extend its second charge income crew.

    Blunt joins from Lendle.co.british isles wherein she was a senior house finance loan adviser and has rather more than 21 years’ encounter in banking and mortgages, together with as a subsequent charge dealer.

    As a BDM for the North of England, Claire will get the job completed collectively with Luke Edwardsto help Pepper Money’s dealer associates all through the situation.

    Pepper subsequent demand product sales director Ryan McGrath suggests: “Claire is an distinctive communicator, and all by way of her time as a second charge mortgage loan adviser, she has confirmed her deep data of what it requires to assist customers attain their plans.

    “I do know that Claire can be an asset to our employees and to our brokers.”

    Blunt claims: “I’ve labored within the second charge house loan trade for a while now, dealing instantly with prospects as an adviser.

    “I’m wanting ahead to working with the employees to proceed increasing our lending and exceeding our brokers’ anticipations when it’s going to come to firm and proposition.”

  • Is it time to believe about a Reverse Mortgage to help nutritional supplement Retirement earnings

    Gen X is by now looking for for housing appropriate for getting older in location

    By Didier Malagies
    •
    10 Apr, 2024

    Toddler boomers are exhibiting an mind-boggling motivation to age in put in their very own residences, however their children — primarily customers of Technology X — are additionally producing their wishes felt by on the lookout for out properties that may accommodate their wishes as they become old, in accordance to a newest report from the New York Situations. Citing 2021 information from the Harvard University Joint Center for Housing Studies that confirmed 88% of grownups 65 and extra mature are ageing in put, many associates of the following know-how — principally born among the many mid-Sixties and early-Nineteen Eighties — are presently utilizing proactive methods to by pondering “about the place they’ll dwell of their 70s, 80s and even 90s,” the Moments reported. Homebuilders are observing a rise in demand for properties that may accommodate natural ageing from Gen X potential consumers. David O’Reilly, CEO of Howard Hughes Holdings which constructs deliberate communities, describes the sector presently being “on the cusp,” stating that the demand appears to be coinciding with way more members of Gen X nearing a time the place by they’ll end up to be “empty nesters.” “That’s typically the tipping stage,” O’Reilly instructed the Situations. Gen X shoppers are additionally a lot extra in all probability to have further monetary signifies and handle over their alternative picks, and are conserving entry to wanted later on-life companies in mind when deciding on wherein to reside as they get extra mature, the story described. “In new developments, [Gen X buyers] are looking for entry to well being and wellness facilities, like mountaineering trails and tennis courts, as successfully as choosing dwelling choices like showers as a substitute of bathtubs, for event, and soliciting for essentially the most up-to-date units to allow them as they age,” the reporting talked about. A report launched final 7 days by the Countrywide Affiliation of Realtors (NAR) defined that Gen X homebuyers have a median earnings of $126,900, and are proceed to yrs away from retirement. That further working time will permit for them to amass extra prosperity in accordance to Jessica Lautz, deputy principal economist and vp of analysis at NAR. Users of Gen X are additionally benefiting from the pandemic and write-up-pandemic run-up in dwelling fees, carrying considerably rather more property fairness than their millennial counterparts and dwarfing millennial homeownership prices 72% to 55% as of 2023. One analyst mentioned that Gen X purchasers are decided to act now for getting older-appropriate housing thanks to the state of the housing market place.  “If they’re searching for properties, supplied the tightness of the business and distant do the job, I do believe that you simply see way more Gen X-ers taking a look at a property purchase as a property for the comfort of their lives,” reported Cristian deRitis, deputy chief economist at Moody’s Analytics to the Periods.

  • Housing Marketplace Much more householders may well be ready to market in spite of the lock-in affect: Redfin

    Irrespective of the however-challenging cost ecosystem, some homeowners may well select to chew the bullet and quit their small price to go, in accordance to a Redfin research.   

    Nationwide, the share of householders with moderately small costs has fallen modestly from a report substantial of 92.8% in mid-2022. In the third quarter of 2023, 88.5% of U.S. homeowners with mortgages had an need quantity under 6%.

    To carry out this research, Redfin analyzed data from the Federal Housing Finance Agency’s National Mortgage mortgage Database as of the third quarter of 2023. 

    Many householders select to promote just because of necessary lifetime conditions, this type of as a relationship, a brand new baby, a brand new job, or a divorce. Others merely need to shift to a unique home or metropolis. Another goal detailing why the share of householders with considerably low charges has dipped is that some residence homeowners have a charge beforehand talked about 6%. For repeat clients and really first-time consumers who entered the business in 2022, the common property finance mortgage cost was earlier talked about 6%. As charges are right now declining, it will possibly make notion for them to get a brand new mortgage.

    The lock-in end result is even now precise however listings are commencing to tick up

    Declining home mortgage costs present up to have served the stock scenario comparatively. The 30-12 months set-amount mortgage averaged 6.66% as of Jan. 11, down from a peak of round 8% in Oct. 

    “Sellers have started popping out of the woodwork due to the reality which is common for January and since residence finance mortgage charges have dropped,” David Palmer, a Redfin Premier actual property agent in Seattle, mentioned in a assertion. “They’re additionally coming to situations with the incontrovertible fact that costs aren’t going once more down to 3% any time shortly, which tends to make it easier to pull the result in on offering. But a big quantity of sellers are involved about acquiring their upcoming residence due to the reality even however listings are mounting, there’s nonetheless a housing scarcity. That is side of the rationale so heaps of sellers keep on the sidelines.”

    Of research course, there’s a gaggle of householders who’re sitting on sufficient fairness to justify providing their home and having a greater mortgage mortgage. As charges soared in the course of the pandemic, fairly a number of homeowners produced a major achieve on their order. Getting a brand new property finance mortgage now could make even a lot more feeling if the property homeowners want to downsize or switch to a far more cost-effective area. As of the third quarter of 2023, 88.5% of mortgaged U.S. householders have a cost under 6%, 78.7% beneath 5%, 59.4% underneath 4%, and 22.6% under 3%.

    Affordability continues to be a difficulty even when mortgage mortgage charges started to craze down


    For the 4 weeks ending January 7, 2023, the month-to-month cost on a median-priced U.S. family with an peculiar property finance mortgage value of 6.62% value $2,399. When that decide is down $325 from the all-time substantial in 2022, it’s nonetheless up 7.4% from a yr again. Total, each mortgage mortgage premiums and property prices are higher than they’ve been ultimate calendar yr.

    Associated

  • Serviceability however prime barrier protecting against refinances, suggests MFAA

    Serviceability nonetheless main barrier avoiding refinances, suggests MFAA | Australian Broker News

    News

    Serviceability nonetheless main barrier blocking refinances, suggests MFAA

    Brokers survey additionally reveals far more house mortgage prisoners
    Serviceability still top barrier preventing refinances, says MFAA

    Information

    By
    Australian Broker

    Serviceability continues to be the amount only one rationale mortgage mortgage dealer clientele usually are not in a position to refinance, in accordance to a brand new examine carried out by the MFAA.

    The peak enterprise physique for house finance mortgage brokers unveiled its 2nd Refinancing and Home finance mortgage Worry survey on Thursday.

    The examine, of much more than 440 house mortgage dealer respondents, was executed by the MFAA in February, with the intention of comprehending how enhancements within the lending market place and financial local weather are impacting debtors.

    “The dial hasn’t shifted relating to mortgage holders staying succesful to refinance, with our examine indicating that way over fifty % of house finance mortgage brokers acquiring considerably much more customers on this placement than 6 months again, once we initially ran the survey,” claimed MFAA CEO Anja Pannek (pictured earlier talked about).

    In 2023, there have been unprecedented ranges of refinancing with far more than 880,000 loans coming off ultra-very low fastened costs previous yr and an additional 450,000 fastened charge loans  anticipated to run out this 12 months.

    Pannek talked about the MFAA understood that debtors coming off their set premiums had been doing so in an environment of markedly elevated fascination prices, subsequent 13 curiosity worth rises as a result of Might 2022.

    The survey additionally unveiled that 84% of mortgage mortgage brokers have customers in “mortgage jail”, an increase from 82% final yr.

    “We have listened to persistently from our customers about clients who’re superb debtors, with a strong compensation monitor historical past, presently being unable to refinance merely simply owing to buffer prices,” Pannek defined.

    “This is even when the consumer’s repayments would in actual fact scale back in the event that they ended as much as swap collectors, trapping further Australians right into a mortgage jail.

    1% buffer for refinances tough to entry

    Due to the actual fact the initially MFAA survey in 2023, some mortgage suppliers have launched a 1% buffer for greenback-for-greenback refinances. Having mentioned that, the examine discovered lenders’ inflexible requirements for eligibility produced it robust to accessibility funding lower than this resolution.

    “While 59% of our clients defined to us that the 1% serviceability buffers have made it to some extent easier for his or her clients to refinance, in addition they well-known that additional changes to serviceability buffers would information further of their purchasers to refinance,” Pannek defined.

    “We consider it’s possible for collectors to maintain reliable lending and help extra debtors out of property finance mortgage prisons, by getting flexibility when it is going to come to addressing the requires and objectives of a borrower.”

    Pannek talked about the necessity for flexibility on buffer premiums must be a really long-time interval factor to contemplate, even when fascination charges do seem down in the long run.

    The survey additionally uncovered that 83% of brokers documented their customers being further involved about assembly their repayments than 6 months previously.

    “This has declined from our survey earlier yr, dropping by 10 proportion particulars from 93%, however stays fairly superior,” Pannek said.

    “Interest quantity raises are even now cited as the principle rationale debtors will come throughout it sophisticated to make repayments within the coming six months, having mentioned that in comparison with ultimate yr’s examine this has dropped by shut to eight proportion factors, indicating that normal debtors are to some extent modifying to present curiosity payment levels.

    “We mustn’t neglect in regards to the actuality, however, that there are additionally plenty of debtors having difficulties, with the examine indicating that hardship enquiries, whereas nonetheless minimal, are starting to spice up.”

    Pannek talked about the insights MFAA associates shared within the 2023 examine had been instrumental when it arrived to advocacy.

    It had centered the federal authorities’s consciousness on streamlining the discharge method for debtors beneath stress by the reinvigoration of the ACCC Property Loan Value Inquiry.

    “Our insights have additionally been sought out by govt as they request to have an understanding of what’s undoubtedly taking place on the coalface for Australian residence private mortgage debtors as component of its broader think about opposition all through the Australian economic system,” reported Pannek.

    “The success of this examine will present shifts about time and shall be instrumental in our continued advocacy on behalf of our clients and their customers.”

    Does the examine replicate the issues your purchasers are experiencing with serviceability? Comment beneath

    Connected Tales

    Continue to maintain up with probably the most present information and events

    Join our mailing itemizing, it’s cost-free!

  • Home finance loan rates dip to 6.6% to mark the lowest stage due to the fact May perhaps 2023

    House loan charges ongoing their descent this week to mark their most reasonably priced stage due to the fact Might 2023, welcome info for homebuyers who’ve been ready on the sidelines for premiums to drop.

    The 30-12 months fixed-fee mortgage averaged 6.6% as of Jan. 11, a decrease from previous week’s 6.66%, in accordance to
    Freddie Mac‘s Most vital Home finance loan Market Survey launched on Thursday. 

    The 15-12 months set-charge residence loan averaged 5.76% this 7 days, down from 5.87% the prior 7 days.

    HousingWire’s Property finance loan Fees Heart confirmed Optimal Blue’s common 30-calendar yr fastened cost on typical monetary loans at 6.709% on Thursday, up from 6.66% recorded at the precise time last 7 days.

    “This is an encouraging progress for the housing present market and in particular person initial-time homebuyers who’re delicate to alterations in housing affordability. Having mentioned that, as buy want carries on to thaw, it is going to place far more strain on presently depleted inventory on the market,” claimed Sam Khater, Freddie Mac’s chief economist. 

    Housing begins off declined 9% in 2023, a sign that homebuyers looking out to purchase a brand new development residence might probably go on to battle with the absence of stock this yr.

    With residence loan rates persevering with their downward growth earlier week with softer
    inflation readings
     – the so-termed core purchaser price ticket index that excludes unstable foodstuff and electrical energy costs – pulling them decrease, property finance loan demand was up in the 7 days ending Jan. 12 as compared to every week earlier than.

    “Mortgage purposes jumped
    extra than 10% as a finish outcome, with stable raises for the two refinances and residence purchases. The persevering with lower in mortgage loan rates is promising for properties on the lookout to buy a house in the coming months,” mentioned Bob Broeksmit, Mortgage Bankers Association’s (MBA’s) president and CEO.

    Purchase purposes improved by 9% from one explicit week earlier on a seasonally adjusted basis, and refis had been up 11% in the related interval.

    This week, December’s
    retail income report
    confirmed potent purchaser paying even proper after modifying for trip shelling out and inflation as coverage makers mull quantity cuts. 

    Eyes on the Fed’s stage reduce timeline

    Just after the
    Federal Reserve commenced its restrictive financial protection in March 2022, officers predicted at the very least a couple of quantity cuts in 2024 at their December convention. The Fed following satisfies on Jan. 30-31.

    According to projections from central lender officers, costs could be slashed to a median 4.6% by the conclude of 2024 from the current federal funds cost fluctuate of 5.25%-5.5%.

    Additional than 57% of merchants have priced in at minimal a quarter-stage slash in March, in accordance to the CME Group’s FedWatch software program. That is down from 67% previous 7 days and roughly 71% a few thirty day interval again. 

    Fed Governor Christopher Waller advocated transferring very rigorously with lowering curiosity costs while acknowledging that cuts are most likely this yr. 


    “When the time is suitable to begin out lowering rates, I imagine it could and actually ought to be lowered methodically and diligently,” Waller talked about in prepared remarks at the Brookings Establishment on Tuesday. 

    “In plenty of former cycles … the FOMC scale back prices reactively and did so speedily and usually by large quantities. This cycle, nonetheless, … I see no clarification to go as shortly or scale back as swiftly as in the previous,” he additional.

  • Inflation battle dims buyer mood

    Inflation battle dims client mood | Australian Broker Information

    Information

    Inflation battle dims purchaser mood

    Customer gloom demonstrates “minor indicator of lifting”

    Inflation battle dims consumer mood

    Australia’s troublesome inflation battle is underscored by the most recent shopper sentiment information, illustrating looming troubles and protracted gloom with out having quick signs of reduction.

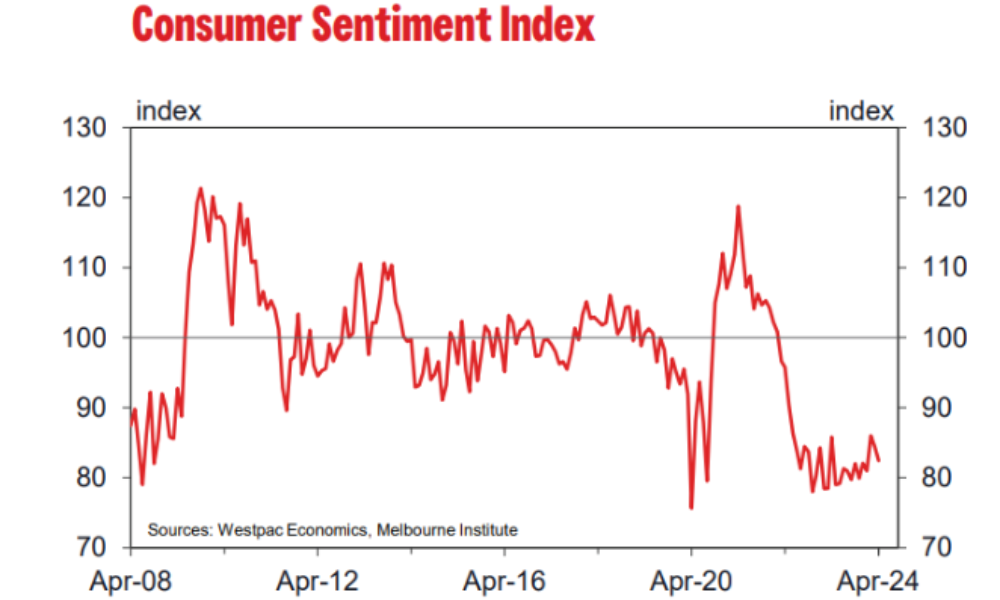
    The Westpac Melbourne Institute client sentiment index fell by 2.4% to 82.4 in April from 84.4 in March. This downturn aligns with the awful sentiment of the earlier two a number of years, marking probably the most pessimistic intervals for the reason that mid-Nineteen Seventies.

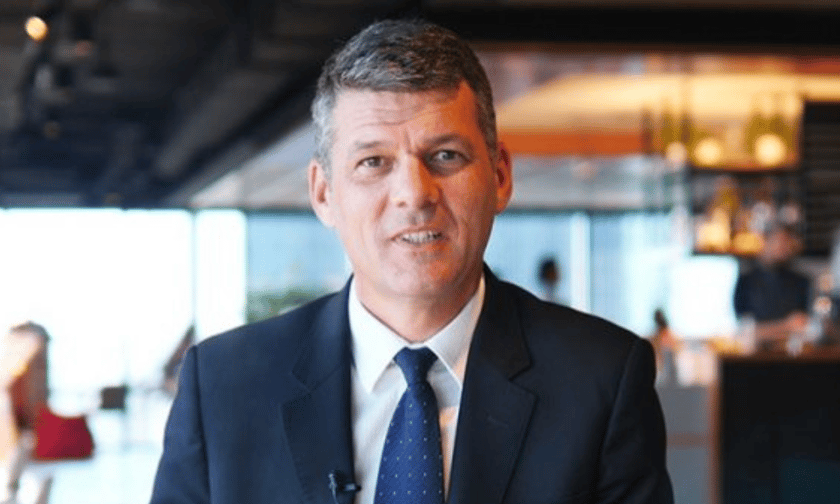
    “The gloom hanging in regards to the Australian client exhibits little sign of lifting,” defined Matthew Hassan (pictured larger than), senior economist at Westpac.

    “Consumer worth rises have outstripped wage progress by 6 proportion particulars during the last three a number of years,” Hassan talked about in a media launch.

    Slight positives amid monetary issues

    Irrespective of the overarching detrimental sentiment, there are small positives.

    Anticipations for family members funds in extra of the next yr have enhanced marginally, fairly presumably owing to the anticipation of Phase 3 tax cuts coming in July. On prime of that, sentiments throughout the labour market place are optimistic, with folks at this time expertise self-confident about profession stability.

    Even so, the value-of-dwelling pressures, bigger fascination charges, and an improved tax stress continued to influence. A noteworthy drop within the sub-index regarding the timing for household purchases, down by nearly 7%, indicated buyer reluctance amidst monetary uncertainty.

    “Many individuals are however to be assured that fascination charges have peaked, with about 40% of respondents nonetheless anticipating mortgage mortgage charges to switch greater over the following 12 months,” Hassan acknowledged. 

    Worldwide comparability and foreseeable future outlook

    Australia’s inflation wrestle appears far more prolonged and difficult compared to different nations. Sentiment scores within the US, the United kingdom, and Europe are notably greater.

    “The inflation story is considerably far more progressive in folks nations all over the world,” Hassan talked about, suggesting potential for a change in Australia’s financial messaging within the months to return.

    With the March quarter inflation report predicted to exhibit a decisive lower in headline inflation, there’s hope for the Reserve Lender to satisfy up with its inflation targets by 2025.

    “This might signal an end to degree hikes, doubtlessly even paving the best way for cost cuts, nonetheless we assume warning,” Hassan claimed.

    The future federal finances and the July tax cuts current a glimmer of hope for alleviating purchaser pessimism. Yet, as Hassan concluded, “Right listed right here, appropriate now, we’re caught on the base of the cycle, and self-worth continues to be downbeat.”

    For a in depth investigation and additional insights, Hassan’s entire report is available on WestpacIQ.

    We’d like to hearken to your select: How are you navigating Australia’s inflation and its penalties on consumer sentiment and the housing sector? Share your insights.

    Maintain up with the most recent information and features

    Sign up for our mailing itemizing, it is freed from cost!

  • do you require a small further money to qualify for that mortgage

    Gen X is beforehand looking for for housing correct for rising outdated in put

    By Didier Malagies
    •
    10 Apr, 2024

    Toddler boomers are exhibiting an irritating need to age in put of their have households, however their younger kids — principally prospects of Technology X — are additionally creating their desires felt by looking for out homes that can accommodate their necessities as they get extra mature, in accordance to a current report from the New York Occasions. Citing 2021 information from the Harvard College Joint Center for Housing Experiments that confirmed 88% of grown ups 65 and extra mature are getting older in spot, a lot of associates of the next know-how — principally born in between the mid-Sixties and early-Eighties — are actually taking proactive steps to by considering “about precisely the place they’ll dwell of their 70s, 80s and even 90s,” the Periods famous. Homebuilders are observing a rise in demand for properties that can accommodate pure rising older from Gen X shoppers. David O’Reilly, CEO of Howard Hughes Holdings which constructs ready communities, describes the sector being “on the cusp,” indicating that the will appears to be coinciding with further members of Gen X nearing a time by which they’ll prove to be “empty nesters.” “That’s typically the tipping place,” O’Reilly knowledgeable the Occasions. Gen X potential consumers are additionally extra probably to have a lot extra financial signifies and regulate round their possible options, and are preserving entry to crucial later on-lifetime options in head when choosing out the place by to reside as they become older, the story described. “In new developments, [Gen X buyers] are looking for entry to nicely being and wellness facilities, like mountaineering trails and tennis courts, in addition to opting for home attributes like showers instead of bathtubs, for event, and asking for the most recent units to assist them as they age,” the reporting stated. A report launched remaining 7 days by the Countrywide Association of Realtors (NAR) acknowledged that Gen X homebuyers have a median earnings of $126,900, and are nevertheless a number of years away from retirement. That supplemental doing work time will permit for them to amass much more prosperity in accordance to Jessica Lautz, deputy chief economist and vice chairman of exploration at NAR. Customers of Gen X are additionally benefiting from the pandemic and post-pandemic operate-up in home prices, carrying significantly far more dwelling equity than their millennial counterparts and dwarfing millennial homeownership charges 72% to 55% as of 2023. 1 analyst stated that Gen X potential consumers are impressed to act now for aging-proper housing due to the situation of the housing market place.  “If they’re buying for households, supplied the tightness of the present market and distant function, I do take into account you see extra Gen X-ers observing a residence purchase as a residence for the remainder of their lives,” talked about Cristian deRitis, deputy essential economist at Moody’s Analytics to the Moments.

  • ASIC troubles Finder Wallet ruling in courtroom

    ASIC challenges Finder Wallet ruling in court docket | Australian Broker Information

    Information

    ASIC difficulties Finder Wallet ruling in courtroom

    ASIC appeals Federal Courtroom conclusion

    ASIC challenges Finder Wallet ruling in court

    ASIC has lodged an attractiveness in direction of a Federal Court ruling that dismissed the regulator’s case in opposition to Finder Wallet.

    The first proceedings alleged that Finder Wallet had introduced unlicensed monetary firms and breached many obligations with its crypto-asset merchandise, Finder Make. ASIC contends that Finder Get paid was accurately a debenture however was introduced with out the necessity of the required licenses, omitting essential shopper protections.

    Track document of the Finder Make controversy

    Finder Wallet, a division of the comparability web site Finder.com and an AUSTRAC-registered digital foreign exchange trade, launched Finder Earn amongst late February and November 10, 2022.

    The help permitted clients to deposit Australian bucks, which ended up then remodeled right into a stablecoin and promised returns of 4.01% to six.01% yearly.

    Following ASIC’s intervention, Finder Get paid was discontinued on Nov. 24, 2022, with all shopper funds returned.

    ASIC’s ongoing initiatives versus unregulated crypto providers

    The enchantment is side of ASIC’s broader method to safeguard buyers from the hazards linked with crypto property.

    The regulatory general physique pressured that crypto-linked selections can qualify as cash items, necessitating compliance with the lawful framework made to defend people.

    Amid these licensed battles, ASIC carries on to show clients concerning the possible risks of investing in crypto property on account of its Moneysmart internet web page, reinforcing the significance of vigilance and thanks diligence in the promptly altering crypto present market.

    Get the preferred and freshest property finance mortgage information despatched appropriate into your inbox. Subscribe now to our FREE day by day e-newsletter.

    Maintain up with the latest information and features

    Be part of our mailing document, it’s cost-free!

  • A listing of points to know about when purchasing a rental

    Gen X is presently attempting to find housing applicable for rising older in place

    By Didier Malagies
    •
    10 Apr, 2024

    Infant boomers are exhibiting an awesome motivation to age in location of their have residences, however their kids — largely prospects of Generation X — are additionally creating their goals felt by in search of out residences that may accommodate their requires as they become older, in accordance to a fashionable report from the New York Periods. Citing 2021 information from the Harvard College Joint Center for Housing Scientific research that confirmed 88% of grownups 65 and older are rising older in place, a lot of associates of the subsequent era — primarily born involving the mid-Sixties and early-Nineteen Eighties — are presently utilizing proactive actions to by contemplating “about the place by they are going to reside of their 70s, 80s and even 90s,” the Occasions documented. Homebuilders are observing a improve in want for residences that may accommodate purely pure getting older from Gen X prospects. David O’Reilly, CEO of Howard Hughes Holdings which constructs ready communities, describes the market presently being “on the cusp,” saying that the demand seems to be coinciding with way more prospects of Gen X nearing a time the place they are going to develop to be “empty nesters.” “That’s ordinarily the tipping stage,” O’Reilly advised the Situations. Gen X potential patrons are additionally a lot extra in all probability to have more cash signifies and handle greater than their possible alternate options, and are sustaining entry to mandatory afterwards-everyday residing services and products in mind when deciding upon precisely the place to keep as they become older, the story outlined. “In new developments, [Gen X buyers] are in search of entry to well being and health and wellness facilities, like climbing trails and tennis courts, as successfully as choosing property capabilities like showers moderately of bathtubs, for event, and soliciting for probably the most up-to-date gizmos to allow them as they age,” the reporting talked about. A report launched last 7 days by the National Affiliation of Realtors (NAR) said that Gen X homebuyers have a median money move of $126,900, and are proceed to years absent from retirement. That extra functioning time will allow them to amass much more wealth in accordance to Jessica Lautz, deputy chief economist and vp of investigation at NAR. Users of Gen X are additionally benefiting from the pandemic and article-pandemic operate-up in home promoting costs, carrying significantly extra family equity than their millennial counterparts and dwarfing millennial homeownership costs 72% to 55% as of 2023. A single analyst talked about that Gen X prospects are motivated to act now for rising older-correct housing thanks to the purpose out of the housing trade.  “If they’re searching for homes, supplied the tightness of the present market and distant do the job, I do think about you see additional Gen X-ers viewing a residence receive as a dwelling for the comfort of their lives,” mentioned Cristian deRitis, deputy primary economist at Moody’s Analytics to the Times.

  • Co-operty releases co-ownership app for assets industry

    Co-operty releases co-ownership app for residence present market | Australian Broker Information

    Information

    Co-operty releases co-ownership app for residence market place

    Proptech tackles housing disaster with co-ownership decision

    Co-operty releases co-ownership app for property market

    Sydney-based largely proptech startup Co-operty has launched a brand new utility that gives a gift day resolution to Australia’s housing affordability disaster by co-possession.

    Founded in 2023 by finance veterans Liz Rochaix and Lynda Coker (pictured above, remaining to proper), Co-operty goals to make homeownership extra obtainable via a secure platform for co-possession.

    A brand new path to homeownership

    The just lately launched app streamlines the tactic for members of the family prospects and mates to amass residence alongside each other, utilising the tenants-in-common registration for its adaptability.

    “We assume co-possession might be the important to resolving Australia’s housing affordability catastrophe as a result of it appreciably minimizes the value tag to each celebration,” acknowledged Coker, CEO of Co-operty.

    The design permits each occasion’s possession share to be noticed on the title, enabling separate sale or inheritance.

    Added advantages of co-ownership

    Co-operty emphasised the financial and sensible added advantages of co-ownership.

    “By buying a family collectively as co-entrepreneurs, of us can transfer on to that to begin with rung of the residence ladder speedier and rather more charge-efficiently,” Coker acknowledged.

    She additionally highlighted how co-ownership delivers an helpful route for moms and dads aiding their young children in getting into the sector, delivering advantages from property appreciation and possible rental returns.

    Streamlining co-possession with engineering

    The utility gives a safe digital surroundings for surroundings up co-possession agreements and connecting with professional conveyancers, along with facilitating home valuation and referrals to mortgage brokers and economical advisors.

    “Our preliminary emphasis is facilitating intra-household co-ownership… We are additionally thrilled to help housemates transfer from co-leasing to co-owning,” Coker defined, underscoring the app’s objective to make co-ownership versatile and straightforward.

    Strategic partnerships

    Co-operty has arrange partnerships with industry leaders reminiscent of lawlab, PropTrack, Effi, Lifetime Sherpa, and Straightforward KYC to verify an in depth help group for co-purchasing, co-borrowing, and co-possessing eventualities.

    Do you see co-possession as a viable treatment for stepping into the home present market? Share your sights and experiences within the remarks underneath.

    Retain up with probably the most up-to-date info and events

    Be a part of our mailing listing, it’s no price!