Tag: uncategorized

  • What competencies are transferable from banking to broking?

    What methods are transferable from banking to broking? | Australian Broker Information

    Industrial

    What abilities are transferable from banking to broking?

    TOFU recipe for achievements, claims banker-turned-broker
    What skills are transferable from banking to broking?

    Commercial

    By
    Ryan Johnson

    Navigating the financial market supplies a number of paths, each main to distinct places.

    For Luke Hanlon, with complete personal banking data at Westpac, ANZ, and CBA, banking serves as a formidable organising degree.

    It provides a sturdy basis, enabling him to adeptly handle intricate lending eventualities and framework reductions for large-internet-really value purchasers.

    “I assume probably the most vital element banking has taught me is to typically put the consumer on the centre of each little factor you do,” stated Hanlon (pictured larger than), a senior dealer at Lending Loop AU.

    “I nonetheless vividly remember ‘TOFU’ – Consider Ownership and Observe Up – from my preliminary objective within the lender.”

    With brokers coping with myriad duties, compliance hurdles, and conflicting priorities every day, it actually is simple to shed sight of overarching targets. Hanlon underscores the significance of adhering to the TOFU concept, even in mundane duties.

    “It aids be sure to have glorious consumer service, this kind of as making an attempt to preserve customers present generally, getting proactive and on the doorway foot with any potential issues, creating deep private associations, and combating for the proper consequence for the patron if you at instances, for illustration, get pushback from credit standing,” Hanlon defined.

    “There is a great deal of emphasis for brand spanking new brokers to have mentors for credit standing and compliance, which I comprehend, however with shut to 20,000 brokers now you’re solely seemingly to be able to be efficient with distinctive providers, differentiating you, and including worth exterior the home of simply producing the consumer’s mortgage.”

    However, Hanlon reported a implausible mentor and aggregator should assist a dealer by means of all of those features.

    “Lending Loop and NLG have been implausible a lot.”

    The variance amongst brokerages and banking corporations

    Though Hanlon has the technique and ideas established to end up to be an efficient dealer, transitioning from banking typically entails a paradigm shift. 

    Financial establishments have various procedures and an finish outcome at one specific financial institution will be considerably distinct at one other, even for among the less complicated situations.

    Furthermore, brokers navigate a numerous array of mortgage supplier insurance coverage insurance policies and compliance protocols to guarantee ideas align with purchasers’ finest pursuits.

    “This will be hours of negotiating pricing with banks, researching monetary establishment insurance policies, finishing servicing calculators, workshopping situations with BDMs all through quite a lot of banking establishments, as opposed to simply doing work with a single set of procedures such as you do inside a financial institution,” Hanlon talked about.

    Nevertheless, it’s this versatility and the aptitude to make a wider affect that was so pleasing to Hanlon, who relishes the prospect to help purchasers with numerous monetary calls for spanning family loans, industrial property, SMSF lending, and personal funding for developments.

    “A dealer who can do that successfully is clearly a major earn for a shopper,” Hanlon reported. “Aggregator compliance can also be fairly numerous to lender compliance, so it’s receiving adjusted to not simply pleasant a particular financial institution’s specs but additionally doing an entire lot further due diligence on the rear of the scenes.”

    “Essentially, you are a dealer preliminary and private mortgage author subsequent.”

    The troubles of getting to be a dealer

    A problem for a number of new brokers will be cashflow, and presumably not taking a look at any cash are available for a number of months following commencing. Obtaining the suitable onerous money buffers upfront is important.

    Setting up a appear pipeline often takes time and customers with pre-approvals actually don’t purchase residence immediately. Then it’s much more time earlier than settlement and in the end having paid.

    Thankfully, Hanlon talked about he has “glorious enterprise mentors” who’ve taught him how necessary mindset is and working expectations.

    “Like any new enterprise enterprise on the start, you want to expect to function tough always working day in and day trip with out having reward,” Hanlon defined. “However, my answer is to do the perfect for my customers, and in the end the outcomes will seem.

    “Business is a prolonged-expression play and I’ve noticed from previous clientele that achievement isn’t in a single day however takes time. If you do an distinctive work on your clientele, they’ll refer you to their friends and family members, and that is the way you assemble a enterprise about time.”

    The main problem Hanlon reported he skilled confronted so considerably in his 4-month journey was readjusting his time administration and “juggling so quite a lot of issues for the time being despite the fact that studying”.

    “As a dealer you are the jack of all trades – you may have to be glorious at shopper acquisition, promoting and advertising and marketing and branding by yourself (with out having the numerous standing of a financial institution behind you), enterprise progress, speaking to a continuous transfer of recent consumers and comprehending their wishes, researching credit score rating throughout a number of banks to make ideas, crafting monetary mortgage apps, and making an attempt to preserve customers up to date to make sure a clear course of… All while the cellphone is ringing incessantly.”

    Of course, a stable function ethic is vital – however so is useful time administration, claimed Hanlon.

    Hanlon claimed every morning he writes a guidelines of issues to do and teams jobs collectively and time blocks to end them without delay.

    “For instance, all my examine out-in calls to purchasers inside progress applications are accomplished in the midst of a specific window,” he defined. “I’m receiving higher at this because the months go by.”

    What did you perceive if you grew to become a dealer? Comment beneath.

    Associated Tales

    Hold up with probably the most up-to-date information and events

    Be a part of our mailing guidelines, it is freed from cost!

  • Freddie Mac would acquire home fairness financial loans below FHFA proposal

    An influential government-related home finance mortgage investor vigorous within the 1st-lien market may flip right into a purchaser of some residence-fairness financial loans beneath a method its regulator place forth late Tuesday.

    Freddie Mac would actively put money into some shut-finish 2nd liens if it retains the first home finance mortgage lower than a proposal the Federal Housing Finance Agency launched according to its pre-acceptance rule for brand new merchandise.

    The proposal is a brand new acquire on just a little one thing Freddie dabbled in many years in the past, despite the fact that within the prior occasion these financial mortgage purchases got here to a nonmaterial quantity. This time all-around, the financial loans would be positioned as a substitute for money-out refinances which have come to be uneconomic for the fairly a couple of extra mature loans originated at reduce-than-recent-current market costs.

    “The proposed motion is supposed to current property homeowners with a charge-successful substitute for accessing the fairness of their residences,” defined FHFA Director Sandra Thompson in a information launch.

    It additionally may have synergies with housing purposes like Freddie’s Inexpensive Seconds. The enterprise has relied on different entities to fund the second liens employed to help improve homeownership alternate options for debtors and the brand new merchandise may broaden its attain.

    Stakeholders may have 30 days to comment on the proposal. The FHFA will determine whether or not to switch forward with the proposal inside simply the next 30 instances, with the pending federal election in November possible together with some urgency for fast decision-generating on the difficulty.

    The technique outlined addresses a sure need inherent within the composition of the most recent market place however how receptive the mortgage mortgage business shall be to it would rely on some nonetheless-to-be specified info.

    “I think about it truly is an intriguing difficulty in time precisely the place laborious cash-out refinances by no means pencil out from the patron viewpoint,” stated Pete Mills, senior vp of residential coverage and member engagement on the Home mortgage Bankers Association. 

    The extent to which it addresses that downside would possibly depend on what Freddie Mac will give you for the following lien it buys and what any linked mortgage-stage pricing adjustments are like, a factor the comment time period would possibly situation.

    “We have not observed pricing or LLPA grids, or something in any respect like that, so it actually is just a little early to clarify to, however I suppose the numerous issue listed right here is which is sort of the extent of the brand new train system,” Mills acknowledged.

    How depositories react to the technique continues to be to be seen. To a diploma, closed-conclude seconds compete with HELOCs, however usually holding the earlier in portfolio shouldn’t be stunning to financial establishments, for whom traces of credit score rating are a greater match with their deposits. Some nonbanks might maybe market shut-close seconds to the private secondary business but it surely actually is regarded a minimal sector.

    “Absolutely that shall be part of the dialogue within the comment methodology round what sector need to have is that this serving?” Mills reported, referring to 1 of the components elevated in a group of questions the FHFA suggested commenters sort out.

    As a authorities-sponsored firm, Freddie Mac might probably be prepared to offer at decrease-than-market place charges for closed-conclude seconds, significantly if it may possibly sooner or later amass enough merchandise for securitization and deal with the loans’ pitfalls with out the necessity of making approach too quite a few pricing changes for them. 

    These financial loans by nature are riskier than first liens supplied their subordinate placement, however Freddie does counsel some guardrails aimed toward defending their general efficiency. These incorporate 20-12 months mounted costs, a completely amortizing construction, and financial loan-to-value ratios constrained to 80% or 65% for produced residences.

    “Credit historical past threat switch prospects would be evaluated in subsequent phases,” the proposal additionally noticed.

    Land believe in and cooperative share financial loans would not be eligible. The illustration and guarantee framework would be neutral from that of the very first home loans.

    Even inside simply restrictions on key financial mortgage selection, the mixed LTV and different variables, the amount may very well be sizeable, significantly if every Freddie and its greater competitor, Fannie Mae, ended as much as flip into energetic on this place, Bank of The usa researchers wrote in a report Wednesday.

    “For home loans owned by the 2 GSEs, fairness extraction may very well be as considerably as $1.8 trillion on sub-4% home mortgage financial loans, conserving the CLTV beneath 75%,” they acknowledged.

    Closed-conclusion seconds may pose significantly much less threat for Freddie than dollars-outs and put extra decisions about distressed financial loans in its fingers versus a servicer’s, in accordance with the Lender of America researchers.

    “Freddie Mac would have a decreased credit score rating initially on a blended decrease initial-charge lien and a superior quantity next-lien than a superior-level funds-out refi financial institution mortgage partly owing to the shorter time period on the following,” they defined. “Acquiring possession of each of these the initially lien and the second lien mortgage would enable for Freddie Mac to have a lot better handle over decline mitigation insurance coverage insurance policies.”

    The proposal seems aimed toward sustaining the servicing comparatively according to that of preliminary home loans, with decline mitigation and foreclosures pursuits for all of the loans requiring Freddie Mac approval. If the very first lien is refinanced, the 2nd need to be paid off absent any jurisdictional approved prohibitions in opposition to it.

    The seconds would be manually underwritten and supplied outright through the earnings window in minimal parts to get began. They would not promptly be appropriate for ahead supply or the to-be-introduced present market. They’d be held for six to 9 months till non-TBA securitizations may very well be arrange.

    Freddie would sooner or later intention to produce computerized underwriting for the home fairness financial loans. 

  • Tenants see file bounce in non-public rental charges – House loan Finance Gazette

    Personal rents in the British isles ongoing to rise at a significantly sooner quantity than inflation, with tenants observing housing bills improve by 9.2% in the 12 months to March 2024.

    later-life-housinig-wealth-620x330.jpg

    This is an maximize on the 9% annual improve recorded the sooner month, in line with the Business workplace of Nationwide Data, and is the best once-a-year bounce contemplating the truth that this data was first collated in 2015.

    These figures clearly present that essentially the most important lease improves have been being in Scotland. Overall the everyday each month rent compensated in England now stands at £1,285, a 9.1% increase. In Wales the conventional lease is £727, a 9% enhance when in Scotland the abnormal rent is  £947 — a ten.5% improve.

    In Northern Ireland  regular rents better by 10.1 per cent in the 12 months to January 2024.

    Further extra regional breakdowns exhibit that in England lease raises have been finest in London at 11.2% across the previous 12 months. The North East had the most cost effective common improve at 6.1%.

    Homes in Kensington and Chelsea in London skilled the utmost abnormal common month-to-month rents, at £3,305. The lowest regular rents have been in Dumfries and Galloway in Scotland, wherever tenants compensated an month-to-month abnormal of simply £475.

    Commenting on these figures Hargreaves Lansdown head of explicit finance Sarah Coles says: “There’s no let-up in the squeeze on renters, as rents have been being up 9.2% in a calendar yr – a file because the information was first gathered in 2015.”

    She claims  current figures from the Royal Institute of Chartered Surveyors (Rics) show why rents are persevering with on this upward trajectory. “The number of new tenants has risen every particular person one month because the present market reopened instantly after lockdown. In the meantime, the quantity of landlords has been falling provided that summer season months 2022, and has solely briefly been in good territory for a handful of months as a result of 2017.”

    She provides: “Rising residence value ranges and bigger house finance loan charges, coupled with more durable taxes and extra stringent insurance policies all-around permitting residence, suggests the portions have stopped together with up for large numbers of landlords, who’ve been steadily offering up and having out of the enterprise.”

    She claims that whereas these rules have been being geared toward safeguarding renters, with elevated taxes developed to stop landlords shopping for up qualities from possible 1st-time clients, the end result has been much less landlords which is placing further stresses on renters because of a scarcity of provide in the business.

    Coles provides that when regular private rents could maybe be corresponding to property finance loan funds households that lease ordinarily receives a commission a lot much less, leaving a few of these households extra monetarily susceptible.

    Former Rics family chairman and north London property agent Jeremy Leaf, claims: “Rents are proceed to growing in response to the persevering with imbalance in between supply and demand.” He supplies that as we speak’s announcement that the cost of inflation has fallen will provide some help for these tenants.

  • Rents increasing at speediest ever level – Mortgage Method

    Private rents within the British isles continued to extend at a a lot faster value than inflation, with tenants seeing housing costs rises by 9.2% within the 12 months to March 2024.

    This is a rise on the 9% once-a-year improve recorded the sooner thirty day interval, in response to the Business workplace of National Statistics, and is one of the best once-a-year soar because of the truth this particulars was to begin with collated in 2015.

    These figures current that the most important rent will increase had been being in Scotland. Over-all the bizarre month-to-month hire paid in England now stands at £1,285, a 9.1% enhance. In Wales the widespread hire is £727, a 9% maximize although in Scotland the traditional hire is  £947 — a ten.5% enhance.

    In Northern Ireland  widespread rents elevated by 10.1 per cent within the 12 months to January 2024.

    Even additional regional breakdowns clearly present that in England lease will increase have been biggest in London at 11.2% in extra of the earlier 12 months. The North East skilled the most cost effective common enhance at 6.1%.

    Properties in Kensington and Chelsea in London skilled the best regular month-to-month rents, at £3,305. The most reasonably priced regular rents had been being in Dumfries and Galloway in Scotland, the place tenants paid an common bizarre of simply £475.

    Commenting on these figures Hargreaves Lansdown head of personalised finance Sarah Coles suggests: “There’s no permit-up within the squeeze on renters, as rents have been up 9.2% in a yr – a file as a result of the data was first collected in 2015.”

    She suggests  current figures from the Royal Institute of Chartered Surveyors (Rics) exhibit why rents are persevering with on this upward trajectory. “The number of new tenants has risen each solitary month as a result of the present market reopened simply after lockdown. Meanwhile, the number of landlords has been falling as a result of summer time 2022, and has solely briefly been in beneficial territory for a handful of months contemplating the truth that 2017.”

    She provides: “Rising residence prices and better dwelling mortgage prices, coupled with extra sturdy taxes and much more stringent guidelines throughout permitting residence, often means the numbers have stopped including up for large numbers of landlords, who’ve been progressively promoting up and discovering out of the group.”

    She says that though these rules had been aimed at safeguarding renters, with elevated taxes made to stop landlords buying up attributes from potential initially-time consumers, the end result has been fewer landlords which is putting further stresses on renters due to to a deficiency of supply within the business.

    Coles provides that when common personal rents could maybe be much like dwelling mortgage funds houses that lease generally earn loads much less, leaving a few of these households extra economically vulnerable.

    Former Rics family chairman and north London property agent Jeremy Leaf, says: “Rents are even now climbing in response to the persevering with imbalance involving present and want.” He gives that right this moment’s announcement that the quantity of inflation has fallen will ship some help for these tenants.

  • Do you need to have a Bridge loan for a industrial task or a household flip

    Bridge loan to purchase, renovate, and stabilize a multifamily monetary dedication residence. When the rents are beneath {the marketplace} and the items are out-of-date. This system permits you to obtain a residence beneath business worth and make magnificence updates to increase rents.

    how about capitalizing the fit-up of retail/administrative center expenditure residence?

    We additionally have flip-resolve monetary loans for residential.

    6 to 24 months

    loan quantities from $250k to 20 Million

    Interest solely

    1 to 3-7 days closing durations

    tune in and discover out a lot extra at https://www.ddamortgage.com/weblog website

    Didier Malagies nmls212566

    DDa House loan nmls324329

    Check with a House loan Concern

    Use the shape beneath and we are going to give your our specialist responses!

    Get began Your Personal loan

    with DDA at the moment

    Your neighborhood Property finance loan Broker

    House loan Broker Largo

    See our Assessments

    Seeking for rather more particulars? Hear to our extended podcast! 

  • Desire level movements – RateCity reveals the hottest

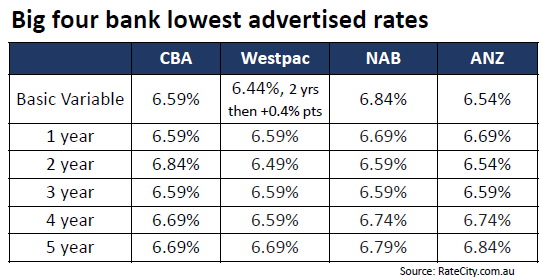
    “This alter was not so considerably a range by the monetary establishment to present big bargains to possible new clients taking out its bundle mortgage, however considerably a strategic choice to superior align its marketed costs with the expenses that patrons shut up getting,” Tindall reported.

    “For a very long time, monetary establishments – the important banking corporations, in sure – have utilized a strategy whereby they promote unrealistically substantial promoting costs on their bundle dwelling monetary loans which then will enable them to offer clients sizeable individualised ‘reductions’ from this worth. NAB’s shift follows a associated resolution by CBA to drop its bundle home mortgage cost costs in November 2022, leaving each of these Westpac and ANZ with inflated larger charges.”

    Other mortgage suppliers additionally modified their expenses, although Tindall well-known a significant slowdown in fee variations amongst the the extra than 115 collectors listed on the RateCity.com.au database.

    Auswide Financial establishment decreased its charges for operator-occupier, variable, and principal and curiosity monetary loans with LVRs involving 90% and 95% by .45 proportion particulars, bringing the worth down to six.89%. Equally, Queensland Country Bank decrease its a single-year mounted worth for owner-occupiers with an LVR beneath 80% by .30 proportion components to six.19%.

  • Company turnover sees blended final results in February

    Enterprise turnover sees mixed outcomes in February | Australian Broker News

    News

    Organization turnover sees mixed advantages in February

    Mining turnover plunges amid slipping commodity prices

    Business turnover sees mixed results in February

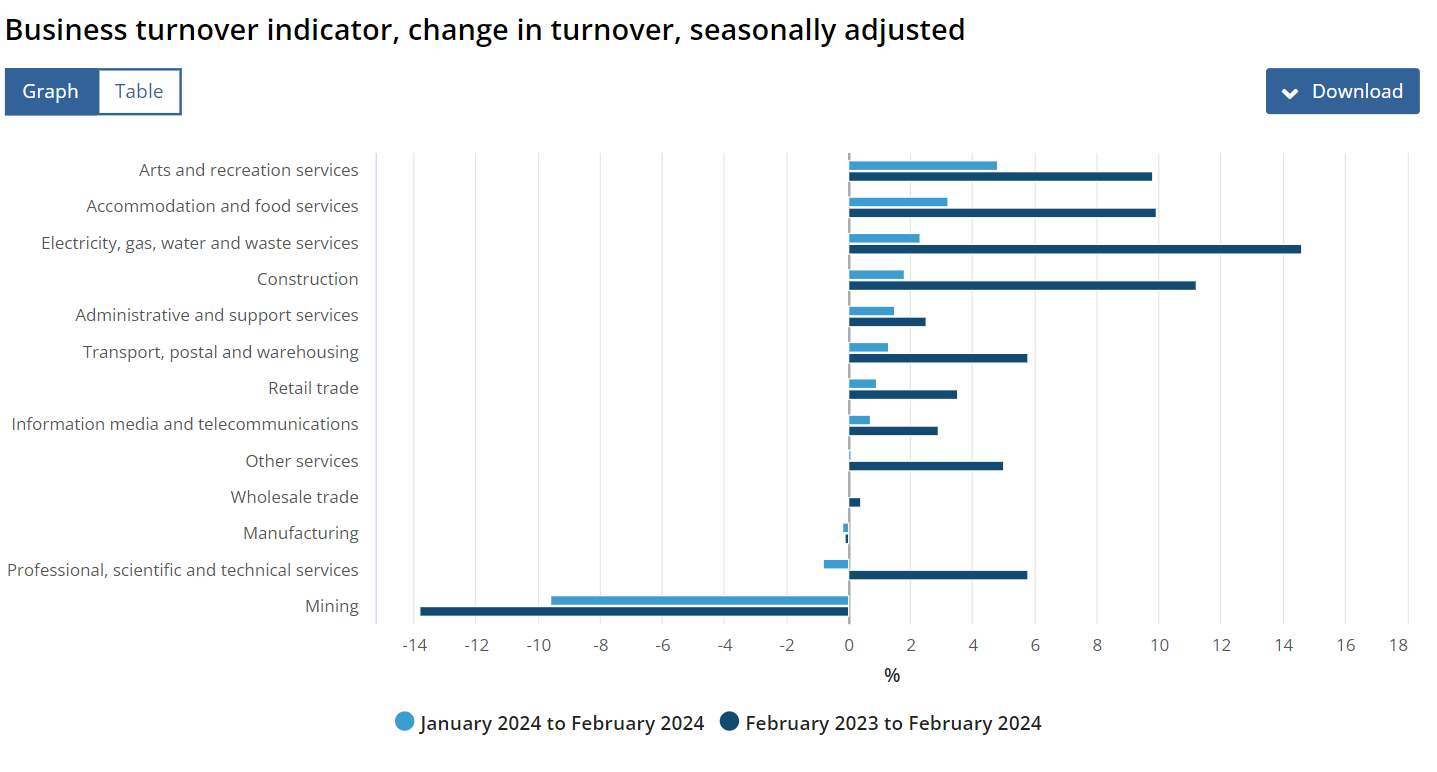
    The experimental Monthly Business enterprise Turnover Indicator (MBTI) for February 2024 confirmed a combined financial panorama with a 1.1% cut back in the seasonally altered 13-field combination, largely pushed by a sizeable decline in mining, Abdominal muscle groups documented.

    Sharp drop in the mining sector

    The downturn was most pronounced in the mining sector, which noticed a vital drop of 9.6%.

    “The massive tumble in mining drove the 1.1% drop in turnover for the 13-marketplace mixture. This was even with solely three of the 13 industries demonstrating a slide,” claimed Robert Ewing, Abdominal muscle groups head of small enterprise knowledge, in a media launch.

    The lower in mining turnover is usually attributed to slipping commodity value ranges, notably iron ore. Nevertheless, this was partly offset by a 5.1% enhance in the oil and gasoline extraction subdivision, reflecting some resilience in simply the broader mining sector.

    Sector effectiveness overview

    In sample phrases, the 13-business combination noticed a slight discount of .1%, marking the to start out with common drop contemplating the truth that August of the previous 12 months.

    General, 11 out of 13 industries monitored confirmed 12 months-on-yr improves.

    Year-on-year progress and declines

    Comparatively, February 2023 confirmed a helpful development with 11 out of the 13 industries recording higher turnover.

    The industries with probably the most important yearly raises bundled power, gasoline, consuming water, and waste suppliers (14.6%), design (11.2%), and lodging and meals gadgets suppliers (9.9%). On the flip aspect, the mining sector not solely led the month to month downturn but additionally marked the largest annual fall with a 13.8% reduce, Abdominal muscle groups claimed.

    Get the most well-liked and freshest mortgage mortgage information delivered appropriate into your inbox. Subscribe now to our FREE day by day publication.

    Retain up with probably the most present info and gatherings

    Be a part of our mailing itemizing, it’s no price!

  • Senate bills address rural housing and tenant protections

    Lawmakers are pushing to maneuver Senate funds that include what has been defined as essentially the most vital rural housing reform in years. 

    Gurus spoke in favor of the Rural Housing Assistance Reform Act Wednesday earlier than a small viewers of the Senate Committee on Banking, Housing and City Affairs. The bill amongst different steps would replace residence mend financing initiatives and protect a whole lot of numerous numbers of renters at houses wherein federally sponsored residence loans are maturing. 

    “This legal guidelines is heading to make prolonged overdue updates to RHS packages which can be actually important,” defined Robin Davey Wolff, senior director of rural communities at Enterprise Group Companions, a housing non-financial acquire. 

    A bipartisan group of senators within the Housing, Transportation and Group Improvement subcommittee have been being optimistic however noncommittal on having a vote on the act by the shut of the yr. Bipartisan U.S. Associates have launched an identical variation within the Residence. 

    The invoice’s widest have an effect on would deal with a hazard coping with rural renting housing monetary loans. Four hundred thousand low-income tenants would acquire rental steerage at properties which have these Division of Agriculture-sponsored loans. Passage of the act would decouple rental assist from these folks residence loans, shielding 137,000 low-revenue renters at properties with these monetary loans maturing sooner or later 10 a number of years.

    The act would additionally make it rather a lot simpler for nonprofits to get these houses, in accordance with Minnesota Sen. Tina Smith’s enterprise. The Democrat and sponsor of the bill defined her residence situation has essentially the most of these folks mortgages maturing than any the place else within the nation.

    The month-to-month invoice would additionally make long-lasting a neighborhood improvement fiscal institution fund for Native American communities, and still-to-be-decided further funding for applied sciences updates for rural housing options. 

    Pennsylvania Sen. John Fetterman, a Democrat, and Wyoming Sen. Cynthia Lummis, a Republican, additionally promoted their Total-Property Repairs Act, which might develop a five-yr pilot centered on a plan in Fetterman’s situation. The system would create a restore grant system for low- and moderate-revenue property house owners. 

    Several residences are irreplaceable in that they might not or wouldn’t be modified because of the truth of the absence of financial incentive to create new models, acknowledged Jesse Ergott, president and CEO of NeighborWorks Northeastern Pennsylvania.

    “Likewise, when you will discover intensive deferred servicing, there is not actually an financial incentive for consumers to amass these homes in plenty of markets,” he defined. 

    Qualified witnesses in distinction the pending funds to stalling assist in Congress. The Community Enhancement Block Grant software program has been flat-funded because of the truth fiscal 12 months 2022, Wolff acknowledged, despite the fact that the Department of Housing and Urban Development’s Property Investment determination Partnerships Program obtained $250 million fewer funds within the earlier fiscal yr. 

    The drive by lawmakers follows the Biden Administration’s merely name for bipartisanship in carrying out housing ambitions. The area within the meantime has had a tepid response to the White House’s bigger sized goals in housing, like a controversial title insurance coverage pilot plan. 

  • Principality BS lifts resi charges by up to 21bps, Accord by 19bps   – Home loan Tactic

    Principality Setting up Modern society will improve picked family fixed-charge residence loans by up to 21 foundation factors, though Accord will carry some landlord and merchandise switch provides by as an excellent deal as 19bps.  

    The mutual will increase, which come to market tomorrow (18 April), defend:    

    Two- and 5-12 months 75% LTV options rise by up to 20bps  

    Two-year 80% LTV merchandise improve by up to 20bps  

    Two-12 months 85% LTV merchandise improve by up to 21bps  

    Two-yr 90% LTV merchandise rise by up to 13bps  

    Two- and 5-12 months 95% LTV merchandise improve by up to 15bps  

    The shift will see its two-calendar 12 months 75% LTV dwelling loan restore supplied at 4.89%.  

    In the meantime, Accord will elevate acquire to enable and merchandise transfers from Friday (19 April).  

    Yorkshire Building Society’s broker-only lender claims its will increase will see:  

    Two-year charges improve by 15bps  

    Three-12 months charges improve by up to 19bps  

    5-12 months prices rise by 15bps  

    Its current fluctuate will probably be withdrawn at 8pm on 18 April, with the brand new fluctuate out there at 9am on 19 April.  

    John Charcol web advertising and marketing supervisor Nicholas Mendes says: “The market is in dire have to have of some optimistic motion from the Lender of England, till we see a stage discount we’re going to see a interval of quantity will increase as marketplaces begin out to grow to be unsettled.  

    “Mortgage holders coming to the top of their set-amount promotions this calendar 12 months and in early 2025 will want to have to be ready to see prices increased than skilled earlier than been predicted.   

    “Initial forecasts of a 3.5% fixed-fee dwelling finance loan supply by August to late September are fairly unlikely, with any sign of those sorts of a deal now pushed again to afterward within the 12 months.”