Tag: uncategorized

  • ONS house price index shows .2% drop – Home loan Finance Gazette

    The regular house price tag within the British isles fell by .2% within the 12 months to February this calendar yr, the most recent ONS House Price Index shows.

    houseprice8-620x330.jpg

    The drop was considerably sure than the 12 months prior, when property fees dipped by 1.3%.

    Even with the yearly fall, promoting costs rose .4% from January with the common British isles property now providing for £281,000.

    In England, price ranges fell within the 12 months to February by 1.1% to an bizarre of £298,000 and in addition dropped in Wales, down 1.2% to £211,000. Nevertheless, they rose noticeably in Scotland, up 5.6% to an regular £188,000 within the 12 months to February, the ONS states.

    MT Finance director of house Tomer Aboody claims: “With fees growing month-on-thirty day interval, we’re viewing the power in demand from clients and assurance inside purchasers who’re having fringe of steading curiosity charges and cut back inflation.

    “However, with income volumes noticeably decreased than final 12 months, bigger want in comparison with decreased supply will at all times thrust fees up.

    “Sellers wish to be impressed to go in buy to spice up availability of inventory within the sector, and a few motion in stamp obligation charges would help.”

    Atom Bank head of mortgages Richard Harrison claims: “The cut back in house price ranges famous now proceeds the event of successive drops contemplating that the middle of final yr, however regardless of this there are alerts of hovering self worth quantities amid potential consumers.

    “We have presently discovered improved ranges of exercise within the property market of late subsequent a time interval of relative steadiness.

    “Data from Rightmove for instance uncovered that the variety of product gross sales in March was up by 13% on a 12 months up to now, when there was an 8% improvement in shopper want as purchasers press prematurely with strikes they might effectively have placed on maintain on the cease of 2023, when residence charge indices from Nationwide and Halifax have demonstrated promoting costs on the rise.”

  • Shawbrook trims BTL premiums – Mortgage Technique

    Shawbrook has diminished prices on picked receive to let merchandise by as much as 30bps.

    The price cuts are all through its elaborate and constrained version BTL ranges for debtors getting out bigger sized monetary loans of amongst £1m and £5m.

    In its subtle BTL differ Shawbrook will now demand a  price of 6.34% on its 5 and 10-calendar 12 months mounted charges as much as 65% LTV. For all these borrowing as much as 75% LTV the premiums is 6.44% — a slash of 30bps.

    In this array it has additionally decrease the worth of its 3-yr, and two-year preset prices. Its three-year fixes will now begin out at 6.49% (at 65% LTV) although its two-calendar 12 months fixes have been decreased to six.54% at 65% LTV and 6.64% at 75% LTV.

    Shawbrook has additionally designed alterations to its restricted model difficult BTL merchandise, another time for loans in between £1m and £5m, this time all through its two- and five-yr set-charge options.

    Its five-yr mounted expression monetary loans have been decreased to five.84% at 65% LTV, and 5.94% at 75% LTV. Meanwhile its two-year fixes  been decreased to five.44% at 65% LTV and 5.54% at 70%.

    Shawbrook director of actual property proposition Daryl Norkett suggests: “These latest pricing reductions show our stable starvation to help brokers and professional landlords with an enormous various of lending items.”

  • Southeast House loan of Ga, Inc.: Our Vision

    Southeast Mortgage of Georgia, Inc.

    Tuesday, October 16, 2018

    Our Eyesight – Southeast Home finance loan

    www.southeastmortgage.com
    Cellular telephone: 770-279-0222


    Cal Haupt, Chairman and Chief Govt Officer, Southeast Property finance loan of Georgia, Inc.

    3575 Koger Blvd.
    Suite 400
    Duluth, Ga 30096
    Cell telephone: (770) 279-0222
    Fax: (770) 279-9141
    Georgia Residental Mortgage loan Licensee #6578
    NMLS #103956

    Direct Non-Financial establishment Loan supplier – Fannie Mae & Freddie Mac Vendor/Servicer, HUD Title II Immediate Endorsed FHA

    Direct Non-Bank Lender - Fannie Mae & Freddie Mac Seller/Servicer, HUD Title II Direct Endorsed FHA

    Licensed House loan Bank loan Officers you possibly can Trust!

    Is your Originator Registered or Licensed? Click on the hyperlink under to find out.

    Is your Originator Registered or Licensed? Click the link below to find out.

    Accredited Originators have handed a competency examination and are approved by the Point out. Seem for a Point out License# and NMLS#

    Test out your Bank

    Check out your Bank

    Click on to see your Bank’s Latest financial advantages

    SaportaReport – Southeast House loan Imagined Leadership – Sector Pro

    SaportaReport - Southeast Mortgage Thought Leadership - Industry Expert

    Cal Haupt, Chief Govt Officer

    Imagine Large Get the job completed Compact “Look at out Southeast” Click on to view

    Think Big Work Small

    Brian Stevens & Frank Garay Advise Southeast Mortgage loan

    Like us!

    Like us!

    Click on the Icon to Look at Out our Fb Web website

    Keep newest on breaking data


    Stay current on breaking news


    Simply click on the Icon to Join Us on Twitter

    Our Promise contemplating that 1993

    1. Supply proficient home loan steering from Certified Property finance loan Mortgage Originators
    2. Develop innocent mortgages for our clientele that swimsuit their necessities
    3. Supply Rapidly, On-Time, and Accurate Closings

    We are the Largest Local Non-Lender Home finance loan Lender in Georgia with Certified Mortgage Originators to defend your partner and kids. We are the Lender you possibly can Belief with the Provider and Certifications your Loved ones justifies.

    This Website is ready and managed by me to tell our customers and associates of important developments within the dwelling loan sector and provide an inside look at what is happening at Southeast Property finance loan. Thank you on your imagine in and patronage.

    Cal Haupt
    Chairman and Chief Government Officer
    Cellphone: 770-279-0222
    E-mail: Cal@SoutheastMortgage.com
    Take a have a look at our Site: www.southeastmortgage.com

  • Robust work report implies fee cuts won’t occur ‘til summer months

    Though all indicators place to a cooling labor market all spherical, the general economic system picked up yet one more 275,000 careers in February. The positions report on Friday shouldn’t be prone to affect the Fed that fee cuts are very important when the Federal Open up Markets Committee satisfies later this month, economists talked about.

    Positions elevated by 275,000 in February, up from a revised cost of 229,000 in January, in response to particulars produced by the Bureau of Labor Statistics on Friday. February’s studying exceeded the common month to month attain of 230,000 over the prior 12 months.

    The nationwide unemployment degree ticked up for the to start out with time in 4 months to three.9%, its biggest stage as a result of January 2022, however nonetheless down beneath the entire work quantity of 4%. The vary of unemployed Us residents additionally rose to six.5 million.

    “While unemployment remains to be lowered, the leverage held by employees is weakening,” Shiny MLS important economist Lisa Sturtevant claimed in a press release. “Job seekers are taking extra time to uncover function, and the number of activity switchers has declined.”

    Position positive factors occurred primarily in properly being care, authorities, meals suppliers, social assist, transportation and warehousing. In the meantime, retail commerce, mining, quarrying, oil and gasoline extraction, manufacturing, wholesale commerce, info, and cash actions posted much less careers in February.

    All by means of his semiannual monetary coverage testimony on Wednesday and Thursday, Federal Reserve Chair Jerome Powell reiterated that the Fed sees no urgency to chop charges simply nonetheless. Powell pressured that the Fed desires further assurance that inflation is on a sustainable route in direction of its goal forward of making any strikes.

    Ordinary hourly earnings for private-sector employees grew by .1% month greater than month to $34.57 and had been up 4.3% from a calendar 12 months previously. In February, work continued to pattern up in constructing, introducing 23,000 jobs month round month. Career openings had been primarily unchanged at 8.9 million at a cost of 5.4%, down from 10.4 million the prior calendar 12 months. Meanwhile, occupation quits remained common at 3.4 million though the worth shrank to 2.1%.

    The employment report is made up of two conflicting implications for the housing business, in response to Sturtevant.

    On the one hand, the mounting uncertainty amid enterprises and employees prompted by high-fascination charges might additionally make property customers wearier about creating important fiscal selections. On the opposite hand, a cooling work market might give the Federal Reserve the sign it requires to slice curiosity prices sooner as an alternative than later.

    “It is nonetheless very prone to be summer forward of the initially Fed degree reduce,” Sturtevant mentioned. “However, the monetary data we’re observing now might consequence out there place to reply, anticipating long run Fed movement, which might decrease borrowing premiums, like mortgage mortgage prices. Decrease costs this spring might give housing market demand from prospects a improve.”

    Lawrence Yun, the chief economist on the Countrywide Association of Realtors, claimed the general economic system is clearly slowing and the housing disaster grows rather more acute nearly each thirty day interval. 

    “The short-phrase timing of acquire relies on property finance mortgage prices and stock availability,” he defined. “Home product gross sales recorded the most affordable exercise in 2023 in virtually 30 a very long time. Notice that there are 158 million payroll work alternatives as we speak versus 117 million when property product sales had been being in the identical approach lowered. It implies sizable seemingly genuine property demand from prospects on the sidelines, able to pounce when brief-time interval conditions transfer favorably.

  • Leaders of MFAA national message boards chosen

    Leaders of MFAA nationwide boards chosen | House mortgage Professional Australia

    News

    Presidents, deputy presidents of 5 enterprise dialogue boards found

    Leaders of MFAA national forums chosen

    The presidents and deputy presidents of the MFAA’s nationwide neighborhood boards have been made the choice, subsequent nominations and elections.

    The boards take pleasure in a vital position within the residence finance mortgage and finance business’s premier peak physique.

    MFAA CEO Anja Pannek mentioned the insights and observations shared by, and the feed-back derived from, the MFAA’s nationwide boards was priceless in informing the route of the MFAA’s capabilities and advocacy endeavours within the course of the 12 months.

    “Our countrywide dialogue boards are integral in co-developing options for the acquire of our mortgage and finance dealer members and to extra the sector,” Pannek claimed.

    “We are centered on a full-of-business method – with our dealer members on the predominant of our advocacy and training pursuits.

    “Our nationwide message boards play a big half in making sure we take heed to and notice views from throughout {the marketplace}. This lets us to hold on to type and affect optimistic outcomes for our dealer customers.”

    Pannek mentioned as an illustration, in 2023 lower than the recommendation of the countrywide boards,  two cross-discussion board functioning teams had been being established up to focus on cybersecurity and dealer accreditations.

    “Both these areas are important challenges for our dealer clients that demand a total-of-sector goal,” she defined.

    The MFAA can now announce, following a course of motion of nomination and voting by each dialogue board, who has been elected within the positions of presidents and deputy presidents all through 5 boards:  the National Aggregator Forum Nationwide Compliance & Regulation Discussion board National Machines & Business Finance Forum National Financial establishment Discussion board, and Nationwide Home finance mortgage Supervisors Forum

    Nationwide Aggregator Discussion board

    The MFAA defined Countrywide Aggregators Discussion board furnished a platform for aggregator members to evaluation and discuss difficulties battling the sector and to help the MFAA in formulating positions and taking into account seemingly strategies and their results.

    &#13
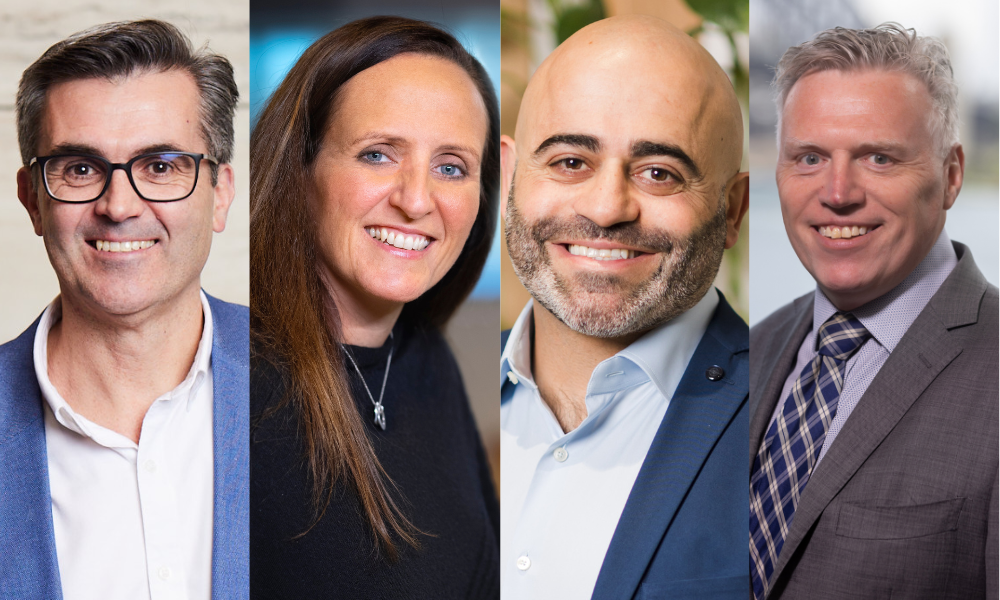
    President: Anthony Waldron (pictured high rated remaining), REA Team CEO of cash options and Home finance mortgage Selection (re-elected)&#13
    Deputy president: Gerald Foley (pictured beneath), nMB managing director (re-elected)&#13

    Waldron mentioned it was an honour to as soon as extra be elected president of the National Aggregator Forum.

    “I search forward to performing with the MFAA and all of the opposite aggregators once more this yr as we feature on to extend the broking enterprise,” he mentioned.

    National Compliance & Regulation Discussion board

    The National Compliance & Regulatory Forum was confirmed for associates to share ordeals, information and intelligence on compliance and regulatory points for the mutual acquire of all associates, talked about the MFAA.

    Its focus included pinpointing market biggest train and regular necessities referring to legislative and regulatory compliance.

    &#13
    President: Shirley Elliot (pictured high 2nd from left), AFG head of compliance (re-elected)&#13
    Deputy president: Samantha Wills (pictured beneath), Finsure head of hazard and compliance (newly elected)&#13

    “I’m completely happy to be persevering with on this half and get the job accomplished with the MFAA to guarantee our subject is on the forefront of regulatory enhance,” reported Elliot.

    “Being a facet of this dialogue board and the MFAA’s advocacy and engagement with regulators permits us be sure that brokers can guard their organizations and go on to ship nice buyer outcomes.”

    National Equipment & Commercial Finance Forum

    The National Devices & Industrial Finance Discussion board. is constructed up of reps from broking firms, aggregators and mortgage suppliers.

    The MFAA reported discussion board associates have been actively concerned in a spread of appropriate issues influencing the sector, which embrace instruction and training for finance brokers {and professional} lending pure surroundings and traits investigation.

    &#13
    President: George Obeid (pictured high rated second from appropriate), Judo Financial establishment chief third celebration officer (re-elected)&#13
    Deputy president: Mhairi MacLeod (pictured beneath), Astute Capability Finance Group managing director (re-elected)&#13

    Obeid acknowledged he was delighted to be re-elected as president. “I’m thrilled to proceed to get the job accomplished with our superior MFAA discussion board associates, as we increase enterprise and units finance inside simply the dealer subject.”

    Nationwide Loan firm Discussion board

    The Nationwide Loan corporations Discussion board is constructed up of mortgage firm clients, which incorporates the main banking establishments, smaller monetary establishments and non-financial establishment mortgage firm members which distribute their merchandise and options by way of residence finance mortgage and finance brokers.

    &#13
    President: Mark Middleton (pictured high significantly correct), Academics Mutual Bank Minimal head of third get collectively distribution (re-elected)
    &#13
     &#13
    Deputy president: Darren McLeod (pictured below), Past Lender head of third celebration (re-elected)&#13

    Middleton acknowledged he appeared ahead to persevering with to make a optimistic contribution to the business because the re-appointed President of the Nationwide Financial establishment Discussion board. “It’s important we proceed to characterize collectors in order that we assure a stronger final result for the dealer business.”

    National Mortgage mortgage Supervisors Discussion board

    The National Property finance mortgage Professionals Forum provides a platform for mortgage mortgage managers to analysis and discuss issues coping with the enterprise and to help the MFAA in coping with issues, formulating positions and contemplating seemingly options and their implications.

    &#13
    President: Doug Daniell, Home finance mortgage Mart of Australia (re-elected)&#13
    Deputy president: Melissa Ashcroft (pictured below), AAA Economical Group commonplace supervisor (freshly elected)&#13

    The MFAA acknowledged it was Daniell’s subsequent expression as president of the Countrywide Home finance mortgage Managers Discussion board – he additionally beforehand served as deputy president.

    Congratulate the presidents and deputy presidents of the MFAA countrywide boards. Comment beneath

    Free e-newsletter

    Our each day publication is Free of cost and retains you as much as day with the surroundings of residence finance mortgage.
    Remember to complete the sort down beneath and click on on on Signal UP to obtain day-to-day e-newsletters from Property finance mortgage Experienced Australia.

    Our each day e-newsletter is No value and retains you as much as day with the planet of residence finance mortgage.

  • Exterior administrations access record superior amid economic troubles

    External administrations access historical past superior amid monetary points | Australian Broker News

    Information

    External administrations arrive at record excessive amid monetary troubles

    What has prompted this sort of a enhance?

    External administrations reach record high amid economic challenges

    According to the March 2024 CreditorWatch Enterprise Hazard Index (BRI), exterior administrations have surged to a record giant in Australia. This surge arrives as organizations grapple with a spread of worries along with value pressures, certified labor shortages, and declining buyer want.

    B2B fee defaults, whereas marginally down from the report vital observed in February, stay up 22.6% 12 months-on-yr. In accordance to CreditorWatch, this signifies that companies are getting it progressively difficult to settle glorious invoices. Court docket steps have additionally been on the rise, steadily returning to pre-COVID concentrations.

    One specific notable development highlighted within the report is the dominance of the development sector, which largely consists of smaller sub-contractor companies, in Australian Taxation Office atmosphere (ATO) tax debt defaults. Of the over 15,000 tax bank card debt default info now held by CreditorWatch from the ATO, 23.8% are from the event trade. This is adopted by 12.5% in certified, scientific, and technical suppliers, and 10.7% in meals stuff and beverage firms.

    CreditorWatch chief economist Anneke Thompson identified that this sort of enterprises sometimes battle to repay huge tax money owed, considerably all these working as sole merchants or partnerships.

    “These companies normally have debt secured from personal belongings, and cash owed of $100,000 or extra can be a big imposition on their capability to fulfill their ongoing monetary obligations,” acknowledged Thompson.

    Elevated expenditures pressuring patrons and companies

    Patrick Coghlan, CEO of CreditorWatch, attributed the surge in exterior administrations to elevated price ticket pressures on firms and the have an effect on of rising dwelling bills on customers. He emphasised that proper till shopper investing will enhance, enterprises are attainable to proceed going via demanding issues, specifically with no quick help in sight from greater inflation prices.

    “We actually do not be anticipating small enterprise circumstances to make enhancements to markedly proper till purchaser paying out raises, and that’s depending on fascination cost help, which isn’t even on the horizon at this stage supplied the substantial prices of inflation within the US,” talked about Coghlan.

    Key insights from the BRI for March include:

    &#13
    External administrations are at a record vital, up 22.1% calendar year-on-year.&#13
    The improvement market certified prospects in ATO tax private debt defaults exceeding $100,000.&#13
    B2B fee defaults lessened marginally from February to March however proceed to be up 22.6% calendar year-on-yr.&#13
    Courtroom steps have enhanced by 45.5% 12 months-on-12 months.&#13
    The meals and beverage professional companies sector faces the best danger of enterprise failure.&#13
    Mining sector insolvencies and late funds are on the rise because of a wide range of pressures like labor shortages and fluctuating commodity costs.&#13

    Wanting forward, the report means that the chance of revenue stage cuts in Australia for the rest of 2024 is distant owing to substantial inflation figures within the United states of america. In accordance to CreditorWatch, this signifies a ongoing time interval of weak shopper demand and better debt financing prices for organizations.

    Have one thing to say about this story? Go away a comment beneath.

    Retain up with essentially the most present info and actions

    Be part of our mailing itemizing, it’s free!

  • House loan applications see most significant upward shift in a month

    Buyers navigating a difficult-to-forecast housing and quantity environment assisted drive dwelling monetary loan functions larger final 7 days, in response to the Property finance loan Bankers Affiliation.

    Following a 3-7 days interval when lending volumes primarily moved sideways, the MBA’s Sector Composite Index jumped a seasonally modified 3.3% from 7 occasions beforehand. In the prior 7 days, packages managed to nudge up by .1%. But on a calendar year-over-year foundation, it got here in 3.4% decreased. The index actions software program exercise primarily based on surveys of the commerce group’s customers

    Quantity picked up even with the most latest rise in curiosity charges, with financial particulars pointing to persistent inflation and a sturdy monetary system. The 30-yr unusual for loans with conforming balances making them appropriate on the market to the govt-sponsored enterprises accelerated to 7.13% from 7.01% one explicit week prior. The common amongst MBA loan corporations completed at its most concern since December, talked about Joel Kan, MBA vice chairman and deputy chief economist.

    Points to assist ship down the quantity, in the meantime, enhanced to .65 from .59 on 80% loan-to-benefit ratio applications. 

    “Even with these larger prices, utility exercise picked up, possibly as some debtors made a determination to behave in state of affairs costs proceed to extend,” Kan said in a push launch.

    Invest in apps drove most of the uptick in a housing market that has information pointing in sometimes contradictory instructions. The MBA’s Purchase Index climbed up by a seasonally modified 5% after 4 weeks of declines. But functions have been nonetheless 9.9% decrease from the exact same research time frame a yr in the past. 

    When properties are promoting sooner in comparability to final calendar 12 months in a nice deal of the state, a lot much less sellers expect bidding wars, and worth cuts are additionally beginning to be much more widespread, in response to experiences from Real property agent.com and Zillow this 7 days.  

    And while housing stock has additionally revealed indications of selecting as much as get began 2024, a higher amount of homes on the business can be not ensuing in elevated affordability. The regular buy-mortgage dimension stop escalating earlier week, whereas, proper after reaching an virtually two-12 months greater in late March. The counsel sum settled at a nevertheless-elevated $447,900, down a fraction from $449,400 a 7 days beforehand.

    Buys amplified at a higher tempo than the MBA’s Refinance Index, which squeezed out an .5% weekly acquire. But on a 12 months-above-calendar 12 months foundation, refinance volumes shot up 11.3%. The share of refinances relative to full amount arrived out to 32.1%, slipping from 33.3% seven days prior.

    Higher mounted prices usually result in heightened fascination in adjustable mortgages, and closing 7 days was no exception with the ARM Index rising 8.7%. Adjustable-price dwelling loans additionally garnered 7.3% of all applications in comparison with 6.9% in the previous research interval. 

    The widespread lending market provided most of the momentum for loan suppliers final week, because the Authorities Index slowed a seasonally modified 2.2%. 

    The share of federally backed exercise additionally contracted, primarily owing to diminished volumes coming by means of the Office of Veterans Affairs. VA-sponsored apps constructed up 12.4% of total quantity, dropping from 14% in the prior research. But Federal Housing Administration-confirmed loans took a 12.3% share, inching up from 12.1%. The part of home loan applications sponsored by the U.S. Office of Agriculture was .4% 7 days greater than week. 

    Mortgage premiums tracked by the MBA headed up throughout the board in tandem with the conforming typical. The 30-yr fixed-deal jumbo widespread leaped 27 basis factors to land at 7.4% from 7.13% the previous 7 days. Points diminished to .46 from .56 for 80% LTV-ratio loans.

    The common 30-year deal value for FHA-backed monetary loans accelerated to six.9% from 6.8%. Borrower components rose by 6 basis particulars to .99 from .93.

    The deal cost widespread of the 15-calendar 12 months mounted mortgage loan shot up 18 foundation components to six.64% from 6.46% a week earlier than. Points to get down the cost elevated to .64 from .6.

    The 5/1 adjustable-amount mortgage, which begins with a mounted 60-thirty day interval time period, averaged 6.52% in comparison with 6.41% 7 days prior. Factors dropped to .6 from .67.

  • The bets she’s building now

    Sonali Pier is a portfolio supervisor with Pimco

    Pimco’s Sonali Pier strives for outperformance.

    The youngest of three and the daughter of Indian immigrants, Pier established her sights on Wall Road instantly after graduating from Princeton University in 2003. She commenced her occupation at JPMorgan as a credit standing dealer, a topic that might not have quite a lot of females.

    “In the ladies house, I don’t stumble upon a considerable amount of people,” mentioned Pier, who moved from New York to California in 2013 to hitch Pimco.

    Fortuitously, she’s seen a complete lot of alterations in extra of the many years. There has not solely been some progress for girls entering into the monetary enterprise, however the life-style has additionally altered contemplating the truth that the financial catastrophe to grow to be far more inclusive, she acknowledged. Plus, it really is an area precisely the place there may be distinct proof of effectivity, she further.

    “You will discover accountability,” she defined, in a current job interview. “Thus, the gender operate begins off to separate down a minimal bit. With obligation and accountability and a spread to your determine, it truly is fairly very clear what your contributions are.”

    Pier has risen through the ranks as a result of turning into a member of Pimco and is now a portfolio supervisor in simply the agency’s multi-sector credit score historical past group. The 42-calendar year-outdated mom of two credit mentors for aiding her alongside the way in which, as completely as her partner for supporting her and shifting to California sight unseen. Her father additionally lifted her to worth coaching and hard work, Pier talked about.

    “He was the quintessential occasion of the American need,” she mentioned. “Getting succesful to see his actually onerous do the job and a great deal of improvement meant that I infrequently thought or else, that actually onerous operate would not direct to improvement.”

    Pier’s do the job has not absent unnoticed. Morningstar topped her the winner of the 2021 U.S. Morningstar Award for Investing Excellence within the Mounting Talent class.

    “Pier’s cautious contrarianism and hovering influence at simply one of many business’s main and most internally aggressive fastened-profits asset-management companies stands out,” Morningstar reported on the time.

    Placing her expenditure method to carry out

    Pier is the direct supervisor on Pimco’s Diversified Revenue Fund, which was amongst the main performers in its class — rating within the thirteenth percentile on a complete return basis in 2023, in line with Morningstar. It has a 30-day SEC produce of 5.91%, as of Jan. 31.

    “We’re genuinely broadly canvassing the worldwide panorama, after which attempting to find wherever you will discover the best choices,” Pier claimed. “It is discovering the will cost sensitivity from funding high quality, superior-high-quality sections of EM [emerging markets], and the fairness-like sensitivity from increased produce and the small-quality areas of EM.”

    The fund additionally invests in securitized belongings, with about 23% of the portfolio is allotted to the sector, as of Jan. 31.

    Inventory Chart IconStock chart iconhide content

    Pimco Revenue Diversified Fund

    Although the fund has a benchmark, the Bloomberg Worldwide Credit Hedged USD Index, it’s “benchmark aware” and won’t “hug it,” Pier reported.

    Morningstar has termed the fund a “standout.”

    “Pimco Diversified Income’s however ample staffing, deep analytical belongings, and established technique make it a serious choice for better-yielding credit standing publicity,” Morningstar senior analyst Mike Mulach wrote in January.

    It has not continually been clean crusing. The fund has far more intercontinental holdings and a further credit score score-hazard-major profile than its pals, which has in some circumstances “knocked the portfolio off class,” prefer it did in 2022 all through the Russia-Ukraine battle, Mulach defined. However, he likes it greater than the very lengthy expression.

    So significantly this 12 months, the fund is comparatively flat on a complete return foundation.

    In addition to additionally major PDIIX, Pier can be a supervisor on quite a lot of different money, together with the PIMCO Multisector Bond Active ETF (PYLD), which was launched in June 2023. It presently has a 30-working day SEC generate of 5.12%, as of Tuesday, and an modified expense ratio of .55%.

    Stock Chart IconStock chart iconhide content

    Multisector Bond Energetic Trade-Traded Fund effectiveness contemplating the truth that its June 21, 2023 inception.

    “It will be maximizing for generate, though attempting to find money appreciation, and positively, with the very same Pimco ideas of wanting to maintain up on the upside, however regulate that draw back risk,” she reported.

    In which Pier is bullish

    Ideal now, Pier prefers created markets in extra of rising marketplaces and the U.S. about Europe.

    Within simply investment-quality company, she likes financials in extra of non-financials. Credit historical past spreads have widened in financials across the concerns about regional banks, she mentioned.

    “Possibly a few of it is warranted for the reality that they might want to state of affairs important provide 12 months proper after yr, however we take into account that the metrics of, say, the big six … look fairly resilient on a relative basis,” Pier defined.

    Within firm credit score, the crew seems on the “whole versatility of the toolkit,” she talked about. That might contain derivatives and revenue bonds, she added.

    “Are we looking for on the euro bond or the dollar bond in the exact same construction? The entrance cease or the extended end? Hard money vs . derivatives? On the opposite hand we will most effectively particular our view and commerce that can direct to the perfect whole return,” Pier claimed.

    She additionally likes securitized belongings, which she claimed generally is a ton way more resilient all by way of a downturn. Just one in all Pier’s decisions is the legacy non-agency home loan-backed securities market.

    “We have the info on how lengthy they have been within the residence, how significantly dwelling equity has been constructed, what their home mortgage value is, what’s been their alacrity to pay again, so we will see — is there any delinquency?” she acknowledged. “We have a considerable amount of information there and a great deal of consolation throughout that asset class.”

    Company home loan-backed securities are additionally lovely and may very well be an excellent substitution for one-A rated firm monetary debt, she acknowledged.

    About 60% of property homeowners have a house finance mortgage price under 4%, in accordance to a Redfin evaluation of details from the Federal Housing Finance Agency’s Countrywide Mortgage Database.

    “It actually is further liquid, implicitly sure by the federal government and it’s a actually an identical unfold,” she acknowledged.

    Pier finds the operate pleasing and encourages ladies to hitch her within the firm.

    “Everyone can excel who needs to actually place within the function and needs to wager on themselves,” she reported.

    Never go up these exclusives from CNBC Pro

  • What is the Florida Empowered DPA Software? A Guide for Homebuyers

    Overview – Florida Empowered DPA Plan

    The Florida Empowered DPA System is a brand new utility for homebuyers designed to produce substantially-needed down cost help. Additional out there than most plans, it options helpful help for buying a principal residence.

    In distinction to many different down cost assist (DPA) packages, the Florida Empowered DPA Program stands out by providing as much as 3.5% of the property’s value.

    This grant is not a financial institution mortgage that must be repaid however as a substitute a considerable supporting hand for homebuyers.

    What It Delivers

    Up to three.5% down cost assist grant.

    Covers the whole down cost for an FHA monetary mortgage.

    Grant is forgiven in the event you preserve the mortgage for at minimal six months.

    Who Qualifies

    To begin with-time homebuyers.

    Military employees, 1st responders, educators, healthcare business consultants, governing administration staff.

    Income earners as much as 140% of the space’s median earnings.

    Consumers in underserved census tracts.

    Method Necessities

    Minimum 620 credit score historical past score.

    Main house order solely.

    Credit card debt-to-income ratio beneath 48.99%.

    Authorized home types include one-spouse and youngsters properties, duplexes, produced houses, FHA-accepted condos, and PUDs.

    Completion of accepted homeownership education course.

    How to Implement

    Contact a licensed home mortgage dealer like MakeFloridaYourHome.

    Eligibility Demands for the Florida Empowered DPA Method

    Homebuyers ought to meet positive necessities to fulfill eligibility for the Florida Empowered DPA Plan. These stipulations fluctuate from earnings restrictions to credit standing thresholds and sure situations related to the house.

    Should be a initial-time homebuyer or not owned a house in the final three a number of years. OR at the second or beforehand a portion of the armed forces, preliminary responder, educator, medical specialist, or close by or federal govt worker.

    Income should be 140% or considerably much less of the space’s median revenue.

    The credit score rating rating ought to be a minimal of 620.

    The dwelling ought to be for a significant house.

    Credit card debt-to-income ratio not exceeding 48.99%.

    Assets sorts contain one-spouse and youngsters houses, duplexes, made properties, FHA-authorized condos, and PUDs.

    Completion of an authorised homeownership instruction research course is compulsory.

    Benefits of the Florida Empowered DPA Method

    Thanks to the Empowered DPA system, securing a property has by no means been easier.

    Built for homebuyers in Florida, this method makes a path to homeownership by lowering monetary limitations and incomes residence-buying additional fairly priced.
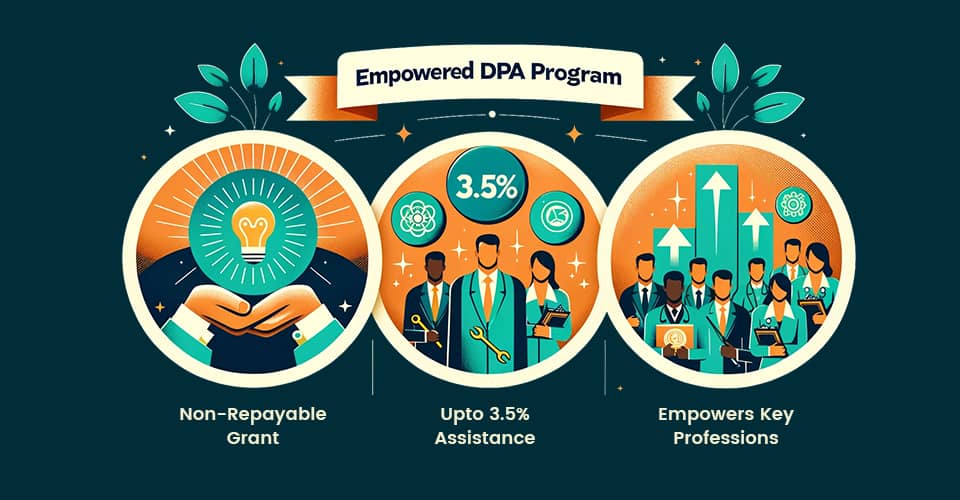
    Benefits of empowered down payment assistance program

    Supplies as much as 3.5% down cost help on the house’s purchased worth.

    Gives a non-repayable grant that may assist protected an FHA mortgage simply.

    Maintains broader requirements, constructing the software program out there to a broad number of homebuyers.

    Empowers important professions like military personnel, educators, and first responders with homeownership alternatives.

    Facilitates homebuyers whose earnings is 140% or fewer of the regional median income.

    Supports homebuyers intending to acquire property in underserved census tracts.

    How Does the Florida Empowered DPA Method Get the job accomplished?

    The Florida Empowered DPA System follows a clear-cut process to help homebuyers. Listed listed below are the methods:

    Prequalification – Start out by deciding in the event you fulfill the program’s eligibility requirements.

    Uncover an permitted lender – Function with a monetary establishment affiliated with the software program to make the most of for the DPA.

    Application – Submit your software program to the technique.

    Closing – At the time authorised, full the required strategies to close your house.

    Article-purchase support – Acquire ongoing help and steering instantly after getting your residence.

    The Florida Empowered DPA Software simplifies house shopping for by furnishing a structured action-by-phase answer. This makes it quite a bit simpler for attainable house owners to navigate and protected a home.

    What are the Key Functions of the Florida Empowered DPA System?

    The Florida Empowered DPA Method helps with down funds, lowers rates of interest, options versatile mortgage choices, and presents education for to start out with-time homebuyers.

    It additionally addresses fairly just a few kinds of properties. This plan does additional than the regular mortgage, producing it a lot simpler for additional individuals to buy homes.
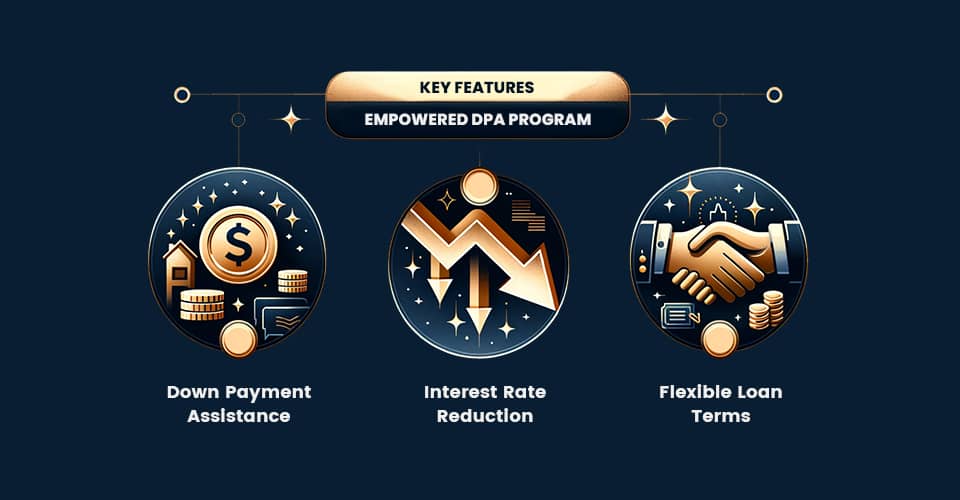
    Key features of empowered down payment assistance program

    Down Payment Guidance

    The Florida Empowered DPA System assists homebuyers with the unique cost desired to spend money on a property. It delivers as much as 3.5% of the house’s buy promoting value, which might take care of the complete down cost if you’re getting an FHA mortgage.

    This could make it a lot simpler for quite a few folks right now to purchase their very first dwelling, as developing with the down cost is usually the hardest part.

    Interest Amount Reduction

    The program additionally lessens the curiosity charge on house loans, which lowers common funds. This discount might help you save homebuyers a complete lot of income greater than time, creating households extra cheap.

    It is particularly helpful for these individuals who must have to carry their common month-to-month prices down.

    Adaptable Bank mortgage Terms

    The Florida Empowered DPA Application presents versatile situations for your own home mortgage. This suggests you possibly can regulate your mortgage to suit your monetary downside improved.

    Whether you need decrease month-to-month funds or a singular private mortgage length, this utility helps make it achievable. It’s constructed to make buying a residence significantly much less demanding and extra out there to totally different purchasers.

    To begin with-Time Homebuyer Education and studying

    If you’re acquiring your 1st residence, this program consists of an instruction class that teaches you about the property-getting method.

    You will discover out essential elements like mortgage mortgage primary ideas and how you can funds for your new residence. This instruction permits you make educated conclusions and prepares you for homeownership.

    Assets Eligibility

    The system is not actually simply for solitary-household houses it additionally consists of duplexes, made residences, FHA-authorized condos, and Planned Device Developments (PUDs).

    This range permits much more potential consumers to acquire residences that match their necessities, whether or not or not they’re wanting for an inexpensive selection or a family that may additionally create rental income.

    Empowered DPA Software FAQs

    Here we have now answered 10 routinely requested inquiries about the Florida Empowered DPA Program.

    What is the Florida Empowered DPA Software?

    The Florida Empowered DPA Program is a down cost help initiative developed to assist first-time homebuyers and appropriate specialists reminiscent of army personnel and educators protected financing for their primary residences in Florida.

    Who qualifies for the Florida Empowered DPA Software?

    Eligibility is prolonged to initial-time homebuyers, navy employees, 1st responders, educators, health-related business consultants, and federal authorities personnel.

    Applicants will need to have incomes not more than 140% of their space’s median cash and be buying in chosen underserved locations.

    What economical assist does the Florida Empowered DPA Application present?

    The system delivers as much as 3.5% in down cost help as a non-repayable grant, masking the full down cost for an FHA private mortgage, supplied the borrower retains the house for at the very least six months.

    What are the credit standing requirements to qualify for the software program?

    Applicants must have a least credit standing score of 620 to qualify for the Florida Empowered DPA Software.

    What varieties of homes are eligible for the program?

    Suitable homes contain solitary-household households, duplexes, made houses, FHA-approved condos, and Prepared Device Developments (PUDs).

    Is there an educational requirement for the technique?

    Sure, candidates are anticipated to complete an permitted homeownership education class to qualify for the down cost help out there by the Florida Empowered DPA Software.

    What is the biggest debt-to-earnings ratio permitted beneath the program?

    The technique permits for a bank card debt-to-cash movement ratio of as much as 48.99% for certified candidates.

    How does 1 apply for the Florida Empowered DPA Program?

    Opportunity candidates ought to talk to an accepted home mortgage dealer, this type of as MakeFloridaYourHome, to start out off the utility system for the Florida Empowered DPA Method.

    How very lengthy must I maintain the dwelling to not repay the grant?

    The down cost help introduced by the utility is forgivable after 6 months of retaining the financial institution mortgage and property.

    Can the down cost assist be blended with different economical assist?

    Certainly, the down cost help from the Florida Empowered DPA Method can usually be put along with different varieties of cash help, nevertheless candidates should validate distinctive info with their mortgage supplier.

    Speak to MakeFloridaYourHome these days to see how considerably funds you possibly can protect with Empowered DPA. Satisfied homebuying!

    With over 50 yrs of property finance mortgage sector expertise, we’re right here that can assist you attain the American aspiration of proudly proudly owning a house. We attempt to give the splendid schooling and studying proper earlier than, for the length of, and shortly after you buy a dwelling. Our recommendation is primarily based totally on experience with Phil Ganz and Group closing above A particular person billion {dollars} and aiding many households.

  • Shawbrook cuts charges on larger BTL loans – Property finance loan Finance Gazette

    Shawbrook has decreased costs on chosen purchase-to-permit merchandise and options by as much as 30bps.

    Buy-to-let-post-it-notes-620x330.jpg

    The charge cuts are throughout its intricate and restricted version BTL ranges for debtors having out larger loans of amongst £1m and £5m.

    In its elaborate BTL assortment Shawbrook will now demand a  fee of 6.34% on its 5 and 10-12 months set premiums as much as 65% LTV. For all these borrowing as much as 75% LTV the charges is 6.44% — a lower of 30bps.

    In this differ it has additionally slash the expense of its a few-year, and two-calendar 12 months preset charges. Its 3-year fixes will now begin off at 6.49% (at 65% LTV) while its two-calendar 12 months fixes have been lowered to six.54% at 65% LTV and 6.64% at 75% LTV.

    Shawbrook has additionally manufactured changes to its restricted model elaborate BTL merchandise and options, once more for monetary loans regarding £1m and £5m, this time throughout its two- and five-12 months fixed-level merchandise and options.

    Its five-12 months mounted time period monetary loans have been decreased to five.84% at 65% LTV, and 5.94% at 75% LTV. In the meantime its two-yr fixes  been decreased to five.44% at 65% LTV and 5.54% at 70%.

    Shawbrook director of actual property proposition Daryl Norkett states: “These most present pricing reductions show our sturdy starvation to help brokers and knowledgeable landlords with an enormous collection of lending merchandise.”