Tag: with

  • Just Mortgages expands Scottish existence with MacKay seek the services of – Property finance loan Technique

    Just Mortgages has additional to its self-used division and its presence in Scotland with the appointment of Grant MacKay as earnings supervisor.

    MacKay will probably be functioning rigorously with 25 self-employed advisers all through Scotland and the North East of England.

    Primarily based mostly in Motherwell, MacKay will assist advisers elevate their experience and enhance their enterprises as properly as making use of the in-property teaching and help available.

    MacKay joins with 15 years of working expertise inside of the subject. He began his job with HSBC in 2010, doing work in its telephony division to help shopper help queries.

    He then moved into the home loan division of HSBC as assistant supervisor and later group supervisor.

    In 2014, he completed his CII qualification and grew to develop into an adviser. Adhering to this, he joined Carrington Home loan Products and services as a property finance loan and safety adviser, proper earlier than transferring to firstmortgages.co.british isles, wherever he was most not too way back product sales high quality supervisor.

    Just Home loans head of mortgages and protection Ben Allkins says: “Grant’s appointment is the subsequent part in rising steerage for brokers and rising our presence north of the border. He delivers with him hundreds of experience which will probably be massively worthwhile to our brokers as they look to reinforce firm, enhance skills and in the finish, broaden their private companies.”

  • Why Gen Z’s homebuying with good friends is up, and what it will take

    Buying a dwelling has come to be so excessive priced that doable prospects of all ages, however particularly youthful people, are wanting into pooling their belongings with unrelated occasions (this type of as good friends) to get in extra of the hump.

    Between present Gen Z homebuyers, 22% blended their {dollars} with friends’ to get a home collectively, the 2024 Point out of Homebuying Report from ServiceLink uncovered. That is a brand new improvement as opposed with previous variations of the survey.

    This as opposed with 14% of millennial respondents, 10% of Gen Xers and 3% of child boomers. The survey protected 1,519 individuals who each purchased a family or tried to buy a house up to now 4 a very long time.

    They have been being requested “precisely the place did the {dollars} on your down fee seem from?” Respondents may pick far multiple response. Throughout all age groups, 11% acknowledged they labored with friends.

    Gen Z is the crew most desperate to get they have been being the one demographic polled that felt situations have been being way more favorable for buying in 2024 than an individual calendar 12 months prior. That translated to 63% of Gen Z respondents scheduling to spend money on a property this 12 months, when put next with 59% of millennials, 45% of Gen X members and 21% of kid boomers.

    A collaborative period enjoying a important half out there

    Gen Z grew up fairly relaxed with social media and engineering. “Why does that make any distinction after we’re speaking about acquiring properties with shut friends?” mentioned Dave Howard, govt director of originations at ServiceLink. “For the explanation that you just could be extra cozy with points like social funding and crowdsourcing.”

    In accordance to a Redfin evaluate, 39.7% of mortgages issued in 2023 went to homebuyers beneath 35, and 26.5% went to purchasers amongst 35 and 44. Then 16.1% went to individuals in between 45 and 54, 10.8 for these 55 to 64 yr olds, when simply 5.4% went to the oldest demographic, the 65 to 74 12 months olds (5.4%).

    People portions additionally exhibit that the Gen Z crew is fairly eager and decided to take half in homeownership. The research throughout the rise confirms anecdotal tales that in addition they have been getting creative as to how they’ll attain it, Howard extra.

    “When you improve up in an ecosystem, precisely the place you are employed to these types of functions, you could be made use of to all these sorts of strategies, it really is a rational extension,” claimed Howard.

    More youthful generations’ collaborative tactic to housing is a chance to broaden the customer basis for homes, in accordance to Nestment, a startup that may assist Gen Zers and millennials hack homeownership.

    The web-site gives potential individuals “a roadmap it claims ‘listed here are your up coming steps,’”  claimed Niles Lichtenstein, CEO and co-founder. When shoppers choose a selected room on the internet website, they will see a established of following strategies to go through. The method gives schooling that aids them make financial projections and educated decisions concerning the appropriate mortgage corporations to get the job completed with, he reported.

    Much greater than 1-Third of newest non-owners are keen to interrupt up a order with one other particular person aside from their partner so as to pay for a home, Lichtenstein famous citing a Credit Karma-Intuit examine. That jumps to 59% when looking at Gen Z respondents.

    “We see this turning into a even bigger and greater portion of the order pathway,” Lichtenstein well-known.

    Somewhat than persevering with to rent, people are considerably taking a look at no matter whether or not they can possess a dwelling and set up wealth, he talked about.

     “I think about anybody ultimately needs to be in a one partner and youngsters home with a beloved one and household, which is the ultimate goal,” defined Lichtenstein. “But it is considerably much less and considerably much less possible for therefore a number of people.”

    Nestment assists many people seem at residence listings and do economical projections collectively, making a pathway wherever they’ll really really feel cozy to go prematurely, Lichtenstein mentioned.

    The demand is rising, he mentioned. In an early part of the duty, Nestment was searching for to have 100 teams arrive on board and in per week it had over 1,000 competent groups that have been seeking to spend money on a home within the up coming 12 months, Lichtenstein defined.

    It was extra than the workers may deal with it narrowed all the way down to 600 people and from that first work it expects regarding 70 and 80 transactions to consequence, he mentioned.

    1 dealer’s data dealing with this type of enterprise

    Tiana Uribe, a mortgage dealer in San Diego, an individual of the optimum expense markets within the nation, additionally reaffirmed the craze

    “It could be severely tough for millennials and Gen Z prospects to even enter the market until after all they’ve sufficient allow from their mother and dad regarding a down fee, or they’re pairing up and acquiring alongside each other,” Uribe claimed. “It makes a substantial amount of feeling whenever you don’t have all these different sources accessible to you.”

    A the newest transaction she taken care of related two individuals right now who lived in the very same rental property, albeit in several fashions. The landlord was searching for to advertise the property. The renters approached Uribe to see if she would converse with the owner because of the reality they ended up eager to buy the property collectively.

    California’s regulatory pure surroundings, the place by residence mortgage brokers are licensed as genuine property brokers, permitted Uribe staying outfitted to signify the shoppers in every capacities.

    An extra purpose the 2 renters, each equally one females, most popular to accumulate was since regular rental worth ranges within the location are regarding $2,500 and $3,000 a month, and that could possibly be for a studio residence, Uribe identified.

    Mainly as a result of the house did want some mend, Uribe was succesful to prepare a Federal Housing Administration 203(ok) plan mortgage, which is utilised for qualities that want renovation or rehabilitation.

    Additionally, the pair have been outfitted to interrupt up the three.5% down fee, with one specific purchaser, a trainer, outfitted to tug the money from her retirement account. The different purchaser skilled loads of in price financial savings.

    Due to the very fact they acquired the home a 12 months in the past, they have been future succesful to achieve a streamlined refinance and cut back their common month-to-month fee whereas on the time sharing within the extra appreciation as the value amplified, Uribe reported.

    In a good friends-joining-forces state of affairs, an individual may presumably think about that the underwriting system could possibly be tough. But Uribe mentioned it wasn’t as a result of each ladies had been dwelling within the residence for 5 yrs and have been able to show their rental funds.

    For the explanation that it was a rehabilitation monetary mortgage, the shoppers skilled to be on board with incomes assured the mortgage firm issued the attracts for the contractors and subcontractors.

    From a approved viewpoint although, many of those members are doable to not have believed by way of all the ramifications and the possible downsides, Howard claimed. You need to need to have a strong romantic relationship with the person you’re getting into into this association with, simply as a single would in the event that they have been being buying a dwelling with a partner or home companion.

    In Uribe’s state of affairs, “My advice to them was to hunt out out an property legal professional in order that they might deal with the division of the house if some factor have been to return about to presumably 1 of them.”

    Just after speaking with that lawyer, they the 2 decided to arrange particular person trusts.

    Uribe termed the association her purchasers entered right into a “good design” she will be able to current to different potential homebuyers who verify with “How can I spend money on a residence when the median residence worth in our massive price spot is $950,000?” 

    The mortgage labored not simply due to the association in regards to the events, but additionally primarily as a result of the place achieved the superior-cost necessities to qualify for FHA financing, by which individuals can qualify as much as 4 debtors (this type of as two companions) on the qualities, Uribe mentioned.

    Her market shopper demographic is single gals. She makes a substantial amount of written content material about dwelling sharing on her Instagram account.

    Individuals new house owners who took the leap are actually gaining in equity and dwelling in an exquisite space “as a result of they failed to carry out.

    “They believed in themselves and they reliable sufficient to do it,” acknowledged Uribe. “It is a severe testomony to acquiring faith that it could be more likely to carry out out.”

    The hazards

    These preparations could be glorious after they seem collectively. However, in the event that they slide aside later, they’ll create a “approved minefield” for contributors, acknowledged Marty Green, principal at property finance mortgage laws company Polunsky Beitel Inexperienced.

    “Anyone goes into these preparations, questioning every little thing’s heading to function out flawlessly, as many cases they do, however a number of conditions they actually do not,” Environmentally pleasant talked about. “And the place they you shouldn’t that is the place points get a tiny dicey.”

    For working example, though these could be one individuals who aren’t romantically included, ultimately an individual may presumably enter right into a romantic relationship, and that may complicate issues.

    So dissolving the partnership can be an area that would wish to need to be resolved in a lawful settlement.

    Property finance mortgage servicers have uncovered on their very own involved in conditions by which a married few divorced and it impacted the possession of the house. Very comparable issues may happen for the mortgage supplier/servicer when it arrives to property possession involving unrelated occasions, Inexperienced defined. 

    The vital distinction is that lawful tips throughout divorce cases additionally go over the equitable division of belongings akin to properties. Individuals insurance policies you shouldn’t exist for single co-proprietors, no matter irrespective of whether or not or not they’re in a romantic relationship, besides they’ve a contractual association.

    Inexperienced has a state of affairs the place a mom and son teamed as much as purchase a home just because every incomes have been needed to qualify for the home mortgage. But the son is now in a wedding and his mother and girlfriend don’t get alongside.

    The son set in significantly lower than fifty p.c of the down fee and closing bills, but wishes to be bought out as if it have been being an equal partnership in get to share within the appreciation. A lawsuit arose just because the occasions could not amicably clear up the predicament.

    “Even family members, after they get a dwelling collectively like that, generally is a bit crossways on the finish of the day,” Green reported. “Not getting compensated curiosity to people features on the outset undoubtedly grew to change into a situation of competitors for each the mother and the son.”

    When it involves underwriting, originators “sometimes rely on every individuals’s money stream and property to approve the financial institution mortgage on the outset,” Eco-friendly mentioned. “For them to be inclined to launch 1 of you from obligation means that something [in a financial situation] necessities to have improved to make the underwriting even now carry out.”

    But so far as the actual underwriting plan of action, “It is actually simply do these two debtors qualify, in the event that they qualify, and which is possibly the conclusion of the inquiry from the lender aspect,” Inexperienced mentioned.

    Consumers are performing extra resourceful issues to get right into a family like placing income collectively for a down fee, turning into co-borrowers and presently being on the take notice collectively, claimed Matt Dunbar, senior vice chairman of the Southeast area at Churchill Property finance mortgage.

    “As the lender we appear at is compensation functionality and default, we appeared on the collateral,” alongside with what is the acceptable use for the home, he talked about.

    “So after we appraise the property, these persons are genuinely the larger fears,” Dunbar extra. “As prolonged as we will doc it, it actually is not really a big situation.”

    Churchill Property finance mortgage works on connecting people with strategies akin to down fee assist and 1st-time residence purchaser plans.

    Dunbar identified that the median cash for a Gen Zer is about $37,300 in accordance to GoBankingRates. In the meantime, median family promoting costs are nonetheless rising, to an all-time massive of $396,000, with a median common month-to-month property finance mortgage fee of $2,781, Redfin acknowledged in a June 20 press launch.

    From the underwriting standpoint, pooling with buddies is extraordinarily much like a married couple getting a house, by which the 2 incomes are seen as and each persons are on the discover.

    “We consider their credit score historic previous, their funds, the supply of their down fee, deposits and reserves, all the exact same means,” defined Dunbar.

    As with married debtors, the bear in mind generates a approved obligation for the 2 get-togethers to be responsible for spending the financial institution mortgage. The lender/servicer has the same therapies in distressed conditions, Dunbar talked about.

    Some final phrases from specialists

    Keep in mind this association tends to be considerably much less well-known between older generations given that they’re usually far more confirmed of their occupation route and have far more fiscal property to faucet in a aggressive housing sector. So they aren’t essentially searching for for a “inventive selection” to acquire homeownership, Howard defined.

    It could be additionally actually value noting that not solely are customers of Gen Z far more desperate to collaborate by way of co-buying or teaming up with a renter, in addition they could be extra speak in confidence to taking a look at different housing decisions this type of as getting a property at public sale, the ServiceLink evaluate recognized.

    That talked about, it’s usually real that the for an extended interval people have been on the sidelines usually due to the deficiency of inventory and hovering fascination prices, the way more most likely they might maybe be to return to the conclusion that they need to work together in revolutionary ways to fulfill the housing sector the place it is proper now.

    Given that quite a few have been delaying relationship and home improvement and residence charges are however substantial, it actually is very possible that co-borrowing and different choices to plain buying will unfold.

    “If they wish to get [a house] now, they will have to find out out a means,” Howard reported.

  • Non-public Label relaunches with ‘prosperous professional debtors’ assortment – House loan Strategy

    Private Label has launched a set of dwelling loans geared toward “prosperous certified debtors”.  

    The lending model owned by the Brightstar Group says its Rockstar Variety attributes desire-only lending as much as 90% mortgage to worth, collectively with into retirement, as very properly as taking a versatile stance on self-employment and complex income.  

    The enterprise will acknowledge expert folks immediately with a lot lower than 12 months’ buying and selling background “and different eventualities that usually make the most of to prosperous skilled debtors”.  

    It may even take into consideration abroad nationals with considerably lower than 12 months within the British isles for this range and can accommodate huge loans above £5m.  

    Private Label, which provides bespoke loans for £500,000 or extra, was relaunched in April under Paul Brett as problem lead, who’s tasked with working with brokers to detect potentialities not achieved by present propositions.  

    He joined the model following investing seven a number of years at Landbay – and has labored within the house finance loan discipline for way over 30 a number of years, for each equally collectors and packagers.   

    Brett elements out that this range “will attraction to a wider range of intermediaries in offering strategies they can’t discover elsewhere.

    “The Rockstar Array of house loans is our 1st begin on this future evolution of the Non-public Label mannequin.”  

    Brightstar Group deputy chief authorities Bradley Moore gives that “this upcoming tranche of lending for Private Label is a return to ‘true exclusivity’ with the conclude goal changing into to help even much more debtors with sophisticated eventualities.”  

    Private Label was a effectively-regarded packager within the middleman mortgage loan market from the late 80s to the early 2000s.  

    It was established by Stephen Knight, Barry Searle, Simon Knight and Godfrey Blight and labored with quite a few lesser, centralised collectors to structure property finance loan gadgets.  

    The producer was bought by Common Motors, which grew to turn into GMAC-RFC, in 1998 and shut to new enterprise in October 2002.  

    Brightstar purchased the enterprise enterprise and area in 2016, launching many fashionable merchandise and options, collectively with an Airbnb giving and a credit score rating mend home loan, in July 2017.  

    However, the group afterwards place the mannequin into “hibernation” though ready for the proper human being to simply take it forward. It was revived lower than Brett within the spring.  

  • England and Wales having fun with enhanced rental yields: Fleet – Home loan Strategy

    The total common rental generate for England and Wales reveals an yearly enhance once more, up 1% % to 7.6% on the very same quarter in 2023. This can be up .5% on the initially quarter 2024 determine of seven.1%.

    This is in keeping with essentially the most present Fleet Mortgages Purchase-to-Permit Rental Barometer protecting Q2 2024 rental yields throughout England and Wales

    Fleet defined strengthening yields excellent throughout each single location of England and Wales was evident with all exhibiting year-on-12 months yield will enhance and the North East carrying out a double-digit produce within the second quarter of this yr.

    The barometer does present some motion amongst the areas although with Yorkshire and Humberside shedding finest place, falling to fifth location with an odd produce of seven.6%, down from 8.5% previous quarter.

    This means the North East strikes prime, in entrance of the North West, whereas each of these Wales and the West Midlands soar ahead of Yorkshire and Humberside.

    There stays an ongoing North/South divide with areas within the North topping the desk. Having mentioned that, Better London, the South East, East Anglia, and the South West haven’t simply seen yearly odd yields increase but in addition quarter-on-quarter.

    When it arrives to regular month to month rent for every belongings, one of the best is within Greater London at £2,024, adopted by East Anglia at £1,594 homes positioned within the North-East area generally see essentially the most inexpensive rents, with month-to-month common rents of £768.

    Rental yield highs

    Fleet mentioned that regardless that rental yields have been attainable to dip off these highs finally, they might be sustained till finally the non-public rental sector might reward from a better collection of residences to fulfill essential demographic issues, notably the populace elevate but in addition the elevated difficulties many individuals at present encounter when looking for to spend money on a family.

    Fleet Mortgages primary business officer Steve Cox commented: “While there are variety of surprises in simply this iteration of the Rental Barometer, it’s clear the traits now we have all been taking a look at within the broader make investments in-to-enable and private rental sector proceed to bolster appropriate all through the board, fuelled by a ongoing present/demand from clients imbalance.

    “Hence now we have each single location in simply which Fleet lends in England and Wales exhibiting a year-on-calendar 12 months enhance in common rental yields.”

    He further: “The calls for for an ongoing stable yield are clearly unlikely away, notably in a elevated interest-rate pure atmosphere through which quite a few refinancing landlord debtors are possessing to pay again much more for his or her common mortgages than they did two/3/five-years previously.”

  • What occurs following closing on your household with all the junk mail

    Immediately after closing on a home mortgage, a number of new house owners see a serious increase in the amount of unsolicited mail, normally known as “junk mail.” Here’s why this occurs and what you’ll be able to rely on:

    Why You Obtain Far extra Junk Mail

    Community Records: When you close to on a property finance mortgage, the transaction will change into a matter of neighborhood file. Firms that supply options and companies related to homeownership incessantly order these normal public knowledge to pay attention on new house house owners.

    Credit score Inquiries: House mortgage lenders normally make a difficult inquiry on your credit standing report once you use for a property finance mortgage. Credit score reporting corporations could nicely present details about these inquiries to entrepreneurs.

    Company Providers: Quite a lot of assist distributors (this type of as insurance coverage protection suppliers, house safety companies, and maintenance corporations) use particulars from public paperwork and credit score rating inquiries to market their merchandise and options to new householders.

    Forms of Junk Mail You May Acquire

    Mortgage Protection Coverage: Features for protection to deal with your home mortgage funds in situation of dying, incapacity, or job discount.

    Homeowner’s Insurance: Solicitations from insurance coverage corporations presenting to insure your new home.

    Property Advancement Services: Flyers and brochures from contractors, landscapers, and different residence development companies suppliers.

    Protection Methods: Delivers for property safety strategies and monitoring services.

    Money Solutions: Credit rating card affords, refinancing prospects, and different financial merchandise focusing on new owners.

    Address Improve Products and companies: Notifications and adverts from corporations providing corporations related to your remodel of tackle.

    Controlling Junk Mail

    Choose-Out Solutions: You can use knowledgeable companies like the Immediate Promoting Association’s Mail Choice Support (DMAchoice) to cut back unsolicited mail.

    Credit score Reporting Companies: Opt out of pre-accepted credit score historical past affords by means of the formal web site OptOutPrescreen.com or by calling 1-888-5-Opt-OUT.

    Public Records: Some counties and states present strategies to decide-out or prohibit the sharing of your public data for advertising and marketing and promoting wants. Verify with your native county clerk’s office for alternate options.

    Return to Sender: Mark undesired mail “Return to Sender” and ship it again once more. This could probably not consistently be highly effective, however it could actually at instances assist reduce future mail from the similar sender.

    Shredding: Be sure to shred any junk mail that consists of non-public details to protect on your personal from identification theft.

    Whilst it may be annoying to get an excessive amount of junk mail following closing on a mortgage, taking these steps can assist lower the quantity and handle the influx of unsolicited options.

    tune in and discover out at https://www.ddamortgage.com/weblog

    Didier Malagies nmls#212566

    DDA  Mortgage mortgage nmls#324329

  • Time to offer with dysfunctional PRS – Home finance loan Approach

    A mate of mine was a short time in the past in search of for a a few-bedroom rental residence within the West Midlands because of a wedding breakdown. Economically safe in a effectively-compensated occupation, his analysis proved frustratingly futile.

    The number of homes verged on non-existent. He complained of residences approaching to the business within the early morning and viewing slots remaining absolutely booked by the point he obtained shut to to getting involved with the letting agent a few hours afterwards. The property he in the end managed to safe after a number of weeks was made accessible to him off-market, however he even now skilled to endure a magnificence parade with a special potential tenant.

    His encounter isn’t uncommon and is symptomatic of a dysfunctional private rental sector (PRS), the place tenant need is drastically greater than on the market present. New particulars from Zoopla reveals that even nonetheless tenant need has happen off its peak of previous summer time, it’s nonetheless operating at 2 occasions the quantity of the pre-pandemic total world, though stock is down by a 3rd in distinction to then.

    Quite a lot of the dialogue in between landlord and tenant groups has targeted on no matter whether or not there was an exodus of residences from the PRS. For me, this misses the extent as there isn’t any conclusive proof. The steps launched within the latter half of the 2010s have clearly slowed the expansion of the PRS and it’s only way more a short time in the past that we’re observing information demonstrating inventory lower as extra compact-scale landlords exit.

    What is irrefutable, nonetheless, is that demand outweighs provide by some margin and that isn’t a wholesome place to be in. It contributes to rental inflation, lowers desire for tenants and capabilities as a barrier to monetary development.

    Flexible housing provision

    The latter place would possibly appear to be a leap, however a rising financial system needs transient and versatile housing provision. For illustration, a small enterprise opening a brand new enterprise workplace or producing basis will want quick time period properties for workforce that comply with the work prospect.  We have witnessed proof of this alongside the M1 distribution centre hall within the East Midlands as new warehouses have been designed, want for rental households has grown.

    With the competing political capabilities all specializing in financial improvement to enhance their paying electrical energy, proudly owning a working housing sector to help will probably be essential.

    As an apolitical organisation, I’m unlikely to touch upon the distinctive manifestos getting place forward by the capabilities. What I’ll say is that in any way bash is in vitality arrive 5 July, they are going to have to look on the nation’s housing provision within the spherical.

    The PRS presents a family to 1 in 5 households. It is the tenure of the working inhabitants. Its relevance want to not be missed or diminished.

    Of coaching course, we absolutely grasp that residence possession is the ultimate goal of most households and across the years we’ve got seen events deal with this group, with a myriad of help presents.

    Those offers have designed a tangible distinction to fairly a number of individuals’s life, however we should always not ignore the acceptable to a great top quality residence at a sensible price ticket for individuals who need or require to lease a house.

    With the inhabitants forecast to improve by 10% in extra of the upcoming 10 to 15 yrs, collectively with some sizeable demographic shifts, it’s important that we improve the present of homes for all tenures and never prioritise or pitch one tenure above an extra.

    Whoever is in Downing Street will will want to retain and set up a devoted base of landlord merchants who can fund the growth of the PRS, help the nation notice monetary improvement and ship a property to the elevating number of tenants who will use its suppliers.

    We look ahead to doing work with whichever bash is in electrical energy to obtain that.

    Richard Rowntree is controlling director of residence loans Paragon Lender

  • Month-to-month property finance loan payments fall for to start with time in 2024

    New property potential patrons noticed some discount final thirty day interval as declining curiosity charges introduced month-to-month fee ranges down for the preliminary time this 12 months, the House loan Bankers Association reported.

    The typical common month-to-month fee for new buy functions previous month dropped 1.6% to $2,219 from April’s mark of $2,256, in accordance to the MBA. The most up-to-date decline helped erase a few of the 2.5% hike seen a thirty day interval earlier than, pointing to the unpredictable types noticed in the housing sector above the earlier 20 years.

    “House client affordability circumstances improved in May as barely lowered house finance loan premiums and an uptick in housing inventory considerably eased the brand new improve in utility fee quantities,” stated Edward Seiler, MBA’s affiliate vp, housing economics, and authorities director, Research Institute for Housing America.

    The typical fee diminished for the to start with time on condition that December, however May’s mark even now stood 2.4% larger from $2,165 an individual 12 months in the previous. 

    The commerce group’s make investments in functions fee index, which steps dwelling affordability centered on rates of interest, home loan portions and shopper wage improvement, additionally fell 1.6% to a wanting by means of of 173.9 previous thirty day interval in contrast to 176.8 in April. 

    A bump in median earnings over the previous 12 months managed to offset newest rising housing charges round the very same interval to present the current PAPI ranking down from 176.7 an individual 12 months again as properly. Scores had been being benchmarked to 100 in 2012 to replicate the housing sector following the Wonderful Economic Crisis, with a decreased quantity indicative of better affordability conditions.

    Anticipations for premiums to tumble further this 12 months will ideally open up probabilities for the set of aspiring potential patrons who’ve been left on the sidelines, Seiler further. 

    “MBA is forecasting for property finance loan prices to tumble nearer to 6.5% by the top of the 12 months, which collectively with climbing inventory ranges and a subsequent slowdown in residence-cost enlargement, ought to support affordability,” he talked about. 

    The housing present market is by now demonstrating indications of promoting value moderation in some marketplaces, in accordance to information compiled by Redfin, The worth of the frequent residence marketed involving mid Might and mid June arrived in .3% beneath their authentic detailed profit, slipping below that mark for the initially time in 4 years, the real property brokerage recognized. Shut to 7% of sellers decreased their inquiring value, the best share on condition that November 2022 and up from 4.7% a yr in the previous.

    In the identical method, the share of homes offering earlier talked about listing value arrived in at simply beneath one particular-third, or 32.3%, which is the smallest portion due to the actual fact 2020 as effectively.    

    Aligning with Redin’s outcomes, the atypical new fee quantity declined all through the board in Might all through borrowing segments, MBA talked about. 

    Debtors making use of for loans backed by the Federal Housing Administration noticed payments slide down 1.6% to $1,924 from $1,955 in April.

    Month to month payments on freshly originated typical mortgages had been being down 2% regularly, slipping to $2,226 from $2,271   

    In the identical method, signify housing payments for shoppers of just lately constructed properties dropped 3.1% amongst April and Could, from $2,604 to $2,522.

    New purchase debtors experiencing essentially the most difficult affordability circumstances appeared concentrated in the Western U.S., as Idaho, Nevada and Arizona took the “prime” 3 locations with MBA index readings of 262.9, 258.3 and 231.4, respectively. They had been being adopted by Florida and Rhode Island.

    On the opposite finish, essentially the most economical states per PAPI had been being unfold out throughout the nation, with Louisiana clocking in at 127.4, Connecticut at 131.4 and New York at 132.2. Alaska and West Virginia took fourth and fifth locations.   

    In the meantime, affordability circumstances improved throughout racial demographics by nearly equal margins of 1.6% to 1.7%. White properties posted a May effectively ranking of 176.5, reducing from 179.4 the prior month, when the Hispanic section of debtors noticed their index ranges decline to 166.1 from 168.9. The countrywide PAPI taking a look at for Black households fell to 180.1 from 183.1.   

  • April Home loans confirms partnership with SPF Private Customers – Mortgage loan Technique

    April Home loans has launched a brand new partnership with SPF Private Purchasers.

    The partnership signifies that SPF advisers can have accessibility to April Mortgages’ vary of lengthy-term preset premiums. In addition, advisers who use the Authorized & Common Mortgage loan Club will probably be geared up to refer best prospects to SPF Personal Clientele, because the adviser is a part of the L&G Referral Professional panel.

    This implies purchasers can benefit from accessibility to merchandise they profit, while the referring adviser receives a fee, with no menace of cross or repeat product sales.

    April Mortgages offers a differ of preset cost gadgets starting from 5 to fifteen yrs, and LTVs of as much as 95% for purchase and 85% for remortgages respectively.

    Debtors who shift home or use their have cash to repay the property finance loan are exempt from Early Reimbursement Expenses, when the preset quantity on give decreases routinely because the borrower drops into decreased LTV brackets as they shell out off their stability or the house features in value.

    Commenting on the partnership April Home loans chief working officer Mark Eaton said: “April Home loans is enthusiastic about bringing critical peace of mind to the British isles mortgage business, and performing with foremost advisers like SPF Private Consumers is core to our plans.

    He added: “Not solely will the SPF advisers have receive to our floor breaking array of options, however advisers from all through the present market will probably be succesful to refer suited prospects by the L&G Referral Professional panel. Expanding our distribution on this approach means we are able to present peace of thoughts and improved certainty to increased figures of debtors and advisers.”

  • Businesses chopping business travel benefits even with potent need

    “The present financial environment is driving rigidity amid business enterprise travellers, trip managers, and business management,” defined Charlie Sultan, president of Concur Travel at SAP Concur, in a assertion.

    “Equilibrium in between flexibility and price ticket is fragile, to not level out pressures from new distribution channels and ongoing geopolitical challenges.

    Unequal travel alternate options

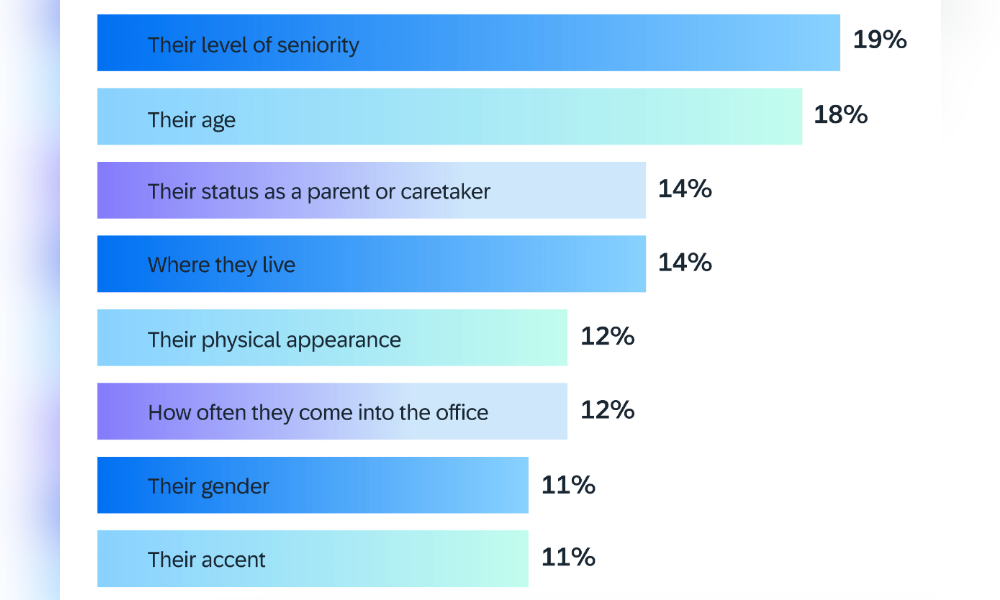
    Meanwhile, the report additionally noticed unequal alternate options for journey within the workforce, as 66% of respondents sense they have not skilled an equal probability to get firm journeys when in comparison with their colleagues.

    Between the motives they cited comprise their stage of seniority (19%), their age (18%), and their place as a mum or dad or caretaker (14%).

  • House loan-backed revenue volumes down 49% even with approvals positivity: Octane – Home loan Technique

    Whilst 2024 has launched a elevated diploma of stability and positivity to the mortgage sector, there’s proceed to carry out to do, with dwelling finance loan-backed revenue volumes above the final three months nonetheless down 49% down beneath this time final 12 months.

    This is in line with Octane Money, whose analysis of mortgage loan earnings volumes expose simply what affect a hike on fascination costs has skilled to purchaser appetites contemplating that the closing phases of 2021.

    In extra of the final 3 months (Dec 23 to Feb 24 – most present available), 61,968 dwelling finance loan-backed transactions had been recorded throughout the United kingdom. This complete is 49% beneath the whole considered by way of the same interval a calendar 12 months again.

    In level, mortgage loan trade train all through each location of the nation continues to be down 12 months on 12 months on this respect – with an individual exception.

    In Scotland, the amount of property finance loan income witnessed in extra of the final a number of months sits just about equal to that witnessed this time final yr.

    Across each single different location of Britain, dwelling finance loan revenue volumes in extra of the final a number of months have fallen by further than 50% versus this time final 12 months, with the East of England trying on the best drop at 56.5%.

    Home finance loan sector positivity has been vital in 2024 and probably the most up-to-date dwelling finance loan acceptance info from the Bank of England reveals that month-to-month approvals sat greater than the 60,000 mark for the third consecutive month in April. Guaranteed signs that the sector is acquiring its toes following a keep on the inspiration worth since September of earlier 12 months.

    The evaluation reveals {that a} keep on the inspiration price has additionally spurred indications of positivity with regard to dwelling loan product sales volumes.

    All by way of the second 50 % of 2023, some 223,465 mortgage loan-backed transactions ended up accomplished throughout the British isles, marking a 5.5% enhance in comparison with the preliminary 6 months of the 12 months.

    The most vital uplift was noticed all through the South East, wherever there was a ten.7% soar in dwelling finance loan product sales volumes by way of H2 when in comparison with H1, with London not considerably guiding with a ten.1% improve.

    Having stated that, probably the most present figures exhibit that there’s nonetheless actually some option to go proper earlier than the mortgage loan sector returns to total energy.

    Octane Funds important govt Jonathan Samuels, commented: “There is a escalating air of positivity all through the mortgage loan sector and that is hardly astonishing with approvals sitting over the 60,000 mark for a number of consecutive months and the prospect of a base cost decrease on the horizon.

    “However, positivity alone is not going to revive the market and, because it stands, there’s nonetheless some option to go upfront of we see mortgage fuelled market place exercise return to previous ranges.”

    He added: “This may be very more likely to get a while but and it’s honest to say the Lender of England’s about tentative technique to operating inflation is partly accountable. But we’re heading in the appropriate course and we depend on this market momentum to maintain constructing because the calendar 12 months progresses.”