Tag: with

  • Bank with the wealthiest customers revealed

    Bank with the wealthiest customers revealed | Australian Broker News

    News

    Bank with the wealthiest customers revealed

    Bank’s customers have increased incomes and homeownership charges
    Bank with the wealthiest customers revealed

    New monetary information from Roy Morgan’s Wealth Report revealed that Macquarie Bank has the wealthiest customers amongst the bigger banks in Australia.

    In March, Macquarie’s buyer web wealth per capita was a powerful $943,000.

    Macquarie customers not solely have increased incomes however are additionally extra prone to personal or be paying off properties, which is a big supply of wealth in Australia.

    Wealth distribution amongst banks

    St George Bank follows in second place with a web wealth per capita of $662,000, primarily on account of its robust buyer base in Sydney, the place housing costs are the highest in the nation.

    Westpac is available in third with $646,000, benefiting from an older buyer base that has had extra time to build up wealth.

    Bank of Queensland ranks fourth with a web wealth per capita of $614,000, reflecting Brisbane’s latest rise in property values.

    ING, the digital-only financial institution, has a web wealth per capita of $503,000, with a youthful buyer demographic primarily comprising Gen X and Gen Y.

    The Commonwealth Bank (CBA) has the lowest web wealth per capita amongst the banks reported, at $474,000. CBA’s youthful buyer base, predominantly Gen Z, has had much less time to build up wealth.
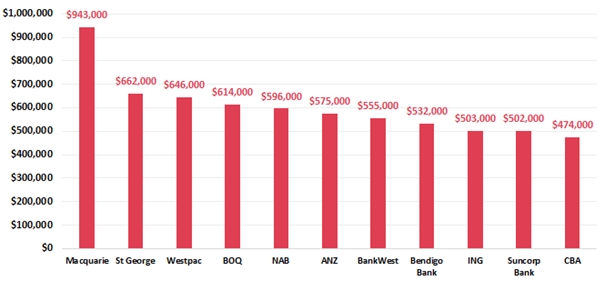
    Customer common per capita web wealth: March 2024

    Source: Roy Morgan Single Source Australia, Apr. 2023 – Mar. 2024, n = 64,597. Base: Australians aged 14+. *The eleven banks reported have a minimal pattern measurement of not less than 1,450 for the interval reported.

    Wealth variations defined

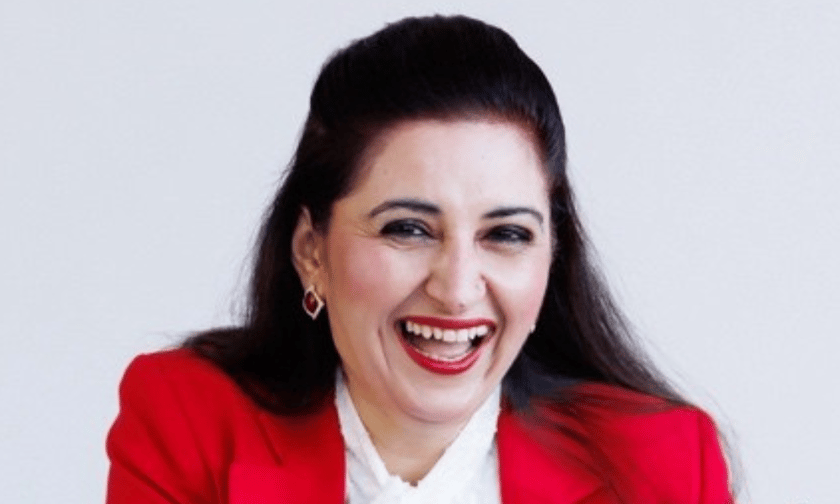
    Roy Morgan CEO Michele Levine (pictured above) defined the wealth disparity.

    “Although total web wealth per capita in Australia is $503,000, the degree of wealth varies drastically between the customers of the bigger banks, starting from $943,000 amongst Macquarie customers to $474,000 amongst customers of CBA,” Levine stated.

    Factors influencing wealth

    Levine highlighted the affect of actual property costs and generational profiles on wealth distribution.

    “These huge variations in total web wealth per capita throughout the bigger banks have quite a bit to do with actual property costs in Sydney, that are increased than wherever else in Australia. The banks with the best proportion of customers residing in Sydney are Macquarie and St George,” she stated.

    “Another issue that helps clarify the distinction in total web wealth per capita between the banks is the banks’ technology profile. Net wealth per capita is highest amongst Baby Boomers, and banks with buyer bases skewed to Baby Boomers are inclined to have increased web wealth.”

    Levine encourages a deeper understanding of those variations.

    “Understanding these variations between places and generations in web wealth ranges throughout the bigger banks presents priceless insights into how and why wealth is distributed in Australia as it’s,” she stated.

    Further detailed evaluation may be present in the newly launched Roy Morgan Wealth Report June 2024.”

    Get the hottest and freshest mortgage information delivered proper into your inbox. Subscribe now to our FREE every day e-newsletter.

    Related Stories

    LATEST NEWS
    Perth market surges

    Keep up with the newest information and occasions

    Join our mailing listing, it’s free!

  • Most landlords plan to push ahead with rent hikes: Landbay – Mortgage Strategy

    The majority of buy-to-let landlords have stated that they plan to increase rents within the coming 12 months, new knowledge from a survey from Landbay reveals.

    While almost 85% of landlords made the admission, greater than a 3rd (36%) stated they plan to increase rents by up to 5%. This is a rise from 27% in Landbay’s earlier survey in 2023.

    Meanwhile, 37% intend to improve rents between 6 and 10%, which intently mirrors the earlier survey’s findings (38%). Less than one-in-ten landlords (8%) plan to increase rents between 11 and 19%.

    Among these trying to increase rents, almost half (42%) is made up of landlords with portfolios of 4-10 properties, adopted by these with 20-plus properties at 28%. Exactly half self-manage their properties or portfolio, whereas 27% depend on an property agent and 20% on an expert administration firm.

    While greater rates of interest proceed to play a consider what landlords cost for rent, so do greater operational prices. Of the landlords set to increase rents this coming 12 months, greater than one-in-ten (16%) pay in extra of 13% of their rental revenue on property administration.

    Just beneath a 3rd (30%) pay 5% of their rental revenue, whereas barely much less once more (29%) pay between 9 and 12%.

    The findings kind a part of Landbay’s newest survey which questions present landlords on a wide range of matters to decide their angle and intentions. The survey uncovered the important thing elements going through landlords and their ideas on upcoming regulation and the way forward for the buy-to-let market.

    Landbay director of gross sales and distribution Rob Stanton commented: “Whereas earlier than, rising rents would usually replicate the rising demand for good high quality rental lodging, in the present day’s market now means landlords even have to consider greater rates of interest and working prices too. With no various, many landlords have to contemplate rising rent to cowl their outgoings.

    “As a lot of landlords take a look at their remortgage choices, they are often inspired by the innovation we’ve seen from lenders throughout the buy-to-let market. At Landbay for instance, we’ve simply expanded our like-for-like remortgage vary with new two-year fastened and tracker merchandise – supported by new decrease stress testing at simply payrate.”

    He added: “This change to affordability calculations is already proving common and useful for each brokers and their purchasers.”

    (Landbay surveyed its total landlord database of greater than 1,500 landlords.)

  • Metro Bank launches into limited company BTL with rates from 3.99% – Mortgage Strategy

    Metro Bank has at this time launched its first Limited Company Buy-to-Let product as a part of its continued deal with changing into a number one specialist lender.

    The financial institution’s new merchandise provide a most LTV of 75% with present rates beginning at 3.99%.

    The mortgage curiosity quantity is calculated on the identical fee of 125% as for the lender’s customary purchase to let stress rates.

    To qualify the company have to be non-trading and limited to solely holding residential property and never engaged in wider actions, i.e. it have to be an SPV.

    Up to 4 administrators and shareholders are accepted and no minimal revenue is required. However no less than one director have to be incomes an revenue aside from rental.

    The most age permissible for an applicant is 85.

    Metro Bank director of mortgage distribution Charles Morley says: “Launching a Limited Company Buy-to-Let product has been on our agenda for a while and we’re actually excited for it to go reside at this time as we proceed our journey to changing into the primary specialist lender on the excessive road.

    “Owning a property portfolio inside a Limited Company moderately than as a person can carry an a variety of benefits. While Limited Company Buy-to-Let is already an established market, we see the potential for it to develop even additional.”

  • House prices show recovery with 0.4% rise in June: e.surv – Mortgage Strategy

    “Of course, inside that there are regional tales. The 1.6% year-on-year lower in home prices seen throughout England and Wales nearly disappears if we exclude London and the South East. The North East and Wales proceed to guide the cost in bettering home value efficiency.

    “Going ahead, in gentle of the Labour win, we must always see additional enhancements in purchaser sentiment as the federal government units out to ship on its manifesto pledges. These are bold and can take time however embrace creating various New Towns, rethinking the inexperienced belt, necessary targets for Local Authorities, a Freedom to Buy Scheme, and a pledge to decrease the stamp responsibility threshold for first-time patrons in April 2025.

    “Also, we might now see motion from the Bank of England on rates of interest, given the bettering inflation image, which is able to enhance affordability for patrons.”

  • Household preliminary: Niti Bhargava launches GB Financiials with vision for community

    Household very first: Niti Bhargava launches GB Financiials with vision for neighborhood | Australian Broker News

    News

    Loved ones 1st: Niti Bhargava launches GB Financiials with vision for group

    Broker departs franchise product, retains aggregator

    Family first: Niti Bhargava launches GB Financiials with vision for community

    Following a affluent occupation in a dealer franchise, Niti Bhargava has launched into a brand new chapter with the beginning of her possess dwelling mortgage brokerage company, GB Financiials.

    The establish holds distinctive meaning, with “GB” symbolizing the initials of her two children, creating this enterprise a deeply personal 1.

    Bhargava (pictured earlier talked about) is joined by her husband Varun as co-founder, and the few is actively developing a workers to reinforce their vision. Notably, Bhargava will protect her affiliation with SFG, expressing her deep appreciation for their unwavering help.

    “Ready to generate a brand new chapter of outcomes, celebrations, milestones and an outstanding journey in new financial 12 months 2025 with my affiliate in crime, Varun Bhargava,” Bhargava talked about.

    “Exciting moments ahead.”

    A Want for Restructuring and Community Aim

    The determination to launch GB Financiials stemmed from a need for a clear get began.

    “I simply required to restructure my enterprise,” acknowledged Bhargava, who earlier was a director in Resolve Finance Derrimut within the suburbs of Melbourne.

    “In within the neighborhood of future, we’re considering to include different corporations with our broking group as properly.  So, a up to date start from a refreshing standpoint was demanded.”

    Though Bhargava could also be restructuring, she even now retained her aggregator, SFG, and is “very grateful” for their help.

    “Their motivation, appreciation and involvement in my small enterprise is unwavering,” she acknowledged. “I’m definitely privileged to proceed on turning into an SFG member and I look ahead to what’s following.”

    The relevance of a stable help community

    Whilst pushed by enthusiasm and a strong assist community, Bhargava acknowledges the troubles of commencing a brand new enterprise, with the system demanding substantial psychological and bodily resilience.

    She urges brokers who is likely to be desirous about an identical path of self-employment exterior of franchise variations to entry deep of their community.

    “To be able to cope up with quite a few variations has undoubtedly taken a serious toll on my bodily and psychological wellness,” defined Bhargava.

    “When you’re beginning something with most quantity of enthusiasm, dedication and adore, you however must have to bolster that self-self confidence, can-do angle and rock-reliable willpower in you.”

    Nevertheless, she harassed that brokers actually do not must do it by yourself.

    “Look throughout and you will note a number of supporters about you,” she acknowledged. 

    “I’m so completely happy that this discipline has offered me life time friendships, connections and supporters who had been being at all times there for me. Grateful for my journey so significantly and hopeful for a productive calendar 12 months upfront.”

    Group initially, moral lending

    Bhargava envisioned a space to not solely provide customary property finance mortgage corporations but additionally maybe combine different fiscal suppliers within the foreseeable future.

    Additional importantly, GB Financiials is crafted on a predominant value proposition: “Community Very first, Moral Lending.”

    “Becoming a voice for migrant existence signifies sharing tales that usually go unheard, shedding light on the troubles and triumphs who depart all the things on the rear of in look for of much better prospects like I did fairly a number of years in the past,” Bhargava acknowledged after attending a contemporary enterprise occasion.

    This dedication will proceed on to be a cornerstone of her new small enterprise.

    “I’ve normally taken pleasure in supporting my neighborhood in each potential method and hope to proceed to drive the business to present again once more and do higher.”

    Relevant Stories

    Maintain up with probably the most up-to-date info and events

    Join our mailing document, it’s freed from cost!

  • Cambridge & Counties strengthen true estate workforce with 3 new hires – Home finance loan Tactic

    Specialist lender Cambridge & Counties Financial establishment has made a couple of new appointments to its Actual Estate Finance workforce.

    Lewis Ashford has joined the monetary establishment as senior firm progress supervisor masking the South West space. He previously labored for The Co-operative Lender, the place he expended the ultimate 15 many years performing in a wide range of roles, together with enterprise development and marriage administration specialising in buying and selling and industrial companies.

    Emma Harris (pictured) joins as partnership supervisor centered on the (*3*) market. She retains a prosperity of present market understanding within the two real estate lending and asset finance, buying previously labored for Synergi Finance. Her numerous occupation has additionally offered 15 years in London main a specialist product sales crew.

    Victoria Pearce has been appointed enterprise enterprise development supervisor for the Midlands. She holds just about 23 a number of years of working expertise within the enterprise, buying started her occupation at Santander proper earlier than transferring to Aldermore. For the length of her vocation, she has specialised in all areas of family, skilled and specialist lending.

    Cambridge & Counties head of precise estate finance Jayne Follows commented: “Real estate finance stays on the core of the financial institution’s group product, and these a couple of new appointments present how deeply dedicated the monetary establishment continues to be to the market place.”

  • Fiba partners with Grant Thornton’s economical expert services bargains group – House loan Tactic

    The Financial Middleman & Broker Affiliation (Fiba) has partnered with Grant Martin ReynoldsThornton’s economical suppliers offers workforce.

    The partnership implies Fiba, part of SimplyBiz, customers may have entry to Grant Thornton’s built-in, multidisciplinary Specials Staff and its data of the expert finance sector, like current M&A (mergers and acquisitions) traits, deal buildings, and valuations.

    Fiba chair Martin Reynolds (pictured) states: “We are blissful to welcome Grant Thornton, and the calibre of help it is able to provide, to our loan supplier panel and associates trying to find help all through their options on this sector.

    “We search forward to embarking on the journey of coaching about their specialist observations and being acquainted with of points inside our sector and attaining a deeper comprehension.”

    Grant Thornton’s company finance head of fiscal suppliers M&A Simon Blackburn states: “Whilst sector M&A motion has been subdued in new a number of years because of the impression of the likes of Covid-19, rising inflation and fascination fees, starvation for M&A is returning as latent purchaser need continues to be excessive, curiosity premiums floor to have stabilised and market place optimism has elevated.

    “We seem ahead to sharing our sector and M&A insights with the FIBA membership and having the prospect to show our steering to the sector.’’

  • Industry all set to function together with Rayner to fulfill housing obstacle – Property finance loan Method

    The specific individual tasked with overseeing Labour’s formidable housebuilding programme is Angela Rayner.

    Propertymark principal govt  Nathan Emerson is looking ahead to working intently with the lately introduced Deputy Prime Minister.

    “It is important housing performs a important precedence shifting ahead, as we’ve witnessed a number of a long time of housing want considerably outstrip supply. At this time we’ve a state of affairs that seems like it’s on a knifes edge, specifically with a populace that’s predicted to develop to round 70 million  inside the up coming 10 years.”

    Emerson added: “There ought to be vital cross-party dialog that units a really clear strategy relocating forwards, and for this to happen, we’ve to have broad stakeholder involvement, enormous ranging infrastructure enhancement and all included ought to appear to the superior use of engineering for each of these notion and ongoing transport and supply.”

    Coventry for intermediaries head of middleman relationships Jonathan Stinton would love to see a much more sure half designed.

    “Housing is a essential location of protection which impacts the lives of tens of tens of millions of voters. Though it does have illustration on the cupboard desk beneath Angela Rayner (as Secretary of Point out for Levelling Up, Housing and Communities), it is only one of fairly just a few protection places and roles that she in the intervening time holds in federal authorities, which embody Deputy Key Minister. Housing is arguably simply as essential as healthcare and training, so shouldn’t it have its have, devoted seat on the cupboard desk?”

    He supplies: “Creating a brand new ‘Secretary of Point out for Housing’ posture would show the federal government’s dedication to undoubtedly acquiring to grips with and tackling the difficulties experiencing the UK’s housing market. Additional importantly, it will assure housing protection is launched additional extra up the priority itemizing and receives the discover it deserves at the very best echelons of authorities.”

  • Mutuals established out strategy to meet up with Labour pledge to ‘double’ sector   – House loan Method

    The Making Societies Affiliation and different mutual our bodies have composed to the brand new Key Minister urging him to stick to Labour’s manifesto pledge to “double” the dimension of the sector and unlock new finance.  

    The letter to Keir Starmer claims: “The co-operative and mutual sector is united throughout an ambition for growth and apparent coverage priorities for unlocking it.   

    “Labour’s manifesto pledge to take away boundaries to our growth, which embrace acquire to finance, aligns completely with our preparations.”  

    It factors out that mutual and co-operative organizations have put collectively once-a-year revenues of £87.9bn, equal to 3.5% of the nation’s gross home services or products.  

    The our bodies additionally set out a ten-issue method to increase the sector.   

    This contains:  

    A brand new govt minister for mutuals and co-operatives  

    The establishment of a council to companion with govt to present the pledge to double the measurement of the cooperative and mutual sector  

    Treasury to set up a British Business enterprise Bank fund solely for brand spanking new and increasing mutuals and co-operatives  

    “We and our member companies are a ready companion on your governing administration,” says the letter signed by Co-operatives Uk, the Affiliation of Economic Mutuals, the Developing Societies Affiliation and the Association of British Credit Unions Minimal.  

    The switch comes proper after a invoice to allow Setting up Societies to elevate lending grew to turn into 1 of the closing objects of legal guidelines to make its method by Parliament ahead of the final election.    

    The Making Societies Act 1986 (Modification) Invoice, handed in Could, was facet of the “wash up”, which lets laws to be handed instantly, prior to parliament dissolved ahead of the 4 July countrywide ballot.  

    The genuine bill was handed virtually 4 a long time again, and on the time constrained the portion of cash making societies might elevate from {dollars} marketplaces to 20%, with the remaining from their prospects.     

    This has been regularly lifted and now stands at 50%.    

    The modification retains this restrict however excludes 3 types of funding from the calculation, which in end result permits mutuals to elevate far extra cash from outdoor assets. 

    These shield:    

    Funds accessed from the Bank of England in anxiousness situations    

    Varieties of reduction-absorbing monetary debt setting up societies could maintain to assure that, actually ought to the enterprise fail, merchants pretty than taxpayers bear losses    

    Sale and repurchase agreements for styles of liquid property creating societies hold as capital buffers    

  • Residence charges flat in June with marginal annual development: Halifax – Property finance loan Technique

    Home prices in the Uk had been principally flat in June, down simply .2% on a month to month foundation, the latest Halifax Home Cost Index has recognized.

    On an once-a-year basis, residence charges had been being up marginally, with growth of 1.6%, equal to the 1.5% recorded a month prior.

    The frequent home price now stands at £288,455, down barely from £288,931 in May maybe.

    The strongest home value progress was recorded in Northern Ireland, the place development of 4% was discovered in the 12 months to June and on a month-to-month foundation, residences rose 3.3%.

    The common value of a belongings in the nation is now £192,457. 

    Of England’s places, the North West noticed the best residence worth improve, up 3.8% on a yearly foundation to an atypical of £231,351.

    Dwelling charges in Scotland additionally elevated, with a traditional home now costing £204,663, +1.6% much more than the 12 months previous to. In Wales, family charges grew yearly by +2.7% to realize £220,197.

    Eastern England was the one area or nation all through the Uk to sign-up a decline in residence charges in regards to the last yr, wherever they now typical £328,747, down -.9% in June on an annual basis.

    London proceeds to have essentially the most highly-priced property costs in the United kingdom, now averaging £536,306, up (+.9%) in comparability to last calendar 12 months.

    Halifax head of mortgages Amanda Bryden claims: “UK home charges stayed pretty flat for the third successive thirty day interval in June, with the slight fall equal to considerably lower than £500 in {dollars} phrases. On an yearly foundation, dwelling value ranges posted a seventh consecutive month of 12 months-on-calendar 12 months development, with the common United kingdom home worth now standing at £288,455.

    “This continued stability in dwelling value ranges – climbing by simply +.4% to date this 12 months – demonstrates a trade that continues to be subdued, although over-all train has been recovering. For now it’s the scarcity of supplied properties, somewhat than demand from clients from potential patrons, that proceeds to underpin larger value ranges.

    “Mortgage affordability is nonetheless the largest downside going by means of each homebuyers and these coming to the conclusion of preset-phrase offers. This issue is probably to be eased slowly, by a mix of decrease curiosity charges, rising incomes, and extra restrained development in property promoting costs.

    “While in the brief-term the housing trade is delicately properly balanced and delicate to the speed of change to Foundation Fee, primarily based totally on our present anticipations residence charges are most likely to extend modestly by the comfort of this yr and into 2025.”