Tag: Politics and policy

  • HUD adds translations of property finance loan servicing paperwork

    The Section of Housing and Urban Enhancement has developed translations of 19 Federal Housing Administration home loan servicing paperwork to enhance data and information entry to debtors with restricted English proficiency.

    These paperwork at the moment are obtainable within the 5 principal languages most spoken by U.S. residents apart from English: Chinese, Korean, Spanish, Tagalog and Vietnamese.

    “We carry on to get the job performed to remove language acquire boundaries for debtors with FHA-insured house loans,” talked about Federal Housing Commissioner Julia Gordon in a push launch. “We really feel it’s actually very important for debtors to completely grasp the chances for paying for a family and for accessing help if an current borrower has issues in creating their mortgage loan funds.”

    HUD desires to make sure all homebuyers, particularly these within the present marketplace for their first property, have entry to knowledge about its applications, Adrianne Todman, performing secretary, talked about in a press launch.

    “This widespread-sense motion will help households notice their aspiration of possessing a home,” Todman ongoing. “Currently, we’re utilizing a vital transfer in the direction of a further inclusive, quite a few and equitable period of property house owners.”

    Beforehand, HUD translated 40 origination and homeownership schooling paperwork into people an identical 5 languages.

    Considering the truth that August 2023, the FHA has important house loan collectors desirous to obtain insurance coverage insurance policies to file the Supplemental Consumer Facts Type, additionally recognised as Kind 1103, with every particular person software program. That type is utilised to report the borrower’s selection for the language they want to discuss in.

    The SCIF was very first a Federal Housing Finance Agency want for monetary loans submitted to Fannie Mae and Freddie Mac.

    Whilst the sort calls for to be bundled within the mortgage file, the borrower can decide to offer all, some or none of the data and information requested.

    In April, the FHFA issued a final rule to codify wants related to honest lending and most well-liked language use.

  • California sets $20B of state bond steps Bay Area adds $20B a lot more

    California’s presidential election poll in November will embody $20 billion bucks of statewide bond measures, with $20 billion extra in only one regional bond election.

    At the purpose out diploma, lawmakers reached agreements earlier week on two $10 billion customary obligation bond actions that had been heading towards acceptance in flooring votes this 7 days.

    The actions have been being set forward as Senate Bill 867, a $10 billion statewide Ok-14 school constructing bond measure, and Assembly Invoice 247, a $10 billion climate bond measure.
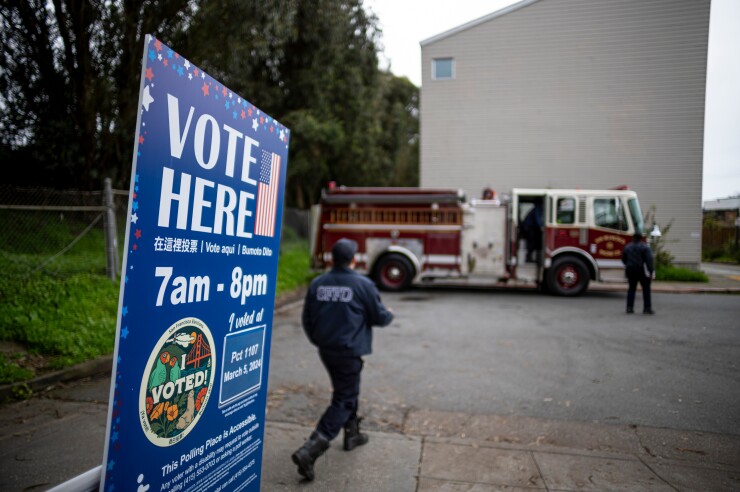
    Signage outside a polling station in San Francisco A indicator outdoors a polling station in San Francisco in March. Voters there’ll take into consideration a $20 billion regional housing bond in November, in addition to $20 billion of situation GO bonds.

    Bloomberg News

    All these steps will compete for consideration on the poll in what some predict might be a doc 12 months for varsity district bond measures, in an election by now juiced with a $20 billion regional housing bond measure within the San Francisco Bay Spot.

    The statewide actions have been place forward as Senate Bill 867, a $10 billion statewide Ok-14 school development bond measure, and Assembly Monthly invoice 247, a $10 billion climate bond consider.

    Supporters say the college bond would strengthen the lives of tens of thousands and thousands of children and modernize normal public colleges, regardless that the climate bond would fund clear up h2o, wildfire avoidance and restoration initiatives.

    “These bond actions are very important to the long run of this level out, and commit in our youngsters, their neighborhood universities, they usually make certain communities large and modest have accessibility to wash ingesting h2o and are wildfire protected,” stated Sen. President Pro Tempore Mike McGuire, D-Healdsburg.

    The Senate chief included that he ran for the college board on the age of 19 after observing his excessive school tumble into disrepair.

    “Our learners, lecturers and crew ought to have superior, particularly folks in underserved universities precisely the place sources are restricted and services are outdated, and at conditions, hazardous,” McGuire stated.

    Proposition 51, the ultimate statewide bond consider to help school design, was permitted by voters in November 2016 and has extended been depleted.

    If the statewide college bond measure passes, space districts will need matching money to protected state money.

    “I really feel we’re going to see a doc selection of GO school bond actions on the poll in 2024,” claimed Adam Bauer, president and principal authorities officer of municipal advisory company Fieldman, Rolapp & Associates.

    In 2020 and 2022, the choice of college bond measures on the poll was light, and the require for school development funding has remained, Bauer claimed.

    “In 2024, school districts have been ramping as much as make up for the absence of bond measures floated in extra of the earlier cycles,” he stated.

    He verified that college districts are working into circumstances precisely the place they won’t have sufficient money for initiatives as a result of truth they have not handed a bond in a while.

    “That is especially perfect, and they’re hopeful the state would set a measure on the poll to assist with matching money,” he talked about.

    Of the statewide climate bond consider, McGuire defined the communities he represents have been devastated by wildfires. Making certain that the state’s communities have the sources to defend themselves from wildfires, drought and floods is “vital to the prolonged-phrase success of the purpose out,” he talked about.

    “Our historically underserved communities on the doorway strains of the native local weather disaster couldn’t have enough money to attend any lengthier, requiring us to switch with urgency to strengthen California native climate resiliency,” reported Assemblymember Eduardo Garcia, D-Coachella, who co-lead the Assembly native local weather bond doing work group with Assemblymember Lori Wilson, D-Suisun Town.

    SB 867 would commit a naked minimal of 40% of the bond funds towards disadvantaged communities.

    The cash can be divided seven means: $3.8 billion for protected ingesting ingesting water, drought and flood protection $1.5 billion for wildfire and forest resilience $1.2 billion to cope with sea stage rise $1.2 billion to guard biodiversity $1.55 billion for park growth and out of doors recreation areas $450 million for excessive warmth mitigation and $300 million for climate-friendly and resilient ranches and farms.

    The climate bond would make investments in “our potential by prioritizing important calls for these varieties of as protected and fairly priced ingesting water entry, wildfire prevention, extreme heat mitigation, sustainable agriculture, and totally clear, renewable energy,” Wilson stated.
    Adam Bauer, president and chief executive officer of financial advisory firm Fieldman, Rolapp & Associates “I think about we’re heading to see a historical past quantity of GO school bond measures on the poll in 2024,” stated Adam Bauer, president and principal govt officer of Fieldman, Rolapp & Associates.

    Fieldman, Rolapp & Associates

    The $20 billion regional primary obligation bond measure within the San Francisco Bay Location would help assemble or preserve 90,000 reasonably priced households all through the 9-county location, supporters say.

    The Bay Location Housing Financing Authority Board, a regional board comprised of neighborhood elected officers, unanimously agreed at their June 26 convention to place the Bay Area’s first regional housing bond on the standard election poll.

    Only 17% of the state’s homebuyers can have enough money the state’s $814,280 median-priced single partner and youngsters home, with 24% able to afford to pay for a $655,000 median-priced condominium or townhome, in accordance to a California Affiliation of Realtors housing affordability report revealed Might 9.

    To afford to pay for a solitary-family members home, in accordance to the CAR’s calculation, potential consumers need to need to make $208,400 yearly to make month-to-month funds of $5,120, like principal, curiosity and taxes on a 30-year preset-level mortgage with a 6.86% curiosity quantity.

    San Mateo and Santa Clara — two counties within the BAHFA location — are the initially and subsequent most expensive components to acquire a residence, in accordance to Automobile.

    If authorized, $10.4 billion would go to assemble 36,000 very reasonably priced properties, $3 billion would go to guard 14,000 present moderately priced residences and $6.6 billion can be utilized as versatile funding to take care of and current homebuyer assist for 22,000 properties, in line with a report.

    Below current laws, the BAHFA measure must have approval by a minimum of two-thirds of voters to go. The bonds can be repaid with the advert valorem residence tax levy within the nine-county location.

    But the state’s voters may even be pondering of Assembly Constitutional Amendment 1, which might established the voter threshold at 55% for voter approval of bond actions for cost-effective housing and infrastructure. In accordance to BAHFA, if ACA1 passes, the authority’s bond consider would solely need a 55% vote threshold.

    “Today’s vote is the fruits of so quite a few a very long time of effort by so many of us all throughout our space,” BAHFA chair Alfredo Pedroza, a Napa County supervisor, acknowledged in a June 26 assertion. “The Bay Area’s longstanding housing affordability challenges affect all of us, our mates, our neighbors and our members of the family associates.”

    The bond consider would break up 80% of the money between the 9 counties (and the cities of San Jose, Oakland, Santa Rosa and Napa, each single of which carries a lot more than 30% of their county’s reduced-profits housing will want), in proportion to every county’s tax contribution to the bond. The remaining 20%, or $4 billion, can be made use of by BAHFA to construct a new regional system to fund economical housing growth and preservation assignments throughout the space.

    The measure additionally would develop a citizen’s oversight committee and bond proceeds account. The committee would report back to BAHFA and the Association of Bay Location Governments authorities boards. There would even be an once-a-year neutral audit.

    It stays to be witnessed if voters could have the precise enthusiasm to approve bond steps because the authors have for the techniques they might assist.

    Sonoma Point out University political science professor David McCuan identified that Gov. Gavin Newsom and lawmakers beforehand designed efforts to lighten the stress placed on voter’s discover by dealing with some initiatives legislatively, considerably than positioning them simply earlier than voters.

    “There might have been 22 to 24 statewide initiatives on the poll quite there might be 9 to 11,” McCuan claimed.

    “There is a lot weighing on voter’s pocketbooks by now, together with it staying a contentious election yr,” he stated.

    Take into consideration all the attention changing into equipped to the battle amongst earlier President Donald Trump and President Joe Biden, he defined.

    “Bond steps have accomplished pretty properly on the neighborhood quantity prior to now 10 or 15 a number of years, however California has been approaching the bond indebtedness ceiling,” he talked about. “When that affliction takes place, it’s actually simpler to get a ‘no’ than a ‘sure’ vote.”

    Regional poll actions, along with however not confined to tax and college bonds have notched a 70% approval quantity, and statewide actions have skilled a from 33% to 38% approval payment within the earlier 10 a few years, he reported.

    McCuan anticipates that fiscal measures, bond steps and steps to rework voter thresholds won’t fare in addition to they’ve within the earlier. If they have been being grabbing 70% of the vote beforehand, he’s predicting the standard acceptance value to fall as very low as 50%.

  • The housing paradox standing in the way of a Fed rate lower

    Lisa Cook Federal Reserve Gov. Lisa Cook dinner said in a speech previous thirty day interval that measuring housing charges in an financial system in which the the overwhelming majority of households are operator-occupied gives a impediment, however talked about that the observe of like implied market rents in inflation metrics was “defensible.”

    Bloomberg Information

    Housing bills appear to be the final hurdle involving the Federal Reserve and its intention of bringing inflation again once more right down to its 2% consider, and the challenges there are most certainly to worsen proper earlier than they get higher.

    Due to the truth of how shelter costs are tracked by the nation’s foremost price ticket indexes, housing costs are most certainly to push up measured inflation round the coming 12 months, in response to a report from the Federal Reserve Financial establishment of Boston, regardless of data demonstrating that lease costs have primarily stabilized.

    The Boston Fed tasks the core readings — people with out unstable meals and electrical energy courses — of the shopper worth index, or CPI, and the explicit consumption bills, or PCE, will enhance by .74% and .29%, respectively, all through the up coming 12 months just because of larger housing costs. Meanwhile, sector rents, as tracked by the analytics enterprise CoreLogic, have been up simply 3% year-around-yr in April, very effectively under the COVID-19 era-high of greater than 13% and on par with their pre-pandemic frequent. 

    Fed officers have acknowledged that the data lags just like housing costs have taken longer to take pleasure in out than they skilled earlier anticipated, noting it may very well be a very long time in advance of market traits and inflation readings sync up. But some others say the downside may very well be a extra basic one, associated to how housing charges are calculated in the U.S. — which differs in vital means from different vital globe economies. 

    Equally CPI and PCE measure the value of housing — additionally known as shelter — by way of modifications in rental charges. But, on account of the truth excess of 65% of households in The us are operator-occupied, these indexes try to include owned residences by way of what’s recognized as homeowners’ equal lease or imputed lease, that are estimates of what a property proprietor would fork out for his or her properties if they’ve been leasing. 

    For most dwelling homeowners, their housing expenditures — particularly their month to month dwelling mortgage funds — haven’t improved drastically in present a few years. Most are locked in at or round traditionally minimal costs. However believed rental growth from property homeowners makes up a even bigger share of housing worth indexes than true rents, and all these homeowners’ equal rents have risen extra swiftly by means of the earlier two a few years.

    Imputed lease accounted for roughly 76% of the over-all housing classification in simply the PCE index, which is tracked by the Bureau of Economic Investigation. Real rents paid by tenants of non-farm housing would make up about 22%. From March 2022 as a consequence of December 2023, homeowners’ equal rents rose about 15% while tenant rents rose 13.9%. In basic housing costs ended up up 14.7% for the period of that interval.

    Other worldwide places methodology housing cost measurements in any other case. The European Central Bank doesn’t embrace issues like operator-occupied housing expenditures in its inflation tracker, the Harmonized Index of Purchaser Rates. The CPI readings utilized by the Bank of England and the Financial establishment of Canada the two incorporate possession prices comparable to home mortgage want, insurance coverage protection and renovations, relatively than asking householders to estimate a rental worth for his or her properties.

    Louise Sheiner, an monetary analysis fellow at the Brookings Institution, talked about searching for to measure housing charges in a uniform way is troublesome, which is why totally different jurisdictions tactic it otherwise. 

    CPI and PCE embrace issues like homeowners’ equal rent to account for the consumptive expenditures householders facial space, Sheiner said, whereas she well-known that in the newest environment, in which home values are persevering with to extend, the consider doesn’t precisely replicate the impression of inflation on people homeowners.

    “It is conceptually improbable how they do it, nevertheless it additionally may set a little little bit significantly much less extra weight on inflation by householders who’re fantastically listed,” she claimed. “They particular person the property so each equally their revenue goes up and, at the related time, their implicit lease goes up far too, so they aren’t worse off in any respect.”

    Fed Gov. Lisa Cook dinner additionally highlighted points in monitoring housing costs by means of a talking engagement with the Financial Club of New York in June, noting that incorporating costs in locations the place by homes are predominantly owned alternatively than rented was 1 of the “vital measurement difficulties” related to inflation. 

    Nevertheless, Cook well-known that the National Academies of Science, Engineering and Medicine have endorsed factoring some variation of homeowners’ equal lease into shopper pricing indexes.

    “Together with [owners’ equivalent rent] is a defensible element to do,” she talked about. 

    Cook added that irrespective of how different central banks consider housing costs, the Fed’s go-to learning has in depth included imputed rent, so it usually are not capable of rework its consider now.

    “Not each European central monetary establishment, in its calculation of inflation, options housing in that consider, so there may be a ton of heterogeneity and ours is the PCE index that we fork out discover to,” she defined.

    Nonetheless, regardless of of how inflation is calculated, some economists say there was ample improvement on different parts of the financial local weather to warrant an want worth reduce. The latest CPI report demonstrates inflation rose 3.3%, pushed primarily by shelter, which was up 5.4% in extra of the previous 12 months. Similarly, PCE, which provides housing a lot much less fats, was up 2.6% on the yr, with housing accounting for an outsized half of the development. 

    Whilst conventional data means that an fascination payment slice would spur want for property purchases, therefore driving up worth ranges extra, Nancy Vanden Houten, a senior economist at Oxford Economics, talked about lowering charges is critical to increasing the provide of every on the market and rental homes all by means of the place. 

    “The extra we see improvement on these different components of inflation, the Fed may have the freedom to look at housing a minor little bit otherwise,” Vanden Houten talked about. “High charges even additional constrain present in the housing business, which is a single of the crucial points propping up promoting costs. If you need a lot extra supply and a few softening in residence value progress, reduce want costs would assist in that regard.”

  • FHLB’s Ryan Donovan on an amazing calendar year and what is actually subsequent

    The Federal Home Mortgage Financial establishments went lower than the microscope ultimate calendar year and the scrutiny persists with its regulator on the lookout for enter on its cost-effective housing plan and position within the residence finance mortgage market. 

    FHLB Ryan Donovan Headshot.png

    The system’s second-ever affect report launched earlier week could maybe assist in all these evaluations because it consolidates a few of the portions and utility descriptions linked to its enhancements, cheap housing, and different exercise within the earlier 12 months. 

    What follows are some remarks on the report from Ryan Donovan, president and CEO of the Council of Federal Property Personal mortgage Banking establishments, with an eye in direction of what it might probably signify for 2024.

    The queries and responses that adjust to have been edited and condensed.

  • Powell: Fed independence has ‘very wide assist’ from each parties

    Fed Chairman Jerome Powell Jerome Powell, chairman of the Federal Reserve, talked about Tuesday that he’s not imagining in regards to the potential clients of earlier president and presumptive Republican nominee Donald Trump profitable re-election, stating that the central financial institution’s political independence has wide assist from each political get-togethers.

    Bloomberg Information

    Federal Reserve Chair Jerome Powell just isn’t involved a few second presidential phrase for Donald Trump.

    For the period of a panel dialogue hosted by the European Central Lender in Portugal on Tuesday, Powell was questioned position-blank how anxious he was that Trump — who was vital of the Fed’s financial procedures throughout his time within the Oval Business and brazenly talked over the potential for dismissing Powell as chair — might threaten the central financial institution’s independence.

    “I’m not focused on that in any respect, and that is not only a conversing stage,” Powell informed CNBC anchor Sara Eisen, who moderated the dialogue. “I actually think about we simply keep finishing up our work. The U.S. financial local weather, we’ve got 4% unemployment, it truly is growing at 2%, inflation is at 2.6%, allow us to maintain that possible, let’s do our work. Record will determine.”

    Powell added that, no matter who’s within the White House, the Fed’s independence is supported and bolstered by bipartisan assist in Congress.

    “Support for the Fed’s independence may be very increased during which it truly points — on Capitol Hill, in each of these political parties, amid the leaders and a lot of the subsequent,” he claimed. “So, I be involved about having the work correct, which is what I stress about.”

    The dialogue will come significantly lower than every week quickly after the first dialogue regarding Trump, the presumptive Republican nominee, and President Joe Biden, the very possible Democratic prospect. A really poor effectiveness by the incumbent has led political analysts — as correctly as Treasury business people — to element in a higher chance that Trump returns to enterprise workplace future 12 months. 

    Powell declined to weigh in on quite a few protection points at take part in within the presidential election, which incorporates people related to commerce, immigration and the environment, noting that they lie exterior the Fed’s remit. He did reiterate his ongoing concern in regards to the price of enlargement of the U.S.’s countrywide bank card debt.

     
    “The United States is managing a fairly giant deficit at a time after we are at complete work. The stage of economic debt we’ve got just isn’t unsustainable, the trail we’re on is unsustainable. That is totally not controversial,” Powell defined. “I’d have believed that is something that should be a prime-amount concern, and also you do hear it from a great deal of elected officers, but it surely ought to actually be a critical focus possible ahead. How will we get again once more to a sustainable path? Mainly as a result of, you can’t function these sorts of deficits in excellent financial intervals for very very lengthy.”

    Powell’s counterpart, ECB President Christine Lagarde, equally declined to weigh in on fashionable political developments in Europe — considerably the present French legislative election which can end in a divided authorities for the continent’s 2nd-most essential financial local weather. 

    Largarde did, alternatively, break from Powell in a single specific vital means: Endorsing central monetary establishment involvement in addressing native local weather enhance. 

    “I’m involved, as an individual further than as president of the ECB, in regards to the backlash there may be in opposition to the wrestle versus native local weather rework,” she stated. “Some would argue that it has little or no to do with central banking, however I’d contend that is truly not the case. It does have a ramification, have an effect on that we actually must be acutely aware about. But it is a hazard that’s there, that can arrive to hang-out us if we do not do considerably about it.”

    Powell, who noticed that his best subject for the safety of the U.S. banking approach is a cyber assault on a big cash institution or financial market utility, talked about the Fed doesn’t need to drift from its express oversight mandates. 

    “We have been supplied this terrific duty and glorious powers and it may be essential that we get it correct, and we have been defined to to remain out of politics and do [our] occupation, and which is what we do,” he talked about. “We don’t try to get included in points that aren’t our considerations.”

  • Even streamlined pandemic forbearance confused some: CFPB

    The Consumer Economic Defense Bureau has launched a overview of pandemic servicing intervention that means no matter methods taken to make it broadly accessible, distressed debtors described a diploma of bother with the entry to and exits from it.

    Almost 50% skilled questions on whether or not they have been being succesful to make use of forbearance speculated to be broadly made obtainable to debtors with hardships linked to COVID-19, primarily on request.

    Even with that streamlining, way more than a third have been being unclear on how one can settle up later, and over 1-fourth noticed the overall course of far too difficult.

    The report additionally positioned that not solely have been being 1 in 15 debtors restricted English proficient, much more than 20% ended up multilingual.

    The conclusions are according to the fact {that a} moderately important share of debtors who’re multilingual is a few factor which is drawing purpose on the federal protection entrance and the business at big.

    “As the amount of debtors and prospects all through the place more and more converse different languages, the wish to present them, according to that, raises,” talked about Joshua Weinberg, president of Firstline Compliance, in an interview beforehand this yr.

    Pandemic ordeals may probably supply clues to means regulators might maybe be rethinking language route in servicing. 

    “There had been a complete lot of troubles with individuals exiting forbearance. I really feel acquiring that amount from COVID gave us information, and that’s facet of the timing of why servicing language steering could be very doubtless now,” talked about Melissa Kozicki, director of compliance at Mortgage Cadence, in the exact same job interview.

    The CFPB isn’t the one normal public firm focused on language. The Federal Housing Administration in May as part of updates that additionally included some new value reimbursement steering for assumptions, added some new language procedures for corporations transferring servicing authorized rights.

    In addition, quite a few states at the moment have language necessities on the publications that servicers ought to actually be pursuing.

    About 30 states have both restricted English proficiency laws, or what are recognized as unconscionability standards, in accordance to George Baker, CEO and founding father of Talk’uments, a provider of digital language expertise for English, Spanish, Chinese, Korean, Vietnamese and Tagalog-talking debtors.

    “An unconscionability regular is buying an individual signal an settlement realizing full effectively that they cannot notice the phrases, the intent or the intent of the settlement. That’s an unconscionable act and a big private debt violation,” Baker claimed in a modern interview.

    The CFPB’s data on pandemic servicing and linked language demographics is based on data and info from the 2020 American Survey of House mortgage Debtors, a subset of the National Property finance mortgage Database. Some of the confusion debtors registered could also be due to to the disaster mom nature of the appliance early on as plan for it was proceed to in flux.

    Other data the lively bureau additionally launched simply these days bundled yet one more subset of the NMD reflecting a number of queries questioned in 2021, which positioned a 70% consumer gratification worth for value determinations. A distinct 23% have been being “to a point joyful. Just 6% have been sad.

    In proof of the early days of the so-named lock-in end result, 50% of respondents have been tired of shifting, with 25% “ready and geared up” to, 20% not sure and 5% “keen however not ready.”

    The CFPB tends to make distinct word of the purpose that 8% of debtors that yr deemed “lodging for folks in the present day with disabilities” a key facet in deciding upon a property, suggesting this can be a totally different area the bureau could also be concentrating on because it considers plan.

    In the earlier week, the bureau additionally reported that truthful-lending enforcement steps are at a file larger, addressed how synthetic intelligence interacts with equity insurance policies, and warned institutions to offer precise Dwelling Home finance mortgage Disclosure Act reporting.

  • Getting to certainly: Reported Basel retooling may — or may not — have legs

    Barr Gruenberg Michael Barr, vice chair for supervision on the Federal Reserve, remaining, shakes palms with Martin Gruenberg, chair of the Federal Deposit Insurance insurance policies Corp., adhering to a Senate Banking Committee listening to previous Might. Regulators are reportedly poised to supply a retooled Basel III endgame rule that noticeably scales again a number of the way more controversial points of earlier July’s proposed rule, however regardless of whether or not all these variations are ample to quell banks’ opposition is unclear.

    Bloomberg News

    WASHINGTON — Whilst it actually is obvious lender regulators put together to make substantive enhancements to a financial institution capital overhaul demanding institutions to put up much more unborrowed cash to lend to customers, banking business consultants differ on how this might probably be completed, and whether or not even a revised proposal will likely be sufficient to preclude lawful difficulties from the banking enterprise.

    The Basel proposal was hotly contested when it was first proposed remaining July on quite a lot of grounds, along with the leading-line money enhance for the foremost monetary establishments, the prospect weight remedy of mortgages, clear electrical energy property and compact enterprise loans. Bloomberg reported final 7 days that regulators are searching a draft set of revisions to the proposal aimed toward quelling these issues.

    Lawyer Gregory Lyons of Debevoise and Plimpton mentioned he is not actually assured of the timeline simply however, supplied regulators nonetheless present up to be hashing objects out internally.

    “I think about yow will discover distinctive proposals circling about how to amend it, however in truth, I’m not assured they know,” said Lyons. “We are fairly shut to what’s probably on and I simply do think about yow will discover a complete lot of inside — superior faith — however inside debates about how that is all going to have interaction in out.”

    Corporate legal professional Chen Xu, additionally with Debevoise, says he thinks the heads of the companies involved within the rulemaking — which is a joint effort and exhausting work involving the Federal Reserve, the Office of the Comptroller of the Forex and the Federal Deposit Insurance insurance policies Corp. — would really like to strike a compromise with their funds skeptic colleagues, a few of that are in the very same firm. 

    “Some of the corporate principals hope in the event that they make ample concessions, they’ll get it through by August so this is not going to get tied up with the election,” he claimed. “We’ve been listening to that try is attaining traction, however we have additionally learn that there are a amount of parents contained in the companies who would considerably have a reproposal, and splendid now it’s difficult to see who’s successful.”

    But whether or not these modifications will be included right into a remaining proposal or ought to be included in a brand new proposal — or some mixture of the 2 — stays unclear. Below the Administrative Method Act, variations produced to remaining guidelines want to be a “affordable outgrowth” of what was within the genuine proposed rule. Lots of in and throughout the banking sector argue that the enhancements required for the Basel III endgame proposal exceed this typical, and for that motive an absolutely new rule want to be put by its private observe and comment time period.

    Jaret Seiberg, cash protection analyst at TD Cowen says he expects regulators will on the very least partially withdraw and re-propose the rule — steadily dubbed Basel III endgame — supplied statements from a single of essentially the most influential avid gamers shaping the pending regulation: Federal Reserve chair Jerome Powell.

    “Powell has effectively designed this motivation to Congress,” commented Seiberg. “It does not signify there’s zero probability for the rule to be finalized, however a re-proposal appears to be like most likely.” 

    Regulators invited banking corporations to present particulars about how they’d suffer from the proposal in January. Seiberg claims the outcomes of the analysis — which he predicts should come this summer season — ought to supply additional readability about regardless of whether or not or how swiftly a re-proposal might happen.

    Whilst the Fed is essentially the most politically unbiased of the fiscal regulators, it’s experiencing drive from each equally the financial subject — which wants a re-proposed rule — when some Democrats and shopper advocates need the rule accomplished primarily as is. A brand new proposal would considerably enhance the timeline for finalization. Banking protection professional Ian Katz of Capital Alpha Partners states the Fed might devise a method to allow public comment on specific rule revisions with out restarting the system.

    “The Fed may maybe place out one thing that in essence looks like a reproposal however is known as a factor else and can enable most of the people to comment with out the necessity of establishing the process from scratch,” said Katz. “If the Fed have been to do this within the tumble — forward of the elections — it might finalize the Basel endgame rule subsequent calendar yr, perhaps within the 1st 50 p.c.”

    Banking corporations and their commerce crew reps have been vocal of their opposition to the Basel proposal and have availed themselves of novel methods in elevating the issue with voters and lawmakers. From launching selling campaigns on Sunday night soccer to determining procedural weaknesses they might downside in court docket, the sector has produced it obvious that it’s going to oppose the rule on as fairly a number of fronts as possible. Financial establishment commerce crew the Lender Coverage Institute, whose associates would all be impacted by the rule, has retained company litigator Eugene Scalia — son of former Supreme Court docket Justice Antonin Scalia — to recommend a probable approved impediment to the rule.

    Though the corporate trio has nevertheless to formally announce deliberate revisions to the rule, market allies inside the regulatory state have begun to current cowl for the kinds of variations monetary establishments are demanding.

    Fed Governor Michelle Bowman — who has beforehand known as for the rule to be reproposed —  Wednesday floated a amount of modifications she thinks are required to garner vast consensus among the many Fed’s deliberative system, the Board of Governors. She argues the rule does minimal to cope with the basic causes of essentially the most newest U.S. monetary establishment failures in March 2023.

    “I take into account we tackled the challenges that we confronted in the course of the earlier than monetary catastrophe by the implementation of Dodd Frank, I assume individuals have confirmed to be thriving,” she reported. “What led to SVB failing was not the similar subject that led to the real property disaster once more then, earlier than, a ten years prior to now.”

    Powell has often pressured the need for this consensus. Bowman termed for the companies’ to pare again once more what she known as redundancies within the funds framework — between the brand new business and operational probability wants within the rule and the strain cash buffer which she claims burdens banks with redundant costs. She additionally known as to recalibrate the present market threat issue of the rule to mitigate substantial will enhance in threat-weighted property, and deal with non-curiosity and price-dependent income extra pretty to encourage earnings diversification. She produced very clear as soon as once more this 7 days she believes any rule that may proceed — enable by yourself method finalization — would require broad changes and enter from fascinated get-togethers within the business and typical basic public. 

    “​​While these actions can be a acceptable commencing place, they’re not a substitute for a knowledge-driven evaluation and an intensive assessment of the evaluations submitted,” she talked about throughout a fireplace chat adhering to her remarks. “This would end result in a superior proposal that options alterations to cope with not solely these points, but in addition a number of different points raised by most of the people.”

    Lyons says two of the important thing issues banking establishments have decided with the rule are the scope of banks — primarily these individuals with in extra of $100 billion in property — roped into the rule’s remit, as very nicely because the business and operational threat parts flagged by Bowman, which he suggests is simply one of many very important issues for giant banking establishments.

    “I feel there are issues of relevance every to the extra substantial banks, specified the operational and present market threat issues,” he claimed. “And to the smaller sized monetary establishments, within the $100 billion asset class, pertaining to how a lot of this may apply to them.”

    Irrespective of what route regulators simply take, the banking market and its allies have questioned the require for money reforms within the to begin with place, supplied their see that firms are effectively-capitalized. But pretty than battle tooth-and-nail to cease any new money requirements, some assume they may probably settle for a slimmed-down version of the proposal in buy to accomplish regulatory certainty.

    “We assume monetary establishments would select to acknowledge a smart final rule than to enhance this combat for what might be yet one more 5 yrs,” Seiberg remarked. “The timing for finalizing the rule is correct after the inauguration. It is why there’s election hazard, nevertheless we take into account the majority of the final rule is probably going to have bipartisan help on the Federal Reserve.”

    Given ongoing talks on the organizations about how to proceed, the business will more than likely be eyeing its allies on the within of, who can assist kind the rule to their liking. Bowman’s opinions on Wednesday recommend the enterprise might get their method in numerous regards. 

    “As Chair Powell has defined, that he expects broad and supplies enhance to this proposal, and I’d hope {that a} vary of the factors that I have decided in a collection of speeches all around the final 12 months or because the proposal was launched can be built-in in a few of individuals changes,” she defined. “If the proposal is [put] forward, it has to be voted on by the board and the opposite regulatory organizations — so we’re going to simply have to see what takes place.”

    Lyons talked about a Supreme Courtroom conclusion Friday upending the Chevron doctrine — which usually mentioned judges ought to actually defer to company judgment on rulemakings — will increase the stress on regulators to make certain their closing rule is something banking corporations can reside with. With the repeal of Chevron, regulators now have to persuade courts of the deserves of non-public restrictions.

    “[Chevron] raises the dilemma of how considerably the courts have to defer to the businesses in rulemakings and so forth,” he talked about. “I think about it heightens the stakes — or hazards, based mostly in your place of watch — banking organizations or their commerce teams may maybe press once more in court docket docket from pointers they perceive to be problematic.”

    Kyle Campbell contributed to this posting.

  • Fannie Mae challenges formal request for suppliers in title-waiver pilot

    Fannie Mae issued an official request for proposal, looking for contractors for its rollout of a controversial title-waiver pilot, as correctly as opinions on different homeownership affordability treatments.

    Intrigued events should sign-up by the government-sponsored enterprise’s Procureone contractor system by July 11. The RFP will keep open for responses proper till July 26. Fannie Mae previously reported it hoped to listen to from corporations “which have viable technological know-how treatments for dealing with title-similar hazard and reducing closing expenditures for debtors.”

    The GSE’s new request offers data to an announcement issued in mid April and divides the RFP into two sections. The first seeks to acknowledge suppliers possessing or at the moment using fast title engines that would present Fannie Mae’s technique. 

    “The subsequent space seeks enter from a varied staff of market members on approaches to minimize title, escrow and different closing bills via know-how, course of developments, substitute title items, alternate charge and worth constructions or different changes to make homeownership additional reasonably priced for debtors in a secure and appear method,” the request talked about. 

    The RFP follows up on the Federal Housing Finance Agency’s unique acknowledge in early March that it deliberate to pilot a title waiver technique, whilst comparable designs had beforehand been floated and deserted. The FHFA is reliable for oversight of Fannie Mae, and its counterpart, Freddie Mac. Incorporated in the GSEs’ missions is the technology of equitable and sustainable entry to homeownership.

    Right after staying proposed as completely as referenced a number of situations in a wide range of White Property addresses, this system encountered quick pushback from the key title insurance coverage coverage and residential finance mortgage enterprise commerce teams and Republican members of Congress. At the identical time, a staff representing lesser mortgage corporations voiced their help. 

    The system would solely permit selections, akin to lawyer-feeling letters, in lieu of title insurance coverage protection for conforming refinance transactions. Currently, refinance apps make up about one particular-third of latest origination amount. 

    In late 2023. Fannie Mae had beforehand up to date its offering handbook to make it attainable for for acceptance of authorized professional-feeling letters in conjunction with mortgages utilised to finance some condominium buys and homes positioned in home-owner affiliation communities.  

    Technologies-relevant enterprises concerned in the title substitute area that maybe may function contractors include the likes of iTitleTransfer and Voxtur Analytics. The latter enterprise, even so, could probably have stepped once more its investments in the area provided that the departure of its earlier CEO in mid 2023. Voxtur can also be presently embroiled in a battle with a staff of dissident shareholders. 

    As it focuses on producing reasonably priced housing alternatives, the FHFA named 19 real property leaders this 7 days to a brand new advisory board to offer steerage on linked considerations. The firm can also be trying for enter on how the Federal Home Loan Bank method, which it governs, can higher present the general public. Earlier this yr, FHFA Director Sandra Thompson really helpful the obligatory share of earnings nearly each FHLB ought to contribute towards cheap homeownership be doubled from 10% to twenty%.

  • Challenge 2025 and property finance loan plan: what you want to know

    The conservative Heritage Foundation has rolled out a proposed blueprint for federal enhance that options some drastic housing issues, and some assume it reveals much more data of Trump marketing campaign targets not essentially in its official Agenda 47.

    The think about tank’s program, dubbed Job 2025, overhauls and shrinks quite a few federal companies, while concurrently eliminating swaths of job assist workers, reprising some methods earlier floated in the midst of Trump’s 1st phrase. The foundation estimates Trump’s actions have been in step with its agenda about two-thirds of the time. Ben Carson, who headed the Section of Housing and Urban Advancement throughout Trump’s first time period, contributed to the report.

    These hypothetical initiatives impression all corporations that govern the financial options house, along with the Division of Housing and Urban Growth, the Federal Housing Administration and the Buyer Fiscal Protection Bureau.

    Suggestions embrace breaking apart HUD and transferring its options to impartial federal organizations, states and localities. The basis additionally seeks to elevate FHA’s mortgage loan insurance coverage charges, unwind the CFPB and launch Fannie Mae and Freddie Mac from conservatorship, a factor the Trump administration took many actions towards all by way of his very first time interval.

    Finally, this system signifies overhauling quite a few Biden-era procedures and initiatives, which embrace the PAVE exercise energy and HUD’s Affirmatively Furthering Fair Housing rule, which was not too way back restored instantly after the to begin with Trump administration rolled it once more.

    Housing teams contacted for touch upon Task 2025 hadn’t rapidly responded on the time of this creating.

    Some Democratic lawmakers are opposing the inspiration’s agenda, with Rep. Jared Huffman of California stating that the maximize in presidential powers and diminishing unbiased companies’ might disrupt governmental checks-and-balances and be “a useful resource of repression.”

    Here’s an intensive breakdown of advisable alterations that might convert housing-connected corporations the wrong way up, a few of which might contain congressional movement:

    A “reset” for HUD/FHA/Ginnie Mae

    A single of the stark alterations proposed within the space ready by Carson is an overhaul of executives who run the division, proscribing positions to the politically-appointed principal deputy assistant secretary, DAS and different workplace management positions.HUD’s Secretary could be produced a member of the Committee on Foreign Investments within the U.S., offering “broader oversight authorities to take care of abroad threats, particularly from China…in each rental and possession markets of solitary-household and multifamily housing.”HUD’s Secretary additionally would even be tasked with undoing “all steps taken by the Biden Administration to progress progressive ideology.” This consists of native local weather regulate as well as to PAVE and the Affirmatively Furthering Fair Housing rule, which is now pending in its final iteration with the Workplace of Management and Spending plan. The undoing of the Federal Housing Administration’s high quality slash could be in step with a shift in the direction of encouraging homeownership alternatives by way of “shorter-period mortgages.” As this kind of, FHA’s mortgage loan insurance coverage insurance policies premiums could be amplified for all merchandise and options over 20-12 months situations. For merchandise beneath 20-year situations and refinances the MIP could be taken care of.FHA would additionally transfer its reverse property finance loan software program to its possess exclusive-chance insurance coverage fund, an plan that was floated by Dana Wade, a former FHA Commissioner beneath Trump.Also, Ginnie Mae “could be ideal-sized to present a outlined mission.” 

    Authorities- sponsored enterprises

    Heritage Foundation’s system asks the Office of the Treasury to conclusion the conservatorship of Fannie Mae and Freddie Mac and “wind each equally down in an orderly vogue.” Tasking the division to privatize the 2, subsequently “restoring a sustainable housing finance sector with a sturdy private property finance loan market place.”

    CFPB

    The plan cellphone calls the federal watchdog an unconstitutional “very politicized, harming, and fully unaccountable federal company.”It additionally urges for the CFPB’s “speedy dissolution,” and failing that, different steps that gut its powers.Stripping the CFPB of its potential to penalize as a complete.Requirements that no CFPB funds be put in on enforcement actions that aren’t depending on rulemaking that complies with the Administrative Treatment Act.Specifying the mom nature of “deceptive, unfair, and abusive” procedures to decide the scope of the CFPB mission much more particularly.Repealing Dodd-Frank necessities The blueprint additionally urges Congress to guarantee that civil penalty money are usually not employed to recompense wronged folks by way of the Treasury Section.

    Federal Reserve

    Venture 2025 would restrict the Federal Reserve’s ability to intervene with the home loan-backed securities present market, as completely as eradicate the Fed’s interventions in company and municipal bank card debt markets. The half masking changes to the Fed blames it for “rising the quantity of cash provided for true property buys despite the fact that lowered fascination charges on mortgage loan borrowing — pushed down in facet by the Federal Reserve’s MBS purchases — induced and enabled debtors to think about on even bigger monetary loans.”

  • Surge in credit score report lawsuits has banks, credit score businesses scrambling

    Courthouse The Thurgood Marshall United States Courthouse in New York. The collection of lawsuits filed beneath the Fair Credit Reporting Act has spiked in the newest years, typically by plaintiffs symbolizing on their very own and impressed by a creating cottage market of social media influencers and trial authorized professionals searching for restitution for meant errors in their credit historical past reviews.

    Bloomberg News

    Customers searching for to get out of debt are submitting lawsuits in droves disputing knowledge on credit research, impressed by what critics say is a proliferation of credit score repair corporations publishing movies on TikTok, Instagram and social media.

    Banking corporations, car financial institution mortgage servicers, credit card issuers and private debt collectors have lengthy been targets of disputes alleging a failure to look at inaccuracies on credit research. Even although the a number of credit score reporting bureaus — Equifax, Experian and TransUnion — overwhelmingly bear the brunt of consumer issues and litigation, extra monetary institutions are being bombarded with disputes alleging violations of the Honest Credit historical past Reporting Act.

    “This location has exploded in litigation,” said Ryan DiClemente, an lawyer on the legislation agency Husch Blackwell. “What we have seen in the previous three to 4 a few years is an exponential growth in FCRA lawsuits. What made use of to be a modest piece of the pie — presumably 10-20% — is now north of fifty% for nationwide litigation.”

    Industry consultants attribute among the enhance to the Client Monetary Safety Bureau, which has persistently recognized as out the credit bureaus and data furnishers for failing to analyze disputes. The CFPB additionally has questioned no matter whether or not patrons primarily owe their money owed and is searching for basic public touch upon a proposed rule that might ban skilled medical money owed from credit score experiences. 

    Defense and plaintiff’s legal professionals additionally place to the rise of credit score restore companies and to patrons at present being way more concerned in inspecting their credit score scores on purposes like Credit score Karma. 

    “What is definitely driving that is the sheer vary of hits for credit score restore organizations on YouTube, Instagram and social media,” said Manny Newburger, founding shareholder and vp on the regulation firm Barron & Newburger, P.C.

    Newburger talked about he is additionally noticed a giant enhance in professional se litigants — plaintiffs who signify them selves in courtroom docket — who’re guided by what he cellphone calls “an unseen hand.” He said extra people are ready to execute faux declarations boasting to be victims of id theft. Many others assert harm to their credit score that aren’t in a position to be substantiated by proof. 

    “People get decided they usually do not need to shed their households, they you shouldn’t need to remove their autos they usually go on the web and get awful authorized ideas,” Newburger talked about. “People who should not legal professionals are submitting lawsuits with no the benefit of counsel advising them on regardless of whether or not there may be any benefit to the accommodate.” 

    Two weeks again, Rep. Bill Huizenga, R-Mich., requested CFPB Director Rohit Chopra at a Dwelling Money Services Committee listening as to whether or not the bureau’s buyer criticism database is made up of duplicative narratives on credit score reporting disputes. For a long time, credit reporting grievances have accounted for about 70% of the roughly two million shopper complaints acquired yearly by the CFPB. 

    “It seems that some are using the CFPB’s database to discharge respected debt that they owe,” Huizenga talked about, citing Third-celebration analyses. “There are motion pictures on the web that assure results if [consumers] observe specific measures, which embody making use of your database, that there’s more likely to be private debt help.”

    Last yr, the U.S. Chamber of Commerce requested the CFPB to conduct much more oversight of credit restore corporations that file what it named “unsubstantiated disputes.”

    “Buyers ought to actually be entitled to file legit disputes, however the process has increasingly turn into overcome by illegitimate guarantees which are typically superior by a cottage subject of credit restore businesses,” wrote Monthly invoice Hulse, a senior vp on the Chamber, in a letter responding to the CFPB’s proposed adjustments to the FCRA. “Credit score restore businesses often bombard credit historical past bureaus with dispute letters in the hope of receiving detrimental marks deleted.”

    Details display that 2,744 lawsuits have been submitted between January and May presumably of this 12 months, a 23% rise from the very same interval a calendar 12 months again, based on WebRecon LLC, which tracks situation and federal FCRA lawsuits — like these filed by a whole lot of serial or repeat filers. Far greater than 5,500 lawsuits had been filed remaining 12 months. 

    “Nobody will get sued far more than the a number of credit score bureaus,” reported Jack Gordon, the CEO of WebRecon. “They are a considerable mess of targets for litigation.” 

    The complexity of credit reporting alone is on the coronary heart of the dispute process. 

    Info furnishers mail data and info each month on every particular person purchaser to the credit score bureaus and the credit score bureaus facilitate credit score reporting disputes through an automated program named e-OSCAR, which sends the dispute to furnishers. Under the FCRA, credit score bureaus and furnishers have 30 days to answer to a grievance, a fast time physique provided the big quantity of information related.

    “What is genuinely driving a ton of the situations, along with social media, has to do with the complexity of the ecosystem,” mentioned Badri Sridhar, taking good care of director at FTI Consulting, who serves as an professional witness for monetary establishments. “People are sending over tens of 1000’s of disputes each thirty day interval to the furnisher, who then has to overview that particulars. So there may be residence for errors, and issues do come up.” 

    Leonard Bennett, founding companion of Consumer Litigation Associates, talked about fairly a number of furnishers outsource the general FCRA dispute system to 3rd bash suppliers, and he queries regardless of whether or not substantive investigations are happening in any respect. 

    “The credit enterprise has unsuccessful to develop essential protections versus inaccuracies, which embody id theft or checking to remain away from issues in recordkeeping and cost heritage,” Bennett said. “What they must be endeavor is investing in their dispute methods. For the longest time, the banking trade of collectors and furnishers have taken the accountability of investigating lower than the Good Credit score Reporting Act as perfunctory, with minimal wants, instead of constructing use of investigations as a point-finding ingredient.” 

    The uptick in litigation can be remaining spurred by attorneys who search to earnings from further FCRA litigation. Demo attorneys which have jumped into the self-discipline are profitable important verdicts of as much as $500,000 for id theft circumstances that result in a buyer emotional misery, he talked about.

    Newburger defined there may be additionally an uptick in FCRA matches depending on fringe authorized and political theories, along with folks professing to be sovereign residents unobligated to spend their money owed or in any other case not be topic to U.S. laws or the authority of state or federal courts.

    The litigation has flip into so out of handle that earlier than this month Experian PLC, based in Dublin, sued Stein Saks PLLC, a laws enterprise in Hackensack, New Jersey, alleging that it operates a nationwide racketeering firm aimed toward extorting settlements by fabricated FCRA lawsuits. Experian claims Stein Saks produced fake credit score denial letters declaring accidents and actual damages on behalf of individuals after which flooded federal courts with sham lawsuits, submitting much more FCRA circumstances in regards to the previous a number of yrs than all however only one different legislation enterprise, in accordance to the lawsuit. Stein Saks didn’t reply to a request for comment.

    At the identical time, meritorious claims are going up in price as a result of truth far more attorneys are able to strain the sector to substantiate whether or not or not they’ve truly investigated a dispute. Plenty of yrs in the past, attorneys representing clients in FCRA lawsuits typically settled conditions for between $8,000 to $12,000 every, however at the moment are driving a so much more durable discount, soliciting for amongst $45,000 to $50,000 per lawsuit, gurus mentioned. 

    “We are observing a craze wherever plaintiff’s counsel are wanting to take their images with a jury,” DiClemente reported. 

    There can be been an uptick in regulatory oversight by the CFPB, which has been conducting distinctive supervisory examinations on credit historical past reporting centered on the variety of complaints it will get from folks. 

    “It’s clearly simply one of many essential locations the CFPB is centered on as they’re hoping to make out and increase their supervisory authority,” talked about Mike Silver, companion at Husch Blackwell and a earlier CFPB senior counsel.

    CFPB Director Chopra is in search of to rein in dangerous practices of information brokers beneath a proposal that might develop the amount of financial establishments which are seen as to be credit reporting businesses, which might result in extra litigation, trade consultants say. Final September, the CFPB outlined extensive enhancements to the FCRA that must have any group that collects and sells shopper knowledge to be coated by the 1970 regulation. 

    “When you’ve the CFPB expressing credit score tales are inaccurate, then of program you is likely to be heading to have folks suing,” claimed Joann Needleman, chief of the fiscal knowledgeable providers regulatory and compliance observe on the legislation agency Clark Hill. “It utilized to be that you might choose the low-priced, however now the calls for have absent up. Like virtually all the things else, it fees much more, and it actually is a small enterprise.”