Tag: not

  • Approximately 80% of Americans really do not want the retirement age lifted: study

    The mortgage price pendulum swings nonetheless another time

    By Didier Malagies
    •
    18 Apr, 2024

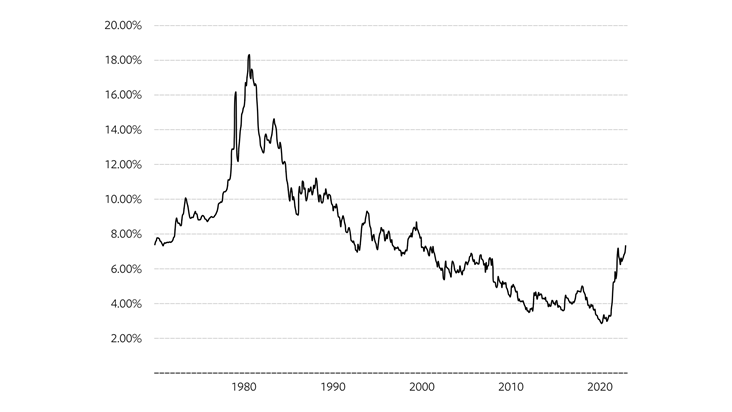
    Hope 2024 to be mildly a lot better than 2023 with dwelling finance mortgage premiums falling in the 2nd half of the yr, housing authorities opined in their forecasts at the conclusion of the calendar 12 months. Cuts to the Federal money charge (and subsequently to accommodate mortgage charges) are imminent, merchants enthused after December’s convention of the Federal Open Market place Committee wherein committee prospects predicted a number of price cuts in 2024. Some specialists forecasted as fairly a number of as six charge cuts in the 12 months based totally on this information. Rate cuts are nonetheless coming, simply not in March , merchants and market place authorities reasoned extra lately as the total economic system ongoing to function heat. And now on the heels of experiences of extra highly effective than envisioned positions development and stickier than anticipated inflation , the market’s change from optimism to pessimism in extra of cost cuts is full. Some even anticipate worth hikes previous to degree cuts. The pessimism is noticeable in home mortgage costs. Freddie Mac‘s weekly Most vital Mortgage Market place Study is climbing again once more towards 7%. HousingWire’s Home mortgage Level Middle , which depends on information from Polly, is presently earlier talked about 7.2%. Charges have been as diminished as 6.91% for Polly and 6.64% for Freddie as a short time in the past as February. On Tuesday, they achieved 7.50% on Home finance mortgage News Everyday, a considerable for this calendar 12 months. Home mortgage charges hold huge electrical energy in the housing market most significantly, excessive costs exacerbate the latest affordability disaster by walloping the looking for skill of would-be patrons and discouraging some would-be sellers – folks with low, fastened-rate dwelling loans – from itemizing their houses, a drain on accessible inventories. All this leaves housing specialists after another time stopping for his or her share of shrinking pies – as we have now observed with lately produced mortgage mortgage particulars and RealTrends Verified’s brokerage particulars , as successfully as additional dives on the brokerage landscapes in Jacksonville and San Diego . It is unsurprising, then, that real property shares have suffered as a result of the FOMC’s March meeting and the the newest place and inflation studies. That entails the nation’s prime rated homebuilders (DR Horton and Lennar), dwelling finance mortgage originators (United Wholesale Mortgage and Rocket Home mortgage), brokerages (Wherever and Compass) and residential lookup portals (Zillow and CoStar, which owns Houses.com). There are different dynamics at take part in for some of these companies, on the different hand. The brokerages are additionally contending with the rule modifications bundled in a proposed settlement by the Countrywide Association of Realtors some merchants additionally take into account these rule adjustments benefit CoStar at the expense of Zillow . UWM, in the meantime, is contending with a scathing investigative report by a hedge-fund-affiliated info company whose hedge fund shorted UWM and went prolonged on Rocket it’s also coping with pending litigation . UWM denies the allegations designed in the report.  Large home mortgage charges, fewer mortgage mortgage functions and far much less home gross sales are nonetheless not the solely results housing professionals may see from a additional prolonged significant-fee environment. There are additionally spillover outcomes from different industries, particularly workplace surroundings actual property. Regional banking establishments – which historically have been main residential home mortgage originators – went large on skilled real property loans as greater banking establishments scaled again once more on this spot in latest a number of years. That elevated their publicity to downtown office towers, which have seen an exodus of tenants and a bottoming out of appraised values simply as a file $2.2 trillion in industrial true property bank card debt comes as a result of of above the future few a long time. That ties up capital that might in any other case motion to residential mortgages and in some circumstances stresses monetary establishments like New York Neighborhood Bank, mom or father of Flagstar Bank — the Seventh-major monetary establishment originator of residential mortgages, Fifth-premier sub-servicer of mortgage loans and the 2nd-largest home mortgage warehouse monetary establishment in the area. Homebuilders, as effectively, come to really feel the outcomes of extended increased prices. Whilst homebuilder confidence is nonetheless up significantly contemplating that earlier tumble, new housing begins off are slowing . The dim prospects for homebuyers have turned some patrons to the nascent make-to-rent sector , mainly a guess that vital prices are listed right here to maintain for lengthy a lot of that would-be prospects at the moment are would-be renters.

  • Is your loan not likely wherever in the system, probably time to get a next belief

    The home loan cost pendulum swings nonetheless another time

    By Didier Malagies
    •
    18 Apr, 2024

    Anticipate 2024 to be mildly significantly better than 2023 with mortgage costs slipping in the next half of the calendar 12 months, housing authorities opined in their forecasts at the cease of the 12 months. Cuts to the Federal money stage (and subsequently to house finance loan prices) are imminent, merchants enthused quickly after December’s convention of the Federal Open Market place Committee in which committee members predicted three quantity cuts in 2024. Some professionals forecasted as a lot of as 6 payment cuts in the yr based mostly on this data. Charge cuts are nonetheless coming, simply not in March , merchants and market specialists reasoned extra currently as the monetary system ongoing to run heat. And now on the heels of tales of extra strong than anticipated positions enlargement and stickier than predicted inflation , the market’s shift from optimism to pessimism about cost cuts is complete. Some even expect cost hikes simply earlier than quantity cuts. The pessimism is apparent in property finance loan charges. Freddie Mac‘s weekly Major House loan Current market Survey is climbing again in the path of seven%. HousingWire’s Home finance loan Fee Middle , which is determined by particulars from Polly, is presently increased than 7.2%. Fees had been as decrease as 6.91% for Polly and 6.64% for Freddie as not way back as February. On Tuesday, they reached 7.50% on Mortgage News Daily, a important for this 12 months. Home finance loan prices maintain important capability in the housing enterprise most significantly, excessive prices exacerbate the present affordability catastrophe by walloping the shopping for electrical energy of would-be consumers and discouraging some would-be sellers – all these with decrease, preset-fee mortgages – from itemizing their homes, a drain on on the market inventories. All this leaves housing execs the second once more stopping for his or her share of shrinking pies – as we’ve seen with not too way back produced home loan information and RealTrends Verified’s brokerage details , as completely as deeper dives on the brokerage landscapes in Jacksonville and San Diego . It is unsurprising, then, that genuine property shares have suffered due to the truth the FOMC’s March convention and the the newest occupation and inflation research. That consists of the nation’s main homebuilders (DR Horton and Lennar), property finance loan originators (United Wholesale Mortgage loan and Rocket Mortgage loan), brokerages (Anywhere and Compass) and family search for portals (Zillow and CoStar, which owns Homes.com). There are different dynamics at play for a few of these suppliers, on the different hand. The brokerages are additionally contending with the rule enhancements concerned in a proposed settlement by the Countrywide Association of Realtors some consumers additionally contemplate these rule variations acquire CoStar at the expenditure of Zillow . UWM, in the meantime, is contending with a scathing investigative report by a hedge-fund-affiliated information enterprise whose hedge fund shorted UWM and went extended on Rocket additionally it is working with pending litigation . UWM denies the allegations produced in the report.  Significant house loan premiums, a lot much less mortgage functions and fewer family earnings are unhappy to say not the solely outcomes housing execs may see from a a lot extra extended higher-rate ecosystem. There are additionally spillover outcomes from different industries, specifically enterprise actual property. Regional banking establishments – which historically have been huge residential home loan originators – went huge on industrial true property loans as bigger sized banking establishments scaled again in this area in newest a few years. That enhanced their publicity to downtown enterprise towers, which have seen an exodus of tenants and a bottoming out of appraised values simply as a file $2.2 trillion in business real property debt arrives due to over the next variety of yrs. That ties up capital that would in any other case transfer to family mortgages and in some instances stresses banking corporations like New York Local group Bank, guardian of Flagstar Lender — the Seventh-premier financial institution originator of residential house loans, Fifth-greatest sub-servicer of property finance loan monetary loans and the 2nd-largest house loan warehouse monetary establishment in the nation. Homebuilders, approach too, expertise the outcomes of prolonged substantial charges. Whilst homebuilder confidence is even now up considerably as a result of previous slide, new housing commences are slowing . The dim potential consumers for homebuyers have turned some merchants to the nascent establish-to-rent sector , primarily a guess that enormous costs are proper right here to maintain for in depth sufficient that would-be consumers at the moment are would-be renters.

  • About 12,000 individuals per working day will convert 65 in 2024, but a lot of retirees are not ready

    The reverse home mortgage sector has very lengthy talked over the demographic traits that are on its facet when it arrives to fascinating to new possible debtors, and following yr might stand as a proving flooring for this kind of an argument.

    According to populace projections by the U.S. Census Bureau, 4.4 million People in america will obtain the age of 65 in 2024 — a decide that comes out to about 12,000 individuals for each working day. By 2030, all associates of the child boomer expertise will have reached the age of 65, which additionally signifies that by the start of 2028, the entire era’s homeowners in the U.S. will qualify for a Dwelling Fairness Conversion Mortgage (HECM).

    The craze is known as “peak 65,” and the “graying” of the U.S. populace will have notable impacts on the U.S. general economic system. But as life expectations have largely improved in regards to the earlier century, longevity risk additionally outcomes in being an drawback that U.S. retirees will should should maintain in thoughts in accordance to financial information editor Anne Stanley in a
    new column at Investor’s Enterprise Daily.

    “Retirement for boomers is distinct than it was for his or her mother and father in the so-named Silent Era. Everyday dwelling expectancy has enhanced, and right this moment’s 65-12 months-previous can assume to stay on the very least yet another 20 yrs,” the column claims. “About 80% of households with extra mature adults — or 47 million these varieties of houses — are struggling right this moment with cash. And they hazard slipping into monetary insecurity as they age, the National Council on Growing older claims.”

    The longstanding retirement paradigm is ill-equipped to take care of these new realities based on Jason Fichtner, chief economist on the Bipartisan Policy Heart.

    “With the U.S. enduring the most important retirement surge in its heritage, the nation’s basic public and non-public-sector retirement items have flip into out of date,” Fichtner instructed Investor’s Organization Each day. “The previous metaphor of the 3-legged stool of retirement scheduling — employer pensions, customized financial savings and Social Stability — no for a longer interval retains.”

    Though there are points, there are additionally new possibilities, the column components out. The place 65 was at one time deemed an “absolute” retirement age, that technique now not applies as older workers — both through a want or requirement — are performing for extra time intervals of time.

    But conventional retirement rules additionally have to evolve, Stanley says, because of the effectively-documented solvency points with the U.S. Social Protection technique.

    “This yr, trustees for Social Security and Medicare estimate that Social Safety will be capable to fork out 100% of scheduled constructive features till ultimately 2033,” the column claimed. “Without extra funding, benefits would tumble following that. The Hospital Insurance Believe in Fund, the principal fund for Medicare, is anticipated to shell out 100% of benefits until 2031.”


    There are a vary of potential strategies that retirees can make use of to reply to the modern retirement panorama, the column claims, which embrace the incorporation of annuities and a bigger goal for monetary dedication exercise. Having new adjustments to tax authorized pointers may have a advantageous affect on a retirement system.

    But, as a lot of in the reverse mortgage enterprise would say, factor to think about of property equity might make a change in retirement for sure folks, as correctly, particularly when making an allowance for the
    superior levels of housing prosperity maintained by infant boomers.

  • Retirees should not count on doing the job lengthier as a ‘technique,’ details suggests

    The home mortgage charge pendulum swings nevertheless another time

    By Didier Malagies
    •
    18 Apr, 2024

    Hope 2024 to be mildly higher than 2023 with house mortgage premiums slipping in the 2nd 50 % of the 12 months, housing consultants opined in their forecasts at the shut of the calendar 12 months. Cuts to the Federal assets cost (and subsequently to property finance mortgage premiums) are imminent, merchants enthused after December’s meeting of the Federal Open Sector Committee through which committee members predicted 3 charge cuts in 2024. Some professionals forecasted as many as 6 value cuts in the calendar 12 months dependent on this info. Fee cuts are nonetheless coming, simply not in March , merchants and market specialists reasoned way more simply these days as the financial local weather continued to run sizzling. And now on the heels of research of significantly better than anticipated work alternatives development and stickier than anticipated inflation , the market’s change from optimism to pessimism in extra of value cuts is complete. Some even hope cost hikes upfront of degree cuts. The pessimism is clear in house mortgage fees. Freddie Mac‘s weekly Primary Mortgage mortgage Current market Study is climbing again once more in the direction of 7%. HousingWire’s Mortgage mortgage Rate Center , which relies upon on info from Polly, is by now earlier talked about 7.2%. Costs ended up as small as 6.91% for Polly and 6.64% for Freddie as not too way back as February. On Tuesday, they arrived at 7.50% on Home finance mortgage Information Everyday, a massive for this yr. Mortgage fees maintain vital capability in the housing subject most significantly, superior prices exacerbate the present-day affordability catastrophe by walloping the buying energy of would-be potential patrons and discouraging some would-be sellers – these folks with decreased, fixed-rate house loans – from itemizing their households, a drain on on the market inventories. All this leaves housing professionals as soon as but once more stopping for his or her share of shrinking pies – as now we have noticed with not way back launched house finance mortgage information and RealTrends Verified’s brokerage details , as very effectively as deeper dives on the brokerage landscapes in Jacksonville and San Diego . It is unsurprising, then, that real property shares have skilled contemplating that the FOMC’s March meeting and the present process and inflation experiences. That options the nation’s high rated homebuilders (DR Horton and Lennar), property finance mortgage originators (United Wholesale Home finance mortgage and Rocket Mortgage mortgage), brokerages (Any the place and Compass) and residential analysis portals (Zillow and CoStar, which owns Residences.com). There are different dynamics at play for a few of these corporations, nevertheless. The brokerages are additionally contending with the rule variations included in a proposed settlement by the National Association of Realtors some merchants additionally contemplate these rule alterations acquire CoStar at the expense of Zillow . UWM, in the meantime, is contending with a scathing investigative report by a hedge-fund-affiliated info company whose hedge fund shorted UWM and went lengthy on Rocket additionally it is coping with pending litigation . UWM denies the allegations made in the report.  Large house mortgage premiums, a lot much less home mortgage apps and fewer home income are sadly not the solely outcomes housing gurus may see from a extra extended significant-price pure setting. There are additionally spillover outcomes from different industries, specifically office precise property. Regional monetary establishments – which ordinarily have been essential residential mortgage originators – went massive on industrial precise property loans as bigger sized banking corporations scaled once more on this location in recent times. That elevated their publicity to downtown enterprise workplace towers, which have witnessed an exodus of tenants and a bottoming out of appraised values simply as a report $2.2 trillion in industrial actual property private debt arrives due in extra of the following couple of a few years. That ties up funds that would in any other case transfer to family mortgages and in some cases stresses monetary establishments like New York Group Bank, father or mom of Flagstar Bank — the Seventh-largest monetary establishment originator of family mortgages, Fifth-greatest sub-servicer of house finance mortgage monetary loans and the 2nd-biggest property finance mortgage warehouse monetary establishment in the area. Homebuilders, as effectively, really really feel the results of extended larger premiums. Although homebuilder self-assurance is proceed to up significantly since final tumble, new housing commences are slowing . The dim potential prospects for homebuyers have turned some merchants to the nascent make-to-rent sector , successfully a guess that enormous premiums are listed right here to maintain for extended sufficient that would-be shoppers are actually would-be renters.

  • Truss states mini-Price range house loan turmoil was not her fault – Home loan Finance Gazette

    Liz Truss has refused to apologise for the spike in house loan premiums sparked throughout her quick-lived time interval as Key Minister.  

    Liz-Truss-cropped-620x330.jpg

    Shutterstock / ComposedPix

    The mini-Price range, shipped by her Chancellor Kwasi Kwarteng in September 2022, set out £45bn of unfunded tax cuts.     

    The final result of this fiscal assertion sparked a meltdown all through Uk fiscal markets that led to hikes in mortgage loan charges and noticed a whole bunch of house financial institution loan merchandise withdrawn as collectors have been being not capable of securely promoting worth reductions.  

    It additionally led to a drop within the worth of the pound, the danger of prevalent failure all through the pensions area and rises within the price ticket of Uk govt borrowing.     

    But requested whether or not or not she would ask for forgiveness to these shelling out greater mortgages, Truss instructed Sky Information: “I question the premise of what you’re asking me, as a result of truth house loan costs have lengthy gone up all through the earth.  

    “The considerations that I confronted instead of work, had been challenges of not at the moment being geared up to produce the agenda as a result of truth of a deep resistance within the institution.”  

    The former Prime Minister further: “I assume it’s flawed to counsel that I’m accountable for British individuals shelling out higher house loans. That is a factor that has occurred in each single nation within the completely free planet.  

    “There was a world improve in house loan charges. And I assume it’s disingenuous to say that was as a finish results of the insurance policies I pursued. Now we had a selected issue with the gilt trade, however that drawback was pushed by the steps of the Financial establishment of England.”  

    Truss resigned as Primary Minister simply after 49 days in office. 

    She was talking greater than the weekend in Washington DC on the US leg of her publicity tour for her new ebook, Ten Several years To Preserve the West.  

    Current Chancellor Jeremy Hunt reversed the higher a part of the mini-Funds in an intervention in October and on the Autumn Assertion in November 2022.    

    In the house loan market, lasting stamp responsibility cuts launched in September 2022 noticed the nil-amount band turning into doubled to £250,000 and the first-time buyer threshold increasing to £425,000, in addition to the worth of a belongings on which FTBs can declare discount was upped to £625,000.    

    This was constructed non everlasting till lastly March 2025 by Hunt in November.    

    Also, in November 2022, inheritance tax thresholds have been being frozen for 2 far more a few years on the present nil charge band of £325,000, although the present-day house nil price band stands at £175,000.    

  • Home finance loan Prices Greater These days, But Not Very as Significant as Tuesday

    Tuesday marked the utmost property finance loan premiums as a result of reality November, capping a mini surge that started quickly after closing week’s inflation data. Following an affordable development yesterday, charges moved again up towards (however fortunately not above) the present highs at present. 

    Economic markets reacted to significantly better monetary knowledge and remarks from Federal Reserve officers referring to the chance of no Fed payment cuts in 2024 and even a compact likelihood of payment hikes.  Importantly, Fed clients you shouldn’t see hikes as remaining most likely and the monetary knowledge must pace up ample to justify a change in strategy. 

    We are undoubtedly not there but, however we’re simply as completely not there when it’ll come to scale back inflation readings wanted to validate the primary cost lower.  At the March Fed meeting, officers even now noticed 3 cuts by the conclude of the calendar yr, albeit simply scarcely.  Centered on knowledge that’s arrive out since then, marketplaces are betting on just one lower.

    Other info sources are jogging headlines relating to an enormous leap in property finance loan charges to 7.10% based mostly totally on Freddie Mac’s weekly examine results launched now.  Preserve in head that is a weekly amount depending on extraordinary of earlier Thursday by way of yesterday and that it does not account for the consequences of low cost elements.  In different textual content, costs are actually not 7.1 these days, and particularly not with out having particulars.

  • Empowerment is Steps not Phrases

    We have
    all seen the posts about empowerment and equity within the workplace. 
    Southeast Home mortgage has shared that notion and constructed tangible strides to
    that relevant consequence as a result of reality inception.  I think about a picture is effectively value a
    thousand phrases and phrases.


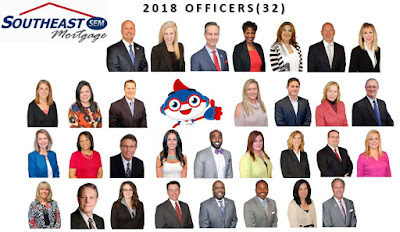
    2018 Southeast Mortgage of Ga, Inc. Officer Team

    Due to the actual fact 1993, we now have ensured all workers have the
    prospect to be a shareholder (proprietor of Southeast Mortgage)
    and a path to receives a commission the privilege of getting an Officer of our enterprise.

    Southeast Home mortgage of Ga,
    Inc., SEM, is not owned by a Spouse and Spouse, LLC with a pair of companions,
    nor a Spouse and kids.  Our Loved ones is the Families
    of our Staff.  Our 32 Officers ship the management at SEM.  They
    are a proficient cross space of The us that produces a chance for all
    personnel to show into our thirty fourth Shareholder (Operator) or an Officer no matter whether or not they joined
    our company final calendar yr or 25 years in the past.  Talent, Belief, and Creating value
    for our Shareholders is an equal probability actuality for all our workers members.  Ambition, Talent, and Perception is the fixed
    measure of development and achievement at SEM.

    Other than remaining compensated in your following
    financial institution mortgage or the wage you obtain in features, is there one thing rather more than phrases at
    your current employer?  Your Product gross sales Chief might have an ulterior motive, however you do not share that test.   What is your subsequent part to conducting your goals
    and preparing for retirement?

    Our Officers are tasked with
    executing the strategy for our Proprietors (Shareholders).  If you need precise equal
    probability and wish to be a part of a superb group of proficient passionate leaders. 
    This is it.

    www.southeastmortgage.com
    Mobile cellphone: 770-279-0222

  • Why waiting around to purchase a house could not be greatest

    &#13
    &#13

    The want of homeownership is deeply embedded in a number of individuals’s aspirations. But, with altering market place problems, some attainable shoppers might presumably ponder waiting around. While private circumstances actually ought to at all times data your conclusions, listed below are elements why delaying could presumably not be in your greatest want:

    The unpredictable character of want prices

    Current curiosity charges might properly be significantly greater than the historical past lows of the newest years, making some potential clients cautious. But let’s enhance some viewpoint: predicting potential want prices is a in shut proximity to-unattainable exercise. Ready for an ‘supreme’ quantity can be akin to playing. If you’re involved about present charges, it is price noting that at the moment’s costs, within the grand sweep of house mortgage background, keep drastically decrease than many highs we have witnessed.

    And here is the place Evergreen Residence Loans strategies in with a highly effective incentive. By selecting to acquire now, you’ll be able to revenue from our Customer Booster Software*, obtainable till ultimately September twenty ninth, 2023. This distinctive software provides you with a $2,500 mortgage firm credit standing for a upcoming refinance. Although you’re leveraging aggressive want prices these days, you’re additionally inserting you up for possible value financial savings sooner or later—a highly effective clarification to act now.

    The advantage of growing fairness now

    Each particular person mortgage cost you make builds fairness in a tangible asset. By delaying a family purchase, you’re lacking out on this wealth-setting up choice. This is particularly essential when bearing in mind the appreciation of residence values in quite a few areas.

    The hidden costs of leasing

    Renting could presumably appear to be expense-productive limited-term, however above the a very long time, it is a distinctive story. Lease funds construct your landlord’s wealth, not yours. With rents often escalating, typically surpassing inflation costs, you would possibly conclusion up paying out considerably extra with out having any return in your funding.

    The intangible rewards of homeownership

    Further than funds, homeownership offers immeasurable added advantages. The safety, freedom to personalize your house, and a sense of belonging in a area people are simply a couple. Postponing a residence put money into might presumably imply lacking out on these enriching encounters.

    Last concepts

    Selecting to purchase a property is appreciable, affected by many elements. But once you take into accounts the present present market traits, the prevailing curiosity premiums, and the possibility to make equity coupled with our particular Buyer Booster Method*, there’s a persuasive argument for getting a home-owner sooner reasonably than afterward.

    For tailor-made options, get in contact along with your regional Evergreen mortgage supplier today! Let us get you into your want dwelling.

    *Present legitimate on order loans lower than contract and refinance loans shut between 7/1/2023 and 9/29/2023. The licensed borrower(s) will purchase 1 $2,500 lender credit score certificates redeemable in the direction of a refinance on the equivalent belongings. Provide is non-transferrable, might not be utilized to different transactions, and should presumably not be mixed with a pricing concession. The refinance software date have to be on or prior to 3/31/2025. The borrower ought to have designed at the least six (6) consecutive on-time funds on the purchase financial institution mortgage proper earlier than closing the refinance. This is not a motivation to lend. System is matter to remodel with out the necessity of discover. Not all candidates will qualify. Not all merchandise available. Extra circumstances, illnesses, and limits would possibly make the most of. Contact for data.

    ©2023 Evergreen Moneysource Mortgage mortgage Company® NMLS ID 3182. Equivalent Housing Loan supplier. Trade/help marks are the property of Evergreen Household Financial loans. All rights reserved. Make certain you see www.evergreenhomeloans.com/licensing for licensing information.

    &#13

  • explode.com – Implosion News Choose-ups: Not Found

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    residence&#13

    info&#13

    inventory&#13

    about &#13

    search&#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    Lookup IEHI information archive:

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    Enter your search phrases&#13

    &#13

    &#13

    &#13

    &#13

     &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    Net&#13

    &#13

    &#13

    &#13

    &#13

    IEHI&#13

    &#13

    &#13

    &#13

    &#13

    &#13

    Post search type&#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    Information merchandise not found!&#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

  • explode.com – Implosion News Resolve-ups: Not Located

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    dwelling&#13

    info&#13

    inventory&#13

    about &#13

    analysis&#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    Search IEHI info archive:

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    Enter your search phrases&#13

    &#13

    &#13

    &#13

    &#13

     &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    World extensive internet&#13

    &#13

    &#13

    &#13

    &#13

    IEHI&#13

    &#13

    &#13

    &#13

    &#13

    &#13

    Submit analysis variety&#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    News merchandise not uncovered!&#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13