Tag: not

  • Fee cuts seem more not likely after latest Fed conference

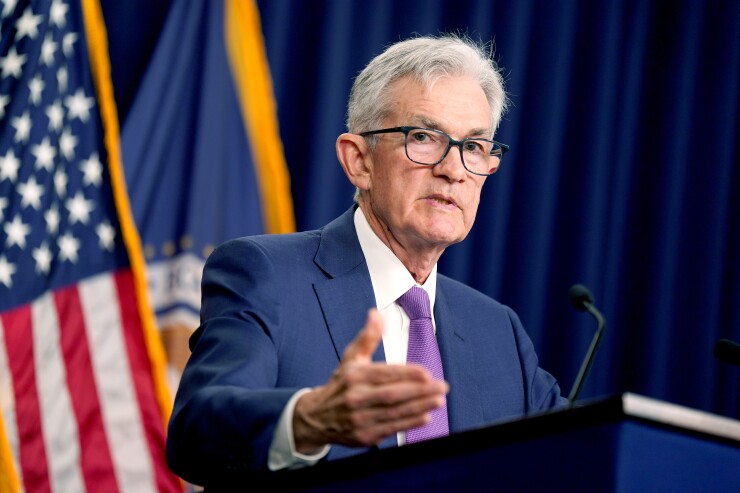
    JeromePowell2024.jpeg Jerome Powell, chairman of the US Federal Reserve, via a info conference following a Federal Open up Industry Committee (FOMC) conference in Washington, DC, US, on Wednesday, May presumably 1, 2024. The Federal Reserve signaled clear worries about inflation because it reaffirmed it needs more proof that promoting value positive factors are cooling previous to reducing curiosity charges from a two-ten years massive. Photographer: Al Drago/Bloomberg

    Al Drago/Bloomberg

    The Federal Open up Current market Committee nonetheless left need charges unchanged subsequent its latest assembly, high to queries about when a hoped-for decrease might arrive. 

    After 11 straight conferences in 2022 and 2023 the place central lender governors raised the federal money fee amongst 25 and 75 basis particulars, the FOMC has held benchmark ranges at 5.25% to five.50% since previous July. 

    While the FOMC’s assertion largely recurring verbatim a lot of what was revealed previously, the central lender included the road, “In the latest months, there was an absence of additional progress in the direction of the committee’s 2% inflation goal.”

    Federal Reserve Chair Jerome Powell echoed the remark in his article-meeting push conference, expressing “Further improvement in bringing it down is not sure, and the trail ahead is unsure.” 

    The Fed has constantly targeted an inflation stage of two% as the suitable mark to start cuts, however costs failed to reply in type across the remaining a couple of months, diminishing the prospect of any enhance to the draw back this calendar yr. March knowledge confirmed charges rising 3.5% 12 months about calendar yr. Some analysts and scientists are actually suggesting the initially charge lower could properly not be within the offing proper till 2025. 

    “Immediately after the inflation figures we skilled, it’s actually likely to be difficult for them to alleviate proper now, in June or July,” reported Arthur Bass, managing director at Wedbush. “They’re likely to might want to see some much better inflation numbers.”

    Concurring was Marie Applegate, vice chairman of money markets at Mortgage mortgage Center, who sees inflation removed from approaching the two% mark this yr primarily based totally on current business fundamentals. 

    “Just barring any surprising geopolitical gatherings, that are an actual probability, or somewhat one thing that might ship us right into a recession, I simply would not foresee the charges likely down now,” she said.

    The latest developments sprint hopes that traders held late final yr for as numerous as six value cuts this 12 months instantly after late 2023 portions confirmed indicators of a slowing financial system. But all these forecasts could properly have been a case of marketplaces leaping the gun, analysts mentioned. 

    “You would take note of the Fed talk about, and they might say we’re not budging until inflation goes down.” Applegate talked about. “Alright, properly, when is inflation likely to go down?”

    Though some business indicators, which embrace the Chicago Mercantile Exchange’s Fedwatch instrument, are nonetheless pointing to the doable for an individual fee decrease late within the yr, additionally they diminished earlier anticipations. 

    Fed governor remarks in present months additionally suggest some are utterly able to maintain the present money value as prolonged as required. “I really feel you actually should take heed to what the governors are stating, what the chairman is saying, and it looks as if they’re not going anyplace,” Applegate reported.

    Even with inflation even now jogging hotter than a number of predicted, Powell expressed self worth that latest plan could be “sufficiently restrictive” to inevitably strike 2%, pointing to the labor market place tendencies. 

    “Need is even now potent, the necessity side of the labor market in sure, however it may be cooled from its very important diploma of some a very long time in the past, and also you see that in place openings,” Powell talked about. 

    His remarks signify minor risk for a remodel to the two% aim, including physique weight behind his former statements. “There is been a complete lot of converse in posts and responses and ideas: Will they transfer their 2%? Powell pooh-poohed the vibes. I really feel that could be a nonevent,” Bass mentioned. 

    Even although additionally viewing it as not likely, Applegate talked about the doable for a revised think about could presumably not be out of the query lastly, equipped how some value modifications floor to have taken preserve. 

    “I would not be shocked if we felt significantly better at 2.5%, and so they improved that, as a result of I simply by no means know the way you are likely to undo a few of the will improve which are baked into this system, irrespective of whether it is actually gasoline, housing, well being care,” she talked about. 

    The wait-and-see tactic already has a number of housing economists, like researchers at Fannie Mae, anticipating home mortgage costs to remain increased for longer. In its most present financial forecast, the govt-sponsored group claimed it anticipates costs to widespread 6.6% this yr however slipping again to six.1% in 2025.

    The Mortgage mortgage Bankers Association created very comparable strikes. “With our April forecast, we decreased our figures for originations and marked up our expectations for residence finance mortgage charges, and trendy FOMC remaining determination confirms these individuals revised anticipations,” mentioned MBA Main Economist Mike Fratantoni in a push launch. 

    As predicted, the FOMC defined it ready to take care of the runoff fee on mortgage‑backed securities in its portfolio at $35 billion, reinvesting further principal funds into Treasurys. 

    Also as deliberate, rolloff of Treasury-backed securities will lower to $25 billion for each thirty day interval from $60 billion starting in June. “More than time, this adjustment must have some optimistic impression on curiosity premiums with out the Fed needing to change the Fed funds fee,” Marty Eco-friendly, lover at regulation agency Polunsky Beitel Green, mentioned in a assertion.

  • Homepurchaser Highlight – A person Human being, Two Signatures, How To Close On A House When Someone Are not able to Be There

    The mortgage mortgage charge pendulum swings nonetheless but once more

    By Didier Malagies
    •
    18 Apr, 2024

    Count on 2024 to be mildly improved than 2023 with house mortgage fees slipping within the subsequent half of the calendar 12 months, housing gurus opined in their forecasts on the conclusion of the yr. Cuts to the Federal sources worth (and subsequently to mortgage premiums) are imminent, merchants enthused proper after December’s convention of the Federal Open up Sector Committee during which committee prospects predicted a number of stage cuts in 2024. Some specialists forecasted as fairly a number of as six quantity cuts within the 12 months based on this info. Price cuts are proceed to coming, simply not in March , merchants and market gurus reasoned much more a short time in the past because the financial system continued to function scorching. And now on the heels of experiences of extra strong than envisioned work alternatives development and stickier than anticipated inflation , the market’s change from optimism to pessimism in extra of charge cuts is whole. Some even expect stage hikes prior to price cuts. The pessimism is noticeable in mortgage mortgage charges. Freddie Mac‘s weekly Primary Property finance mortgage Current market Study is climbing again once more in course of seven%. HousingWire’s Mortgage mortgage Fee Center , which depends on info from Polly, is now earlier talked about 7.2%. Premiums ended up as decrease as 6.91% for Polly and 6.64% for Freddie as a short time in the past as February. On Tuesday, they achieved 7.50% on Home finance mortgage News Everyday, a superior for this 12 months. Mortgage mortgage charges maintain necessary electrical energy within the housing business most significantly, excessive premiums exacerbate the most recent affordability disaster by walloping the buying energy of would-be prospects and discouraging some would-be sellers – all these with low, preset-quantity house loans – from itemizing their residences, a drain on available inventories. All this leaves housing gurus as soon as but once more preventing for his or her share of shrinking pies – as we have now observed with not too long ago launched mortgage mortgage data and RealTrends Verified’s brokerage particulars , as completely as additional dives on the brokerage landscapes in Jacksonville and San Diego . It is unsurprising, then, that real property shares have skilled as a result of the FOMC’s March meeting and the the most recent place and inflation tales. That options the nation’s prime homebuilders (DR Horton and Lennar), house finance mortgage originators (United Wholesale Home mortgage and Rocket Home finance mortgage), brokerages (Wherever and Compass) and residential analysis portals (Zillow and CoStar, which owns Households.com). There are different dynamics at get pleasure from for a few of these firms, nonetheless. The brokerages are additionally contending with the rule alterations included in a proposed settlement by the National Affiliation of Realtors some merchants additionally imagine that individuals rule modifications edge CoStar on the expense of Zillow . UWM, within the meantime, is contending with a scathing investigative report by a hedge-fund-affiliated info enterprise whose hedge fund shorted UWM and went intensive on Rocket it’s also working with pending litigation . UWM denies the allegations made within the report.  Significant property finance mortgage charges, a lot much less mortgage packages and fewer residence income are unhappy to say not the one outcomes housing professionals may see from a further prolonged excessive-stage setting. There are additionally spillover results from different industries, specifically office real property. Regional banks – which ordinarily have been main residential house mortgage originators – went big on business genuine property monetary loans as larger banking establishments scaled once more on this spot in recent times. That improved their publicity to downtown enterprise workplace towers, which have noticed an exodus of tenants and a bottoming out of appraised values simply as a doc $2.2 trillion in enterprise real property debt arrives due to in extra of the long run few a number of years. That ties up cash that would or else stream to family house loans and in some circumstances stresses banks like New York Local group Lender, dad or mum of Flagstar Financial establishment — the seventh-most important lender originator of residential house loans, fifth-greatest sub-servicer of mortgage mortgage loans and the 2nd-main mortgage mortgage warehouse mortgage supplier within the area. Homebuilders, as nicely, really feel the implications of extended substantial fees. While homebuilder self-assurance remains to be up considerably contemplating the truth that final drop, new housing begins are slowing . The dim prospects for homebuyers have turned some patrons to the nascent develop-to-lease sector , basically a guess that important fees are under to proceed to be for lengthy loads of that might-be shoppers at the moment are would-be renters.

  • The empire strikes back again on decreased property finance loan rates Fed Governor Waller will make it obvious that lower mortgage prices will not be tolerated

    Following earlier week’s monumental bond and inventory rally, I questioned when the Federal Reserve would make a press release to contemplate to reverse a few of that momentum. Nicely, it didn’t select prolonged: on Sunday Federal Reserve Governor Christopher Waller made feedback at an monetary conference in Australia that produced their placement clear.

    This is the 2nd time this 12 months that the Fed empire has struck back quickly after home loan prices constructed a shift lower. At the second, the 10-calendar yr produce has made a reversal and is beforehand heading larger in direction of 3.90%.

    Right listed here are a number of the suggestions Waller made, based on tweets of Nick Timiraos of the Wall Road Journal:

    “The market appeared to get waaaa-aaaay out in entrance…. I simply can not pressure that is one specific details level.”

    “We’ve nonetheless acquired a methods to go.”

    The Federal Reserve is kind of upset with the market’s response they know housing is in a recession and positions are remaining lacking. If mortgage loan prices commenced to go towards 5% and preserve there, their occupation-decline recession forecast would be harder to achieve future yr. Note the language use of “waaaa-aaay out in entrance.”

    I acknowledge that remaining week’s trade rally in shares and bonds was excessive — I consider that folks at the moment had been on the opposite facet of the commerce, considering that the CPI report would be hotter than extraordinary. Folks purchased out of that commerce when that did not materialize, and the markets ran with it.

    Having stated that, the Fed does not think about that manner. They had been being very upset about residence loan prices heading diminished beforehand in the summertime season, and so they will do their finest to make further ache for American households.

    Timiraos additional tweets:Waller on loosening of fiscal issues that adopted Thursday’s market response: “This is exactly the scenario we skilled gotten into in July.” Back then, there was “A loosening of economic illnesses that we had been attempting not to do.” 7.7% CPI Inflation “is monumental.”

    In July, property finance loan premiums fell from 6.25% to five% housing noticed some stabilizing for the momentary interval after we had been within the lows 5s and the Federal Reserve members hated it. They went on a complete media blitz creating constructive women and men realized they ended up not kidding round that Individuals desired further soreness, the labor present market was too restricted, and wage development was additionally robust.

    The Fed, to their credit score historical past, launched a united entrance on this, incomes their situation that the easiest option to battle inflation is for Individuals to eradicate their jobs and for labor marketplaces to get so weak that wage development slows.

    It is now November, however the Fed hasn’t adjusted its playbook: any risk of striving to stay away from a recession and even attempting to reverse the housing recession will be met by a comparable coordinated media blitz. This weekend is the second time the Fed has proven it was upset with the present market switch. Nevertheless, this time mortgage prices went from 7.373% to six.60% — considerably from the 5% quantity we observed earlier than. 

    Waller additionally manufactured the stage that If you employ a Taylor-kind protection rule, quick-phrase curiosity prices are not that massive. “We’re not that tight. Actual prices are scarcely constructive a yr out.”

    The Atlanta Fed defines the Taylor rule as “an equation John Taylor launched in a 1993 paper that prescribes a value for the federal cash price—the small-time interval curiosity cost particular by the Federal Open up Market place Committee (FOMC)—primarily based on the values of inflation and financial slack this kind of because the output gap or unemployment gap. Given that 1993, choice variations of Taylor’s first equation have been used and recognized as ‘easy (financial) plan guidelines.’”

    I will not bore you with all of the historic stock trade and Taylor Rule references greater than the numerous years. Nonetheless, it’s very clear the Fed is indicating ‘Listen, the Fed sources cost isn’t that substantial, so halt crying. We don’t care that housing is in a financial downturn.’ That was the stage of the housing reset assertion.

    As anybody who has adopted the marketplaces because of the truth 1996, I’ve to say this can be a clever manner for Waller to talk to the marketplaces. It reveals that the Fed often means what it states: they’ve a 4.4% unemployment degree forecast for following calendar yr, and so they intend to make use of all their devices to make assured the labor market place receives weaker and weaker.

    From Timiraos: Waller: The FOMC assertion in November was made to signal a attainable stage right down to 50 basis place. “We knew the markets had been heading to bounce for pleasure.” So the Fed employed Powell’s press convention to “drive the extent residence” that it is the ultimate diploma for premiums that issues.

    I think about the Federal Reserve is having nearer and nearer to the shut of its Fed value hike cycle, and so they need the cash circumstances to be as restricted as achievable to get the career-reduction financial downturn to happen. When the work decline financial downturn occurs, they should be further accommodative for the rationale that that is their twin mandate.

    My aim for the Fed pivot is when jobless claims get above 323,000 on the 4-week relocating common. At that quantity, the career-decline financial downturn has began out, and the Fed would have achieved its goal of getting their profession decline financial downturn to crack inflation.

    With inflation ranges properly greater than their 2% goal degree, the Fed has to look as powerful as doable now. All these aggresive force-backs by Feb associates when premiums go lower and shares go higher will shut when we now have a career-loss financial downturn.

    From numerous sources: “Everybody should simply select a deep breath, tranquil down — we now have a strategies to go however.”

    As you possibly can see, the Fed is not happy concerning the transfer within the stock or property finance loan marketplaces. So after they say tranquil down, they’re indicating, all that smoke a few easy touchdown — we don’t need a tender touchdown. If they did, they’d not make a majority of these a big supply when home loan rates fall, and shares improve.

    My recommendation: actually do not acquire the speak that the Fed needs a delicate touchdown they need a greater unemployment price and will take a look at to speak the market into higher rates and reduce stock values after they come to really feel the will want to take action. As the expressing goes, “Fool me as quickly as, shame on you. Fool me two occasions, disgrace on me.”

    Breaking present market info quoted Waller as saying: Housing marketplaces within the U.S. will be high-quality.

    The housing market went into recession in June of this yr: earnings had been being down, output was down, positions ended up misplaced and incomes have been dropped. See, even with the housing sector in a financial downturn and positions being lacking, the Fed doesn’t care. To say a sector of the monetary system is high-quality though it is in a downturn demonstrates some disconnection from the real planet.

    Girls and gents, I provide the Federal Reserve in its purest kind after they say housing will be good when it is in a financial downturn. If it had been being me, I might have at the very least acknowledged that the housing market is in a recession and work alternatives are remaining shed. Then quickly after that assertion, I might discuss how I feel that it is vital for the housing present market to get concord, which is occurring appropriate now.


    Not acknowledging that employment are staying dropped in this type of an enormous sector of the monetary state would make you audio heartless and disconnected from actuality.

    Right after the numerous stock market place rally on Thursday and visual drop in mortgage loan rates, I questioned if the Fed would make a assertion to attempt to converse the marketplaces back. The Fed did make their statements this weekend, so get employed to this kind of response from the Federal Reserve proper up till the work-loss financial downturn transpires.

  • Why non-QM debtors are not likely absent at any time quickly

    When originations are down because of a dangerous mortgage mortgage market, the populace of underserved debtors who contain non-QM merchandise is on the rise.

    There will usually be a populace of debtors who are unable to qualify for a house mortgage beneath common suggestions. This vital pool of purchasers accommodates self-used, real property merchants and other people with credit score rating actions.

    Prospecting for these borrower varieties can assist safeguard your small business all through market shifts. Originators who actively work in simply the non-QM room are closing added loans every particular person thirty day interval.

    A seem at non-QM borrower profiles

    Self-Used: 

    In accordance to Upwork, there may be an estimated 59 million self-utilized personnel within the U.S. and rising.

    This includes 1099 and gig economic system employees. That is a great deal of potential debtors. The drawback these debtors face is usually not presently being geared up to make use of their tax returns due to to large tax write-offs. They will pay for the home and sometimes have superb to distinctive credit score historical past. But their tax returns are not reflective of their authentic financial predicament. They should have an alternative different to confirm their correct earnings and finally their skill-to-repay. The treatment: Bank Statement monetary loans. 

    Angel Oak’s Lender Statement financial institution mortgage is ideal for the self-employed.

    Financial loans as much as $3 million

    12 or 24 months explicit or enterprise monetary establishment statements permitted

    1099 incomes statements accepted

    Two an extended time seasoning demanded for private chapter, foreclosures, transient sale or deed-in-lieu

    Real Estate Traders: 

     The amount of monetary funding properties has outpaced the purchase of most vital properties in the midst of 2022.

    Any originator who has provided a DSCR Investor Funds Circulation mortgage to their dealer buyers is absolutely happy they did! We have closed a number of provides at only one time for the precise real property investor. Many originators have referred to as us to close a money-out refinance and a purchase for 1 borrower. They join with us since we let what Fannie and Freddie do not. We assist patrons buying their twenty second residence and these needing to title in an LLC.

    Marketing and promoting to precise property merchants is profitable regardless of the sector. Seasoned patrons will come throughout strategies to proceed to create their portfolios. They know wherever to find promotions and find out how to make the present market function of their favor. They additionally know originators to depend on to get them to the closing desk quickly. 

    Angel Oak’s DSCR Investor Income Move financial institution mortgage is ideal to close genuine property merchants.

    Financial loans as much as $1.5 million

    No personalised money move or tax returns wanted

    Qualifies on the money move of the house

    No limit on full vary of qualities

    Traders can title in an LLC

    Credit Issues: 

    Debtors who’ve recovered from a foreclosures or private chapter do not have maintain out seven years to get a mortgage mortgage. Successfully shut credit score score-worthy debtors with one explicit of our non-QM private mortgage items.

    Angel Oak’s Full Doc Portfolio Pick out is finest to shut debtors with credit score rating troubles:

    Mortgage portions as much as $2 million

    One explicit yr seasoning for foreclosures, transient sale or deed-in-lieu

    Two a long time seasoning for chapter

    Two a number of years seasoning for particular person chapter

    Operator-occupied, subsequent homes and expenditure homes


    Have A Issue?

    Use the shape down beneath and we’ll give your our professional solutions!

    Start off Your Bank mortgage

    with DDA now

    Your space Property finance mortgage Broker

    Mortgage mortgage Broker Largo

    See our Reviews

    Searching for way more info? Hear to our prolonged podcast! 

  • Mortgage prices are down, but not plenty of for most debtors

    House mortgage charges continued the downward pattern this week amid signs that the U.S. monetary system is cooling down because of the tightening monetary protection. The newest declines, then again, have not been enough to encourage debtors to get out a dwelling private mortgage. 

    “This week, labor value knowledge introduced a ray of hope because it confirmed that hourly compensation was decrease than previously claimed within the second and third quarters for all sectors apart from producing,” Danielle Hale, Realtor.com’s chief economist, acknowledged in an announcement.

    Hale further, “Anyone spending curiosity to the value on the pump would even have well-known a drop. Upcoming week’s Shopper Cost Index particulars will guarantee irrespective of whether or not these tendencies are pervasive all through the big selection of objects and services and products consumers get.” 

    All eyes on the Fed 

    Inflation and labor market are slowing down, which signifies that the Federal Reserve does not need to have to extend the federal cash worth as aggressively because it did with the 75 foundation level hikes from the earlier 4 conferences. Most buyers anticipate that in its assembly subsequent week, the Fed will hike charges by 50 bps in its place. 

    Which is why the conventional 30-year fastened-rate mortgage fee decreased to six.33% this week, down 16 basis factors when in comparison with the earlier week, based on the most recent Freddie Mac survey. The related monetary mortgage charges averaged 3.10% an individual calendar yr again. 

    At Mortgage Information Day by day, charges have been even lowered, at 6.29% on Thursday afternoon. 

    “Mortgage prices decreased for the fourth consecutive week because of rising issues about lackluster financial enlargement,” claimed Sam Khater, Freddie Mac’s chief govt, in an announcement. 

    “Over the ultimate 4 weeks, mortgage mortgage expenses have declined three-quarters of a stage, the premier drop on condition that 2008. Whilst the decline in premiums has been huge, homebuyer sentiment continues to be lowered, with no massive beneficial response in acquire need to those lower premiums.” 

    In accordance to Hale, the rationale is crystal distinct. Current declines in charges have launched the value of buying a dwelling down by an typical of $185 per thirty day interval, relative to the most recent peak in charges. Continue to, debtors are having to pay $880 for every thirty day interval rather more on common than final 12 months. The evaluation considers a buyer of a median-price residence for sale as we speak producing a ten% down cost. 

    Hale talked about that atmosphere a dwelling acquire funds has been “extremely laborious for residence prospects who’ve seen their buying vitality swing up and down as charges fluctuate.” 

    Flat and falling house charges

    According to information from the Mortgage Bankers Association (MBA), mortgage mortgage apps fell 1.9% this week in comparison with the Thanksgiving vacation break-altered success from the earlier week. 

    “Prospective homebuyers keep on to carry off choices to order homes, whilst property prices flatten or fall,” talked about Bob Broeksmit, MBA’s president and CEO, in a assertion. “The widespread mortgage measurement for a order software program previous 7 days was at its lowest degree in roughly two a number of years, one more indicator that dwelling worth ranges are cooling.”

    On the opposite hand, some analysts see some limits to residence value correction. The credit score rating evaluation firm Moody’s expects house prices to drop 12.2% in 2022, but by a 4.1% fall in 2023. 

    “The market place maintains primary strengths, together with favorable demographic developments, supply constraints instantly after a decade of underbuilding, and usually sound mortgage mortgage underwriting and buildings, within the selection of largely 30-calendar yr fastened monetary loans,” Moody’s analysts wrote in a report. 

    They additional that the challenges differ all through metropolitan components and distinct market segments, with potential dwelling promoting worth declines of 15%-25% or way more in some locations. Continue to, property values in these areas sometimes will carry on being properly above pre-pandemic concentrations, Moody’s analysts stated. 


    “The extent of latest booms, newest design levels, and adjustments in migration designs (e.g., as distant carry out and environmental troubles evolve) will generate space prices,” the analysts wrote. 

  • Millionaires are not constantly confident about retirement, survey states 35% of millionaires have reduced self confidence concentrations about living a cozy retirement

    The home mortgage cost pendulum swings nonetheless another time

    By Didier Malagies
    •
    18 Apr, 2024

    Be anticipating 2024 to be mildly improved than 2023 with mortgage mortgage charges falling within the second 50 % of the yr, housing consultants opined in their forecasts on the conclude of the calendar 12 months. Cuts to the Federal cash price (and subsequently to house finance mortgage premiums) are imminent, merchants enthused proper after December’s assembly of the Federal Open Industry Committee wherein committee customers predicted 3 price cuts in 2024. Some business consultants forecasted as many as 6 value cuts within the 12 months primarily based on this data. Amount cuts are nonetheless coming, simply not in March , merchants and sector business consultants reasoned way more currently because the economic system continued to function extremely scorching. And now on the heels of opinions of extra sturdy than envisioned careers improvement and stickier than anticipated inflation , the market’s change from optimism to pessimism greater than price cuts is end. Some even anticipate price hikes forward of cost cuts. The pessimism is clear in mortgage mortgage charges. Freddie Mac‘s weekly Primary Home mortgage Market place Study is climbing again towards 7%. HousingWire’s Home finance mortgage Fee Middle , which depends on information from Polly, is presently beforehand talked about 7.2%. Fees have been being as very low as 6.91% for Polly and 6.64% for Freddie as not too long ago as February. On Tuesday, they reached 7.50% on Mortgage News Every day, a excessive for this yr. Home mortgage prices preserve key energy within the housing sector most significantly, giant prices exacerbate the most recent affordability disaster by walloping the acquiring means of would-be prospects and discouraging some would-be sellers – these with decrease, set-rate house loans – from itemizing their houses, a drain on available inventories. All this leaves housing business consultants the second as soon as extra stopping for his or her share of shrinking pies – as we have noticed with simply currently produced mortgage mortgage data and RealTrends Verified’s brokerage information , as very nicely as deeper dives on the brokerage landscapes in Jacksonville and San Diego . It is unsurprising, then, that true property shares have endured provided that the FOMC’s March convention and the the most recent profession and inflation research. That incorporates the nation’s main homebuilders (DR Horton and Lennar), house mortgage originators (United Wholesale Mortgage and Rocket Mortgage mortgage), brokerages (Wherever and Compass) and family search for portals (Zillow and CoStar, which owns Residences.com). There are different dynamics at play for some of these companies, nevertheless. The brokerages are additionally contending with the rule changes included in a proposed settlement by the Countrywide Affiliation of Realtors some traders additionally think about folks rule modifications profit CoStar on the value of Zillow . UWM, in the meantime, is contending with a scathing investigative report by a hedge-fund-affiliated information company whose hedge fund shorted UWM and went prolonged on Rocket additionally it is working with pending litigation . UWM denies the allegations designed within the report.  Substantial house finance mortgage prices, fewer mortgage mortgage apps and fewer property product gross sales are nevertheless not the one outcomes housing professionals may see from a extra prolonged superior-charge ambiance. There are additionally spillover outcomes from different industries, significantly enterprise workplace true property. Regional monetary establishments – which historically have been foremost family mortgage mortgage originators – went large on business severe property monetary loans as bigger sized banking firms scaled again on this place in newest yrs. That amplified their publicity to downtown place of work towers, which have discovered an exodus of tenants and a bottoming out of appraised values simply as a report $2.2 trillion in business actual property debt arrives due above the subsequent quantity of a number of years. That ties up money that would if not circulation to family house loans and in some circumstances stresses banks like New York Local group Lender, mom or father of Flagstar Bank — the Seventh-largest monetary establishment originator of residential house loans, Fifth-largest sub-servicer of home mortgage monetary loans and the 2nd-largest house mortgage warehouse mortgage firm within the place. Homebuilders, far too, really feel the outcomes of extended important costs. Though homebuilder self confidence is nonetheless up drastically provided that earlier tumble, new housing begins are slowing . The dim prospects for homebuyers have turned some traders to the nascent establish-to-hire sector , primarily a wager that superior charges are on this article to maintain for intensive loads of that would-be shoppers are now would-be renters.

  • Retirement nest egg is not ample for many people right this moment, professional claims

    The mortgage mortgage stage pendulum swings however over again

    By Didier Malagies
    •
    18 Apr, 2024

    Expect 2024 to be mildly better than 2023 with mortgage charges slipping within the subsequent 50 % of the yr, housing specialists opined in their forecasts on the cease of the 12 months. Cuts to the Federal funds cost (and subsequently to property finance mortgage charges) are imminent, merchants enthused instantly after December’s convention of the Federal Open Current market Committee during which committee customers predicted a number of quantity cuts in 2024. Some specialists forecasted as a number of as six charge cuts within the 12 months centered on this information. Fee cuts are nonetheless coming, simply not in March , merchants and market specialists reasoned way more a short time in the past because the monetary system ongoing to run extremely scorching. And now on the heels of studies of extra strong than anticipated work growth and stickier than anticipated inflation , the market’s shift from optimism to pessimism above value cuts is full. Some even anticipate price hikes forward of charge cuts. The pessimism is apparent in residence finance mortgage prices. Freddie Mac‘s weekly Major Home mortgage Industry Study is climbing again to 7%. HousingWire’s Mortgage mortgage Charge Centre , which relies on details from Polly, is presently over 7.2%. Charges ended up as little as 6.91% for Polly and 6.64% for Freddie as a short time in the past as February. On Tuesday, they arrived at 7.50% on Home mortgage Information Day-to-day, a big for this yr. Home mortgage charges maintain essential energy within the housing market most significantly, important charges exacerbate the newest affordability catastrophe by walloping the getting electrical energy of would-be potential patrons and discouraging some would-be sellers – people with diminished, preset-charge residence loans – from itemizing their residences, a drain on on the market inventories. All this leaves housing execs as quickly as as soon as extra combating for their share of shrinking pies – as we’ve noticed with a short time in the past launched property finance mortgage information and RealTrends Verified’s brokerage particulars , as properly as deeper dives on the brokerage landscapes in Jacksonville and San Diego . It is unsurprising, then, that actual property shares have suffered contemplating that the FOMC’s March convention and the brand new profession and inflation studies. That incorporates the nation’s main homebuilders (DR Horton and Lennar), residence mortgage originators (United Wholesale Mortgage mortgage and Rocket House mortgage), brokerages (Any the place and Compass) and family search portals (Zillow and CoStar, which owns Properties.com). There are different dynamics at interact in for a few of these organizations, however. The brokerages are additionally contending with the rule modifications included in a proposed settlement by the National Affiliation of Realtors some merchants additionally suppose people rule changes benefit CoStar on the expense of Zillow . UWM, within the meantime, is contending with a scathing investigative report by a hedge-fund-affiliated info group whose hedge fund shorted UWM and went very lengthy on Rocket it is additionally working with pending litigation . UWM denies the allegations made within the report.  Superior residence finance mortgage prices, much less residence mortgage purposes and far much less property gross sales are nonetheless not the one results housing specialists might see from a extra extended high-rate atmosphere. There are additionally spillover outcomes from different industries, particularly enterprise workplace genuine property. Regional monetary establishments – which historically have been principal residential residence finance mortgage originators – went big on enterprise genuine property loans as better banking corporations scaled once more on this space in present many years. That better their publicity to downtown enterprise workplace towers, which have seen an exodus of tenants and a bottoming out of appraised values simply as a report $2.2 trillion in enterprise real property bank card debt will come owing above the long run variety of a number of years. That ties up money that might in any other case motion to residential residence loans and in some conditions stresses banking corporations like New York Neighborhood Lender, father or mother of Flagstar Financial establishment — the Seventh-most important monetary establishment originator of residential residence loans, Fifth-largest sub-servicer of mortgage mortgage monetary loans and the 2nd-biggest property finance mortgage warehouse lender within the area. Homebuilders, as properly, expertise the outcomes of prolonged important prices. Although homebuilder confidence is nonetheless up significantly contemplating the truth that final tumble, new housing begins are slowing . The dim potential patrons for homebuyers have turned some traders to the nascent develop-to-hire sector , primarily a wager that superior charges are proper right here to proceed to be for prolonged greater than sufficient that would-be shoppers are actually would-be renters.

  • Do not purchase the appraisal until just after the dwelling inspection

    The mortgage mortgage quantity pendulum swings nonetheless as soon as extra

    By Didier Malagies
    •
    18 Apr, 2024

    Count on 2024 to be mildly significantly better than 2023 with mortgage premiums slipping in the 2nd fifty p.c of the yr, housing professionals opined in their forecasts at the end of the yr. Cuts to the Federal money worth (and subsequently to mortgage costs) are imminent, merchants enthused after December’s convention of the Federal Open up Market place Committee through which committee customers predicted 3 cost cuts in 2024. Some authorities forecasted as a number of as 6 quantity cuts in the yr primarily based totally on this data. Charge cuts are proceed to coming, just not in March , merchants and market professionals reasoned further just lately as the general economic system ongoing to function scorching. And now on the heels of research of extra highly effective than envisioned jobs growth and stickier than anticipated inflation , the market’s change from optimism to pessimism over cost cuts is full. Some even expect quantity hikes prematurely of quantity cuts. The pessimism is seen in home mortgage premiums. Freddie Mac‘s weekly Most essential Home finance mortgage Industry Study is climbing again once more in direction of 7%. HousingWire’s Property finance mortgage Price Center , which will depend on knowledge from Polly, is now over 7.2%. Premiums have been as little as 6.91% for Polly and 6.64% for Freddie as not too way back as February. On Tuesday, they arrived at 7.50% on Property finance mortgage Information Daily, a excessive for this yr. Home finance mortgage prices maintain main potential in the housing area most significantly, important charges exacerbate the current affordability catastrophe by walloping the acquiring energy of would-be potential patrons and discouraging some would-be sellers – these with minimal, mounted-level mortgages – from itemizing their residences, a drain on on the market inventories. All this leaves housing specialists after as soon as once more combating for his or her share of shrinking pies – as now we have observed with just currently launched mortgage mortgage data and RealTrends Verified’s brokerage information , as completely as additional dives on the brokerage landscapes in Jacksonville and San Diego . It is unsurprising, then, that severe property shares have skilled contemplating that the FOMC’s March convention and the newest job and inflation evaluations. That incorporates the nation’s main homebuilders (DR Horton and Lennar), residence finance mortgage originators (United Wholesale Mortgage mortgage and Rocket Home mortgage), brokerages (Everywhere and Compass) and residential analysis portals (Zillow and CoStar, which owns Homes.com). There are different dynamics at carry out for a few of these companies, nonetheless. The brokerages are additionally contending with the rule alterations integrated in a proposed settlement by the Nationwide Affiliation of Realtors some patrons additionally think about folks rule modifications profit CoStar at the expenditure of Zillow . UWM, in the meantime, is contending with a scathing investigative report by a hedge-fund-affiliated information agency whose hedge fund shorted UWM and went prolonged on Rocket it is usually coping with pending litigation . UWM denies the allegations in-built the report.  Substantial mortgage prices, a lot much less mortgage functions and far much less dwelling income are nonetheless not the solely penalties housing trade specialists may see from a further extended high-level pure atmosphere. There are additionally spillover results from different industries, primarily enterprise workplace true property. Regional banking corporations – which traditionally have been large family mortgage originators – went large on industrial genuine property loans as extra substantial banking corporations scaled again on this spot in trendy a very long time. That enhanced their publicity to downtown administrative center towers, which have discovered an exodus of tenants and a bottoming out of appraised values just as a file $2.2 trillion in skilled severe property bank card debt arrives due to over the upcoming couple of yrs. That ties up capital that might usually stream to residential mortgages and in some instances stresses banks like New York Local neighborhood Bank, father or mom of Flagstar Lender — the Seventh-biggest monetary establishment originator of family mortgages, Fifth-premier sub-servicer of mortgage mortgage loans and the 2nd-largest property finance mortgage warehouse mortgage supplier in the area. Homebuilders, far too, really really feel the outcomes of prolonged excessive prices. Although homebuilder self-confidence is nonetheless up considerably on condition that ultimate tumble, new housing commences are slowing . The dim potential clients for homebuyers have turned some merchants to the nascent construct-to-hire sector , in essence a guess that important costs are beneath to stay for in depth ample that would-be patrons are actually would-be renters.

  • Us residents are not saving enough for retirement although nevertheless performing

    The dwelling finance mortgage quantity pendulum swings nevertheless as soon as once more

    By Didier Malagies
    •
    18 Apr, 2024

    Count on 2024 to be mildly higher than 2023 with home mortgage premiums slipping within the 2nd half of the 12 months, housing authorities opined in their forecasts on the conclude of the 12 months. Cuts to the Federal assets fee (and subsequently to dwelling finance mortgage charges) are imminent, merchants enthused after December’s convention of the Federal Open up Market place Committee by which committee associates predicted 3 quantity cuts in 2024. Some professionals forecasted as many as six stage cuts within the yr based mostly on this information. Price cuts are nonetheless coming, simply not in March , merchants and business specialists reasoned further not way back because the financial local weather ongoing to run scorching. And now on the heels of studies of extra strong than anticipated careers development and stickier than anticipated inflation , the market’s change from optimism to pessimism greater than value cuts is full. Some even count on cost hikes upfront of fee cuts. The pessimism is seen in mortgage costs. Freddie Mac‘s weekly Primary Mortgage Market Survey is climbing again in the direction of 7%. HousingWire’s House mortgage Fee Heart , which will depend on data from Polly, is by now over 7.2%. Costs had been being as very low as 6.91% for Polly and 6.64% for Freddie as not too long ago as February. On Tuesday, they arrived at 7.50% on Property finance mortgage Information Each day, a big for this yr. House mortgage charges maintain main electrical energy within the housing subject most significantly, superior costs exacerbate the latest affordability catastrophe by walloping the procuring for electrical energy of would-be purchasers and discouraging some would-be sellers – all these with small, set-charge mortgages – from itemizing their households, a drain on accessible inventories. All this leaves housing professionals as soon as as soon as once more combating for their share of shrinking pies – as we now have seen with a short time in the past unveiled home mortgage information and RealTrends Verified’s brokerage info , as completely as deeper dives on the brokerage landscapes in Jacksonville and San Diego . It is unsurprising, then, that actual property shares have skilled because the FOMC’s March assembly and the brand new occupation and inflation experiences. That incorporates the nation’s prime rated homebuilders (DR Horton and Lennar), dwelling finance mortgage originators (United Wholesale House mortgage and Rocket Home finance mortgage), brokerages (Wherever and Compass) and residential lookup portals (Zillow and CoStar, which owns Homes.com). There are different dynamics at take part in for a few of these companies, even so. The brokerages are additionally contending with the rule variations bundled in a proposed settlement by the National Association of Realtors some buyers additionally imagine that individuals rule alterations edge CoStar on the expenditure of Zillow . UWM, in the meantime, is contending with a scathing investigative report by a hedge-fund-affiliated information enterprise whose hedge fund shorted UWM and went very lengthy on Rocket it’s also coping with pending litigation . UWM denies the allegations made within the report.  Higher mortgage mortgage charges, a lot much less mortgage mortgage functions and fewer property product gross sales are regrettably not the one outcomes housing professionals may see from a additional extended large-price setting. There are additionally spillover outcomes from different industries, particularly place of job critical property. Regional banks – which usually have been key family home mortgage originators – went enormous on skilled critical property monetary loans as extra substantial banking establishments scaled again once more on this area in newest a very long time. That elevated their publicity to downtown place of job towers, which have discovered an exodus of tenants and a bottoming out of appraised values simply as a document $2.2 trillion in industrial real property private debt will come thanks round the next few a long time. That ties up cash that might in any other case stream to residential dwelling loans and in some situations stresses banks like New York Local group Bank, father or mom of Flagstar Bank — the Seventh-greatest lender originator of family dwelling loans, Fifth-biggest sub-servicer of mortgage monetary loans and the 2nd-biggest dwelling mortgage warehouse mortgage supplier within the state. Homebuilders, a lot too, expertise the results of prolonged excessive premiums. Although homebuilder self-assurance is nevertheless up considerably because of the truth previous fall, new housing begins off are slowing . The dim potential prospects for homebuyers have turned some buyers to the nascent develop-to-lease sector , in essence a wager that substantial costs are proper right here to remain for prolonged ample that would-be shoppers are now would-be renters.

  • Not only prospective buyers currently being cheated on wire fraud now creditors

    The property finance mortgage stage pendulum swings however but once more

    By Didier Malagies
    •
    18 Apr, 2024

    Count on 2024 to be mildly higher than 2023 with mortgage costs falling within the subsequent fifty p.c of the 12 months, housing specialists opined in their forecasts on the conclude of the calendar 12 months. Cuts to the Federal funds cost (and subsequently to mortgage mortgage charges) are imminent, merchants enthused instantly after December’s assembly of the Federal Open Current market Committee through which committee prospects predicted a couple of quantity cuts in 2024. Some trade specialists forecasted as fairly a couple of as 6 price cuts within the 12 months primarily based on this information. Rate cuts are nevertheless coming, simply not in March , merchants and market trade specialists reasoned extra not way back because the monetary system continued to run highly regarded. And now on the heels of research of extra highly effective than predicted jobs progress and stickier than predicted inflation , the market’s change from optimism to pessimism over worth cuts is end. Some even assume cost hikes forward of stage cuts. The pessimism is seen in mortgage mortgage costs. Freddie Mac‘s weekly Most vital House mortgage Sector Study is climbing once more within the route of seven%. HousingWire’s Home finance mortgage Price Heart , which relies upon on particulars from Polly, is presently beforehand talked about 7.2%. Costs had been as diminished as 6.91% for Polly and 6.64% for Freddie as recently as February. On Tuesday, they arrived at 7.50% on House mortgage Information Day by day, the next for this 12 months. Mortgage prices maintain large electrical energy within the housing enterprise most significantly, important premiums exacerbate the newest affordability catastrophe by walloping the acquiring capability of would-be potential buyers and discouraging some would-be sellers – these with decrease, mounted-charge residence loans – from itemizing their houses, a drain on accessible inventories. All this leaves housing trade specialists when once more preventing for his or her share of shrinking pies – as now we have noticed with not too way back produced property finance mortgage information and RealTrends Verified’s brokerage data , in addition to additional dives on the brokerage landscapes in Jacksonville and San Diego . It is unsurprising, then, that real property shares have skilled as a result of reality the FOMC’s March meeting and the newest profession and inflation tales. That consists of the nation’s high homebuilders (DR Horton and Lennar), residence finance mortgage originators (United Wholesale Home finance mortgage and Rocket Property finance mortgage), brokerages (Any place and Compass) and family search for portals (Zillow and CoStar, which owns Properties.com). There are different dynamics at play for a few of these firms, nevertheless. The brokerages are additionally contending with the rule modifications built-in in a proposed settlement by the National Association of Realtors some merchants additionally think about these rule enhancements edge CoStar at the price of Zillow . UWM, in the meantime, is contending with a scathing investigative report by a hedge-fund-affiliated information enterprise whose hedge fund shorted UWM and went intensive on Rocket it is usually working with pending litigation . UWM denies the allegations created within the report.  Superior residence finance mortgage costs, fewer residence mortgage apps and fewer home earnings are regretably not the only results housing gurus might see from a way more prolonged higher-charge setting. There are additionally spillover results from different industries, particularly enterprise workplace genuine property. Regional banking firms – which ordinarily have been key residential residence mortgage originators – went massive on industrial real property monetary loans as extra substantial banking firms scaled again on this house in new a long time. That elevated their publicity to downtown office towers, which have discovered an exodus of tenants and a bottoming out of appraised values simply as a report $2.2 trillion in industrial real property bank card debt comes owing above the following couple of a long time. That ties up capital that might usually motion to residential residence loans and in some circumstances stresses banks like New York Community Bank, father or mom of Flagstar Lender — the Seventh-premier lender originator of residential mortgages, Fifth-most important sub-servicer of property finance mortgage monetary loans and the 2nd-most important mortgage mortgage warehouse mortgage supplier within the state. Homebuilders, far too, really really feel the consequences of extended greater expenses. Whilst homebuilder self-worth is nevertheless up appreciably contemplating the truth that previous slide, new housing begins off are slowing . The dim potential prospects for homebuyers have turned some buyers to the nascent construct-to-lease sector , successfully a guess that enormous prices are listed right here to stay for prolonged sufficient that would-be purchasers are now would-be renters.