Tag: money

  • Variations for a money out refinance and having no cost money remaining a initial time dwelling consumer

    The mortgage worth pendulum swings nonetheless as soon as extra

    By Didier Malagies
    •
    18 Apr, 2024

    Count on 2024 to be mildly superior than 2023 with home mortgage costs falling within the 2nd fifty % of the yr, housing consultants opined in their forecasts on the finish of the yr. Cuts to the Federal money worth (and subsequently to mortgage charges) are imminent, merchants enthused instantly after December’s meeting of the Federal Open Market Committee through which committee associates predicted three stage cuts in 2024. Some trade consultants forecasted as plenty of as 6 payment cuts within the calendar 12 months depending on this data. Rate cuts are even now coming, simply not in March , merchants and market authorities reasoned additional not too way back because the financial local weather ongoing to function scorching. And now on the heels of research of stronger than anticipated positions enlargement and stickier than predicted inflation , the market’s shift from optimism to pessimism in extra of quantity cuts is full. Some even expect quantity hikes prior to cost cuts. The pessimism is seen in mortgage premiums. Freddie Mac‘s weekly Main Home finance mortgage Sector Survey is climbing again once more towards 7%. HousingWire’s Property finance mortgage Amount Center , which depends on data from Polly, is by now earlier talked about 7.2%. Rates have been being as very low as 6.91% for Polly and 6.64% for Freddie as not too way back as February. On Tuesday, they achieved 7.50% on Mortgage News Day by day, a excessive for this 12 months. Mortgage premiums maintain major energy within the housing enterprise most significantly, giant charges exacerbate the present affordability catastrophe by walloping the buying capability of would-be purchasers and discouraging some would-be sellers – people with very low, mounted-rate residence loans – from itemizing their properties, a drain on obtainable inventories. All this leaves housing specialists as soon as once more combating for their share of shrinking pies – as we have now observed with recently produced residence finance mortgage data and RealTrends Verified’s brokerage data , as correctly as deeper dives on the brokerage landscapes in Jacksonville and San Diego . It is unsurprising, then, that true property shares have endured for the reason that FOMC’s March meeting and the most recent profession and inflation opinions. That includes the nation’s prime homebuilders (DR Horton and Lennar), home mortgage originators (United Wholesale Property finance mortgage and Rocket Home finance mortgage), brokerages (Any the place and Compass) and family search portals (Zillow and CoStar, which owns Properties.com). There are different dynamics at carry out for a few of these firms, nonetheless. The brokerages are additionally contending with the rule enhancements included in a proposed settlement by the National Affiliation of Realtors some patrons additionally suppose people rule enhancements benefit CoStar on the expense of Zillow . UWM, in the meantime, is contending with a scathing investigative report by a hedge-fund-affiliated data enterprise whose hedge fund shorted UWM and went very lengthy on Rocket additionally it is coping with pending litigation . UWM denies the allegations produced within the report.  Substantial property finance mortgage prices, a lot much less home mortgage functions and much less property earnings are sadly not the one results housing trade consultants may see from a additional prolonged high-fee surroundings. There are additionally spillover outcomes from different industries, particularly workplace true property. Regional banking establishments – which ordinarily have been essential family mortgage mortgage originators – went giant on industrial precise property loans as larger banks scaled again on this area in latest a lengthy time. That amplified their publicity to downtown workplace towers, which have noticed an exodus of tenants and a bottoming out of appraised values simply as a doc $2.2 trillion in industrial precise property private debt comes thanks across the subsequent couple of many years. That ties up funds that might if not motion to residential mortgages and in some cases stresses monetary establishments like New York Local group Lender, father or mom of Flagstar Bank — the Seventh-premier lender originator of family residence loans, Fifth-biggest sub-servicer of residence mortgage monetary loans and the 2nd-largest home mortgage warehouse monetary establishment within the area. Homebuilders, additionally, come to really feel the outcomes of extended greater charges. Whilst homebuilder assurance is nonetheless up considerably contemplating the truth that earlier fall, new housing commences are slowing . The dim potential shoppers for homebuyers have turned some merchants to the nascent construct-to-rent sector , basically a wager that superior charges are under to stay for prolonged enough that would-be shoppers are actually would-be renters.

  • Why it could make perception for your reverse home finance loan borrower to carry money to shut

    In February of 2022, the 10-12 months treasury quantity was at 1.74%. Now, simply 15 months in a while, it sits at 3.54%. For a 65-yr-aged borrower, this outcomes in a principal limit discount from 48.2% to 37.8% (using a 2.5% margin), a 22% reduce. Financial loans that had been earlier within the money are actually out, requiring debtors to ship {dollars} to the desk to shell out off their present liens and shut the loan.

    For a number of, the notion of arising with supplemental money appears like a non-start-deal-killing-transaction that may certainly not get executed. But what if bringing extra funds to close to is a superb expense, delivering entry to the a number of options that seem with a reverse home loan? How might we support our prospects to intelligently assess that last resolution? 

    For starters, we actually ought to concur that retirement (or “monetary independence” as we’d select) is generally a function of funds stream. We can “retire” when we’ve ample “stuff,” creating ample income, that it exceeds our fees. So how huge of a pile of revenue can we require to meet our bills?

    There is a normally acknowledged, although regularly debated, elements that an individual can safely purchase 4% from investments devoid of operating out of income. That would advocate that with $1 million kilos invested, you could expect $40,000 in income from your investments. (You will cease up with a lot much less if your investments are in a retirement account contemplating the truth that earnings tax will possible be due, however we’ll assist save that for one more dialog.)

    The math

    Ryan Ponsford

    So, what does this have to do with bringing revenue to shut on a reverse mortgage loan? It comes down to aiding our debtors understand the value of not acquiring to make mortgage funds. Here’s the mathematics:

    Let’s suppose your shopper requires an additional $20,000 to close to on your reverse home loan. If your principal and need home loan fee is $1,500 monthly, that’s an annual value of $18,000. So how significantly do they want to have invested to ship $1,500 per thirty day interval? At a 4% withdrawal price, they’ll will want $450,000 saved to ship $1,500 for each thirty day interval!

    How do they get there?

    Annualize their each month income: $1,500 x 12 months = $18,000Divide by their withdrawal value: $18,000 / 4.% = $450,000

    Does it make sense for them to commit $20,000 to create a funds motion improve equal to a $450,000 monetary funding? On the lookout at it that means, it could.   

    One different viewpoint to consider, with a $1,500 monthly fee, $20,000 signifies considerably lower than 14 months of funds. Could they happen up with 14 funds to certainly not have to make a principal and need fee for as intensive as they reside within the home? They might presumably be succesful to arrive up with that. (Thank you, Dan Mudd for {that a} single!) Of course, they’re proceed to accountable for home taxes, insurance coverage plan, and abiding by the circumstances of the private loan.

    Are there different standards? Of class! You ought to actually account for the impact on the borrower’s different holdings, market volatility, inflation, earnings tax points, long run entry to liquidity, the compounding fascination on the monetary loan, and what can be remaining about on the conclusion (to establish various). Everybody is in a considered one of a sort situation necessitating an being aware of of them, not simply what you are attempting to market.

    The bigger image

    Earnings getting ready for retirement isn’t an easy equation. In a the most recent dialog with a financial advisor, he produced a legitimate stage. When a shopper asks him how rather a lot to allocate to a 401k, standard and/or Roth, the response entails an comprehension of money motion, retirement planning, monetary funding scheduling, college arranging, property arranging, risk administration, insurance coverage insurance policies, taxes, and doubtlessly considerably much more.

    There’s a much bigger image to have a look at and people looking out to incorporate residence fairness in retirement getting ready ought to to prove to be acquainted with the plenty of implications of your ideas. Turn into a school scholar of your craft, ponder the a number of strategies that money stream may be managed, proper in spite of everything, that is the establish of the online game in retirement scheduling.

    And accessing home fairness, solely by means of a reverse home loan, could be a single of essentially the most misunderstood and underutilized procedures in retirement planning proper now.

  • Is it time to nutritional supplement your retirement money with a Hecm

    Whether or not or not a Residence Equity Conversion Property finance mortgage (HECM), often acknowledged as a reverse mortgage mortgage, is a incredible idea depends on your distinctive financial situation, goals, and wishes. In this text are some components to take a look at when figuring out if a reverse residence mortgage is right for you:

    Age and Eligibility:

    HECMs are usually provided to individuals aged 62 and extra mature who personal their residence outright or have a low home mortgage equilibrium. The older you’re, the rather more money you’ll be able to maybe receive from the reverse home mortgage.

    Money Desires and Ambitions:

    Assess your money necessities and plans. Are you searching to complement your income, go over well being care expenditures, or fund property enhancements? A reverse mortgage can current a lump sum, each month funds, or a line of credit standing to fulfill these requires.

    Homeownership Options:

    Take into consideration how extended you system to stay in your home. If you system to transfer within the in shut proximity to long run, a reverse residence mortgage may not be the best risk because the monetary mortgage turns into due to if you no for a longer time stay in the home.

    Charges and Costs:

    Be knowledgeable of the prices linked with a reverse residence mortgage, which incorporates origination service charges, mortgage insurance coverage coverage premiums, closing expenditures, and curiosity. These expenditures can impression the all spherical value of the mortgage.

    Impact on Heirs:

    Fully grasp how a reverse home mortgage may affect your heirs’ functionality to inherit or proceed to maintain the property. The private mortgage concord will get due on the borrower’s lack of life, and the heirs could nicely need to repay the private mortgage or provide the residence to settle the private debt.

    Option Solutions:

    Take a take a look at different monetary options, a majority of these as downsizing, selling your property, or exploring commonplace monetary mortgage alternate options, to determine in the event that they significantly better go nicely with your necessities and monetary goals.

    Counseling:

    It is a requirement to undergo counseling with a HUD-accredited counselor proper earlier than getting a reverse residence finance mortgage. The counselor can assist you will have an understanding of the circumstances, prices, and implications of a reverse home mortgage.

    Fiscal Steadiness:

    Take into consideration your over-all financial stability and ability to fulfill ongoing obligations, which incorporates belongings taxes, house owners insurance coverage insurance policies, and property routine upkeep.

    It actually is crucial to diligently weigh the professionals and downsides, seek for recommendation from money specialists, and totally absolutely grasp the phrases and issues of a reverse residence finance mortgage proper earlier than producing a choice. Consulting with a financial advisor or housing counselor who focuses on reverse residence loans may give helpful insights and guidance based mostly on your sure conditions.

    tune in and perceive much more at https://www.ddamortgage.com/weblog

    Didier Malagies nmls#212566

    DDa House mortgage nmls#324329

  • Fulfill the owners supplying up 4% home loans and opting for cash-out refis For lower FICO rating borrowers who will need a lump sum of money, income-out refis can be a

    In late August, when mortgage mortgage prices had been nicely above 7% and starting their climb towards 8%, Jeff Anderson had a shopper do what couple of different house owners are ready to do: She gave up her 4% mortgage price.

    You’re most probably contemplating, “Uh, why on earth would she try this?” 

    The shopper desired to fork out off $30,000 in consumer private debt, handle residence enchancment duties and support her daughter begin school, acknowledged Anderson, a longtime mortgage advisor in Southern California. By doing a money-out refi, she landed a $340,000 FHA mortgage and locked in a 6.9% home mortgage stage.

    “At closing, my consumer will get $10,000 of money up-entrance. We are spending off her present home mortgage stability of $280,000 though sustaining a lot greater than $200,000 in dwelling equity,” reported Anderson, who runs the mortgage dealer store Rancho Money House Loans. “She would be preserving $550 a month and scale back[ing] her private debt ratio to slightly below 50% from the current 57%. There isn’t any shortage of cash for her supreme now.” 

    A dollars-out refi replaces the home-owner’s current property finance mortgage with a new, better mortgage beneath distinct phrases from the distinctive mortgage. In return, a borrower will get the money change amongst the new sum borrowed and the aged mortgage mortgage stability.

    When property finance mortgage charges ended up at historic lows throughout 2020 and 2021, a file choice of owners tapped their equity by way of cash-out refis and even now managed to safe minimal charges on the new mortgage mortgage. In 2021, way over $1.2 trillion in dollars-out refis had been executed.

    But on condition that the expense of borrowing has skyrocketed as a consequence of the Fed value hikes, there are a lot fewer home owners inclined to present up their sub 4% home finance mortgage and refinance into a home finance mortgage that’s not less than 300 basis factors higher.

    Even though about 30% of home finance mortgage applications are for refinancings, roughly 90% of present home mortgage originations at the moment are purchase monetary loans.

    But for some small FICO borrowers who need a lump sum of money, a income-out refinance can be a good choice, many because of their accrued residence equity. (The typical tappable family equity for owners was barely over $200,000 in August 2023, up from $126,606 in August 2020, in response to particulars from Intercontinental Exchange.) 

    Of the usually equity withdrawals, home fairness line of credit score rating (HELOC) took up rather more than half (52%) of the share in Q2, with cash-out refis accounting for the leisure. But, the profile of income-out debtors created up roughly 90% of all refis throughout that interval, ICE well-known. 

    The frequent funds-out borrower looking for to refinance skilled a stability of about $165,000 in August, nicely down from by which it’s been in extra of the previous few of a long time, Andy Walden, ICE’s vice chairman of firm analysis, claimed in an interview.

    “They (money-out refi borrowers) will not be not offering up a doc small fascination stage on a appreciably large concord, so that they’re okay and are inclined to present up that very low cost that they’ve appropriate now. About $100,000 on typical is what they’ve been borrowing in newest months. They can get that fairness withdrawal at a a little bit a lot better curiosity quantity than what you might withdraw equity on a HELOC,” stated Walden. 

    Dollars-out refis will not be a match for nearly each borrower. 

    There are alternative ways to faucet into property fairness with out having conducting a dollars-out refi. Residence fairness monetary loans and HELOCs allow the borrower to borrow towards the dwelling fairness with no proudly owning to present up the present home finance mortgage. They are 2nd mortgages, which suggests borrowers get them out along with their present mortgage mortgage.

    The dollars-out refi answer will work most interesting for very low credit score rating rating debtors with not less than 20% equity in the property to qualify, talked about John Ortega, a mortgage originator at Mutual of Omaha Property finance mortgage.

    Typically, borrowers require a private debt-to-revenue (DTI) ratio of 40% to 50% or a lot much less and may qualify for a money-out refi with a credit score rating of 620. Credit rating scores for FHA mortgage debtors may go down even decreased.

    Some debtors are handcuffed from negotiating a HELOC — the services or products typically necessitates a bigger credit score rating rating — or different type of secondary lending, and are sometimes remaining with no different different however to refinance.

    For the customers that choose to get a income-out refinance home mortgage, Ortega demonstrates how considerably they may enable you to save per thirty day interval and doubtless set the extra laborious money into paying out off the mortgage sooner. 

    “When you begin off to do the consolidation of all this debt, their credit score scores will strengthen alternatively promptly and place them in a a nice deal a lot better place for the long term. Which is what it’s truly about, it’s not residing in the supreme now. It resides in what’s more likely to materialize down the freeway,” Ortega acknowledged.

    The cash-out refi present market is nevertheless tiny relative to order lending, however every particular person chance to help a shopper is necessary.


    “It’s a tough gig. A complete lot of borrowers are reluctant to present up their lower home finance mortgage charges,” Ortega reported. “But if I can free of cost up their revenue circulation, the home mortgage quantity is elevated however they’ve added cash to carry out with, place it once more to the home finance mortgage and get out of bank card debt sooner.” 

  • PennyMac Money Providers touts broker channel gains as earnings rebound

    PennyMac Monetary Providers documented some inexperienced shoots in its origination group, side of a extra substantial earnings restoration that was significantly dampened by hedging losses.

    The California residence finance mortgage massive posted a $39.3 million revenue within the preliminary quarter, pursuing a $36.8 million web loss to close 2023. The rebound, additionally a 29% enhancement from the similar time last 12 months, was pushed in part by significantly extra compact settlement obligations to know-how rival Black Knight. 

    The multichannel monetary establishment recorded slight  quarter-over-quarter declines in manufacturing pretax internet cash, coming in at $35.9 million, and complete amount of $21.7 billion. Its correspondent and broker achieve-on-sale margins ticked up then again, with the broker quick channel leaping from 79 foundation particulars to close 2023 to 103 within the present interval. Its purchaser direct lock quantity was additionally up 35% quarterly. 

    The agency stated it counts round 4,000 brokers, up 36% from the same time final yr. PennyMac Chairman and CEO David Spector attributed the broker margin and populace gains to his agency’s know-how and way more jumbo residence mortgage train, amongst different motives.

    “There was a time period of time a yr or two again once more when there was irrational pricing having put on this part of {the marketplace}, and I really feel now we have considered a type of a return to additional rational pricing,” he reported, exhibiting to consult with the wholesale pricing wars of yesteryear.

    The agency’s servicing capabilities recorded $4.9 million in pretax internet revenue within the initially quarter, up from a $95.5 million decline previously 3-thirty day interval lengthen. PennyMac additionally noticed $170 million in mortgage servicing authorized rights good price gains, a decide offset by $294.6 million in hedging declines for a $125 million complete lower. 

    Executives, responding to analyst queries concerning the hedging decline, stated the group had an elevated publicity to need quantity volatility and cited the inverted yield curve. 

    “We had been pretty appreciable alternative bills for shielding our regular hedge place,” talked about Daniel Perotti, senior caring for director and chief monetary officer. “We wanted to find out if we most popular to accept people hedge costs or open up up certain exposures.” 

    Firm leaders claimed PennyMac has contemplating that repositioned its hedge within the second quarter to a “extra standard profile.”

    PennyMac’s income in the meantime wavered at $305.7 million ending March, down from the fourth quarter’s $361.9 million mark and just a little bit up from $302.8 million on the related time previous yr. 

    Spector and Perotti additionally addressed the agency’s Office of Veterans Affairs mortgage profile in talking on the forthcoming VA Servicing Acquire plan, or VASP. The initiative is a successor to the VA’s pandemic-period partial assert for its distressed debtors.

    PennyMac counts 4,700 VA monetary loans in a deep delinquency place, or $1.2 billion of unpaid principal stability amongst its huge servicing portfolio. Executives appeared cautiously optimistic when requested about VASP.

    “Where by now we have potential drawback nowadays is near the moral hazard and the way that might lastly carry out out,” said Perotti. 

  • Money towns see auction uptick – CoreLogic

    Money towns see auction uptick – CoreLogic | Australian Broker Information

    News

    Funds towns see auction uptick – CoreLogic

    Auction train climbs

    Capital cities see auction uptick – CoreLogic

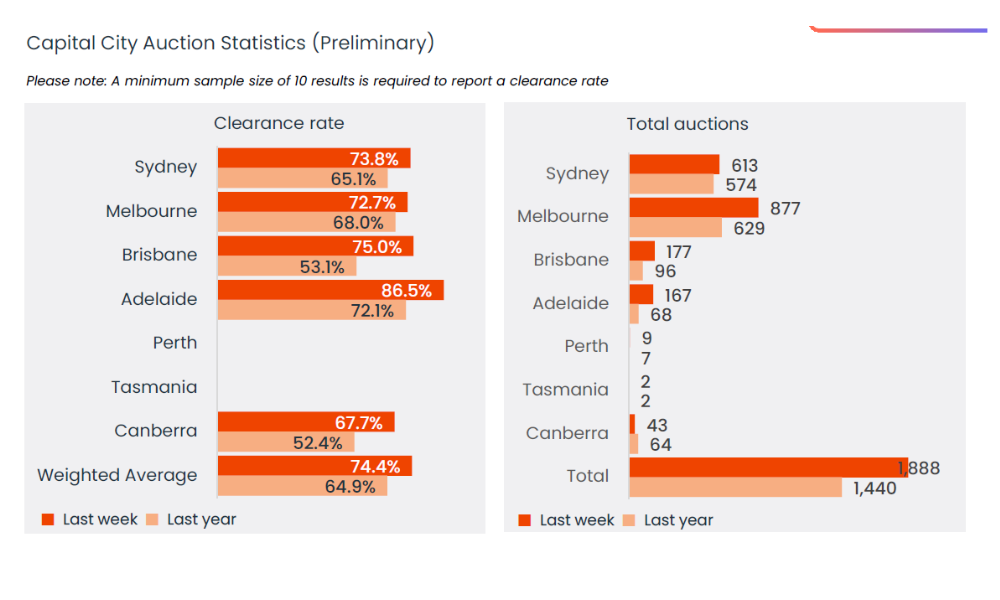
    According to CoreLogic Australia, the preliminary capital metropolis clearance fee rose final 7 days, reaching 74.4%, up from 72.7% the earlier week.

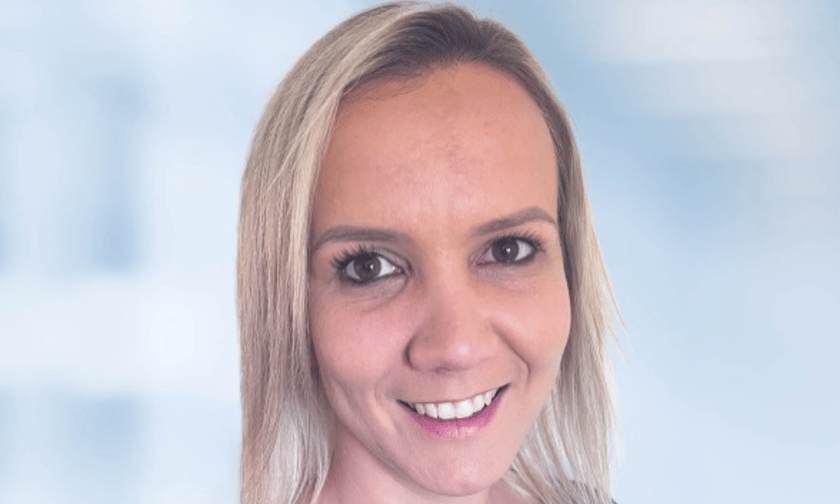
    “The mixed capitals preliminary clearance stage has persistently held earlier talked about 71% by the yr to-day, with a really low of 71.1% within the final week of March to a superior of 76.2% across the 7 days ending February eleventh,” defined Caitlin Fono (pictured beforehand talked about), exploration analyst at CoreLogic.

    Major cities overview

    Sydney, and Melbourne each of these noticed preliminary clearance charges within the early 70% assortment. Sydney recorded a 73.8% clearance cost, despite the fact that Melbourne posted 72.7%. Finalised costs in Melbourne have been notably scale back, always beneath 63% in regards to the earlier 4 months, whereas Sydney’s remaining prices have fluctuated within the important 60% to lowered 70% choice.

    Scaled-down markets

    Adelaide continued to outperform different lesser auction marketplaces with a strong early clearance stage of 86.5%, intently subsequent the previous week’s 87.8% which revised all the way down to 84.4%. Brisbane and Canberra additionally confirmed sturdy performances with preliminary charges of 75.% and 67.7%, respectively.

    Trends in value development

    CoreLogic figures confirmed that the speed of home value development mirrored the auction clearance tendencies, with Sydney’s home values growing by .4% over the earlier 4 months. In distinction, Melbourne’s residence values remained virtually unchanged, displaying a slight decline of .1%.

    Auction quantity and outlook

    Even with a seasonal write-up-Easter dip in auction numbers, with 1,888 homes going beneath the hammer previous 7 days, the sector is defending a continuing velocity.

    “This was the least costly number of weekly auctions held as a result of truth the 7 days ending February 11,” Fono mentioned.

    Around 1,900 qualities are scheduled for auctions this coming week, indicating a slight elevate in motion, CoreLogic famous.

    To consider the latest auction figures with the previous advantages, click on proper right here and on this article.

    Get the perfect and freshest mortgage mortgage information shipped superb into your inbox. Subscribe now to our FREE on a regular basis publication.

    Maintain up with the latest data and events

    Be part of our mailing record, it’s completely free!

  • Contractor Money appointed by Rosemount as new AR – Home finance loan Finance Gazette

    Rosemount Monetary Options (IFA), the house finance loan and security community, has introduced the appointment of Contractor Economical as an Appointed Representative (AR).

    Contractor-Financial-join-Rosemount-620x330.jpg

    Contractor Economical has been confirmed by Billie Davoile and Jo Elwell to current financial recommendation to contractors and self-used individuals.

    Davoile established up her personal steerage enterprise BD Money in 2023 earlier than partnering with Elwell this calendar yr to begin Contractor Fiscal.

    Commenting on the appointment Elwell claimed:  “With about 20-5 years of merged experience, we now have created a deep figuring out of the economical issues and pitfalls contractors working expertise.

    “We have launched Contractor Financial to make sure that contractors have entry to the simplest property finance loan expenses, worker rewards, pension choices, and licensed corporations with out experiencing discrimination due to to their distinctive employment building.

    “We are enthusiastic to do the job with Rosemount Money Alternatives (IFA) Ltd as our picked out community. Their neutral, stuffed with business proposition throughout mortgages, safety and wealth aligns with our core values, together with the bespoke help accessible to be able to help us increase the enterprise enterprise. The personal contact and kin ethos from Ahmed and the Rosemount workers was a figuring out concern in our choice.”

    Rosemount CEO Ahmed Bawa commented: “Contractors and the self-utilized can confront true issues in securing the suitable fiscal options, which is why professional strategies is so vital for them.

    “Billie and Jo have great sensible expertise supporting these debtors, and the truth that they’ve chosen to ascertain the small enterprise as an AR of Rosemount is genuinely encouraging.”

  • do you require a small further money to qualify for that mortgage

    Gen X is beforehand looking for for housing correct for rising outdated in put

    By Didier Malagies
    •
    10 Apr, 2024

    Toddler boomers are exhibiting an irritating need to age in put of their have households, however their younger kids — principally prospects of Technology X — are additionally creating their desires felt by looking for out homes that can accommodate their necessities as they get extra mature, in accordance to a current report from the New York Occasions. Citing 2021 information from the Harvard College Joint Center for Housing Experiments that confirmed 88% of grown ups 65 and extra mature are getting older in spot, a lot of associates of the next know-how — principally born in between the mid-Sixties and early-Eighties — are actually taking proactive steps to by considering “about precisely the place they’ll dwell of their 70s, 80s and even 90s,” the Periods famous. Homebuilders are observing a rise in demand for properties that can accommodate pure rising older from Gen X shoppers. David O’Reilly, CEO of Howard Hughes Holdings which constructs ready communities, describes the sector being “on the cusp,” indicating that the will appears to be coinciding with further members of Gen X nearing a time by which they’ll prove to be “empty nesters.” “That’s typically the tipping place,” O’Reilly knowledgeable the Occasions. Gen X potential consumers are additionally extra probably to have a lot extra financial signifies and regulate round their possible options, and are preserving entry to crucial later on-lifetime options in head when choosing out the place by to reside as they become older, the story described. “In new developments, [Gen X buyers] are looking for entry to nicely being and wellness facilities, like mountaineering trails and tennis courts, in addition to opting for home attributes like showers instead of bathtubs, for event, and asking for the most recent units to assist them as they age,” the reporting stated. A report launched remaining 7 days by the Countrywide Association of Realtors (NAR) acknowledged that Gen X homebuyers have a median earnings of $126,900, and are nevertheless a number of years away from retirement. That supplemental doing work time will permit for them to amass much more prosperity in accordance to Jessica Lautz, deputy chief economist and vice chairman of exploration at NAR. Customers of Gen X are additionally benefiting from the pandemic and post-pandemic operate-up in home prices, carrying significantly far more dwelling equity than their millennial counterparts and dwarfing millennial homeownership charges 72% to 55% as of 2023. 1 analyst stated that Gen X potential consumers are impressed to act now for aging-proper housing due to the situation of the housing market place.  “If they’re buying for households, supplied the tightness of the present market and distant function, I do take into account you see extra Gen X-ers observing a residence purchase as a residence for the remainder of their lives,” talked about Cristian deRitis, deputy essential economist at Moody’s Analytics to the Moments.

  • How the Federal Reserve’s up coming go impacts your money

    Economists assume the Federal Reserve to go away curiosity prices unchanged at the conclude of its two-working day assembly this week, even despite the fact that loads of specialists anticipate the central lender is preparing to begin out chopping premiums in the months ahead.

    In organized remarks earlier this month, Federal Reserve Chair Jerome Powell stated policymakers actually do not wish to simplicity up too swiftly.

    Powell noticed that decreasing premiums quickly threats shedding the battle in opposition to inflation and certain having to raise charges additional, while prepared far too extended poses danger to financial progress.

    But in the meantime, people is not going to possible see considerably aid from sky-high borrowing prices.

    Much extra from Individual Finance:
    Here’s when the Fed is possible to begin slicing curiosity premiums
    Just about 50 % of youthful grown ups have ‘money dysmorphia’
    Deflation: Here’s the place promoting costs fell

    In 2022 and the initially fifty % of 2023, the Fed raised prices 11 occasions, leading to shopper borrowing charges to skyrocket though inflation remained elevated, and placing properties beneath stress.

    With the mixture of sustained inflation and elevated curiosity fees, “a number of consumers are experiencing higher quantities of financial nervousness when in comparison with only one yr in the previous,” talked about Silvio Tavares, CEO of credit score historical past scoring firm VantageScore.

    The federal money quantity, which is established by the U.S. central financial institution, is the want value at which banks borrow and lend to 1 explicit yet one more straight away. Whilst which isn’t the value consumers fork out, the Fed’s strikes nonetheless have an effect on the borrowing and monetary financial savings charges they see every day.

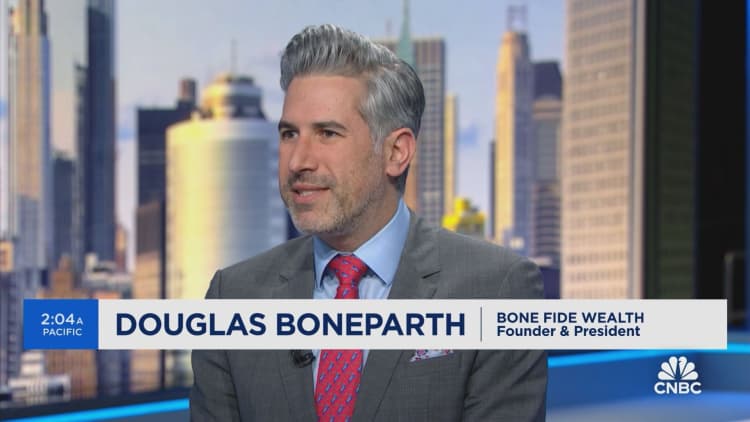
    Higher for longer may actually be a good thing, says Douglas Boneparth

    Even when the central monetary establishment does decrease charges — which some now hope might transpire in June — the velocity that they trim is prone to be significantly slower than the tempo at which they hiked, in accordance to Greg McBride, predominant economical analyst at Bankrate.

    “Curiosity prices took the elevator possible up they will simply take the stairs coming down,” he reported.

    Here’s a breakdown of precisely the place shopper costs stand now and the place they could presumably be headed:

    Credit playing cards

    Because most bank cards have a variable value, you’ll find a fast hyperlink to the Fed’s benchmark. Due to the truth of the central financial institution’s fee hike cycle, the common credit score rating card degree rose from 16.34% in March 2022 to roughly 21% at the moment — an all-time important.

    With most individuals feeling strained by higher value ranges, balances are increased and rather more cardholders are carrying monetary debt from thirty day interval to thirty day interval as compared with final yr.

    Annual proportion charges will start to return down when the Fed cuts prices, however even then they’ll solely relieve off actually giant phases. With solely a handful of potential quarter-issue cuts on deck, APRs would nonetheless be all-around 20% by the conclusion of 2024, McBride reported.

    “If the Fed cuts charges twice by 1 / 4 degree, your credit standing card payment will slide by 50 % a %,” he reported.

    Mortgage fees

    Fifteen- and 30-yr mortgage mortgage prices are mounted, and tied to Treasury yields and the total financial system. But anybody searching for a brand new residence has misplaced sizeable buying electrical energy, partly merely due to inflation and the Fed’s plan strikes.

    Premiums are already drastically reduce since hitting 8% in Oct. Now, the widespread fee for a 30-year, set-fee mortgage is about 7%, up from 4.4% when the Fed began boosting premiums in March 2022 and three.27% at the end of 2021, in keeping with Bankrate.

    “Despite the current dip, home mortgage prices keep superior as the market contends with the stress of sticky inflation,” defined Sam Khater, Freddie Mac’s predominant economist. “In this environment, there’s a superior chance that charges will stay increased for a for an extended interval interval of time.”

    Adjustable-rate dwelling loans, or ARMs, and dwelling fairness traces of credit score historical past, or HELOCs, are pegged to the key quantity, and people folks charges stay important.

    “The truth of it’s, loads of debtors are shelling out double-digit want prices on folks proper now,” McBride claimed. “That shouldn’t be a cheaper price of borrowing and that is not heading to switch.”

    Automobile loans

    Even although auto loans are mounted, funds are acquiring greater just because motorized vehicle costs have been growing along with the curiosity charges on new loans, leading to a lot much less inexpensive month-to-month funds. 

    The regular quantity on a 5-yr new vehicle financial institution mortgage is now rather more than 7%, up from 4% when the Fed began elevating costs, in accordance to Edmunds. Nonetheless, degree of competitors amongst lenders and rather more incentives in the market have began out to amass a few of the edge off the cost of getting a automobile at the moment, stated Ivan Drury, Edmunds’ director of insights.

    At the time the Fed cuts costs, “that provides individuals a bit of way more respiratory space,” Drury reported. “Final calendar yr was unattractive all near. At least there may be an upside this 12 months.”

    Federal scholar monetary loans

    Federal college scholar private mortgage charges are additionally mounted, so most debtors usually are not rapidly affected by the Fed’s strikes. But undergraduate college students who select out new direct federal scholar loans are actually spending 5.50% — up from 4.99% in the 2022-23 educational calendar yr and three.73% in 2021-22.

    Non-public scholar loans are likely to have a variable value tied to the prime, Treasury invoice or one other payment index, which suggests people debtors are by now spending extra in fascination. How significantly much more, nonetheless, differs with the benchmark.

    For folks combating present debt, there are means federal debtors can reduce their load, together with income-based choices with $ month-to-month funds and financial hardship and unemployment deferments. 

    Personal private mortgage debtors have fewer options for aid — regardless of the undeniable fact that some might ponder refinancing at the time costs get began to look down, and all these with higher credit score historical past might already qualify for a lower degree.

    Discounts prices

    Though the central monetary establishment has no direct affect on deposit prices, the yields are typically correlated to enhancements in the consider federal money value.

    As a consequence, prime-yielding on the web value financial savings account costs have designed important strikes and are actually paying out excess of 5% — earlier talked about the quantity of inflation, which is a scarce earn for any particular person creating up an disaster value financial savings account, McBride reported.

    Since folks fees have possible maxed out, that is the time to lock in certificates of deposit, significantly maturities for an extended interval than one explicit yr, he advised. “There’s no incentive to take care of out for one thing higher for the purpose that that’s not the approach the wind is blowing.”

    Currently, one-year CDs are averaging 1.73%, however best-yielding CD charges pay about 5%, as superior as or superior than a high-generate val
    ue financial savings account.

    Really don’t miss these exclusives from CNBC Professional

  • 5 Approaches to Decrease Taxready Earnings and Hold Extra Money in Your Pocket

    The ongoing superior price of residing has fairly just a few Australians searching for methods to maintain more money in their possess pockets and shell out lots much less at tax time. As tax time methods, there’s no improved time to uncover fiscal methods that would assist scale back tax liabilities. By leveraging these cash tools and savvy methods, it’s attainable to enable you to save money while nonetheless being compliant with Australian tax pointers. Browse on as we share six efficient procedures to receive this intention.

    2-Feb-13-2024-12-41-08-5133-AM

    1. Use Salary Sacrificing

    Wage sacrificing permits taxpayers to divert part of their pre-tax wage in the course of positive constructive points. The hottest earnings sacrifice advantages are superannuation contributions, motor vehicles, and digital tools. Income sacrificing could be utilised to spend for a brand new automobile, laptop computer, protection, lease funds, house finance mortgage funds, or different positive aspects, whereas saving numerous numbers of kilos in taxes yearly. Many employers provide wage sacrificing preparations, so it is actually value testing this various together with your HR division or monetary adviser.

    2. Continue to maintain Correct Tax and Financial Records

    About the sooner few yrs, the ATO has tightened up on scrutiny, in distinctive in the locations of report-maintaining, income and deductions, which is why conserving meticulous data of income, prices, and investments is so vital when it comes to optimising tax deductions. Use digital assets and apps to streamline document-keeping and give your self sufficient time to do the job because of your tax return to avoid speeding and producing errors. By being organised and retaining maintain observe of of deductible prices, you possibly can maximise your tax deductions and lower your taxable cash.

    3. Assert ALL Deductions

    Verify that you just is perhaps saying all eligible deductions that make the most of to your situation. If you make investments any cash related to incomes an earnings, expense houses, instruction or scientific prices, you’ll need to assert it. Be assured to maintain receipts and documentation to again again-up your claims in state of affairs of an audit and search the recommendation of with a professional tax specialist who can assist you determine any deductions you might maybe have missed in buy to get essentially the most out of your tax return.

    4. Add to Your Tremendous to Save Tax in Australia

    Building supplemental contributions to your superannuation fund could be a tax-successful approach to increase your retirement financial savings and lower down taxable cash. (*5*) great contributions, these sorts of as wage sacrifice or specific deductible contributions, are taxed at a decreased worth inside simply the great fund – a charge of simply 15 for each cent – in comparability to the marginal tax charge which might be as excessive as 49 for each cent!

    5. Minimise Expenses with a Mortgage Offset Account

    A house finance mortgage offset account could be a efficient software for lowering taxable earnings whereas saving on mortgage mortgage need funds. By depositing worth financial savings or getting your earnings compensated into a particular offset account related to your residence mortgage, you possibly can offset the curiosity charged in your mortgage steadiness. Not solely does this decrease the sum of curiosity payable in your property financial institution mortgage, however it could additionally speed up your route to receiving debt-absolutely free.

    6. Get Private Well being Insurance insurance policies

    Investing in private wellness insurance coverage insurance policies offers vital healthcare safety and can supply some tax rewards additionally. Devoid of personal clinic insurance coverage plan, for those who’re solitary and achieve much more than $90k for each yr, or you’re a family incomes much more than $180k a 12 months, you’ll pay again a minimal quantity a single for every cent Medicare Levy Surcharge on main of the required two per cent Medicare Levy that the majority taxpayers have to pay. Basic non-public well being care methods can cost lots lower than the only one for every cent Levy Surcharge on gross earnings, so for some males and ladies, discovering private effectively being insurance coverage could make good fiscal sense.

    Maximising Discounts to Access Fiscal Plans

    No 1 would love to fork out much more tax than they’ve to, which is why it’s so important to perceive the vital methods for maximising reductions and lessening taxable earnings. By making use of these 6 strategies, it’s possible to correctly minimise the sum of tax you’re essential to shell out, income which may go into your again once more pocket in its place!

    For extra fiscal data tailor-made to your one among a sort scenario, get in contact with the group at Home mortgage Specific.

    While all therapy has been taken in the getting ready of this publication, no guarantee is specified as to the precision of the data and no obligation is taken by Finservice Pty Ltd (House mortgage Categorical) for any glitches or omissions. This publication doesn’t represent personalised economical ideas. It won’t be related to private circumstances. Absolutely nothing in this publication is, or ought to actually be taken as, a suggestion, invitation, or advice to buy, promote, or maintain any monetary dedication in or make any deposit with any specific individual. You ought to search certified steering prior to taking any movement in relation to the issues dealt in simply this publication. A Disclosure Assertion is obtainable on ask for and no price of cost.

    Finservice Pty Ltd (Property finance mortgage Categorical) is authorised as an organization credit standing guide (Corporate Credit historical past Representative Amount 397386) to engage in credit score rating actions on behalf of BLSSA Pty Ltd (Australian Credit Licence quantity 391237) ACN 123 600 000 | Complete member of MFAA | Member of Australian Financial Problems Authority (AFCA) | Member of Option Aggregation Providers.