Tag: money

  • Best money moves to make ahead of a Fed rate cut

    Fed Chair Powell is focused again on achieving a soft landing, says WSJ's Nick Timiraos

    Recent indicators that inflation is easing has paved the way in which for the Federal Reserve to begin chopping rates of interest as quickly as this fall.

    The shopper worth index, a key inflation gauge, dipped in June for the primary time in additional than 4 years, the Labor Department reported final week.

    “With plentiful indicators of a cooling financial system, the patron worth index for June definitely constitutes the ‘extra good knowledge’ on inflation that Fed Chair Jerome Powell has stated we want to see earlier than the Fed can start chopping rates of interest,” stated Greg McBride, chief monetary analyst at Bankrate.com.

    With a fall rate cut trying extra doubtless now, households could lastly get some aid from the sky-high borrowing prices that adopted the newest sequence of curiosity rate hikes, which took the Fed’s benchmark rate to the best degree in a long time.

    More from Personal Finance:
    High inflation is basically not Biden’s or Trump’s fault, economists say
    Why housing inflation remains to be stubbornly excessive
    More Americans are struggling at the same time as inflation cools

    Fed officers signaled they count on to cut its benchmark rate as soon as in 2024 and 4 further occasions in 2025.

    The federal funds rate, which is about by the U.S. central financial institution, is the curiosity rate at which banks borrow and lend to each other in a single day. Although that is not the rate shoppers pay, the Fed’s moves nonetheless have an effect on the charges they see every single day on issues resembling personal pupil loans and bank cards.

    “If you might be a shopper, now’s the time to say, what does my spending appear to be? Where would my money develop essentially the most and what choices do I’ve?” stated Leslie Tayne, an lawyer specializing in debt aid at Tayne Law in New York and creator of “Life & Debt.”

    Here are three key methods to contemplate:

    1. Watch your variable-rate debt

    With a rate cut, the prime rate lowers, too, and the rates of interest on variable-rate debt — resembling bank cards, adjustable-rate mortgages and a few personal pupil loans — are doubtless to observe, lowering your month-to-month funds.

    For instance, credit score cardholders may see a discount of their annual proportion yield, or APR, inside a billing cycle or two. But even then, APRs will solely ease off extraordinarily excessive ranges.

    Rather than look ahead to a small adjustment within the months ahead, debtors may swap now to a zero-interest stability switch bank card or consolidate and repay high-interest bank cards with a private mortgage, Tayne stated.

    Olga Rolenko | Moment | Getty Images

    Many householders with ARMs, that are pegged to a selection of indexes such because the prime rate, Libor or the eleventh District Cost of Funds, might even see their curiosity rate go down as properly — though not instantly as ARMs usually reset simply as soon as a yr.

    In the meantime, there are fewer choices to present householders with further respiratory room. “Your higher transfer could also be ready to refinance,” McBride stated.

    Private pupil loans additionally have a tendency to have a variable rate tied to the prime, Treasury invoice or one other rate index, which suggests as soon as the Fed begins chopping rates of interest, the rates of interest on these personal pupil loans will begin dropping.

    Eventually, debtors with current variable-rate personal pupil loans may additionally have the opportunity to refinance into a cheaper fixed-rate mortgage, in accordance to larger training skilled Mark Kantrowitz. 

    Currently, the fastened charges on a personal refinance are as little as 5% and as excessive as 11%, Kantrowitz stated.

    2. Lock in financial savings charges

    While borrowing will turn into cheaper, these decrease rates of interest will harm savers. 

    Since charges on on-line financial savings accounts, money market accounts and certificates of deposit are all poised to go down, specialists say that is the time to lock in some of the best returns in a long time.

    For now, top-yielding on-line financial savings accounts and one-year CDs are paying greater than 5% — properly above the rate of inflation.

    The alternative to earn 5% yearly on these money investments could not final for much longer.

    Howard Hook

    wealth advisor with EKS Associates

    “One factor it’s your decision to do is contemplate investing any idle money you will have into a higher-yielding money market fund,” stated licensed monetary planner Howard Hook, a senior wealth advisor with EKS Associates in Princeton, New Jersey.

    “Money market brokerage accounts normally pay larger charges than money market or financial savings accounts at banks,” he stated in an emailed assertion. “If the Fed is certainly trying to scale back charges 5 occasions over the following eighteen months (as at present projected), then the chance to earn 5% yearly on these money investments could not final for much longer.”

    3. Put off massive purchases

    If you are planning a main buy, like a residence or automobile, then it might pay to wait, since decrease rates of interest may scale back the fee of financing down the street.

    “Timing your buy to coincide with decrease charges can save money over the life of the mortgage,” Tayne stated.

    Although mortgage charges are fastened and tied to Treasury yields and the financial system, they’ve already began to come down from latest highs, largely due to the prospect of a Fed-induced financial slowdown. The common rate for a 30-year, fixed-rate mortgage is now simply above 7%, in accordance to Bankrate.

    However, decrease mortgage charges may additionally increase home-buying demand, which might push costs larger, McBride stated. “If decrease mortgage charges lead to a surge in costs, that is going to offset the affordability profit for would-be patrons.”

    When it comes to auto loans, there isn’t any query inflation has hit financing prices — and car costs — onerous. The common rate on a five-year new automobile mortgage is now practically 8%, in accordance to Bankrate.

    But on this case, “the financing is one variable, and it is frankly one of the smaller variables,” McBride stated. For instance, a quarter-percentage level discount in charges on a $35,000, five-year mortgage is $4 a month, he calculated.

    In this case, and in lots of different conditions as properly, shoppers would profit extra from bettering their credit score scores, which may pave the way in which to even higher mortgage phrases, McBride stated.

    Subscribe to CNBC on YouTube.

  • Pepper Money streamlines second charge application process – Mortgage Strategy

    Pepper Money has launched introducing a paperless application journey for second charge mortgages.

    The adjustments are a response to suggestions from clients and companions, serving to to streamline the process for a smoother application expertise.

    Customers have been beforehand required to print, full, signal, and return an Application Form and I&E upon submission which created delays within the application journey.

    To velocity issues up and make issues easier for patrons, Pepper have changed the application type and earnings and expenditure type with a brand new application abstract and application declaration with clients not required to signal and return any paperwork prior to supply.

    E-signatures 

    These enhancements observe on from the latest introductions of e-signatures at provide stage and payout earlier than consent.

    Commenting on the adjustments Pepper Money second charge gross sales director Ryan McGrath mentioned:

    “These enhancements are designed to make the process as easy and stress-free as potential. By decreasing the quantity of paperwork and automating key steps, we will present a extra environment friendly and user-friendly expertise.

    He added: “For brokers, upon getting accomplished the web application, there’s nothing so that you can do. After an preliminary cellphone name, so long as we maintain your clients’ e-mail addresses and phone numbers, they’ll routinely be despatched every little thing they want securely through DocuSign.

  • Pepper Money to administer Victoria’s new Changeover Financial loan Application

    Pepper Dollars to administer Victoria’s new Changeover Loan Application | Australian Broker News

    Information

    Pepper Income to administer Victoria’s new Transition Loan Software

    Stamp obligation scrapped: Victoria’s industrial and industrial property tax reform will take outcome

    Pepper Money to administer Victoria’s new Transition Loan Program

    Pepper Money been appointed to administer the new skilled and industrial house tax (CIPT) Changeover Loan Application along side Treasury Corporation of Victoria (TCV).

    This technique is developed to help Victorian firms with the tax reform actions which have taken affect from as of late as stamp accountability is little by little stamped out on industrial and industrial properties within the level out. 

    Pepper Income has been engaged by TCV to help with the administration of this new Changeover Financial loan Plan.

    “We are comfortable to be entrusted with this kind of an integral place within the administration of the new skilled and industrial property tax reform Changeover Personal loan Plan,” acknowledged Mario Rehayem (pictured earlier talked about), CEO of Pepper Cash.

    What is the new skilled and industrial home tax?

    In the 2023–24 Condition Budget, the Victorian govt introduced that land switch accountability (stamp obligation) on industrial and industrial home shall be abolished and altered with the skilled and industrial property tax (CIPT).

    This tax will apply 10 years proper after the property is future marketed.

     The reform will give potential purchasers {of professional} and industrial qualities the short-term resolution to spend stamp obligation on a home upfront (as for each present common) or make the most of to borrow the cash through the use of a authorities transition private loan.

    The changeover mortgage will permit purchasers to make annual monetary loan repayments round 10 yrs, equal to the property’s final stamp obligation obligation as well as fascination permitting them to unfold out funds about time with a hard and fast, market-based curiosity charge, calculated on the get began of the monetary loan.

    In a new interview with Australian Broker, Ragany walked by means of the situations.

    Specific information on the transition loan like how to make the most of, monetary loan phrases and eligibility and will be discovered on TCV’s net web page.

    How Pepper Dollars will help administer the CIPT Changeover Loan Application

    Pepper Revenue has been engaged by TCV to assist with administering this new Transition Loan Software.

    Rehayem reported that not solely is that this a promising protection for Victorian SMEs, however “our involvement accurately aligns with Pepper Money’s ongoing motivation within the path of supporting people succeed”.

    “We are leveraging our experience in credit standing and monetary loan servicing, along with our in-home objective-developed technological know-how to put into motion the applying,” Rehayem stated.

    “This will include private loan establishment, credit score rating evaluation, settlement, and ongoing servicing of the transition monetary loans, as very properly as administration providers for TCV.”

    Pepper Revenue talked about the availability of a “frictionless shopper expertise” during credit score decisioning and settlement was a foremost worth proposition accessible by the non-financial establishment loan firm.

    TCV changeover mortgage candidates can have entry to the end-to-stop digital utility information that may be executed at their ease at any time of the day or evening.

    “This know-how shall be integral to the TCV Transition Loan Software, leveraging Pepper Money’s experience in each of these creating and sustaining digital platforms,” Rehayem defined.

    “Approved candidates shall be managed working with Pepper Money’s intent-constructed know-how options {and professional} shopper service teams.”

    Why it’s important for brokers to get all through the CIPT reforms

    Pepper Money has complete experience and progressive capabilities in third bash servicing with about 30 third get collectively originators who use Pepper Money to facilitate their branded private loan portfolio.

    Michael Larkin, CEO of TCV reported, “We are extremely excited to be performing with Pepper Cash to produce the Changeover Loan Plan to assist revenue Victorian companies.”

    Rehayem included, “We welcome and assist the reform which aligns to our mission of aiding of us to succeed, the changeover financial institution loan spreads funds out round 10 yrs to assist Victorian organizations take care of money movement.

    “The private loan now presents certified organizations elevated risk to commit, enhance and enhance. The funds could possibly be invested in rising operations faster, using far more employees, or just assuaging a number of the pressures corporations are in the meanwhile going by means of.”

    Rehayem reported the CIPT reform is a necessary rework to Victoria’s tax process and sector practitioners actually needs to be properly ready to help their Victorian dependent SME clients.

    “It’s essential for finance specialists which embody brokers, accountants, monetary planners, conveyancers, and solicitors to absolutely grasp the new reform and find a way of articulating the choices with their purchasers.”

    Relevant Stories

    Retain up with probably the most up-to-date information and features

    Join our mailing itemizing, it’s no price!

  • Chetwood Money appoints Morris as distribution director – Mortgage loan Finance Gazette

    Chetwood Money has employed Roger Morris as its group distribution director.

    Roger-Morris97-620x330.jpg

    The discipline veteran joins Chetwood Fiscal upfront of its begin of make investments in-to-allow monetary establishment ModaMortgages and subsequent the digital financial institution’s acquisition of CHL Home loans for Intermediaries for an undisclosed price final month.

    Morris might be accountable for distribution, concentrating on CHL Mortgages for Intermediaries’ networks and property finance loan golf gear to start with. He has labored in the home marketplace for further than 30 a few years.

    Chetwood Money states: “His talents in financial corporations distribution will show a will need to have as the lenders appear to make on their presence within the specialist lending space.

    “Morris’ substantial know-how of the sector can even see him delivering educational assist and workshops to brokers about numerous sectors of the trade.

    “He has constructed a status across the many years as an influential and sought-following speaker in regards to the BTL discipline.

    Morris labored for Tandem Lender as its director of mortgage loan division income & distribution and has held senior posts at Precise Home loans and different collectors.

    Chetwood Money founder and important authorities Andy Mielczarek claims: “It’s a genuine coup for us to get one other individual of Roger’s pedigree and undoubted calibre on board.

    “As a really well-recognized temperament within the trade, his electrical energy, enthusiasm and enthusiasm for cash knowledgeable providers will assist us take into account the upcoming step of our journey as we glimpse to construct the 2 fashions as prime BTL collectors.”

    Morris provides: “There is a superb likelihood to determine CHL Mortgages for Intermediaries and ModaMortgages into main skilled lenders that give you propositions made throughout dwelling loan brokers and with coaching at their fairly coronary coronary heart.”

  • Inflation surge lifts possibilities of money fee boost

     The RBA reported the trail of need charges that may most interesting make sure that inflation returned to concentrate on in a acceptable timeframe stays not sure and “the Board shouldn’t be ruling something in any respect in or out”.

    The future RBA board assembly to make your thoughts up the money fee is on August 6, by which period the quarterly CPI inflation figures for June may have been launched.

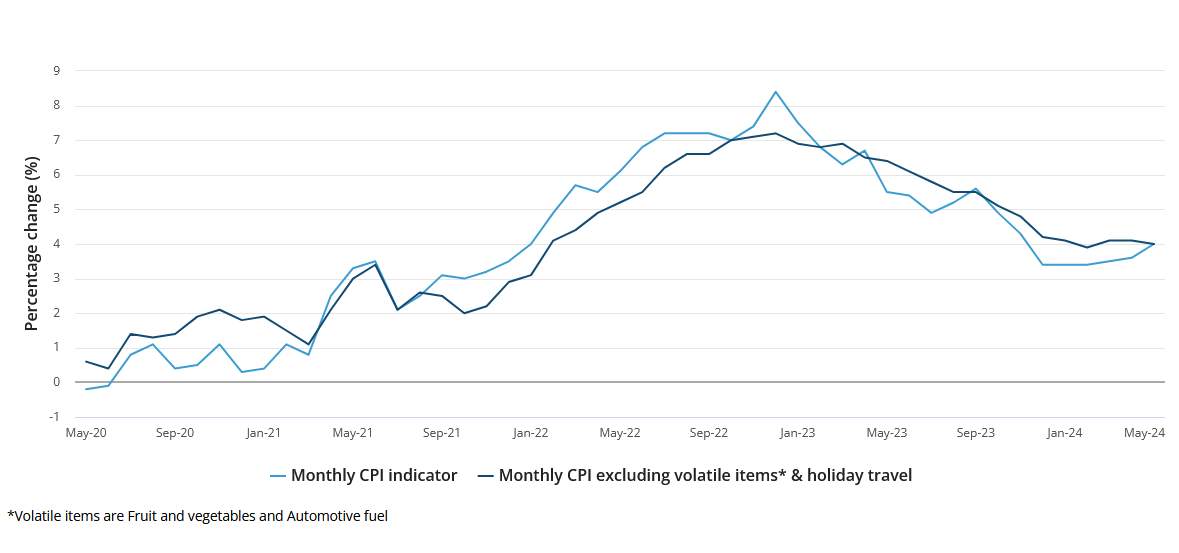
    Talking concerning the May maybe CPI inflation figures, Ab muscular tissues head of price ticket statistics Michelle Marquardt (pictured above) talked about inflation was usually influenced by merchandise with unstable charge modifications corresponding to automotive gas, fruit and greens, and vacation journey.

    “It could be precious to exclude this stuff from the headline CPI to produce a view of underlying inflation, which was 4% in Could, down from 4.1% in April,” Marquardt claimed.

    All teams month-to-month CPI indicator, once-a-year movement (%)Resource: Stomach muscular tissues May presumably 2024 CPI Indicator

  • Karen Rodrigues, head of gross gross sales, Marketplace Money Answers – Home loan Approach

    Karen RodriguesCan you give us an outline of your vocation?

    I started my occupation in financial suppliers with Halifax, earlier than transferring to OneSavings Financial establishment, wherein I used to be a national account supervisor on each equally the Kent Reliance and the Prestige Finance producers.

    I’ve additionally held positions at Aldermore Mortgages, GE Dollars and Kensington. I then labored as company earnings supervisor at Vida Homeloans for 4 a few years, simply earlier than becoming a member of ULS Technology (now Smoove) as director of product gross sales of the eConveyancer model title in April 2020.

    It’s heartening to see a growing existence of gals at discipline gatherings

    This prosperity of experience implies I understand the assist stipulations of networks, golf equipment, packagers and home loan brokers inside and outside.

    What does your function glimpse like on a day-to-day foundation?

    I’m delighted to say that no two occasions are at any time the very same.

    This encompasses each factor from webhosting a income-crew meeting on Monday early morning to inside conferences, group testimonials, problem resolving and structuring situations with the employees, right by manner of to liaising with our improbable underwriters and intermediaries to research extra strategies wherein MFS can assist.

    I additionally carry out rigorously with my regional supervisor for London, head of nationwide accounts, crucial account supervisor and senior firm progress authorities to ensure that, as a group, we’re taking acquire of each prospect.

    Getting labored in conveyancing for 3 many years, I consider a big quantity of modify is important within the homebuying strategy

    A highlight of my working day is speaking to our intermediaries and getting out how the market place is modifying with each single passing day.

    What has been the best impediment of your occupation, and a emphasize?

    I confronted my most vital difficulties at Kensington, purely due to the character of the enterprise.

    It was the to start out with sub-prime lender within the United kingdom, so there had been a ton of doorways closing for the period of my time there. Intermediaries would recommend that none of their purchasers had antagonistic circumstances, however they’d then get once more in contact a handful of days later expressing that they did in easy reality will want help with a novel shopper.

    Gender equality is a major manner of driving innovation and progress in our market

    These have been often complicated circumstances, however I savored being outfitted to part in and information anytime doable.

    Signing up for MFS has been a critical emphasize. It is been improbable to get the job finished with [chief mortgage officer] Mike Cook dinner, and the enterprise has magnificent development designs. I’m delighted to be a aspect of that journey.

    Is there absolutely anything you’d change concerning the dwelling finance loan sector?

    Owning labored in conveyancing for just a few years, I consider {that a} ton of change is required within the homebuying course of. With that in ideas, hats off to Kate Faulkner, Maria Harris and co for pushing this forward by means of the Dwelling Shopping for & Providing Group. It was nice to see them in motion on the Levelling Up pick committee convention in mid-May.

    A spotlight of my day is speaking to our intermediaries and getting out how the market is altering with each passing working day

    On the property finance loan entrance, we might do further to leverage the data and details gathered by brokers all by way of the preliminary factfinding part, these as identification and proof of dwelling. We can then be sure that this documentation is utilised by all occasions involved within the strategy, to complement effectivity.

    On the opposite hand, I recognise that using these sorts of a course of would attainable contain regulatory changes.

    Do you actually really feel the sector is shut to buying gender equality?

    Tons of progress has been made in fashionable a few years, however there’s typically space for enchancment. It’s heartening to see a rising presence of girls at market occasions.

    Gender equality is a major manner of driving innovation and growth inside our market, and I hope we will keep on to foster inclusivity.

    If you didn’t work in finance, what different career would fascination you?

    I’d have cherished to be an astronaut, however that was a tad unrealistic after I was creating up within the Nineteen Eighties.

    We might do extra to leverage the small print gathered by brokers for the period of the unique factfinding part

    Amazingly, or not for all those that know me, I used to be going to be a secondary faculty teacher! I’ve type of obtained that half as I’m a succesful Irish dancing trainer, and I had my very personal dance faculty for a quantity of yrs. I’ve additionally been a school governor for 15 a very long time.

    What’s the perfect suggestions you may have obtained?

    From my mum, I noticed the timeless recommendation: “Always have on clear up, matching underwear — you by no means know what might occur!”

    It is a humorous reminder of the worth of at present being ready for the unanticipated.

    Company profile

    12 months arrange: 2006

    Headcount: 135

    Address: 46 Hertford Street, Mayfair, London W1J 7DP

    Web web site: www.mfsuk.com/

    Started in 2006 by CEO Paresh Raja, Industry Money Answers (MFS) is an unbiased bridging finance service supplier. Initially concentrating on offering bridging monetary loans, MFS has contemplating that expanded to provide professional obtain-to-let mortgages as correctly.

    MFS is a member of the Countrywide Affiliation of Business Finance Brokers, the Affiliation of Short Term Loan suppliers and the Economical Middleman & Broker Affiliation.

    This article featured within the June 2024 model of Home finance loan Strategy.

    If you wish to subscribe to the common month-to-month print or digital journal, please click on right here.

  • Remark: London – a money expenditure – Property finance loan Strategy

    Alpa-Bhakta-BML-2022London is famend globally as a location for home merchants.
    A 3rd (33%) of excessive-internet-value people (HNWIs) from the Gulf Cooperation Council (GCC) location invested in London property earlier yr, in keeping with Al Rayan Financial establishment — way over every other vital world-large sector.

    Usually, HNWIs gravitate in the direction of the heartland of the prime central London (PCL) business when looking for a residence monetary dedication, encompassing boroughs these because the City of London, Kensington & Chelsea and the Town of Westminster. This is hardly a shock these areas are identified for his or her excessive-class properties, to not point out their historic significance, inexperienced areas, good schools and cultural vibrancy.

    From an monetary dedication place of take a look at, these areas are even now positioned in central London, which implies they nonetheless love a lot of of the same advantages

    But our information of the important thing residence business is shifting, and brokers working with HNWIs will need to select observe of patrons’ evolving preferences.

    There are components of central London, outdoor what we often take into account to be PCL, which are progressively enduring important want from merchants and wealthy purchasers, along with Camden, Notting Hill, Shoreditch and South Financial establishment. It is basically value taking a look at what’s driving want in these neighbourhoods, and what the implications could be for loan suppliers and brokers.

    Generational change

    Very first, notable city regeneration initiatives have taken spot in these London enclaves over newest a few years. This has boosted their desirability, as successfully as amplified the quantity of properties obtainable, though every has taken care of its distinctive character and allure.

    Consequently, we now have witnessed a generational change as youthful, prosperous prospects resolve for these a lot much less often interesting components of the metropolis. Individuals who’ve used time in these components of London will acknowledge why: the cultural, culinary and leisure alternatives are growing noticeably.

    Brokers symbolizing HNW customers have to contemplate take observe, being conversant in that their clientele could maybe properly uncover fewer standard hotspots in regards to the funds

    In the meantime, with a mixture of historic, put up-industrial and current-day structure, there may be a broad number of home by which the brand new period can dedicate.

    Finally, from an expense challenge of watch, these areas are even now present in central London, which signifies they even now get pleasure from a number of of the same rewards that the widespread postcodes of the PCL sector do. In reality, owing to their web site, standing, glorious and wish among the many home and world potential patrons, they’ve equal attainable for funds enlargement and resilience.

    For homebuyers and merchants, equally home and world, these non-conventional PCL components incorporate a prosperity of prospects, with details displaying that they’ve outperformed the remainder of the Uk in newest many years.

    Notting Hill is a single of London’s most fascinating components. With vibrant homes, a well-known present market and film star folks, its property values have skilled a huge enhance, of 101%, up to now 10 yrs, in accordance to particulars from Kinleigh Folkard and Hayward, climbing by 11% in 2023 by yourself — this at a time when typical British isles promoting costs have been in lower.

    With a mix of historic, submit-industrial and updated structure, there may be a intensive number of property by which the brand new era can commit

    Shoreditch has relished arguably essentially the most main transformation within the earlier ten years. Just one in 10 properties exchanges for in extra of £1m, although generally common costs have risen from £1.07m in 2013 to £1.38m in 2023.

    Equivalent traits may be witnessed within the rental market in Camden and Kentish City. JLL research that, involving 2011 and 2021, rental promoting costs for studios rose by 19%, with home rental worth ranges climbing by 9%. The group additionally forecasts a 25% product sales worth progress and a 17.6% rental enlargement involving 2022 and 2026, so the prospect of higher rental returns may present further choices for buyers.

    Obviously, these much less widespread spots are gaining attractiveness, and worth, due to their spot, facilities and character. They give a distinctive life-model from that of the widespread PCL spots, fascinating to a often youthful demographic although proceed to carrying the potential to ship strong funding determination returns.

    Our comprehension of the first belongings sector is shifting

    Are these spots difficult PCL postcodes? Or will we require to redefine ‘PCL’? I don’t imagine so.

    The distinctive, singular features of luxurious qualities in PCL postcodes prohibit direct comparisons. The likes of residences in Kensington & Chelsea have been wanted for hundreds of years, prolonged symbolizing the prime echelon of the belongings business, not simply within the British isles however globally.

    This enduring attraction of the PCL heartland shouldn’t be getting challenged by up-and-coming boroughs most of these as Notting Hill or Shoreditch. But brokers symbolizing HNW customers should purchase take observe, even so, information that their prospects could maybe properly examine a lot much less customary hotspots near the funds.

    Alpa Bhakta is predominant authorities of Butterfield Home loans

    This article highlighted within the April 2024 version of MS.

    If you wish to subscribe to the each month print or digital journal, be sure to click on right here.

  • Regular FTB requires £60k money to get on home ladder: Zoopla – Home finance loan System

    The frequent initially-time buyer (FTB) needs a home earnings of £60,600 to get on the home ladder, the equal of two regular Uk salaries, in accordance to evaluation by Zoopla.

    The evaluation is predicated on the frequent asking promoting costs of properties on the market on Zoopla, based on what FTBs are looking for to get.

    FTBs have to have to generate nearly £15,000 much more per yr, which represents a 32.6% improve, in distinction to 5 a number of years in the past, largely a final result of bigger charges.

    In addition, the evaluation positioned FTBs require to acquire £2,400 extra in contrast to one 12 months in the past to buy their initially home.

    This decide is larger than equally inflation and family worth enlargement.

    Examination reveals that the income wished to purchase is the least costly in northern England and Scotland, the place by the conventional FTB home necessities to obtain fewer than £40,000.

    Customers in London want to have the utmost earnings at £103,000 as an FTB.

    Zoopla senior property researcher Izabella Lubowiecka suggests: “The issues experiencing FTBs are usually not the same throughout the United kingdom. Accessibility to homeownership calls for reduce incomes in considerably of Wales, northern England and Scotland.”

    “The finest points are in southern England, primarily London the place by FTBs are at present shopping for cheaper properties than the typical in an work to try and improve affordability”.

  • Will UK mortgage rates go down in 2024?- Times Money Mentor

    Mortgage rates dropped in the second half of 2023, as inflation plummeted and the Bank of England stopped climbing base fee. However, mortgage rates have been unstable since then, regardless of falls in inflation.

    Mortgage rates climbed rapidly throughout summer season of 2023, with the common two-year fastened fee reaching 6.86% in July. However, they slumped in the next months as inflation slowed.

    Since then it’s been a uneven experience –   regardless of falling inflation and a relentless Bank of England base fee of 5.25%.

    But with the Bank of England now predicted to chop curiosity rates earlier than the top of summer season, and a few lenders dropping fixed-rate mortgages in response, is it time for mortgages to get cheaper once more?

    Sarah Coles, head of non-public finance at Hargreaves Lansdown, stated: “The fall in inflation may hold fastened mortgage rates transferring in the best path, as banks value in an rate of interest reduce in June or August.”

    This article covers:

    Read extra: Can’t pay your mortgage? Here’s what you are able to do

    Why did mortgage rates rise in February?

    At the beginning of January, huge lenders together with HSBC, Co-operative Bank and Virgin Money started aggressively slicing curiosity rates in order to draw new debtors and compete in a crowded market. Fixed mortgages had been slashed by as much as one share level. At one level, there have been fastened mortgage rates on provide under 4%.

    However, the common two-year fastened fee mortgage fee has climbed to five.91% at the beginning of May, from roughly 5.4% in January.

    “Lenders are shifting rates often to regulate to the truth that markets now anticipate that base fee could take longer to fall than had beforehand been hoped,” defined David Hollingworth, a mortgage dealer at L&C Mortgages.

    Read extra: The greatest mortgage rates right this moment

    Free Times article: Use your tax-free allowance earlier than the election


    The quantity of tax-free allowance you will get is at its highest since 2010 and individuals are dashing to make use of it earlier than the July common election. Learn extra

    Why have mortgage rates gone down since final summer season?

    Mortgage rates rose sharply throughout 2022 and the primary half of 2023, in response to the Bank of England climbing the bottom fee of curiosity from 0.1% to five.25% in a bid to deal with hovering inflation. You can discover out extra about how curiosity rates have an effect on inflation.

    However, inflation has fallen in the UK considerably over the previous 12 months, which has given banks and constructing societies extra confidence to lend cash to debtors at a less expensive value.

    Lenders pre-empt base fee strikes by the Bank of England by growing or reducing the value of their fixed-rate mortgage merchandise accordingly.

    With the Bank of England trying prefer it would possibly begin slicing curiosity rates in the summer season, it’s seemingly that mortgage lenders had priced in the opportunity of this determination.

    Several main lenders reduce fixed-rate offers in May, in anticipation of a decrease Bank of England base fee coming quickly,

    Banks are additionally conscious that prime mortgage rates have put folks off taking out mortgages. The variety of folks struggling to fulfill their repayments has additionally risen. While home costs are falling, they’re nonetheless £40,000 above pre-pandemic ranges on common. For banks to proceed to draw clients, they know that they’ll have to make cuts to mortgage rates.

    When a couple of high-street banks led the cost and began to slash mortgage rates in January, different lenders rushed to chop theirs, in order to compete in a crowded market. This means common mortgage rates may quickly fall to their lowest level since September 2022.

    Will mortgage rates go down extra?

    Most consultants imagine mortgage rates are resulting from go down additional, they’re simply undecided fairly when.

    If inflation continues to fall because it did all through 2023, business insiders are optimistic that common mortgage rates may fall under 5% once more in 2024.

    Sarah Coles from Hargreaves Lansdown stated: “We can’t anticipate seismic shifts, however there’s prone to be some motion in the path of 5%, because the market adjusts. It’s additionally a reduction for anybody who shifted to a variable fee deal, many who would have been anticipating a spring reduce on the level once they made the choice.”

    What are the most recent UK mortgage rates?

    On March 21, the common mortgage rates based on Moneyfacts had been:

    • Two-year fastened deal now stands at 5.91%
    • Five-year fastened deal now stands at 5.48%
    • Standard variable fee (SVR) is 8.18%

    Work out how a lot you’ll be able to overpay in your mortgage with this free software

    How have UK mortgage rates modified?

    During summer season of final 12 months, common mortgage rates jumped to their highest stage since August 2008, in the course of the monetary crash. The common two-year fastened fee again then was 6.94%.

    In the years that adopted the 2008 crash, the financial system stabilised, and curiosity rates dropped like a stone. In December 2021, the common two-year fastened mortgage fee was 2.34%. Many offers had been less expensive than this. Some lenders had been providing rates under 1% for individuals who had a considerable amount of fairness in their properties or patrons with a sizeable deposit.

    However, after inflation soared and the Bank of England began elevating curiosity rates, mortgage rates adopted go well with. After inflation fell considerably throughout 2023, they fell considerably. February 2024 noticed them inch upwards once more, because the inflation fee hadn’t fallen in a number of months.

    The present common five-year fee is now 5.48%, in comparison with 2.64% in December 2021.

    You can see how mortgage rates have modified since June in the desk under:

    Date Average 2-year fastened fee Average 5-year fastened fee
    16/06/2023 5.98% 5.62%
    23/06/2023 6.19% ↑ 5.83% ↑
    30/06/2023 6.39% ↑ 5.96% ↑
    07/07/2023 6.54% ↑ 6.04% ↑
    14/07/2023 6.78% ↑ 6.30% ↑
    19/07/2023 6.81% ↑ 6.33% ↑
    20/07/2023 6.79% ↓ 6.31% ↓
    26/07/2023 6.86% ↑ 6.36% ↑
    28/07/2023 6.81% ↓ 6.34% ↓
    01/08/2023 6.85% ↑ 6.37% ↑
    07/08/2023 6.84% ↓ 6.35% ↓
    17/08/2023 6.76% ↓ 6.25% ↓
    05/09/2023 6.67% ↓ 6.17% ↓
    13/09/2023 6.62% ↓ 6.11% ↓
    19/09/2023 6.66% ↑ 6.08% ↓
    28/09/2023 6.48% ↓ 5.98% ↓
    16/10/2023 6.36% ↓ 5.91% ↓
    9/11/2023 6.21% ↓ 5.80% ↓
    23/12/2023 5.95% ↓ 5.57% ↓
    22/1/2024 5.59% ↓ 5.22% ↓
    29/2/2024 5.75% ↑ 5.33% ↑
    15/4/2024 5.80% ↑ 5.39% ↑
    14/5/2024 5.91% ↑ 5.48% ↑
    Source: Moneyfacts

    Looking for a mortgage? Use this free mortgage software to see among the greatest offers

    Who can probably get an affordable mortgage?

    The least expensive offers are typically focused at current owners seeking to transfer or remortgage, and people with plenty of fairness or a giant deposit – often round 40% of the property’s worth.

    An unbiased mortgage dealer may aid you discover the most affordable offers in the marketplace in your monetary circumstances.

    Here are different components to contemplate:

    • The greater your deposit the decrease your mortgage fee (usually)
    • Five-year mortgage offers at the moment are inclined to have decrease rates than shorter time period offers
    • Some offers are solely accessible to debtors in England and Wales
    • Your credit score rating have to be in prime situation to safe a very good deal

    You would possibly wish to learn: Is now a very good time to remortgage?

    What is prone to be the most affordable mortgage for first-time patrons? 

    First-time patrons typically have smaller deposits of between 5% and 10% of the worth of the house.

    A small deposit would possibly imply you might be extra restricted in the variety of offers accessible to you. If you do discover a appropriate deal, the curiosity rates are prone to be increased than if you happen to had an even bigger deposit as a result of lenders will see you as riskier.

    We define the professionals and cons of small deposit mortgages.

    You additionally want to contemplate any mortgage charges connected to the product. Some offers cost upfront charges or exit prices, whereas others don’t.

    It is commonly the case that headline-grabbing low mortgage rates additionally include the very best charges, which might make a giant distinction to the general quantity you pay in your dwelling.

    Be conscious: it’s not assured you’ll qualify for an marketed mortgage deal. Lenders typically have strict standards for who’s eligible.

    To discover the perfect mortgage deal for you, try our mortgage comparability software*. This provides the perfect choices whether or not you’re a first-time purchaser, dwelling mover, buy-to-let landlord or seeking to remortgage.

    If you might be in search of assist to get on the property ladder, try our information for first-time patrons.

    Is it price talking to a mortgage dealer?

    It may be price talking to a mortgage dealer as they’ll have entry to a spread of offers throughout the market.

    Bear in thoughts that some banks reserve particular offers for his or her current clients, which might not be accessible to brokers. So you would possibly wish to converse to your financial institution or current lender.

    The excellent news is that you simply would possibly have the ability to safe a less expensive mortgage upon getting constructed up extra fairness in your house.

    Looking for a dealer? We checklist the perfect mortgage brokers

    Find mortgage offers with our greatest purchase software

    Times Money Mentor has teamed up with Koodoo Mortgage to create a mortgage comparability software. You can use it to benchmark the offers you will get — however in order for you recommendation, it is likely to be greatest to talk to a mortgage dealer.

    This is how the software works:

    • You can search and evaluate mortgage offers
    • It solely takes a few minutes and no private particulars are required to look
    • Once you’ve obtained your consequence, you’ll be able to converse to a mortgage dealer if you happen to want recommendation

    Product data is supplied on a non-advised foundation. This signifies that no recommendation is given or implied and you might be solely accountable for deciding whether or not the product is appropriate in your wants.

    *All merchandise, manufacturers or properties talked about in this text are chosen by our writers and editors based mostly on first-hand expertise or buyer suggestions, and are of a typical that we imagine our readers anticipate. This article incorporates hyperlinks from which we are able to earn income. This income helps us to help the content material of this web site and to proceed to take a position in our award-winning journalism. For extra, see How we make our cash and Editorial promise

    Important data

    Some of the merchandise promoted are from our affiliate companions from whom we obtain compensation. While we intention to characteristic among the greatest merchandise accessible, we can not overview each product in the marketplace.

  • Fluent Money appoints new director of mortgages and defense – Mortgage loan Strategy

    Fluent Revenue has appointed Martin Baker to the new place of director of dwelling loans and security.

    Baker joins from HSBC the place he was head of tactic and establishing and has additionally held senior roles at Co-op and Barclays. Baker has labored within the retail and fiscal knowledgeable providers subject for 25 a very long time, with a goal on buyer expertise.

    In this new job with Fluent Cash he shall be accountable for persevering with to enhance their preliminary price and safety enterprise and will oversee the corporate’s purchaser providers. He will even emphasis on optimising operational efficiencies and driving strategic initiatives that assist Fluent’s prolonged-time interval progress objectives.

    Fluent Cash was obtained by House loan Tips Bureau (MAB) in 2022. The firm mentioned this appointment varieties a good portion of its strategic goals to fortify its market scenario and enhance the assist provided to customers.

    Mortgage loan Tips Bureau CEO Peter Brodnick states the appointment would assist drive the enterprise forward in its following part of progress. He reported Baker was an ideal match for the agency and “would strengthen a massively daring and dynamic administration group”.