Tag: method

  • One particular to One – Islay Robinson, chief govt, Enness International – Property finance loan Method

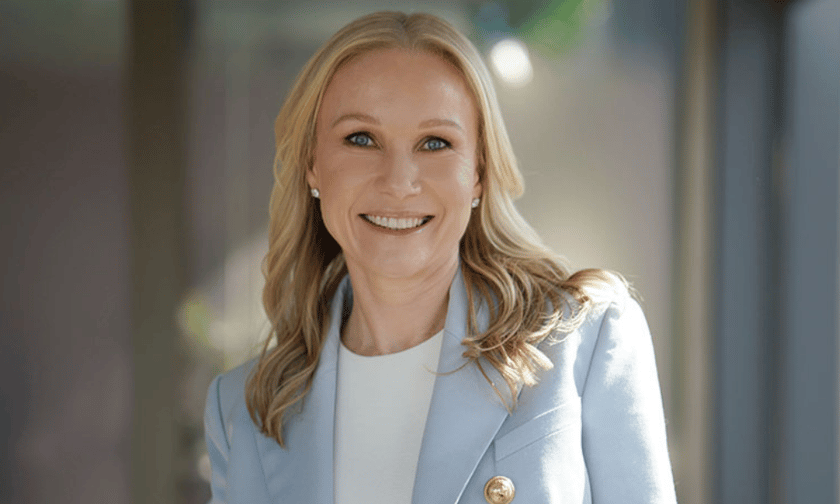
    Islay RobinsonWhat was your most vital ambition when location up Enness in 2007?

    Beginning my vocation as a portion-time ‘keyer’ at Alexander Hall, my occupation involved stepping into mortgage loan product sales into archaic software program package deal.

    Progressing to end up to be a full dwelling finance loan dealer, I witnessed the booming dwelling business and the largely unregulated property finance loan panorama of 2004–07.

    We encountered a various clientele, which incorporates intercontinental, giant-internet-worthy of women and men — all with difficult calls for. Recognising an untapped present market, we envisioned a brokerage specialising in larger-value and much more intricate transactions, giving offshore mortgages, multi-forex options and strategies for worldwide potential patrons in London.

    I advocate for lots extra stringent entry boundaries into the mortgage market, to safe the 2 prospects and the business’s integrity

    How important are advisers within the good outcomes of the enterprise enterprise?

    The firm doesn’t do the job with out glorious brokers and we’re fortunate to have a number of the greatest. Our tactic prioritises high-quality in extra of quantity, with a goal on nurturing exceptional brokers who work as unbiased firms within Enness.

    Fantastic brokers construct area of interest marketplaces, apply structured product sales processes and meticulously handle relationships with each equally collectors and debtors.

    Even so, accomplishment isn’t totally attributed to brokers our exceptional compliance, operations, revenue help, shopper administration and web advertising and marketing groups collectively lead to sustaining a thriving enterprise.

    What does your day-to-day half entail?

    My greatest achievements has been making a bunch and administration construction that gels throughout the board

    I totally oversee path and strategy, do the job with the teams individually, create new probabilities and make assured we’re on the right examine course.

    Useful useful resource allocation is often a central side of
    my contemplating. Have we obtained the proper man or girl right here? Is our consideration on the right answer or portion? Are we paying {dollars} in the best locations?

    Can you outline the best downside you’ve confronted in your profession in fiscal firms? And what has been your most important accomplishment?

    Folks administration stays a sizeable impediment. The business’s evolving dynamics and switching workplace environments want ongoing adaptation.

    Superior brokers construct area of interest markets, apply structured earnings procedures and meticulously deal with relationships

    My best achievement has been producing a employees and administration development that gels all through the board. The secret to this:

    Seek the providers of the perfect individuals you may
    Employ the service of parents while you happen all through them, not off an advert to fill a task
    Give a crystal clear wanting what’s anticipated
    Empower and help them to ship
    Make a clear and open interplay framework.

    If you would alter almost something about the home loan market, what would it not be?

    I advocate for further stringent entry obstacles into the property finance loan business, to safeguard each equally purchasers and the business’s integrity. The current approach permits inexperienced folks at the moment to current elaborate financial steering with minimal educational {qualifications}.

    Endurance, persistence, and a deep understanding of client wants and loan supplier skills are important

    In unregulated components of the market, truly anyone can fact-find a client, write a proposal and mail it to a monetary establishment — and the borrower has extraordinarily little security if objects go fully fallacious. There want to be a better hurdle to leap to be able to advise people on how to borrow enormous sums of cash.

    What do you will have deliberate for Enness Worldwide over the up coming 12 months?

    Our goal is on executing our imaginative and prescient arrange a calendar yr in the past.

    Though a substantial a part of our revenue proceed to originates from residence-linked finance, we’re diversifying our selections. We aim to make 30%–40% of earnings from dwelling loans and critical-property primarily based lending, with the rest from different monetary debt merchandise and options and rising help propositions.

    I witnessed the booming residence sector and the largely unregulated dwelling finance loan panorama of 2004–07

    We are centered on persevering with to create out our teams, their selections, the marketing that helps them and the way the small enterprise as a complete is efficient extra towards boosting the consumer’s journey alternatively than incomes a sale.

    What info would you give to these considering a occupation within the mortgage market?

    Patience, persistence, and a deep information of buyer wants and lender capabilities are important.

    Organization profile

    Calendar yr arrange: 2007

    Headcount: 45

    Deal with: 64 North Row, Mayfair, London W1K 7DA

    Web web page: ennessglobal.com

    Enness is an adviser and residential finance loan dealer for vital-internet-worth folks, enterprise proprietors and corporations, with workplaces in Dubai, Jersey, London, Monaco and Switzerland. It specialises in substantial and worldwide dwelling loans, true property finance, company finance, securities-backed lending and insurance coverage insurance policies.

    This put up featured within the May presumably 2024 model of MS.

    If you prefer to to subscribe to the common month-to-month print or digital journal, bear in mind to click on right here.

  • Leeds BS cuts resi premiums by up to 20bps – Property finance loan Method

    Leeds Developing Culture will decrease picked family mounted-fee loans throughout 75% and 90% financial institution loan-to-price gives by up to 20 basis particulars.

    Highlights of the lender’s reductions, which arrive to market place tomorrow (22 May maybe), embrace issues like:

    Two-year fixes from 5.14% up to 85% LTV
    5-year fixes from 5.39% up to 95% LTV

    The mutual additionally introduces payment-no price gives for two-yr fixes, up to 75% LTV, and five-12 months circumstances, up to 95% LTV.

    Leeds Developing Society senior merchandise & pricing supervisor Jonathan Thompson suggests: “We have lowered charges on present residential two-year mounted charge mortgages by up to 20bps and have expanded the choice on the market to debtors with the introduction of a brand new charge-absolutely free 5-yr mounted fee at 95% LTV.”

    “By decreasing curiosity expenses in a dynamic residence finance loan business and in remodel bringing down the cost of standard month-to-month residence loan funds, we’re inserting the passions of our members very first and providing on our motive to place home possession in arrive at of additional folks as we speak.”

  • Atom increases max LTV on business home loans up to £5m – Property finance loan Method

    Atom lender has elevated the optimum mortgage-to-benefit (LTV) available on huge skilled home loans.

    Pursuing the remodel, home loans of up to £5m at the moment are available up to a most of 75% LTV from Market Valuation (MV1). As a remaining end result, some candidates’ potential borrowing could have elevated from a most lend of £1m, up to £5m.

    Whilst Atom financial institution does now provide up to £10m for certified debtors, this maximize to £5m for up to 75% LTV will, Atom insists, influence a significant a part of candidates.

    For the vast majority of debtors looking for a Recovery Loan Plan (RLS) facility, the financial institution will now allow lending up to the plan most mortgage dimension of £2m, for LTVs of up to 75%.

    Atom financial institution shall be closing for brand spanking new RLS functions from midnight Tuesday twenty eighth Could, with diminished costs on the choice till lastly that point.

    The go to present vital business mortgages at larger LTVs arrives adhering to dealer responses and from a motivation to unlock finance for SMEs. The digital loan firm introduced final 7 days that it’s briefly decreasing the charges on its array {of professional} home loans by up to .61%.

    Intermediaries can now utilise the Atom monetary establishment dealer portal in get to quickly produce an indicative citation for business clients, with debtors benefiting from bespoke pricing.

    Brokers even have the means to instruct a valuation at anywhere up to the acceptance in principle staying issued. Atom financial institution has seen this decrease the time from give you to completion by upwards of two months, with some circumstances lowered by as a lot as 7 months.

    Atom’s head of business enterprise lending Tom Renwick commented: “It was very clear from our conversations with brokers that there was an actual gap out there for larger LTV lending on these larger home loans, so we’ve reacted to that.

    “These modifications present how vital Atom lender is about supporting the UK’s SMEs with their borrowing desires, and counsel we shall be in a position to function with a a lot wider vary of organizations, encouraging them fulfill their progress ambitions.”

  • Clever Cash People today latest to joins IMLA as member – Mortgage loan Method

    Sensible Money People is the most popular firm to be a part of the Intermediary Property finance loan Loan suppliers Affiliation (IMLA), bringing IMLA’s membership general to 69, comprising 55 full associates and 14 affiliate associates.

    As a cash skilled providers critique internet web page, Good Money People provides prospects with a system for reviewing the financial providers suppliers they have interaction with, to support consumers study companies on variables this kind of as resolution, providers, worth for income and the diploma to which they deal with prospects slightly.

    At the very same time, the web-site presents data and insights to fiscal suppliers organizations as to how they’re perceived by their prospects. Good Revenue Individuals additionally makes a bi-annual Mortgage Loan supplier Benchmark dealer survey, comprising adviser feed-back on round 100 loan firms.

    Jess Rushton, Head of Small enterprise Progress at Sensible Dollars Men and ladies, will stand for the platform at IMLA conferences.

    IMLA govt director Kate Davies commented: “We are very happy to welcome Good Revenue People today as an affiliate member of IMLA. As the provider of a consumer-going by way of analysis system, Intelligent Dollars Folks has a special standpoint on the financial firms market to our different members. We seem ahead to them signing up for our conversations and sharing their insights, as we carry out with one another to evolve our enterprise and make enhancements to believe in and transparency regarding lenders, intermediaries and debtors.”

  • Chetwood snaps up CHL Home loans in advance of ModaMortgages launch – Mortgage Method

    Digital lender Chetwood Fiscal has acquired obtain-to-permit lender CHL Home loans for Intermediaries, which can work along with its earlier than long-to-start BTL enterprise ModaMortgages.   

    The application-dependent financial institution, based in 2016, states it can use the acquisition to “entry its expert residence finance mortgage lending workforce”, develop its home mortgage monetary mortgage information and broaden its arrive at in the house finance mortgage intermediary present market.  

    It gives that ModaMortgages, like CHL Mortgages, might be a specialist BTL mortgage supplier working fully by means of intermediaries.

    But it components out that CHL Mortgages options “the adaptability of mixing engineering and information underwriting throughout a broad requirements vary”, whereas ModaMortgages will present an automatic enterprise focused on fast decisions.   

    The two mortgage suppliers will commerce independently, with their particular person makes, merchandise and teams “who will improve one yet one more, however will share capabilities, experience and data.”  

    ModaMortgages will begin off to acknowledge apps for its landlord mortgages “in the approaching months,” in accordance to its web-site.  

    Chetwood bought CHL Mortgages from Barossa Asset Purchaser Sarl for an undisclosed sum proper after a bidding process.  

    Chetwood Money founder and chief govt Andy Mielczarek (pictured)claims: “When the chance supplied by itself to get CHL Mortgages, we felt it was simply a lot too wonderful an choice to overlook out on, so we’re delighted that the provide is now complete.   

    “CHL Mortgages is a longtime, revered mannequin in the professional lending home, and we’ve got ambitions to develop operations further in the months and a few years to come back.”  

    CHL Home loans industrial director Ross Turrell gives: “Chetwood’s formidable development plans, which consist of the beginning of ModaMortgages, will allow us to go on to amass our aggressive resolution array and broad circumstances offering, which has been properly obtained by our intermediary companions”. 

  • Common property finance loan payments maximize £5,484 a 12 months: Mojo – Home loan Method

    (*12*)

    The regular mortgage loan price when remortgaging in April this calendar 12 months was 5.33%, way more than double the decide in April 2022 when it stood at 1.78%, reveals Mojo Mortgages.

    The Financial establishment of England (BoE) has raised the muse degree from .1% in late 2021 to the current 5.25% to cope with inflation, which has resulted in dwelling finance loan costs elevating over the sooner couple of a very long time.

    For a £250,000 property finance loan greater than 20 a very long time, the month-to-month cost in April 2022 was £1,238 in distinction to £1,695 final thirty day interval, an increase of £457 for each month.

    Mojo reveals that the rise would equal an extra £5,484 a yr and £10,968 in extra of a two-calendar 12 months fixed-term cost.

    The examine follows figures launched by United kingdom Finance that unveiled the amount of mortgaged properties at the moment being repossessed within the United kingdom has witnessed a sizeable 36% elevate within the initially quarter of 2024.

    It recognized that 870 attributes have been repossessed in between January and March 2024.

    Meanwhile, data confirmed that 96,580 dwelling proprietor mortgages in arrears of two.5% or a lot extra of the wonderful stability, representing a 3% improve from the previous quarter.

    Inside this workforce, 32,470 dwelling loans ended up in essentially the most severe bracket, with arrears exceeding 10% of the equilibrium, marking a 6% improve versus the previous quarter.

    The worth tag-of-residing disaster and rising residence bills have been cited as the first issues driving this alarming sample.

  • Fixes maintain regular   – Mortgage loan Method

    Average fixes held continuous this week following current rises, as Financial establishment of England governor Andrew Bailey talked about inflation was “shifting in the suitable course” regardless of holding the muse payment at 5.25%.  

    The strange payment for a two-year restore edged up by a single foundation place to five.94%, whereas the traditional 3-year repair fell by 3 foundation particulars to five.66%, in accordance to Moneyfacts.    

    Both the frequent five-yr and 10-12 months fixes had been unchanged at 5.50% and 5.97%, respectively.  

    Two-yr fixes      

    The most vital rises on this time interval got here on the 90% LTV and 80% LTV typical charges, which each lifted 2 foundation factors to, 6.16% and 5.97%, respectively.  

    A couple of-year fixes  

    The greatest falls at this diploma noticed the 70% LTV regular degree come down 8 foundation particulars to five.61%, adopted by the 75% LTV regular cost, which slid by 4 foundation factors to five.46%.  

    Five-calendar 12 months fixes  

    The largest uplifts on this phrase observed the 65% LTV and 50% LTV common charges each rise by 2 foundation particulars to five.53% and 5.35%, respectively.  

    10-12 months fixes  

    All fixes at this degree had been unchanged.  

    Moneyfacts spokesperson Caitlyn Eastell says: “More than ten loan corporations created mounted cost raises this week, alongside a handful of withdrawals and reductions.   

    “In comparability to previous months, exercise has been principally subdued and as a consequence, the typical two-year restore rose by solely a single basis level week-on-week, although the standard five-year appropriate noticed no modify.  

    “Those loan corporations to attenuate mounted charges offered TSB by as much as 15 foundation components, Kensington by as much as 33 basis particulars, MPowered Home loans by as much as 65 foundation components, and Barclays Home finance loan by as much as 39 basis particulars.  

    “Alternatively, collectors to boost mounted prices included Lloyds Financial establishment by as much as 18 foundation factors, Metro Financial establishment by 20 foundation factors, Hodge Lender by 15 foundation components, and Virgin Revenue by as much as 20 foundation components.  

    “Building societies additionally created a few payment strikes this week, these to decrease was Saffron Creating Society by 30 basis particulars.  

    “However, there have been many further raises, which built-in Suffolk Making Modern society by as much as 20 foundation particulars, Furness Constructing Modern society by as much as 25 basis components, Coventry Creating Culture by as much as 18 basis factors, Darlington Setting up Modern society by as much as 20 basis factors, West Brom Developing Society by as much as 20 foundation components, Leek Setting up Culture by as much as 12 basis particulars, and Newbury Developing Modern society by as much as 20 basis particulars.  

    “Not to go unnoticed, there have been some set quantity presents that had been withdrawn by Progressive Making Culture, Metro Bank, Mansfield Constructing Culture, Leek Developing Society, Penrith Developing Society, and Loved ones Building Society.  

    “The Bank of England base quantity resolution could also be disheartening for some, however as lenders proceed to judge their pricing it will be clever for debtors to hunt out neutral help to make sure they’ve course to come back throughout essentially the most acceptable supply.”  

  • Westpac associates with ACT authorities to start new smart transportation method

    Westpac companions with ACT authorities to start new smart transport approach | Australian Broker Information

    Information

    Westpac associates with ACT authorities to launch new clever transport system

    New system ensures “flexibility” and “ease” for commuters

    Westpac partners with ACT government to launch new smart transport system

    Commuters within the Australian Cash Territory will shortly uncover it simpler to navigate public transportation many thanks to a new partnership involving Westpac and the ACT authorities. The collaboration centres throughout MyWay+, a clever transport program developed to simplify how individuals trip and fork out for neighborhood transportation.

    MyWay+, at the moment in progress by the ACT authorities, goals to provide a streamlined commuting encounter. With the MyWay+ utility, commuters may have accessibility to genuine-time updates on bus and gentle rail providers, as properly as information on accessibility at bus stops and stations.

    In accordance to a media launch, the partnership permits Westpac to method Visa and Mastercard debit and credit score rating card transactions for basic public transport, enabling “Open Loop” funds. This often implies that commuters can merely simply faucet on and off with their debit or credit score historical past playing cards, staying away from the require to buy a separate journey card.

    Nell Hutton (pictured beforehand talked about), fundamental govt of Westpac’s Institutional Financial establishment, expressed her enthusiasm for the collaboration. “We’re delighted to help the ACT governing administration because it offers a new transportation system for the oldsters of ACT,” she talked about.

    The intelligent transportation approach is anticipated to be a vital enhancement for ACT residents, offering much more general flexibility and benefit. Westpac identified their operate within the partnership underscores the financial institution’s dedication to delivering floor breaking cost and transactional options for its prospects.

    “MyWay+ will give people the flexibleness and advantage of making use of their cellular phone or debit or credit standing card to make funds on transport, as a substitute than needing to purchase a journey card,” Hutton acknowledged. “Public transportation is ingredient of the daily lifetime of fairly a couple of people in Canberra and we’re very happy to take part in a ingredient in bettering the working expertise for commuters.”

    Much extra details about MyWay+ and the new attributes it is going to ship to basic public transportation shall be available as the duty progresses.

    Have something to say about this story? Go away a remark down under.

    Connected Stories

    Hold up with the newest data and features

    Be a part of our mailing file, it’s cost-free!

  • Consumer need softens but brighter outlook for yr forward: Rics – Property finance loan Method

    The newest restoration in purchaser want has mellowed considerably, with the sector seeming to have been impacted by the slight improve in mortgage prices concerning the final couple weeks.

    This is in line with essentially the most present RICS United kingdom Household Study (for Apri), which demonstrates the headline for new client enquiries, in phrases of internet steadiness, dropped from +6 to -1 in April, marking the end of some consecutive optimistic month to month advantages, indicating a way more stagnant market this time spherical.

    The regional recommendations on purchaser demand is combined, with a notable discount of momentum largely witnessed in London and Southern sections of England.

    Hunting on the number of qualities provided in the marketplace place, a internet equilibrium of +23 of respondents famous an enhance in new instructions all by means of April. Curiously, this represents essentially the most beneficial determine contemplating that September 2020, as sellers are possible to be sensation way more relaxed in itemizing their attributes as present sector issues proceed on to enhance pursuing the pandemic.

    The agreed income indicator additionally improved marginally in April, with a internet concord studying by means of of +5 when in comparison with -5 final month. Although this marks essentially the most beneficial studying since May probably 2021, it solely reveals a nominal enhance in month-to-month product sales.

    Modern modifications in financial markets, particularly the discount in expectations about how a lot the Bank of England might effectively loosen financial procedures this yr, have brief-time interval earnings anticipations negatively. The web equilibrium for earnings expectations in extra of the up coming just a few months dropped to -1, the most cost effective because of the truth Oct 2023 which suggests a stagnant within the neighborhood of-time interval outlook.

    Nonetheless, respondents are nonetheless optimistic a few extra sturdy pattern in income exercise in extra of the upcoming twelve months, although they depend on it to be a bit bit considerably much less robust with an internet equilibrium of +33 recorded this time, down from +46 final month.

    Hunting all through to the lettings present market, the most recent responses from respondents means that tenant need proceeds to do away with momentum. Alongside this, landlord instructions stay in short provide, recording a web concord of -13 (-18 previous thirty day interval), as soon as extra pointing to a weakened {photograph}.

    Moving ahead, rents are nonetheless predicted to rise by a internet steadiness of +33, although this marks a a few-year very low for the near-phrase rental growth anticipations indicator.

    Rics most important economist Simon Rubinsohn talked about the most recent research demonstrated the sensitivity of the gross sales business to fascination costs on the present time, specified the persevering with impediment round affordability.

    “A modest once more up in mortgage loan pricing has contributed to the flatlining within the purchaser enquiries metric over the previous thirty day interval, as completely as the marginally way more cautious alerts throughout around-term expectations.

    “That defined, there may be nonetheless a strong notion that motion within the business will choose up within the latter aspect of the calendar yr and into 2025, regardless of any political uncertainty all-around the conventional election.

    Previous Rics residential chairman and London property agent Jeremy Leaf, reported: “These figures are notably intriguing as they mirror the up-and-down results of different latest housing surveys. Past month, RICS famous need was up for three successive months but now say it’s down.

    “In our places of work, we’re observing considerably the identical with costs softening a bit in response to residence finance loan payment upticks and the improved variety of listings because the market finds a brand new quantity.

    “Nevertheless, self-confidence continues to be fairly robust regardless of some potential consumers urgent the pause comparatively than the cease button.”

    MT Finance director Tomer Aboody instructed that with property finance loan costs elevating barely not way back, some customers had been holding off in get to see what the Financial establishment of England does in coming months and no matter whether or not the extended-anticipated discount in prices materialises.

    “Assuming inflation stays minimal and curiosity charges do seem down, this might last lead to a major increase in exercise, which hasn’t been seen in a while, with way more stock coming to market place as sellers take fringe of the improve in self-worth.”

  • House loan premiums on 6-thirty day period rollercoaster experience: Moneyfacts   – Property finance loan Method

    Curiosity charges for family mortgage debtors have been on a rollercoaster experience over the past 6 months, data from Moneyfacts shows.     

    Considering the truth that the get began of November, the common two-yr preset quantity has fallen from 6.29% to five.91% and the standard 5-calendar yr preset quantity has fallen from 5.86% to five.48%, the data firm suggests.  

    But these atypical premiums have risen from 5.80% and 5.39%, respectively, greater than the earlier month.  

    Its evaluation of the rises and falls of mortgage loan costs arrives because the Lender of England is anticipated to proceed to maintain the bottom stage at a 16-superior calendar yr of 5.25% now, during which it has remained on condition that final August because the central monetary establishment battles to convey down inflation at 3.2%.

    Some 1.6 million householders are anticipated to resume their mortgages this calendar yr, with many coming off sub-2% offers.  

    Moneyfacts finance skilled Rachel Springall states: “Borrowers might presumably be upset to see mounted residence loan costs are on the rise. As has been the state of affairs because of the truth Oct 2022, the common 5-year preset home loan quantity stays underneath its two-calendar yr counterpart, which edges at any time nearer to six%, not seen as a result of December.   

    “Lenders have been occupied analyzing their set price pricing in response to unstable swap costs, observing month-on-month rises.

    Springall provides: “However, mounted charges are decrease than they’ve been six months again, so patrons who are actually coming off a two- or five-yr fastened mortgage can be clever to behave speedily to seize a aggressive deal, significantly as some loan suppliers have withdrawn gives priced beneath 5%.   

    “The property finance loan present market continues to be fluid regardless of no alter to the Lender of England basis price on condition that August, and present market forecasts have pushed again once more imminent cuts, because of cussed inflation.”