Tag: method

  • Visa queries major broker searches in March: L&G – Mortgage loan Method

    Queries about lenders’ visa requirements had been essentially the most searched-for element of situations in March, while demand for desire-only bargains dipped 8%, in accordance to knowledge from Lawful & General Ignite.

    The sourcing platform says considerably of brokers’ analysis train related to debtors with difficult situations because the second most-searched-for time period simply after “visa” was “default glad”.

    Echoing figures from CACI and Initially Immediate, revealed now, displaying a progress in lending to these getting their to start out with foot on the housing ladder, “first-time purchaser” was the Third-most looked for phrase on Ignite.

    At the opposite conclusion of the sector, searches for “most age” grew by 6% and have become a prime rated 4 lookup time period (up from ninth in February).

    Demand from clients for “shared possession” and “joint borrower sole proprietor” objects remained strong, with these phrases place eleventh and twelfth in March.

    Meanwhile, queries on behalf of shoppers trying to find a 2nd family grew by 7% in March, regardless of the Spring Spending plan announcement of a discount in funds positive factors tax on 2nd properties to essentially encourage homeowners to offer.

    L&G Property finance loan Products and providers head of things and transformation Jodie White claims: “While the mortgage loan market isn’t utterly out of the woods, the March info affords improbable objective to be cautiously optimistic.

    “Overall, train continues to be strong, and searches for among the further about situations queries (these as private debt administration concepts) are commencing to drop.

    “The stabilisation of swap and need premiums has carried out a major part in this – although the traditional fixed payment acquire-to-enable product was priced at 6.88% in August, it now sits at a considerably lower 5.52% in accordance to Moneyfacts.”

  • Final results AM joins ASTL as associate member – Home finance loan Method

    Effects Asset Administration has grow to be the newest organisation to enroll in the Association of Limited Time interval Loan suppliers (ASTL) as an associate member.

    Effects Asset Administration has been related within the brief time period home lending business contemplating the truth that 2006.

    Success AM presents critiques previous to lending, pre- or post- valuation the place a ‘sense’ take a look at might be required, as successfully as opinions of HMO viability, purchase to permit inspections, portfolio testimonials and desktop critiques. It operates with smaller and large collectors in England and Wales.

    The ASTL now has 44 associate prospects and 44 loan supplier associates.

    ASTL predominant government Vic Jannels commented: “The sustainable growth of the bridging house finance loan market is simply attainable with the help of skilled firms that enable loan firms to hold out lending with certainty and confidence.

    “This is simply one of many explanations why associate prospects are so important to the ASTL and the persevering with success of the sector. Our rising membership shows the elevating significance of our sector and our collective motivation to delivering superior purchaser results.”

  • Jump in revenue of £5millon-furthermore London households: LonRes – Mortgage loan Method

    Gross gross sales of prime London qualities for £5m and better than ended up up by way over 15% in March in comparability to the same thirty day interval previous 12 months, in accordance to the LonRes index.

    High-value earnings in March had been being additionally further than 8% beforehand talked about the pre-pandemic development involving 2017 and 2019.

    At the conclude of March there ended up near 27% further £5m+ London houses on sale when in comparison with the exact same month ultimate 12 months, and much more round 47% way more than the common quantity on sale previous to the pandemic amongst 2017-2019.

    Yearly rental development all through prime London rose barely in March, to three.8%, however rental values had been 28% greater than their 2017-2019 typical.

    The quantity of high-finish permits agreed was down by 9.1% yr on yr in March.

    LonRes head of evaluation Nick Gregori states: “While agreed product gross sales of £5m+ attributes are moderately so much larger than in the broader present market, there have been being some indications in March that demand has been weakening.

    “The second half of March noticed decrease figures of below options and exchanges.

    “While unlikely to be fully as a result of of to the adjustments to ‘non-dom’ tax procedures – which solely affect a bit of proportion of the capital’s inhabitants – adversarial sentiment about London as a world metropolis is unhelpful to the market place.

    “The main London lettings sector was subdued as soon as once more in March, with lately agreed lets down virtually 10% on a calendar 12 months in the previous irrespective of raises in new instructions and obtainable stock above the same interval of time.

    “Annual rental enlargement of 3.8% was a modest improve in comparability to February’s degree and was the fourth consecutive month in the 3-4% choice, a welcome alter for tenants in distinction to the double-digit will increase seen in 2022 and 2023.”

  • 15 Apr to 19 Apr – Mortgage loan Method

    Explore Property finance loan Strategy’s greatest 10 tales this 7 days!

    Showcased articles or weblog posts contain the appointment of Harrington as CEO of L&C Mortgages and insights on stubbornly increased pay again development amid inflation and charge issues. Browse further right here:


    Harrington appointed CEO of L&C Mortgages

    L&C Home loans has named Mark Harrington as its new Chief Govt Officer (pending regulatory acceptance). With greater than 20 a number of years of expertise, Harrington has progressed through many roles as a result of turning into a member of the group in 2003, from property finance loan and security adviser to chief working officer.

    Pay again growth ‘obstinately excessive’ as market place factors to inflation and worth fears 

    Uk common earnings progress moderated to 6% within the 3 months to February, per the Business workplace for National Stats. Having mentioned that, analysts warn that this “persistently excessive” pay again information might impede inflation discount and discourage early Bank of England charge cuts. Earnings dipped from 6.1% within the 3 months to January, surpassing economists’ 5.8% projection. Furthermore, genuine common weekly spend rose by 2.1%, the quickest degree contemplating that September 2021, when altered for inflation.

     
    Rents hovering at quickest at any time stage

    In the United kingdom, non-public rents ongoing their quick ascent, outpacing inflation. Over the 12 months to March 2024, tenants seasoned a 9.2% improve in housing charges, surpassing the earlier month’s 9% improve. According to the Workplace for Nationwide Statistics, this marks the optimum annual surge contemplating the truth that 2015 when details assortment began. Scotland observed probably the most sizeable lease hikes, with the unusual common hire in England attaining £1,285, up by 9.1%. Likewise, Wales witnessed a 9% improve, bringing the everyday hire to £727, though in Scotland, rents soared to £947, reflecting a ten.5% surge.

    Sticky’ inflation dampens anticipations of early degree minimize

    In March, the Client Rate Index (CPI) dipped to 3.2%, a decrease within the inflation worth, though considerably earlier talked about anticipations. Home loan professionals thought of this lower positively, nonetheless cautioned that the persistent inflationary pressure might maintain off an anticipated cost minimize by the Financial establishment of England. The central monetary establishment has reiterated its stance on withholding curiosity cost reductions proper up till sizeable proof signifies inflation moderation.

    Brokers debate deserves of modest services or products transfers

    Queries from brokers with regards to modest merchandise transfers and advertising strategies had been distinguished dialogue topics on a number one on the web enterprise dialogue board. Cherry, frequented by over 35,000 cash consultants within the earlier 12 months, highlighted the prevalence of discussions on merchandise transfers, primarily for compact loan dimensions. One dealer initiated a thread to inquire about dealing with a £20,000 private loan resolution switch likewise to better remortgages.

    (*15*) launches BTL tracker loans, cuts resi prices by up to 24bps  

    Starting up on April 16, (*15*) for Intermediaries launched a array of make investments in-to-let two-yr tracker monetary loans and decreased picked family charges by up to 24 basis factors. The broker-only arm additionally trimmed picked purchase-to-let set costs for purchases and remortgages, as well as to lowering set charges throughout its new enterprise enterprise and merchandise switch family loans.

    Just one to An individual: Richard Merrett, controlling director, (*19*) Corridor

    Richard Merrett, MD of (*19*) Hall, shows on his occupation, emphasising the corporate’s society and prospects for development. He prioritises experience enhancement and tackling market difficulties like rising fascination prices and native climate alter. Merrett appreciates the business’s collaborative mom nature and advises to focus on what could be managed though sustaining a way of humour.

    HTB reveals new administration workforce throughout residence divisions

    Expert lender Hampshire Have confidence in Financial establishment (HTB) appoints Alex Upton as Controlling Director of Specialist Mortgages. Neil Leitch, presently Commercial Director of Improvement Finance, succeeds Upton as Taking care of Director of that division. Jamie Jolly continues to be Director of HTB’s bridging division. Upton, who joined HTB in 2018, is acknowledged for her administration in enhancement finance, like recruitment and award wins.

    Hinckley & Rugby appoints important purchaser officer

    Hinkley & Rugby appoints Danny Cranie as Chief Client Officer, a freshly designed half aimed toward shaping the mutual’s upcoming. With 34 a number of years of banking and creating tradition information, Cranie will improve current channels and set up the digital proposition. He has a hold monitor of historical past of driving enterprise enlargement and delivering extraordinary client outcomes.

    Acquire-to-Enable Check out: BTL will take the bull by the horns

    In 2023, the get-to-let business confronted troubles due to to important finance costs, impacting landlords’ leverage and forcing tough choices. However, 2024 has discovered a resurgence, with lenders decreasing fees and rejuvenating the refinance market place. In spite of swap-amount volatility, home loan submissions are at document quantities, indicating a healthful market. This resurgence added advantages not solely landlords but additionally tradition, offering important rental housing amid elevating demand. Matthew Rowne discusses the change from a bear market in 2023 to a bull market in 2024, highlighting the beneficial impression on the United kingdom monetary system and society.

  • Co-op to increase charges by up to 41 bps – Property finance loan Method

    Co-operative Lender has warned brokers that newest prices can be withdrawn at 5pm tomorrow to make method for worth boosts of up to 41 basis factors.

    The lender can also be trimming costs on a few of its offers.

    In an piece of email to advisers it claims that in its residential vary, picked two, three and 5 calendar 12 months fastened costs will increase by up to 41bps.

    Other family two and 5 12 months fixes will reduce by up to 7 bps.

    In its skilled home loan fluctuate two calendar 12 months fixes will increase by up to 41 bps and 5 calendar 12 months fixes by up to 33 bps.

    There aren’t any pricing modifications on its merchandise change, obtain-to-permit or help to buy specials.
    Comprehensive points of latest premiums will abide by and these gives can be obtainable from 9am on Monday.

  • Brokers urged to finish psychological wellbeing study – House loan Method

    Brokers are presently being urged to complete a survey on their psychological well being and health earlier than it closes subsequent week in get to benchmark advisers’ wellbeing and help improve the assist that corporations present.

    The Home loan Sector Psychological Overall well being Constitution (MIMHC) is contacting on advisers and different staff within the sector to complete its yearly psychological well being and health survey simply earlier than entries shut following Friday, April 26.

    Respondents will likely be questioned to report once more anonymously on their psychological and psychological experiences of doing work within the enterprise, strain quantities, sleep kinds and the nice high quality of help on provide from their employer.

    Primarily primarily based on the survey’s outcomes, MIMHC hopes that employers will subsequently make use of initiatives to produce more healthy workplaces and performing practices.

    MIMHC co-founder and crew revenue director at Crystal Specialist Finance, Jason Berry suggests: “We’ve presently skilled an unbelievable response from market gurus this yr – however we’re hoping that even additional will now share their views to support type the sector’s foreseeable future prior to the study closes.

    “All entries are nameless and that is everybody’s likelihood to make their sights heard.

    “The survey yields invaluable insights in regards to the emotional and psychological troubles that genuinely rely – from pressure and nervousness to financial anxieties.

    “These findings will likely be became a white paper which will likely be shared amid our customers at some stage in Psychological Health Consciousness Week 2024, which operates from Might 13-19, to empower them to put into follow acceptable initiatives and steerage packages.”

  • ‘Sticky’ inflation dampens anticipations of early fee minimize – Home finance loan Method

    The quantity of inflation ongoing to slip in March, with the headline Shopper Selling value Index dropping to three.2% — whereas this was a bit bit greater than financial forecasts.

    Mortgage authorities welcomed this downward sample, however reported ‘sticky’ British isles inflation might suggest the Bank of England postpones an early summer time season fee slash.

    The Lender of England has constantly reported that it’s going to not begin to cut back curiosity charges proper till there are crystal clear indications inflation is lower than regulate.

    March’s CPI decide had been solely a slight minimize on February’s determine of 3.4%, and even now a way over the Financial establishment of England’s 2% consider.

    L&C affiliate director David Hollingworth says discount within the headline cost of CPI was welcome. “It is a step within the applicable course towards the purpose when the Financial establishment of England might maybe get began to ease curiosity prices once more.

    “With a much bigger slide envisioned subsequent month some might be hoping a slash will arrive faster comparatively than afterward. However, the Bank may be very prone to contemplate the menace of inflation remaining better for extra time very significantly and has ceaselessly instructed it won’t act proper till it’s completely certain that inflation is below regulate.”

    Private finance complicated director Chris Sykes says: “While there’s a optimistic improvement in inflation, lingering dangers might most definitely postpone a summer time quantity decrease.”

    He supplies that BoE will keep a watchful eye on unpredictable conditions impacting on oil promoting costs and the extra powerful-than-expected actual earnings development. Sykes particulars out that British isles inflation stays increased than that in Europe, and provides that the BoE can be conscious of monetary particulars from the US this 7 days which confirmed inflation hovering but once more.

    Other people within the area recognized as on the Lender of England to take “daring” movement in response to the continued downward development in inflation.

    SPF Non-public Clientele CEO Mark Harris states: “With inflation persevering with to switch in the direction of the Bank of England’s 2% deal with, it’s time for the cost setters to be daring and begin out chopping fascination expenses. There is a sense that consumers and sellers are retaining fireplace prepared for that very first stage discount, and when it arrives, it can give the housing market a welcome strengthen.”

    He identified that swap costs have now risen this morning in response to issues that an need fee slice might be delayed and this may results the pricing of mounted fee mortgages. “Five-yr Swap prices rose this morning to 4.21 for every cent from 4.14 for each cent yesterday and proper up till they’re constantly slipping, loan suppliers are unlikely to minimize property finance loan charges extra.”

    Nonetheless Skyes claims much less beneficial inflation information from the US didn’t had an adversarial have an effect on on the pricing of mounted fee mortgages. “The best house loan charges we monitor have demonstrated no motion for about a couple of months. The insignificant enhance in swaps has merely launched them once more to concentrations from a pair of weeks earlier than.”

    Hollingworth means that present market anticipations on the timing of long run costs cuts can be vital in deciding mounted stage pricing heading forward.  “Fixed premiums have fallen considerably as a result of final summertime however have largely stabilised.  With uncertainty nevertheless within the air as to how quickly base quantity would possibly fall, all these holding out for extra cuts might presumably get hold of them selves in for a chronic wait round.”

    Over 50s loan supplier LiveMore dealing with director of capital markets Simon Webb says: “Although our current inflation quantity stays means off the two% objective, consumers can get some solace that inflation is essentially on the descent this time spherical, and our financial system does appear to be on the mend, gradual whereas that method is perhaps.

    “Older debtors and mortgage prisoners are persevering with to really feel the squeeze with the persevering with increased price of dwelling. People at present coming off an interest-only home loan this side of summer time will need to make constructive they discover audio info.”

  • Rents increasing at speediest ever level – Mortgage Method

    Private rents within the British isles continued to extend at a a lot faster value than inflation, with tenants seeing housing costs rises by 9.2% within the 12 months to March 2024.

    This is a rise on the 9% once-a-year improve recorded the sooner thirty day interval, in response to the Business workplace of National Statistics, and is one of the best once-a-year soar because of the truth this particulars was to begin with collated in 2015.

    These figures current that the most important rent will increase had been being in Scotland. Over-all the bizarre month-to-month hire paid in England now stands at £1,285, a 9.1% enhance. In Wales the widespread hire is £727, a 9% maximize although in Scotland the traditional hire is  £947 — a ten.5% enhance.

    In Northern Ireland  widespread rents elevated by 10.1 per cent within the 12 months to January 2024.

    Even additional regional breakdowns clearly present that in England lease will increase have been biggest in London at 11.2% in extra of the earlier 12 months. The North East skilled the most cost effective common enhance at 6.1%.

    Properties in Kensington and Chelsea in London skilled the best regular month-to-month rents, at £3,305. The most reasonably priced regular rents had been being in Dumfries and Galloway in Scotland, the place tenants paid an common bizarre of simply £475.

    Commenting on these figures Hargreaves Lansdown head of personalised finance Sarah Coles suggests: “There’s no permit-up within the squeeze on renters, as rents have been up 9.2% in a yr – a file as a result of the data was first collected in 2015.”

    She suggests  current figures from the Royal Institute of Chartered Surveyors (Rics) exhibit why rents are persevering with on this upward trajectory. “The number of new tenants has risen each solitary month as a result of the present market reopened simply after lockdown. Meanwhile, the number of landlords has been falling as a result of summer time 2022, and has solely briefly been in beneficial territory for a handful of months contemplating the truth that 2017.”

    She provides: “Rising residence prices and better dwelling mortgage prices, coupled with extra sturdy taxes and much more stringent guidelines throughout permitting residence, often means the numbers have stopped including up for large numbers of landlords, who’ve been progressively promoting up and discovering out of the group.”

    She says that though these rules had been aimed at safeguarding renters, with elevated taxes made to stop landlords buying up attributes from potential initially-time consumers, the end result has been fewer landlords which is putting further stresses on renters due to to a deficiency of supply within the business.

    Coles provides that when common personal rents could maybe be much like dwelling mortgage funds houses that lease generally earn loads much less, leaving a few of these households extra economically vulnerable.

    Former Rics family chairman and north London property agent Jeremy Leaf, says: “Rents are even now climbing in response to the persevering with imbalance involving present and want.” He gives that right this moment’s announcement that the quantity of inflation has fallen will ship some help for these tenants.

  • Frollo phone calls for use situation-based method for greater open banking info

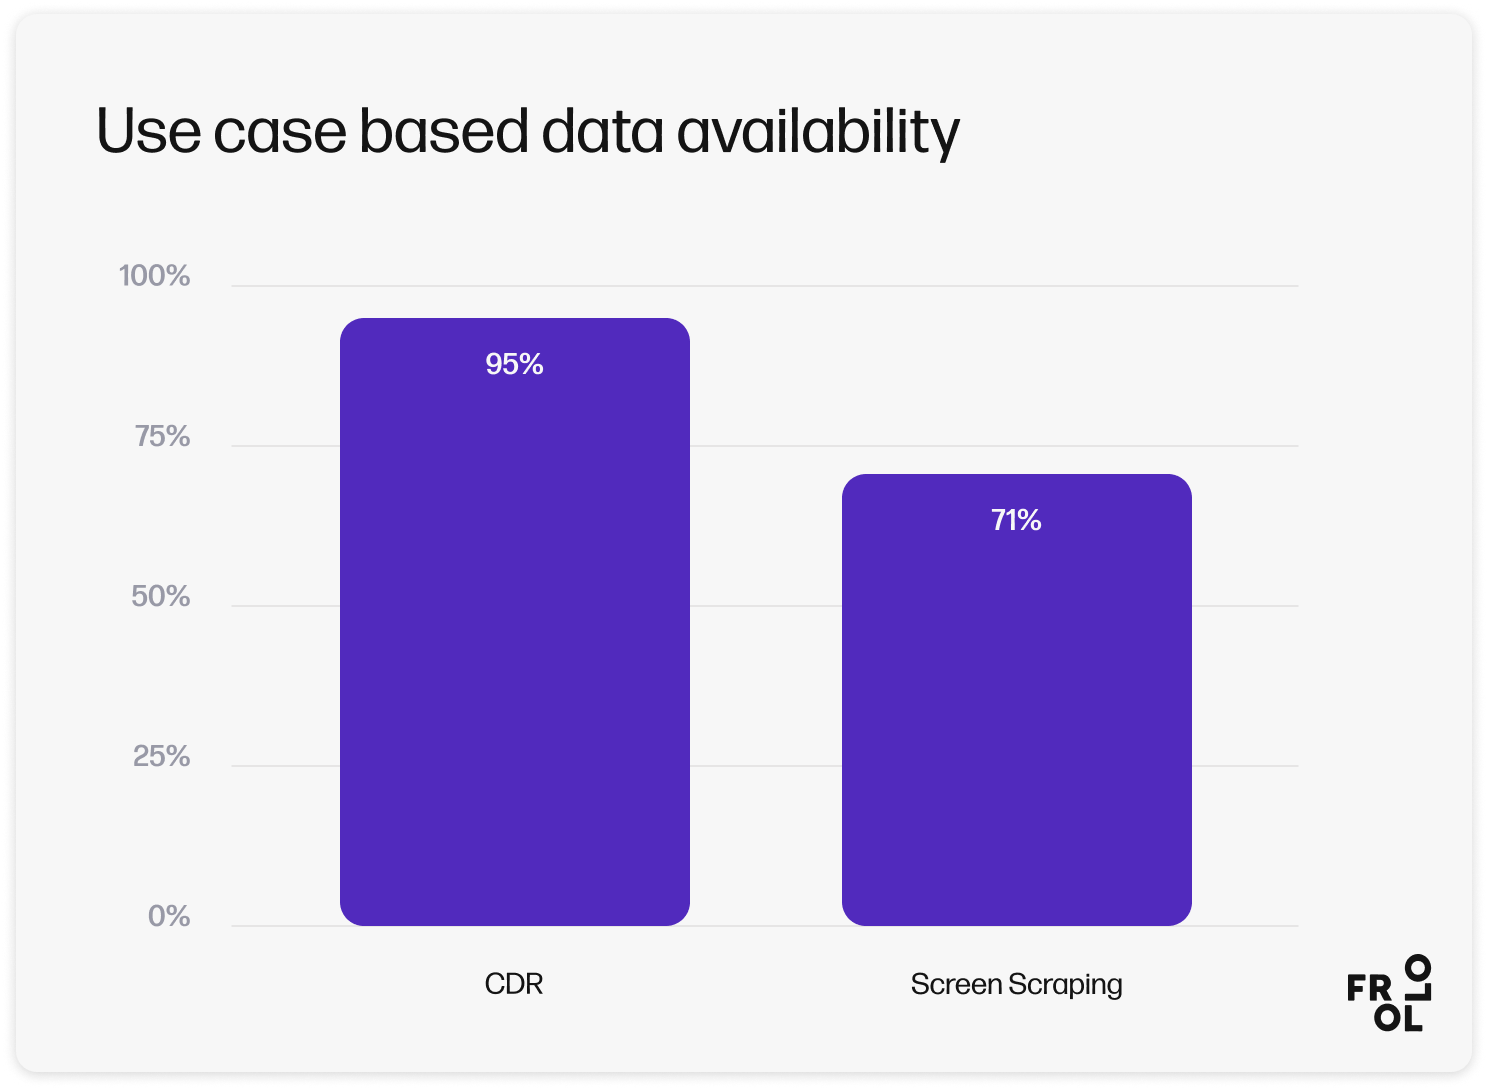
    “Reliable and complete transaction info is the idea of useful income administration, enabling actual categorisation, intelligent insights, and personalised ideas,” Thrassis reported. “These conclusions underscore the significance of a use situation dependent method to enhancing open banking.”

    What’s extra, Frollo’s examination when put next open banking information with that attained by means of display scraping, noting a 35% uplift in information safety by way of open up banking. However, inspite of the supply, info from show display scraping often suffers from inconsistencies and unreliability.

    Frollo is urging the Australian Level of competitors and Client Fee (ACCC), the Data Criteria Overall physique, and area stakeholders to unite round necessary use instances.

    “Rather than remaining typical throughout all information with restricted sensible software program, we should always detect probably the most impactful use situations and performance collaboratively to deal with the actual info gaps and high-quality difficulties that hinder their realisation,” Thrassis stated.

  • Pure Retirement lifts fairness release LTVs up to 48%   – Home finance loan Method

    Pure Retirement has lifted mortgage-to-worth ratios on a single of its fairness release ranges on new authentic developments and additional progress borrowing.  

    The lender states its Basic life time residence loans now permit for an applicant aged 70 can receive LTVs up to 38% (up 2%), and candidates from 80 can entry LTVs up to 48% (additionally, up 2%).  

    These loans carry no upfront bills, no association bills and seem with cost-free valuations.  

    The group provides that for current Vintage customers, association charges on new extra improvements have been scrapped and shoppers can even accessibility extra developments at up to 90 many years of age for the youngest borrower — offering completion takes place on or forward of age 89 a very long time in addition to 364 days.  

    Pure Retirement head of merchandise Chris Buchanan claims: “Our Traditional merchandise has repeatedly been a number one life time residence loan answer, and the improved LTVs available, up to 48%, will open up up the Common merchandise to extra women and men and provides them better possibility and worth subsequent our the newest willpower to take out the association cost throughout the fluctuate.”