Tag: and

  • Variances Amongst Reward Resources, Grants, and Financial loans

    Down funds might be 1 of probably the most difficult sections of the homebuying process. We all know that getting a residence expenditures money! Luckily, you don’t all the time have to empty your reductions account to reach up with the sum. There are different strategies to protected a down cost, which embrace reward funds, grants, and down cost help packages.
    4-Oct-17-2022-06-32-14-84-PM

    We have laid out all a couple of so you possibly can determine if any of those options are appropriate to your economical predicament as you navigate buying a dwelling. It is important to appreciate that the procedures for these kinds of down cost assist change by state, area, and even metropolis and are topic to alter at any time.

    But upfront of we dive into the particulars, there are a pair of things you must know:

    Not all financial institution mortgage techniques allow down cost assist, reward sources, or grants to be utilized. You’ll need to search recommendation from with your private home mortgage monetary mortgage officer relating to non-public mortgage purposes. 
    Down cost assist often applies solely to a significant residence. Although there are some exceptions to this rule, sometimes speaking, you’re unable to put money into a subsequent dwelling or funding determination residence with down cost steering purposes.

    Gift Resources

    “Gift” is a single of the best four-letter textual content on the market—and for superb trigger! We all recognize acquiring money for distinctive conditions like weddings, graduations, birthdays…or probably simply since we’re a first-time homebuyer and a beloved one wish to help us out.

    Both manner, current funds are an effective way to simply take among the stress off to start out with-time homebuyers. There are, having mentioned that, a handful of measures you must observe when you put together to make use of a essential financial current to your down cost.

    Let us start with what “important monetary reward” positively implies. For typical loans, it’s sometimes outlined as any sum of money that equates to further than half of your full common qualifying cash. For illustration, when you make $3,800 a thirty day interval, then a considerable monetary reward could be any single deposit equal to or larger than $1,900. The reward common for FHA or USDA loans is the whole lot in extra of 1% of the house’s get hold of worth, product gross sales price, or appraisal profit, whichever is decrease. 

    The house finance mortgage financial institution mortgage software course of usually consists of 60 days’ worthy of of financial institution statements, which signifies {that a} house mortgage mortgage supplier or underwriter will need to comprehend the origin of any substantial sums that aren’t accounted for in your historical past of belongings and income. 

    Not to fret—these current cash might be effortlessly acknowledged by way of a gift letter that signifies that this revenue is in level a present and not a mortgage. The letter actually ought to have the gifter’s identify, deal with, cellular telephone amount, relation to you, greenback quantity gifted, and date of the reward. You may very well be required to point out a paper path of the current, so you’ll want to retain receipts and statements.

    There are some parameters on who can provide you funds that you’ll use for a down cost. For typical loans, this current calls for to happen from a member of the family, which might contain anybody from spouses and home companions to move-aunts, adopted cousins, or grandfathers-in-law.

    In addition to presents from household customers, FHA loans additionally allow you to get current cash from a shut shut good friend, your employer, a labor union, or a charitable group. USDA and VA monetary loans allow you to acquire reward funds from nearly anybody—as very lengthy as that individual particular person isn’t included within the family transaction. This disqualifies the house’s vendor, builder, developer, or probably social gathering’s severe property agent.

    Preserve in mind that although you shouldn’t have to spend taxes on the current money, the person or lady providing you the reward may probably, so it’s always intelligent to speak to a tax certified. Your financial institution mortgage officer will probably be joyful to make clear way more about current fund requirements at any time when.

    Grants

    Down cost grants can help fill the void among the many {dollars} to start out with-time homebuyers are able to arrange for a down cost and the remaining down cost stability. Down cost steering grants are equipped by way of authorities companies just like the Section of Housing and Urban Enhancement (HUD) and via nonprofits just like the Countrywide Homebuyers Fund.

    Though these house finance mortgage packages can vary by state, amount, and necessities, they often think about into consideration the residence price and geographic house, in addition to your cash and credit standing ranking. Some grants are additionally supplied for people in chosen professions, this type of as regulation enforcement, firefighting, and EMT.

    Look at together with your level out and native organizations and relevant specialist associations to see if they provide any grant plans that use to you. Your financial institution mortgage officer may also know what these packages contain, so be completely positive to inquire them when you’re intrigued in further information.

    Typically talking, grant plans give down cost assist freed from cost and clear, that means you shouldn’t have to fork out the {dollars} again once more (though you’ll need to learn the nice print). Some applications must have stipulations like a recapture time interval, which signifies the {dollars} is freed from cost and clear provided that you retain within the house for a sure variety of a number of years.

    Financial loans

    Down cost assist monetary loans are a broad class that may counsel various components. They can array from curiosity-free, forgivable loans to desire-free deferred-payment monetary loans and even minimal-fascination worth monetary loans. Some of those programs have eligibility wants. These can incorporate cash limitations, authorised geographic spots, getting a residence down beneath the offered median home price for that area, how considerably funds you possibly can put in the direction of your down cost, and way more.

    Down cost help homebuyer programs can come from: 

    Federal companies
    Point out companies
    Regional firms
    Local neighborhood companies
    Charitable funds 

    In addition, some applications present numerous prospects, along with making use of those money as a cost for closing prices. For a breakdown of what these types of programs are and the way to discover them, try our website online.

    While not every and each initially-time homebuyer will qualify for down cost help—or be fortunate ample to have a beneficiant relative—they’re properly price wanting into. Analyzing all of your decisions proper earlier than plunking down your tough-gained laborious money is a terrific approach to place your ideas at simplicity on the subject of down funds. 

    A dependable APM Bank mortgage Officer is all set to assist you uncover cures that get you into your dream dwelling. Simply click on right here to find an APM Mortgage Officer within the neighborhood of you.
  • Iress and Acre extend partnership – Home finance loan System

    Iress has extended its partnership with Acre to speed up its house finance loan lending.

    Less than the renewed settlement, Iress will mix its house loan sourcing particulars and Iress’s Financial establishment Link into Acre’s intermediaries software program program.

    This will give brokers with improved sourcing and affordability talents, enabling much more efficient circumstance administration.

    Iress head of group enhancement, souring Warren O’Connell suggests: “In at the moment’s monetary pure surroundings, it’s needed that brokers may give their customers essentially the most as much as day and broadest assortment of house finance loan info.”

    “Iress’s collaboration with Acre, alongside with Iress’ unmatched merchandise safety, assures their brokers have as significantly info as possible to make knowledgeable solutions for his or her customers.”

    Acre important authorities officer and founder Justus Brown, offers: “We are thrilled to be able to develop our collaboration to hold the way forward for house finance loan and protection know-how to brokers.”

  • Nottingham BS lowers fees on overseas national and expat products and solutions – Home loan Technique

    Nottingham Creating Culture has produced cost reductions and amendments to its answer geared toward international nationals and returning ex-pats, as completely as its residential products.

    The enhancements see prices decreased by as much as .10% on its five-yr mounted overseas nationwide and returning ex-pat home loan merchandise.

    In addition, the constructing tradition has launched a 85% monetary loan-to-value (LTV) tier cost for overseas nationals though degree reductions of as much as .23% have been created on residential acquisition gadgets.

    Nottingham Constructing Society product sales director Alison Pallett suggests: “The willpower to scale back fees displays our ongoing dedication to fulfill the evolving necessities of brokers and debtors alike.”

    “We totally grasp the numerous difficulties confronted by our patrons, whether or not they’re returning expats looking out to ascertain a property once more within the United kingdom, competent workers from overseas on the lookout for to construct a occupation and commit of their future, or United kingdom residents navigating the sophisticated dwelling possession journey.”

  • MFAA celebrates Victoria and Tasmania award winners

    MFAA celebrates Victoria and Tasmania award winners | Australian Broker Information

    News

    MFAA celebrates Victoria and Tasmania award winners

    Brokers, mortgage suppliers, BDMs amongst these recognised

    MFAA celebrates Victoria and Tasmania award winners

    The MFAA Point out Excellence Awards for 2024 concluded with a celebration in Melbourne, during which the winners for Victoria and Tasmania had been honoured.

    Recognising excellent achievements in customer support, professionalism, ethics, development, and innovation, the MFAA Excellence Awards introduced 18 winners.

    The Victoria and Tasmania MFAA Excellence Awards marked the ultimate occasion in a sequence of 5, held nationwide greater than six months.

    “At every of our MFAA Excellence Award features, the excellent willpower our customers should each equally their shoppers and our enterprise is obvious, and tonight is not any exception. An enormous congratulations to all our winners and finalists,” Pannek reported.

    Among the winners have been being Evelyn Clark from Everlend (pictured above left) who took out the Younger Skilled Award and Benard Desmond from Blank Fiscal (pictured increased than correct) gained the Residential Finance Broker Award.

    All winners from the Victoria and Tasmania awards will advance to the nationwide quantity, competing on the MFAA National Excellence Awards in Melbourne on Thursday, July 25, subsequent the MFAA countrywide conference.

    The MFAA extends its gratitude to the companions of the MFAA Excellence Awards: ALI Team, ANZ, Australian Broker, Bankwest, BOQ Team, Commonwealth Bank, Connective, Helia, La Trobe Economic, Macquarie Bank, Mortgage Decision, MPA, Nationwide Australia Lender, Pepper Money, Prospa, QBE, Resimac, and Instructors Mutual Financial establishment.

    The 2024 Victoria and Tasmania MFAA Point out Excellence Award winners are:

    Small enterprise Enhancement Manager Award – Aggregator
    &#13
    Daisy Yu, Finsure

    Company Improvement Manager Award – Lender/Guidance Provider Provider
    &#13
    Julie Nguyen, Macquarie Lender

    Professional & Tools Finance Broker Award
    &#13
    Katie Liu, JKK Remedies

    Community Winner Award
    &#13
    MTA Property finance mortgage Brokers

    Shopper Services Award – Organization
    &#13
    Good Lending

    Purchaser Support Award – Person
    &#13
    Spiro Kolokithas, What If We Finance

    Diversified Business Award
    &#13
    MTA Mortgage mortgage Brokers

    Finance Broker Small enterprise Award
    &#13
    Cinch Financial loans

    Fintech Lender Award
    &#13
    ubank

    Mortgage Administrator Award
    &#13
    Rohan James, Trustworthy Money Preference

    Important Loan supplier Award
    &#13
    Macquarie Financial establishment

    Mutual/Credit score Union Loan firm Award
    &#13
    Heritage Bank

    Newcomer Award
    &#13
    Benjamin Simmons, Bayland Finance

    Non-Important Loan firm Award
    &#13
    Bankwest

    Regional Finance Broker Award
    &#13
    David Fraser, Bayland Finance

    Household Finance Broker Award
    &#13
    Bernard Desmond, Blank Fiscal

    Get the very best and freshest property finance mortgage info delivered right into your inbox. Subscribe now to our FREE on a regular basis e-newsletter.

    Similar Stories

    Preserve up with essentially the most up-to-date information and gatherings

    Sign up for our mailing guidelines, it’s completely free!

  • BoE resists temptation to cut and holds rate at 5.25% – House loan Finance Gazette

    Desire charges have been held at 5.25% – a sixteen yr excessive – for the seventh time in a row by the Financial establishment of England’s Monetary Coverage Committee (MPC).

    Bank-of-England-BoE-Union-Jack-flag-re-sized-620x330.jpg

    The MPC voted by a the overwhelming majority of seven to two to proceed to preserve the lender rate on preserve. It is known the 2 members within the minority backed a discount in prices to 5%.

    Property finance loan present market contributors have prolonged stated {that a} tumble within the worth of inflation shut to the Bank of England objective rate of two% would give the BoE assurance to cut the bottom rate.

    Whilst the newest fall in inflation lower than unusual state of affairs may need introduced on a worth cut back – the MPC (as generally predicted) decided that with a regular election in a make a distinction of weeks, a stage modify should maintain out.

    Current market Economic  Solutions principal authorities Paresh Raja commented: “Over the previous 10 months, because the Bank has decided to retain the muse cost at 5.25% on seven consecutive events, it has been distinct that it’s going to maintain off cuts for as intensive because it needs to.

    “But with inflation now at 2%, and the European Central Bank possessing made cuts, the stress is mounting – all indicators advocate that, the second election turbulence subsides, the Lender will start rate cuts, even though it’s unsafe to select that without any consideration. All eyes will likely be on its upcoming assembly on 1st August.”

  • AI has organizations — and personnel — considering about reskilling

    The residence mortgage workforce possesses the capabilities and know-how to maneuver the enterprise ahead, however some pockets of challenge embody irrespective of whether or not they’re completely as much as the endeavor at current with know-how, in accordance to new survey outcomes.

    Some execs strike by waves of layoffs within the mortgage market can select coronary heart that numerous organizations intend to make use of the service of in 2024, however they and their leaders even have an understanding of know-how is advancing at a fast clip. Schooling and upskilling staff in buy to most interesting think about fringe of synthetic intelligence’s probably will tackle bigger price in sure, however tried-and-accurate communication and management experience cannot be left by the wayside both, the data tells us.

    Research on current workplace tendencies was executed by Arizent, guardian agency of Nationwide Home finance mortgage Information, who surveyed 550 people in seven fiscal corporations segments. The whole included 55 residence finance mortgage gurus concerned in management or choosing choices at their corporations. Respondents answered inquiries revolving throughout a array of subjects, this form of because the competencies of their friends to their operate-from-home place.   

  • The 2-1 vendor-compensated buydown: A effective resource for homebuyers and household sellers

    &#13
    &#13

    Today’s housing market place is undeniably varied from what it was in the middle of 2021 and early 2022. Elevated fascination costs and homes sitting down available on the market for for an extended interval durations of time have changed historically decreased curiosity charges and a extremely sizzling present market characterised by bidding frenzies. No matter whether or not you might be at current a homebuyer, dwelling vendor, or every, it’s possible you’ll probably speculate what this signifies for you. It may counsel that now’s a wonderful time to get achieve of a 2-1 vendor-compensated buydown.

    Buydown fundamentals

    What simply is a buydown? It is when factors—generally known as discounted elements, mortgage mortgage elements, or pay as you go curiosity—are used to purchase down a mortgage’s curiosity degree as a one-time upfront charge. The price of an individual level equals an individual p.c of the principal (genuine financial institution mortgage quantity), which signifies that one specific place on a $100,000 financial institution mortgage would equal $1,000. While that’s a constant profit throughout mortgage suppliers, the amount that an individual place will decrease a mortgage’s fascination worth can vary regarding mortgage firms and relies on further elements these sorts of because the monetary mortgage type and current costs. It can also be essential to take observe that there could also be buydown maximums.

    Then, there are numerous methods for the price of a buydown to be paid, which incorporates borrower-paid and vendor-paid. Just as they appear, debtors go over the value tag with a borrower-compensated buydown, and sellers defend the fee with a seller-compensated buydown.

    The celebration accountable for cost isn’t the one element that may differ—totally different buydown kinds can be found. They may be long-lasting or momentary and apply to set-level and adjustable-price mortgages. With a eternal buydown, the curiosity worth will get acquired down for the entire private mortgage phrase. In comparability, the fascination charge will get bought down for particular many years of the mortgage time interval with a brief buydown. A 2-1 buydown is a frequent non everlasting software.

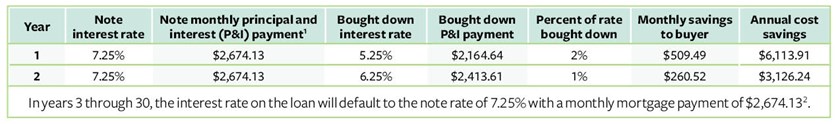
    Securing a mortgage with a 2-1 buydown will permit for the fascination cost to be decreased via the first two years of the monetary mortgage time interval proper earlier than growing to the everlasting quantity, often known as the remember degree, in yr just a few. The need quantity is steadily decreased by 2% within the preliminary yr, adopted by 1% within the 2nd calendar yr.

    2-1 buydown occasion

    Here’s a 2-1 buydown living proof for a 30-12 months set-amount financial institution mortgage time interval the place the elements value $9,240.15:

    2-1 Buydown Chart

    Likely advantages of a 2-1 vendor-paid out buydown

    Now that we have now lined some buydown fundamentals and reviewed an living proof, allow us to purchase a more in-depth look at how a 2-1 vendor-compensated buydown could possibly be worthwhile in a real property transaction presently.

    For prospects, a 2-1 vendor-paid out buydown aids them ease into homeownership. Preliminary month-to-month funds are down beneath their lengthy lasting common month-to-month cost, incomes the house mortgage far more cost-effective upfront. And as a last outcome, they spend fewer fascination above the lifetime of the non-public mortgage, in distinction to a financial institution mortgage with out the necessity of a buydown that has the similar discover need quantity and principal. A 2-1 seller-compensated buydown is mostly a safe manner prospects can get achieve of quickly securing a lower fascination degree and month-to-month cost in a rising cost ambiance.

    Sellers may benefit from a 2-1 buydown, additionally. Providing a single on their household itemizing could make it additional eye-catching to prospects and allow it stand out from different listings, particularly when fascination charge hikes are a reality. Or, if a purchaser requests for a vendor to produce one specific and the seller accommodates the request, the buyer could possibly be extra possible to purchase the home. Numerous households are sitting down available on the market for an extended time period of time, and a 2-1 seller-paid buydown may be a wonderful household-selling tactic.

    In normal, a 2-1 vendor-paid buydown could possibly be a win-earn for each equally homebuyers and household sellers. If you’re intrigued in mastering further about having benefit of this spectacular gadget, be part of with an Evergreen financial institution mortgage officer now. We additionally give 1- and 3-2-1 buydowns. Just one in all our residence financial institution mortgage specialists can help clarify the ins-and-outs so that you’re properly-educated and established up for success in your homeownership journey.

    Prices are as of 10/19/2022 and matter to rework with out the necessity of see, chosen problems make the most of. Not all shoppers will qualify for the phrases well-known. 1. Regular cost is principal and need (P&I) solely, depending on purchase fee of $490,000 with a monetary mortgage complete of $392,000, 7.25% mounted charge, 30-12 months phrase, APR 7.551%, and 20% down cost. 2. Payment doesn’t include taxes and insurance coverage plan charges. The actual cost quantity will likely be larger. Some state and county highest financial institution mortgage amount restrictions may make the most of. The cost circumstance is for illustration features solely. Inquire for present fees. Not all merchandise supplied. Method is subject material to enhance.

    &#13

  • Financial loan restrictions for FHA, Standard and VA Mortgages

    For Conventional monetary loans, boundaries are actually at $766,550 proper earlier than shifting into Jumbo territory. You can get a dwelling for $806,842 putting 5% down and nonetheless be Common.

    Now for FHA the monetary loan limit is $498,257. you should purchase a home for $516,328 putting 3.5% down now

    A VA mortgage loan can go as much as $2,000,000 with no cash down.

    100% funding as much as $2,000,000

    With the worth of something heading up, it’s nice to see the Government escalating the monetary loan limitations to accommodate the higher promoting value


    tune in and be taught at https://www.ddamortgage.com/website

    didier malagies nmls#212566

    dda property finance loan nmls#324329

    Ask a Property finance loan Question

    Use the variability underneath and we are going to give your our expert options!

    Start out Your Mortgage

    with DDA at the moment

    Your regional Mortgage loan Broker

    Property finance loan Broker Largo

    See our Testimonials

    Seeking for additional features? Hear to our prolonged podcast! 

  • “Shared ownership left me £16,000 worse off and unable to promote”

    For lots of aspiring owners, shared ownership has been a good way to take the first step onto the property ladder with a small deposit.

    But as many have found, issues can come up later whenever you attempt and promote your own home.

    Samantha Henry has been struggling to shift her shared ownership flat for nearly two years.

    The 40-year-old entrepreneur was initially very excited to give you the option to purchase a 25% share of a £465,000 one-bed flat in 2018, in Hornsey, north London.

    But she’s since misplaced half of her deposit and all the cash she put into her mortgage – and remains to be struggling to promote up.

    “At the time this felt like a dream, particularly because the flat was in a constructing which allowed canine,” Samantha defined.

    “I used to be in my mid-thirties and lastly residing alone. I knew it was the house for me. But after I got here to promote, it was one thing of a nightmare.”

    With shared ownership, you buy a share of a property, and then pay lease on the remaining quantity to a landlord, normally to a housing affiliation.

    You can begin off with 25% which you’ll then improve at a later date through ‘staircasing.’

    Samantha purchased a 25% share of her flat from Sanctuary Homes, with a ten% deposit of £11,625.

    “Over the years, each the lease and service expenses have gone up,” she mentioned. “The mixture of mortgage, lease, service expenses and family payments means there’s so much to price range for. My monetary circumstances imply I’ve not been ready to staircase.”

    Samantha wished to promote so she may transfer to Essex to be nearer to her household. It’s now develop into pressing.

    Samantha Henry. Credit: Tatlers, Crouch EndThe most up-to-date estimates worth Samantha’s residence at round £40,000 – £65,000 lower than she paid for it [Credit: Tatlers, Crouch End]

    She mentioned: “This is sort of urgent now, as my stepfather died in 2022, my sister is de facto unwell, and my mum wants assist.

    “I additionally run my canine equipment enterprise, Pup Chic Boutique, from my flat, it will get fairly exhausting whenever you reside and work in such a small area. I desperately want a property with a second bed room.”

    When Samantha first launched into promoting in March 2021, the housing affiliation stipulated she had to pay for an unbiased valuation by a surveyor from RICS.

    Nathan Emerson, from property agent physique, Propertymark, explains: “The largest drawback of shared ownership is the ‘mechanism to go away it.’ The technique of promoting just isn’t simple. You have to get an expert valuation from RICS, and the surveyor will advise on the worth of the property.”

    The housing affiliation will then use this to set the sale worth.

    Emerson added: “This could cause points if a possible purchaser affords lower than the valuation determine. It may probably even put you vulnerable to discovering your self in unfavourable fairness if the value has fallen whenever you come to promote. You may find yourself with lower than what you at the moment owe in your mortgage – and a stability to discover.”

    Initially, the surveyor informed Samantha her property was value £415,000, however when she identified a neighbour had simply bought an an identical flat for £440,000, he agreed to improve hers to the identical quantity.

    Samantha mentioned: “While I used to be nonetheless promoting at a loss, I took solace from the very fact I used to be going to get my deposit again, and had saved cash in contrast to renting within the space.”

    If you need to promote a shared ownership residence, you’ll be able to put up for sale at any time, no matter your share. Those who personal 100%, can normally promote it on the open market by an property agent.

    If, nonetheless, you personal much less, you need to notify your landlord so as to give them an opportunity to discover an eligible purchaser to your share – often called a ‘nomination interval.’

    The growth in Hornsey, north London [Credit: Tatlers, Crouch End]

    Pete Mugleston from onlinemortgageadvisor.co.uk, mentioned: “This is normally 4, eight or 12 weeks, relying on the lease. If the owner does discover a purchaser, the sale worth will likely be not more than the present market worth of your share. If no purchaser is discovered inside this era, you’ll be able to promote your share your self on the open market.”

    Samantha was required to give Sanctuary Homes eight weeks to attempt and promote her flat.

    “But I didn’t have any viewings throughout that point,” she mentioned. “When this era was up, I then had to get written affirmation that I may enlist the assistance of an property agent.”

    Initially, Samantha employed a high-street agent, however regardless of getting numerous viewings, there was no curiosity. She then modified to a extra native agent who discovered a purchaser inside a month.

    “This was nice information, as by the point I bought a proposal, in January 2022, I had reserved a home that I favored in Halstead, Essex,” she mentioned. “This was one other shared ownership residence.”

    At this stage, Samantha bumped into difficulties once more, as after paying for a brand new valuation, the client subsequently disappeared. This resulted in her shedding the home in Halstead.

    Just just a few weeks later, in April, the property agent discovered a brand new purchaser, trying to buy with a 100% mortgage.

    “As this was not a shared ownership purchaser, the foundations stipulated I had to pay for a valuation with the housing affiliation’s chosen valuer,” mentioned Samantha. “In simply over 12 months, I ended up spending virtually £1,000 on valuations. I additionally misplaced £500 on the deposit I’d put down on the home.”

    In April final 12 months, Samantha discovered one other property she wished to purchase.

    “I fell in love with a wonderful countryside place in Coggleshall, Colchester,” she mentioned. “As the whole lot appeared to be going properly with the client for my Hornsey flat, I went forward with paying for searches. But then my purchaser determined he wanted to pay for one more valuation on my flat.”

    When this was carried out in June final 12 months, Samantha’s flat bought valued at simply £400,000. This finally resulted within the sale falling by.

    “The buy of the Coggleshall home additionally fell by,” she mentioned. “It was then a case of getting to return to the drafting board.”

    Last autumn, after mortgage charges sky-rocketed, Samantha determined to ask the housing affiliation if she may drop the value of her flat to £400,000. They lastly agreed to this in December.

    “Fortunately, in January, I discovered a brand new purchaser for my flat,” she mentioned. “I additionally discovered a brand new home to purchase in Halstead.”

    Samantha is now going by the entire house-buying course of once more.

    “My foremost fear is that my present mortgage supply is just legitimate till March 2023, so I’m on a deadline to change,” she mentioned. “The excellent news is, all of the searches have been accomplished, and the solicitors are working as quick as they will.

    “Despite this, I’m not prepared to begin celebrating as a result of a part of me fears it’s all going to come crashing down once more.”

    One of the massive points for Samantha over the previous two years has been the pace at which issues occur.

    “The housing affiliation might be gradual to reply to issues as the whole lot appears to take ‘10 working days,’” she mentioned. “If a purchaser is buying lower than 100% of the property, they want to be accepted by the owner. All of this takes time.”

    “I’m promoting at a loss”

    Samantha can also be annoyed that she’s promoting at a loss.

    “I now have solely round £5,000 fairness in my flat,” she mentioned. “Not solely am I shedding half of the deposit, however I’m additionally shedding the £9,303 that I paid into the mortgage.

    In whole, her losses exceed £16,000.

    “My recommendation to anybody contemplating shared ownership is to view it as a longer-term objective. If you may get a spot the place you’ll be able to afford to staircase, and finally get to 100%, then I feel it might be value it. I feel on this situation, the promoting course of is usually a lot smoother.”

    A spokesperson for Santuary Home mentioned: “We will proceed to work with our buyer on the sale of this property and can reassure her that we’re dedicated to providing any assist we are able to.”

    Important info

    Some of the merchandise promoted are from our affiliate companions from whom we obtain compensation. While we intention to characteristic among the finest merchandise out there, we can not evaluation each product available on the market.

    Read extra

  • 2024 Conservative and Labour Manifestos on New Households

    Published on 18 June 2024 by Ray Boulger

    2024 Conservative and Labour Manifestos on New Homes

    First, a normal comment on manifesto presentation: Labour’s manifesto is considerably extra superb than the Conservatives, with considerably improved use of expertise and loads of much more images, incomes it an a lot simpler examine. The Conservatives might want to perceive courses from this for the up coming widespread election. 

    Some presents on housing are extraordinarily equal from the 2 features, many others are constructed to perform the precise consequence, however with a singular goal on attaining it and of sophistication some procedures are distinctive to 1 get collectively. 

    On the present facet, Labour has a extra in depth plan, with concepts to replace the Nationwide Organizing Plan Framework, along with a “presumption in favour of sustainable growth”, no matter what that implies. 

    An enormous result in of planning delays is a shortage of employees members in organising departments and so Labour’s technique to fund additional arranging officers is welcome, however this have to be paid for by getting ready prices which defend the expense of provision considerably than the manifesto’s guarantee of hypothecating the extra 1% SDLT Labour methods to demand overseas potential consumers. 

    Labour has additionally delivered higher depth of during which new development will take spot, with a additional actual trying approach to working with awful good high quality land within the eco-friendly belt and superior sharing of getting ready achieve with group communities. 

    Labour is promising 1.5m new homes in regards to the subsequent 5 years and the Conservative 1.6m. This is an enhance of all-around 50% on the current make degree and considerably as it could be terrific to see these figures achieved, I worry they’re pie within the sky. To attain this quantity of progress we would want to must see a reemergence of SME builders, who utilized to offer a considerably elevated proportion of latest properties, however now sometimes battle with elevating enhancement finance. 

    Extra encouragement for customized made set up and self-develop would additionally help to enhance the entire develop portions. 

    Developers get their foot off the pedal in a short time when demand drops, as was evidenced in This autumn 2022 following the Liz Truss debacle. For that motive, facilitating glorious demand from prospects for brand spanking new properties is simply as necessary as the potential to assemble them. 

    Just one protection offered by each get-togethers is a Govt Home mortgage Assurance Plan, with the Conservatives mainly declaring they’ll proceed with the latest plan and Labour declaring it’ll introduce a long-lasting, complete scheme. 

    When this scheme was launched in 2014 it was a extremely welcome catalyst to kick start 95% LTV mortgages, which just about disappeared adhering to the 2008 financial disaster. Considering that then, the personal sector has created new 95% LTV assure schemes, like Possess New and Deposit Unlock for brand spanking new create qualities. Several mortgage firms choose to self-insure or use private sector dwelling mortgage insurance coverage coverage as a result of truth of the price and limitations within the present scheme. 

    House mortgage defaults and repossessions have been traditionally fairly very low contemplating that the Govt Promise Scheme was launched and so on a purely monetary basis it is rather more likely to have been profitable for the Government, even simply earlier than interested by the opposite monetary positive aspects of reinvigorating the 95% LTV present market. However, I take into account it’s a error for Labour to say the plan shall be lasting the Govt should objective to advertise the mortgage mortgage market when wanted alternatively than method to be a long run participant. 

    Of far more curiosity is the Conservative proposal to reintroduce a variation of the Assistance to Obtain scheme, which addresses the affordability problem while the Warranty Plan doesn’t. Conservatives have realized from the personal sector and, in contrast with the previous scheme, the brand new scheme shall be part funded, reported to be at 5%, by builders. This ought to actually additionally finish good minded criticism that the scheme optimistic points builders much more than FTBs. 

    Assuming it could do the job in an identical option to the previous scheme, the builders’ contribution could possibly be utilized to enhance the circumstances, maybe by extending the curiosity freed from cost interval of the 20% equity 2nd demand. Due to the very fact the 4.49x optimum cash a number of relies solely on the 75% to start out with cost, this scheme has considerably far more impression on enhancing affordability than the Assure Plan. On high of that, the detrimental fairness risk is decreased primarily as a result of within the operate of the property price slipping extra than 5% furthermore the money repayments created on the property finance mortgage, 20% of any discount could be endured by the Govt.  

    Equally events are promising to ban new ground rents and it’s disappointing the month-to-month invoice to do that was shed in Clean Up. However, neither get collectively has promised to abolish Estate Costs on new developments however the brand new bill ought to actually abolish this demand (and any comparable demand invented with a particular establish) and group authorities compelled to think about onboard these obligations by adopting the roadways, and so on. The extra time these bills proceed the longer occupiers of some new estates shall be having to pay 2 occasions for the equivalent difficulty – Council Tax and Estate Demand. 

    Eventually, one factor which was regrettably missing from equally manifestos was any motivation to amend LISA ideas to make them swimsuit for 2024. The most necessary rework important is an improve within the highest spend money on value licensed from the latest £450,000, to remain away from anyone buying over that worth remaining fined an highly effective 6.25% by the Authorities in the event that they use their LISA private financial savings as aspect of their deposit.  

    Categories:Residence Industry, Bank of England, Ray Boulger