Tag: and

  • April Home loans and SPF Private clients agree partnership – Mortgage loan Finance Gazette

    April Mortgages has introduced a brand new partnership with SPF Private Clients.

    Mark-Eaton-New-v1-560x330.jpeg

    The partnership signifies that SPF advisers could have entry to April Mortgages’ fluctuate of very long-phrase preset charges. In addition, advisers who use the Legal & Normal Home loan Club will be capable to refer appropriate clients to SPF Personal Shoppers, because the adviser is portion of the L&G Referral Pro panel.

    This signifies consumers can profit from entry to merchandise they profit, although the referring adviser will get a fee, with no chance of cross or repeat product sales.

    April Home loans presents a variety of mounted price merchandise starting from 5 to fifteen years, and LTVs of as much as 95% for receive and 85% for remortgages respectively.

    Debtors who transfer home or use their very personal cash to repay the property finance loan are exempt from Early Repayment Expenses, when the mounted cost on provide decreases immediately because the borrower drops into lower LTV brackets as they spend off their stability or the house beneficial properties in price.

    Commenting on the partnership April Home loans chief working officer Mark Eaton acknowledged: “April Mortgages is obsessed with bringing real peace of mind to the British isles dwelling finance loan sector, and performing with main advisers like SPF Personal Shoppers is major to our applications.

    He added: “Not solely will the SPF advisers have receive to our fashionable assortment of merchandise, however advisers from all through the market will likely be succesful to refer applicable clientele by the use of the L&G Referral Pro panel. Growing our distribution on this means implies we are able to produce peace of head and improved certainty to elevated numbers of debtors and advisers.”

  • Shawbrook expands conditions for new and qualified landlords   – Mortgage System

    Shawbrook has rolled out a group of standards changes aimed toward supporting new landlords and seasoned patrons who wish to develop their portfolios.  

    The knowledgeable monetary establishment has broadened its scope for multi-unit freehold blocks — and will now acknowledge apps from to start out with-time landlords for these varieties of homes conserving as much as six fashions.   

    It has additionally amplified the utmost LTV to 75% for industrial houses, providing monetary loans available on interest-only, portion-capital, or comprehensive-capital reimbursement.   

    This switch helps landlords in diversifying their portfolios with skilled properties, with prices starting from 7.39% at 75% LTV, the mortgage supplier states.  

    The agency has additionally expanded its proposition for lending on social housing, “recognising that tiny private landlords are convention this rising demand”.   

    Its difficult get-to-enable merchandise are on the market on one permit or properties in a number of occupation qualities let to social housing or supported dwelling operators.  

    Last however not least, the mortgage supplier states that has “launched new standards that helps landlords selecting out to accumulate the shares of a property-owning group, versus the non-public attributes by themselves with no naked minimal monetary mortgage dimensions.   

    “This strategic modify goals to provide landlords with a assortment of lending options, providing skilled finance to their quite a few client base.”  

    Shawbrook head of proposition Daryl Norkett elements out: “These enhancements not solely show our dedication to convention the evolving needs of knowledgeable landlords but additionally admit the market’s adaptation to a elevated curiosity value ambiance.   

    “We’ve noticed a necessary improve in need for houses in varied occupation, from 27% of our BTL originations in 2022 and 2023, to 34% in 2024.   

    “Additionally, our evaluation final August disclosed that 37% of landlords looking for portfolio enlargement ended up fascinated in business houses for diversification.  

    “By increasing our conditions, we’re producing extra prospects for landlords to diversify and improve their portfolios, regardless of if by better-yielding residential property, business attributes, or social housing.”  

  • Shawbrook boosts standards for new and portfolio landlords   – Home loan Finance Gazette

    Shawbrook has rolled out a sequence of necessities enhancements aimed toward supporting new landlords and seasoned traders who need to broaden their portfolios.  

    rental-income-620x330.jpg

    The skilled lender has broadened its scope for multi-device freehold blocks — and will now take functions from very first-time landlords for these types of qualities conserving as much as six models.   

    It has additionally larger essentially the most LTV to 75% for industrial homes, giving loans on the market on interest-only, part-cash, or complete-capital reimbursement.   

    This go helps landlords in diversifying their portfolios with skilled attributes, with costs beginning up from 7.39% at 75% LTV, the lender claims.  

    The enterprise has additionally expanded its proposition for lending on social housing, “recognising that little private landlords are meeting this escalating demand”.   

    Its superior make investments in-to-allow merchandise are on the market on solitary allow or homes in a number of occupation attributes let to social housing or supported residing operators.  

    Eventually, the loan supplier claims that has “launched new standards that helps landlords selecting to acquire the shares of a assets-possessing group, versus the particular person properties by themselves with no minimal mortgage measurement.   

    “This strategic rework goals to supply landlords with all kinds of lending alternate options, providing specialist finance to their assorted buyer basis.”  

    Shawbrook head of proposition Daryl Norkett particulars out: “These enhancements not solely exhibit our motivation to convention the evolving necessities of certified landlords but in addition admit the market’s adaptation to a larger curiosity value setting.   

    “We’ve observed a sizeable rise in want for homes in varied career, from 27% of our BTL originations in 2022 and 2023, to 34% in 2024.   

    “Additionally, our examine previous August found that 37% of landlords trying for portfolio development had been being fascinated in industrial qualities for diversification.  

    “By increasing our circumstances, we’re constructing further alternatives for landlords to diversify and enhance their portfolios, irrespective of whether or not on account of better-yielding family belongings, industrial homes, or social housing.”  

  • Suffolk BS launches shared possession personal loan, cuts holiday getaway permit and expat offers    – Property finance loan System

    Suffolk Developing Society has launched a brand new shared possession 95% LTV 5-yr property finance loan merchandise as properly as slicing chosen offers on different shared possession, holiday let and expat offers by as much as 29 basis particulars. 

    The mutual’s variations shield: 

    95% LTV shared possession five-year restore at 5.25% for 60 months 

    95% LTV residential five-calendar yr resolve (C&I) diminished by 10bps to five.39% for 60 months 

    95% LTV shared possession two-calendar yr repair lowered by 15bps to five.60% proper up till 31 Oct 2026 

    80% LTV getaway permit five-12 months mounted lowered by 10bps to five.69% for 60 months 

    80% LTV expat buy-to-let 5-12 months fastened slash by 29bps to five.80% for 60 months 

    Suffolk Creating Culture head of intermediary relations and house finance loan product sales Charlotte Grimshaw says: “In the present market, affordability generally is a true barrier to many to start out with-time shoppers.

    “Having a five-calendar yr fastened shared possession selection accessible assists to produce not simply additional peace of head on their home loan funds, but in addition will assist with affordability.  

    “By additionally drastically minimizing our expat purchase to permit 5-calendar yr services or products, we’re extra supporting British expats dwelling and functioning abroad on this area of interest place, whether or not they’re looking out to put money into a house again once more house for rental revenue, or by now have a residence they allow out. 

    “Whatever a buyer’s borrowing calls for might maybe be, our crew of information underwriters assesses each single case individually.”  

  • Benham and Reeves – Mortgage loan Finance Gazette

    1st-time shoppers (FTBs) climbing on the residence ladder in London went up by 24% in 2022/2023, reaching a 20-yr excessive with 181,000 securing their spot, exploration by Benham and Reeves reveals.

    first-time-buyers5-620x330.jpg

    The evaluation, which focused on probably the most present authorities figures on FTB market exercise, recognized that London’s FTBs actually do not require to be incentivised to get a foot on the ladder, with business exercise acquiring elevated notably of late.

    Although that is the state of affairs, the upcoming election has seen the Conservatives pledge to scrap stamp obligation on buys as much as £425,000, though Labour will give FTBs preliminary dibs on new development houses forward of merchants.

    The typical age of a FTB in London all through 2022/2023 was 35.3 yrs earlier, up from 33.8 a long time the previous calendar 12 months and 32 years outdated two a very long time previously in 2003/2004.

    In the meantime, the analysis reveals that London’s FTBs accounted for 21% of full FTB present market exercise discovered in the middle of the calendar 12 months – the premier proportion witnessed as a result of 2014/2015 and the fourth main within the final 20 years.

    In distinction, the choice of FTBs exterior of London fell by -1.8% on an once-a-year basis, marking a 2nd yearly drop, with the 693,000 who did get a foot on the ladder additionally at the moment being the most cost effective complete as a result of the pre-pandemic present market in 2019.

    Benham and Reeves director Marc von Grundherr suggests: “It’s fairly outstanding that regardless of London boasting the utmost residence promoting costs within the land, and with the additional issues of bigger dwelling loan costs, the stage of FTB exercise considered of late has improved vastly.”

    “This has no query been served by the reality that London home values have cooled, presenting an exquisite choice for these seeking to climb the ladder. But it additionally demonstrates the desirability of London among the many shoppers and it’s this desirability that makes it one of the crucial resilient residence markets on a worldwide scale.”

    “So while we could effectively now see a wonderful provide of political pandering to FTB within the lead as much as the election, the consequence will not be more likely to affect the momentum that has been making throughout the London present market relating to these individuals producing their preliminary bricks and mortar receive.”

  • Lloyds Banking Team appoints Dean as head of housing and sustainability   – Mortgage loan Finance Gazette

    Lloyds Banking Team has appointed Andy Dean as its new head of housing & sustainability.   

    Andy-Dean-crop-620x330.jpg

    Dean joins from Nationwide Making Modern society, the place by he’s presently head of intermediary help & new assemble for the mutual and its acquire-to-permit arm, The Mortgage loan Performs.  

    He has been accountable for main the society’s new-create agenda as a result of 2018, as successfully as main its dealer assist teams, which features a huge group of small enterprise development managers.  

    Dean has labored for 16 yrs on the mutual, from 2008, in a assortment of roles these as an organization growth supervisor and a key account supervisor.  

    Prior to that, he labored as a small enterprise development supervisor at Edge Residence Loans for 2 a few years commencing in 2006.  

    Dean select up his publish on the monetary establishment in September and will report proper to its dealing with director, intermediaries Esther Dijkstra.  

    His appointment follows the retirement of Andy Mason in April, who nonetheless left the monetary establishment quickly after 30 many years. 

    Dijkstra claims: “The intermediary residence loan business is of crucial significance to us, incorporating Andy’s encounter and deep sector know-how to our employees will assist us go on to journey developments and initiatives that stick with it to reinforce our help prospects, brokers and the home loan market.”  

    Dean has additionally served on the Middleman Mortgage Creditors Association’s administration committee for the previous 4 many years.   

  • Benham and Reeves – Mortgage Method

    Initially-time potential consumers (FTBs) climbing on the home ladder in London went up by 24% in 2022/2023, reaching a 20-calendar 12 months excessive with 181,000 securing their location, analysis by Benham and Reeves reveals.

    The investigation, which targeting the most recent governing administration figures on FTB market train, discovered that London’s FTBs actually do not should should be incentivised to get a foot on the ladder, with market place train possessing improved notably of late.

    Although that is the case, the approaching election has discovered the Conservatives pledge to scrap stamp obligation on buys as much as £425,000, though Labour will give FTBs initially dibs on new growth homes forward of traders.

    The widespread age of a FTB in London in the midst of 2022/2023 was 35.3 a long time earlier, up from 33.8 a number of years the previous calendar 12 months and 32 yrs earlier two a very long time in the past in 2003/2004.

    Meanwhile, the examine reveals that London’s FTBs accounted for 21% of full FTB present market exercise seen by the 12 months – the most important proportion seen on condition that 2014/2015 and the fourth greatest within the last 20 yrs.

    In distinction, the vary of FTBs exterior the home of London fell by -1.8% on an yearly basis, marking a 2nd yearly drop, with the 693,000 who did get a foot on the ladder additionally changing into the most cost effective total contemplating the truth that the pre-pandemic market place in 2019.

    Benham and Reeves director Marc von Grundherr suggests: “It’s reasonably distinctive that no matter London boasting the utmost residence costs within the land, and with the supplemental troubles of higher dwelling finance mortgage premiums, the stage of FTB exercise noticed of late has elevated significantly.”

    “This has no query been assisted by the reality that London home values have cooled, presenting a wonderful alternative for these individuals trying to climb the ladder. But it additionally demonstrates the desirability of London amid customers and it’s this desirability that might make it simply some of the resilient property markets on a world scale.”

    “So while we could probably now see a wonderful supply of political pandering to FTB within the direct as much as the election, the consequence just isn’t more likely to have an effect on the momentum that has been creating throughout the London business when it arrives to all these creating their to begin with bricks and mortar buy.”

  • Surge in tax frauds prompt warnings from CPA Australia and NAB

    Surge in tax scams prompt warnings from CPA Australia and NAB | Australian Broker Information

    News

    Surge in tax ripoffs prompt warnings from CPA Australia and NAB

    Younger Australians at most danger this submitting 12 months
    Surge in tax scams prompt warnings from CPA Australia and NAB

    As tax 12 months methods, Australians are getting urged to proceed being vigilant from an enhance in subtle frauds specializing in taxpayers. Both equally CPA Australia and NAB have highlighted the relevance of recognizing rip-off tries and shielding personal data, as reviews of fraudulent motion are on the rise.

    In a current episode of CPA Australia’s “With Fascination” podcast, ATO’s assistant commissioner of cyber governance, Joda Walter, acknowledged that ATO-branded SMS and electronic mail messages with inbound hyperlinks to fake myGov web pages are between probably the most prevalent fraud techniques. Bogus social media accounts posing because the ATO and myGov have additionally develop to be frequent on platforms like Fb and X.

    Identifying respected messages from the ATO could be powerful, however there are numerous indicators to assist discern authenticity. E-mail or SMS messages with grammatical errors or unconventional language are almost definitely scams. The ATO no prolonged contains hyperlinks in unsolicited SMS messages, so any data with inbound hyperlinks or QR codes is a purple flag.

    Verifying the sender’s cope with for anomalies, this form of as further letters or figures in what seems to be official ATO electronic mail messages, can be essential. Be cautious of messages requesting private or financial particulars urgently, because the ATO won’t ever ever ask for delicate knowledge by way of e-mail or SMS. On social media, search for formal verification ticks on ATO or myGov accounts. Keep in thoughts that the ATO doesn’t discuss private account facets on these platforms.

    If in query, affirm the legitimacy of the message by calling the ATO instantly at 1-800-008-540 or visiting the formal ATO website.

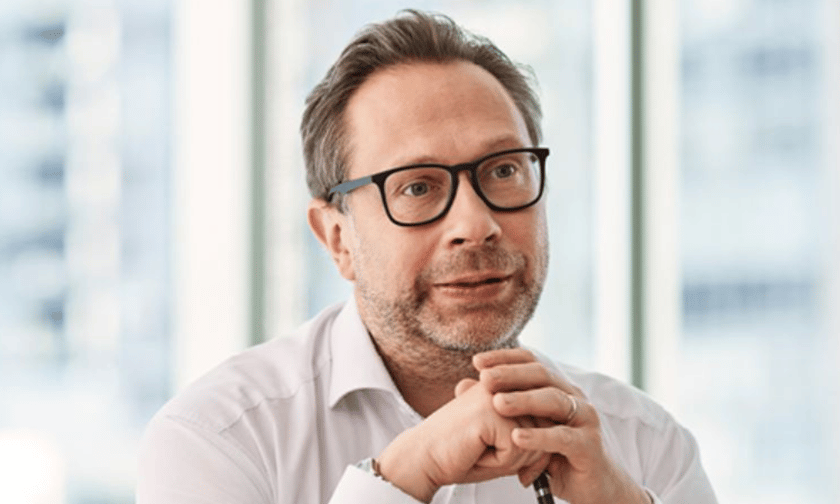
    “Scammers simply benefit from any downside, and at tax time, they aim unsuspecting folks as we speak by unsolicited messages claiming to be the ATO or yet another reliable company. Always stop, assume, and by no means share any personalised particulars, together with your tax file choice or financial institution particulars,” stated CPA Australia spokesperson Gavan Ord (pictured increased than).

    The ATO critiques that Australians aged 25-34 are probably the most possible to slip goal to ATO impersonation frauds, whereas all age teams are focused.

    “It’s alarming that youthful, tech-savvy Australians are sometimes victims of those scams. It’s a wake-up join with for everyone to proceed being vigilant,” Ord claimed. He additionally recommended checking in with aged and susceptible members of the family members to make sure they’re conscious of widespread rip-off methods.

    NAB has noticed that in extra of 1,800 impersonation cons famous common month-to-month to the ATO. Rip-off reviews enhanced by 34% between March and April this 12 months. Common tax scams embrace ATO impersonation scams, in which textual content messages with backlinks assert to be from the ATO tax refund frauds, which ask for particular person facets and bills to launch meant tax refunds tax owed scams, involving threats of arrest besides a fake tax bank card debt is paid through the use of credit score historical past card, cash switch, or reward enjoying playing cards tax ideas cons, the place scammers give you help with tax and large issues from pretend ATO social media accounts and TFN and ABN cons, the place by fake web pages supply options for a price however in its place steal revenue and personal data.

    To safeguard towards these scams, NAB implies staying away from responding to unsolicited messages requesting personalised data, not clicking on suspicious hyperlinks, and verifying surprising mobile phone calls by making contact with the group using publicly proven figures.

    Connected Tales

    Maintain up with the newest information and features

    Be a part of our mailing report, it’s cost-free!

  • OMS hires Tunsay and Jones as telephone BDMs – Mortgage Strategy

    One Mortgage System (OMS) has appointed Ahmet Tunsay and Matt Jones as telephone enterprise improvement managers (BDM).

    Tunsay and Jones have been employed to drive enterprise progress and domesticate consumer relations.

    Tunsay began his profession at NatWest the place he held quite a lot of roles together with account administration throughout his 5 years with the lender.

    Transitioning to the function of a dealer, he expanded his experience throughout the complete mortgage market over a five-year interval and will use this banking and finance background, alongside his middleman expertise, in his new function with OMS.

    Jones has labored inside monetary providers for over 27 years, beginning his journey as an adviser with Prudential and Zurich earlier than coming into the fintech area in 2002 as a BDM at O&M Systems.

    Following O&M’s acquisition by Iress in 2020, he transitioned into an account supervisor function, specializing in enterprise companies utilising their again workplace software program.

    Earlier this 12 months in January, he moved to the place of nationwide gross sales supervisor at Twenty7tec.

    OMS managing director Neal Jannels feedback: “Ahmet and Matt are two key additions to a gross sales assist workforce which continues to drive the enterprise and their distinctive talent units, market data and dedication will show invaluable in serving to to ship the bold progress technique that we at present have in place.”

  • RAW reduces rates by up to 0.50% for non-UK residents and UK expats – Mortgage Strategy

    RAW Capital Partners (RAW) has decreased the rates of two merchandise inside its non-UK residents and UK expats by up to 0.50%.

    The product’s introductory mounted price has been decreased from 6.99% to 6.49% for a restricted time solely. Its variable price product is priced at an rate of interest margin of two.25% above the financial institution price.

    The Guernsey-based funding administration agency, by its RAW Mortgage Fund, supplies specialist buy-to-let (BTL) mortgages to international purchasers investing in UK properties.

    RAW is providing its new, decrease rates on the primary 55% loan-to-value (LTV) of its time period mortgage merchandise.

    The 6.49% introductory mounted price is on the market for UK expats and non-UK residents as long as they full earlier than 31 October 2024.

    The BTL asset should be situated in a significant UK city or metropolis.

    Raw Capital Partners interim managing director Ben Nichols says: “Appetite for UK residential property stays robust amongst worldwide buyers, so our focus is on guaranteeing they’re effectively served from a finance perspective. We’re trying ahead to working with present and new intermediaries as we enter the second half of the 12 months.”