Tag: 2024

  • Get Completely ready for Economical Achievements in 2024

    Heading into a brand new 12 months is a superb time to judge your fiscal state of affairs and program for a prosperous 12 months ahead. Irrespective of whether or not you might be aiming to acquire a preliminary dwelling, fork out down an current property finance mortgage, or principally make enhancements to your financial wellbeing, remaining proactive about attaining financial achievements is a certain-fireplace technique to obtain extra together with your money. Follow these 3 measures to help construct extra wealth and enhance your economical stability in 2024.
    1-Feb-13-2024-12-41-08-1929-AM

    Action 1: Do a In depth Financial Look at-up

    Monetary success commences with a holistic perspective of your current fiscal predicament. Past merely scrutinising your house finance mortgage, it is important to judge your current income, money owed, budgeting, investments, insurance coverage insurance policies cowl, and retirement reductions. Conducting a in depth critique of your funds will support you set collectively for any sudden monetary points which may crop up this calendar yr.

    Revisit your funds by analyzing your revenue and payments and placement your fiscal priorities for the 12 months in advance.
    Test in in your disaster fund. An sudden emergency fund can help proceed to maintain you financially afloat for the period of arduous durations. As a traditional rule of thumb, saving a couple of to 6 months’ price of dwelling bills is finest.
    Take into consideration utilizing methods to help decrease or consolidate your debt. Minimizing the vary of monetary loans you might be carrying will simplify your funds and relieve income rigidity.
    Review your insurance coverage protection and get info from an insurance coverage protection dealer to check you might have the suitable diploma of cope with for your latest conditions.

    Action 2: Investigate Refinancing Solutions

    Fluctuating home mortgage charges and altering market issues might sign a possibility to refinance with a perspective to maximizing your cash standing. By leveraging funds contributions from new mortgage corporations and securing reduce curiosity premiums, you can probably unlock substantial value financial savings above the lifetime of your financial institution mortgage.

    Action 3: Raise Tremendous Price financial savings

    Superannuation is a cornerstone of retirement arranging in Australia, giving a spectacular normally technique of accumulating wealth for the long-time interval. By actively managing your superannuation, you help maximise its potential to protected a comfortable retirement.

    Think about escalating your contributions, having fringe of employer contributions and leveraging govt incentives to bolster your superannuation financial savings.
    If you might be providing your loved ones members residence to downsize, get tips on Downsizer Contributions to ramp up your Super with as much as a $300,000 contribution.
    Get fiscal info to make sure you is perhaps investing in the right fund with probably the most suited supplier for your cases.

    Planning for Economical Achievements

    Reaching a fiscally efficient yr normally takes thorough arranging and considered choice-building. By prioritising cash examine-ups, testing refinancing selections, and maximising Superannuation, you might be encouraging get ready for a prosperous calendar yr ahead.

    Join with a Home finance mortgage Categorical dealer in your area now, to get personalised help tailored to your unique financial ambitions. Our crew is devoted to serving to Australian homeowners and would-be house homeowners navigate the complexities of property finance mortgage administration and economical good outcomes.

    Though all therapy has been taken in the planning of this publication, no assure is offered as to the precision of the information and no obligation is taken by Finservice Pty Ltd (Home mortgage Specific) for any faults or omissions. This publication doesn’t represent personalised fiscal ideas. It won’t be associated to non-public circumstances. Absolutely nothing in this publication is, or ought to actually be taken as, an provide, invitation, or recommendation to acquire, promote, or retain any expenditure in or make any deposit with any particular person. You ought to actually search specialist help earlier than having any motion in relation to the problems dealt in this publication. A Disclosure Assertion is obtainable on ask for and no value of demand.

    Finservice Pty Ltd (Home mortgage Convey) is authorised as a company credit standing guide (Corporate Credit rating Representative Selection 397386) to engage in credit score historical past pursuits on behalf of BLSSA Pty Ltd (Australian Credit score Licence selection 391237) ACN 123 600 000 | Entire member of MFAA | Member of Australian Monetary Problems Authority (AFCA) | Member of Preference Aggregation Expert providers.
  • 10 Details You Have to have to Know About Created Households in 2024

    With a 71% gratification cost between homeowners and an enhance in family values, the extent of recognition of created properties is on the rise.

    This publish explores the most recent developments in manufactured housing, showcasing why they’re a wide selection for fairly a couple of People.

    Affordability of Created Properties

    Produced homes give substantial affordability benefits round customary website-designed properties. They present wonderful wonderful and normal efficiency at promoting costs which are up to 50% lots much less for each sq. foot.

    This price ticket effectivity is attributed to the manufacturing facility-creating strategy, which makes use of normal making supplies and assembles properties virtually fully off-web web page.

    This managed setting minimizes challenges encountered in basic constructing, these as climate delays and theft, main to much more productive and useful workforce administration.

    The all spherical widespread worth of a brand new manufactured home with no land in 2022 was $127,250, at an extraordinary price of $85.00 for every sq. foot for single-segment properties and $158,633 at $85.00 per sq. foot for multi-segment residences, making them an moderately priced possibility for homeownership.

    Financing Created Properties

    Funding for manufactured properties will be organized by way of a number of avenues, catering to equally personalised property and precise property transactions.

    Homebuyers have the choice to finance their manufactured dwelling as personal residence, or chattel, even when the family and land are financed with one another.

    Standard mortgage corporations that specialize in manufactured dwelling funding current packages for land-and-house financing as personalised dwelling.

    Moreover, if homebuyers want to finance their home and land collectively as genuine property, they will get hold of customary dwelling mortgage funding by the use of conventional mortgage mortgage lenders.

    This technique is akin to financing for net site-constructed properties and might include securing a mortgage that addresses each the land and the residence.

    For these fascinated in the newer course of manufactured homes, recognised as CrossMod® residences, Fannie Mae and Freddie Mac supply financing programs.

    These programs give debtors customary funding alternate options, which embody decrease want prices, and let for net site-created comparisons in the appraisal system.

    Price Appreciation of Made Households

    Made properties have demonstrated the probably for value appreciation greater than time.

    Involving 2017 and 2022, the median dwelling value of created properties in the United States enhanced by greater than 34.6%, demonstrating that like conventional site-built residences, manufactured homes can even respect in profit.

    This appreciation is motivated by parts some of these as the house’s situation, locale, and the all spherical housing present market dynamics.

    However, it actually is vital to discover that although manufactured residences have the possible for appreciation, the speed and extent of appreciation can change centered on these and different variables.

    Introduction of CrossMod® Properties

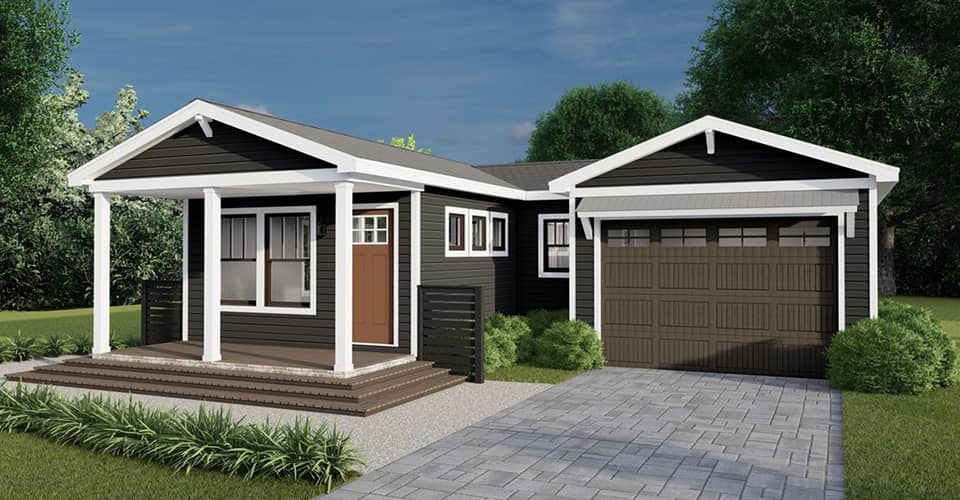
    CrossMod® properties characterize a progressive development in the made housing subject, giving a brand new course of households which are nearly indistinguishable from common site-built properties.

    These homes happen equipped with architectural capabilities some of these as pitched roofs, porches, garages, and lasting foundations, mixing seamlessly into present neighborhoods and communities.

    CrossMod Home

    The introduction of CrossMod® properties addresses a wider array of home-owner tastes, merging the affordability and effectiveness of made housing with the aesthetic and structural traits usually affiliated with web site-designed households.

    This innovation not solely expands the options for potential homeowners but additionally elevates the notion and attraction of created housing as a full.

    Substantial Pleasure Between Manufactured Property Residents

    A significant better a part of produced property individuals, 71%, report being happy with their properties. This important degree of gratification displays the prime quality, affordability, and luxury that these properties provide.

    Manufactured homes have developed to present an unlimited assortment of facilities and patterns that fulfill the various wishes and tastes of homeowners.

    From spacious flooring concepts and modern-day kitchens to electrical power-successful capabilities and customizable exteriors, created residences present a dwelling data that rivals typical website-crafted homes.

    The gratification charge underscores the success of created housing in supplying a viable and engaging housing possibility for plenty of Us residents.

    Living in Produced Home Communities

    Dwelling in produced home communities presents a particular established of constructive elements for individuals. These communities, typically referred to as land-lease communities, current an ecosystem the place by women and men can delight in homeownership along with neighborhood options.

    There are over 43,000 land-lease communities in the United States, presenting round 4.3 million homesites. These communities typically include shared facilities this kind of as clubhouses, swimming pools, and playgrounds, fostering a way of group and belonging amid residents.

    An individual noteworthy part of residing in these communities is the fiscal mannequin individuals typically very personal their manufactured property however lease the land it sits on. This can consequence in a additional economical entry degree into homeownership.

    Even so, it actually is important to ponder that website lease can maximize greater than time. The doc notes an typical yearly web site hire increase of 6.2%, in distinction to a 12% enhance for brand spanking new condo tenants and a 3.5% improve for condo tenants who renewed leases in 2022.

    (*10*)Growth in Made Residence Output

    The created family sector has seen appreciable growth, with 146 homebuilding amenities operated by 35 companies, collectively making 112,882 properties in 2022.

    This progress is indicative of the elevating demand from prospects for produced households, pushed by their affordability, effectivity in development, and the vary of construction choices accessible.

    The ability to generate a considerable amount of properties in simply managed manufacturing unit choices not solely assures a considerable typical of high quality but additionally contributes to the trade’s potential to fulfill the housing requires of assorted populations.

    This output skill highlights the job of manufactured properties in addressing the cheap housing catastrophe and that includes a sustainable path to homeownership.

    Safety and Durability of Created Homes

    Manufactured properties are meant and manufactured to fulfill stringent safety and sturdiness benchmarks, ensuring they’re a safe and prolonged-long lasting housing selection.

    These homes have to adhere to the federal HUD Code, which was confirmed in 1976 and units arduous pointers for dwelling structure, design toughness and sturdiness, hearth resistance, and electrical energy effectivity.

    Notably, the HUD Code was present in the early Nineties to drastically improve energy efficiency and air movement necessities, as successfully as to increase the wind resistance of manufactured properties in spots inclined to hurricane-force winds.

    Today’s created households profit from the precise growing parts noticed in site-constructed households, and they’re engineered for wind fundamental security and energy effectiveness.

    Federal legal guidelines additionally mandate safety options this sort of as smoke detectors, escape dwelling home windows, and the usage of restricted flamable supplies round furnaces, consuming water heaters, and kitchen ranges, producing created homes amongst the most secure housing picks provided now.

    Customization Alternatives for Created Houses

    Made households supply a broad differ of customization alternate options, permitting for shoppers to tailor their residences to meet up with distinctive wishes and tastes.

    From fundamental to elaborate floor applications, these residences can include capabilities some of these as vaulted or tray ceilings, entirely-outfitted kitchens, walk-in closets, and lavish bogs.

    The exterior of manufactured properties will be personalized with a wide range of siding parts together with metallic, vinyl, wooden or hardboard, and stucco, enabling householders to accomplish the best look and are available to really feel of their dwelling.

    Additionally, the manufactured housing subject has launched a brand new class of properties acknowledged as CrossMod® residences.

    These properties are indistinguishable from common net page-built households and supply additional customization choices, together with pitched roofs with shingles, gabled finishes, porches, garages, and lasting foundations.

    This evolution in the types and prime quality of residences obtainable lets purchasers to love a dwelling that matches their life type and desires although mixing seamlessly into most neighborhoods.

    Electricity Efficiency in Manufactured Households

    Created residences proper now are constructed with energy effectivity in mind, incorporating upgraded levels of insulation, additional environment friendly heating and cooling strategies, and different electricity-conserving traits.

    These enhancements are in response to improved federal necessities, this kind of as these individuals established by the HUD Code, which was revised in the early Nineties to improve energy efficiency and air movement standards in created housing.

    This goal on electrical energy effectivity not solely helps in lowering the environmental impact of those households but additionally presents substantial monetary financial savings for householders, notably in the period of accelerating energy expenditures.

    Also, a number of made households now seem with the selection to include EnergyStar-labeled home equipment and applications, which extra cuts down electrical energy consumption and expenditures.

    EnergyStar-labeled produced properties are solely designed to be extra strength-productive than customary homes, conserving homeowners main portions of earnings on heating, cooling, and electrical vitality funds above the lifetime of the house.

    Base Line

    In 2024, the panorama of created homes has superior appreciably, marked by wonderful developments that enrich their enchantment and performance.

    These residences have emerged as a cornerstone of cost-effective housing, giving up to 50% decreased charges for each sq. foot in comparison to conventional net site-built households.

    Innovations in financing have expanded, with decisions like CrossMod® properties staying financed by applications by Fannie Mae and Freddie Mac, producing homeownership extra obtainable.

    A notable improve in worth, with median family values appreciating greater than 34.6% in 5 a long time, underscores their funding choice possible.

    Communities about these households ship a sense of belonging, with in extra of 43,000 land-lease communities provided nationwide.

    Generation development, with 146 providers producing 112,882 households in 2022, meets the growing want. Customization decisions have expanded, permitting homeowners to tailor their residences to their preferences and necessities.

    Last of all, electrical energy effectivity stays a vital focus, with homes created to embody state-of-the-art insulation and EnergyStar-labeled home equipment, emphasizing sustainability and expense price financial savings.

    These developments spotlight the created family trade’s motivation to innovation, affordability, and prime quality, constructing these homes an ever extra widespread choice among the many People in america searching for accountable and expense-efficient housing options.

  • 25 First-Time Florida Home Buyer Grants and Programs in 2024: Ranked

    Expert Answer: Hey Johnny. We specialize in down cost help for Florida homebuyers so that you’re in luck.

    We’ve put collectively a listing of each Florida first-time homebuyer grant in the state in 2024 and our Florida mortgage consultants have ranked them for you!

    And keep in mind, in case you need assistance determining what you are eligible for, we’re blissful to assist!

    In Florida, as of 2024, first-time homebuyers have entry to 25 totally different applications that present alternate options to the standard 20% down cost.

    These applications embrace money grants, tax credit, and lowered mortgage charges, providing sensible options for these seeking to buy their first house.

    Remember, whereas every house help program has distinctive phrases, the overall {qualifications} embrace:

    Being a first-time house purchaser in line with this system’s definition.

    Completing a house purchaser training course.

    Adhering to specified earnings and buy worth limits.

    Purchasing a property in an accepted space.

    Using the house as your main residence.

    A large board with title Home Buyer Grants and Programs in Florida

    Florida Hometown Heroes Program

    The Florida Hometown Heroes Housing Program offers down cost and closing price help to first-time, income-qualified homebuyers who work or serve in the Florida group the place the house is being bought.

    The Florida Hometown Heroes Program presents substantial advantages and help for first-time homebuyers who work or serve in their native communities.

    Key advantages of this system embrace as much as $35,000 in help for down funds and closing prices, together with a decrease first mortgage rate of interest for eligible debtors.

    Additionally, no month-to-month mortgage insurance coverage premiums (PMI) profit these choosing FHA loans. This program is particularly tailor-made for buying a main residence in the group the place the borrower works or serves.

    To be eligible, candidates have to be first-time homebuyers employed in or serving the group the place they intend to buy the house. They should meet sure earnings limits primarily based on family measurement and location and have a credit score rating of at the very least 620.

    (*25*)FHA Loan Program

    FHA loans, backed by the Federal Housing Administration, are a tried-and-true resolution for homebuyers, notably these buying their first house.

    They require a decrease minimal down cost, as little as 3.5%, and are extra accessible to patrons with decrease credit score scores than standard loans.

    FHA loans additionally enable for larger debt-to-income ratios, offering extra flexibility in qualifying for a mortgage. Additionally, they provide the choice of a decrease rate of interest, making them a beautiful choice for these seeking to decrease upfront prices and month-to-month funds.

    Miami-Dade Advocacy Trust Grant

    The Miami-Dade Advocacy Trust grant’s Homeownership Assistance Program presents as much as $28,500 in no-interest, no-payment mortgage type for down cost and closing prices to first-time homebuyers in Miami-Dade County, primarily based on earnings.

    This mortgage is forgiven after 20 years, supplied the borrower continues to occupy the house.

    Eligibility features a requirement for candidates to contribute their very own funds towards the acquisition and to safe a mortgage via an accepted lender, guaranteeing a dedication to homeownership and monetary accountability.

    Hallandale Beach Community Grant

    The Hallandale Beach Community Grant, facilitated by the Hallandale Beach Community Redevelopment Agency, assists first-time homebuyers with as much as $100,000 for down cost and closing prices.

    This substantial help is aimed toward encouraging homeownership throughout the Hallandale Beach group reinvestment space.

    The help comes as a no-interest mortgage, forgivable after the borrower maintains the property as their main residence for at least ten years.

    To qualify, candidates are required to speculate $2,000 of their very own funds in direction of the down cost, amongst different eligibility standards, demonstrating a private dedication to homeownership in Hallandale Beach.

    Own a Home Opportunity Grant Program

    The Own a Home Opportunity Grant Program (OAHO) represents a major stride in direction of making homeownership extra attainable for residents throughout a number of Florida counties.

    Designed to reduce the monetary burden on homebuyers, this program extends a beneficiant provide of as much as 5% of the entire mortgage quantity.

    This help will be utilized in direction of a down cost or to cowl closing prices, immediately addressing two main monetary hurdles in the homebuying course of.

    Eligibility for the OAHO grant is prolonged to patrons in a variety of counties: Broward, Charlotte, Collier, DeSoto, Lee, Palm Beach, Sarasota, St. Johns, and Volusia.

    This broad eligibility standards be sure that a considerable variety of potential householders can profit from this system, fostering homeownership alternatives throughout various communities.

    To qualify for the OAHO grant, candidates should meet particular monetary standards, together with adhering to earnings and buy worth limits, guaranteeing that this system advantages those that want it most.

    Additionally, a credit score rating of at the very least 640 is required.

    Own a Home Opportunity Program

    The Own a Home Opportunity Program is a monetary help initiative designed to help first-time homebuyers in Florida.

    Targeting a number of counties, together with Charlotte, Collier, DeSoto, Lee, Sarasota, and particularly Palm Beach County, this system seeks to make homeownership extra accessible and reasonably priced.

    Eligible members in Charlotte, Collier, DeSoto, Lee, and Sarasota counties can obtain as much as $7,500 in help for down funds and closing prices.

    To handle the various financial landscapes throughout these areas, this system presents an elevated help quantity of $10,000 to patrons in Palm Beach County, recognizing the distinctive monetary challenges confronted by residents in this space.

    The monetary support supplied by the Own a Home Opportunity Program comes in the type of a zero-interest, deferred mortgage, including an additional layer of affordability for first-time patrons.

    The Good Neighbor Next Door (GNND) Program

    The Good Neighbor Next Door (GNND) Program is a U.S. Department of Housing and Urban Development (HUD) initiative to encourage group revitalization and homeownership.

    This program presents vital monetary help to eligible academics, regulation enforcement officers, firefighters, and emergency medical technicians (EMTs) once they buy houses in designated revitalization areas.

    Key options of the GNND Program embrace offering eligible members with a considerable low cost of fifty% off the checklist worth of houses situated in these areas. In trade, members should decide to utilizing the house as their sole residence for at the very least 36 months.

    This dedication is a part of HUD’s effort to strengthen communities and foster a way of funding and stability in these areas.

    HOME Homebuyers Program

    The HOME Homebuyers Program presents as much as $12,500 in down cost and closing price help as a zero-interest deferred mortgage to first-time homebuyers in Escambia County and Pensacola.

    This monetary help is designed to make homeownership extra accessible by easing the preliminary monetary burden, with out the strain of rapid compensation or curiosity accumulation.

    Eligibility standards embrace houses constructed after 1978, adherence to HOME worth limits, and location throughout the specified areas. This ensures this system helps fashionable, protected housing and stays centered on serving the local people.

    Through offering important monetary help and clear eligibility tips, the HOME Homebuyers Program considerably aids in selling homeownership, supporting the financial and communal development of Pensacola and Escambia County.

    SHIP First Time Homebuyers Program

    The SHIP First Time Homebuyers Program, supported by state funds in Pensacola and Escambia County, offers as much as $25,000 in down cost and closing price help.

    This help, decided by the borrower’s earnings, is delivered as a zero-interest deferred mortgage, which means there isn’t any curiosity accumulation through the deferment interval.

    A key eligibility issue is this system’s broad definition of a first-time purchaser, together with those that have not owned a house in the final three years. This flexibility makes it simpler for extra people to entry this system and pursue homeownership.

    VA Mortgage

    The VA mortgage is a 100% mortgage assured by the Department of Veterans Affairs and is particularly designed for active-duty navy members, veterans of the armed providers, and surviving spouses.

    VA loans don’t require mortgage insurance coverage and have a minimal credit score rating requirement of 620. Eligible patrons can make the most of VA loans to buy residential properties with 1-4 items throughout all 50 states and U.S. territories.

    Panama City Grant

    The Panama City Grant: Homeownership Assistance Program offers first-time homebuyers with as much as $50,000 to cowl closing prices, down funds, and mortgage funds.

    This monetary help is prolonged as a second mortgage, accommodating a various vary of house sorts to make sure broad accessibility.

    To be eligible, the acquisition worth of the property should not exceed $300,000, permitting for all kinds of housing choices inside this funds.

    This program goals to make homeownership extra attainable for first-time patrons in Panama City, supporting their journey in direction of proudly owning a house.

    USDA Mortgage

    The USDA mortgage is a 100% mortgage supported by the U.S. Department of Agriculture. It is particularly designed for houses in non-urban communities, which account for 91 % of the United States land mass.

    USDA mortgages are a wonderful choice for patrons with a minimal credit score rating of 580, as they permit 100% financing. Furthermore, USDA mortgage charges are ceaselessly essentially the most reasonably priced low-down-payment mortgage loans.

    FHFA First-Time Home Buyer Discount

    In 2024, first-time homebuyers will obtain a reduction on rates of interest for his or her loans from the Federal Housing Finance Agency (FHFA) to make housing extra accessible. To be eligible, you need to meet these standards:

    First-time homebuyers who’re eligible might obtain computerized mortgage charge reductions of as much as 1.75 proportion factors on standard 30-year fixed-rate mortgages, which might scale back month-to-month mortgage funds by as much as 20%.

    The quantity of mortgage charge reductions for first-time homebuyers will fluctuate relying on elements akin to credit score rating, the quantity of the down cost, the kind of property, and the mortgage program.

    Dare to Own the Dream

    Tampa’s Dare to Own the Dream program presents eligible homebuyers as much as $40,000 in help for down cost and closing prices.

    This help is supplied as a deferred-payment mortgage that’s utterly forgiven after 10 years of possession and occupancy.

    Applicants are required to collaborate with city-approved counseling companies, mortgage officers, and actual property brokers to make sure a complete help community all through the homebuying course of.

    A private monetary contribution in direction of the acquisition can be mandatory, reinforcing the customer’s funding in homeownership.

    Properties eligible for this program have to be inside Tampa metropolis limits and cross a metropolis inspection, guaranteeing security and compliance requirements are met.

    East Tampa CRA Down Payment Assistance Program

    The East Tampa CRA Down Payment Assistance Program targets first-time homebuyers in buying throughout the East Tampa group reinvestment space, providing as much as $50,000 in help.

    This zero-interest mortgage aids in protecting down cost prices and is forgiven after the house stays the customer’s main residence for seven years.

    Eligibility mirrors that of the DARE program, with the important thing distinction being the property’s location throughout the East Tampa CRA, guaranteeing centered help for homebuyers in this particular space.

    HomeReady

    HomeReady is a mortgage program that gives decrease charges and prices to low- and moderate-income house patrons and a 3% down cost choice.

    To be eligible for HomeReady, you need to have a minimal FICO rating of 620.

    When shopping for a HomePath property with HomeReady, you will get a $500 credit score for closing prices. The HomePath Ready Buyer program additionally presents a 3% money contribution to cowl your mortgage closing bills.

    Fannie Mae’s Standard 97% LTV Loan

    This program is designed for first-time homebuyers who may not have a big down cost. The Standard 97% LTV (Loan-to-Value) Loan by Fannie Mae permits patrons to finance as much as 97% of their house buy, which means they solely have to put down 3%.

    This program is much like the HomeReady mortgage however doesn’t have as many earnings restrictions. It requires at the very least one borrower to be a first-time homebuyer and has a minimal credit score rating requirement, which might fluctuate relying on the lender.

    Home Possible

    Home Possible is a mortgage program for low and moderate-income house patrons that enables a 3% down cost, much like HomeReady. It offers lowered mortgage charges and prices and contains fixed-rate and adjustable-rate mortgage choices.

    Home Possible requires a minimal FICO rating of 660 to qualify. It is a wonderful alternative for multi-generational households in search of a mortgage with a low down cost.

    The National Homebuyers Fund

    Homebuyers can make the most of the National Homebuyers Fund, a non-profit public profit company that gives money grants as much as 5 % of the acquisition worth.

    To be eligible, you need to decide to residing in your new house for at the very least 5 years. Sadly, renters can not apply immediately – solely their mortgage firm can apply on their behalf.

    Forgivable Mortgages

    Forgivable mortgages are a kind of mortgage that may be canceled after a house owner meets sure situations, akin to making common funds for an agreed-upon interval.

    In this situation, a first-time purchaser would use a standard mortgage to buy a house and make the down cost with a forgivable mortgage of $15,000, for instance.

    Suppose the customer resides in the house and meets their cost obligations for the agreed-upon time period, normally 5 years. In that case, the lender will forgive the $15,000 mortgage and launch their declare on the property’s title.

    Forgivable mortgages are a preferred software governments leverage to advertise homeownership, neighborhood growth, and native funding – all mandatory for a thriving economic system.

    If you may have ever come throughout cities providing incentives for people to maneuver there, forgivable mortgages are possible built-in into that technique.

    Discounted Homes from HUD

    The Good Neighbor Next Door Program (GNND) by the U.S. Department of Housing and Urban Development (HUD) presents repossessed houses to first-time patrons at a 50% low cost.

    This program is designed for academics, firefighters, regulation enforcement officers, and emergency medical technicians who wish to reside in the group the place they work. To apply for GNND, one can seek for eligible houses on the HUD web site and apply for a mortgage on-line.

    Down Payment Loans

    Down cost loans are loans from non-profit and group organizations that exchange a house purchaser’s down cost with borrowed money. Interest charges on these loans are normally in the one-percent vary and amortized over 30 years for ultra-low funds.

    To see if down cost loans can be found in your space, contact your municipal authorities’s housing administration, which might provide native connections.

    However, some mortgage applications don’t enable down cost loans, so patrons ought to test with their lenders earlier than making use of.

    Deferred Mortgages

    Deferred mortgages enable debtors to delay compensation till they promote or refinance their house. Municipal governments and native foundations usually provide them.

    They can present as much as $25,000 in funding for first-time homebuyers who meet sure standards, together with having an earnings under the realm common and a credit score historical past with a monitor file of on-time funds.

    Every session, Congress helps first-time house patrons by introducing laws to help renters in changing into householders. In the present session, Congress is predicted to current two important payments – a tax credit score and a money grant.

    The $15,000 First-Time Home Buyer Tax Credit

    The proposed $15,000 First-Time Home Buyer Tax Credit goals to help people buying their first house.

    This program, impressed by an analogous initiative from 2009, is designed to ease the monetary burden for first-time householders.

    Key Aspects:

    Eligibility – Targets first-time homebuyers.

    Refundable Credit – Offers a tax credit score of as much as $15,000.

    Purchase Period – Applicable for houses purchased after December 31, 2020.

    Tax Deductions – Includes the potential for claiming mortgage curiosity and credit for house enhancements.

    The $25,000 Down Payment Toward Equity Cash Grant

    In addition to the tax credit score, the Down Payment Toward Equity Act proposes additional monetary help.

    This grant is aimed toward first-generation house patrons and these from deprived backgrounds, providing as much as $25,000 to help house purchases.

    Elements of the Grant:

    Amount – Up to $20,000 for first-generation patrons, plus an extra $5,000 for patrons from deprived backgrounds.

    Usage – Covers down funds, closing prices, and actual property taxes and allows decrease mortgage charges.

    Legislative Status – Currently proposed, with expectations of reintroduction in the present Congressional session.

    Florida Homebuyer Programs and Grants FAQs

    We’ve answered some widespread questions that you might have whereas making an attempt to select a grant or program right here:

    How do I decide which Florida first-time homebuyer grant is true for me?

    Consider your location, earnings, credit score rating, and the kind of property you are in. Matching these elements with the precise necessities of every program might help slim down your choices.

    Can I apply for multiple grant program at a time?

    Yes, relying on the applications’ guidelines. Some might enable combining grants for higher help, however at all times test the precise eligibility necessities and restrictions.

    What are the advantages of finishing a house purchaser training course?

    Besides being a requirement for many applications, these programs present helpful info on the homebuying course of, monetary planning, and homeownership duties.

    Are there grants accessible for houses outdoors city areas?

    Yes, applications just like the USDA mortgage are particularly designed for rural areas, providing 100% financing and low charges to encourage homeownership in much less densely populated areas.

    How does the first-time homebuyer definition have an effect on eligibility?

    Most applications outline a first-time homebuyer as somebody who hasn’t owned a house in the previous three years. This broader definition permits extra people to qualify for help.

    What position does my credit score rating play in qualifying for these applications?

    Your credit score rating can affect which applications you are eligible for and the quantity of help you possibly can obtain. Programs usually have a minimal credit score rating requirement.

    Can I take advantage of these grants for any sort of house?

    Each program has its personal restrictions on the kind of properties eligible, akin to single-family houses, condos, or townhouses, and some have worth limits or location necessities.

    What occurs if I transfer out of my house earlier than the grant’s occupancy requirement is met?

    You might should repay the grant or a portion of it, relying on the precise phrases of this system. These necessities are designed to encourage long-term homeownership and group funding.

    How do earnings and buy worth limits have an effect on my eligibility?

    These limits make sure the applications help these most in want and fluctuate by location and family measurement. Staying inside these limits is essential for qualifying for help.

    Where can I discover extra details about making use of for these applications?

    Visit the web sites of the precise applications you are in or contact native housing authorities. They can present detailed info, software tips, and help all through the method.

  • Nominations open for Elite Ladies 2024

    Nominations open for Elite Ladies 2024 | Mortgage mortgage Expert Australia

    Information

    MPA’s annual Elite Females shines a light on the main gals in mortgage

    Nominations open for Elite Women 2024

    MPA has opened nominations for Elite Women of all ages 2024, proudly sponsored by ANZ, to highlight female leaders who’ve manufactured strides within the enterprise this 12 months.

    Nominations might be made by means of this on line sort for gals who’re shaping the Australian residence mortgage trade’s potential.

    “ANZ continues to be dedicated to enhancing the inclusiveness and vary of our enterprise. We appear ahead to celebrating the Elite Girls who’ve created their mark on the home mortgage enterprise,” claimed Natalie Smith, normal supervisor retail dealer at ANZ.

    Nominations shut Friday, May properly 10.

    Elite Gals 2024 might be posted in problem 24.04 of MPA journal and on the net in August.

    Related Articles or weblog posts

    No value e-publication

    Our each day e-newsletter is No value and retains you as much as day with the earth of mortgage.
    Make positive you full the type beneath and click on on on Indication UP to acquire each day e-newsletters from Mortgage Qualified Australia.

    Our on a regular basis publication is Free of cost and retains you updated with the world of home mortgage.

  • Alberta’s New Collision Reporting Threshold in 2024: What You Require to Know

    Jan 10 2024

    Fast Update on Collision Reporting Procedures

    Hey there Alberta! We’ve acquired a speedy replace that is actually value your curiosity. Beginning January 1, 2024, there’s a regulate in the collision reporting insurance policies in Alberta. It actually isn’t a major shake-up, however it’s a factor which will prevent a little bit of time and paperwork in the foreseeable future.

    What’s Modifying?

    Previous to this new rework, in case you have been being related in a car collision and the issues was estimated about $2,000, you needed to report it to the police. From 2024, this threshold is growing to $5,000.

    Why the Change?

    This change is a response to rising car restore service expenditures. It is designed to reduce the have to have to report slight damages, simplifying factors for you and the police.

    What Doesn’t Modify

    Important to bear in mind: the reporting requirements for collisions involving accidents or fatalities stay unchanged. Protection first, often!

    How Does This Have an affect on You?

    In fundamental phrases, for minor bumps and scrapes with harm lower than $5,000, you’ll unlikely want to file a regulation enforcement report. It streamlines the plan of action, releasing you from some pink tape.

    We’re Here to Assist

    If you have got questions on how this rework might affect your protection or simply want typical suggestions, bear in thoughts, we at To begin with Foundation are only a get in contact with or e mail absent. We are listed right here to support you along with your insurance coverage insurance policies desires, ensuring you is likely to be usually protected and educated.

    Continue to be Educated

    These tiny modifications could make a serious change in our every day life. Which is why we’re totally commited to preserving you up to date. For any insurance coverage plan queries – auto, property, enterprise – we’re utterly prepared to provide our expertise.

    Arrive at Out Whenever

    Questions or issues? Contact Veralin at this time! She’s right here to support you navigate these modifications with relieve.

    Keep risk-free and knowledgeable, Alberta!

  • APM Economical Conditioning: March 2024

    Previous month noticed the get began of the Lunar New 12 months, which is the 12 months of the Dragon. It actually is an auspicious yr, as it’s believed that younger youngsters born this 12 months are destined for accomplishment. Some well-known Dragon toddlers: Keanu Reeves, Rihanna, Dr. Martin Luther King Jr, John Lennon and Peyton Manning.

    financial fitness march

    No make a distinction what 12 months you have been being born in, you could have some actually critical help shopping for a home this yr should you may be even now leasing! A invoice launched in 2021 might be handed quickly, which would supply a number of initial-time customers with as much as $25,000 in assist. Read via all about this invoice beneath. Other issues: methods to regulate a home remodel, essentially the most up-to-date on automobile insurance coverage plan pricing, and why chances are you’ll maybe need to confirm out your VantageScore.

    Residence Funding

    Down Payment Help Might Get Severe Shortly

    Even nonetheless the 20% down fee rule is not any much more than a fantasy, there are nonetheless loads of potential home purchasers who have to bump up their laborious money belongings upfront of buying their first property. If the Downpayment Towards Fairness Act passes this calendar yr, these initially-time prospects could get hold of a cash grant for as much as $25,000.

    This Act was designed to allow further Individuals purchase their properties and start making a protected cash foreseeable future. Although it actually continues to be within the will work, it was just lately declared that the Act is a part of President Biden’s 2024 Fiscal Yr funds proposal.

    Here are the fundamental ideas of this invoice.

    The Downpayment Toward Fairness Act will ship dwelling possession within the arrive at of further individuals, which incorporates folks with reduce incomes.
    The proposed plan affords as much as $25,000 to initially-time patrons. Initially-era homeowners qualify for $20,000, with $25,000 for potential patrons considered socially or economically disadvantaged. (1st-technology house homeowners are outlined as customers whose mother and father or guardians have by no means owned a dwelling, or customers who previously lived in foster care.)
    Grant funds might be utilised to go over down fee and shutting prices, and for looking for low value elements to decreased a mortgage’s fascination quantity.
    The money funding is shipped to qualifying prospects when a house order is finalized.

    At current, the invoice is nonetheless remaining considered by Congress and is subject material to dialogue and possible alterations previous to it may be permitted and signed into regulation. For updates, pay a go to to the Congress.gov web page showcasing the invoice’s historical past.

    Supply: themortgagereports.com

    Insurance protection

    Automobile Insurance insurance policies Pricing Climbs More than 25%

    If you have just lately been given your automobile insurance coverage renewal discover, you possibly can have felt rear-ended by your new premium. According to new data, drivers all through the nation are having to pay an regular of $212 for vehicle insurance coverage protection, which is above 25% from 2023 premiums.

    When inflation is nonetheless having fun with an element in rising value ranges, different elements are driving up driving charges. A single essential indicator: the place you reside. If you occur to be in some extent out inclined to regular disasters, your charges have been being most completely impacted. For living proof, California drivers noticed their insurance coverage prices head north due to newest abuses meted out by Mother Character, as purely pure disasters harm autos and repairs are getting much more expensive.

    Other states’ motorists often aren’t off the hook. Louisiana and Florida drivers are weathering far more than hurricanes across the earlier couple of a very long time, they’ve been forking over the most important share of their paychecks in the direction of automobile insurance coverage. Louisiana drivers shell out an typical of 6.53% of their earnings for auto insurance coverage though Florida drivers are tailgating them and spending 5.69%. Missouri gained the prize for the premier 12 months-more than-yr enhance in premiums, with drivers paying throughout 40% far more to make sure their rides than they did earlier yr.

    A handful of states’ drivers aren’t struggling as terribly. For occasion, Massachusetts drivers admire a few of the nation’s most cost-effective charges, as level out regulation prohibits the usage of age as a rating facet for surroundings insurance coverage insurance policies pricing. They are paying out simply 1.76% of their earnings in the direction of insuring their cars. Wyoming drivers have been the one situation through which protection costs fell, with common prime quality pricing slipping by an individual buck (hey, it actually is much better than little or no!).

    Resource: cbsnews.com

    In the News

    Inflation’s Down however Not Out

    Current data from the U.S. Labor Office built-in an unpredicted rise within the Customer Cost Index (CPI), which performs an enormous job in inflation. January’s CPI posted a 3.1% annual improve —a bigger leap than anticipated—whereas month to month features better as properly.

    Core CPI portions (which don’t include energy and meals fees) rose 3.9% every year previous month, which was the exact same as December. On a daily basis, CPI rose .3% last month instantly after mounting .2% in December. Core CPI rose .4%, up from the .3% purchase the previous thirty day interval.

    Even though over-all price ticket pressures have moderated, relieving some purchasing pressure, discovering inflation completely again to common might be much more difficult than economists anticipated. The inflation slowdown in extra of the earlier 12 months occurred alongside a stable monetary system, bucking predictions that the U.S. financial local weather must expertise a financial downturn to convey down charges. The huge query is no matter whether or not this pattern will go on in 2024.

    When The Federal Reserve hiked curiosity fees many durations in 2023 to rein in inflation, associates of the Reserve at the moment are attempting to establish whether or not or to not provide the decreased curiosity prices predicted for this 12 months. Not way back, Fed officers are hinting that the decrease charges won’t get there as earlier than lengthy as hoped, as they need additional proof that the battle on inflation has been actually gained forward of reducing need fees.

    Source: axios.com

    Credit score and Purchaser Finance

    FICO Rating, Satisfy VantageScore

    Probabilities are you occur to be at the moment accustomed to the ideas of credit score rating scores, together with methods to take care of your funds and credit score historical past accounts for an even bigger rating. Even so, chances are you’ll maybe not be accustomed to VantageScore®, a substitute for FICO.

    VantageScore was created in 2006 as an alternate to plain credit score historical past scoring. It procedures credit score historical past and cash habits in any other case, giving way more people the capability to ascertain a superior credit score historical past score. Two teams that VantageScore assists: increased schooling school college students and new immigrants. 

    VantageScores are extensively made use of by credit score historical past card issuers, with 9 of the ten largest banking corporations making use of this credit score rating score. Due to the actual fact your following credit score historical past utility might be processed together with your VantageScore, it is a major introduction. 

    VantageScore considers 4 important funds administration elements when calculating your score.

    Very influential: Total credit score rating use, concord and provided credit score historical past
    Remarkably influential: Credit mix and encounter
    Reasonably influential: Payment historical past
    Considerably much less influential: Age of credit score rating background and new accounts opened

    Related to FICO, VantageScore scores you on a spread from 300 to 850. Scores of 499 and beneath are regarded Inadequate, and scores above 781 are graded Outstanding.

    If you’d prefer to see your VantageScore, there are quite a few strategies to do that. Numerous credit standing card issuers, like Chase and Capital One explicit, give their cardholders completely free accessibility to this data and info. You may additionally check out the VantageScore website for much extra choices.

    Resource: cnbc.com

    Did You Know?

    How To Keep Tabs on a Reworking Venture

    If you might be arranging a significant remodel this yr, you possibly can be eager to know methods to handiest deal with the job. Using the companies of a bonded, licensed contractor is an obligatory first motion. The 2nd stage? Monitoring the function because it progresses, if attainable, to make sure all staff are adhering to your major contract.

    The unlucky reality about transforming is that it truly is ceaselessly tough to establish if a contractor is decreasing corners with sub-par parts, workmanship, or each equally. Here are some instances to look at out for, collectively with approaches for challenge-solving.

    Your contractor is working with low-high-quality components. This could occur when inflation causes the substance costs to rise quickly after you’ve signed off on the problem, however your contractor feels pressured to proceed to be within the preliminary value vary. One technique to cease this state of affairs is to ask for a radical estimate that describes the precise grade and mannequin of every product. When these get there at your own home, double-look at to guarantee they match your agreed-upon estimate. A distinct system: go over the probability of climbing costs mid-project together with your contractor earlier than carry out commences, collectively with a contingency program.

    Some parts are lacking or you shouldn’t match. Make sure your rework comprises all of the options you have compensated for. If you are lacking electrical retailers, constructed-in cupboards, or different features, it’s time to blow the whistle. Another crimson flag: tiles that by no means match or are a a little bit bit distinct form or color. This may essentially imply that they ended up purchased from salvage or discounted warehouses.

    Drawers aren’t opening effortlessly. You could properly presume that your drawers are buying trapped on something, however it may be usually since they’re as properly small—a frequent cash-saving tactic.

    Gaps throughout house home windows or doorways. These might be introduced on by improper set up or cheaper substitutes.

    If you discover (or suspect) that your contractor is slicing corners, proper listed below are some strategies to decide on.

    If you location proof simply earlier than function is completed, select pictures of your issues.
    Ask for components invoices and evaluate them to your genuine packages.
    Upcoming, timetable a meeting with the contractor.
    Be geared as much as make clear your concerns politely and generate proof of things that require to be modified.
    Maintain in thoughts that your contractor could properly have manufactured an real error. Most will upkeep, swap or redo one thing you are not happy with.

    If you occur to be not geared up to seem to an association, herald a second contractor or an unbiased inspector to judge the carry out and provide estimates for rectifying issues. Other methods: in quest of licensed data or calling the purpose out workplace surroundings or regulatory board that issued your contractor’s license.

    Supply: lifehacker.com

    Nevertheless hoping to find out in case your reworking methods make sense on your fiscal picture? We have a terrific publish that handles the home renovations with the perfect return on expense in addition to a completely free E guide with renovation funding fundamentals.

  • The $25,000 Down Payment Toward Equity Act in 2024: Current

    The Act’s significance in the most recent housing present market cannot be overstated it seeks to sort out the widening homeownership gap, primarily amongst socially and economically disadvantaged groups, along with racial minorities and people with disabilities.

    What is the Down Payment Toward Fairness Act?

    The Down Payment Towards Fairness Act is a legislative proposal aimed toward supplying sizeable monetary help to very first-time and initial-technology house consumers.

    This act proposes as much as $25,000 in steerage to allow tackle the bills concerned with buying a house, these as down funds, closing prices, and mortgage mortgage fascination cost reductions.

    The most vital aim of the act is to make homeownership extra obtainable to minimal- and moderate-income individuals at this time, as very effectively as to deal with racial disparities in homeownership premiums.

    The system emphasizes help for “socially deprived people,” aiming to cut back monetary boundaries to homeownership for traditionally underserved communities.

    A family receiving financial assistance for first time homebuyers

    Eligibility Requirements for the $25,000 Grant

    To be certified for the $25,000 grant beneath the Down Payment Toward Fairness Act, candidates ought to meet fairly a number of important necessities meant to guarantee the plan added advantages initial-time, low- to average-income residence clients, significantly people from deprived backgrounds.

    These requirements embrace:

    To begin with-Time Household Customer Status

    Applicants should not have owned a dwelling or co-signed on a house finance mortgage in the earlier three a number of years. This incorporates these individuals who have beforehand owned a house however not inside simply the ultimate three many years, making them appropriate as very first-time shoppers after as soon as extra.

    Income Limitations

    Eligibility is restricted to individuals at this time with house incomes at or under 120% of the area median earnings (AMI) for many areas.

    However, for substantial-value areas, candidates can qualify with incomes as much as 180% of the AMI, creating the plan accessible to a broader collection of alternative potential consumers in high-priced markets.

    Main Residence Prerequisite

    The methodology mandates that the bought home must be the principle residence of the applicant. This excludes household trip households, expense qualities, or 2nd properties from eligibility.

    Initially-Technology Home Buyer

    Precedence is specified to candidates who’re 1st-era family potential consumers, indicating their mother and pa or authorized guardians haven’t owned a residence during the applicant’s life span. This necessity is waived for candidates who’ve lived in foster care.

    Use of Governing administration-Backed Home loans

    Applicants have to safe a property finance mortgage that’s backed by authorities companies this kind of as Fannie Mae, Freddie Mac, FHA, VA, or USDA. These mortgages give you much more accessible situations for initial-time shoppers, which embrace reduce down funds.

    Instructional Course Completion

    To qualify, candidates ought to complete a HUD-permitted homebuyer schooling and studying system. These lessons are constructed to place collectively initially-time consumers for the duties of homeownership and may ceaselessly be accomplished on-line.

    What Is The Standing of The Program in Mid-2024?

    As of mid-2024, the Down Payment Toward Equity Act stays in legislative limbo, nonetheless beneath thought by the 2023-2024 Congress.

    Irrespective of its introduction and lots of important milestones since 2021, the invoice has however to be handed into regulation. Right up till the month-to-month invoice is formally handed and will get regulation, potential beneficiaries can’t declare the $25,000 grant.

    In the meantime, all these trying into homeownership could effectively take into consideration the number of grants and programs that MakeFloridaYourHome provides, just like the Florida Hometown Heroes $35,000 grant.

    When Is Biden’s Grant Projected to Go and the $25,000 Predicted to Turn out to be Readily accessible?

    Primarily based mostly on the legislative timeline and progress of the Down Payment Towards Fairness Act as of mid-2024, it is difficult to pinpoint an actual date when the $25,000 grant will turn into obtainable.

    The bill has been on account of varied levels of introduction and dialogue in Congress as a result of 2021, with probably the most up-to-date version launched in March 2024.

    Legislative processes, in explicit for expenditures involving substantial financial allocations like this one explicit, will be extended and superior, involving quite a lot of steps of approval and possible revisions.

    Specified the historic velocity of comparable legislative efforts and the good significance of coordination all through varied federal authorities organizations to place into motion the grant program, it is believable that the earliest the invoice might go can be sometime following mid-2024.

    Possible dwelling potential consumers fascinated in this grant are inspired to maintain up-to-date on the invoice’s growth on account of official legislative monitoring platforms and information from revered sources like MakeFloridaYourHome.

    Alternatives to the $25,000 Down Payment Grant

    For people looking for for prospects to the Down Payment Toward Fairness Act’s $25,000 grant, there are numerous different packages created to help very first-time homebuyers and local people heroes with the purchase of their key house.

    Here is a abstract of some notable packages:

    Florida Hometown Heroes Method

    This program targets initial-time homebuyers who’re actively working or serving in their Florida communities, giving as much as $35,000 in steerage for down funds and shutting expenditures.

    Vital beneficial properties contain a scale back to begin with home mortgage rate of interest and no necessity for each month property finance mortgage insurance coverage charges for all those that pick FHA monetary loans.

    Eligibility necessities include being a 1st-time homebuyer used in a qualifying occupation within the group, convention explicit cash limitations, and getting a naked minimal credit score historical past rating of 620.

    FHA Personal mortgage Application

    The Federal Housing Administration backs the FHA financial institution mortgage software, which is specifically beneficial for initial-time homebuyers.

    It wants a minimal quantity down cost of simply 3.5% and accommodates consumers with decreased credit score historical past scores than all these ordinarily anticipated for normal loans.

    The methodology additionally delivers extra lenient bank card debt-to-profits ratios, making it easier for candidates to qualify for a financial institution mortgage.

    In addition, FHA monetary loans can ship scale back curiosity costs, supporting to cut back each equally upfront prices and month-to-month mortgage mortgage funds.

    Great Neighbor Subsequent Door (GNND) Program

    Operated by the U.S. Office of Housing and Urban Development, the GNND Plan goals to encourage group revitalization by means of homeownership.

    It offers a 50% worth reduce on the report price ticket of properties in chosen revitalization areas to eligible instructors, regulation enforcement officers, firefighters, and disaster health-related specialists. Members have to decide to residing in the residence for at minimal 36 months as their key house.

    This system not solely helps personal homeownership aims but in addition contributes to the strengthening of communities.

    Each of those packages offers unique benefits and eligibility requirements, catering to a array of potential homebuyers.

    They stand for beneficial means for these individuals looking for help in buying a house, offering monetary help and incentives over and above what’s accessible via the Down Payment Towards Fairness Act.

    Routinely Questioned Issues (FAQs)

    Navigating the complexities of family getting and understanding the Down Payment Towards Fairness Act will be demanding.

    This FAQ section goals to deal with a number of the most frequent inquiries and provide very clear, concise options to allow you in your journey to homeownership.

    Who is appropriate for the Down Payment Towards Fairness Act?

    Eligibility is principally for 1st-time and to begin with-generation homebuyers who fulfill sure earnings requirements.

    This comprises individuals who haven’t owned a house in the earlier 3 a few years, people who’re buying a house in a bunch precisely the place they do the job or present, and people who fulfill particular earnings restrictions centered on the place median money circulate.

    What is the aim of the Down Payment Towards Fairness Act?

    The Act goals to make homeownership way more obtainable to small- and average-profits people by providing as much as $25,000 in steerage for down funds and shutting prices.

    It targets lowering the homeownership hole, specifically among the many traditionally underserved communities.

    How an amazing deal help can I get from this system?

    Qualified homebuyers can rise up to $25,000 in assist, which will be utilised for down funds, closing costs, and different costs linked with buying a residence.

    When will the Down Payment Toward Equity Act turn out to be provided?

    As of mid-2024, the Act is proceed to under thought by Congress and has not nonetheless turn into regulation. The timeline for when it would move and develop to be accessible is not sure.

    Are there decisions to the Down Payment Towards Equity Act?

    Indeed, there are a number of prospects, along with the Florida Hometown Heroes Method, FHA Personal mortgage Program, and the Good Neighbor Up coming Doorway (GNND) Plan, every supplying certainly one of a sort beneficial properties for homebuyers.

    What are the essential optimistic elements of the Florida Hometown Heroes Software?

    This plan delivers as much as $35,000 in steerage for very first-time, income-skilled homebuyers in Florida, giving help for down funds and shutting prices, alongside with a decreased first home mortgage fascination degree and no PMI for FHA monetary loans.

    How do FHA monetary loans perform?

    FHA loans contain a lowered minimal quantity down cost (as lowered as 3.5%) and are obtainable to clients with decrease credit score scores than typical monetary loans, making them a superb risk for to begin with-time homebuyers.

    What is the Excellent Neighbor Future Doorway Application?

    The GNND Application delivers a 50% low cost on homes in specified revitalization areas to eligible public servants, these as instructors and regulation enforcement officers, promoting neighborhood revitalization via homeownership.

    Can I exploit the $25,000 grant for any residence make investments in?

    The grant is specifically meant for the order of a major house and easily can’t be employed for 2nd residences or expense properties. The residence should additionally fulfill different software-unique eligibility situations.

    How do I exploit for the Down Payment Towards Fairness Act or its options?

    Application procedures differ by methodology. For the Down Payment Towards Equity Act, details will grow to be clearer the second the month-to-month invoice will get regulation.

    For different packages just like the FHA Personal mortgage System or the GNND Application, potential homebuyers have to contact authorised collectors or HUD for software program details.

    What’s Future?

    As the journey to homeownership unfolds, particularly with alternatives just like the Down Payment Towards Equity Act and its options, it actually is vital to remain educated and request professional path.

    MakeFloridaYourHome is a useful ally in this methodology, offering insights and assist tailor-made to your house-buying aspirations.

    With the right sources and help, navigating the path to homeownership can turn out to be additional easy and attainable.

    Try to recollect, reaching your intention of possessing a house is in get to, and certified help could make all the excellence.

  • Florida Housing Corp Income Limits & Purchase Price Limits in 2024

    Some {qualifications} embody earnings and buy value limits, first-time homebuyer necessities, minimal FICO scores, and FHA necessities.

    This weblog submit will take a look at the earnings and buy value restrict necessities that debtors should fulfill to qualify for backed mortgage loans.

    Florida Housing Down Payment Assistance Programs

    Before we discover these necessities, let’s first take a look at the several types of loans provided by Florida Housing.

    Florida Housing gives essential help to eligible homebuyers by numerous mortgage packages designed to make homeownership extra attainable.

    Florida Hometown Heroes Housing Program

    This program gives as much as a $35,000 grant to all full-time employees in Florida. It is designed to acknowledge and help those that dedicate their careers to serving their communities.

    The Florida Assist (FL Assist)

    Up to $10,000 is usable with FHA, VA, USDA, and Conventional Loans. This is a 0% curiosity, non-amortizing, deferred second mortgage.

    The mortgage reimbursement is deferred till the house is bought, the primary mortgage is glad, the house is refinanced, or it’s now not the borrower’s main residence.

    The Florida Homeownership Loan Program (FL HLP) Second Mortgage

    Offers a flat $10,000. This is a 3% curiosity, absolutely amortizing second mortgage with a 15-year time period.

    Similar to the FL Assist, reimbursement is deferred underneath circumstances like promoting the house or refinancing. However, it has a month-to-month cost that should be factored into the borrower’s debt-to-income ratio throughout credit score analysis.

    3%, 4%, and 5% HFA Preferred and HFA Advantage PLUS Second Mortgage

    Provides 3%, 4%, or 5% of the full mortgage quantity. This second mortgage is forgivable, amortized over 5 years, and forgiven at 20% annually.

    Available solely with Florida Housing’s standard first mortgage merchandise labeled HFA Preferred for TBA or HFA Advantage for TBA.

    Florida Housing Program General Requirements

    To qualify for the Florida Housing Loan packages, it’s best to meet the next necessities:

    You are a first-time homebuyer – with solely two exceptions. One is that you’re a navy, air service, or naval veteran who was launched or discharged underneath honorable circumstances. Second, you reside in a federally designated focused space.

    You have a minimal FICO rating of 640 or 660 or decrease for particular mortgage merchandise and mortgage reservation necessities.

    You meet the earnings and buy value restrict necessities.

    An illustration emphasizing the Florida Housing Income and Purchase Price Limits

    Income Limits Requirements for Every County in Florida (2024)

    The earnings restrict for the FL mortgage mortgage packages is the utmost quantity of earnings your family should not exceed to qualify for the backed loans.

    This restrict will depend on the place the property you need to purchase is situated and can also be adjusted for particular family sizes.

    Note that focused areas are sometimes designated as economically distressed, usually qualifying for larger earnings limits to encourage funding and homeownership, whereas non-targeted areas don’t obtain these designations and subsequently have normal earnings limits.

    So, for example, in Miami-Dade County in 2024, you may solely qualify for the FL mortgage mortgage packages in case your family earnings:

    Doesn’t exceed $64,200 adjusted for 1-2 individuals when buying a property in a non-targeted space.

    Doesn’t exceed $93,100 adjusted for 3+ individuals when shopping for a property in a non-targeted space.

    Doesn’t exceed $93,100 when buying a property in a focused space. (There are not any family unit restrictions/changes).

    Florida
    County
    Non-Targeted Area
    (1-2 Persons)
    Non-Targeted Area
    (3+ Persons)
    Targeted
    Area

    Alachua
    $66,800
    $93,320
    $93,320

    Baker
    $57,800
    $80,720
    $80,720

    Bay
    $57,800
    $80,720
    $80,720

    Bradford
    $57,800
    $80,720
    $80,720

    Brevard
    $64,200
    $89,880
    $89,880

    Broward
    $73,800
    $103,320
    $103,320

    Calhoun
    $57,800
    $80,720
    $80,720

    Charlotte
    $64,500
    $90,300
    $90,300

    Citrus
    $55,000
    $76,800
    $76,800

    Clay
    $64,200
    $89,880
    $89,880

    Collier
    $64,200
    $89,880
    $89,880

    Columbia
    $64,100
    $89,740
    $89,740

    DeSoto
    $55,300
    $77,420
    $77,420

    Dixie
    $53,900
    $75,460
    $75,460

    Duval
    $68,300
    $95,620
    $95,620

    Escambia
    $65,500
    $91,700
    $91,700

    Flagler
    $66,500
    $93,100
    $93,100

    Franklin
    $60,300
    $84,420
    $84,420

    Gadsden
    $63,400
    $88,760
    $88,760

    Gilchrist
    $69,800
    $97,720
    $97,720

    Glades
    $58,500
    $81,900
    $81,900

    Gulf
    $61,700
    $86,380
    $86,380

    Hamilton
    $62,200
    $87,080
    $87,080

    Hardee
    $57,200
    $80,080
    $80,080

    Hendry
    $57,300
    $80,220
    $80,220

    Hernando
    $63,200
    $88,480
    $88,480

    Highlands
    $55,900
    $78,260
    $78,260

    Hillsborough
    $76,600
    $107,240
    $107,240

    Holmes
    $57,600
    $80,640
    $80,640

    Indian River
    $64,000
    $89,600
    $89,600

    Jackson
    $57,400
    $80,360
    $80,360

    Jefferson
    $67,100
    $93,940
    $93,940

    Lafayette
    $62,700
    $87,780
    $87,780

    Lake
    $69,000
    $96,600
    $96,600

    Lee
    $70,400
    $98,560
    $98,560

    Leon
    $71,300
    $99,820
    $99,820

    Levy
    $58,900
    $82,460
    $82,460

    Liberty
    $57,800
    $80,720
    $80,720

    Madison
    $59,100
    $82,740
    $82,740

    Manatee
    $73,100
    $102,340
    $102,340

    Marion
    $60,600
    $84,840
    $84,840

    Martin
    $76,500
    $107,100
    $107,100

    Miami-Dade
    $64,200
    $93,100
    $93,100

    Monroe
    $79,000
    $110,600
    $110,600

    Nassau
    $74,700
    $104,580
    $104,580

    Okaloosa
    $70,900
    $99,260
    $99,260

    Okeechobee
    $57,700
    $80,780
    $80,780

    Orange
    $72,000
    $100,800
    $100,800

    Osceola
    $70,200
    $98,280
    $98,280

    Palm Beach
    $75,300
    $105,420
    $105,420

    Pasco
    $68,700
    $96,180
    $96,180

    Pinellas
    $69,500
    $97,300
    $97,300

    Polk
    $62,800
    $87,920
    $87,920

    Putnam
    $53,800
    $75,320
    $75,320

    Santa Rosa
    $76,800
    $107,520
    $107,520

    Sarasota
    $73,400
    $102,760
    $102,760

    Seminole
    $71,900
    $100,660
    $100,660

    St. Johns
    $77,100
    $107,940
    $107,940

    St. Lucie
    $64,400
    $90,160
    $90,160

    Sumter
    $68,900
    $96,460
    $96,460

    Suwannee
    $58,400
    $81,760
    $81,760

    Taylor
    $57,400
    $80,360
    $80,360

    Union
    $59,600
    $83,440
    $83,440

    Volusia
    $65,900
    $92,260
    $92,260

    Wakulla
    $63,700
    $89,180
    $89,180

    Walton
    $74,200
    $103,880
    $103,880

    Washington
    $59,100
    $82,740
    $82,740

    Purchase Price Limits For Every County in Florida (2024)

    The buy value restrict for the FL mortgage mortgage program requires that the contracted value would not surpass the acquisition value limits in the county the place the property is situated.

    Florida County
    Non-Targeted Area
    Targeted Area

    Alachua
    $317,789
    $388,150

    Baker
    $303,789
    $371,150

    Bay
    $295,789
    $361,550

    Bradford
    $287,789
    $352,050

    Brevard
    $312,789
    $382,450

    Broward
    $345,789
    $422,850

    Calhoun
    $275,789
    $337,050

    Charlotte
    $295,789
    $361,550

    Citrus
    $275,789
    $337,050

    Clay
    $310,789
    $380,150

    Collier
    $350,789
    $429,050

    Columbia
    $290,789
    $355,450

    DeSoto
    $275,789
    $337,050

    Dixie
    $275,789
    $337,050

    Duval
    $325,789
    $398,450

    Escambia
    $300,789
    $367,550

    Flagler
    $310,789
    $380,150

    Franklin
    $280,789
    $343,050

    Gadsden
    $285,789
    $349,450

    Gilchrist
    $275,789
    $337,050

    Glades
    $275,789
    $337,050

    Gulf
    $275,789
    $337,050

    Hamilton
    $275,789
    $337,050

    Hardee
    $275,789
    $337,050

    Hendry
    $275,789
    $337,050

    Hernando
    $290,789
    $355,450

    Highlands
    $275,789
    $337,050

    Hillsborough
    $340,789
    $416,450

    Holmes
    $275,789
    $337,050

    Indian River
    $310,789
    $380,150

    Jackson
    $275,789
    $337,050

    Jefferson
    $275,789
    $337,050

    Lafayette
    $275,789
    $337,050

    Lake
    $315,789
    $386,150

    Lee
    $335,789
    $410,450

    Leon
    $320,789
    $392,150

    Levy
    $275,789
    $337,050

    Liberty
    $275,789
    $337,050

    Madison
    $275,789
    $337,050

    Manatee
    $340,789
    $416,450

    Marion
    $290,789
    $355,450

    Martin
    $345,789
    $422,850

    Miami-Dade
    $330,789
    $404,450

    Monroe
    $360,789
    $440,950

    Nassau
    $330,789
    $404,450

    Okaloosa
    $320,789
    $392,150

    Okeechobee
    $275,789
    $337,050

    Orange
    $335,789
    $410,450

    Osceola
    $330,789
    $404,450

    Palm Beach
    $345,789
    $422,850

    Pasco
    $310,789
    $380,150

    Pinellas
    $325,789
    $398,450

    Polk
    $295,789
    $361,550

    Putnam
    $275,789
    $337,050

    Santa Rosa
    $295,789
    $361,550

    Sarasota
    $330,789
    $404,450

    Seminole
    $325,789
    $398,450

    St. Johns
    $335,789
    $410,450

    St. Lucie
    $310,789
    $380,150

    Sumter
    $295,789
    $361,550

    Suwannee
    $275,789
    $337,050

    Taylor
    $275,789
    $337,050

    Union
    $275,789
    $337,050

    Volusia
    $305,789
    $374,150

    Wakulla
    $275,789
    $337,050

    Walton
    $320,789
    $392,150

    Washington
    $275,789
    $337,050

    Bottom Line

    Florida Housing gives numerous mortgage packages to help eligible homebuyers, together with grants for full-time employees and deferred cost loans which can be important for making homeownership extra attainable in economically various areas.

    To qualify for these packages, candidates should meet particular standards together with earnings limits, buy value limits, and first-time homebuyer standing, alongside minimal FICO scores and FHA necessities.

    The earnings and buy value limits fluctuate considerably throughout counties, accommodating each non-targeted and focused areas that are designed to encourage funding in economically distressed places.

    To discover your eligibility and study extra about how these packages might help you buy a house in Florida, go to MakeFloridaYourHome.

    With over 50 years of mortgage business expertise, we’re right here that will help you obtain the American dream of proudly owning a house. We try to offer the very best schooling earlier than, throughout, and after you purchase a house. Our recommendation relies on expertise with Phil Ganz and Team closing over One billion {dollars} and serving to numerous households.

  • APM Elevate: March 2024

    As we changeover into the spring season, we’re thrilled to share essential insights and updates from the globe of residence finance.

    In this model, we are going to delve into vital enterprise traits, current beneficial sources to empower you in your homeownership journey – and even share just a few suggestions about your IRA and adjustments to credit score rating card late prices which can be on the horizon.

    APM Elevate March 2024

    Whether or not you are a initial-time purchaser, a seasoned home-owner, or just simply curious in regards to the residence finance mortgage panorama, we’re beneath to take care of you knowledgeable and equipped with the knowledge you need. Let us dive in and try what March has in retail outlet!

    Achieve YOUR Ambitions

    Sign up for Us in Celebrating Women’s History Month

    March is Women’s Heritage Thirty day interval, which might make it a wonderful time to glimpse at girls’s place in American banking and finance, along with their achievements greater than the numerous years.

    Initially, allow us to search at some historic examples of monetary inequality that you possibly can or may not be educated of.

    Until finally 1974, banking establishments might legally deny credit standing to women based fully on their gender or marital standing. Often credit standing was issued provided that there was a co-signer, these sorts of as a partner or father.
    In the course of the Nineteen Sixties, gender redlining was prevalent. Gals had been being charged elevated fascination premiums than guys, particularly in the event that they had been solitary or divorced.
    Both of these cash and different enterprises normally important girls of all ages to surrender their work alternatives if and once they married. This eradicated their potential to assemble a separate credit score historical past file.

    Even although 100% equality hasn’t nonetheless been achieved, the final a very long time have seen some essential enhancements.

    In 2009, the Lily Ledbetter Good Shell out Act turned regulation. It stated that companies had been prevented from discriminatory pay out costs based mostly on intercourse, race, shade, religion or nationwide origin.
    An elevating amount of girls have turn into CEOs of Fortune 500 firms all by the previous 24 a number of years. Economist Janet Yellen grew to turn into the preliminary head of the Federal Reserve.
    Women have develop to be much better savers, placing absent an typical of 9% of their yearly earnings though grownup males preserve an frequent of 8.6%.

    Resource: bankrate.com

    Home mortgage IQ

    Completely prepared To Obtain? A HomePrepared® Personal mortgage Could Be the Respond to.

    The final a number of years have produced home possession rather more powerful, particularly for potential consumers who require assist with closing bills. Starting earlier than this 12 months, alterations to the HomePrepared residence mortgage system had been being launched, like a $2,500 credit standing for debtors with constrained incomes.

    HomePrepared monetary loans are backed by Fannie Mae, a government-sponsored entity that was developed to assist extra working Individuals spend money on houses. Applicants may qualify for a HomePrepared mortgage or refinance if their residence income falls beneath a specific limit.

    Other pointers, this type of as adaptable credit score historical past scores and down funds as little as 3%, make HomePrepared an possibility for these who could maybe not qualify for different types of mortgages. Concerns? Get in contact with me to grasp way more about HomePrepared and different home funding options.

    Resource: singlefamily.fanniemae.com

    Financial News

    Bypass the Roth IRA’s Money Limitations As a results of the Backdoor

    If you’ve established up a Roth IRA to assist fund your retirement, you may appear ahead to tax-cost-free withdrawals and additional funding options. Having stated that, you may finally function up in opposition to the Roth IRA’s revenue limitations, which signifies you’d no lengthier be geared up to make a contribution to your account.

    Just one methodology to bypass the income restrictions is by setting up a backdoor Roth IRA. This enables you to to remodel non-deductible, common IRA contributions to a Roth IRA.

    What is the excellence amongst a Roth IRA and a backdoor Roth IRA?

    A Roth IRA is an account which makes it attainable for tax-totally free withdrawals in retirement. When you’ve a Roth IRA, you add quickly after-tax {dollars}—as much as a sure restrict every particular person 12 months. You will get hold of info of those boundaries on-line on the IRS site.

    A “backdoor” Roth IRA permits massive earners to sidestep the Roth IRA’s cash restrictions by changing nondeductible basic IRA contributions to a Roth IRA. That normally necessitates you to pay out income taxes on cash remaining rolled into the Roth account that haven’t beforehand been taxed. In this text are the fundamental measures for backdoor contributions:

    1. Open up and make a nondeductible contribution to a brand new customary IRA, or add to an present customary IRA.

    2. Convert your contributions to a Roth IRA. The nondeductible contribution principal sum will not be taxable as with a traditional Roth IRA conversion, however the earnings might be taxable.

    One specific essential rule pertinent to the backdoor Roth conversion is the skilled rata rule. If you you attempt to rework quickly after-tax basic IRA contributions to a Roth IRA, however there are current pretax IRA kilos, you might be subjected to taxation on a prorated basis.*

    Source: empower.com

    *We are fairly clever, however we’re not licensed financial planners, CPAs or tax execs. You could presumably wish to speak about your Roth IRA methods with an individual like them.

    DID YOU KNOW?

    Staying Polite Goes a Long Way, Even With AI

    Irrespective of whether or not you’ve got began conversing with ChatGPT, Google Bard or yet another AI chatbot, it would be best to be superior to them, no make a distinction what mood you is perhaps in. Here’s why.

    Recently, researchers at Cornell University examined six fashionable AI chatbots by assigning them dozens of duties, using as much as 150 distinctive prompts every particular person time. Out of many traits that emerged, the chatbots that acquired well mannered prompts delivered higher, extra exact responses.

    Scientists discovered that impolite prompts “could maybe information to a deterioration in product efficiency, similar to generations made up of faults, extra highly effective biases, and omission of knowledge.” This was not restricted to English language prompts and responses, because the chatbots responded equally when buying prompts in Japanese and Chinese.

    Although they weren’t hurting any chatbot emotions, they noticed that they mirrored sure dialog qualities shared by people (successfully, most of us). Inquiring a question politely in true time normally encourages a higher response, and fairly just a few chatbots’ language varieties have adopted this.

    Supply: axios.com

    Individual Funds

    CFPB Reins In Credit historical past Card Late Service charges

    Earlier this 7 days, the Purchaser Economical Safety Bureau (CFPB) issued a brand new ruling to decrease the same old credit standing card late cost from near $32 to $8. The company talked about that the 45 million consumers who incur occasional late charges might save additional than $10 billion (about $31 per specific individual within the US) each single yr.

    Even although some banking commerce teams objected to this transfer, legislators see it as an exertion to close a loophole within the Credit rating Card Accountability Obligation and Disclosure (CARD) Act of 2009.

    This is rather more {qualifications} on this go: The CARD Act banned credit score rating card firms from charging bigger late fees than wanted to go over the charges concerned with the late cost. But the Federal Reserve Board of Governors voted to incorporate issues like a provision within the CARD Act that permitted banking firms to cost as much as $25 for the initially late cost and $35 for different late funds. In addition, these figures had been altered for inflation. This resulted in frequent late charges increasing to $32 in 2022, which was $10 rather more than 2010 bills.

    The cut back prices are anticipated to amass influence inside 3 months, which might give card issuers time to replace their disclosures and methods.

    Resource: nerdwallet.com

    Meals

    St. Patrick’s Working day Sugar Cookies

    Not solely does this recipe for normal sugar cookies have secrets and techniques for easier rollouts, additionally, you will learn the way to implement icing that stays set! In addition to a shamrock-shaped cookie cutter, you should use fundamental rectangular cutters for Irish flags and even hat-formed cutters for leprechaun headwear.

    Serious ESTATE Traits

    Clever Telephone, Intelligent Car or truck…Now Smart Home furnishings

    Have you at any time checked right into a lodge house and seen lamps or tables with constructed-in USB chargers? You could have even already acquired an individual or much more items of residence furnishings on your residence with these increase-ons, particularly when you’re weak to eliminating or loaning out your phone or laptop computer pc price cords.

    If you is perhaps redecorating this spring, you might properly wish to take into consideration one specific or extra of those objects. They can help you loosen up, be rather more profitable, or in no way get off the bed till lastly you are nice and all set.

    Wise Tables

    If your notion of an ideal sport day or Netflix binge-view is to rarely need to stand up to get a devour or snack, a wise desk could possibly be the choice. Whilst these began to floor many a number of years again, some producers have taken sensible tables into genius method. For illustration, LIVTAB’s LT135 smart espresso desk is made up of refrigerated drawers, wi-fi audio system, a charging center and lights. You may bear in mind a lesser bedside desk/fridge combo full with motion-detected lightweight.

    Gaming and Function Desks

    Even although a wise desk can help you purchase command of the a number of electrical energy cords functioning out of your pc, screens and audio system, there are extra capabilities obtainable. In addition to the frequent standing desk possibility, different increase-ons encompass regulate arms, created-in lights and supplemental methods to administration these pesky vitality cords.

    Sensible Beds

    Though one of the best mattress room ought to be a comforting location, a clever mattress can provide these and many rather more. Whilst not for scaled-down budgets, a wise mattress might include created-in audio system, USB charging ports, built-in lights, and extra. Some of probably the most deluxe designs happen complete with an air purification methodology and therapeutic therapeutic massage chair.

    Supply: jubileefurniturelv.com

  • Financial Health: April 2024

    As April blossoms forth, indicators of renewal are throughout us. Though inflation and the specter of upper rates of interest linger, there’s hope within the air. Forecasters predict a gradual upturn within the residential actual property market, with extra new constructions and current properties hitting the market all through 2024, akin to buds bursting into bloom. Moreover, customers might discover reduction of their funds following the latest resolution by the CFPB to rein in financial institution overdraft charges and bank card late fee costs, promising a brighter monetary panorama forward.

    financial fitness april 2024

    Home Financing

    Proposed Tax Incentives for Home Buyers and Sellers

    During his March State of the Union speech, President Biden launched plans to deal with the nation’s points with lack of inexpensive housing. These included the introduction of two new tax breaks: one for first-time consumers, and one other for the sellers of the starter properties which have turn into scarce.

    First time homebuyers would obtain a $5,000 mortgage reduction credit score for the primary two years after their buy. This could be roughly equal to reducing mortgage rates of interest for these consumers by 1.5 proportion factors.

    Sellers who half with their starter properties would obtain a one-year credit score of as much as $10,000. In this occasion, starter properties are outlined as properties valued under the median value for the vendor’s county.

    These tax breaks are estimated to help over 3 million first-time consumers, along with the same variety of sellers.

    Details of those and different housing-related issues, together with proposals to help renters, had been just lately launched by the White House and made obtainable throughout the March 7 Fact Sheet. The content material discusses the acquainted “golden handcuffs” downside that plagues owners who obtained their mortgages throughout 2020 and 2021, when charges had been at near-historic lows. Although many of those owners are experiencing purchaser’s remorse and want to promote, they’re understandably reluctant, as shopping for one other house would require a brand new mortgage at a significantly greater rate of interest.

    Source: cnbc.com

    Insurance

    Protection From Unwelcome Surprises: Umbrella Insurance

    While insurance coverage protection is designed to guard your belongings from losses, unexpected circumstances—or simply plain dangerous luck—can play havoc along with your funds and extra. This is when an umbrella insurance coverage coverage can stop this from occurring by protecting claims which are outdoors, or exceed, your current insurance policies’ limits.

    Here are some examples of unpredictable occasions the place umbrella protection might save the day:

    • Your canine escapes and assaults a neighbor, who sues you to cowl medical payments, misplaced wages, and ache and struggling.
    • You trigger a six-car accident, and your insurance coverage protection does not cowl the medical and restore prices of all drivers and their autos.
    • You ship sandwiches to your son’s faculty for a discipline journey lunch. Several college students come down with meals poisoning, and their mother and father sue you.

    Umbrella insurance coverage additionally covers sure legal responsibility claims comparable to libel, slander, and false imprisonment. And if you happen to personal rental property, umbrella insurance coverage gives legal responsibility protection past what your renter’s coverage covers. It might be the protection that helps you and your loved ones members (and your pets) sleep higher at night time.

    Source: bankrate.com

    In the News

    Inflation’s Not a Quitter

    Even although this yr’s inflation numbers are significantly decrease than in 2022 and 2023, they’re nonetheless enjoying havoc with costs and budgets. Data launched earlier this week mirrored a rising Consumer Price Index (CPI). Some of the objects which are nonetheless dogged by inflation embody housing prices and insurance coverage premiums. Gasoline costs additionally spiked throughout February.

    The CPI rose 0.4% in February, whereas the Core CPI quantity that excludes meals and power costs elevated by the identical quantity. Core CPI, which economists see as a key gauge of underlying inflation, additionally rose 0.4% in January, reflecting a rise from extra gentle will increase in late 2023.

    Looking on the numbers for the final 12 months by way of February, total inflation was 3.2%, in comparison with the three.1% as of January. Core CPI was 3.8%, versus the three.9% the prior month—the bottom since 2021.

    The new knowledge will most definitely have an effect on the timing for the Federal Reserve’s deliberate charge cuts for this yr. Members of the Fed have described plans to chop rates of interest in some unspecified time in the future this yr, although policymakers say they need extra proof that inflation is actually receding.

    Source: axios.com

    Credit and Consumer Finance

    CFPB Slashes Credit Card Late Fees

    Earlier this month, the Consumer Financial Protection Bureau (CFPB) issued a brand new ruling to cut back the everyday bank card late payment from round $32 to $8. The company stated that the 45 million customers who incur occasional late charges might save greater than $10 billion (about $31 per individual within the US) annually.

    While some banking commerce teams objected to this transfer, legislators see it as an effort to shut a loophole within the Credit Card Accountability Responsibility and Disclosure (CARD) Act of 2009. The CARD Act banned bank card firms from charging greater late charges than essential to cowl the prices related to the late fee. But the Federal Reserve Board of Governors voted to incorporate a provision within the CARD Act that allowed banks to cost as much as $25 for the primary late fee and $35 for different late funds. In addition, these figures had been adjusted for inflation. This resulted in common late charges rising to $32 in 2022, which was $10 greater than 2010 charges.

    The decrease charges are anticipated to take impact later this yr, which might give card issuers time to replace their disclosures and methods.

    Source: nerdwallet.com

    Did You Know?

    Take Spring Cleaning Outdoors

    While we’re all accustomed to the phrase spring cleansing, many people are inclined to assume it solely applies to our house’s interiors. However, your property’s exteriors will profit from inspections and tidying simply as a lot because the indoors, particularly as it can save you on restore payments by recognizing and remedying issues. Here’s a useful record of spring duties that may maintain your property wanting and performing its finest.

    Air Conditioning Systems

    Trim any weeds or different plant progress close to your A/C compressor. If you may have an proprietor’s handbook, test to see if different upkeep is required.

    Foundation

    If you discover cracks in your own home’s basis or exterior partitions, or gaps round a number of home windows, seek the advice of knowledgeable.

    Roof Gutters

    Inspect your gutters and downspouts for rust or leaks. If water is not diverted away from your property, it might finally trigger basis and different issues

    Trees

    Look for damaged limbs or any indicators of illness or insect infestation. You might need to seek the advice of a tree surgeon or arborist if a number of timber are dying.

    Windows

    If caulking and/or climate stripping are leaking, it is time to renew or exchange. Consider changing your home windows if final yr’s electrical energy payments had been painfully excessive.

    Source: frontdoor.com