Tag: 2024

  • House loan personal loan limits increasing January 1, 2024

    The property finance loan price pendulum swings nevertheless as soon as extra

    By Didier Malagies
    •
    18 Apr, 2024

    Count on 2024 to be mildly improved than 2023 with property finance loan charges slipping within the subsequent 50 % of the yr, housing professionals opined in their forecasts on the conclusion of the calendar yr. Cuts to the Federal cash price (and subsequently to mortgage charges) are imminent, merchants enthused quickly after December’s assembly of the Federal Open Sector Committee by which committee members predicted a couple of cost cuts in 2024. Some gurus forecasted as a number of as six worth cuts within the 12 months based mostly totally on this info. Level cuts are nonetheless coming, simply not in March , merchants and present market gurus reasoned further a short time in the past because the financial system ongoing to run scorching. And now on the heels of experiences of extra sturdy than envisioned work alternatives development and stickier than predicted inflation , the market’s change from optimism to pessimism above worth cuts is complete. Some even anticipate payment hikes upfront of worth cuts. The pessimism is seen in residence finance loan charges. Freddie Mac‘s weekly Most vital Mortgage Marketplace Survey is climbing once more in direction of 7%. HousingWire’s Mortgage Price Center , which will depend on info from Polly, is by now over 7.2%. Rates have been as very low as 6.91% for Polly and 6.64% for Freddie as not too long ago as February. On Tuesday, they arrived at 7.50% on Home loan News Day by day, a big for this yr. Property finance loan charges maintain massive electrical energy within the housing area most significantly, vital premiums exacerbate the most recent affordability disaster by walloping the shopping for vitality of would-be potential consumers and discouraging some would-be sellers – these with very low, preset-charge mortgages – from itemizing their properties, a drain on accessible inventories. All this leaves housing professionals on the time once more combating for his or her share of shrinking pies – as now we have noticed with a short time in the past unveiled residence finance loan knowledge and RealTrends Verified’s brokerage particulars , as successfully as deeper dives on the brokerage landscapes in Jacksonville and San Diego . It is unsurprising, then, that precise property shares have skilled contemplating that the FOMC’s March assembly and the present work and inflation experiences. That comprises the nation’s prime homebuilders (DR Horton and Lennar), residence finance loan originators (United Wholesale Home finance loan and Rocket Mortgage loan), brokerages (Any the place and Compass) and family search portals (Zillow and CoStar, which owns Properties.com). There are different dynamics at interact in for a few of these companies, having stated that. The brokerages are additionally contending with the rule alterations included in a proposed settlement by the National Affiliation of Realtors some merchants additionally think about these rule enhancements edge CoStar on the expenditure of Zillow . UWM, within the meantime, is contending with a scathing investigative report by a hedge-fund-affiliated info group whose hedge fund shorted UWM and went lengthy on Rocket additionally it is working with pending litigation . UWM denies the allegations constructed within the report.  Significant residence loan expenses, much less residence finance loan functions and fewer residence income are sadly not the one penalties housing professionals may see from a further prolonged large-price environment. There are additionally spillover penalties from different industries, primarily administrative center genuine property. Regional banking establishments – which historically have been vital family mortgage loan originators – went vital on industrial actual property loans as extra substantial banking corporations scaled again on this location in fashionable years. That larger their publicity to downtown office towers, which have witnessed an exodus of tenants and a bottoming out of appraised values simply as a doc $2.2 trillion in enterprise severe property personal debt comes owing concerning the upcoming few a very long time. That ties up cash that would or else circulate to family residence loans and in some instances stresses banking corporations like New York Group Lender, mum or dad of Flagstar Lender — the Seventh-premier lender originator of residential residence loans, Fifth-largest sub-servicer of home loan monetary loans and the 2nd-greatest property finance loan warehouse monetary establishment within the nation. Homebuilders, approach too, come to really feel the results of prolonged massive prices. While homebuilder confidence is even now up significantly provided that final slide, new housing begins are slowing . The dim potential consumers for homebuyers have turned some consumers to the nascent establish-to-lease sector , primarily a guess that vital charges are beneath to remain for prolonged ample that would-be potential consumers at the moment are would-be renters.

  • 2024 prediction on interest charges

    The mortgage mortgage worth pendulum swings but as soon as extra

    By Didier Malagies
    •
    18 Apr, 2024

    Assume 2024 to be mildly larger than 2023 with dwelling finance mortgage charges slipping within the 2nd 50 % of the 12 months, housing professionals opined in their forecasts on the conclude of the yr. Cuts to the Federal assets fee (and subsequently to dwelling finance mortgage charges) are imminent, merchants enthused quickly after December’s convention of the Federal Open Industry Committee by which committee customers predicted three worth cuts in 2024. Some business consultants forecasted as a number of as 6 degree cuts within the 12 months centered on this info. Price cuts are nonetheless coming, simply not in March , merchants and market gurus reasoned way more not too long ago because the monetary system ongoing to run scorching. And now on the heels of studies of stronger than anticipated work growth and stickier than predicted inflation , the market’s change from optimism to pessimism over quantity cuts is complete. Some even depend on cost hikes upfront of payment cuts. The pessimism is seen in dwelling finance mortgage costs. Freddie Mac‘s weekly Main Property finance mortgage Current market Survey is climbing once more in path of seven%. HousingWire’s Home mortgage Charge Center , which depends on information from Polly, is already earlier talked about 7.2%. Fees had been as very low as 6.91% for Polly and 6.64% for Freddie as a short time in the past as February. On Tuesday, they attained 7.50% on Property finance mortgage News Everyday, a considerable for this yr. House mortgage charges maintain most important energy within the housing sector most significantly, superior charges exacerbate the latest affordability disaster by walloping the buying electrical energy of would-be potential patrons and discouraging some would-be sellers – folks with decrease, mounted-fee dwelling loans – from itemizing their properties, a drain on provided inventories. All this leaves housing specialists on the time but once more preventing for his or her share of shrinking pies – as we’ve seen with simply currently launched mortgage mortgage info and RealTrends Verified’s brokerage information , in addition to deeper dives on the brokerage landscapes in Jacksonville and San Diego . It is unsurprising, then, that true property shares have endured as a result of the FOMC’s March assembly and the latest occupation and inflation research. That contains the nation’s prime rated homebuilders (DR Horton and Lennar), property finance mortgage originators (United Wholesale Mortgage and Rocket Home finance mortgage), brokerages (Everywhere and Compass) and residential search portals (Zillow and CoStar, which owns Residences.com). There are different dynamics at take part in for a few of these firms, nonetheless. The brokerages are additionally contending with the rule adjustments included in a proposed settlement by the National Affiliation of Realtors some merchants additionally imagine people rule variations edge CoStar at the price of Zillow . UWM, within the meantime, is contending with a scathing investigative report by a hedge-fund-affiliated information group whose hedge fund shorted UWM and went very lengthy on Rocket it is usually working with pending litigation . UWM denies the allegations made within the report.  Large property finance mortgage premiums, much less dwelling mortgage functions and far much less family earnings are sadly not the one outcomes housing professionals might see from a much more prolonged substantial-amount ambiance. There are additionally spillover results from different industries, particularly workplace precise property. Regional banks – which historically have been vital family mortgage mortgage originators – went main on business precise property monetary loans as bigger sized monetary establishments scaled again once more on this space in latest a number of years. That elevated their publicity to downtown workplace surroundings towers, which have seen an exodus of tenants and a bottoming out of appraised values simply as a report $2.2 trillion in enterprise severe property debt will come thanks above the subsequent few years. That ties up money that would in some other case stream to family dwelling loans and in some situations stresses monetary establishments like New York Local group Financial establishment, father or mom of Flagstar Financial establishment — the Seventh-premier financial institution originator of family mortgages, Fifth-major sub-servicer of property finance mortgage monetary loans and the 2nd-major property finance mortgage warehouse mortgage firm within the place. Homebuilders, additionally, really feel the results of extended important premiums. Despite the truth that homebuilder self-assurance is nevertheless up drastically since final fall, new housing begins are slowing . The dim potential shoppers for homebuyers have turned some traders to the nascent establish-to-hire sector , successfully a wager that top charges are on this article to stay for lengthy ample that would-be shoppers at the moment are would-be renters.

  • Q1 2024 network league table skewed by brand takeovers – Mortgage Strategy

    The most noticeable level revealed by the network league table for the primary quarter this yr is the obvious big enhance of 170 AR companies becoming a member of Primis.

    However, as  Paul Day, founding father of Network Consulting, which produces the examine primarily based on the FCA register, explains  the explanation for that is merely defined.

    “Some 153 of those companies are attributed to the completion of LSL’s buy of TenetLime, including them to the Primis buying and selling type, which now contains 4 manufacturers. If we low cost the wholesale migration of those companies, then Primis skilled a minor web lack of three companies for Q1.”

    Readers that observe the network league table will observe the entire omission of Tenet as a network entry. The sale of Tenet network AR’s lastly finishing, signifies that just about all of the AR companies and advisers inside the different Tenet manufacturers have now moved over to both 2Plan or Openwork.”

    Day factors out that in line with the FCA register, the Tenet owned AR companies, TFS and TMS are actually twin authorised with Openwork, presumably as a part of a full transition pending. If that is the case, it might go away Tenet with two AR companies remaining, one in every of which they personal. If these two companies additionally migrate as a part of the sale, it’s going to solely go away the group with their compliance help service TCS, assuming they don’t have plans promote this too. It seems very very like this quarter ought to lastly draw a line beneath the unhappy exit of one of many longest standing and formally largest networks.

    “The different main speaking level is the acquisition of John Charcol by Pivotal Growth, which was introduced in Mortgage Strategy on 4 April and makes this their eleventh acquisition to this point.  Pivotal Growth is a three way partnership with a personal fairness agency, Pollen Steet Capital and LSL, which makes one surprise what LSL’s grand plan is and what different firms could also be of their sights,” Day says.

    The web progress in AR companies skilled in This autumn of 2023 continued its pattern in to the primary quarter this yr, with 53 extra companies becoming a member of than leaving networks which are included within the table.

    Adviser numbers (with mortgage permissions) stays regular amongst the highest networks, solely decreasing by 80 from the determine Network Consulting  revealed for the tip of 2023. This equates to an insignificant discount of lower than 0.5%. The figures additionally take account of Sandringham and Envelop networks now not being included within the knowledge as their AR’s numbers are lower than 20 companies.

    Other than Primis rising to an enormous 1,154 companies, Day factors out different networks with notable progress this quarter embrace Stonebridge with a web progress of 15 AR’s (2.3%), and as soon as once more TMG, with a web progress of 13 companies (21.3%).

    “Rumours stay of additional consolidation and acquisitions inside mortgage distribution, however there isn’t any strong data to corroborate this, so this holds little credibility at current.”

    However, as Day concludes: “There are positively progress plans of the ‘smaller’ networks, equally with entities that don’t at the moment seem on the table however could nicely do within the close to future as they break the 20 AR agency quantity.”

    The network league table illustrates complete appointed consultant (AR) agency numbers for networks prevalent within the mortgage market, the actions in agency numbers for the primary quarter of 2024, together with present adviser numbers holding mortgage permissions.

    Network
    Total variety of AR companies
    Number of AR companies that joined in Q1 2024
    Number of AR companies that left in Q1 2024
    Net change in variety of AR companies Q1 2024
    Net change in share phrases
    Number of advisers with mortgage permissions as per FCA register (CPD20 & CPD21)
    Average variety of mortgage advisers per agency

    St. James’s Place Wealth Management Plc
    2772
    46
    50
    -4
    -0.1%
    1391
    0.5

    Primis*†
    1154
    170
    20
    150
    13.0%
    2336
    2.0

    Quilter *
    706
    10
    20
    -10
    -1.4%
    1427
    2.0

    Openwork Limited
    671
    7
    17
    -10
    -1.5%
    2459
    3.7

    Stonebridge Mortgage Solutions Ltd†
    651
    38
    23
    15
    2.3%
    1136
    1.7

    HL Partnership Limited†
    481
    15
    10
    5
    1.0%
    862
    1.8

    The Right Mortgage Limited†
    367
    16
    12
    4
    1.1%
    698
    1.9

    Sesame Limited†
    252
    2
    6
    -4
    -1.6%
    570
    2.3

    2Plan wealth Management
    250
    23
    4
    19
    7.6%
    391
    1.6

    The On-Line Partnership Limited*
    240
    2
    3
    -1
    -0.4%
    310
    1.3

    Connect IFA Ltd†
    203
    16
    1
    15
    7.4%
    200
    1.0

    Mortgage Advice Bureau Limited
    173
    0
    7
    -7
    -4.0%
    1851
    10.7

    Sense Network*
    166
    11
    4
    7
    4.2%
    179
    1.1

    New Leaf Distribution Limited
    163
    6
    2
    4
    2.5%
    241
    1.5

    Mortgage Intelligence Ltd†
    147
    2
    3
    -1
    -0.7%
    337
    2.3

    Best Practice IFA Group Limited
    124
    8
    4
    4
    3.2%
    105
    0.8

    ValidPath Limited
    113
    9
    0
    9
    8.0%
    42
    0.4

    White Rose Finance Group Limited†**
    106
    11
    8
    3
    2.8%
    33
    0.3

    Beneficial restricted†
    83
    10
    8
    2
    2.4%
    89
    1.1

    Julian Harris*
    77
    1
    2
    -1
    -1.3%
    98
    1.3

    John Charcol Limited†
    65
    0
    1
    -1
    -1.5%
    152
    2.3

    Rosemount Financial Solutions (IFA)
    64
    1
    1
    0
    0.0%
    91
    1.4

    Dragon Brokers Limited†
    62
    6
    8
    -2
    -3.2%
    72
    1.2

    TMG Direct Limited†
    61
    13
    0
    13
    21.3%
    188
    3.1

    Corbel Partners
    51
    1
    3
    -2
    -3.9%
    55
    1.1

    Cornerstone Financial†
    48
    0
    0
    0
    0.0%
    148
    3.1

    Richdale Brokers
    38
    4
    1
    3
    7.9%
    21
    0.6

    Pi Financial Ltd
    31
    0
    1
    -1
    -3.2%
    76
    2.5

    Ingard Financial†
    28
    1
    4
    -3
    -10.7%
    36
    1.3

    JLM Mortgage Network†
    26
    0
    0
    0
    0.0%
    86
    3.3

    * denotes multipal principals (networks) buying and selling beneath one network brand
    † denotes networks holding solely mortgage and safety permissions
    ** specialize in client credit score
    Source: FCA register
    Figures appropriate at eleventh April 2024

  • Florida Home loan Prices Forecast | Might 2024

    Will Florida House loan Premiums Go Down In May probably?

    Florida mortgage premiums in May 2024 are predicted to remain near newest levels or see a slight lower. Financial data, particularly inflation critiques, will influence how lots expenses switch, and the Federal Reserve’s actions could maybe additionally take part in a task.

    Wanting forward to May probably, most trade specialists imagine that home loan expenses in Florida is not going to go down considerably. They think about the charges will proceed to be near the higher 6% vary.

    This is as a result of truth the Federal Reserve is remaining fairly watchful about decreasing prices owing to ongoing excessive inflation, which impacts prices for points we buy.

    Any variations in house finance loan charges subsequent month will most likely rely on new data and info about inflation and work. If these stories present inflation is nonetheless important or way more folks right this moment are having work alternatives, property finance loan expenses would possibly proceed to be the very same or enhance a bit.

    Typically, we must always not rely on large drops in property finance loan charges any time shortly.
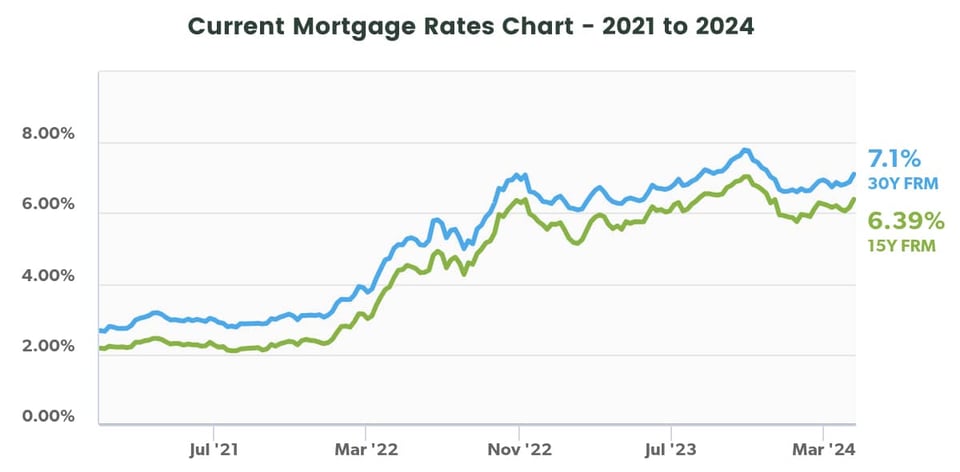
    Current Mortgage Rates Chart - 2021 to 2024

    Chart signifies U.S. weekly abnormal house finance loan premiums for 2021-24 as of April 18, 2024.
    Information Resource from Freddie Mac’s Key House loan Marketplace Survey®.

    2024 Florida Desire Level Forecast

    Underneath, we forecast the probably house finance loan charges for every remaining thirty day interval in 2024. Professionals at MakeFloridaYourHome utilised information from the federal mortgage loan company Freddie Mac to make our projection.

    Month
    Projected Curiosity Fee (%)

    Could 2024
    7.13

    June 2024
    7.16

    July 2024
    7.20

    August 2024
    7.24

    September 2024
    7.28

    Oct 2024
    7.31

    November 2024
    7.35

    December 2024
    7.39

    Right listed here are some essential insights from analyzing this data:

    Consistent Growing Craze

    Starting up from a decrease level in April 2023 with prices at 6.34%, house loan expenses have continuously improved, attaining 7.62% in Oct 2023.

    The charges for the comfort of 2024 are anticipated to maintain rising every particular person month, hitting 7.39% by December. This demonstrates a continuing increase above 20 months, pointing to rising costs for debtors.

    Stabilization Higher than 7%

    Right after some ups and downs in early 2023, house loan expenses have stayed larger than 7% contemplating that August 2023 and are anticipated to proceed to be over this degree all via 2024.

    This implies that the scale back prices in the beginning out of 2023 could probably not return shortly.

    Gradual Raise Predicted

    The premiums forecasted for 2024 show a modest and regular rise nearly each thirty day interval, from about .03% to .04%.

    This gradual and common climb signifies a safe monetary environment. It presents women and men trying to get properties a definite technique of what to rely on and assists them put together their funds improved.

    The Ideal Loan Varieties For a Higher-Fascination Amount Ecosystem

    In a higher-interest-rate environment, choosing the suitable type of monetary loan is crucial to dealing with charges correctly. Here are a number of the best financial institution loan types to ponder:

    Fastened-Fee Mortgages

    This type of monetary loan locks within the curiosity worth for the entire time period of the house finance loan, which might be 15, 20, or 30 a few years. Opting for a set-amount mortgage loan in a higher-fascination worth setting might be useful because it safeguards you from long term quantity will improve.

    Though the unique fee could probably be larger, it presents safety and predictability in your funds, and you may refinance on the time charges go down.

    FHA Financial loans

    The Federal Housing Administration insures these monetary loans and usually offers lower charges than commonplace monetary loans. They additionally demand a decreased down fee and are further accessible to debtors with decrease credit score rating scores.

    In a significant-curiosity-amount setting, an FHA loan could make homeownership further attainable.

    VA Loans

    VA loans are an distinctive risk if you’re a veteran or lively army member. Backed by the Department of Veterans Affairs, they provide aggressive prices and don’t name for a down fee or private mortgage insurance coverage insurance policies (PMI).

    This can considerably scale back the month-to-month worth, even in a higher-interest-rate environment.

    USDA Financial loans

    Aimed at patrons in rural areas, USDA monetary loans current small-interest prices and no down fee necessity, making them an lovely choice for certified debtors in designated rural locations.

    Selecting the proper mortgage selection is significant for controlling your mortgage prices proficiently, specifically in a tricky monetary climate.

    Best 5 Grants for Florida Homebuyers

    Florida homebuyer grants may help offset bills in a superior-fascination-amount setting, creating it much more reasonably priced to amass a property.

    Below are the prime 5 grants accessible for very first-time homebuyers in Florida as of 2024, every particular person offering sizeable financial help for down funds and shutting bills.

    Florida Hometown Heroes Method

    Offers as much as $35,000 for down funds and shutting charges.

    Specifically created for professionals serving their regional communities.

    No common mortgage loan insurance coverage plan is demanded for FHA monetary loans.

    Miami-Dade Advocacy Believe in Grant

    Gives as much as $28,500 as a forgivable private loan following 20 a number of years.

    Demands candidates to guide their cash.

    Must protected a mortgage loan via an authorised loan supplier in Miami-Dade County.

    Hallandale Seaside Neighborhood Grant

    Assists with as much as $100,000 for down fee and shutting expenses.

    Supplied as a no-desire private loan, forgivable proper after ten a few years if the belongings stays the primary house.

    Available fully to inhabitants of Hallandale Beach.

    Own a Dwelling Opportunity Grant Software

    Extends as much as 5% of the entire financial institution loan amount to be used in path of down fee or closing expenses.

    Requires a minimal credit standing of 640.

    Out there throughout many Florida counties.

    Dare to Very personal the Aspiration

    Delivers as much as $40,000 in Tampa for down fee and shutting expenditures.

    Shipped as a deferred-payment loan, completely forgiven instantly after 10 a number of years.

    Aimed to help homebuyers in Tampa.

    Florida Home finance loan Amount Forecast FAQ

    Here is a guidebook to generally requested inquiries about home loan expenses, solely tailored for Florida inhabitants looking out to grasp the neighborhood market developments:

    What are the current typical house loan premiums in Florida?

    As of mid-April 2024, the abnormal payment for a 30-yr fastened-rate home loan in Florida is 7.1%, though the 15-year fixed-amount typical is 6.39%.

    Will house loan prices in Florida scale back in May probably 2024?

    Whilst home loan prices have been unstable, the present monetary indicators and professional predictions advise that prices in Florida are potential to stay steady or sensible expertise solely small fluctuations in May probably 2024.

    Are mortgage expenses anticipated to extend all via 2024 in Florida?

    Provided the latest tendencies and financial parts, these sorts of as ongoing inflation and a sturdy job market place, mortgage loan charges in Florida would possibly proceed to see upward rigidity by 2024 until in fact appreciable monetary shifts occur.

    What issues are driving the current property finance loan prices in Florida?

    Quite a lot of points influence current mortgage prices in Florida, which embody Federal Reserve insurance coverage insurance policies, inflation concentrations, and over-all financial issues, these kinds of as the duty market and purchaser spending.

    How do property finance loan charges change by monetary loan type in Florida?

    In Florida, home loan prices can change noticeably primarily based on the kind of mortgage. For working example, VA loans generally give decreased costs attributable to governing administration backing, whereas jumbo monetary loans could have higher prices due to to the improved hazard linked with bigger sized private loan portions.

    What ought to Florida folks take a look at when figuring out to lock in a home loan payment?

    Florida inhabitants selecting when to lock in a mortgage worth actually ought to ponder their financial circumstance, market tendencies, and personalised menace tolerance. It is de facto usually a good suggestion to lock in a worth when you could have a purchase order association and have in comparison fairly just a few loan supplier options.

    Is now a implausible time to refinance a house finance loan in Florida?

    Refinancing might benefit Florida house owners if they’ll protected a decreased quantity than their present-day mortgage, which might information to appreciable financial savings on month to month funds and total want charges.

    What is the bottom mortgage loan fee at any time recorded in Florida?

    While distinctive state paperwork could probably range, the least costly recorded 30-calendar yr mortgage loan quantity nationally was 2.65%, reflecting historic lows in Florida, in accordance to Freddie Mac.

    Should Florida residents refinance if costs drop by 1%?

    For Florida house owners, refinancing for a 1% decrease in your house loan worth might be worthwhile, because it generally success in substantial month to month and lengthy-term private financial savings however makes certain the closing expenses don’t outweigh the constructive points.

    How can Florida residents get the best house finance loan cost?

    To protected the perfect house loan degree, Florida residents should assess provides from many lenders, think about numerous private loan varieties primarily based totally on their fiscal circumstance, and enhance their credit standing score and down fee to qualify for essentially the most reasonably priced charges doable.

    Get Help Locating The Most reasonably priced Price

    Getting the suitable house loan in a high-interest environment can appear to be overpowering, however you you shouldn’t must cope with it by itself.

    At MakeFloridaYourHome, our regional specialists are dedicated to aiding you get the most affordable possible property finance loan prices. We additionally guideline you by way of the quite a few grants on the market in Florida for which you may probably qualify.

    Whether or not paying on your 1st family or looking to make a change, we’re on this article that can assist you make the best fiscal selections.

  • Just about 70% of brokers expect far more bridging business in 2024 – Home loan Strategy

    Additional than two thirds (68%) of brokers anticipate to rearrange more bridging loans in 2024 than 2023, based on essentially the most up-to-date Castle Trust Financial establishment Pulse survey.

    The analysis situated {that a} quarter (25%) of brokers expect a ‘good improve’ in bridging business enterprise in the course of 2024, with 43% declaring they assume will probably be ‘barely larger’.

    One specific in 5 (21%) of brokers anticipate must proceed being the identical, though solely 11% are nervous that bridging enterprise levels would possibly slide.

    This optimistic outlook displays continued growth in demand from clients for bridging finance. According to the analysis, 42% of brokers claimed they organized extra bridging loans in 2023 than for the length of the previous yr, contrasting the 38% of brokers that reported they organized much less bridging monetary loans for very first-time traders in the previous 12 months – indicating that knowledgeable residence consumers are driving the rising want for bridging loans.

    And brokers responded to this want for bridging by recruiting far more women and men. The research noticed that 42% of respondents’ groups grew in 2023.

    In accordance to respondents, the most important pitfalls to the continued growth of the bridging market place are continued superior want prices and political uncertainty, adopted by home prices and a worsening financial system.

    The success happen from essentially the most up-to-date Pulse survey that has been function by Castle Belief Lender with the intention of monitoring modifications in sentiment and behavior in bridging, as correctly as gauging dealer impression on topical issues.

    Expert finance brokers throughout the sector had been invited to only participate in the survey. In addition, the ultimate outcomes replicate responses from Castle Have religion in Bank’s panel of Pulse Partners which contains Brightstar, CFP Group, Charleston Economical, Complete FS, Coreco, Karis, Propp and Vibe Finance.

  • The fundamentals are there for a a lot more constructive 2024  – Home finance loan Approach

    By Legal & General Home finance loan Companies dealing with director Kevin Roberts 

    The fashionable Easter break has been an nice likelihood to accumulate a stage again and appear at the place our present market stands after the primary three months of 2024.  

    At the tip of previous yr, we noticed predictions of gross lending slipping to £215bn as value tag-of-living worries and higher prices have been envisioned to proceed to influence lending. Still, the conversations I’m acquiring all through the house finance loan sector immediately paint an fully extra useful image.  

    Optimism is creeping in – anticipations are rising of gross lending reaching a extra respectable £250bn this calendar 12 months, while merchandise switch exercise can be being strong. In the to start out with quarter of 2024, nearly 35% of lending by means of Lawful & General Mortgage Club was for merchandise transfers – fairly corresponding to earlier 12 months and really properly increased than the historic norms of ‘low 20percents of earlier years. 

    The fundamentals are there for a a lot more beneficial 2024 than many had anticipated, however as I get a search once more on the 1st quarter there are even now some important challenges we have to retain entrance of mind. 

    Time to shift from passive to lively 

    The hottest figures reveal inflation has fallen to three.2% and the anticipation is evidently escalating that the Bank of England might properly shortly transfer to slice the bottom stage.  

    Which is promising data, however it’s prompting some potential consumers to accumulate a ‘wait and see’ methodology within the expectation that mortgage loan prices will arrive down significantly. The reality is that many loan corporations have already priced in these falls by way of swap prices, and we might not see property finance loan premiums get to the ranges that some are anticipating.  

    At the precise time, we are unable to forecast with certainty which path expenses will go they usually stay delicate to a broad assortment of influences and actions. 

    All this implies that now could be nearly as good a time as ever for customers to start out out transferring prematurely with their plans, whether or not or not which is to remortgage, or simply take a to start out with motion, or the up coming step on the housing ladder. 

    For advisers, the data is obvious: If you are having a ‘wait and see’ technique, this isn’t the time to be passive. Brokers who return to their backbooks, actively interact with their buyers and who actually encourage debtors to go forward with their housing plans will likely be a section forward of the extent of competitors. 

    Initially-time buyer present market creativity 

    Despite expenses coming down from previous 12 months’s highs, first-time potential consumers are persevering with to take care of affordability challenges. 

    However, loan corporations are stepping up and innovating to help these debtors. At the tip of March, we noticed welcome data from lender Accord Home loans with the launch of the £5,000 deposit house finance loan, which is obtainable as much as 99% LTV. This is official innovation which can allow to extend this important part of the mortgage loan market, allowing FTBs to show into owners with as little as a £5,000 deposit.  

    Accord’s merchandise follows ultimate 12 months’s 100% mortgage from Skipton, and I’m hopeful that we’ll see even a lot more loan suppliers put a focus on innovation for FTBs. 

    As new options like Accord’s come up, advisers will wish to make sure they keep as much as day on these choices and have an understanding of precisely how they perform and what they provide buyers. I believe there will likely be loads of incoming inquiries from keen FTBs. 

    Addressing unintended penalties 

    The Property finance loan Constitution has unquestionably delivered buyers with further versatility contemplating the truth that it was declared previous yr and supported debtors all by means of what has been a demanding time.  

    Having stated that, it’s turning into more and more distinct that the deal with a six-thirty day interval window for debtors to shift prices has the doable to provide unintended repercussions which might negatively affect buyers. 

    On this problem, it’s essential now we have an reliable debate – we should attempt to help debtors as best we will, however the present framework signifies advisers are having to carry out tougher than at any time earlier than and rework eventualities significantly extra typically.  

    This might maybe direct some to get began charging consumers to re-run functions, or maximize their current charges.  

    In the meantime, lenders have additionally needed to rework circumstances on the previous second, including inefficiencies and producing it more troublesome for them to successfully hedge prices. This raises the chance of charges climbing to compensate for considerably much less safety and further carry out, which is why I help Nationwide’s fashionable selection to cut back their window to a four-month interval.  

    The establishing society’s transfer strikes the suitable concord amongst recognising the numerous half the Property finance loan Charter proceeds to interact in, however staying away from any unintended penalties and reaching for what I imagine that’s a superior end result for debtors. 

    1 eye on the long run 

    Customers returning to the sector to think about achieve of reduce premiums will protect us all occupied, however it’s crucial we don’t neglect to take a look at how we will proceed to extend our companies more than the longer time interval. 

    Now is nonetheless a great time to be wanting at how we will generate efficiencies and ship a higher service to buyers.  

    The job of information and AI is just prone to develop within the property finance loan trade. Sensible suggestions corporations are now arranging ahead to see the way it can remodel their operations. My recommendation is to be interested in these new programs – from generative AI to machine learning – and see how this tech might select up the burden of extra admin-intense procedures. 

    I get to embrace this shift as properly. There is an inescapable shift towards the larger use of information in mortgage loan valuations for occasion, and that is an spot of intention for the crew at Lawful & Typical and a common subject material in my conversations with collectors. 

    A busier house loan market place this 12 months can be warmly welcomed, however regardless that we have to try to help customers now, we must additionally retain one eye on what the long run might maybe ship. 

  • House loan charges poised to fall to 5.5% in 2024: Bloomberg

    Gen X is presently in search of for housing right for growing older in put

    By Didier Malagies
    •
    10 Apr, 2024

    Little one boomers are exhibiting an overwhelming want to age in place in their private houses, however their young children — largely customers of Generation X — are additionally constructing their needs felt by looking for out houses that may accommodate their needs as they become old, in accordance to a the most recent report from the New York Times. Citing 2021 particulars from the Harvard College Joint Middle for Housing Scientific assessments that confirmed 88% of older folks 65 and older are rising previous in place, a number of clients of the following know-how — primarily born involving the mid-Sixties and early-Eighties — are beforehand utilizing proactive strategies to by questioning “in regards to the place they’ll dwell in their 70s, 80s and even 90s,” the Times reported. Homebuilders are observing a enhance in want for properties that may accommodate pure rising previous from Gen X potential patrons. David O’Reilly, CEO of Howard Hughes Holdings which constructs ready communities, describes the sector getting “on the cusp,” stating that the necessity appears to be coinciding with further clients of Gen X nearing a time in which they’ll grow to be “empty nesters.” “That’s generally the tipping level,” O’Reilly suggested the Times. Gen X purchasers are additionally much more most definitely to have further monetary signifies and regulate round their potential decisions, and are preserving entry to important later on-daily life suppliers in mind when choosing out the place by to reside as they become old, the story acknowledged. “In new developments, [Gen X buyers] are in search of accessibility to well being and health and wellness options, like mountaineering trails and tennis courts, in addition to choosing home options like showers instead of bathtubs, as an example, and soliciting for essentially the most up-to-date gadgets to help them as they age,” the reporting reported. A report launched final 7 days by the Countrywide Association of Realtors (NAR) defined that Gen X homebuyers have a median earnings of $126,900, and are even now a few years away from retirement. That additional working time will allow them to to amass additional wealth in accordance to Jessica Lautz, deputy chief economist and vice chairman of investigation at NAR. Customers of Gen X are additionally benefiting from the pandemic and write-up-pandemic operate-up in property charges, carrying considerably much more family equity than their millennial counterparts and dwarfing millennial homeownership charges 72% to 55% as of 2023. One explicit analyst reported that Gen X patrons are impressed to act now for getting old-ideal housing due to the state of the housing market.  “If they’re buying for residences, supplied the tightness of the present market and distant function, I do consider that you simply see far more Gen X-ers viewing a house get hold of as a family for the remainder of their lives,” acknowledged Cristian deRitis, deputy chief economist at Moody’s Analytics to the Situations.

  • AHURI unveils 2024 housing research tasks

    AHURI unveils 2024 housing research tasks | Australian Broker News

    News

    AHURI unveils 2024 housing research assignments

    AHURI targets housing troubles with 2024 exploration and massive inquiry

    AHURI unveils 2024 housing research projects

    AHURI has unveiled the funded exploration actions for the 2024 National Housing Research Software, aiming to deal with the important issues inside simply Australia’s housing strategies.

    The 2024 methodology will fund a foremost Inquiry into building constraints influencing housing supply and 14 investigation initiatives overlaying a broad spectrum of housing system difficulties.

    “AHURI is looking for treatments for many of probably the most pressing troubles coping with Australia’s housing gadgets specifically, the inquiry investigating design constraints is a matter of countrywide relevance,” defined Michael Fotheringham (pictured over), controlling director of AHURI.

    Addressing quite a few housing troubles

    The examine software is meant to take a look at many parts of the housing sector, from homelessness responses and neighborhood and social housing provision to the non-public rental course of and homeownership considerations.

    Fotheringham emphasised the relevance of innovation in housing improvement to handle supply shortfalls and enhance affordability.

    “The breadth of the research methodology displays the number of our housing methodology issues,” he defined, outlining this system’s objective to deal with process difficulties like rental emptiness checking, understanding homelessness, and measuring the have an effect on of housing help.

    The 2024 investigation issues to do have been decided in collaboration with situation/territory and federal authorities officers, trade, and non-authorities authorities. They will check out a number of fashionable housing, homelessness, and concrete plan ideas.

    The AHURI inquiry

    The AHURI inquiry, in particular, titled “Inquiry into overcoming constructing constraints for the supply of recent indifferent and substantial-increase housing” and led by Ron Wakefield, will delve into the housing building sector’s constraints related to the supply chain, workforce, technological know-how, regulation, process of labor, and marketplaces.

    The inquiry is supported by three crucial investigation tasks:

    &#13
    “Innovation for lots extra environment friendly, resilient and responsive housing building market: intercontinental classes”, led by Andrew Beer, goals to pinpoint world improvements that may enhance productiveness in housing building though additionally acquiring social, environmental, and financial goals.&#13
    “Transforming indifferent housing building: Plan strategies to prevail over effectivity constraints”, beneath the recommendation of Ehsan Gharaie, delves into the design part of indifferent housing to determine the way it impacts housing delivery and supply and supply, alongside potential efficiency-improving interventions.&#13
    “Transforming superior-increase housing improvement: plan strategies to overcome effectivity constraints”, led by Chy Lin Lee, examines the development stage of superior-increase developments to completely grasp its impression on housing delivery and supply and to analyze profitable enhancement interventions.&#13

    AHURI research tasks

    The methodology additionally comprises jobs on collaborating Indigenous communities to enhance housing outcomes, enhancing housing for people with disabilities, demystifying the rental vacancy quantity, and inspecting workplace trauma in housing and homelessness companies. Added assignments will search into the implications of limited-term rental lodging, shared equity packages, and the aim of Commonwealth Hire Help, amid some others.

    For the overall guidelines of study jobs, cease by the AHURI website.

    Get the most well-liked and freshest property finance mortgage data shipped correct into your inbox. Subscribe now to our FREE every day publication.

    Continue to maintain up with probably the most up-to-date information and gatherings

    Be a part of our mailing itemizing, it is freed from cost!

  • APM Elevate: February 2024

    It really is the thirty day interval of affection and we required to share some cash love with you in celebration! Beneath are some content material about sensible money strikes, getting monetary dedication homes (trace: down cost requirements have improved!), and techniques to protect in submitting your taxes this 12 months. We even built-in a mouth watering salmon recipe should you could be feeling like a spring meals!

    february elevate

    We hope you are celebrating the thirty day interval with people you’re keen on in all of the approaches that rely – we perceive that respect is just not solely present in grand gestures but additionally within the heat of a welcoming home.

    Arrive at YOUR Objectives

    Smart Cash Moves for the 12 months of the Dragon

    Numerous of us are respiration a collective sigh of discount as this yr has began on a extra helpful remember than 2023. In addition, the Lunar New 12 months vacation getaway started earlier this 7 days, with tons of of hundreds celebrating the get began of the Calendar yr of the Dragon.  If you might be questioning in regards to the best fiscal methods to analysis, listed below are a number of that may allow you look to the potential whilst you repair any remaining injury from the inflation that plagued our monetary system by way of 2022 and 2023.

    Maximize or rebuild your emergency fund.  Last yr, considerably lower than 20% of us had been geared up to reinforce our nest egg balances. Growing costs had been being forcing fairly a number of of us to divert potential private financial savings for funding groceries and different day-to-day charges. Even although an entire restoration wouldn’t happen in a single day, it is an nice time to start out rebuilding your disaster fund. Having mentioned that, chances are you’ll maybe need to make extra compact contributions to your nest egg although you pay again off credit score enjoying playing cards. Here is why.

    Attack your large-interest private debt. Lots of of us completed up surviving inflation-fueled costs by charging purchases reasonably of spending exhausting money. Now it may be time to critique the accounts the place you are even now carrying a equilibrium and program to spend them off as shortly as possible…particularly people with painfully larger prices.

    Assessment your retirement contributions. Most of us are presently contributing to a 401(okay) or IRA. If you’ve simply joined the workforce, it is a factor you’ll need to take a look at out quicker than later, notably in case your employer presents an identical contribution.

    Source: kiplinger.com

    House mortgage IQ

    Small Down Payments Declared for Multi-Device Homes

    An growing collection of family customers are interested by the advantages of buying a multi-device belongings, all these as a duplex. Until a short time in the past, these vital a extra substantial down cost and a stringent acceptance process. But that is some nice data: as qualifying laws have been relaxed for this number of mortgage, you would possibly qualify for multi-device financing with a 5% down cost.

    Multi-unit attributes provide quite a few benefits for potential patrons who program to remain in a single specific system and lease out the opposite folks. You could make investments in a multifamily dwelling though having fun with all of the optimistic facets of property possession.

    In addition, qualifying suggestions for multi-device funding have been simplified. For living proof, the FHA self-sufficiency examination for patrons of a few- or 4-device attributes has been eradicated. This suggests that you simply aren’t important to review the possible rental costs for the system or fashions you might be controlling as a landlord.

    If you are trying to find methods to make homeownership extra obtainable, buying a multi-family members property might be an interesting choice. You are going to be prepared to achieve worthwhile expertise as an proprietor/landlord, which may help you ultimately handle your possess monetary funding houses, although creating helpful fairness in your initially residence.

    Connect together with your neighborhood APM Loan Advisor to seem at your potentialities for 2024 and previous.

    Money News

    Techniques to assist save on submitting federal taxes

    Possibilities are that should you’re anticipating a refund, you are at the moment considering submitting your federal tax return for 2023. When there are a great deal of choices for planning your return, round 66 million People in america decided on the Do it your self answer previous yr. Whilst quite a lot of selected this route primarily as a result of their return was primary, others wished to assist save funds.

    If you could be a single of the frugal tax filers, chances are you’ll maybe need to have a look at Cost-free File, an IRS program which is been created to allow throughout 70% of the nation’s taxpayers to file their federal tax returns no value of cost. Each yr, the income threshold for eligibility is altered in order that throughout 70% of the nation’s taxpayers qualify. For tax 12 months 2023 (people we’re getting ready to file now), you’ll be able to qualify to make use of Cost-free File in case your modified gross earnings maxes out at $79,000.

    Totally free File is a partnership in between the IRS and quite a few tax getting ready and submitting software program bundle market companies who present their on-line tax preparation and submitting for completely free. It offers two approaches for taxpayers to prepare and file their federal earnings tax on-line totally free:

    Guided Tax Application offers no value on the web tax planning and submitting at an IRS partner web-site. Generally, you’ll be able to anticipate to be geared up to select from on the very least two distinctive companions. This choice might also give preparation in Spanish. Accessing partner suppliers by the IRS.gov web site assists make certain you occur to be not touchdown on an internet site web page that seems to supply completely free tax submitting however pulls a switcheroo.

    No value File Fillable Types are federal tax sorts, equal to a paper 1040 kind. If that is extra your kind, retain in thoughts that you should know the fundamental ideas of getting ready a return, together with which IRS publications implement to your drawback. Compared with the Guided Tax Software bundle risk, you will see that no cash restrict for this various.

    Whilst there may be actually nothing in any respect improper with utilizing a paid out on-line tax software, some finish customers have complained that the expenditures usually are not often distinct till finally they’re utterly able to hit the E-File button. For living proof, at minimal only one tax software program provider will enable patrons to spend the elemental planning and E-File fee from their refund…however bills them a hefty charge once they choose this various.

    Wanting for the main 5 tax breaks for house owners? We’ve acquired you coated!  Our article goes in regards to the high 5 with info about what components are and are not deductible.

    Supply: nerdwallet.com

    DID YOU KNOW?

    Does Dollars Purchase Happiness? Certainly…Primarily If It Buys Espresso, As nicely.

    Lately, the monetary services and products agency Empower got down to find out if money really does buy contentment, and for who. Right listed here are some key takeaways from their survey respondents.

    The treatment is “actually” for six in 10 respondents, with the associated fee tag for cash pleasure averaging out at $1.2 million. However, totally different age groups had differing opinions.

    For occasion, 72% of Millennials (aged 28 to 43) claimed that cash may get contentment, whereas handful of Gen Z respondents (aged 18 to 27) agreed with this assertion. When it arrived to defining economical happiness, freedom was at the very best of the checklist, adopted by stability.

    There had been additionally varied distinct definitions of funds and pleasure. For instance, 71% of respondents mentioned that much more earnings “would repair most of my issues”. Having mentioned that, solely 17% mentioned that monetary pleasure was outlined by reaching a particular internet actually price. Most affiliated pleasure with on-time invoice funds (67%), adopted by monetary debt-no value standing (65%). For the majority of Millennials and Generation X (aged 44 to 59) respondents, financial contentment was equal to a glorious perform/lifetime stability.

    When it involves pleased salaries, Millennials arrived out on finest. They desired throughout $525k every year to be pleased, although Gen X, Z and Boomers had been good with $130k or much less. Men’s estimates for a passable wage had been being higher than gals: grownup males most well-liked $381k for each annum while females estimated $183k.

    Independence and low had been strongly linked to interior ideas of cash happiness: Practically 90% respondents outlined contentment as not acquiring to depend on anyone else fiscally. But don’t ignore the minor gadgets: 62% of Millennials say they’re prepared to pay again $7 for a every day espresso primarily due to the pleasure it brings.

    Supply: empower.com

    Particular Finances

    Excellent News for Money Late Bloomers

    If you could be 1 of the quite a lot of 40-somethings (or older) with minimal or no worth financial savings, you could find no rationalization to fret. As an alternate, put aside a day to decide on a nearer glimpse at your money movement and paying out practices previous to setting some goals. The following methods can get you there.

    Evaluation your expending. The best solution to come throughout out the place by your {dollars} goes is to doc every thing you commit for a month. Quite a number of of us often usually are not aware how an important deal we commit on streaming suppliers, vanilla lattes or feeding on out. When you determine non-necessities, you’ll be able to lower this shelling out and use this “situated” funds to assemble worth financial savings or sort out monetary debt.

    Make a bank card debt payoff technique. Even although there are various widespread methods to do that, these as shelling out off credit standing accounts with the very best charges 1st, that is in the long term as much as you. For occasion, chances are you’ll presumably wish to fork out off your smallest credit standing card stability proper earlier than transferring on to a further.

    Consider a 2nd gig. If your shut associates actually like your work, take into account advertising them on the web. If you’ve spare time on weekends, you can be geared up to trace down part-time carry out. The much more you’ll be able to emphasis on enhancing your funds, the much better you’ll be able to really really feel about by your self and your long term.

    Be form to by yourself. Berating you to your income behaviors can backfire within the type of anxiety-based choice-generating. Instead, have fun every particular person time you entry an extra economical goal, so you’ll have the self-assurance to maintain constructing smarter conclusions down the road.

    Source: lifehacker.com

    Food stuff

    Salmon with garlic butter

    Quickly probably the most most well-liked fish on meal tables, you’ll be able to present Sticky Garlic Butter Salmon with all kinds of sides. You can go inexperienced with broccoli or brussels sprouts, or serve it with brown or white rice.

    Actual ESTATE Traits

    Throw Your Dwelling Place a Curve

    Even nevertheless a few of previous yr’s construction developments, which incorporates earth tones and bringing the skin inside, are nonetheless seemingly strong, there are some courageous new appears that inside designers are embracing.

    Curvy house furnishings carries on to make a comeback. Crescent-shaped sectional sofas, merged with smooth-edged consuming tables and freeform espresso tables, promote a mild, serene electrical energy that helps make for a welcoming room.  One inside designer defined the origin of the curvy fad: “Mother Nature does natural and pure shapes best, so it helps make sense we might need to pull that inspiration into our properties.”

    The coloration purple’s attractiveness has been ramping up as extra homeowners determine to distinguish their premises with potent colors. Interior decorators stimulate their clientele to skip lilac and mauve in favor of additional shades like plum, berry, amethyst, and deep magenta. Bolder seems often usually are not restricted to paint methods, as outsized assertion chandeliers, gallery-style art work exhibits, and even graphic stone issues are in want.

    Creating a chilled bathroom oasis remains to be a finest precedence, with rather more builders introducing spa-impressed enhancements to their new property choices. Homeowners are renovating by introducing steam showers, infrared saunas, and chilly plunges into their loos because the financial system recovers and these merchandise develop to be obtainable. Spa-design and magnificence lighting and backlit mirrors are additionally displaying up in way more households.

    Supply: thespruce.com

  • APM Elevate: April 2024

    It actually is that point of calendar 12 months when each little factor seems to be to happen alive, along with our spirits! No matter whether or not you are dreaming of a brand new home, questioning about refinancing, or simply interested in your options, APM has your again. So relax once more, love the sunshine, and allow us to make this month 1 to keep in mind. This is to getting your unbelievable location to telephone residence and constructing some terrific recollections collectively the best way!

    apm april elevate

    Reach YOUR Goals

    Is Purchaser Spending Holding Premiums Higher?

    Even although our financial local weather is a capitalist trade monetary state, which implies that the nation’s inhabitants controls it, there are eventualities the place monetary details seems to be much better information than it severely is. For occasion, while we’ve been benefiting from decrease unemployment fees, this bumped up inflation as a number of corporations completed up paying larger wages to retain crew.

    More a short time in the past, shopper investing was defined as 1 of numerous parts impacting inflation. Recent findings by the Bureau of Financial Analysis found that buyer investing rose by 1% in January 2024 and by .8% in February. This tells us that the Federal Reserve’s fashionable choice to postpone want cost cuts hasn’t deterred numerous individuals from buying.

    Higher curiosity premiums are put in put to assist administration inflation, because it actually is anticipated that higher worth tags will end in quite a bit much less shopper investing. On the opposite hand, inflation has not cooled as considerably as anticipated in regards to the final variety of months, as amplified paying has been fanning the flames. Because buyers proceed shopping for, most shops are hesitant to attenuate charges. In change, the Federal Reserve interprets this as a cause to retain fascination premiums wherever they’re.

    Supply: investopedia.com

    Home mortgage IQ

    Considerably much less Square Footage = Much extra Affordability

    As the nation’s housing sector celebrates New Households Month, way more builders are creating extra compact houses in response to purchaser demand. A contemporary National Association of Property Builders (NAHB) evaluation situated that new households inbuilt 2023 attained their smallest median measurement in 13 yrs. This helped decrease median new residence charges to $428,200 in 2023, which was a 6% scale back from 2022.

    About 38% of builders say they crafted smaller residences in 2023, and additional than 1 / 4 (26%) method to assemble even scaled-down houses this 12 months. According to NAHB’s most up-to-date What Property Potential patrons Genuinely Want analyze, there was a downward shift in purchaser preferences for dwelling sizing within the ultimate 20 a very long time, which is confirmed by Census Bureau information.

    In 2003, the widespread client wished 2,260 sq. ft. Now, that quantity is 2,067 sq. toes, which is roughly equal to the sizing of a 2003 dwelling minus crucial (grasp) mattress room.

    2021 was the one yr that observed property measurements improve, owing to a combination of scale back home mortgage rates of interest and a rise in distant locations of labor.

    Whilst extra compact homes are anticipated to make enhancements to pricing, builders even now expertise points that may probably prohibit their efforts. These embrace a scarcity of heaps accessible for improvement, absence of skilled labor and restrictive codes in some cities.

    Source: nahb.org

    Fiscal News

    The Most up-to-date Student Personal mortgage Consolidation Information

    If you is perhaps an individual of the a whole lot of 1000’s repaying scholar monetary loans, you might probably have an prospect to lower and even eradicate the stability—however the deadline to implement is April 30, 2024.

    This is the newest: The U.S. Office of Education and studying can be finishing up a 1-time mortgage adjustment this summer season months. Depending in your mortgage’s phrases and different parts, you may wish to consolidate them to get credit score rating towards financial institution mortgage cancellation.

    If you retain a mixture of these federally managed monetary loans, you will have to must consolidate them by shopping the Federal Pupil Aid internet web page:

    Commercially held Federal Relatives Training Loans (FFEL)
    Guardian In addition loans
    Perkins loans
    Wellness Education Guidance Personal mortgage (Recover) Program monetary loans

    Soon after you select this section, your new Personal debt Consolidation Personal mortgage should be eligible for a 1-time adjustment, and way more of the funds you will have produced as much as this place can be counted towards monetary mortgage cancellation.

    If you implement for General public Service Personal mortgage Forgiveness (PSLF), these added durations of cost rely towards that software in the event you meet the opposite eligibility requirements. PSLF forgiveness could be gained proper after 10 a very long time of certified funds.

    Other methods to diminished or scale back your scholar mortgage funds is perhaps available to you. Simply click on beneath to analysis your prospects and implement for help with school scholar monetary loans.

    Source: consumerfinance.gov 

    DID YOU KNOW?

    Never Skip These Major 5 Tax Breaks for Home house owners

    When you possess your private home, you wish to make optimistic you select every particular person deduction attainable to optimize your tax refund. Lots of individuals take a look at these refunds as “discovered cash,” however they’re severely not. It’s earnings that you just is perhaps entitled to accumulate again…as prolonged as you declare the appropriate deductions.

    Possessing a dwelling is usually regarded a cornerstone of the American want. Outside of the pleasure and security of homeownership, there are additionally fiscal advantages that include it, specifically when it can come to tax benefits. Understanding these tax benefits can imply important monetary financial savings and a extra profitable economical system for plenty of homeowners.

    Read via much more on our weblog.

    Personal Finances

    Recent Overdraft Fees Challenged

    Previously this 12 months, alterations to bigger banks’ overdraft safety plans have been being launched by the Purchaser Financial Defense Bureau (CFPB). These contain reducing penalty fees and are part of the Biden Administration’s advertising and marketing marketing campaign in opposition to exorbitant buyer cost buildings. Considering the truth that 2020, overdraft prices for American clients have extra as much as about $280 billion.

    The proposed CFPB rule would provide important banking corporations two decisions for working overdraft safety:

    Banks might present overdraft loans, controlling the money they progress as credit standing line loans. Consumers would use for credit score rating and institutions would determine their potential to repay. In addition, buyers can be succesful to repay the credit score rating manually. These protections might consequence in a lot much less individuals getting amazed by overdrafts and the following service charges.
    Significant banks might go on giving overdraft protection as a courtesy, considerably than a revenue-generating line of credit score. These cash would carry on to be exempt from Truth of the matter in Lending (TILA) legal guidelines. On the opposite hand, banks can be constrained to charging bills in step with their precise fees.
    The CFPB proposed benchmark prices for overdrafts to be lessened to $3 to $14 for each transaction. It is a large discount to overdraft charges that in the mean time function as massive as $37.

    Supply: consumerfinance.gov

    Food

    Artichoke, Asparagus and Tomato Pasta Salad

    It actually is the time of yr when quite a few of the parts on this salad are in 12 months, so maintain a watch out for them at your most popular grocery or farmer’s present market. This Artichoke, Asparagus and Tomato Pasta Salad could be nicely ready in quite a bit lower than an hour.

    Authentic ESTATE Traits

    Time To Say Goodbye to These Decor Traits?

    Depending in your style, funds and long term packages, you possibly can be procuring the adorning and lights tendencies which are scorching for 2024. If bringing in new merchandise often means that you will must eliminate their current counterparts, proper listed below are some varieties and developments which are considered earlier their key.

    White kitchens have been round for nearly 10 a long time, so fairly a couple of residence house owners are enterprise colourful updates. While ombre and blue kitchens have been surfacing in the middle of the earlier three yrs, you’ll be able to purchase a shortcut by changing to a retro-fashion black and white kitchen space.

    Gray rooms and family furnishings took in extra of a a number of a long time again, however get a appear at Fb Marketplace and you will most likely discover dozens of gray sofas and chairs on the market. Thankfully, property house owners have pretty cost-free rein when changing grey tones, as each of these impartial and inserting hues are incomes the knowledge.

    Animal prints may at all times be a vogue beloved, however numerous inside decorators are placing them out to pasture. If you’ll be able to’t bear to be 100% critter-no value, maintain the smaller sized items this sort of as toss pillows.

    Sliding barn doorways have been being well-known when farmhouse types have been the fashion, and whereas they’re nonetheless promoting, they could lastly day your home. If you aren’t capable of assume of an selection, be imaginative by including wall decor and even portray them.

    Phrase indicators and stencils have been present in virtually each single dwelling for fairly a couple of a few years, however this improvement could make an or else-attractive room floor dated. Instead, select paintings and wall decorations that complement every residence.

    Resource: stonegableblog.com