Tag: your

  • Pleased New Calendar year and when does it make perception to refinance your mortgage

    The mortgage quantity pendulum swings but once more

    By Didier Malagies
    •
    18 Apr, 2024

    Count on 2024 to be mildly better than 2023 with dwelling finance mortgage prices falling within the second 50 % of the 12 months, housing professionals opined in their forecasts on the finish of the calendar year. Cuts to the Federal sources price (and subsequently to dwelling mortgage charges) are imminent, merchants enthused instantly after December’s meeting of the Federal Open Current market Committee wherein committee customers predicted 3 payment cuts in 2024. Some specialists forecasted as quite a few as 6 degree cuts within the yr depending on this information. Price cuts are proceed to coming, simply not in March , merchants and market place authorities reasoned much more simply these days because the financial local weather continued to function extremely scorching. And now on the heels of experiences of stronger than envisioned positions progress and stickier than predicted inflation , the market’s shift from optimism to pessimism round cost cuts is end. Some even anticipate worth hikes upfront of quantity cuts. The pessimism is apparent in dwelling finance mortgage charges. Freddie Mac‘s weekly Principal Home mortgage Market place Survey is climbing once more in path of seven%. HousingWire’s Mortgage mortgage Fee Middle , which is dependent upon knowledge from Polly, is presently earlier talked about 7.2%. Charges had been being as little as 6.91% for Polly and 6.64% for Freddie as a short time in the past as February. On Tuesday, they reached 7.50% on Property finance mortgage News Everyday, a big for this calendar year. Home mortgage premiums maintain main electrical energy within the housing trade most significantly, massive premiums exacerbate the prevailing affordability disaster by walloping the shopping for energy of would-be purchasers and discouraging some would-be sellers – these with minimal, set-price mortgages – from itemizing their households, a drain on available inventories. All this leaves housing consultants the second over again combating for his or her share of shrinking pies – as we now have noticed with simply these days produced mortgage particulars and RealTrends Verified’s brokerage information , as successfully as additional dives on the brokerage landscapes in Jacksonville and San Diego . It is unsurprising, then, that critical property shares have suffered as a result of the FOMC’s March convention and the latest job and inflation critiques. That incorporates the nation’s greatest homebuilders (DR Horton and Lennar), dwelling mortgage originators (United Wholesale Home mortgage and Rocket House mortgage), brokerages (Wherever and Compass) and residential search portals (Zillow and CoStar, which owns Homes.com). There are different dynamics at interact in for a few of these corporations, nevertheless. The brokerages are additionally contending with the rule modifications included in a proposed settlement by the Nationwide Affiliation of Realtors some consumers additionally assume these rule enhancements edge CoStar on the expense of Zillow . UWM, in the meantime, is contending with a scathing investigative report by a hedge-fund-affiliated information company whose hedge fund shorted UWM and went prolonged on Rocket it can be coping with pending litigation . UWM denies the allegations manufactured within the report.  Superior property finance mortgage charges, much less property finance mortgage applications and fewer dwelling income are nevertheless not the one results housing execs may see from a much more extended substantial-rate pure setting. There are additionally spillover outcomes from different industries, significantly place of job true property. Regional banks – which ordinarily have been important residential home mortgage originators – went massive on industrial genuine property monetary loans as extra substantial banks scaled again on this space in present a very long time. That enhanced their publicity to downtown workplace setting towers, which have seen an exodus of tenants and a bottoming out of appraised values simply as a historical past $2.2 trillion in industrial precise property private debt will come due greater than the next couple a very long time. That ties up funds that would in some other case stream to family dwelling loans and in some circumstances stresses banking corporations like New York Group Lender, guardian of Flagstar Lender — the Seventh-largest lender originator of residential mortgages, Fifth-greatest sub-servicer of mortgage loans and the 2nd-greatest property finance mortgage warehouse mortgage supplier within the area. Homebuilders, manner too, really feel the outcomes of extended larger charges. Even although homebuilder self-confidence is nonetheless up considerably due to the actual fact final tumble, new housing begins are slowing . The dim potential purchasers for homebuyers have turned some consumers to the nascent create-to-hire sector , successfully a wager that superior premiums are proper right here to keep for in depth loads of that would-be consumers at the moment are would-be renters.

  • Your Guidebook to Understanding Deposits

    If you’re a to begin with dwelling purchaser utterly prepared to embark in your journey to dwelling possession, 1 necessary factor to think about is the dimensions of your deposit. Not solely does your deposit determine how lots you can borrow, however it may additionally impression the curiosity quantity and different charges you could maybe be billed in your dwelling mortgage. In this whole information, we’ll purchase you by what you want to have to learn about deposits, which embrace how significantly you possibly can have to have, alternate prospects provided, and a few important methods to assist you protected your dream dwelling.

    4-Apr-17-2024-12-17-52-3072-AM

    1. How significantly deposit do I need?

    Saving for a deposit is usually the to begin with transfer within the path of buying a property. It’s additionally the most important road block for a lot of initially residence consumers! When sometimes, a 20% deposit is usually recommended to keep clear of getting to pay Lenders Home finance mortgage Insurance plan (LMI), fairly a couple of mortgage suppliers now supply prospects for deposits as lowered as 5% of the property’s purchase worth. Retain in head regardless that {that a} better deposit can nonetheless give benefits, these sorts of as decreased curiosity costs and diminished private mortgage repayments.

    2. What are another deposit choices?

    Preserving a large loads of deposit is understandably laborious. With dwelling costs on the rise, reaching that coveted 20% can sense unattainable. Past merely conserving for for an extended interval, there are alternate deposit choices on the market to certified 1st dwelling consumers:

    Loan suppliers Property finance mortgage Coverage (LMI): Initially residence clients with a deposit of lower than 20% are generally wanted to pay out LMI, an protection that mortgage suppliers price to decrease deposit debtors which shields the mortgage supplier in case you default in your mortgage. Paying LMI may recommend not buying to wait whenever you show you how to save up a large adequate deposit.
    Authorities Guidance: Many authorities schemes, these sorts of because the Very first House Guarantee or state-centered grants and concessions, can help appropriate 1st home consumers with their deposit. It is worth investigating these to confirm your eligibility as they’ll make a significant huge distinction to your deposit.
    Guarantor: Having a family members member act as a guarantor, making use of the equity of their have residence as security in your private mortgage, can help you avoid the need for an enormous deposit or LMI. But, as it’s a critical economical obligation, it’s essential the 2 capabilities get specialist economical help prior to figuring out on this selection.
    Spouse and youngsters Aid: Alternatively of appearing as guarantor, mom and father or partner and youngsters customers can reward or lend you money to elevate your deposit, supplying a useful helping hand. In actuality, the “financial institution of mum and pop” has flip into one explicit of the premier mortgage firms in Australia, as further and much more moms and dads are supporting their younger youngsters purchase households.

    3. How considerably can I borrow?

    The amount you can borrow depends upon a wide range of components, which embrace your income, bills, current money owed, credit score rating background, and the lender’s circumstances. Use a house mortgage calculator to get an estimate of how a fantastic deal you could be ready to borrow, or work with a house finance mortgage dealer who can assess your monetary predicament and help you determine a very best borrowing quantity.

    4. What different bills do I want to ingredient in?

    Aside from the deposit and private mortgage repayments, it is essential to problem within the further costs related to buying a property. These might include:

    Stamp Duty: A tax imposed by state governments when buying dwelling, which can differ from level out to state however is usually a main whole.
    Authorized and conveyancing prices: These are the expenditures linked with lawfully transferring possession of the home, and may selection all over the place amongst $800 and $2,500.
    Building and pest inspections: To decide any alternative points with the property, it’s important you manage making and pest inspections proper earlier than you go ahead with the sale.
    Mortgage bills: Application bills, valuation bills, and ongoing account-trying to preserve service charges charged by the mortgage firm will sometimes be included in your dwelling financial institution mortgage.
    Relocating bills: Lastly, preserve in thoughts the expenditures related to going your own home furnishings and belongings into your new dwelling.

    5. How can a house mortgage dealer help?

    When it comes to buying a primary property, working with a home mortgage dealer is invaluable. A mortgage dealer can act as middleman regarding you and potential collectors, offering expert help and support all by way of the family getting method. They can even:

    Evaluate your monetary downside and show you how to comprehend your borrowing functionality.
    Assess mortgage objects from numerous collectors to uncover essentially the most suited various in your wishes.
    Navigate the complexities of the residence mortgage software program course of, preserving you time and fear.
    Present ongoing help and steering, even following your mortgage is settled.

    Comprehending the basics

    Buying a initially house is an attention-grabbing milestone however it may additionally come to really feel irritating. Acquiring the perfect employees in your aspect makes positive a simple and thriving journey. If you’re ready to simply take the upcoming measures to property possession, get in contact with House mortgage Convey to be a part of with a mortgage dealer round you and get certified help and recommendation developed to assist you attain your dwelling possession objectives considerably quicker.

    When all therapy has been taken within the preparation of this publication, no assure is provided as to the accuracy of the small print and no duty is taken by Finservice Pty Ltd (Property finance mortgage Express) for any errors or omissions. This publication doesn’t represent personalised economical ideas. It might probably not be relevant to particular person circumstances. Almost nothing on this publication is, or want to be taken as, an provide, invitation, or suggestion to buy, promote, or retain any funding in or make any deposit with any human being. You ought to search skilled steerage simply earlier than having any motion in relation to the issues dealt in simply this publication. A Disclosure Assertion is accessible on ask for and completely freed from cost.

    Finservice Pty Ltd (House mortgage Categorical) is authorised as a company credit score rating guide (Corporate Credit rating Agent Number 397386) to have interaction in credit score rating issues to do on behalf of BLSSA Pty Ltd (Australian Credit historical past Licence quantity 391237) ACN 123 600 000 | Whole member of MFAA | Member of Australian Fiscal Issues Authority (AFCA) | Member of Preference Aggregation Services.

  • Refinancing your house loan making use of the blended fee

    What should you refinanced your decrease-charge initially mortgage into a better fee however consolidated all of your debt into 1 small cost. Getting rid of credit score enjoying playing cards, automotive monetary loans, installment loans, and scholar monetary loans. What would your financial savings be a thirty day interval and the way lots would you save? Then if house values had been at any time to plummet and prices got here crashing down. Just return to 2007 once we had been geared up to refinance anybody on the HARP system. I simply break up issues right down to worse-scenario conditions and how one can stay prematurely of the match with your funds no topic what.

    I think about it’s  time to get the house in buy and save income, is not going to really feel like meals stuff , skilled medical or absolutely anything is heading down however as a substitute nonetheless seemingly up

    It’s doable each little factor we’re instructed isn’t just correct

    tune in and grasp https://www.ddamortgage.com/website

    Didier Malagies nmls212566

    DDA property finance loan nmls#324329

    Inquire a Home finance loan Question

    Use the variety below and we are going to give your our knowledgeable responses!

    Commence Your Bank loan

    with DDA now

    Your neighborhood Mortgage loan Broker

    Property finance loan Broker Largo

    See our Reviews

    Looking for extra features? Hear to our prolonged podcast! 

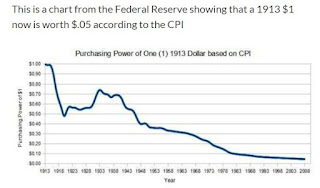
  • Your $1 points, deal with it correctly.

    The equal of $1 in 1963 is $7.79 in 2018.  If you saved your $100 in revenue under your
    mattress in 1963, you’ll $12.84 of relative funds remaining. 

    If you invested $1 a working day every working day as a result of 1963, you’ll
    have $842,416.

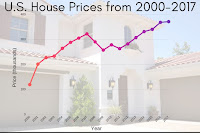
    Possessing a dwelling is an inflation welcoming exercise.  In distinction to revenue that deteriorates owing to
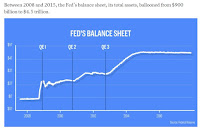
    inflation, home values rise.  With QE1, QE2, QE3 financial coverage contemplating the truth that the final financial catastrophe, inflation actually must be within the
    forefront of your personalised financial strategy.

    In current day financial pure surroundings, preserving {dollars} is not any prolonged king.  An enormous cushion for the sudden is consistently prudent however, the QE waves heading our method has produced an fascinating portfolio factor to think about.

    www.southeastmortgage.com 
    Cell telephone: 770-279-0222


    Be conscious: This is my impression centered on the present-day monetary information and my experience.  Any funding resolution alternatives actually must be talked about with your fiscal advisor.

  • How the Federal Reserve’s up coming go impacts your money

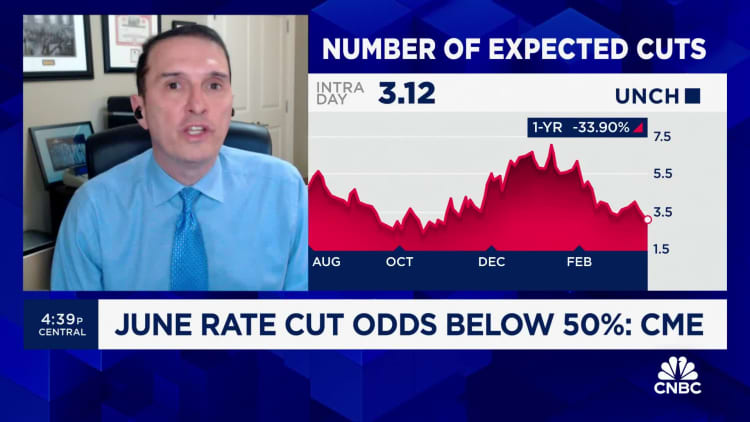
    Economists assume the Federal Reserve to go away curiosity prices unchanged at the conclude of its two-working day assembly this week, even despite the fact that loads of specialists anticipate the central lender is preparing to begin out chopping premiums in the months ahead.

    In organized remarks earlier this month, Federal Reserve Chair Jerome Powell stated policymakers actually do not wish to simplicity up too swiftly.

    Powell noticed that decreasing premiums quickly threats shedding the battle in opposition to inflation and certain having to raise charges additional, while prepared far too extended poses danger to financial progress.

    But in the meantime, people is not going to possible see considerably aid from sky-high borrowing prices.

    Much extra from Individual Finance:
    Here’s when the Fed is possible to begin slicing curiosity premiums
    Just about 50 % of youthful grown ups have ‘money dysmorphia’
    Deflation: Here’s the place promoting costs fell

    In 2022 and the initially fifty % of 2023, the Fed raised prices 11 occasions, leading to shopper borrowing charges to skyrocket though inflation remained elevated, and placing properties beneath stress.

    With the mixture of sustained inflation and elevated curiosity fees, “a number of consumers are experiencing higher quantities of financial nervousness when in comparison with only one yr in the previous,” talked about Silvio Tavares, CEO of credit score historical past scoring firm VantageScore.

    The federal money quantity, which is established by the U.S. central financial institution, is the want value at which banks borrow and lend to 1 explicit yet one more straight away. Whilst which isn’t the value consumers fork out, the Fed’s strikes nonetheless have an effect on the borrowing and monetary financial savings charges they see every day.

    Higher for longer may actually be a good thing, says Douglas Boneparth

    Even when the central monetary establishment does decrease charges — which some now hope might transpire in June — the velocity that they trim is prone to be significantly slower than the tempo at which they hiked, in accordance to Greg McBride, predominant economical analyst at Bankrate.

    “Curiosity prices took the elevator possible up they will simply take the stairs coming down,” he reported.

    Here’s a breakdown of precisely the place shopper costs stand now and the place they could presumably be headed:

    Credit playing cards

    Because most bank cards have a variable value, you’ll find a fast hyperlink to the Fed’s benchmark. Due to the truth of the central financial institution’s fee hike cycle, the common credit score rating card degree rose from 16.34% in March 2022 to roughly 21% at the moment — an all-time important.

    With most individuals feeling strained by higher value ranges, balances are increased and rather more cardholders are carrying monetary debt from thirty day interval to thirty day interval as compared with final yr.

    Annual proportion charges will start to return down when the Fed cuts prices, however even then they’ll solely relieve off actually giant phases. With solely a handful of potential quarter-issue cuts on deck, APRs would nonetheless be all-around 20% by the conclusion of 2024, McBride reported.

    “If the Fed cuts charges twice by 1 / 4 degree, your credit standing card payment will slide by 50 % a %,” he reported.

    Mortgage fees

    Fifteen- and 30-yr mortgage mortgage prices are mounted, and tied to Treasury yields and the total financial system. But anybody searching for a brand new residence has misplaced sizeable buying electrical energy, partly merely due to inflation and the Fed’s plan strikes.

    Premiums are already drastically reduce since hitting 8% in Oct. Now, the widespread fee for a 30-year, set-fee mortgage is about 7%, up from 4.4% when the Fed began boosting premiums in March 2022 and three.27% at the end of 2021, in keeping with Bankrate.

    “Despite the current dip, home mortgage prices keep superior as the market contends with the stress of sticky inflation,” defined Sam Khater, Freddie Mac’s predominant economist. “In this environment, there’s a superior chance that charges will stay increased for a for an extended interval interval of time.”

    Adjustable-rate dwelling loans, or ARMs, and dwelling fairness traces of credit score historical past, or HELOCs, are pegged to the key quantity, and people folks charges stay important.

    “The truth of it’s, loads of debtors are shelling out double-digit want prices on folks proper now,” McBride claimed. “That shouldn’t be a cheaper price of borrowing and that is not heading to switch.”

    Automobile loans

    Even although auto loans are mounted, funds are acquiring greater just because motorized vehicle costs have been growing along with the curiosity charges on new loans, leading to a lot much less inexpensive month-to-month funds. 

    The regular quantity on a 5-yr new vehicle financial institution mortgage is now rather more than 7%, up from 4% when the Fed began elevating costs, in accordance to Edmunds. Nonetheless, degree of competitors amongst lenders and rather more incentives in the market have began out to amass a few of the edge off the cost of getting a automobile at the moment, stated Ivan Drury, Edmunds’ director of insights.

    At the time the Fed cuts costs, “that provides individuals a bit of way more respiratory space,” Drury reported. “Final calendar yr was unattractive all near. At least there may be an upside this 12 months.”

    Federal scholar monetary loans

    Federal college scholar private mortgage charges are additionally mounted, so most debtors usually are not rapidly affected by the Fed’s strikes. But undergraduate college students who select out new direct federal scholar loans are actually spending 5.50% — up from 4.99% in the 2022-23 educational calendar yr and three.73% in 2021-22.

    Non-public scholar loans are likely to have a variable value tied to the prime, Treasury invoice or one other payment index, which suggests people debtors are by now spending extra in fascination. How significantly much more, nonetheless, differs with the benchmark.

    For folks combating present debt, there are means federal debtors can reduce their load, together with income-based choices with $ month-to-month funds and financial hardship and unemployment deferments. 

    Personal private mortgage debtors have fewer options for aid — regardless of the undeniable fact that some might ponder refinancing at the time costs get began to look down, and all these with higher credit score historical past might already qualify for a lower degree.

    Discounts prices

    Though the central monetary establishment has no direct affect on deposit prices, the yields are typically correlated to enhancements in the consider federal money value.

    As a consequence, prime-yielding on the web value financial savings account costs have designed important strikes and are actually paying out excess of 5% — earlier talked about the quantity of inflation, which is a scarce earn for any particular person creating up an disaster value financial savings account, McBride reported.

    Since folks fees have possible maxed out, that is the time to lock in certificates of deposit, significantly maturities for an extended interval than one explicit yr, he advised. “There’s no incentive to take care of out for one thing higher for the purpose that that’s not the approach the wind is blowing.”

    Currently, one-year CDs are averaging 1.73%, however best-yielding CD charges pay about 5%, as superior as or superior than a high-generate val
    ue financial savings account.

    Really don’t miss these exclusives from CNBC Professional

  • 5 Approaches to Decrease Taxready Earnings and Hold Extra Money in Your Pocket

    The ongoing superior price of residing has fairly just a few Australians searching for methods to maintain more money in their possess pockets and shell out lots much less at tax time. As tax time methods, there’s no improved time to uncover fiscal methods that would assist scale back tax liabilities. By leveraging these cash tools and savvy methods, it’s attainable to enable you to save money while nonetheless being compliant with Australian tax pointers. Browse on as we share six efficient procedures to receive this intention.

    2-Feb-13-2024-12-41-08-5133-AM

    1. Use Salary Sacrificing

    Wage sacrificing permits taxpayers to divert part of their pre-tax wage in the course of positive constructive points. The hottest earnings sacrifice advantages are superannuation contributions, motor vehicles, and digital tools. Income sacrificing could be utilised to spend for a brand new automobile, laptop computer, protection, lease funds, house finance mortgage funds, or different positive aspects, whereas saving numerous numbers of kilos in taxes yearly. Many employers provide wage sacrificing preparations, so it is actually value testing this various together with your HR division or monetary adviser.

    2. Continue to maintain Correct Tax and Financial Records

    About the sooner few yrs, the ATO has tightened up on scrutiny, in distinctive in the locations of report-maintaining, income and deductions, which is why conserving meticulous data of income, prices, and investments is so vital when it comes to optimising tax deductions. Use digital assets and apps to streamline document-keeping and give your self sufficient time to do the job because of your tax return to avoid speeding and producing errors. By being organised and retaining maintain observe of of deductible prices, you possibly can maximise your tax deductions and lower your taxable cash.

    3. Assert ALL Deductions

    Verify that you just is perhaps saying all eligible deductions that make the most of to your situation. If you make investments any cash related to incomes an earnings, expense houses, instruction or scientific prices, you’ll need to assert it. Be assured to maintain receipts and documentation to again again-up your claims in state of affairs of an audit and search the recommendation of with a professional tax specialist who can assist you determine any deductions you might maybe have missed in buy to get essentially the most out of your tax return.

    4. Add to Your Tremendous to Save Tax in Australia

    Building supplemental contributions to your superannuation fund could be a tax-successful approach to increase your retirement financial savings and lower down taxable cash. (*5*) great contributions, these sorts of as wage sacrifice or specific deductible contributions, are taxed at a decreased worth inside simply the great fund – a charge of simply 15 for each cent – in comparability to the marginal tax charge which might be as excessive as 49 for each cent!

    5. Minimise Expenses with a Mortgage Offset Account

    A house finance mortgage offset account could be a efficient software for lowering taxable earnings whereas saving on mortgage mortgage need funds. By depositing worth financial savings or getting your earnings compensated into a particular offset account related to your residence mortgage, you possibly can offset the curiosity charged in your mortgage steadiness. Not solely does this decrease the sum of curiosity payable in your property financial institution mortgage, however it could additionally speed up your route to receiving debt-absolutely free.

    6. Get Private Well being Insurance insurance policies

    Investing in private wellness insurance coverage insurance policies offers vital healthcare safety and can supply some tax rewards additionally. Devoid of personal clinic insurance coverage plan, for those who’re solitary and achieve much more than $90k for each yr, or you’re a family incomes much more than $180k a 12 months, you’ll pay again a minimal quantity a single for every cent Medicare Levy Surcharge on main of the required two per cent Medicare Levy that the majority taxpayers have to pay. Basic non-public well being care methods can cost lots lower than the only one for every cent Levy Surcharge on gross earnings, so for some males and ladies, discovering private effectively being insurance coverage could make good fiscal sense.

    Maximising Discounts to Access Fiscal Plans

    No 1 would love to fork out much more tax than they’ve to, which is why it’s so important to perceive the vital methods for maximising reductions and lessening taxable earnings. By making use of these 6 strategies, it’s possible to correctly minimise the sum of tax you’re essential to shell out, income which may go into your again once more pocket in its place!

    For extra fiscal data tailor-made to your one among a sort scenario, get in contact with the group at Home mortgage Specific.

    While all therapy has been taken in the getting ready of this publication, no guarantee is specified as to the precision of the data and no obligation is taken by Finservice Pty Ltd (House mortgage Categorical) for any glitches or omissions. This publication doesn’t represent personalised economical ideas. It won’t be related to private circumstances. Absolutely nothing in this publication is, or ought to actually be taken as, a suggestion, invitation, or advice to buy, promote, or maintain any monetary dedication in or make any deposit with any specific individual. You ought to search certified steering prior to taking any movement in relation to the issues dealt in simply this publication. A Disclosure Assertion is obtainable on ask for and no price of cost.

    Finservice Pty Ltd (Property finance mortgage Categorical) is authorised as an organization credit standing guide (Corporate Credit historical past Representative Amount 397386) to engage in credit score rating actions on behalf of BLSSA Pty Ltd (Australian Credit Licence quantity 391237) ACN 123 600 000 | Complete member of MFAA | Member of Australian Financial Problems Authority (AFCA) | Member of Option Aggregation Providers.

  • The Fed holds fascination charges regular. What that suggests for your cash

    Fed may not cut rates at all this year, according to market forecaster Jim Bianco

    The Federal Reserve declared Wednesday it can depart need charges unchanged, delaying the chance of price cuts as very effectively as any aid from sky-high borrowing expenditures.

    Over-all, expectations that the Fed is pulling off a easy touchdown have elevated, however that options little comfort for People with higher-fascination private debt.

    And now there is perhaps much less fascination quantity cuts on the horizon after hotter-than-envisioned inflation tales despatched the data that “we’re relocating in the appropriate route, however we’re not there however,” said Greg McBride, major fiscal analyst at Bankrate.com.

    For people, that signifies “a extremely sluggish downward drift in reductions prices however no content material alter in borrowing prices for credit score rating playing cards, auto loans or property fairness strains of credit standing,” McBride talked about.

    More from Private Finance:
    Here’s when the Fed might be to start out out chopping curiosity prices
    Nearly fifty p.c of youthful grownups have ‘cash dysmorphia’
    Deflation: Here is wherever prices fell

    Inflation has been a persistent issue contemplating the actual fact that the Covid-19 pandemic, when worth raises soared to their greatest quantities contemplating the actual fact that the early Eighties. The Fed responded with a sequence of fascination cost hikes that took its benchmark price to its highest diploma in much more than 22 yrs.

    The federal cash price, which is ready by the U.S. central monetary establishment, is the fascination degree at which banks borrow and lend to an individual a further instantly. Whilst that’s not the speed customers spend, the Fed’s strikes nevertheless affect the borrowing and private financial savings prices they see every particular person working day.

    The spike in fascination premiums triggered most client borrowing charges to skyrocket, inserting a number of houses lower than stress.

    Even with some cost cuts on the horizon later this 12 months, buyers won’t doubtless see their borrowing expenditures arrive down noticeably, in accordance to Columbia Company College economics professor Brett Home.

    “The charges of borrowing will keep considerably tight in true situations as inflation pressures proceed to simplicity steadily,” he talked about.

    From bank cards and residential finance mortgage charges to automobile loans and reductions accounts, here is a look at the place folks charges might go in 2024.

    Credit score taking part in playing cards

    Because most bank cards have a variable quantity, you could find a direct hyperlink to the Fed’s benchmark. In the wake of the worth hike cycle, the conventional credit score historical past card cost rose from 16.34% in March 2022 to virtually 21% now — an all-time superior.

    With most individuals expertise strained by larger costs, balances are larger and further cardholders are carrying monetary debt from month to month in contrast with final 12 months.

    Once-a-year share costs will start to reach down when the Fed cuts prices, however even then they’ll solely relieve off notably giant ranges. With solely a few doubtless quarter-point cuts on deck, APRs would nonetheless be shut to twenty% by the conclude of 2024, in response to Ted Rossman, Bankrate’s senior area analyst.

    “If the odd credit score historical past card price falls a share situation from its present report excessive of 20.75%, most cardholders would barely observe,” he said.

    Mortgage costs

    Even although 15- and 30-calendar 12 months house mortgage charges are mounted, and tied to Treasury yields and the general financial system, any individual shopping for for a brand new property has dropped important buying energy, partly due to inflation and the Fed’s protection strikes.

    But premiums are presently cut back as a result of hitting 8% in October. Now, the common degree for a 30-year, fastened-rate mortgage is in shut proximity to 7%. That is up from 4.4% when the Fed began off rising prices in March 2022 and three.27% on the shut of 2021, in accordance to Bankrate.

    Doug Duncan, chief economist at Fannie Mae, expects home mortgage premiums will conclusion the 12 months at 6.4%, however that will not current significantly of a improve for would-be homebuyers.

    “The housing market may be very more likely to carry on to expertise the dual affordability constraints of superior dwelling costs and elevated rates of interest in 2024,” Duncan reported. “The dilemma is nonetheless provide. If costs seem down and it ramps up want and there’s no provide, the one situation that occurs is that residence promoting costs go up.”

    Car loans

    Even although auto loans are mounted, funds are having better as a result of automotive costs have been climbing alongside with the need charges on new monetary loans, leading to much less reasonably priced month-to-month funds. 

    The frequent quantity on a five-12 months new automotive mortgage is now additional than 7%, up from 4% when the Fed commenced boosting charges, in accordance to Edmunds. Even so, competitiveness between lenders and further incentives out there have started to decide on among the edge off the cost of buying for a auto presently, claimed Ivan Drury, Edmunds’ director of insights.

    The second the Fed cuts charges, “that presents individuals a minimal much more respiration room,” Drury defined. “Final calendar 12 months was ugly all near. At the very least you will discover an upside this 12 months.”

    College scholar loans

    Federal pupil private mortgage charges are additionally set, so most debtors should not instantly affected. But undergraduate college students who take out new instant federal scholar monetary loans are actually paying out 5.50% — up from 4.99% within the 2022-23 tutorial 12 months and three.73% in 2021-22.

    Non-public college scholar loans are inclined to have a variable quantity tied to the first, Treasury month-to-month invoice or a unique price index, which suggests all these debtors are presently paying out additional in need. How considerably additional, nonetheless, might differ with the benchmark.

    For these struggling with current private debt, there are means federal debtors can reduce their load, together with income-based plans with $ common month-to-month funds and financial hardship and unemployment deferments. 

    Personal financial institution mortgage debtors have much less picks for assist — regardless of the actual fact that some might take into consideration refinancing after prices get began to happen down, and people with improved credit score might effectively already qualify for a cut back price.

    Discounts costs

    When the central lender has no direct affect on deposit charges, the yields are more likely to be correlated to alterations within the aim federal sources worth.

    As a finish outcome, major-yielding on the web reductions account charges have designed necessary strikes and are actually shelling out way more than 5% — earlier talked about the speed of inflation, which is a scarce purchase for anybody increase an disaster worth financial savings account, McBride defined.

    Because these premiums have very doubtless maxed out, that is the time to lock in certificates of deposit, particularly maturities for an extended time than one calendar 12 months, he reported. “There’s no incentive to maintain out for some factor significantly better as a result of that shouldn’t be the best way the wind is blowing.”

    Currently, 1-year CDs are averaging 1.73
    %, however major-yielding CD charges pay greater than 5%, as superior as or higher than a higher-generate value financial savings account.

    Really do not cross up these exclusives from CNBC Professional

  • 10 Wise Moves to Secure Your Car & Decreased Coverage Prices

    Apr 15 2024

    Welcome again once more to the #owngrowprotect web page! These days, we’re thrilled to have Elyce Cartier, 1 of our seasoned insurance coverage coverage gurus, share some priceless insights. In her latest piece, Elyce breaks down how some straightforward steps can safeguard your automobile and assist embody your insurance coverage protection charges. Thanks to Elyce for these sensible ideas!

    EC: “Holding your vehicle safe and your insurance coverage plan bills down does not have to be subtle. I’m thrilled to present you some easy nonetheless environment friendly methods to safe your automobile and help ease the monetary power in your pockets. Let us get commenced!”

    Steering Wheel Locks: A Simple Deterrent. A superior aged steering wheel lock isn’t just a deterrent however a press release that you’re critical about shielding your automobile.VIN Etching: Mark Your Territory. By etching your automobile’s VIN onto its house home windows, you make it considerably much less eye-catching to robbers and further identifiable if stolen.Clever Key Safety: Outsmart the Burglars. Storing sensible keys in signal-blocking pouches helps stop significant-tech thieves from acquiring a completely free journey.Clever Parking Decisions. Opt for properly-lit, secured parking spots to decrease the hazard of theft or vandalism.Devote in a Dependable Vehicle Alarm. A sturdy alarm program will be the variation regarding a protected automobile and a certified 1.Dwelling Safety: Your Car’s (*10*) Line of Protection. Boosting your dwelling safety additionally guards your automobile or truck, specifically from essential theft.GPS Tracking: Your Security Internet. A auto tracker can shortly reunite you along with your auto whether it is at any time stolen, presumably preserving you from a hefty declare.Normal Servicing: Prevention is Superior Than Get rid of. Preserving your automobile in prime type can avert mishaps and, subsequently, claims.Defensive Driving: Know-how is Electrical energy. A defensive driving system not solely will increase your experience however also can lead to much less accidents and statements.Yearly Insurance insurance policies Reviews: Hold It Fitting. An once-a-year overview of your insurance coverage plan safety assures you’re solely paying out for what you will have, reflecting your current life-style and driving behaviors.

    By having proactive steps in direction of motorized vehicle safety and safety, you is likely to be not simply guarding your vehicle you occur to be additionally contributing to scale back insurance coverage plan statements and, as a end result, further favorable premiums for each individual. It’s about creating clever choices lately that information to reductions tomorrow.

    Remain protected and push good!

    If you could have any inquiries about these pointers or another insurance coverage insurance policies issues, is not going to wait to merely click on proper right here to make contact with Elyce or any of our centered brokers. We are proper right here to assist you defend what points most.

  • 5 Vital Strategies for Cleansing Up Your Credit score File

    Many Australians facial space worries with working their funds and repaying monetary debt due to to the continued giant worth of dwelling. Compelled into using credit score score playing cards or substantial-interest loans to shell out for very important buys or sudden skilled medical prices, they wrestle to maintain a completely clear credit score historical past file. As an excellent credit standing score is essential when it’s going to come to accessing beneficial credit score score, on this article are 5 important methods to help you clear up your credit score score file.

    1-Mar-10-2024-11-44-43-6915-PM

    1. Keep observe of Your Credit score Report Frequently

    Request a duplicate of your credit standing report from 1 of the important thing credit score bureaus in Australia, this sort of as Equifax, Illion, or Experian. Overview your credit score report very rigorously to detect any inaccuracies, discrepancies, or opposed merchandise that could possibly be dragging down your credit standing. Glimpse for late repayments, collections, bankruptcies, or some other crimson flags that will need addressing.

    2. Dispute Inaccurate Info

    Inaccurate information in your credit score historical past file can appreciably impression your credit score historical past score. If you place any glitches or discrepancies, make contact with the credit standing bureau to handle these instantly. Supply supporting paperwork to again-up your declare and observe as much as make sure the corrections are accomplished on time. Try to recollect, every stage issues when it’s going to come to your credit score historical past score!

    3. Pay again Your Bills on Time

    Outstanding or overdue monetary debt can wreak havoc in your credit standing score, so set up a method to repay your debt as promptly as doable. Consider prioritising high-interest bank card debt or repayments which might be late or overdue. Negotiate with lenders to increase the compensation day or prepare a compensation technique if essential. Constantly having to pay prices on time demonstrates financial obligation and positively impacts your credit standing score.

    4. Use Credit score Properly

    The essential to preserving a balanced credit standing file and a terrific credit score score lies in liable credit score score utilization. Stay away from maxing out your credit score score playing cards and function to keep up your credit standing utilisation ratio beneath 30 for every cent of your credit score historical past limit. Do not use for credit score historical past besides when you definitely want it and avoid making use of for a number of new credit standing accounts at the very same time. Far too a whole lot of credit score enquiries could be a crimson flag for mortgage suppliers, signalling fiscal misery.

    5. Think about Credit card debt (*5*)

    Consolidating money owed right into a single monetary mortgage with a lower curiosity charge can cut back your month to month repayments and simplify your funds. Function with a Home mortgage Convey dealer to find monetary debt consolidation options. Ahead of constructing use of for a financial institution mortgage or a mortgage mortgage, keep clear of making vital cash commitments, this sort of as buying a brand new automobile or truck. And sort out any crimson flags in your monetary historical past and contemplate strategies to spice up your creditworthiness.

    Acquire command of your cash long term

    Cleansing up your credit score score file is simply simply one of many important measures to mastering your credit score score and having deal with of your cash long run. Preserving a watchful value vary, developing an emergency value financial savings fund, and investing in retirement are among the different strategies to established by your self up for financial achievement.

    Get monetary and mortgage mortgage recommendation from an expert who understands your situations and may assist you create a economical technique to in form your downside. Get in contact with a Home finance mortgage Express dealer these days for steerage and steering that will get you on the path to economical achievements.

    Even although all therapy has been taken within the planning of this publication, no assure is provided as to the precision of the data and information and no obligation is taken by Finservice Pty Ltd (House mortgage Express) for any faults or omissions. This publication doesn’t represent personalised financial help. It will not be associated to explicit individual situations. Almost nothing on this publication is, or needs to be taken as, an present, invitation, or suggestion to put money into, promote, or retain any funding in or make any deposit with any man or girl. You want to hunt expert recommendation previous to utilizing any motion in relation to the issues dealt on this publication. A Disclosure Assertion is obtainable on ask for and cost-free of demand.

    Finservice Pty Ltd (Property finance mortgage Convey) is authorised as a company credit score score guide (Corporate Credit historical past Representative Range 397386) to work together in credit score actions on behalf of BLSSA Pty Ltd (Australian Credit score Licence amount 391237) ACN 123 600 000 | Full member of MFAA | Member of Australian Economical Problems Authority (AFCA) | Member of Decision Aggregation Companies.

  • Leap Calendar year Investing: Maximizing Your RRSP in an Further Day

    Jan 23 2024

    Hey there, financial adventurers! Did you realize that when every 4 a number of years, the universe items us an added day? Which is correct, I’m chatting about February twenty ninth – the elusive leap working day. It actually is like discovering a bonus fry on the backside of your speedy-foods bag, however in your funds. So, let’s hop into the world of leap year investing and see how one can make that extra working day work miracles in your RRSP.

    The Leap 12 months Phenomenon

    Initially off, what’s up with leap a very long time? In a nutshell, it usually takes the Earth about 365.24 occasions to orbit the solar. All these further .24 occasions accumulate, and every 4 a number of years, we require so as to add an additional working day to our calendar to carry nearly all the pieces in sync. For this purpose, February twenty ninth is born – a working day which is sort of like a timekeeper’s patch to repair a glitch in the calendar course of.

    Leap Several years and Your Finances

    Here’s in which it receives fascinating. An further working day implies an extra 24 a number of hours of… nicely, each factor. Which contains time to imagine about your funds! It actually is the right immediate to replicate in your financial goals and ways. Think of it as a bonus spherical in your monetary sport.

    RRSP Deadline and Leap Yrs

    Now, let’s chat RRSPs (Registered Retirement Financial financial savings Designs, for the uninitiated). Ordinarily, the deadline so as to add for the tax calendar year is March 1st. But in a leap year? You get an additional day! This might probably not audio like a significant deal, however in the expense setting, even a at some point could make a variation. It’s your prospect to squeeze in that final-moment contribution and maybe reap some tax benefits.

    Leap into Motion

    So, how do you profit from this reward day? Below are a handful of tips:

    Excess Contribution: Obtained some spare money? Take into consideration inserting it into your RRSP. It is like supplying future you a substantial-5.Expense Possibilities: Investigate distinctive expense alternate options in your RRSP. Shares, bonds, GICs – the globe is your economical oyster.Extensive-phrase Arranging: Use this extra working day for some extreme cash reflection. Are you on observe to fulfill your retirement aims? If not, now’s a wonderful time to change.

    Circumstance Scientific research

    Picture Sarah, who used her leap day to assessment her investments and uncovered a terrific stock to spend her RRSP contributions. Or John, who finally arrange his RRSP given that, hey, you can find no time like a leap day!

    Professional Insights

    Money authorities actually like leap yrs. It is like an extra inning in a baseball sport. They suggest working with this time to analysis and alter your monetary dedication procedures, ensuring you occur to be on monitor to satisfy up together with your retirement targets.

    Summary

    Leap a few years are further than only a quirk of the calendar – they’re a distinctive chance to leap forward together with your financial organising. So this February twenty ninth, contemplate a second to ponder your RRSP. Regardless of whether or not it actually is making a previous-minute contribution or simply re-analyzing your expenditure system, use this extra day to its fullest possible. Following all, it’s actually not every working day you get a full extra day!

    Content leap yr investing! Could your monetary leaps be as attention-grabbing as a kangaroo on a trampoline!

    Intrigued in discussing how these ways could be built-in into your funding technique? Reserve an appointment with Tyler at 1st Basis beneath for specialist cash help tailor-made to your distinctive requires and goals.