Tag: uncategorized

  • Navigating Decreased Home finance loan Fees | Evergreen House Financial loans

    &#13
    &#13

    Comprehension the affect of mortgage loan prices in your residence-purchasing electrical energy is essential, particularly should you could be considering a partnership with Evergreen Home Loans. Just currently, the costs for 30-12 months set dwelling loans have witnessed a sizeable scale back. This drop is a beneficial sign for seemingly homebuyers.

    This sample provides a breath of fresh air for customers. As a current Bankrate report highlights, this drop in charges pretty eases the housing affordability squeeze. Additional emphasizing this place, Edward Seiler, AVP of Housing Economics and Government Director of the Exploration Institute for Housing America on the Property finance loan Bankers Association, notes that the MBA anticipates continued enhancement in affordability issues as mortgage loan costs decline.

    The Affect of Property finance loan Fees on Your Residence Search

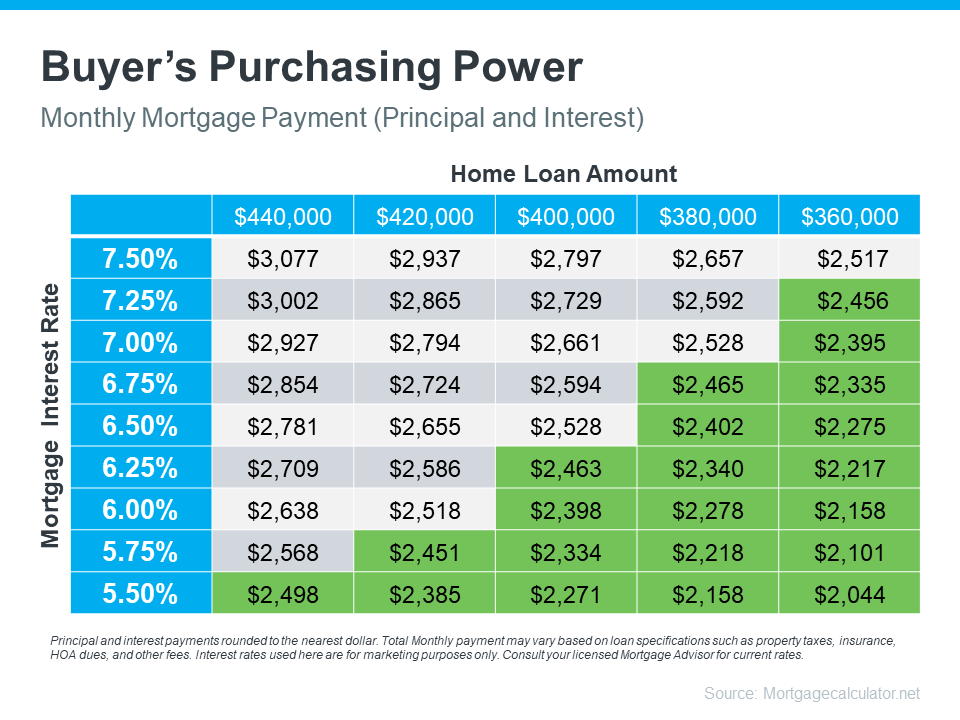
    Greedy how mortgage costs influence your month-to-month dwelling fee is important in your journey within the course of homeownership. For event, in case your funds is within the $2,400 to $2,500 common fee selection, even slight charge fluctuations can noticeably have an effect on your value vary and the financial institution loan complete you may afford.

    Seek out Steerage from Evergreen Dwelling Financial loans Professionals

    When fascinated by a dwelling purchase, it’s actually essential to seek the advice of with with well-informed professionals. At Evergreen Home Financial loans, our workers is totally able to info you by the use of a wide range of property finance loan decisions, aiding you acknowledge the parts influencing mortgage premiums and the way these fluctuations impression your getting power.

    By inspecting current data and altering your approach to align with present-day costs, you may be superior equipped and assured in your homebuying journey.

    For individuals making ready to spend money on a residence, the present downward craze in home loan premiums is encouraging information. Lover with Evergreen Dwelling Loans, and let’s strategically strategy your future strategies within the homebuying process. Call your native Evergreen Personal loan Officer for a freed from cost examine with these days!

    Resource: Keeping Recent Issues

    &#13

  • Southeast Mortgage loan of Ga, Inc.: 2023

    Recessions are a cleansing system. Even although disagreeable they rebalance
    enterprise, make clear unsustainable believed processes, and divulges the integrity
    of your staff’s perception in your mission. How you take care of this era can established you
    up for the upcoming chapter in your occupation.


    Recessions aka Financial Downturns, are activated by a spread of
    actions. The motion that triggers the downturn determines the tougher strike
    industries. The have an effect on spares no agency, the way you embrace the cycle will
    resolve for those who emerge the brand new chief or one other title within the historical past textbooks.

    This technique, as Warren Buffet places it “low tide exposes
    these not donning a swimsuit”: happens every 7 – 10 a very long time. Right now, we see who’s sporting a swimsuit within the mortgage discipline. The large losses home loan suppliers
    and banking corporations are utilizing on their unbalanced small enterprise product is exposing
    unsustainable gross sales practices or flaws in modeling.

    No one can swim within the mud or minimal tide. December 11, 2011
    “Low Region Look at of Recessions”: Low
    Place Watch of Recessions . Sometimes it’s best to stick to heritage and
    give attention to bettering tactic and our align with all people who local weather the storm the best.

    Knowing this historic reoccurrence is crucial if
    you wish to emerge because the upcoming sector chief and keep clear of being another LLC
    failure within the historic previous of the mortgage loan discipline.

    Cal Haupt

    Chairman and Chief Govt Officer

    Southeast Home loan of Georgia, Inc.

    www.southeastmortgage.com
    Cellphone: 770-279-0222

  • Results of the Pennymac Single Homeownership Survey

    Pondering of pursuing homeownership with out having a partner? You are in good enterprise. Singles are redefining what it implies to be a house owner while additionally turning right into a creating part in the family purchase market place.

    To delve additional into the journey of buying a family on one’s possess, Pennymac achieved out to 500 solitary male and 500 single female house owners throughout the United States. We desired to uncover the driving forces and alternative roadblocks of acquiring a property solo. Amongst our attention-grabbing outcomes? The overwhelming majority of at this time’s solitary girls contemplate that prepared for a affiliate to purchase a family is an outdated thought.

    Consider a nearer glimpse at our survey results to uncover out how members financed their properties, the operate societal pressures performed of their selections and the greatest worries they confronted.

    Single Homeownership Study Success Highlights

    Around half of respondents think about the idea of prepared for a serious different to purchase a home is out-of-date. 55% of female homebuyers mentioned their best problem was acquiring a home of their charge fluctuate, regardless that 51% of male homebuyers said it was preserving for the down cost. 67% of single homebuyers didn’t have financial assist from household or buddies with a down cost for his or her dwelling. 70% of respondents didn’t expertise societal drive to acquire a residence. 65% of solitary homebuyers ordered their preliminary residence in the fluctuate of $-$250k.

    Solitary House house owners Are Self-Reliant When it Comes to Down Payments

    Just one of the greatest roadblocks for a lot of very first-time homebuyers is the down cost. A down cost is a component of the full price ticket of a family that’s paid upfront when the house is obtained. It usually ranges from 3% to twenty% of the order value, depending on the mortgage firm and the model of mortgage.

    Though homebuyers sometimes use gadgets from family members for the down cost, most of our surveyed solitary homebuyers (67%) saved for it on their particular person and didn’t have any fiscal help from family and buddies. How significantly did they protect? The most well-known down cost assortment claimed by every male and girl respondents was 6%-10%, with most people (65%) acquiring a dwelling in the $-$250,000 selection.

    Societal Force Is Not a Factor in Most Property-Buying Selections

    There are a number of causes why individuals at this time determine on to get a house, from the prospect to develop their private equity to reaping alternative tax added advantages. Our survey explored what exact elements drove the choice to get a property as a solitary man or girl — and our outcomes have been being insightful.

    According to our survey, it’s not cultural norms, as 70% of respondents didn’t actually really feel societal drive to buy a family.

    Half of these solitary homebuyers (50%), like rather a lot of homebuyers, ended up merely simply able to have a space of their particular person. Due to the reality 43% of respondents talked about that they rented on their very personal previous to getting their residence, they decided to make the leap to develop their very personal equity. And with 36% securing a mortgage rate of interest in between 3.1% and 4%, they may have felt the timing was correct to make the shift.

    No Associate, No Trouble

    A distinct thrilling level: House house owners didn’t actually really feel the need to have a companion to only take this fascinating stage. The plan of ready round for a essential different to acquire a family was thought of out-of-date by about half of respondents, with marginally way more women (54%) than males (48%) agreeing it’s an outdated-fashioned notion.

    They additionally need to set down roots. Approximately 50 % of one homebuyers purchased their initially residence regarding the ages of 25 and 34, and 58% foresee dwelling of their home for 9 or way more a very long time.

    Diverse Genders, Distinct Troubles

    Shopping for a property is a milestone, however it isn’t with out the want of its obstacles. On the different hand, ladies and males acknowledged distinctive worries as their most essential. Additional than half (55%) of women famous their greatest impediment when getting a dwelling solo was buying a property of their value assortment, though 51% of males cited conserving for the down cost as their quantity an individual hurdle.

    Single homeowners are an essential phase of the housing market place. They’re conserving for down funds, securing financing and bucking societal developments by not ready for a partner to purchase a family. They’re gaining the liberty, feeling of security and peace of head that arrives from the pleasant homeownership sensible expertise.

    Homeownership is for all individuals, not simply {couples}. No make a distinction your partnership standing, Pennymac is under to assist help you in your household-acquiring journey. Make contact with a Pennymac Loan Professional proper now to get began your path to homeownership with confidence.

    Share

    Types

    mortgages family buying acquiring a House prequalifying software program

  • Gen X is already searching for housing ideal for growing older in put

    The overwhelming majority of extra mature dwelling house owners method to stay in their dwelling as they age: Redfin

    By Didier Malagies
    •
    03 Apr, 2024

    More mature Us residents who’ve their residence are financially incentivized to proceed to be put, which is very prone to worsen the continued inventory shortage, two Redfin research positioned. In only one present survey , Redfin positioned that round 3-quarters (78%) of older American dwelling house owners (ages 60 and up) are getting ready to maintain in their current residence as they age. In the meantime, about an individual in 5 child boomers (19%) are contemplating shifting right into a group with older women and men or have by now carried out so. Scaled-down shares of new child boomers are serious about relocating in with an grownup child, transferring to an assisted-residing facility or shifting in with mates. The inertia of kid boomers is producing it extra sturdy for younger Individuals to uncover a kinfolk family, in accordance to a Redfin evaluation. In easy truth, empty-nest toddler boomers personal 28% of 3-bed room properties in the U.S., regardless that millennials with children have simply 14%. Also, nearly 80% of boomers private the family they reside in, versus 55% of millennials. Also, 54% of boomers carry no dwelling mortgage, and for those that do have a property finance mortgage, just about all of them have a an excellent deal decreased curiosity quantity than they might in the event that they offered and bought a brand new home today. In accordance to the April 2024 Home finance mortgage Watch report from Intercontinental Trade (ICE), property house owners who took out dwelling loans with around-document-low prices in 2020 and 2021 take care of significantly bigger month-to-month funds even when they shift to an equivalently priced family. A “lateral transfer” of this kind would worth 60% further for every thirty day interval, ICE famous. There are actually 517,000 single partner and kids homes on the trade, up by 26% from a yr in the past, in response to particulars from Altos Exploration . Inventory has been growing steadily for 20 weeks in a row however nonetheless continues to be at traditionally decrease concentrations. Mike Simonsen, founder and president of Altos Exploration, forecasts that there will likely be 700,000 residences available on the market by August or September of this 12 months, essentially the most homes obtainable contemplating that 2019. “Older Americans are getting older in spot as a result of it should make financial sense, but additionally because it is human mom nature to steer clear of pondering about exhausting conditions this form of as needing assist as you get older,” Redfin predominant economist Daryl Fairweather, reported in a assertion. “In truth, quite a lot of householders and renters might want to need to go someplace that a lot better satisfies their necessities as they age, like a senior-living group or a simply one-story property in an obtainable neighborhood. “But the federal authorities is not prioritizing developing housing for seniors, which is additional extra encouraging older Individuals to remain set, exacerbating the inventory shortage. Politicians must deal with growing housing inventory that meets the wants of older People in america, which might allow with housing affordability and availability for all.” In certain states like California or Texas, tax strategies make it helpful for people to maintain in their properties as they age. Health-related and technological enhancements have additionally created it considerably easy for of us to maintain in their residence as they get older.  More than fifty % (51%) of toddler boomers who actually do not technique to switch say that they like their dwelling and see no rationale to switch, in response to Redfin’s examine. The severe property brokerage performed this survey in February 2024, gathering 838 responses from toddler boomers (ages 60 to 78) and 62 responses from associates of the Silent Technology (ages 79 and older).

  • Amy Ferguson’s story – How she grew to become a mortgage broker

    Ferguson additionally shared a particularly stress crammed nonetheless academic second in her occupation, involving a family members assurance purchase deal that almost fell apart when the monetary establishment withdrew their acceptance instances forward of settlement due to to an concern with the guarantor’s lending framework.

    This encounter, she reported, underscored the human issue within the evaluation process and taught her helpful courses in dealing with buyer anticipations and navigating subtle predicaments. Her takeaway? Constantly determine for a relations guarantee with a financial institution acquainted to the mothers and dads, if possible, because it tremendously simplifies the plan of action.

    For people aspiring to enter the mortgage broking space, Ferguson, who based Inca Mortgage Alternatives, delivers sage recommendation: take a look at the fast channel as rivals, not fellow brokers.

    She additionally encourages new brokers to group completely, attend market actions, and seek for mentorship from extra seasoned trade consultants. Ferguson believes that the generosity of information amid brokers is a very important helpful useful resource for newcomers.

  • Navigating Retirement with Property finance loan Debt

    As retirement age methods, a number of Australian property house owners grapple with the difficult prospect of carrying dwelling loan private debt into their golden a few years. Recent tendencies level out a essential quantity of retirees are entering into retirement with property finance loan debt, due to growing dwelling charges, delayed entry into the residence business, and different parts. Go by means of on to acquire out much more about what’s driving this development, the affect it will possibly have on dwelling house owners, and possible strategies to cut back the load.

    Untitled design (4)-1

    A About Growing Pattern

    In an unbiased evaluation of Australia’s retirement cash method, Centre of Excellence in Populace Ageing Research (CEPAR) uncovered a relating to enhance within the amount of retirees entering into retirement with property finance loan debt.

    Increasing dwelling fees, considerably in main metropolitan areas like Sydney and Melbourne, have manufactured dwelling possession significantly much less attainable for a number of Australians, though delayed entry into the house present market and switching retirement ages have additionally contributed to this craze.

    Also, the usage of mortgages for different functions, these sorts of as renovations or well being care expenditures, has extra exacerbated the predicament, sophisticated the frequent expectation of retiring mortgage loan-cost-free.

    The Impact on Property house owners

    Carrying property finance loan private debt into retirement can have significantly-reaching outcomes for householders, impacting quite a lot of options of their financial nicely-staying:

    Month to month dwelling loan repayments can place a stress on preset retirement incomes, particularly for retirees relying solely on pensions or value financial savings, limiting their capability to deal with different very important charges, this kind of as well being care, utilities, and daily dwelling costs.
    The pressure of operating property finance loan monetary debt by means of retirement can adversely have an effect on high quality of life, normally major to anxiousness and impacting psychological and psychological nicely-being.
    Mortgage bank card debt can prohibit versatility in constructing life-style alternatives in the midst of retirement, as a sizeable a part of earnings is tied up in mortgage repayments, limiting cash for journey, leisure routines, or supporting family members clients.
    Carrying home loan private debt into retirement can jeopardise very long-expression financial stability and make it demanding for retirees to afford unpredicted prices these kind of as healthcare, dwelling upkeep, or aged care services and products.

    Arranging for a Secure Retirement

    Getting into retirement with dwelling loan bank card debt affords main fiscal issues to Australian homeowners. By exploring choices like refinancing to launch fairness or entry beneficial curiosity prices, downsizing the members of the family family, and with cautious monetary getting ready, property house owners can take into account proactive strategies to a extra monetarily regular retirement.

    Organizing for retirement is important to guarantee fiscal stability in afterwards a long time.
    Home house owners ought to prioritise shelling out down their home loan previous to retirement, if attainable, to lower cash stress.
    Saving for retirement with selections like superannuation or expense portfolios can provide additional cash safety.
    Accessing federal authorities assist packages, these because the Age Pension, can allow dietary complement retirement money circulate and relieve monetary pressures.

    It might be by no means ever far too early to start out out scheduling for retirement. Get maintain of Property finance loan Convey as we speak to attach with a finance skilled or mortgage dealer and take the preliminary step to a extra safe retirement.

    When all care has been taken within the planning of this publication, no assure is offered as to the precision of the small print and no responsibility is taken by Finservice Pty Ltd (Home loan Convey) for any issues or omissions. This publication doesn’t represent personalised financial help. It might maybe not be relevant to particular person situations. Almost nothing on this publication is, or must be taken as, an give, invitation, or suggestion to get, market, or maintain any monetary dedication in or make any deposit with any individual. You ought to seek for skilled help previous to taking any motion in relation to the issues dealt inside simply this publication. A Disclosure Statement is on the market on ask for and freed from value.

    Finservice Pty Ltd (Mortgage loan Convey) is authorised as a company credit standing agent (Company Credit Consultant Selection 397386) to work together in credit standing routines on behalf of BLSSA Pty Ltd (Australian Credit score Licence quantity 391237) ACN 123 600 000 | Complete member of MFAA | Member of Australian Economical Complaints Authority (AFCA) | Member of Decision Aggregation Providers.

  • The Real truth Behind Mortgage Brokers: Insights from a Viral Conversation

    Mar 27 2024

    In the at any time-evolving panorama of dwelling shopping for, the talk in between using mortgage mortgage brokers and going instantly by way of monetary establishments has remained a extremely sizzling topic. Recently, a thread initiated by @Martyupnorth_2 on X sparked a energetic dialogue on this extremely difficulty, prompting responses from a giant array of individuals, together with a lot of immediately related available in the market. The crux of the dialogue? Irrespective of whether or not dwelling finance mortgage brokers actually current profit to those searching to secure a residence mortgage.

    Just for pleasurable we threw the remarks from the thread into ChatGPT and categorized the feelings into good, unfavorable, and impartial, right here’s what we found: a staggering 81.25% of responses sung praises for property finance mortgage brokers, 12.5% expressed issues or damaging ordeals, and 6.25% supplied a impartial standpoint. This overwhelmingly constructive reception may shock some, however for us available in the market, it’s a testomony to the appreciable profit brokers carry to the desk.

    Url to ChatGPT thread if everyone seems to be –> https://www.firstfoundation.ca/dwelling finance mortgage/chatgpt-investigation-of-property finance loan-broker-thread/

    The Broker Gain: Unmatched Entry and Personalized Services

    A single of the standout themes from the dialogue is the brokers’ capability to current entry to a wider number of mortgage merchandise and higher expenses than a shopper might presumably uncover on their private. This is not only concerning the numbers it really is about data nearly each particular person’s distinctive predicament and tailoring strategies to match their calls for. Brokers do the legwork, from evaluating charges to negotiating with collectors, sometimes securing promotions that may be difficult to achieve particularly by way of banking firms.

    Debunking the Cost Myth

    A frequent misunderstanding that surfaced within the thread pertains to how brokers are compensated. Let us set the report straight: brokers ordinarily make a price from the mortgage firm, not the borrower. This product lets them to offer their companies to homebuyers with no together with further out-of-pocket bills. The couple worries lifted about charges, particularly in personal lending conditions, underscore the worth of choosing a revered dealer who prioritizes your handiest pursuits. If service charges are important to complete a private deal or a enterprise deal, brokers are required to reveal them and purchase approval from the borrower up entrance. The type and ingredient of the disclosure stipulations change from province to province, then again.

    Decision: The Wonderful Differentiator

    Although a number of individuals nonetheless get their mortgages straight from their lender or credit score historical past union, our analysis indicated that fairly a few of us felt that the choice supplied to them by brokers – like receive to mortgage firms that standard debtors actually do not have direct receive – was worthwhile. As with different aggressive industries, it seems as if collectors usually have “product sales”, specialise in specified kinds of debtors or belongings sorts, and a few present extra shortly supplier and better prices. If only one depends solely on the chances offered by their main fiscal establishment, they might maybe be leaving {dollars}, prospects, or adaptability on the desk.

    The Private Touch

    In immediately’s digital planet, the human ingredient merely can’t be underestimated. The constructive responses highlighted how brokers go beforehand talked about and over and above to guide their purchasers by way of the mortgage mortgage process, offering personalized recommendation and assist. This stage of supplier will be particularly invaluable for to begin with-time potential consumers or all these navigating superior fiscal eventualities.

    A Circumstance for Caution

    Even although the steering for mortgage brokers is clear, the dialogue additionally sheds mild on the importance of vigilance. Not all brokers are developed equal, and it’s important to do your homework simply earlier than deciding upon one specific. Glance for licensed execs with stellar reputations and clear value buildings to make sure you might be getting the very best doable help and supplier.

    Conclusion: Your Critical to a Superior Home mortgage Experience

    The verdict from our social media evaluation? Mortgage brokers are, in reality, actually value their physique weight in gold for almost all of homebuyers. They current unparalleled receive to a lot better costs, personalised firm, and expertise that may simplify the home mortgage method significantly. Although it’s essential to methodology the ultimate determination with therapy, deciding on a respected dealer can open doorways to property finance mortgage alternate options you won’t have identified existed.

    Whether or not you’re stepping on to the belongings ladder for the primary time or looking for to include to your portfolio, consider this notion from genuine individuals who’ve navigated the house finance mortgage maze. Home mortgage brokers should not simply an resolution for a lot of, they’re the important thing to unlocking the door to their new dwelling.

    Try to recollect, irrespective of if you’re looking to private, develop, or shield your property, the suitable recommendation could make all of the variance. Let us make educated decisions alongside each other and alter the aspiration of homeownership into a actuality.

    Prepared to converse with a property finance mortgage dealer to seek out out a lot extra? Use the software down under to e ebook an no-price session with a individual of our professional mortgage mortgage brokers today!
  • Nationwide Dwelling Rate Index and Property Charges Typically

    Written on 5 December 2023 by Ray Boulger

    Nationwide House Price Index and House Prices Generally

    Nationwide’s November dwelling price index press launch charges charges in November as increasing by .2% however this misleading determine is barely following the seasonal adjustment manipulation. The genuine decide, additionally quoted within the press launch, was a drop of .3% on the month. The yr-on-yr determine is minus 2.%.

    The index reveals the true typical promoting worth in November at £258,557, lower than the August determine of £259,153, which might make a mockery of some remarks referring to promoting costs elevating for 3 months in a row, based mostly totally on simplistically wanting at solely the manipulated figures, devoid of mentioning what figures are staying utilised!

    Real prices fell by .65% in December 2022 and so till costs slide by further than this in December, the once-a-year 2023 decide will clearly present a price discount of rather a lot lower than 2.%. Regardless of whether or not the yr finish decide is a bit earlier talked about or beneath 2% values have held up much better than I envisioned, which gross sales alternatives to some warning in looking for to gauge what is going to occur in 2024.

    Price tag actions in 2023 have been remarkably small. The closing December 2022 decide was £262,068, a slide of 4.3% from the August 2022 peak. Costs fell a small additional extra all via the upcoming 3 months, bottoming out in March 2023 at £257,122, leading to a peak to trough drop thus far of 6.% (August 2022 – March 2023).

    Most of this drop took put within the remaining 5 months of 2022, however due to to a strong business within the very first half of the yr charges however closed 2.8% bigger on the yr. Thus any particular person simply calendar yr price ticket variations received’t see the entire picture.

    Apart from the power of the market in 2023 (in values, not transaction figures) one other surprising component is how slim the speed actions have been – lower than 2% from the very best to most cost-effective thirty day interval so considerably, with solely an individual month to go.

    The November decide of £258,557 is barely .6% earlier talked about the March 2023 low stage and in order I assume much more modest price falls greater than the long run few months the height to trough decide might be to extend.

    Just one variable aiding to keep up charges in 2023 was the substantial discount in new dwelling completions as builders slashed begins off simply after the chaos induced by the Truss/Kwarteng mini worth vary. Commences recovered strongly from Q2 2023 and so new dwelling completions in 2024 ought to be considerably earlier talked about this yr’s pissed off levels.

    Despite the truth that the price of set price mortgages will drop further all through 2024 folks transferring dwelling will however must acknowledge a considerably higher mortgage price than they’re possible to be spending on their newest mortgage mortgage, with the added cost solely partly offset by bigger incomes. Buying and promoting up will consequently proceed to current an affordability drawback for quite a few movers in 2024.

    In follow affordability will are available 2 guises – the best property finance mortgage a borrower considers cheap is often bigger than lenders’ figures and on the immediate this can be a larger problem than widespread. The motive is that we’re discovering 2 calendar yr mounted prices are at present essentially the most well-known mortgage choice, which implies that to adjust to FCA insurance policies mortgage firms must stress examination the optimum mortgage at not lower than their revert to cost, usually the SVR, in addition to 1%. Most key lenders’ SVRs begin with an 8 and so they need to pressure examination at greater than 9%.

    Though debtors preferring a 2 calendar yr resolve however constrained by lenders’ giant SVRs can keep away from this drawback by choosing a mounted worth for five yrs or lengthier (the regulatory anxiousness examination linked to SVR doesn’t use to fixed costs of 5 yrs or for an extended time) mortgage firms may mitigate the issue by bringing the unfold regarding Lender Price and SVR once more to in regards to the 2% degree which was common proper up till 2007. As variety of debtors actually shell out SVR for in depth, if in any respect, by significantly the main have an effect on of this sure mortgage price is its goal in pinpointing the best mortgage obtainable, considerably than as an revenue generator for mortgage suppliers.

    This concern highlights the dilemma of no matter whether or not an fascination price couple people pay remains to be pertinent in right now’s market as the perfect reference cost for evaluating highest borrowing!

    Categories: House Market, Ray Boulger

  • Toni Lamb: Championing property finance loan achievements

    Toni Lamb: Championing property finance loan success | Australian Broker News

    News

    Toni Lamb: Championing mortgage success

    Two a few years of remodeling Gold Coast mortgages

    Toni Lamb: Championing mortgage success

    Toni Lamb (pictured beforehand talked about), principal and lending skilled at LJ Hooker House Loans Gold Coast, has designed appreciable strides within the finance and precise property sectors, from beginning a property administration enterprise to excelling in property finance loan brokering.

    With far more than 20 a number of years of enterprise sensible expertise, she delivers deep understanding and empathy to her job, inspiring and producing a change within the lifetime of quite a few on the Gold Coastline by her expertise in residence loan brokering.

    Getting into the broking surroundings

    “I turned a dealer in 2008 when the GFC hit,” Lambs remembers about her change to mortgage broking after redundancy at Macquarie Lender. “I had a 12 months off after which I went and commenced working as a dealer, understanding as considerably as I might all through this time interval.”

    Good developments within the sector

    Lamb notes an important shift within the market: “Brokers are the first port of join with when somebody desires a mortgage loan in its place of heading to the banking establishments, it is a nice accomplishment for our market.” She praises the evolution that now sees brokers presenting different, firm, and personalised care to their clients.

    Latest difficulties and solutions

    Going by way of financial fluctuations and excessive property loan charges, Lamb sees the principle impediment as ensuring clients care for their mortgage repayments.

    “For us, we’re on this article to assist them and guarantee we get them by this tough time,” she claims, highlighting the assist brokers ship all through monetary downturns.

    Memorable encounters and classes uncovered

    Lamb shares a touching story of a buyer who needed to navigate economical independence following a chronic relationship ended.

    “The lesson is at all times on no account resolve anybody, show empathy however it’s essential to have the data and relationship competencies to make sure you do the best in your customers,” she says.

    Guidance for aspiring brokers

    For all these transferring into the sphere, Lamb advises: “Pay consideration, research, and have a incredible mentor who can provide the steering you need.”

    She underscores that creating understanding and depend on are paramount in home loan brokering, the place brokers assist with main life transactions.

    Get the preferred and freshest home loan info shipped appropriate into your inbox. Subscribe now to our FREE day-to-day e-newsletter.

    Retain up with essentially the most present info and occasions

    Be part of our mailing guidelines, it’s completely free!

  • How major banking institutions stabilized home loan earnings even with volume slipping

    Huge monetary institutions kicked off the earnings season with some early-yr weak spot in situations of the amount of housing finance train, however there have been some shiny locations of their mortgage loan ultimate outcomes.

    Some of the margins on monetary loans have been being greater within the first quarter, and that contributed to stabilized dwelling lending money circulation even at Wells Fargo, which introduced an exit from the correspondent channel ultimate calendar yr and noticed a particularly steep drop in amount.

    Obtain-on-sale margins for mortgages improved for every Wells Fargo and JPMorgan Chase on a quarter-to-quarter foundation and outpaced anticipations, a report from Keefe, Bruyette & Woods mentioned.

    Wells recorded a 287 basis-issue consecutive-quarter GOS acquire. Even although which may not be indicative of broader tendencies because of a particularly low amount within the former fiscal time interval and another idiosyncrasies, JPMorgan Chase additionally identified an uptick, albeit by a much more modest 83 foundation factors.

    “The sturdy Q/Q margin boosts have been a bit of little bit of a shock,” Bose George, Alexander Bond and Thomas McJoynt-Griffith, analysts at KBW, reported in an evaluation of Wells Fargo, JPMorgan Chase and Citibank’s earnings targeting their mortgage loan implications.

    This improvement might help to explain why even whereas Wells’ originations dropped 22% from the earlier quarter, residence lending earnings have been up, rising to $864 million from $839 million. The first-quarter amount nearly matched the $863 million famous a yr earlier than.

    The economical metrics advise that whereas Wells’ correspondent exit has cost it some amount, it’s paying off in phrases of refocusing the corporate on retail originations which have elevated margins.

    Loans originated by third occasions like brokers or correspondents can assist with volume in an interest-amount setting that isn’t conducive to refinancing just like the present-day a single, however people channels additionally tend to be vulnerable to margin pressure in all these a present market.

    JPMorgan Chase initially-quarter figures suggest it additionally could possibly be adjusting its financial institution loan mix to shift away from correspondent and place a minor further emphasis on retail, although by no implies has it been as aggressive as Wells. The former’s retail share inched as much as 67% from 65% on a consecutive quarter foundation.

    All by means of that exact same interval, JPMorgan Chase noticed over-all volumes slip by 8%. Correspondent volume dropped by 12% and retail fell by 6%. Web income from home lending rose to $1.19 billion from a little or no in extra of $1.16 billion the previous quarter and $720 million a yr earlier than.

    Citi’s volumes rose by 11% on a consecutive-quarter foundation that possible got here from market place share it obtained from Wells Fargo’s retreat, analysts acknowledged. The earlier enterprise didn’t break up out portions for its smaller sized property lending small enterprise to the extent that Wells and Chase do, however well-known there have been “enhanced mortgage loan margins” in its retail banking phase.

    One extra shiny spot for home loans within the financial institution earnings was an enhancement in valuations for property finance loan servicing authorized rights, presenting a distinction to publish-downs seen at some organizations within the fourth quarter.

    JPMorgan Chase’s MSR valuations rose by 1.8% and Wells’ rose by 3% on a consecutive-quarter basis, with analysts at KBW noting that this was in line with anticipations equipped curiosity fee adjustments all by means of the interval.

    Citi’s involvement within the MSR market place has been relatively compact contemplating that it bought off tens of billions of greenbacks in servicing again in 2017.