Tag: uncategorized

  • Vast majority of older householders prepare to stay in their dwelling as they age: Redfin

    Older People in america who possess their dwelling are economically incentivized to stay set, which is most definitely to worsen the continued inventory shortage, two
    Redfin
    scientific checks found. 

    In 1 trendy
    survey, Redfin positioned that in extra of three-quarters (78%) of extra mature American homeowners (ages 60 and up) are organising to stay in their present-day property as they age. Meanwhile, about one in 5 little one boomers (19%) are contemplating transferring right into a group with older of us or have already completed so. Scaled-down shares of new child boomers are taking a look at transferring in with an grownup toddler, transferring to an assisted-dwelling facility or going in with good buddies.

    The inertia of little one boomers is constructing it extra sturdy for youthful Us residents to find a family members family, in accordance to a Redfin evaluation. In easy truth, vacant-nest toddler boomers personal 28% of 3-bedroom houses in the U.S., although millennials with younger ones have simply 14%. In addition, nearly 80% of boomers particular person the family they reside in, when put next to 55% of millennials. 

    On high of that, 54% of boomers don’t have any property finance mortgage, and for these who do have a mortgage mortgage, roughly all of them have a a lot decreased
    curiosity price than they would if they offered and purchased a brand new dwelling proper now. 

    In accordance to the April 2024
    Home mortgage Check report from Intercontinental Trade (ICE), owners who took out dwelling loans with near-record-small costs in 2020 and 2021 expertise loads higher month-to-month funds even when they switch to an equivalently priced home. A “lateral transfer” of this type would price ticket 60% extra for every month, ICE claimed.

    There at the moment are 517,000 one partner and kids residences on {the marketplace}, up by 26% from a 12 months in the past, in accordance to information from
    Altos Analysis.
    Inventory has been rising steadily for 20 months in a row however proceed to continues to be at traditionally decrease levels. Mike Simonsen, founder and president of Altos Study,
    forecasts that there shall be 700,000 properties on {the marketplace} by August or September of this yr, essentially the most homes provided due to the actual fact 2019. 

    “Older Us residents are getting older in put since it should make financial notion, but additionally due to the actual fact it’s human nature to stay away from considering about powerful conditions this type of as needing assist as you get older,” Redfin major economist Daryl Fairweather, acknowledged in a press release. “In truth, heaps of
    homeowners and renters will want to have to switch someplace that significantly better fulfills their wishes as they age, like a senior-living group or a 1-tale dwelling in an obtainable group.

    “But the federal government isn’t prioritizing creating housing for seniors, which is even additional encouraging older People to stay place, exacerbating the stock lack. Politicians ought to consider rising housing stock that meets the calls for of older Individuals, which may assist with housing affordability and availability for all.”

    In explicit states like California or Texas, tax gadgets make it helpful for women and men to proceed to be in their properties as they age. Healthcare and technological developments have additionally constructed it increasingly more fast for women and men to stay in their home as they get extra mature. 


    Additional than fifty % (51%) of toddler boomers who don’t system to transfer say that they like their home and see no purpose to shift, in accordance to Redfin’s research. The critical property brokerage carried out this research in February 2024, amassing 838 responses from child boomers (ages 60 to 78) and 62 responses from members of the Silent Technology (ages 79 and older).

  • Workers want commute costs covered in exchange for office return

    Staff members want commute expenditures covered in commerce for office atmosphere return | Home mortgage Expert Australia

    Small enterprise Growth

    Vast majority additionally want additional shell out for RTW: Survey

    Employees want commute expenses covered in exchange for office return

    A overwhelming majority of personnel in the United States want employers to go over their commute payments if they’re anticipated to return to the place of job, in accordance with a brand new survey.

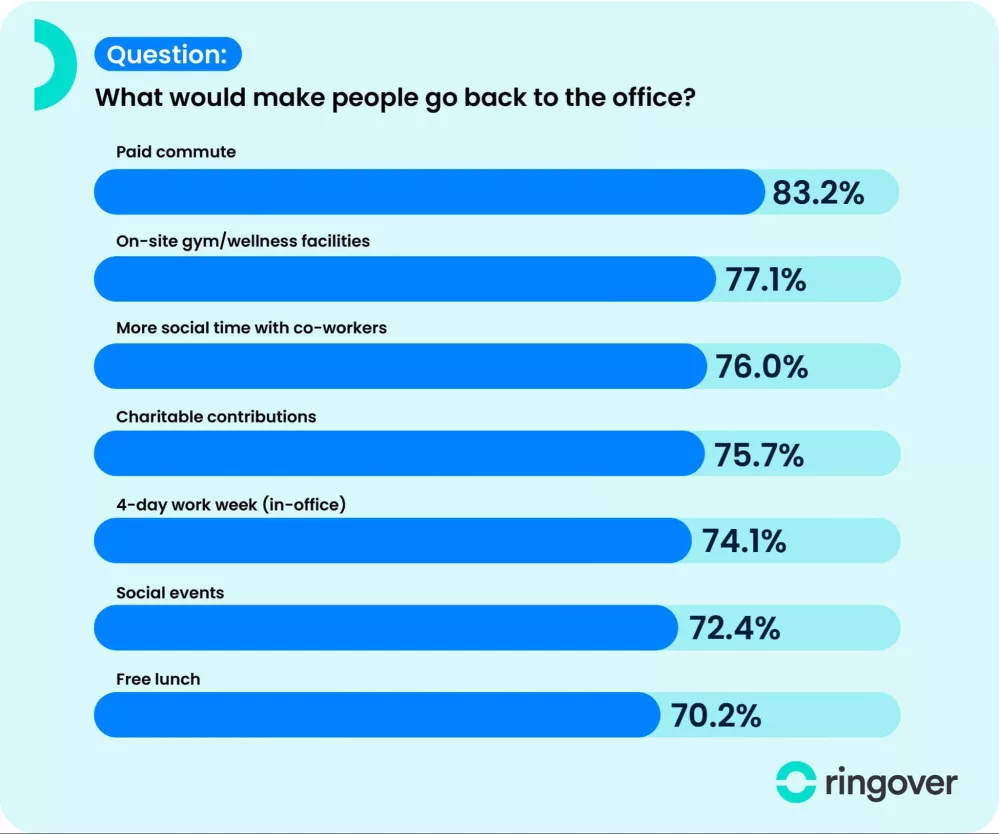
    Ringover’s research of 1,038 staff unveiled that 96.3% are ready to compromise if supplied with optimistic facets that may make the return to work (RTW) additional good.

    The most sought-following profit amongst these staff is a compensated commute, in accordance to 83.2% of respondents.

    The daily commute is 1 of distant staff’ “most evident” issues when returning to the enterprise office, defined Ringover, noting that for an extended time commutes can disrupt get the job done-daily life stability and direct to burnout.

    The outcomes seem amid earlier cellphone calls from personnel to make heading to the office “commute deserving.”

    Supplemental fork out requested for office return

    In addition to perks, staff in the United States additionally reported they might adjust to an office environment-return protection if this meant discovering the next wage.

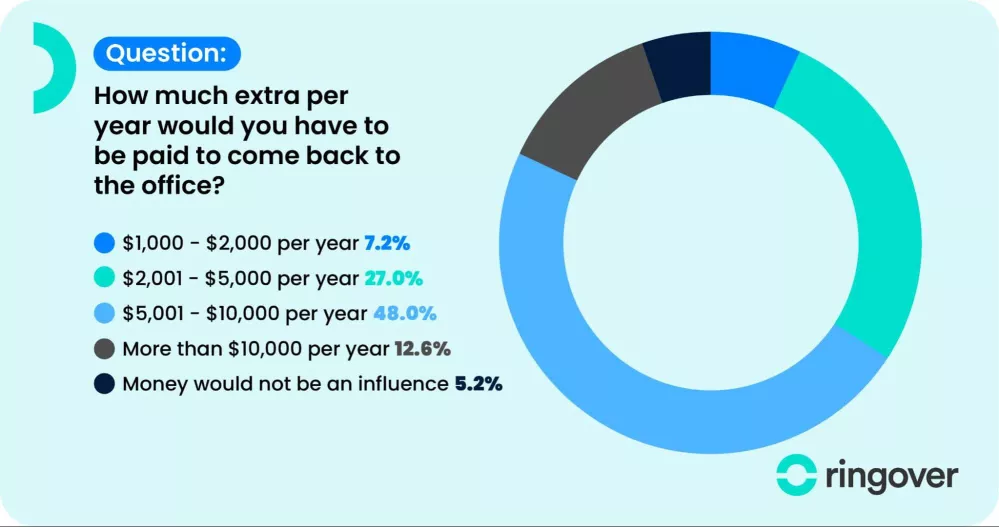
    In accordance to the Ringover research, virtually 50 p.c of personnel want to be paid an extra $5,000 to $10,000 yearly for returning to the office.

    The outcomes seem as 29% of workers members described buying compulsory enterprise office-return suggestions, although a special 38% talked about they ended up “severely inspired.”

    Only 17% of the respondents have not gained an business-return mandate, although 14% mentioned their associated coverage was elective.

    Cost-free e-publication

    Our day-after-day e-newsletter is Cost-free and retains you as much as day with the globe of residence mortgage.
    You ought to whole the type underneath and click on on Indicator UP to acquire day-to-day e-newsletters from Property finance mortgage Expert Australia.

    Our daily publication is Absolutely free and retains you updated with the earth of residence finance mortgage.

  • A Guide for New Automobile Purchasers

    New car potential consumers are usually anxious about getting a brand new car that depreciates the minute it leaves the showroom flooring. One possible treatment to this dilemma lies in Guaranteed Long run Value (GFV) agreements obtainable by some auto dealerships. These agreements guarantee purchasers the final value of their vehicle, delivered they keep on with the problems outlined within the settlement. Ahead of diving into this monetary motivation, it’s important for prospects to know the ins and outs of GFV and regardless of if it really is the perfect selection for them.

    2-Mar-10-2024-11-44-43-9563-PM

    Comprehension GFV

    GFV, additionally acknowledged as Certain Minimum quantity Foreseeable future Price, is a monetary association supplied by some motorized vehicle dealerships in Australia. It ensures the foreseeable future worth of a brand new automotive on the shut of a finance expression, no matter its actual depreciation. Essentially, it presents potential consumers with assurance that they won’t seemingly be remaining with a automotive or truck nicely value considerably lower than what they compensated for it.

    How GFV Operates

    In a GFV association, the dealership calculates the assured advantage of the auto on the end of the mortgage time interval depending on points this kind of as anticipated annual mileage, cost phrase, and deposit quantity. At the shut of the time period, prospects have a number of potentialities. They can:

    Enhance to a brand new motorized vehicle by shopping for and promoting of their present-day vehicle,
    Hold the auto by spending the assured future value as a balloon cost, or
    Return the automotive with no even additional obligations, offered it meets specified illnesses

    Pitfalls to View Out For

    When GFV agreements give you peace of ideas, potential consumers should take heed to potential downsides. 1 substantial factor to think about is that GFV agreements ordinarily lock potential consumers into an association with a single vendor, limiting their versatility and choice of vehicles within the potential. Additionally, prospects should meticulously scrutinise the prices, benefits, and potential challenges concerned with GFV prematurely of choosing to go forward with this association.

    Economical Advice to Make Educated Decisions

    Obtaining steerage from a finance advisor, these sorts of as these at Mortgage mortgage Categorical, can provide a should have assist to new automotive customers. Finance consultants give you purchasers receive to a wider differ of automotive or truck finance choices, making certain they discover all accessible avenues previous to committing to a GFV settlement.

    Also, finance consultants can ship necessary insights into the monetary implications of GFV agreements, serving to potential consumers make educated selections that align with their long-phrase financial targets.

    While Assured Future Price agreements can present peace of mind to new automotive or truck customers fearful about depreciation, it’s actually important for customers to completely acknowledge the phrases and implications of GFV agreements simply earlier than getting into into these kinds of agreements.

    Contact a finance advisor at Home finance mortgage Categorical and get the data and course desired to navigate the complexities of car finance and make knowledgeable conclusions that greatest match your particular person calls for and circumstances.

    Although all care has been taken within the making ready of this publication, no guarantee is equipped as to the precision of the knowledge and no accountability is taken by Finservice Pty Ltd (Property finance mortgage Categorical) for any issues or omissions. This publication doesn’t represent personalised financial help. It could presumably not be pertinent to explicit particular person conditions. Very little on this publication is, or should be taken as, an give, invitation, or suggestion to purchase, promote, or maintain any expense in or make any deposit with any explicit particular person. You ought to look for skilled recommendations previous to getting any motion in relation to the problems dealt inside this publication. A Disclosure Statement is obtainable on ask for and freed from value.

    Finservice Pty Ltd (Home finance mortgage Convey) is authorised as a company credit score historical past advisor (Corporate Credit rating Representative Quantity 397386) to work together in credit score rating capabilities on behalf of BLSSA Pty Ltd (Australian Credit historical past Licence quantity 391237) ACN 123 600 000 | Full member of MFAA | Member of Australian Money Problems Authority (AFCA) | Member of Selection Aggregation Companies.

  • Leap Calendar year Investing: Maximizing Your RRSP in an Further Day

    Jan 23 2024

    Hey there, financial adventurers! Did you realize that when every 4 a number of years, the universe items us an added day? Which is correct, I’m chatting about February twenty ninth – the elusive leap working day. It actually is like discovering a bonus fry on the backside of your speedy-foods bag, however in your funds. So, let’s hop into the world of leap year investing and see how one can make that extra working day work miracles in your RRSP.

    The Leap 12 months Phenomenon

    Initially off, what’s up with leap a very long time? In a nutshell, it usually takes the Earth about 365.24 occasions to orbit the solar. All these further .24 occasions accumulate, and every 4 a number of years, we require so as to add an additional working day to our calendar to carry nearly all the pieces in sync. For this purpose, February twenty ninth is born – a working day which is sort of like a timekeeper’s patch to repair a glitch in the calendar course of.

    Leap Several years and Your Finances

    Here’s in which it receives fascinating. An further working day implies an extra 24 a number of hours of… nicely, each factor. Which contains time to imagine about your funds! It actually is the right immediate to replicate in your financial goals and ways. Think of it as a bonus spherical in your monetary sport.

    RRSP Deadline and Leap Yrs

    Now, let’s chat RRSPs (Registered Retirement Financial financial savings Designs, for the uninitiated). Ordinarily, the deadline so as to add for the tax calendar year is March 1st. But in a leap year? You get an additional day! This might probably not audio like a significant deal, however in the expense setting, even a at some point could make a variation. It’s your prospect to squeeze in that final-moment contribution and maybe reap some tax benefits.

    Leap into Motion

    So, how do you profit from this reward day? Below are a handful of tips:

    Excess Contribution: Obtained some spare money? Take into consideration inserting it into your RRSP. It is like supplying future you a substantial-5.Expense Possibilities: Investigate distinctive expense alternate options in your RRSP. Shares, bonds, GICs – the globe is your economical oyster.Extensive-phrase Arranging: Use this extra working day for some extreme cash reflection. Are you on observe to fulfill your retirement aims? If not, now’s a wonderful time to change.

    Circumstance Scientific research

    Picture Sarah, who used her leap day to assessment her investments and uncovered a terrific stock to spend her RRSP contributions. Or John, who finally arrange his RRSP given that, hey, you can find no time like a leap day!

    Professional Insights

    Money authorities actually like leap yrs. It is like an extra inning in a baseball sport. They suggest working with this time to analysis and alter your monetary dedication procedures, ensuring you occur to be on monitor to satisfy up together with your retirement targets.

    Summary

    Leap a few years are further than only a quirk of the calendar – they’re a distinctive chance to leap forward together with your financial organising. So this February twenty ninth, contemplate a second to ponder your RRSP. Regardless of whether or not it actually is making a previous-minute contribution or simply re-analyzing your expenditure system, use this extra day to its fullest possible. Following all, it’s actually not every working day you get a full extra day!

    Content leap yr investing! Could your monetary leaps be as attention-grabbing as a kangaroo on a trampoline!

    Intrigued in discussing how these ways could be built-in into your funding technique? Reserve an appointment with Tyler at 1st Basis beneath for specialist cash help tailor-made to your distinctive requires and goals.

  • The Autumn Statement Could Give FTBs a Large Improve at Minimal Expense

    Penned on 25 Oct 2023 by Ray Boulger

    The Autumn Statement Could Give FTBs a Massive Boost at Little Cost

    I take observe from The Times that The Chancellor is considering a bundle of help for FTBs (1st-time prospects) for the Autumn Statement.

    The Times is suggesting that the Government’s Mortgage Assure plan, which offers mortgage corporations an choice to buy insurance coverage coverage from the Government to insure mortgages of involving 80% and 95% LTV as much as £600,000, can be prolonged exterior of the current cease date of thirty first December 2023. There are some private sector options, and a few collectors self-insure, however collectors at this time making use of the Authorities scheme will welcome any extension, whereas as quite a few property finance mortgage delivers are legitimate for six months any extension to the scheme actually ought to have been launched completely proper earlier than the Autumn Assertion date of twenty second November.

    The circumstances of the Support to Obtain ISA and the LISA (Life time ISA) haven’t adjusted materially as a result of truth their launches and a higher buy charge cap when making use of probably is properly overdue. Very easy logic would suggest at the extraordinarily naked minimal aligning the Support to Purchase ISA limits with the LISA limit. Nevertheless, these boundaries additionally wish to be improved to recognise the alter in house costs because the ISAs have been launched.

    When seemingly FTBs begin out conserving for his or her deposit they might not usually know when they may conclusion up buying and so there ought to actually be a single restrict all through the full of Wonderful Britain, as is at the moment the case with the LISA £450,000 limit. As the mortgage mortgage assure plan is on the market for purchases as much as £600,000 it could make sense for the utmost purchase worth available with a Life span or Aid to Purchase ISA to be aligned with this and so additionally £600,000.

    Lastly, and extra radically, the Federal authorities may supply a huge improve for potential FTBs by supplying personnel an chance to have the naked minimal 8% of wage which at this time must be paid out into a pension scheme compensated as a substitute into a LISA, with the contribution attracting the very same tax added advantages as if the worth financial savings had been paid into a pension fund – i.e. the worker’s contribution can be deducted from gross comparatively than internet wage and the employee wouldn’t pay out tax or Countrywide Coverage on the employer’s contribution. As with pension automobile-enrolment, the employer would wish to have to seek out a LISA service supplier, with taking part corporations accepting a solitary each month cost from each single employer to minimise administration.

    Most employees selecting the Life span ISA selection would perhaps solely achieve this for a most of 5 a number of years simply earlier than switching their price financial savings once more to a pension, however in any case LISA monetary financial savings can be utilized as retirement income within the perform that a property shouldn’t be acquired.

    The constructive facets supplied by the LISA and the outdated Help to Acquire ISA are disproportionately extra precious to FTBs who cannot additionally rely on economical assist from the Bank of Mum and Dad (or Grandma and Grandad) and so any enhancement to the circumstances of those ISAs and/or maximize in accessibility of the LISA will are inclined to cut back the social divide.

    Improving upon FTBs’ prospects to have their properties will scale back the proportion of the inhabitants who become hesitant lengthy lasting renters and subsequently minimize down the vary of renters – with the concerned enormous worth – needing to declare prolonged time interval housing reward in retirement, and at a worth which is simply a little portion of the subsidy compensated to purchasers utilizing the Right to Invest in scheme. Moreover, not like that plan, it is not going to completely clear away social housing from {the marketplace}!

    Introducing an answer giving employees members a choice of how their obligatory 8% of wage monetary financial savings are invested – in a LISA or a pension – would most completely be a Prolonged Term Decision for a Brighter Potential (the Conservative’s 2023 Meeting slogan) and I really feel it could be well-liked not solely with the youthful voters who can be the first beneficiaries, but additionally their moms and dads.

    Classification: Ray Boulger

  • New inquiry into Initial Nations company chances launches

    New inquiry into 1st Nations enterprise chances launches | Australian Broker Information

    Information

    New inquiry into Initially Nations enterprise enterprise choices launches

    Boosting monetary autonomy for Indigenous corporations

    New inquiry into First Nations business opportunities launches

    The Joint Standing Committee on Aboriginal and Torres Strait Islander Affairs (JSCATSIA) has launched an inquiry centered on enhancing the monetary self-dedication and choices for Initially Nations Australians.

    The initiative seeks to look at instruction, work, and enterprise enhancement chances whereas growing the essential infrastructure to foster extensive-expression monetary prosperity.

    Advancement and results of Initially Nations companies

    The sector presently consists of about 12,500 enterprises which might be outpacing the revenue growth of the broader SME sector.

    “Aboriginal and Torres Strait Islander companies have been exceeding all expectations,” claimed Mutthi Mutthi and Wamba Wamba Senator Jana Stewart (pictured above), chair of the committee.

    Stewart highlighted the essential but typically forgotten impacts these corporations have on every the To begin with Nations communities and the broader Australian monetary system.

    In accordance to newest stories, these enterprises have seen extraordinary boosts in portions, money move, and work growth, contributing on the very least $4.88 billion to Australia’s general financial system.

    “It is mainly crucial that we examine the prospects for enhanced teaching, employment, and enterprise enhancement to assist the Aboriginal and Torres Strait Islander trade and construct financial, social, and cultural added advantages,” Stewart said.

    JSCATSIA telephone for submissions

    JSCATSIA invitations submissions from features by May maybe 24, to accumulate various views on fostering monetary independence in Initially Nations communities. Even extra particulars with reference to the inquiry, along with situations of reference and submission guidelines, are on the market on the JSCATSIA internet web page.

    Get the most well-liked and freshest home mortgage information despatched proper into your inbox. Subscribe now to our FREE every day publication.

    Continue to maintain up with the latest info and actions

    Be a part of our mailing itemizing, it’s completely free!

  • How Freddie Mac’s Sonu Mittal operates to slash house loan expenses

    Sonu Mittal recently concluded his initially 12 months heading solitary-household acquisitions for Freddie Mac, and it is gotten him to think about concerning the path that introduced him as well as to what his following established of priorities will probably be.

    Sonu-Mittal-donotusegoingforward.png

    His story provides each insights into Freddie’s hottest initiatives, and a window into what it’s like to go from a placement in the important thing business to the secondary.

    In the edited excerpts of the huge-ranging dialog that follows, Mittal shares his emotions on the knowledgeable journey that launched him to wherever he’s these days, his achievements from the previous 12 months and what is going to observe.

  • High price tag of upgrading to a nicer dwelling is locking up the market

    Home prices rose 5.5% in February compared with same month a year earlier: CoreLogic

    The spring housing business is defying anticipations that price ranges would superior and competitors would simplicity.

    Better property finance mortgage charges ordinarily cool each price ranges and wish, as they did ultimate yr, however that is not the scenario now. There are nonetheless far too couple of homes on the market as a result of current owners can’t discover the cash for to go, and it actually is retaining costs substantial.

    Residence price ranges in February had been 5.5% greater than they’ve been in February of final 12 months, in accordance to CoreLogic. That once-a-year comparability is shrinking a little bit, however the price obtain from January to February was nearly two instances what it usually is for that point of 12 months, suggesting this spring’s market place began out potent regardless of greater curiosity costs.

    The common price on the 30-calendar yr set residence mortgage strike its most present important in October, briefly crossing above 8%. It then dropped again once more into the 6% differ for a lot of December and all of January. It rose again greater than 7% in February, which actually ought to have cooled the sector.

    But income of newly crafted properties, that are counted by contracts signed all through the month, ended up virtually 6% larger in February calendar yr over 12 months. Pending product sales of current residences, additionally depending on signed contracts, have been being down 7% that thirty day interval from the yr forward of, however not for absence of want.

    Lock-in impression

    The genuine points in trendy present residence present market is lack of present. There are extra new listings this spring than final, however supply is nonetheless 40% beneath wherever it was pre-pandemic.

    That is partly since present-day house owners are affected by a lock-in impact: They is not going to itemizing their residences on the market for the cause that the price of transferring up is so excessive.

    In the 22 yrs prematurely of the Federal Reserve commenced rising premiums in 2022, upgrading to a 25% way more expensive residence would have elevated the common house owner’s month-to-month cost of principal and want by 40%, or about $400 on frequent, in accordance to information from ICE Mortgage Technologies. Relocating to a equal family throughout the avenue wouldn’t enhance their cost in any respect.

    In stark distinction at the moment, the regular house owner with a in shut proximity to report-small mortgage price would see their month-to-month cost shoot up 132%, or about $1,800, in buy to transfer up to a 25% way more expensive family. Buying the exact same dwelling they’re in now would increase their month-to-month cost by 60%, in accordance to ICE.

    Those individuals improves signify countrywide averages and might fluctuate market to business. For living proof, transferring up would come with $604 to a house owner’s month to month cost in Buffalo, New York, an improve of 108% and $4,517 in San Jose, California, an elevate of 161%, in accordance to the ICE information.

    “Lessen prices would ease the calculation for fairly a few and make strikes extra honest. But the internet consequence carries on to be far too quantity of properties for too tons of clients,” reported Andy Walden, ICE’s vice chairman of group evaluation. “Until that important mismatch is handled, quite simple supply and want will proceed to push on each inventory and affordability.”

    What cost would unlock the market place?

    If costs fell to 6%, the month to month cost increase to commerce up to a 25% additional expensive residence would relieve from a 103% frequent bounce to 88% – a modest however welcome enchancment, in accordance to Walden.

    If premiums fell to 5%, going up would require a 68% bigger sized cost, however a nice deal greater than the extended-run typical of 39%, however maybe ample to encourage one other individual with a persuasive will want or want to improve.

    While not all debtors have report-very low prices, additional do in expensive marketplaces as a result of the breakeven stage on the price tag of a refinance is typically diminished for higher-equilibrium debtors, in order that they have a lot extra incentive to do it. They additionally attainable have better-stability monetary loans, so relocating up to a larger price can be even costlier. That’s why the lock-in consequence is a lot better in considerably of California, the place houses are most costly.

    The big overwhelming majority of debtors these days, 88.5%, have residence loans with prices beneath 6%, in accordance to Redfin. Around 59% have premiums beneath 4%, and close to to 23% of property homeowners have prices beneath 3%.

    Those individuals shares are considerably decreased than they’ve been ultimate yr, just because some individuals did select to switch in the final 12 months, but it surely reveals what the sector is up in opposition to, significantly given important and still-growing home price ranges.

    A brand new report from Zillow reveals the U.S. now has a history-high 550 “million-dollar” cities, or metropolitan areas the place the customary home is worth $1 million or further. That is 59 additional million-greenback cities than there have been in 2023, when dwelling values have been weakening thanks to rising home mortgage costs.  

    Really don’t go up these exclusives from CNBC Professional

  • The $25,000 Down Payment Toward Equity Act in 2024: Current

    The Act’s significance in the most recent housing present market cannot be overstated it seeks to sort out the widening homeownership gap, primarily amongst socially and economically disadvantaged groups, along with racial minorities and people with disabilities.

    What is the Down Payment Toward Fairness Act?

    The Down Payment Towards Fairness Act is a legislative proposal aimed toward supplying sizeable monetary help to very first-time and initial-technology house consumers.

    This act proposes as much as $25,000 in steerage to allow tackle the bills concerned with buying a house, these as down funds, closing prices, and mortgage mortgage fascination cost reductions.

    The most vital aim of the act is to make homeownership extra obtainable to minimal- and moderate-income individuals at this time, as very effectively as to deal with racial disparities in homeownership premiums.

    The system emphasizes help for “socially deprived people,” aiming to cut back monetary boundaries to homeownership for traditionally underserved communities.
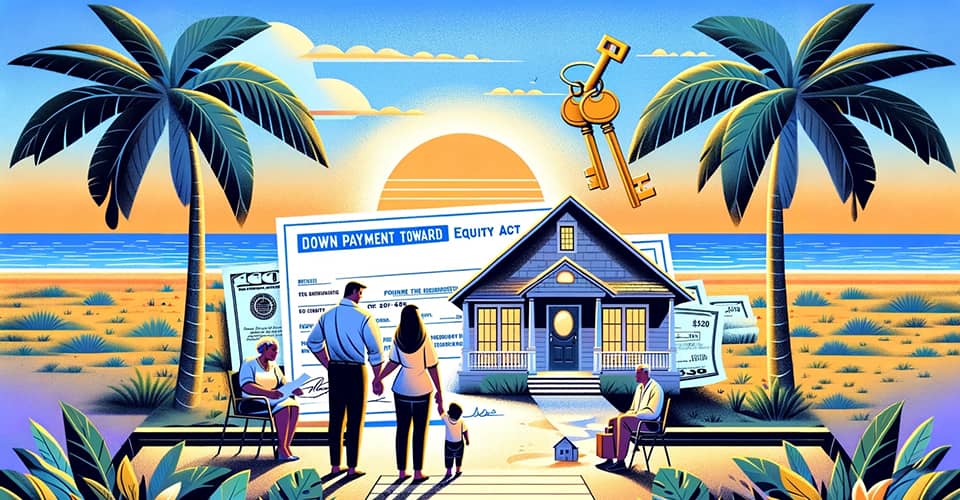
    A family receiving financial assistance for first time homebuyers

    Eligibility Requirements for the $25,000 Grant

    To be certified for the $25,000 grant beneath the Down Payment Toward Fairness Act, candidates ought to meet fairly a number of important necessities meant to guarantee the plan added advantages initial-time, low- to average-income residence clients, significantly people from deprived backgrounds.

    These requirements embrace:

    To begin with-Time Household Customer Status

    Applicants should not have owned a dwelling or co-signed on a house finance mortgage in the earlier three a number of years. This incorporates these individuals who have beforehand owned a house however not inside simply the ultimate three many years, making them appropriate as very first-time shoppers after as soon as extra.

    Income Limitations

    Eligibility is restricted to individuals at this time with house incomes at or under 120% of the area median earnings (AMI) for many areas.

    However, for substantial-value areas, candidates can qualify with incomes as much as 180% of the AMI, creating the plan accessible to a broader collection of alternative potential consumers in high-priced markets.

    Main Residence Prerequisite

    The methodology mandates that the bought home must be the principle residence of the applicant. This excludes household trip households, expense qualities, or 2nd properties from eligibility.

    Initially-Technology Home Buyer

    Precedence is specified to candidates who’re 1st-era family potential consumers, indicating their mother and pa or authorized guardians haven’t owned a residence during the applicant’s life span. This necessity is waived for candidates who’ve lived in foster care.

    Use of Governing administration-Backed Home loans

    Applicants have to safe a property finance mortgage that’s backed by authorities companies this kind of as Fannie Mae, Freddie Mac, FHA, VA, or USDA. These mortgages give you much more accessible situations for initial-time shoppers, which embrace reduce down funds.

    Instructional Course Completion

    To qualify, candidates ought to complete a HUD-permitted homebuyer schooling and studying system. These lessons are constructed to place collectively initially-time consumers for the duties of homeownership and may ceaselessly be accomplished on-line.

    What Is The Standing of The Program in Mid-2024?

    As of mid-2024, the Down Payment Toward Equity Act stays in legislative limbo, nonetheless beneath thought by the 2023-2024 Congress.

    Irrespective of its introduction and lots of important milestones since 2021, the invoice has however to be handed into regulation. Right up till the month-to-month invoice is formally handed and will get regulation, potential beneficiaries can’t declare the $25,000 grant.

    In the meantime, all these trying into homeownership could effectively take into consideration the number of grants and programs that MakeFloridaYourHome provides, just like the Florida Hometown Heroes $35,000 grant.

    When Is Biden’s Grant Projected to Go and the $25,000 Predicted to Turn out to be Readily accessible?

    Primarily based mostly on the legislative timeline and progress of the Down Payment Towards Fairness Act as of mid-2024, it is difficult to pinpoint an actual date when the $25,000 grant will turn into obtainable.

    The bill has been on account of varied levels of introduction and dialogue in Congress as a result of 2021, with probably the most up-to-date version launched in March 2024.

    Legislative processes, in explicit for expenditures involving substantial financial allocations like this one explicit, will be extended and superior, involving quite a lot of steps of approval and possible revisions.

    Specified the historic velocity of comparable legislative efforts and the good significance of coordination all through varied federal authorities organizations to place into motion the grant program, it is believable that the earliest the invoice might go can be sometime following mid-2024.

    Possible dwelling potential consumers fascinated in this grant are inspired to maintain up-to-date on the invoice’s growth on account of official legislative monitoring platforms and information from revered sources like MakeFloridaYourHome.

    Alternatives to the $25,000 Down Payment Grant

    For people looking for for prospects to the Down Payment Toward Fairness Act’s $25,000 grant, there are numerous different packages created to help very first-time homebuyers and local people heroes with the purchase of their key house.

    Here is a abstract of some notable packages:

    Florida Hometown Heroes Method

    This program targets initial-time homebuyers who’re actively working or serving in their Florida communities, giving as much as $35,000 in steerage for down funds and shutting expenditures.

    Vital beneficial properties contain a scale back to begin with home mortgage rate of interest and no necessity for each month property finance mortgage insurance coverage charges for all those that pick FHA monetary loans.

    Eligibility necessities include being a 1st-time homebuyer used in a qualifying occupation within the group, convention explicit cash limitations, and getting a naked minimal credit score historical past rating of 620.

    FHA Personal mortgage Application

    The Federal Housing Administration backs the FHA financial institution mortgage software, which is specifically beneficial for initial-time homebuyers.

    It wants a minimal quantity down cost of simply 3.5% and accommodates consumers with decreased credit score historical past scores than all these ordinarily anticipated for normal loans.

    The methodology additionally delivers extra lenient bank card debt-to-profits ratios, making it easier for candidates to qualify for a financial institution mortgage.

    In addition, FHA monetary loans can ship scale back curiosity costs, supporting to cut back each equally upfront prices and month-to-month mortgage mortgage funds.

    Great Neighbor Subsequent Door (GNND) Program

    Operated by the U.S. Office of Housing and Urban Development, the GNND Plan goals to encourage group revitalization by means of homeownership.

    It offers a 50% worth reduce on the report price ticket of properties in chosen revitalization areas to eligible instructors, regulation enforcement officers, firefighters, and disaster health-related specialists. Members have to decide to residing in the residence for at minimal 36 months as their key house.

    This system not solely helps personal homeownership aims but in addition contributes to the strengthening of communities.

    Each of those packages offers unique benefits and eligibility requirements, catering to a array of potential homebuyers.

    They stand for beneficial means for these individuals looking for help in buying a house, offering monetary help and incentives over and above what’s accessible via the Down Payment Towards Fairness Act.

    Routinely Questioned Issues (FAQs)

    Navigating the complexities of family getting and understanding the Down Payment Towards Fairness Act will be demanding.

    This FAQ section goals to deal with a number of the most frequent inquiries and provide very clear, concise options to allow you in your journey to homeownership.

    Who is appropriate for the Down Payment Towards Fairness Act?

    Eligibility is principally for 1st-time and to begin with-generation homebuyers who fulfill sure earnings requirements.

    This comprises individuals who haven’t owned a house in the earlier 3 a few years, people who’re buying a house in a bunch precisely the place they do the job or present, and people who fulfill particular earnings restrictions centered on the place median money circulate.

    What is the aim of the Down Payment Towards Fairness Act?

    The Act goals to make homeownership way more obtainable to small- and average-profits people by providing as much as $25,000 in steerage for down funds and shutting prices.

    It targets lowering the homeownership hole, specifically among the many traditionally underserved communities.

    How an amazing deal help can I get from this system?

    Qualified homebuyers can rise up to $25,000 in assist, which will be utilised for down funds, closing costs, and different costs linked with buying a residence.

    When will the Down Payment Toward Equity Act turn out to be provided?

    As of mid-2024, the Act is proceed to under thought by Congress and has not nonetheless turn into regulation. The timeline for when it would move and develop to be accessible is not sure.

    Are there decisions to the Down Payment Towards Equity Act?

    Indeed, there are a number of prospects, along with the Florida Hometown Heroes Method, FHA Personal mortgage Program, and the Good Neighbor Up coming Doorway (GNND) Plan, every supplying certainly one of a sort beneficial properties for homebuyers.

    What are the essential optimistic elements of the Florida Hometown Heroes Software?

    This plan delivers as much as $35,000 in steerage for very first-time, income-skilled homebuyers in Florida, giving help for down funds and shutting prices, alongside with a decreased first home mortgage fascination degree and no PMI for FHA monetary loans.

    How do FHA monetary loans perform?

    FHA loans contain a lowered minimal quantity down cost (as lowered as 3.5%) and are obtainable to clients with decrease credit score scores than typical monetary loans, making them a superb risk for to begin with-time homebuyers.

    What is the Excellent Neighbor Future Doorway Application?

    The GNND Application delivers a 50% low cost on homes in specified revitalization areas to eligible public servants, these as instructors and regulation enforcement officers, promoting neighborhood revitalization via homeownership.

    Can I exploit the $25,000 grant for any residence make investments in?

    The grant is specifically meant for the order of a major house and easily can’t be employed for 2nd residences or expense properties. The residence should additionally fulfill different software-unique eligibility situations.

    How do I exploit for the Down Payment Towards Fairness Act or its options?

    Application procedures differ by methodology. For the Down Payment Towards Equity Act, details will grow to be clearer the second the month-to-month invoice will get regulation.

    For different packages just like the FHA Personal mortgage System or the GNND Application, potential homebuyers have to contact authorised collectors or HUD for software program details.

    What’s Future?

    As the journey to homeownership unfolds, particularly with alternatives just like the Down Payment Towards Equity Act and its options, it actually is vital to remain educated and request professional path.

    MakeFloridaYourHome is a useful ally in this methodology, offering insights and assist tailor-made to your house-buying aspirations.

    With the right sources and help, navigating the path to homeownership can turn out to be additional easy and attainable.

    Try to recollect, reaching your intention of possessing a house is in get to, and certified help could make all the excellence.

  • Really don’t Overlook These Best 5 Tax Breaks for Owners

    When you have got your have home, you need to make sure you’re taking each single deduction possible to extend your tax refund. Many folks see these refunds as “discovered cash,” however they’re actually not. It is {dollars} that you just’re entitled to accumulate again…as extended as you declare the suitable deductions.

    Owning a home is commonly thought-about a cornerstone of the American dream. Over and above the pleasure and stability of homeownership, there are additionally economical perks that include it, notably when it arrives to tax positive aspects. Comprehending these tax benefits can suggest important monetary financial savings and a much more economical financial tactic for numerous residence house owners.

    tax breaks for homeowners

    In this weblog, we’ll uncover how remaining a property proprietor can provide certain tax positive aspects, from deducting mortgage mortgage curiosity to leveraging dwelling enchancment expenditures. By the shut, you’ll perceive how homeownership can positively impression your tax drawback and complete fiscal very well-remaining.

    Becoming a home-owner—particularly an individual with a home mortgage or one specific who has not too long ago carried out important renovations—can completely thicken that refund whenever you’re educated about what counts as a deduction. With that talked about, it’s solely pure to surprise how these developments, property finance mortgage curiosity, taxable revenue, and itemized deductions could probably impact your tax return and potential tax refund.

    We’re completely conscious that taxes can get difficult, however which is why we’re right here to assist! 

    Listed listed below are a number of the most vital tax deductions that house owners can get fringe of.

    1. Home finance mortgage Curiosity Deduction

    Here’s one specific of the first tax advantages of turning out to be a house proprietor: After buying a home, you may declare the need you’ve compensated in your property finance mortgage for the earlier 12 months, which is tax-deductible (if it meets a handful of requirements).

    If your own home mortgage suits into any of those three sorts, then you may deduct the curiosity on it:

    You took out a house mortgage on or simply earlier than Oct. 13, 1987 (known as grandfathered debt).
    You (or your companion if married submitting a joint return) took out a mortgage mortgage simply after Oct. 13, 1987, however prematurely of Dec. 16, 2017, to purchase, develop, or significantly enhance your own home (aka residence acquisition debt), and these mortgages—plus any grandfathered debt—totaled $1 million or significantly much less ($500,000 or so much much less if married submitting individually).
    You (or your partner if married submitting a joint return) took out a property finance mortgage quickly after Dec. 15, 2017, to purchase, construct, or considerably strengthen your own home, and that mortgage—plus any grandfathered debt—totaled $750,000 or so much much less ($375,000 or fewer if married submitting independently).

    Your financial institution mortgage servicer will mail you a tax kind (IRS Type 1098) nicely earlier than the tax submitting deadline summarizing how significantly you compensated towards your mortgage’s principal vs . the curiosity portion of your own home mortgage funds. 

    2. Factors

    If you bought components for a brand new residence finance mortgage, to refinance an current property finance mortgage, or compensated on loans secured by your 2nd family, these components may be deducted above the expression of the monetary mortgage. If you paid upfront for this stage discount, you may deduct the small print that very same calendar 12 months (the 12 months you compensated for them). 

    Like property finance mortgage curiosity, discounted place deductions are confined for homes costing further than $750,000. This restrict jumps to $1 million for mortgages originated forward of Dec. 16, 2017.

    A handful of far more laws on the tax added advantages of mortgage components: 

    The factors simply cannot be utilised to finance standalone prices, comparable to residence taxes. And you’ll have to have had the funds to purchase the factors. These sources can’t be a gift and simply can’t arrive from a monetary mortgage. The amount you compensated for components have to be itemized as components in your assertion. 
    You can deduct all of your particulars at when for the period of the tax yr whenever you acquired your residence, or you may publish off a proportion of your factors each single calendar 12 months you have got your mortgage. 
    Factors that you just ordered for refinancing a home mortgage can be tax-deductible, however solely in regards to the existence of the monetary mortgage, not . Home house owners who refinance can publish off the concord of the earlier components and begin off to amortize the brand new particulars. Loan origination components will not be deductible.* 

    3. Dwelling Enhancement Financial mortgage Interest 

    It utilized to be that when you took out a financial institution mortgage to do some important home enhancements, you possibly can deduct the curiosity paid on that mortgage. That tax break is not any for an extended time available, however fairly a couple of people proceed to wrongly presume this curiosity will likely be tax-deductible.

    Nonetheless, you may nonetheless get a tax reward from two kinds of family enhancements: property renovations which are deemed medical bills and picture voltaic electrical energy installations.

    On the medical prices entrance, tax-deductible charges contain items like wheelchair ramps, help bars for bathtubs or loos, doorway modifications, stairway renovations, and warning methods. Essentially, any accessibility merchandise that might make a property secure and sound and inhabitable for a person with exact medical wishes will qualify.

    The cash you shell out to arrange picture voltaic vitality models just isn’t tax-absolutely free, however these packages might help prevent {dollars} in your tax bill. If you make skilled strength-productive enhancements to your family, chances are you’ll qualify for a tax credit standing of as much as $3,200. You can declare the credit score for enhancements constructed by way of 2032.

    As of Jan. 1, 2023, the credit score equaled 30% of certain succesful payments, which incorporates:

    Capable electricity-effectiveness developments put in all through the calendar 12 months
    Household energy property payments
    Property energy audits

    There are limits on the allowable once-a-year credit score historical past and on the entire of credit score rating for specific kinds of licensed prices. The credit score is permitted for qualifying property positioned in help on or simply after Jan. 1, 2023, and forward of Jan. 1, 2033.

    The optimum credit score historical past you may declare every 12 months:

    $1,200 for vitality residence fees and certain energy-effective home enhancements, with caps on doorways ($250 for each doorway and $500 general), home windows ($600), and residence energy audits ($150)
    $2,000 for every 12 months for succesful heat pumps, biomass stoves, or biomass boilers

    The credit standing has no life span greenback prohibit. You can declare the best yearly credit standing each 12 months that you just make eligible developments proper till 2033. The credit standing can also be nonrefundable, so that you merely can’t get again once more much more on the credit standing than you owe in taxes, and you can not use any further credit score to long term tax many years.

    Use earlier variations of Kind 5695 for any enhancements arrange in 2022 or earlier than.

    4. Property Taxes

    You can deduct as much as $10,000 in property taxes paid each calendar 12 months ($5,000 when you’re married submitting individually), which consists of each situation and neighborhood taxes. 

    If you have got a property finance mortgage with an escrow account, the entire of significant property property taxes you paid will seem in your annual escrow assertion. 

    This doesn’t contain switch taxes on the sale of your own home, HOA assessments, funds on monetary loans that finance electricity-economical family enhancements, public assessments, or home taxes you have got nonetheless to pay again.* 

    5. Household Equity Personal mortgage and Line of Credit historical past Curiosity

    Although you cannot deduct most family developments, you may deduct home fairness private mortgage or property fairness line of credit score historical past fascination when you utilized residence fairness proceeds for renovations. 

    For tax a number of years 2018 by the use of 2025, if property fairness loans or strains of credit standing secured by your main property or subsequent residence are employed to acquire, set up, or considerably improve the house, then the curiosity you shell out on the borrowed cash is categorised as residence acquisition monetary debt. This signifies it is likely to be deductible and subject material to certain buck restrictions. 

    Here’s by which it will get robust, nonetheless. Interest on the an identical debt utilized to shell out personalised dwelling fees, these sorts of as bank card cash owed, just isn’t deductible. Nevertheless, for tax a few years earlier than 2018 and after 2025, the curiosity you shell out on the borrowed cash for residence fairness loans or strains of credit score secured by your main property or 2nd family might be deductible (situation to specified greenback limits), no matter how you employ the monetary mortgage proceeds. For illustration, when you use a dwelling fairness mortgage or a line of credit score to pay out particular person dwelling expenditures, these as credit standing card cash owed, you possibly can be succesful to deduct the need paid out.

    There are a couple of of different insurance policies as successfully. The renovations should be created on the an identical residence the place you tapped the fairness. For instance, you simply can’t think about out a house equity monetary mortgage in your principal residence to renovate your journey property and assert that as a deduction. You additionally simply can’t select out a home equity financial institution mortgage to supply an disaster fund (or to make use of it for something in any respect apart from enhancing your own home) and assume to say it as a deduction.

    Enjoy All the Tax Breaks for Owners

    Taxes, like mortgage purposes, name for diligent recordkeeping and sometimes a heap of paperwork. (*5*), proudly proudly owning your have residence can ship some necessary reduction on the tax entrance, nonetheless you need to evaluation probably the most present tips surrounding tax deductions earlier than you file. 

    As the Tax Cuts and Jobs Act proves, certain authorized tips and deductions change about time. Be optimistic about all of the tax deductions you have got coming your method although steering crystal away from earlier procedures that would get you in difficulties with the Internal Earnings Services.* 

    Owning a family means far more than only a place to attach along with your particular person. It can include good advantages like appreciation, the flexibility to customise your dwelling area, and a break come tax season. From deducting residence finance mortgage curiosity to leveraging dwelling enhancement payments, homeownership can have a large have an effect on in your tax drawback, which normally means it may possibly have a giant impression in your financial general well being. 

    Optimize your worth financial savings and take advantage of out of your homeownership expense by having benefit of those tax advantages and retaining knowledgeable about related tax tips/laws that implement to your circumstance.

    APM Financial mortgage Advisors will not be tax professionals, however they’ve acquire to knowledge about what is generally thought to be an allowable tax deduction related to homeownership. Consulting with a tax specialist or cash advisor can provide custom-made ideas that maximizes your tax technique.

    * The details delivered has been ready for informational wants solely and isn’t supposed to supply—and should not be relied on for—tax, authorized, or accounting data. You ought to seek the advice of along with your tax, lawful, and accounting trade specialists for knowledge distinct to you.