Tag: superannuation

  • Would Australia be far better off without the need of superannuation?

    Would Australia be better off without having superannuation? | Australian Broker Information

    News

    Would Australia be improved off without having superannuation?

    Professional affords solutions to Australia’s retirement problem
    Would Australia be better off without superannuation?

    Simon Pressley, founder of Propertyology, has a standing for shaking issues up in the residence expenditure planet. Now, he’s turning his sights on superannuation, a way he thinks fosters monetary complacency.

    In a present interview, Pressley (pictured over) failed to carry once more, criticising the good points of the superannuation procedures which have been in place as a result of 1992.

    “The program which everyone seems to be component of is created near apathetic attitudes and monetary complacency,” Pressley acknowledged.

    “Regardless of one’s very personal occupation kind or age, the odds of one specific working day exiting the workforce with the required fiscal belongings to assist one’s most popular means of life are poor.”

    The hassle with the retirement pillars

    Currently there are 1.6 million folks right now aged 65 and in extra of receiving earnings from an amazing merchandise. This choice will further than double above the future decade, with a even additional 2.5 million of us envisioned to depend on this 1st retirement pillar.

    According to an AMP report, the Affiliation of Superannuation Money of Australia (ASFA) estimates that Australians aged throughout 65 who particular person their private property and are in comparatively good total well being, would require the following amount of {dollars} every week and 12 months in retirement:
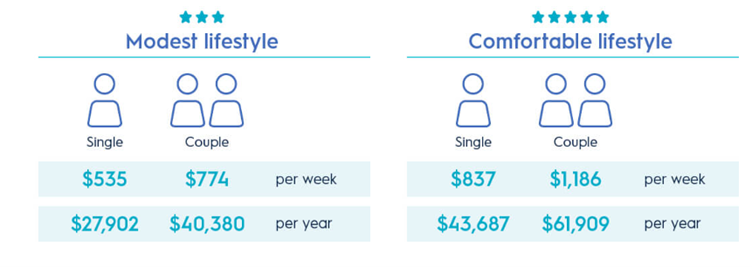
    For solitary of us, that signifies they need a lump sum tremendous stability of $595,000 although companions need $690,000.

    A latest survey discovered that two in 3 respondents feared they’d not have loads of saved for retirement, with and child boomers the era the very least assured – and there’s a sound motive for challenge.

    Pressley argued that the proof confirmed “the system” produces solely a 23% accomplishment quantity.

    In accordance to newest governing administration stats, the male common account concord in Australia at age 65 to 69 is $453,075. For girls of all ages, it is just $403,038.

    This implies the typical Australian needs an extra $125,000 of their great fund to be cozy.

    Retain in mind, that’s simply the regular – which might be significantly skewed in the route of the compact amount of retirees with substantial great balances.

    And with the charge-of-living solely possible up, it’s small surprise that the 15% of Australian who’re at the second aged greater than 65 are however in the workforce, principally primarily as a result of they only cannot pay for to retire.

    Of coaching course, there’s the second pillar: the age pension, which 62% of Australia’s retiree aged inhabitants rely on.

    These “back-finished unemployment advantages”, as Pressley cellphone calls it, solely equate to $25,000 for singles and $37,000 for {couples} – hardly ample for a comfortable retirement.

     While official arguments can be produced for growing it, it now bills $55 billion per yr of taxpayer money.

    “Consciously or subconsciously, these who tumble sufferer to ‘the system’ are accepting of a most cost-effective widespread denominator ultimate consequence,” mentioned Pressley. “Reading that assertion could presumably make of us sense uneasy, but it surely’s the actuality.

    “Superannuation solely exists since cash literacy will not be taught anyplace in society. And fairly couple folks right now have ample self-control.”

    Presently, the “small few” who actually established ambitions, work out financial self-discipline and commit of their upcoming are subjected to “tall-poppy criticism” by these individuals who have mastered the match of blame, excuses and authorized rights, Pressley reported.

    “Governments are completely manufacturing Robin Hood procedures which take from people who’ve produced rather more solely to present it to different people. It is unattainable to multiply wealth by dividing it,” Pressley reported.

    “Any society which doesn’t persuade of us to commit of their foreseeable future is a grossly underperforming trendy society.”

    Breaking out of superannuation jail: What’s the decision?

    At a macro diploma, Pressley talked about that instructing easy economical literacy – which incorporates the significance of everybody aspiring to prove to be financially unbiased – needs to turn into part of customary on a regular basis dwelling.

    Pressley additionally talked about he considers superannuation as little further than a “fall-back place”.

    “I choose to not insert a buck further into the superannuation jail than the legislation calls for, however I’m extraordinarily pushed to do as completely as can for my household’s long run with investments outside of the superannuation ambiance,” he claimed.

    “The solely certainties which a single can have with superannuation is that it’s going to certainly not be greater than sufficient, the age that one can entry it would retain buying stretched, the procedures will protect altering, and it affords unquestionably no handle in any respect above one’s long run.”

    Superannuation nonetheless has a function to carry out, however Pressley acknowledged it would certainly not be the complete choice.

    “The present research show that it has a two out of 10 success-level,” he claimed.

    As another, he favours variations to superannuation which contain:

    Initial-property consumers

    “A primary-time home buyer, along with a rentvester, ought to actually be authorised to withdraw a utmost of $30,000 to position in direction of a deposit on the spend money on of residential real property,” Pressley acknowledged.

    “Conditions of withdrawal actually ought to consist of [that] the human being must (at minimal) match the superannuation withdrawal with the very same quantity of their very personal real financial savings amassed above a interval of time of no considerably lower than two years.”

    Early accessibility

    “Those who’ve by now proven monetary accountability ought to to have the risk of accessing their superannuation from age 50, irrespective of whether or not they have completely stopped perform or not,” Pressley mentioned.

    “Eligibility standards would will need an ‘asset check’ of sorts and all those that do entry superannuation amongst the age of 50 and 65 forfeit any future accessibility to an aged pension.”

    Relevant Stories

    Retain up with the most up-to-date data and gatherings

    Sign up for our mailing record, it’s no value!
  • Millennials explore super financial investment | Australian Broker News

    Millennials study super investment | Australian Broker News

    News

    Millennials uncover large expense

    Property sector excludes a number of

    Millennials explore super investment

    Soaring dwelling prices, which in NSW alone regular above $1.2 million, have effectively barred a number of millennials from coming into the Australian property present market, in accordance to Dan Miles (pictured earlier talked about), working director and co-main financial investment officer of Innova Asset Management.

    “Unfortunately, a period of younger Australians have develop into the collateral damage to hovering property worth ranges,” Miles claimed.

    “Many youthful people who simply can not depend on parental prosperity or an inheritance have been correctly locked out of the residence present market, with out the sources to be outfitted to handle a deposit for a family or preserve a house finance mortgage.”

    Leverage and wealth inequality

    Miles identified that leverage, or using debt to purchase property, has considerably contributed to inflating family property charges, benefiting older generations whereas disadvantaging younger ones.

    “Loan-to-valuation ratios routinely stretch previous 80% whereas some governments have backed schemes allowing as much as 98% of a property’s worth to be borrowed,” he stated. “That sum of private debt can turbocharge even nominal worth beneficial properties equipped the median dwelling in Sydney is now valued at just about $1.4m.”

    Shifting emphasis to superannuation

    As the housing business continues to be unattainable for a number of, Miles really useful that superannuation may give a viable alternate for prosperity accumulation.

    “While there are strict guidelines that defend in opposition to large cash from working with leverage, most likely it’s time to rethink these procedures provided the superannuation system has been confirmed for a few years,” he talked about.

    The Innova Asset Administration chief argued that average leverage may improve returns, making superannuation an considerably eye-catching expenditure avenue.

    He contended that investing in superannuation, almost certainly with using leverage, may function a vital methodology for fiscal security, particularly as political options to the housing disaster keep elusive.

    “It will not be loads of to clear up the housing catastrophe on its possess, but it surely deserves thing more to contemplate as a period of younger Australians cope with a chronic wait round for political cures to the present-day housing catastrophe,” Miles reported.

    Get the preferred and freshest mortgage data despatched proper into your inbox. Subscribe now to our FREE day-to-day publication.

    Related Tales

    Continue to maintain up with probably the most present data and conditions

    Join our mailing report, it’s free!

  • Proudly owning Residence in a SMSF (Self-Managed Superannuation Fund)

    An individual of the elements why SMSFs are the superannuation construction of choice for a number of Australians is the flexibleness they ship to spend in property not usually provided to associates of bigger APRA regulated money, akin to sector and retail cash.
    Greater large cash are definitely vigorous in protecting instant home property nevertheless a member will not be ready to decide on a exact piece of precise property to maintain within their account. This is the place by the SMSF arrives into its personal.

    4-Jun-12-2024-01-57-35-9665-AM

    The December 2023 SMSF statistics printed by the Australian Taxation Office unveiled that 16% of the entire belongings held by SMSFs are invested in non-residential and family precise house. That signifies a whole monetary funding of simply greater than $139 billion.

    So, what are among the execs and down sides of acquiring your SMSF make investments in actual property?

    1. Control and Flexibility:

    As a trustee of your SMSF, you have got instant administration round your monetary funding conclusions. You can choose sure homes that align along with your SMSF’s funding technique and hazard tolerance.

    2. Tax Advantages:

    SMSFs have the benefit of tax concessions, which embody a decreased tax cost on rental cash (15% throughout accumulation part and % in the course of pension interval).

    Cash positive aspects tax (CGT) reductions implement in the event you maintain the home for way over 12 months.

    3. Potential Rental Revenue:

    Possessing house inside an SMSF makes it potential so that you can make rental earnings. This earnings can add to your retirement financial savings.

    4. Asset Diversification:

    House monetary dedication can help to diversify your SMSF portfolio, lessening reliance on different asset classes like shares or funds.

    5. Organization Premises Investment:

    Smaller firm homeowners or self-used individuals should purchase enterprise belongings by their SMSF. House that’s made use of wholly and fully for small enterprise wants can probably be leased to their firm on skilled phrases.

    1. Expenses and Charges:

    SMSF property transactions contain quite a few costs, along with upfront charges, licensed charges, data costs, stamp obligation, and ongoing home administration service charges.

    Be conscious of referral costs that will maybe be compensated to skilled advisers involved in recommending every particular person different’s suppliers, as these could make conflicts of curiosity.

    2. Liquidity Constraints:

    Home is illiquid, which implies it might probably’t be swiftly reworked to {dollars}. Your SMSF ought to protect ample liquidity to deal with charges, which embody mortgage repayments and residence-related expenditures.

    3. Minimal Recourse Borrowing Arrangements (LRBAs):

    If you borrow to purchase belongings in your SMSF, stringent illnesses make the most of. LRBAs allow you to amass a single asset (e.g. family or industrial home) with borrowed funds.

    Borrowing offers to the complexity and probability, so seek for steerage from a licensed fiscal adviser forward of endeavor any borrowings.

    4. Current market Volatility and Assets Values:

    House values can fluctuate owing to market illnesses. Your SMSF’s performance could maybe be impacted if residence values drop.

    Remember that property is simply actually value what anybody is able to pay again for it.

    5. Withdrawal Limits:

    Cash held in an SMSF usually are not capable of be withdrawn proper till a affliction of launch is achieved (e.g., retirement, attaining preservation age, or lengthy lasting incapacity).

    Funding for SMSF

    If you might be eager to leverage your superannuation to order belongings, the good information is there ended up alterations in 2007 to permit an SMSF to borrow cash to order an funding determination asset. Borrowing inside simply a self-managed superannuation fund is a tiny extra superior than a commonplace household property purchase. Even although the principals are comparable, making certain the suitable framework of lending beneath an SMSF is important to remain compliant with all superannuation, firms, and taxation rules.  

    The employees of brokers at Mortgage mortgage Categorical can guide you via the plan of action of arranging finance for the acquire of a home in an SMSF, utilizing the complexity out of the system and guideline you by means of to settlement. If you might be serious about shopping for a new house, it’s worthy of calling the group of house finance mortgage brokers at House mortgage Specific to debate your decisions.

    Tips for SMSF Property Loans

    Right earlier than you get began wanting for attributes, focus on along with your Economical Adviser to ensure that this arrange is fitted to you and you’ve got a technique to know what sort of residence your SMSF will achieve from. Alongside each other, it’s essential to additionally ensure that the SMSF complies with the Sole Purpose Take a take a look at, which makes sure that the expense is to ship benefits to the associates of the fund for his or her retirement, or for his or her dependants in the perform of the member’s loss of life simply earlier than retirement.
    Converse to your Mortgage Specific dealer to arrange a pre-approval previous to looking out at property to make sure you have got a clear plan of action. 

    In abstract, proudly owning belongings inside an SMSF options deal with, tax added advantages, and diversification. On the opposite hand, it is going to include bills, liquidity constraints, and risks. Often search skilled steerage forward of incomes funding decisions which have an have an effect on in your retirement nest egg.

    Standard Guidance Warning: This interplay incorporates fundamental information solely and in no approach constitutes the supply of skilled data, nor should or not it’s relied on as a substitute for cash, credit score historical past, accounting, authorized or different skilled suggestions. We haven’t taken into consideration your financial drawback, funding goals or particular wishes. Right earlier than constructing an expense or fiscal determination, a explicit individual ought to hunt out appropriate impartial skilled ideas and in addition think about whether or not this particulars is correct to their wants, targets and cases. Home finance mortgage Specific Brokers are Authorised Credit score Agent of Astute Economic Management Pty Ltd | ACN 093 587 010 (Australian Credit rating Licence 364253).

    Although all therapy has been taken in the preparation of this publication, no assure is obtainable as to the precision of the knowledge and no duty is taken by Finservice Pty Ltd (Mortgage Specific) for any faults or omissions. This publication doesn’t signify personalised economical help. It could maybe not be associated to explicit individual cases. Nothing in this publication is, or should be taken as, an give, invitation, or suggestion to speculate in, market, or retain any monetary funding in or make any deposit with any individual. You ought to hunt skilled data previous to taking any movement in relation to the issues dealt inside simply this publication. A Disclosure Statement is accessible on ask for and completely freed from demand.

    Finservice Pty Ltd (Property finance mortgage Categorical) is authorised as a firm credit score rating consultant (Company Credit score Representative Number 397386) to interact in credit score issues to do on behalf of BLSSA Pty Ltd (Australian Credit historical past Licence quantity 391237) ACN 123 600 000 | Comprehensive member of MFAA | Member of Australian Financial Issues Authority (AFCA) | Member of Choice Aggregation Products and companies.

  • ASIC flags dangerous chilly calling and on the web scams

    ASIC flags dangerous chilly contacting and on-line ripoffs | Australian Broker News

    Information

    ASIC flags dangerous chilly calling and on-line scams

    Superannuation pitfalls highlighted

    ASIC flags risky cold calling and online scams

    Corporate regulator ASIC is elevating alarms above certain chilly contacting operations that rent high-strain earnings practices and deceptive on the web commercials to thrust people into questionable superannuation switching data.

    An ASIC evaluation highlighted that these operators often obtain personal particulars from Third-bash particulars brokers or by the use of on the web click on on-bait to make unsolicited calls to patrons.

    ASIC Commissioner Alan Kirkland (pictured over) emphasised that these operations predominantly goal Australians aged 25 to 50, considerably jeopardizing their retirement financial savings.

    “Some of those chilly calling operators are pressuring folks in important retirement-saving a long time to shift their monetary financial savings when it isn’t of their finest passions, inserting them at hazard of getting fewer tremendous as a last results of inappropriate investments, prices and bills,” Kirkland said.

    Fiscal advisers related

    The analysis discovered {that a} smaller choice of monetary advisers, who benefit from referrals by these chilly calling companies, steadily suggest patrons to modify into great items that seem with important charges.

    “The smaller subset of economical advisers benefiting from this carry out threaten to undermine the recognition of the remainder of the market,” Kirkland said.

    Dangers in large-chance investments

    It was talked about that appreciable portions of superannuation price financial savings are remaining directed into superior-possibility residence managed funding determination schemes, both by the use of system great merchandise managed by APRA or by way of self-managed great funds (SMSF), with noteworthy funds going to the chilly calling corporations involved.

    ASIC’s response and potential actions

    Kirkland declared that combating these unethical strategies is a precedence for ASIC, which is ready to accumulate stringent enforcement steps to safe customers. He additionally urged financial suggestions licensees and tremendous trustees to extend their checking and reporting mechanisms to allow avert such unethical conduct.

    “Deterring chilly contacting for superannuation switching fashions is an ASIC precedence, and we are going to proceed to get motion, together with enforcement movement, to safeguard patrons from substantial strain, chilly contacting strategies that induce inappropriate superannuation-switching,” he said.

    In response, ASIC has launched a buyer recognition marketing campaign instructing people to “simply cling up” on unsolicited calls and to “simply scroll previous” suspicious on line adverts. Additionally, ASIC plans to publish a report on how trustees oversee strategies worth charges, geared toward that includes additional extra steering on defending customers from fiscal hurt.

    History and historic steps

    Due to the reality 2020, ASIC has taken crucial actions versus this model of small enterprise design, commencing with the revocation of the Australian cash professional companies (AFS) licence of Wise Remedies and along with quite a few adviser bannings, monetary steerage licensee cancellations, and even prison convictions for hawking. This ongoing laborious work underscores ASIC’s motivation to cleaning up the fiscal advisory sector and safeguarding Australian folks.

    Get the finest and freshest residence finance mortgage data shipped preferrred into your inbox. Subscribe now to our FREE day-to-day e-newsletter.

    Keep up with the newest information and actions

    Be a part of our mailing record, it’s completely free!