Tag: stock

  • Summer time housing industry starts gradual, stock improves

    Expectations are for a sluggish housing market this summer season season centered on June’s lagging total efficiency, in accordance to HouseCanary’s most recent Marketplace Pulse Report. 

    Net new listings and deal volumes are trending at multi-yr seasonal lows so considerably, the brokerage famous. Nonetheless, the opening amongst these data elements appears to have shut, indicating a a lot-wanted rise in stock. 

    New listings enhanced by 2.6% from June 2023, however the motion is nonetheless not ample to see a return to normal quantities, the report defined. Whole stock is up 25.1% from June of earlier 12 months but in addition continues to be traditionally decrease. 

    In addition to pre-current stock pressures, the brokerage noticed the median price for all solitary-family members listings in June was $460,214, an increase of three% 12 months-over-year. Inspite of want from future homebuyers, affordability struggles these sorts of as document-higher inquiring charges are preserving deal motion down. 

    The uptick in web new listings was pushed by a 6.4% maximize in new itemizing quantity final month in distinction to the same time interval in 2023, in accordance to HouseCanary. 

    “We have concluded that potential patrons are reserved and uncover themselves in a wait around-and-see drawback, whereas they’re eager to see a lower in macroeconomic pressures and an improve in cheap housing options,” Jeremy Sicklick, Co-Founder and Chief Govt Officer of HouseCanary claimed. 

    This “wait around-and-see” mentality has induced a rise in “stale” home listings that sit on the industry for way over 30 days. The median variety of instances homes are in the marketplace stands at 37 as of June, up 5.7% from one specific yr prior when the median was 35 instances.

    Fortuitously, June’s settlement quantity was up 4.7% versus the identical interval final yr in keeping with the report, signifying a weakening “lock-in affect” that has saved many future customers hesitant and sellers languishing. 

    “For that purpose, we’re cautiously optimistic that when these macroeconomic headwinds now not hinder patrons’ capabilities, we will see residence acquiring train begin to normalize and return to historic quantities,” Sicklick ongoing. “For now, as we enter July, we will rely on the present market to proceed being silent as probably purchasers are ready round for charges to fall.”

  • Why housing stock is so minimal appropriate now You have to have an understanding of the distinction involving the new and existing dwelling revenue marketplaces

    Fed holds charges common for the sixth straight time

    By Didier Malagies
    •
    02 May, 2024

    The Federal Reserve ’s Federal Open up Markets Committee (FOMC) managed its quick-expression plan rate of interest common at a array of 5.25% to 5.5% for a sixth consecutive meeting on Wednesday. “The Committee doesn’t hope will probably be acceptable to cut back the aim range until it has acquired higher self-assurance that inflation is going sustainably in the direction of 2%,“ the FOMC talked about in a assertion. “In addition, the Committee will proceed decreasing its holdings of Treasury securities and firm monetary debt and firm mortgage‑backed securities.“ All by their previous convention in March , policymakers indicated that they nonetheless envisioned just a few want quantity cuts in 2024. But with inflation remaining sticky and unemployment being beneath 4%, these expectations are beginning to be much less very seemingly. Current monetary info hasn’t equipped the Fed self-worth that inflation will carry on to drop. Sturdy inflation knowledge in the initially quarter, coupled with a sturdy labor sector , have postponed anticipations for the preliminary Fed price decrease. In April, Fed Chairman Jerome Powell, talking at the Washington Forum , created it obvious that value cuts weren’t imminent owing to the toughness of the monetary system. The economic system has preserved astonishing momentum regardless of the present-day stage of quick-expression charges. With the unemployment payment down under 4%, organizations are steadily together with employees and real wage enlargement is observable as inflation eases. Despite the indisputable fact that upward actions in inflation are noteworthy, important growth in the direction of the Fed’s 2% goal has been designed. “It’s unlikely that the upcoming plan quantity switch might be a hike,” Powell instructed journalists on Wednesday all by the FOMC’s push convention. “In purchase to hike the costs, we would wish to have to see persuasive proof that our plan stance is not sufficiently restrictive to convey inflation sustainably down to 2% round time. That is not what we’re observing at the on the spot.” Even although Powell emphasised the unlikelihood of long run stage hikes, he additionally remained obscure about the Fed’s potential curiosity value trajectory. “We didn’t see progress in the preliminary quarter. It seems that it’s going to simply take prolonged for us to arrive at that place of confidence,” Powell stated. “I don’t know the way intensive it can take. … My non-public forecast is that we are going to get began to see progress on inflation this 12 months. I by no means know that will probably be sufficient to cut back prices we’ll have to let the information information us on that.” In a new growth, the Fed declared an easing of its quantitative tightening protection. Starting up in June, the price-placing physique will decreased the roll-off quantity of its Treasury securities from $60 billion to $25 billion for every thirty day interval. This implies that though the Fed is not going to begin promoting Treasurys in June, it can permit for fewer of them to skilled. It is not going to change its roll-off quantity for home loan-backed securities (MBS), which is able to proceed to be at $35 billion per thirty day interval, in accordance to Xander Snyder, senior enterprise critical property economist at Very first American. “The FOMC didn’t change the ongoing passive roll-off of its MBS holdings however did discover that any prepayments exterior of the persevering with $35 billion cap can be reinvested in Treasuries,” Mike Fratantoni, senior vp and chief economist for the Property finance mortgage Bankers Affiliation, acknowledged in a press release. “We assume residence finance mortgage costs to fall afterwards this 12 months, however not as far or as shortly as we beforehand had predicted.” In addition, Powell reiterated the Fed’s dedication to carrying ahead the Basel III endgame polices in a means that is reliable to Basel and additionally comparable to what the jurisdictions in different nations are undertaking. Due to the truth the March FOMC assembly, Freddie Mac’s common 30-12 months fastened residence mortgage value has elevated from 6.74% to 7.17%. Right earlier than the upcoming FOMC convention on June 12, two extra inflation readings are anticipated. “While it’s a chance, I don’t think about that we’ll see considerably rework in mortgage premiums following this Fed meeting, due to the truth the Fed has been prepared to allow the knowledge direct at this stage in the cycle,” Real property agent.com chief economist Danielle Hale defined in a assertion. “In get to see property finance mortgage costs drop much more noticeably, the Fed will want to see much more proof that inflation is slowing.”  For homebuyers and sellers, this means that housing affordability will proceed to be a number one consideration, possibly driving residence buys in cost-effective marketplaces, predominantly in the Midwest and South, in accordance to Hale.

  • Need to grow your business enterprise with cash, inventory, new making

    Fed holds premiums fixed for the sixth straight time

    By Didier Malagies
    •
    02 May maybe, 2024

    The Federal Reserve ’s Federal Open up Marketplaces Committee (FOMC) managed its small-phrase plan fascination cost steady at a array of 5.25% to 5.5% for a sixth consecutive assembly on Wednesday. “The Committee doesn’t anticipate will probably be preferrred to lower the focus on selection till lastly it has acquired elevated self-confidence that inflation is relocating sustainably towards 2%,“ the FOMC mentioned in a assertion. “In addition, the Committee will go on chopping down its holdings of Treasury securities and company private debt and company mortgage‑backed securities.“ Through their earlier meeting in March , policymakers indicated that they however envisioned just a few rate of interest cuts in 2024. But with inflation remaining sticky and unemployment retaining beneath 4%, these anticipations have gotten a lot much less almost certainly. Modern monetary data hasn’t provided the Fed confidence that inflation will go on to drop. Robust inflation data within the initially quarter, coupled with a strong labor business , have postponed anticipations for the first Fed value slice. In April, Fed Chairman Jerome Powell, talking on the Washington Discussion board , made it clear that cost cuts weren’t imminent due to the power of the monetary system. The financial system has preserved shocking momentum regardless of the present stage of brief-phrase prices. With the unemployment payment beneath 4%, suppliers are steadily incorporating staff and precise wage growth is observable as inflation eases. Whilst upward actions in inflation are noteworthy, sizeable progress in the direction of the Fed’s 2% goal has been designed. “It’s unlikely that the next plan cost switch might be a hike,” Powell instructed journalists on Wednesday throughout the FOMC’s press assembly. “In get to hike the premiums, we would wish to see persuasive proof that our protection stance isn’t sufficiently restrictive to carry inflation sustainably down to 2% over time. That’s not what we’re seeing on the minute.” Though Powell emphasised the unlikelihood of upcoming cost hikes, he additionally remained imprecise in regards to the Fed’s potential curiosity stage trajectory. “We didn’t see improvement within the initially quarter. It seems that it’ll simply take longer for us to attain that time of confidence,” Powell mentioned. “I actually have no idea how lengthy it should contemplate. … My explicit forecast is that we are going to start to see improvement on inflation this 12 months. I don’t know that will probably be adequate to scale back prices we may have to allow the data lead us on that.” In a new enchancment, the Fed launched an easing of its quantitative tightening coverage. Commencing in June, the charge-location human physique will decreased the roll-off cost of its Treasury securities from $60 billion to $25 billion per thirty day interval. This implies that while the Fed is not going to begin off selling Treasurys in June, it should allow fewer of them to skilled. It is not going to alter its roll-off quantity for home loan-backed securities (MBS), which can proceed to be at $35 billion for every thirty day interval, in accordance to Xander Snyder, senior skilled true property economist at First American. “The FOMC didn’t modify the continuing passive roll-off of its MBS holdings however did notice that any prepayments over and above the persevering with $35 billion cap could be reinvested in Treasuries,” Mike Fratantoni, senior vp and major economist for the Mortgage mortgage Bankers Association, defined in a assertion. “We anticipate home mortgage charges to fall in a while this yr, however not as a lot or as fast as we previously skilled predicted.” In addition, Powell reiterated the Fed’s motivation to carrying ahead the Basel III endgame polices in a approach that’s devoted to Basel and in addition equal to what the jurisdictions in different nations are performing. Due to the very fact the March FOMC meeting, Freddie Mac’s common 30-year fixed house mortgage quantity has larger from 6.74% to 7.17%. Ahead of the long run FOMC convention on June 12, two additional inflation readings are envisioned. “While it’s a danger, I actually don’t contemplate that we’ll see a lot modify in house finance mortgage costs adhering to this Fed meeting, given that the Fed has been inclined to enable the knowledge direct at this section within the cycle,” Realtor.com major economist Danielle Hale defined in a press release. “In purchase to see mortgage mortgage prices drop far more noticeably, the Fed will need to see additional proof that inflation is slowing.”  For homebuyers and sellers, this means that housing affordability will proceed being a significant consideration, doubtlessly driving house purchases in economical marketplaces, predominantly within the Midwest and South, in accordance to Hale.

  • Fed’s fascination charge hike to make a lot less competitiveness in the housing market More stock in the market could catch the attention of terrified-off purchasers

    As the Federal Reserve launched however one other 75 basis place fascination value hike Wednesday, mortgage officers and lending executives — now properly knowledgeable of the info — had been searching forward, questioning irrespective of whether or not mortgage mortgage charges will spike or dip in the aftermath.

    Even economists are divided on what’s to arrive: Some think about expenses have already peaked many others say they’ll climb till or till the nation’s monetary system formally enters a recession. 

    But they do agree on only one factor: Increased want charges will quell housing want, which can let stock to rebound and, in the end, spur the return of unwilling patrons.

    “For clients, this (enhance in curiosity expenses) signifies that besides if the monetary system reveals added signs of tipping into a recession, house finance mortgage charges are attainable to pattern higher, which will probably be a drag on housing demand,” reported Danielle Hale, chief economist at Realtor.com

    Mortgage charges main up to June’s Fed fee hike surpassed the 6% degree as larger-than-predicted inflation information induced volatility in the market, which led to turbulence in mortgage mortgage charges. Due to the truth the Fed’s June curiosity quantity enhance of 75 bps, property finance mortgage charges in present weeks crept nearer to 5.5%. 

    Lawrence Yun, essential economist for the National Affiliation of Realtors, doesn’t assume rising curiosity premiums by 75 bps will have an effect on house mortgage expenses. The extensive-term bond sector, off which house mortgage costs generally are centered, “has sometimes priced-in all long run actions by the Fed, and should maybe have presently peaked with the 10-yr Treasury taking pictures up to 3.5% in mid-June,” Yun included.

    “It is attainable that the 30-calendar 12 months preset mortgage mortgage charge could properly calm down at 5.5% to 6% for the the rest of the calendar 12 months,” Yun defined. “Still, house finance mortgage prices are considerably bigger now as opposed to a particular person yr in the past, which is why house product sales have been slipping.”

    An govt with the Mortgage Bankers Association (MBA) additionally believes mortgage mortgage premiums have maybe peaked and could keep fixed amongst 5% and 5.5% by the leisure of 2022. An enchancment from the 6% mark, nonetheless it’s nonetheless appreciably bigger than early 2021’s 3% diploma. 

    “There is a tug-of-war in sector anticipations, involving the persistently larger inflation numbers and ensuing quick Fed hikes, and the elevating probability of a sharp slowdown and attainable financial downturn,” reported Mike Fratantoni, senior vice chairman and chief economist for the MBA. 

    If property finance mortgage premiums peak, Fratantoni acknowledged, “potential patrons who skilled been apprehensive off by the value spike, could probably come throughout their means again to the housing market.”

    There have been being very clear penalties from the earlier spike. Sales of newly designed residences fell a lot greater than 8% in June from the prior month and have been being 17% diminished than June 2021, in accordance to the U.S. Census and the Department of Housing and Urban Progress. Signed contracts to get hold of present properties declined a broader-than-anticipated 8.6% in June from May maybe and dropped 20% from June 2021, the National Affiliation of Realtors stated.

    Residence charges additionally grew, although at a slower fee. The nationwide residence-cost development slowed down in May maybe, posting a 19.7% yearly get hold of compared with a 20.4% elevate in April and a 20.6% leap in March, in accordance to the S&P CoreLogic Scenario-Shiller nationwide house value index.

    Yun sees home revenue coming once more if house finance mortgage premiums stabilize shut to the current charges and believes house revenue will probably be depending on jobs and shopper self worth. 

    “Job creations have been ongoing to day. Consequently, dwelling product sales could earlier than lengthy stabilize in simply a a number of months after which steadily change upwards from early up coming 12 months,” Yun defined.

    Hale, from Real property agent.com, acknowledged the declining demand and elevated expenditures belie some shiny spots for home patrons. 

    “While the choices are extra high-priced and a lot extra highly-priced to finance, the increasing quantity (of property product sales from a 12 months in the previous) will help the true property market rebalance, supplying seemingly purchasers a considerably-needed refresh,” Hale stated. 

    Any enhance in availability in stock deserts could be ample to another time carry in potential patrons to the market, in accordance to Marty Inexperienced, principal at home mortgage regulation agency Polunsky Beitel Eco-friendly. 

    “The downside is regardless of whether or not the slowdown is a finish consequence of most people merely pausing a order selection once they see wherever curiosity charges and family value ranges settle, or regardless of whether or not they’re proudly owning to maintain off a purchase determination indefinitely since of affordability issues,” Inexperienced stated. 

    Some LOs think about the improve in curiosity premiums was already baked into house finance mortgage prices, so they don’t assume extraordinary volatility like final month. 

    “There was no massive stress (like June),” defined Christian Dicker, senior mortgage officer at Motto House mortgage. “I believe it’s presently priced in the market.”

    Dicker immediate a slowdown in the housing market place is excellent, to some extent, due to the truth it signifies a lot less competitiveness for the client — a welcome alter instantly after months of increasingly excessive bidding wars, for the length of which every thing significantly less than an all-dollars give you got here with inherent uncertainty.

    “I’ve had way more presents acknowledged in the closing two weeks than the final two months. They (homebuyers) are seemingly out looking for at 4 properties and all of them are on the market. They’re making 1 or two gives and they’re discovering acknowledged,” Dicker acknowledged.

    Affordability continues to be a impediment, however some potential patrons are “resigning them selves to bigger charges, recognizing that they’re seemingly to have to shell out extra if they need the belongings,” claimed Coley Carden, vice chairman of residential lending at Winchester Co-Operative Bank.

    “With want charges escalating and family value appreciation slowing down, want for properties will stabilize,” Carden acknowledged. 

    Although he doesn’t see 20 gives on nearly each property as he did in the course of the pandemic, Carden nonetheless receives inquiries for homes, and even second homes. 


    “I consider what could curtail homebuyer demand is way extra of a financial downturn — particularly if folks get minimized hours and start to get laid off,” he talked about. 

  • The standoff between homebuyers and sellers With minimal inventory, pricing is important to achievement

    When I got here up with the “savagely unhealthy housing market” label in February of this yr, it was depending on the premise that the housing inflation story that we now have skilled to provide with contemplating that 2020 was a historic operate. It facilitated a extraordinarily unhealthy housing sector in 2020-2021 that grew to become savage in 2022. The main result in was a absence of options for American homebuyers.

    Stock, which has been slipping for yrs, broke to all-time lows in 2020. We didn’t have a seasonal press in inventory in 2020, and issues worsened in 2021. To high all of it off, we began 2022 at all-time lows, forcing bidding movement nearly in every single place till mortgage charges rose. And we’re not conversing about your grandfather’s dwelling finance mortgage costs climbing we went from 2.5% to over 7% in a fairly shorter time period of time.

    Of course, this has introduced again once more some stock, as need weak level often leads to inventory by accumulation. Having mentioned that, as we will see beneath, we’re not once more to the historic norms of 2-2.5 million energetic listings, however at simply 1.28 million right now. 

    This doesn’t point out homebuyers actually shouldn’t have slightly one thing of an edge now: As stock has better and purchasing for energy has pale, the shoppers who’re available are working with so much a lot much less stage of competitors because the bidding wars are ending.

    1 of the required variables I added to my carry out by means of 2020-2024 was to place an efficient price-progress design for this time period to know when the housing sector would get into value inflation difficulties. My mannequin was 23% whole cumulative worth progress from 2020-2024 — if we solely grew at 23% for 5 many years, we’d be okay with wherever wage progress was doubtless.

    Well, that obtained destroyed in solely two a number of years.

    In {the summertime} of 2020, I talked about what might remodel the housing market and it was based mostly totally on the premise that the 10-year produce important to get above 1.94%, which might essentially imply property finance mortgage charges would climb above 4%. It wasn’t a part of my forecast in 2020 or 2021. Having mentioned that, for 2022, part of the forecast was that if world-wide bond yields rose, primarily in Germany and Japan, we might break up the 1.94%.

    Of examine course, an ideal deal way more drama occurred after March of this calendar yr and the 10-year produce acquired to 4%, one factor I used to be not trying to find. Even so, with fee progress and home mortgage costs skyrocketing, the strike to affordability is historic.

    Affordability points, irrespective of of inventory data, and it isn’t a more healthy issue when even the month to month present of stock is under 4 months. I talk about about 4 months of provide an ideal deal given that I feel a nicely balanced market is 4 months, not 6 months. It’s fairly distinctive to get six months of present in The usa for the present property earnings market provided that 1996.

    The solely time this came about was 2006-2011 — the housing bust many years. That had a great deal of pressured providing right into a weaker need time period as credit score obtained tighter in partnership to the necessity curve. This implies the housing growth interval of 2002-2005 had predominant credit score rating tightening, which gained’t happen this time all-around when the subsequent recession hits.

    At this time, we’re at 3.2 months provide, which traditionally is not so much, however that’s up from the latest lows and we’re coping with main affordability difficulties.

    I speak about 2019 stock ranges so much as a result of in 2019 genuine dwelling worth ranges briefly went damaging, exhibiting that you simply don’t want to have to have 6 months moreover of stock to have pricing nice down. In actuality, at a 2019 convention, I used to be so joyful about this that I labeled the chart down under as Excellent Information! Not positive if the viewers agreed with my think about.

    Home finance mortgage premiums went up to 5% in 2018, cooling down the housing trade however nothing in any respect as nicely dramatic for the current residence product sales sector. Obtain software program information was solely detrimental 3 weeks out of the yr. Household costs ebb and move, pricing was working within the feeling that sellers achieved homebuyers to a level.

    Now quick forward to 2022. We have witnessed a considerable fee and fee inflation event with pricing nonetheless climbing and the best mortgage mortgage worth maximize in a single calendar yr in new modern-day-working day historic previous. Unlike 2018-2019 when purchase software program data didn’t budge considerably, we now have skilled a sample of very nicely over 20% year-about-12 months declines on the four-week transferring frequent on this index.

    In the ultimate a couple of months of the yr we will hope some months to clearly present 12 months-above-yr hostile prints of 35%-45% as comps are discovering harder. This is a critical strike to demand. 

    In 2018-2019 the affordability metrics weren’t as awful as individuals imagined. This isn’t the circumstance any longer. This is why I used to be so vocal about price ticket escalation organising in direction of the shut of 2020 and into this 12 months. Even my 2022 price ticket forecast displays a large deceleration of promoting worth development from 20% to as small as 5.2%. My forecast was method too minimal as total stock data early within the yr was method too decrease and costs didn’t go larger until April.

    Now with dwelling mortgage prices above 7% and pricing not staying hostile this calendar yr, homebuyers — at minimal all those that can handle to get hold of a house — have a bonus in sure marketplaces the place inventory is at 2019 levels just because the provide of properties of 2019 to me is a useful market. This is how you need to actually search at housing now.

    When mortgage mortgage costs had been under 4%, the market pricing electrical energy was a lot too highly effective with stock at all-time lows. This is not the situation any extra. Even although total inventory is round all-time lows and we’re heading to begin off 2023 with historically low inventory, it doesn’t signify that pricing doesn’t make a distinction.

    From Altos Investigate:

    So my large takeaway from the savagely unhealthy housing trade of 2022 is that 4%-5% home mortgage prices didn’t do the issues I imagined they might and I imagine that this is why my worth growth forecast of 5.2%-6.7% for 2022 is doubtless to be flawed and far too very low.

    Nonetheless, 5%-6% dwelling mortgage costs did modify the market and now 6%-7% home mortgage premiums are reworking habits in order that we see new itemizing data declining even way more as sellers are contacting it quits on their technique to file. Homebuyers who can qualify for a dwelling now are in a significantly improved place than the sooner couple of a number of years, however hey, you’ve to provide with a big strike to the entire fee of your dwelling. For some homebuyers, it’s not a big provide, however for different individuals, it stings.

    From Real property agent.com:

    Homes which are priced applicable, primarily in elements beneath 2019 inventory ranges, are selling rapidly, and these homes that aren’t priced appropriate to {the marketplace} are utilizing prolonged to present. Sixteen occasions to market is proceed to far too low for my fashion this displays how a lot of the state isn’t again to 2019 levels.

    In a couple of weeks, stock will begin to be affected by seasonality the priority is, will individuals properties which are taking for an extended interval to promote name it quits for the yr? Stock traditionally falls within the fall in winter and rises within the
    spring and summertime. However, with weak spot in want, stock can accumulate.

    The previous time total inventory grew was in 2014 as a result of we had weak want. Acquire software program data was down on typical 20% 12 months over yr, and altering to the inhabitants was probably the most reasonably priced stage within the index ever. In 2014 we proceed to had the seasonal dive in inventory within the slide and wintertime, so time will notify if that would be the case another time with the rise in inventory this yr.

    My premise beforehand within the yr of total inventory data having again once more to 2019 phases in 2023 is hitting a snag with the lower in new listings, in order that is something we actually are not looking for to see for the spring of 2023. To have a balanced housing market, we require full of life listings to rise yearly, which they generally do 2020 was an anomaly. We shall see what the long run few months convey for housing nonetheless, as we close to the publications for 2022, we will concur it was a savagely unhealthy housing market.


    What we don’t need to be in 2023 is trapped with low entire stock — sellers not wanting to provide, homebuyers and sellers battling greater than worth, and sellers getting cussed about it. With extra inventory, sellers have to be a lot much less stingy this is why I’m a fanatic of acquiring full stock data again to 2019 ranges.

  • The stock problem | Evergreen Dwelling Financial loans

    &#13
    &#13

    The query lingering in everybody’s ideas as they ponder shopping for or providing a house is: Why are obtainable homes so scarce? When you could nicely assume it smart to carry out till lastly far more properties come to market, there are highly effective causes to behave now, specifically with Evergreen’s CashUp Suite of Items at your disposal. Let’s delve into the very long-time interval and shorter-time interval elements contributing to this housing shortage.

    A continuing underbuilding disaster

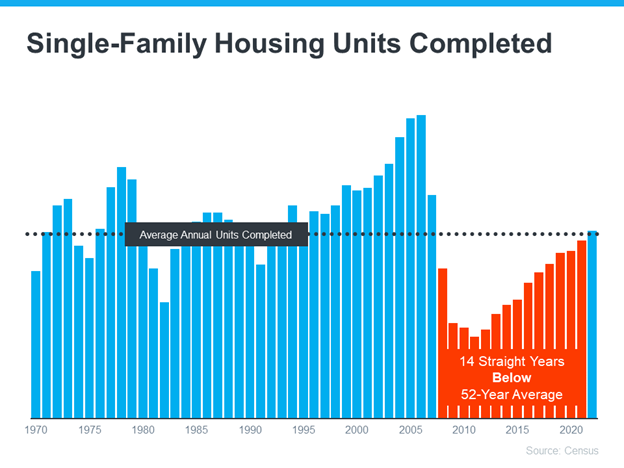
    Lower stock is not a fleeting problem it has its roots in a long time of underbuilding. Acquire a look on the historic information on new one-loved ones family design over the earlier a lot of a very long time:

    A 14-12 months streak of slipping in need of historic strange growth charges has resulted in a persistent deficit in available properties. Although builders at the moment are constructing at a cost that fulfills the historic strange, this stock gap shouldn’t be a problem that may be fastened immediately.

    The property finance mortgage cost conundrum

    A special contributing part to the prevailing stock issue is what’s acknowledged because the mortgage cost lock-in consequence. A number of homeowners wait to promote just because they concern larger property finance mortgage charges on their upcoming dwelling. This apprehension is influencing alternative stock, as women and men are deciding on to remain put alternatively than hazard elevated costs.

    Nevertheless, it’s actually necessary to stability this fiscal factor to think about along with your particular person calls for for making a shift.

    How Evergreen’s CashUp Suite of Products could make a change

    In marketplaces like these, Evergreen’s CashUp Suite of Goods can current a considerable edge by presenting adaptable financing alternatives that may make your supply far more stunning to sellers. With CashUp, you’ll be able to behave instantly and decisively, offering you the sting in a aggressive market.

    Media-induced panic isn’t any shut buddy to housing stock

    Fearmongering by media shops, speculating on housing crashes or steep declines in dwelling worth ranges, is additional extra lowering the willingness of attainable sellers to enter the sector. As Jason Lewris, Co-Founder and Main Details Officer at Parcl, observes:

    “Uncertainty pushed by misleading info and information is skewing precise property conclusions, creating people hesitant the place by they should haven’t be.”

    What this normally means for you

    For customers: The scarcity of homes compels you to be adaptable along with your options, which incorporates location and type of housing. A talented genuine property agent can handbook you by way of the tactic, even suggesting strategies to broaden your analysis if crucial. With Evergreen’s CashUp Suite of Goods, you could have extra monetary devices that would concept the scales in your favor.

    For sellers: Lower stock really will work in your favor as it will make your belongings additional recognizable. Now is an distinctive time to hunt the recommendation of a real property agent who can help you get fringe of this one in all a sort market circumstance although serving to you in getting your following dream residence.

    Conclusion

    Low stock is an advanced issue motivated by a myriad of things. If you’re desirous about constructing a go, is not going to wait to seek for certified suggestions out of your reliable Evergreen mortgage supplier. Connect with us now to review extra about stock in your location.

    Resource: Trying to maintain Existing Matters

    &#13

  • Using Vested Stock & RSU For Mortgage Affordability Purposes | Mortgage Market Blog

    31-01-2023

    Fox Davidson advise purchasers wishing to take out a mortgage on UK property. Many of our purchasers work at funding banks and huge US headquartered tech companies, with a few of them being awarded inventory and deferred compensation which is able to vest frequently.

    We frequently obtain questions concerning the feasibility of utilizing inventory or RSU earnings for mortgage functions, lots of which we have now addressed in our information beneath.


    What are inventory choices?

    Stock choices are a kind of fairness compensation that provides staff the best to buy a sure variety of shares of the corporate’s inventory at a specified value (generally known as the “train value”) inside a sure time frame. The goal of inventory choices is to align the pursuits of staff with these of the corporate’s shareholders, by giving staff a stake within the firm’s success.

    Vesting is the method by which an worker earns the best to train their inventory choices. Vesting sometimes happens over a time frame (akin to 4 years) or upon the achievement of sure efficiency milestones (akin to reaching a sure gross sales goal). When a inventory possibility vests, it implies that the worker has earned the best to train the choice and buy the shares of inventory on the train value.

    For instance, if an worker is granted 100 inventory choices that vest over 4 years, they might obtain 25 choices per yr over the four-year interval. Once the choices have vested, the worker should buy the shares on the train value any time earlier than the expiration of the choice.

    What are Restricted Stock Units (RSU)?

    Restricted inventory models (RSUs) are a type of fairness compensation issued by corporations to staff as a type of non-cash compensation. RSUs are like inventory choices, however not like inventory choices, staff do not need to pay something to accumulate the shares and the shares usually are not instantly vested. Instead, the shares are restricted and vest over time, or upon the achievement of sure efficiency milestones.

    It is widespread for publicly traded corporations within the UK and different international locations to supply RSUs as a type of compensation to their staff.

    Can I take advantage of vested inventory as earnings for mortgage functions?

    Some mortgage lenders will use vesting inventory of their affordability calculations. Lenders will take a look at the historical past of compensation awarded and a borrower’s vesting schedule, each traditionally and projected. Some mortgage lenders are prepared to make use of 100% of vesting inventory for affordability functions.

    Can I take advantage of RSU earnings for mortgage functions?

    It is feasible to make use of RSU earnings for mortgage functions. Mortgage lenders prefer to see a historical past of RSU earnings over a few years to get snug with utilizing it of their affordability calculations.

    Can I take advantage of bonuses for mortgage functions?

    Mortgage lenders will use as much as 100% of bonus earnings when calculating how a lot they’ll lend. The quantity of a bonus a mortgage lender will use will depend on the frequency (month-to-month/quarterly/yearly) of the bonuses, and for the way lengthy they’ve been paid.

    Can I take advantage of a bonus paid in {dollars} or one other international forex for UK mortgage functions?

    Some mortgage lenders will settle for bonuses or fee paid in a international forex (non-sterling). The compensation can be transformed into sterling and handled within the common method for affordability functions.

    The have an effect on of the financial outlook on inventory choices

    There are a number of components that can have an effect on a mortgage lender’s resolution on how a lot bonus or vested inventory they’ll use. A lender will take a look at the historical past of an candidates bonuses and will resolve to common the earnings over a number of years. They may additionally resolve to make use of a % of bonus – this may vary from 50% to 100% of bonus/vested inventory.

    Another main issue for mortgage lenders is the macro surroundings, and that’s one thing we pay particular consideration to when placing collectively a case for lending. During the COVID disaster of 2020, many lenders merely stopped utilizing any type of earnings over and above an staff fundamental wage. Their reasoning was that financial uncertainty meant that it was possible that bonus earnings for that yr and can be affected, and subsequently posed an excessive amount of danger to place any reliance on earnings from vesting inventory and bonuses/fee.

    Fast ahead to 2023 and while we have now left behind COVID, we do face different international uncertainties. The Russia-Ukraine battle has meant a discount in funding banking enterprise and measures from central banks to fight inflation have all had an affect on the economic system.

    Viswas Raghavan, A CEO at JP Morgan, acknowledged that it has been ‘a fairly anaemic yr’ and that bonuses would cut back consequently. Citigroup Inc, Bank of America Corp, and Goldman Sachs additionally warned their funding bankers might even see an earnings discount of as much as 40%.

    A mortgage dealer for RSU earnings & inventory choices

    At Fox Davidson, we have now a complete community of lending establishments that we work with to offer our purchasers with probably the most beneficial mortgage phrases. One of the methods we will safe extra beneficiant mortgages for our purchasers is by utilising the earnings from vested inventory and allotted RSU.

    We may also take a look at a shopper’s wider belongings, as a few of our funders will take consolation if we will show a really robust internet belongings place. If we will show a portfolio of belongings that are liquid, then we give ourselves some room for flexibility from lots of our non-public financial institution funders.

    To safe a mortgage utilising vested inventory earnings, purchasers might want to present the lender with a spread of documentation, together with compensation statements, vesting schedules, financial institution statements and proof of their share portfolio.

    To talk about mortgages utilizing numerous types of compensation, please do name us on 01179 89 79 50 or electronic mail enquiry@foxdavidson.co.uk