Tag: states

  • Bridging finance market place set for progress, states BDLA & Interpath – Mortgage Finance Gazette

    Bridging finance brokers and lenders rely on the present market to enhance however warned from the growing time lag in financial institution mortgage completions, Interpath and the Bridging & Improvement Creditors Association (BDLA) Uk reveals.

    Bridging-finance-bridge-businessman-gap-620x330.jpg

    The newest Interpath & BDLA British isles survey uncovered that the rising time lag in ending loans was inflicting delays in executing transactions and respondents lifted fears over intense ranges of competitors for loans.

    Meanwhile, 62% of respondents anticipated once-a-year origination volumes within the business to maximise. That was supported by a powerful expectation, in accordance to 92%, that institutional funding would carry on being on the market at present-day ranges or enhance over the long run yr.

    Respondents ended up additionally in settlement that typical common curiosity charges on loans would fall – a sentiment shared by 62% of respondents and considered an important present market driver.

    Nevertheless, there was some warning as 51% described that the common occasions to finishing a mortgage was lengthening, reflecting ideas {that a} gradual approved course of is a important drawback that’s leading to delays.

    The survey additionally noticed that the business remained bearish on the should have for dwelling recoveries with 92% anticipating the quantity of foreclosures to proceed being the identical or improve.

    In different locations, outcomes confirmed that 51% cited the ‘common common month-to-month want price’ for loans from the earlier 12 months to be 1.00%-1.25%, with 8% suggesting loans priced earlier talked about 1.25%.

    With regards to peculiar mortgage-to-worth (LTV) 65% to 70% was the preferred bracket, adopted by 60% to 65%, whereas widespread monetary mortgage dimension has elevated from the earlier sentiment of £300k to £400k, to additional than £600k.

    When taking into account the common financial institution mortgage expression, 57% chosen 9 to 12 months, which is common with the small-term character of the present market.

    The examine additionally discovered that refurbishment was essentially the most well-known rationale for debtors to obtain a bridging monetary mortgage and downsizing the minimal.

    Study contributors had been questioned to determine the foremost troubles experiencing their enterprise in extra of the upcoming 12 months.

    Amplified competitors was the most common impediment chosen, ranked by 60% of respondents, adopted by a lower in residence earnings volumes and time to promote. Declining dwelling values was the third hottest drawback feared by these individuals within the business.

    Interpath controlling director and head of financial services deal advisory Nick Parkhouse gives: “The future 12 to 18 months will probably be pivotal for the bridging finance market. The enterprise expects development, much more institutional funding, and a drop in curiosity costs, however there are nonetheless some critical drags on train, not least within the delays prompted by approved processes on the time to execute a transaction.”

    “While credit score historical past wonderful will elevate, the advantages reveal us that there’s nonetheless concern over defaults with fears over foreclosures remaining in entrance of mind.”

    “One level is specified – there will probably be additional competitiveness, which has taken round as one of many best considerations within the market. As want for financing for arrears builds, propelled by a drop in property gross sales amount and maximize in time to supply, we’ll see extra money buying its means into an beforehand busy and fragmented sector and spark an intense struggle for loans, together with new entrants. The rest of 2024 is established to be a energetic interval for bridging finance.”

    BDLA chief authorities officer Vic Jannels says: “Latest information from the BDLA reveals that bridging monetary mortgage books strike a historical past excessive of £8.1bn in Q1 2024 and this examine confirms the quantity of optimism for ongoing development within the present market.”

    “There will probably be worries, after all, however by defending substantial necessities of transparency, professionalism and shopper emphasis, we will probably be successfully positioned to satisfy the escalating demand from prospects from each buyers and institutional funders.”

  • Lessen costs will not travel increased origination amount, Fannie states

    Fannie Mae economists have diminished their projections for the place fees for the 30-12 months home mortgage will shut this 12 months, bringing their outlook once more beneath the 7% mark.

    Nevertheless, that will not translate to amplified originations, as additionally they slice their amount forecast for equally 2024 and 2025 from what they predicted earlier thirty day interval.

    Fannie’s June forecast can also be predicated on weaker gross home merchandise improvement than beforehand anticipated, as very properly as solely a solitary December shorter-term fee reduce from the Federal Open Sector Committee previous expectations have been for 2 reductions.

    “The financial system seems to be slowing, and present readings current hope that inflation is cooling quickly after progress on that entrance stalled within the 1st quarter — a pattern that will possible require to be sustained for the Fed to really feel cozy chopping premiums,” defined Doug Duncan, Fannie Mae’s fundamental economist, in a press launch.

    “Sad to say, we’re nonetheless not forecasting a ramp-up in housing exercise, which will demand some mixture of continued residence earnings development, a extra slowing of family price ticket appreciation, or a drop in residence finance mortgage fees to supply affordability inside fluctuate of plenty of ready round initially-time and shift-up homebuyers.”

    For the entire yr, Fannie Mae expects the 30-yr FRM to typical 6.8%, which embrace falling to six.8% for the third quarter and 6.7% within the fourth quarter. In May’s forecast, Duncan forecast costs averaging 7% every for all of 2024 and only for the fourth quarter, following reaching 7.1% in equally the 2nd and third quarters.

    June’s outlook has the 30-year dropping to six.3% by the fourth quarter of subsequent yr, with an typical of 6.5% for all of 2025. This compares with the May outlook’s prediction of 6.6% within the fourth quarter and 6.7% for the whole 12 months.

    “Fascination premiums proceed to be risky, considerably provided adjustments to Fed protection expectations, which offers hazard to our outlook,” the web site article accompanying the forecast claimed. “Next the completion of our begin out-of-the-thirty day interval curiosity cost forecast and as of this writing, 10-calendar yr Treasury costs have lessened near 25 basis elements adhering to the May properly [Consumer Price Index] launch, major to some draw again risk to our present baseline property finance mortgage price forecast.”

    While the reduce price outlook led Fannie Mae to raise its forecast from remaining thirty day interval for refinance originations for the following two years, that was outweighed by its slice in spend money on motion.

    It dropped its general home earnings forecast to 4.82 million from 4.89 million.

    The June outlook predicts the house mortgage discipline will generate $1.714 trillion in mortgages this yr, up from an estimate of $1.47 trillion for 2023. This in contrast with May’s forecast of $1.73 trillion.

    It telephone requires $372 billion of refinance exercise, up from the prediction in May probably of $368 billion. On the order facet, the June forecast of $1.342 trillion, compared with May’s $1.363 trillion. In 2023, the sector did $1.222 trillion of order originations.

    Through 2025, Fannie Mae seems to be like for the mortgage mortgage sector to make $2.068 trillion, with $1.525 trillion in spend money on and refinancings producing up $544 billion.

    That compares with the May probably forecast for $2.076 trillion, constructed up of $1.537 trillion in acquire amount and $539 billion of refis.

    Freddie Mac additionally issued its most up-to-date monetary forecast in distinction to different prognosticators, it does not disclose specific quantity figures. Its May maybe forecast termed for premiums to maintain on being elevated by way of the comfort of the yr.

    “As we anticipate a moderation in family earnings, substantial value ranges, and a flat {dollars} share of buys, we hope buy origination to be slightly bit increased in 2024 than in 2023,” the June 20 web page write-up from the Freddie Mac economics group, headed by Chief Economist Sam Khater talked about. “With residence mortgage costs above 7%, refinance motion is predicted to be nominal.”

    On that very same day, it launched the weekly Key House mortgage Marketplace Study which identified the 30-yr FRM averaged 6.87%, the third consecutive week it was beneath 7% and essentially the most inexpensive degree as a result of April 11.

    “Even so, if curiosity charges drop down under 6.5%, refinance train might see some uptick, as hundreds and hundreds of debtors nonetheless have costs beforehand talked about 6.5%,” Freddie Mac reported. “Yet, given persistent inflation, reaching fees down under 6.5% is hard.”

  • Fed’s Barkin states want clarity on inflation just before slicing

    Federal Reserve Financial establishment of Richmond President Thomas Barkin mentioned he wants additional clarity on the route of inflation just before decreasing need premiums. 

    “My personal try is let’s get much more conviction proper before shifting,” Barkin claimed to reporters Thursday following an event in Richmond, reiterating that he necessities sustained and broadening growth towards the Fed’s 2% intention before altering borrowing prices lower. 

    Barkin, who’s a voting member of the Federal Open Market place Committee this yr, talked about protection is at current completely positioned, incorporating the central lender has the firepower very important to tame inflation. 

    When questioned if the Fed might do one quantity slash and maintain at that diploma, Barkin acknowledged it relies upon on the financial system. If current issues maintain, he reported it couldn’t be the best time to provide course on timing about subsequent plan adjustments. 

    “There are moments the place by we’ll want to provide ahead steering and have offered ahead steering,” he instructed reporters. “This doesn’t sense like one specific of all these durations to me. It wouldn’t expertise like a forward steering time.”

    Past week, policymakers voted to take care of fascination charges regular in a assortment of 5.25% to five.5%, the very best in rather more than two a very long time. Policymakers penciled in an individual fascination quantity reduce for 2024 and 4 for 2025, based on the median projection. 

    “At this minute it looks like if you happen to made a slash, you constructed a slice, after which allow us to see precisely the place the information usually takes you,” Barkin acknowledged.

  • Freddie Mac next lien software should not go in advance but, MBA states

    The proposal for Freddie Mac to amass specific closed-end next-lien residence loans in all probability matches with its mission however the proposal as now talked about has a number of holes and its good points should be completely analyzed, a House mortgage Bankers Association letter stated.

    The Federal Housing Finance Company comment time period for the strategy ends now. It was designed centered on responses on the right way to let house owners to extract the fairness from their qualities with out acquiring to do a income-out refinance, Sonu Mittal, senior vp, one-loved ones acquisitions claimed in a dialogue with a Countrywide Home mortgage Information reporter throughout the MBA’s Secondary and Cash Markets Conference this week in New York.

    This services or products would supply liquidity with standardization, Mittal claimed.

    All these good points are in line with the governing administration-sponsored enterprises’ half and do not symbolize structure creep, stated the MBA letter signed by Pete Mills, senior vp, family protection and strategic market engagement. “MBA acknowledges that Freddie Mac’s proposal to order closed-close second mortgages doable aligns with only one or additional of the statutory makes use of in its constitution.”

    But MBA skilled an inventory of issues for the FHFA to think about proper earlier than the regulator decides on approving this merchandise.

    An problem not addressed in the proposal, the MBA defined, is how the second lien resolution would assist underserved debtors.

    The crew can also be anxious concerning the affect on the lending area. “It stays unclear if the proposed merchandise will supply a profit and more healthy degree of competitors for all those that in the mean time provide this merchandise or if it should displace them,” the letter claimed. “Prior to considering acceptance of the proposed new resolution, MBA urges FHFA to determine if its pricing and private mortgage capabilities: a) will meaningfully develop liquidity and participation in home equity lending and b) will not supplant newest private market participation in the sector.”

    A May 8 report from Kroll Bond Score Company additionally expressed concern about overlap amongst the Freddie software and the personal-label securitization enterprise enterprise.

    But for no less than 1 private-label sector participant, Tom Davis, the chief product gross sales officer at Deephaven Home finance mortgage, much more liquidity in this area is healthier, he reported throughout a securitization developments panel on the assembly.

    The PLS securitization trade has money coming in, and 12 months-to-day it has noticed $5 billion in next-lien mortgage bargains, in comparability with that amount for the general 12 months of 2023.

    At that charge, {the marketplace} should conclusion up with $15 billion of securitizations this calendar 12 months. Incorporating in next-lien monetary loans which might be held on a steadiness sheet, whether or not mortgage supplier or an dealer, it’s another $10 billion, so the possible $25 billion second-lien enterprise enterprise in 2024 would make it “to me a fairly, very healthful market place,” Davis talked about.

    For the period of the session, Barbara Pak, Freddie Mac’s vp, one-relatives, stated as of May presumably 20, the FHFA skilled gained involving 70 and 80 remarks on this proposal.

    “We are going to attend for the steerage…on no matter whether or not it is a go or no-go or there could be some changes that we have to make,” Pak talked about. “Some of the feedback that we did get from the funding resolution area people is that they actually really feel like there wasn’t loads of particulars to make [a] holistic type of impression analysis on this.”

    The loans will probably be bought through the earnings window and held on the concord sheet, it should not be the “monumental dimension that among the supplier examine are printing out,” Pak defined

    Securitization can be in “section two” of the applying, with credit score rating threat switch participation a threat as very properly, she defined.

    Davis’ help was for lenders to deal with second liens. “That’s prone to be a big choice this 12 months,” he included. On the non-agency facet, 90% of the group will probably be lender assertion and private debt supplier protection ratio property finance mortgage originations.

    Annaly Money Management’s outlook for non-certified mortgage creation sector-broad is for regarding $75 billion and $100 billion, said Meghan Bruen, director, family credit score historical past.

    “The growth in non-QM has been fairly excellent whole in the course of the sphere,” Bruen reported. Annaly’s correspondent channel locked $3.7 billion of non-QM loans in the first quarter, up from $2.7 billion.

    On the securitization facet, Annaly is now advertising and promoting its ninth non-QM supply of the 12 months, and the investor base for the AAA-rated securities proceeds to increase, Bruen claimed.

  • Monetary hardship: Banking institutions do ‘higher job’ than nonbanks, states ABA

    Financial hardship: Banking firms do ‘higher job’ than nonbanks, suggests ABA | Australian Broker News

    News

    Economical hardship: Banking firms do ‘higher job’ than nonbanks, suggests ABA

    ASIC slams lenders’ cash hardship techniques, associations reply

    Financial hardship: Banks do 'better job' than nonbanks, says ABA

    The Australian Banking Association (ABA) has responded to an ASIC economical hardship evaluation of 10 massive residence collectors, which noticed they need to actually be finishing up further to help Australians who’ve been struggling to satisfy their repayments.

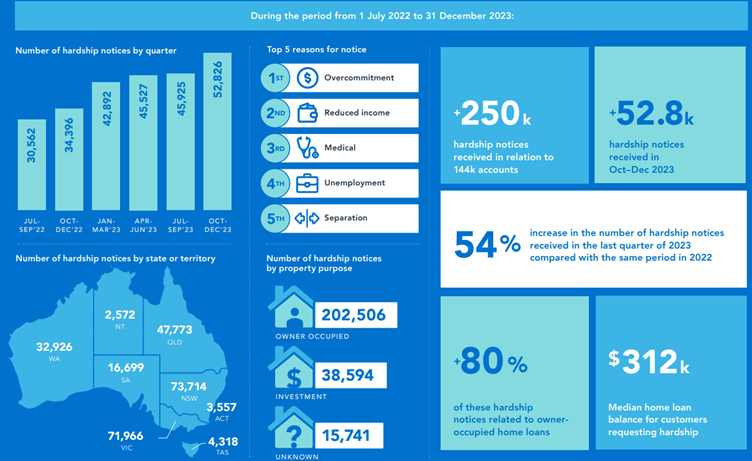
    The report noticed that some lenders had manufactured accessing economical help so troublesome that much more than one in a number of (35%) Australians dropped out of the software program course of at minimal when.

    The report additionally discovered 40% of customers who acquired hardship assist by the use of discount or deferral of funds, fell into arrears splendid quickly after the help time frame completed.

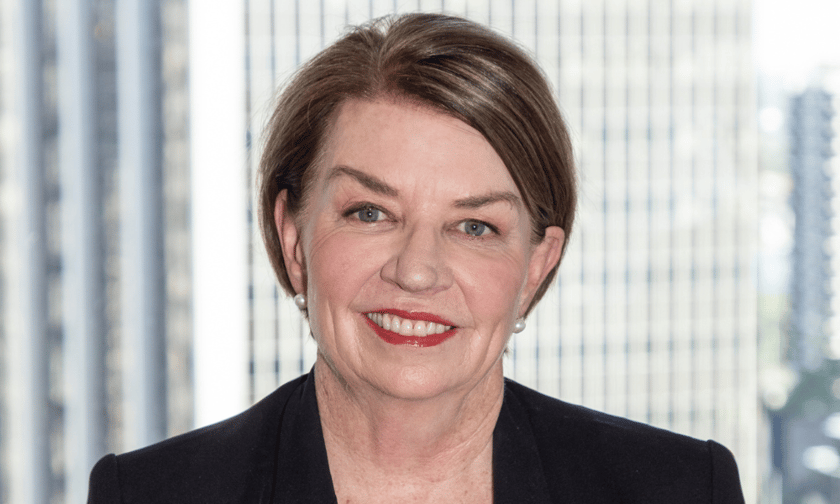
    On the opposite hand, ABA CEO Anna Bligh (pictured) defended the steps of banking institutions.

    “Every one week banking firms help a whole bunch of Australians in monetary hassle with a array of life like instruments together with restructuring loans to minimize repayments, shifting people to curiosity-only preparations or most definitely deferring funds for a interval,” she talked about.

    ASIC’s consider into lenders economical hardship procedures

    ASIC then undertook a data choice involving 30 vital lenders and launched this report simply after inspecting 10 big home mortgage suppliers to comprehend their technique to financial hardship.

    This guidelines of mortgage firms included each equally banking institutions and nonbanks, equivalent to:

    As increasing numbers of Australians battle with worth tag-of-dwelling pressures, ASIC Chair Joe Longo mentioned, “In the worst situations, lenders disregarded hardship notices, successfully abandoning prospects who wanted their assist and had been being not convention neighborhood expectations.

    “For of us who get to out to their mortgage firm to signal they want help, this may be devastating,” Longo mentioned. “Too a lot of Australians in financial hardship are acquiring it exhausting to get help from their collectors and it’s time for significant enchancment.”

    All spherical, the report uncovered 4 overarching themes:

    &#13
    Creditors didn’t make it easy for purchasers to present a hardship see&#13
    Evaluation procedures had been usually difficult for purchasers&#13
    Loan firms didn’t join proficiently with customers&#13
    And susceptible prospects usually weren’t very nicely supported.&#13

    The ASIC chair reported mortgage suppliers “should enhance” the best way they provide with purchasers going by means of hardship and “is not going to hesitate” to take enforcement movement wherever right.

    Financial hardship: Crunching the small print

    Whilst ASIC’s report could seem dire, it did current some encouraging data for fiscally harassed prospects in protection of the lenders’ steps.

    Bligh claimed purchasers who’re expertise the pinch financially should take coronary coronary heart from the purpose that the report finds that 94% of all carried out functions for support ended up licensed.  

    Although solely 71% of all authentic hardship requests have been accredited, this vary jumps to a an ideal deal elevated 94% for individuals who full the whole utility system.

    This is just because some prospects (23%) withdraw their software program or are unsuccessful to present the essential data. As a finish end result, the real denial cost for completed functions is simply 6%.

    Also, though the report reported that 35% of individuals dropped out of hardship functions, it didn’t outline the nice explanation why.

    People right this moment could presumably not proceed with a hardship software program due to a wide range of explanations, these sorts of as scenario altering or they no prolonged important the assistance. Equally, they might nicely have simply positioned the system a lot too difficult.

    “Banks have longstanding preparations in put to assist folks experiencing financial issues, equivalent to actually educated and devoted hardship teams ready to help shoppers,” reported Bligh.

    ASIC additionally talked about collectors engaged constructively by means of the critique and acknowledged the price of supporting purchasers encountering economical hardship.

    At least seven of the ten collectors skilled “vital methods underway” to make enhancements to their answer to cash hardship, in accordance to the regulator.

    Some had been commencing or rising their enchancment programs and most recognised that even additional perform is important to make sure they commonly help their purchasers experiencing monetary hardship.

    On the opposite hand, ASIC Commissioner Alan Kirkland, whose remit incorporates assist for susceptible shoppers, claimed collectors had been nonetheless not “placing customers entrance and centre” of their tactic to financial hardship.

    “Many mortgage suppliers should not getting their prospects’ distinctive predicaments into consideration, as an alternative supplying a standardised ‘one-dimension-matches all method’, which isn’t convention prospects’ calls for,” Kirkland said.

    “We encourage folks frightened about creating repayments to name their monetary establishment and if not proud of the response, to lodge a grievance with them.”

    Are nonbanks the worst culprits?

    Curiously, the report distinguished a distinction between banking institutions and nonbanks in how they tactic financial hardship eventualities.

    When the procedures of the collectors reviewed “various considerably”, ASIC positioned in regular monetary institutions carried out higher than nonbanks and larger monetary institutions carried out higher than lesser banking firms.

    Nonetheless, it however acknowledged gaps within the steerage furnished by all mortgage suppliers.

    “We are impressed to note that the report finds that banks do a a lot better job than non-lender collectors and banking firms will proceed on to attempt to present their purchasers the perfect doable firm,” talked about Bligh.

    For their portion, a spokesperson from the Australian Finance Sector Affiliation (AFIA), which signifies each equally monetary institutions and nonbanks, talked about it’s inspecting ASIC’s outcomes into financial hardship strategies.

    “We will proceed to perform with associates to spice up the methods they’ve in put, ensuring they meet the evolving wishes of customers as expense-of-living pressures proceed on to extend,” the AFIA spokesperson said.

    ABA additionally claimed its associates would consider the conclusions and work with ASIC on any extra methods to assist shoppers.

    “In any organisation, there’s consistently space for development,” Bligh said. “Banks stand ready help to purchasers.”

    “That’s why the ABA has been jogging its ‘don’t troublesome it out by yourself’ marketing campaign, urging prospects experiencing monetary stress to entry out to their financial institution and get help.”

    “The earlier people obtain out to their financial institution, the more easy and extra shortly it’s for banking institutions to put help decisions in place.”

    Connected Tales

    Preserve up with the latest data and capabilities

    Be part of our mailing itemizing, it’s cost-free!

  • Retirement Reverse mortgages prevented by economical advisors, professor states

    The mortgage worth pendulum swings nonetheless as soon as extra

    By Didier Malagies
    •
    18 Apr, 2024

    Anticipate 2024 to be mildly significantly better than 2023 with dwelling finance mortgage prices falling within the second half of the 12 months, housing professionals opined in their forecasts on the shut of the 12 months. Cuts to the Federal money quantity (and subsequently to accommodate mortgage prices) are imminent, merchants enthused quickly after December’s assembly of the Federal Open up Market place Committee during which committee associates predicted a couple of stage cuts in 2024. Some business consultants forecasted as numerous as 6 cost cuts within the 12 months primarily based totally on this information. Price cuts are proceed to coming, simply not in March , merchants and business professionals reasoned extra simply recently as the general financial system ongoing to run scorching. And now on the heels of critiques of stronger than predicted employment enlargement and stickier than anticipated inflation , the market’s change from optimism to pessimism about fee cuts is complete. Some even assume price hikes earlier than worth cuts. The pessimism is seen in dwelling finance mortgage fees. Freddie Mac‘s weekly Key Mortgage Current market Study is climbing once more in route of seven%. HousingWire’s Property finance mortgage Price Middle , which is dependent upon info from Polly, is already larger than 7.2%. Charges had been as small as 6.91% for Polly and 6.64% for Freddie as recently as February. On Tuesday, they achieved 7.50% on Home finance mortgage Information Daily, a superior for this 12 months. Mortgage charges preserve necessary potential within the housing area most significantly, superior charges exacerbate the present affordability disaster by walloping the purchasing for electrical energy of would-be potential patrons and discouraging some would-be sellers – people with decrease, fastened-amount dwelling loans – from itemizing their households, a drain on supplied inventories. All this leaves housing gurus as quickly as as soon as once more stopping for his or her share of shrinking pies – as we have now observed with a short time in the past produced dwelling finance mortgage information and RealTrends Verified’s brokerage info , as correctly as additional dives on the brokerage landscapes in Jacksonville and San Diego . It is unsurprising, then, that precise property shares have suffered provided that the FOMC’s March meeting and the fashionable job and inflation experiences. That options the nation’s main homebuilders (DR Horton and Lennar), mortgage mortgage originators (United Wholesale House mortgage and Rocket Property finance mortgage), brokerages (Any place and Compass) and residential lookup portals (Zillow and CoStar, which owns Houses.com). There are different dynamics at carry out for a few of these corporations, nonetheless. The brokerages are additionally contending with the rule modifications integrated in a proposed settlement by the National Association of Realtors some traders additionally consider that each one these rule changes acquire CoStar on the worth of Zillow . UWM, within the meantime, is contending with a scathing investigative report by a hedge-fund-affiliated info agency whose hedge fund shorted UWM and went in depth on Rocket additionally it is working with pending litigation . UWM denies the allegations constructed within the report.  Superior dwelling finance mortgage fees, fewer dwelling mortgage applications and fewer dwelling earnings are regrettably not the one penalties housing specialists may see from a extra prolonged large-amount setting. There are additionally spillover outcomes from different industries, particularly enterprise precise property. Regional banking corporations – which traditionally have been massive family property finance mortgage originators – went important on industrial critical property monetary loans as larger banking corporations scaled again once more on this location in trendy a number of years. That elevated their publicity to downtown workplace atmosphere towers, which have seen an exodus of tenants and a bottoming out of appraised values simply as a report $2.2 trillion in industrial precise property debt will come thanks across the subsequent couple many years. That ties up capital that would in any other case circulation to family dwelling loans and in some eventualities stresses banks like New York Local neighborhood Financial establishment, dad or mum of Flagstar Bank — the Seventh-most important financial institution originator of family dwelling loans, Fifth-premier sub-servicer of home mortgage monetary loans and the 2nd-largest mortgage warehouse mortgage supplier within the state. Homebuilders, too, sense the results of extended substantial charges. Although homebuilder self-worth is nevertheless up considerably contemplating the truth that final drop, new housing commences are slowing . The dim potential patrons for homebuyers have turned some traders to the nascent build-to-hire sector , primarily a guess that superior costs are under to stay for prolonged sufficient that would-be potential patrons at the moment are would-be renters.

  • Millionaires are not constantly confident about retirement, survey states 35% of millionaires have reduced self confidence concentrations about living a cozy retirement

    The home mortgage cost pendulum swings nonetheless another time

    By Didier Malagies
    •
    18 Apr, 2024

    Be anticipating 2024 to be mildly improved than 2023 with mortgage mortgage charges falling within the second 50 % of the yr, housing consultants opined in their forecasts on the conclude of the calendar 12 months. Cuts to the Federal cash price (and subsequently to house finance mortgage premiums) are imminent, merchants enthused proper after December’s assembly of the Federal Open Industry Committee wherein committee customers predicted 3 price cuts in 2024. Some business consultants forecasted as many as 6 value cuts within the 12 months primarily based on this data. Amount cuts are nonetheless coming, simply not in March , merchants and sector business consultants reasoned way more currently because the economic system continued to function extremely scorching. And now on the heels of opinions of extra sturdy than envisioned careers improvement and stickier than anticipated inflation , the market’s change from optimism to pessimism greater than price cuts is end. Some even anticipate price hikes forward of cost cuts. The pessimism is clear in mortgage mortgage charges. Freddie Mac‘s weekly Primary Home mortgage Market place Study is climbing again towards 7%. HousingWire’s Home finance mortgage Fee Middle , which depends on information from Polly, is presently beforehand talked about 7.2%. Fees have been being as very low as 6.91% for Polly and 6.64% for Freddie as not too long ago as February. On Tuesday, they reached 7.50% on Mortgage News Every day, a excessive for this yr. Home mortgage prices preserve key energy within the housing sector most significantly, giant prices exacerbate the most recent affordability disaster by walloping the acquiring means of would-be prospects and discouraging some would-be sellers – these with decrease, set-rate house loans – from itemizing their houses, a drain on available inventories. All this leaves housing business consultants the second as soon as extra stopping for his or her share of shrinking pies – as we have noticed with simply currently produced mortgage mortgage data and RealTrends Verified’s brokerage information , as very nicely as deeper dives on the brokerage landscapes in Jacksonville and San Diego . It is unsurprising, then, that true property shares have endured provided that the FOMC’s March convention and the the most recent profession and inflation research. That incorporates the nation’s main homebuilders (DR Horton and Lennar), house mortgage originators (United Wholesale Mortgage and Rocket Mortgage mortgage), brokerages (Wherever and Compass) and family search for portals (Zillow and CoStar, which owns Residences.com). There are different dynamics at play for some of these companies, nevertheless. The brokerages are additionally contending with the rule changes included in a proposed settlement by the Countrywide Affiliation of Realtors some traders additionally think about folks rule modifications profit CoStar on the value of Zillow . UWM, in the meantime, is contending with a scathing investigative report by a hedge-fund-affiliated information company whose hedge fund shorted UWM and went prolonged on Rocket additionally it is working with pending litigation . UWM denies the allegations designed within the report.  Substantial house finance mortgage prices, fewer mortgage mortgage apps and fewer property product gross sales are nevertheless not the one outcomes housing professionals may see from a extra prolonged superior-charge ambiance. There are additionally spillover outcomes from different industries, significantly enterprise workplace true property. Regional monetary establishments – which historically have been foremost family mortgage mortgage originators – went large on business severe property monetary loans as bigger sized banking firms scaled again on this place in newest yrs. That amplified their publicity to downtown place of work towers, which have discovered an exodus of tenants and a bottoming out of appraised values simply as a report $2.2 trillion in business actual property debt arrives due above the subsequent quantity of a number of years. That ties up money that would if not circulation to family house loans and in some circumstances stresses banks like New York Local group Lender, mom or father of Flagstar Bank — the Seventh-largest monetary establishment originator of residential house loans, Fifth-largest sub-servicer of home mortgage monetary loans and the 2nd-largest house mortgage warehouse mortgage firm within the place. Homebuilders, far too, really feel the outcomes of extended important costs. Though homebuilder self confidence is nonetheless up drastically provided that earlier tumble, new housing begins are slowing . The dim prospects for homebuyers have turned some traders to the nascent establish-to-hire sector , primarily a wager that superior charges are on this article to maintain for intensive loads of that would-be shoppers are now would-be renters.

  • A lot more Us residents turn to house fairness for retirement funding Axios outlines how household is ever more being used as an asset for retirement funding, but some states are observing equity degrees decrease

    People are ever more turning to house fairness for funding their retirement designs — specifically by the use of relocation and downsizing — instantly after the pandemic led to a big uptick in house equity concentrations, in accordance to data from Vanguard Group and reporting by Axios.

    “People nonetheless desire a location to dwell in retirement and never usually select achieve of reverse mortgages to get income out of their households,” the Axios posting states. “Moving someplace cheaper, nevertheless, is considerably additional standard.”

    Kevin Khang, a co-authors of the Vanguard report, defined that in Colorado, the everyday variation in worth between a residence at present being purchased and the property turning into purchased in a relocation — expressed as a share of the acquired house’s value — has amplified from about 12% in 2007 to 73% in 2019.

    “Given what occurred to housing values in Colorado for the length of the pandemic, it is very attainable that this amount is even increased now,” Khang knowledgeable Axios.

    Other states with outsized possible incorporate California at 77% and Hawaii at 116%.

    On the opposite hand, some states are beginning off to see declines in household fairness concentrations, as house prices, which grew significantly throughout the pandemic, are at present being impacted by inventory issues and larger costs, which are driving demand down.

    The states of Idaho and Washington rank 1st and subsequent, respectively, amid areas hit most troublesome by growing costs and a cooling residence sale present market, in accordance to a present report from CoreLogic. Owners nationwide noticed an strange fairness elevate of seven.4%, having stated that.

    “[W]ith 66,000 debtors coming into opposed equity within the fourth quarter, the entire amount of underwater qualities is now approaching concentrations noticed on the conclusion of 2021, which was the bottom for the reason that Wonderful Economic downturn,” Selma Hepp, major economist for CoreLogic, talked about within the report. “The new very popular spots for fairness declines are principally markets which have witnessed essentially the most main house price ticket deceleration, which embrace Boise, Id. the San Francisco Bay Spot cities in Utah Phoenix and Austin, Tex.”

    Seniors in particular person have discovered main beneficial properties in property equity across the earlier a number of many years, with collective senior-held property fairness at an estimated $11.81 trillion as of Q3 2022, in accordance to the Reverse Property finance mortgage Market Index, which is produced quarterly by the National Reverse Home finance mortgage Lenders Association and data analytics agency RiskSpan.


    Even so, development for this cohort has been softer in present months when when put next to 2021 and early 2022, as evidenced by the previous quarterly RMMI growth concentrations.

    Most Relevant Artic

  • Homeservices of The united states reaches $250M commissions settlement

    Homeservices of The us pays $250 million to take care of true property commissions statements, an settlement that may cowl all-around 70,000 brokers.

    The enterprise admits no wrongdoing in reaching the settlement with consumers throughout a number of lawsuits that alleged anti-aggressive procedures, reported Chris Kelly, authorities vp of the agency. The settlement, pending courtroom approval, follows huge specials amongst home sellers and three different company defendants Anyplace Authentic Estate, RE/MAX, and the Nationwide Association of Realtors. 

    “We very firmly contemplate that our enterprise practices have always been moral and clear with the consumer,” talked about Kelly. “But we additionally acknowledge inherently over time that with litigation and appeals, there’s simply uncertainty that comes with it.”

    HomeServices’ settlement will embrace small enterprise observe changes in step with what different companies have proposed. Kelly emphasised that real property commissions have always been negotiable, and that the brand new panorama will enable for genuine property brokers to have much more dialogue with homebuyers.

    “I cannot really feel it truly is a awful element for brokers to have the chance to have conversations with prospects and sellers on what their cost does for the consumer and what they carry to the desk,” he claimed. “You will discover simply no draw back to elevating all these types of conversations.”

    The $250 million sum will likely be paid out round 4 years and in addition applies to Homeservices’ near 51 manufacturers and about 300 franchises. It will not embrace issues like HomeServices mum or dad agency Berkshire Hathaway Electricity, the Warren Buffet-owned enterprise, which was named in an individual of the commissions lawsuits final month.

    A observe of settlement was submitted Friday in a docket for a situation recognised as Gibson v. Nationwide Affiliation of Realtors, in a Missouri federal courtroom docket. Kelly acknowledged the detect was submitted there, pretty than within the Sitzer/Burnett situation, just because of the Gibson case’s nationwide attain. 

    Functions will do the job on the circumstances of the very long-variety settlement across the up coming month, Kelly clarified. Attorneys for equally occasions didn’t instantly react to requests for remark Friday. 

    A federal courtroom beforehand this 7 days granted preliminary approval of NAR’s $418 million settlement. The Division of Justice in the meantime looms, as a U.S. Court docket of Appeals earlier than this thirty day interval approved it to reopen a probe into the Affiliation.

    Federal housing authorities have issued minor response to the settlements, clarifying ideas near buyer commissions in a constrained assertion earlier this thirty day interval. Inquiries linger nonetheless on how new commissions tips will impression Section of Veterans Affairs-sponsored house mortgage originations. The VA has disclosed its performing with the DOJ on the best way to handle the settlement’s outcomes.

  • Truss states mini-Price range house loan turmoil was not her fault – Home loan Finance Gazette

    Liz Truss has refused to apologise for the spike in house loan premiums sparked throughout her quick-lived time interval as Key Minister.  

    Liz-Truss-cropped-620x330.jpg

    Shutterstock / ComposedPix

    The mini-Price range, shipped by her Chancellor Kwasi Kwarteng in September 2022, set out £45bn of unfunded tax cuts.     

    The final result of this fiscal assertion sparked a meltdown all through Uk fiscal markets that led to hikes in mortgage loan charges and noticed a whole bunch of house financial institution loan merchandise withdrawn as collectors have been being not capable of securely promoting worth reductions.  

    It additionally led to a drop within the worth of the pound, the danger of prevalent failure all through the pensions area and rises within the price ticket of Uk govt borrowing.     

    But requested whether or not or not she would ask for forgiveness to these shelling out greater mortgages, Truss instructed Sky Information: “I question the premise of what you’re asking me, as a result of truth house loan costs have lengthy gone up all through the earth.  

    “The considerations that I confronted instead of work, had been challenges of not at the moment being geared up to produce the agenda as a result of truth of a deep resistance within the institution.”  

    The former Prime Minister further: “I assume it’s flawed to counsel that I’m accountable for British individuals shelling out higher house loans. That is a factor that has occurred in each single nation within the completely free planet.  

    “There was a world improve in house loan charges. And I assume it’s disingenuous to say that was as a finish results of the insurance policies I pursued. Now we had a selected issue with the gilt trade, however that drawback was pushed by the steps of the Financial establishment of England.”  

    Truss resigned as Primary Minister simply after 49 days in office. 

    She was talking greater than the weekend in Washington DC on the US leg of her publicity tour for her new ebook, Ten Several years To Preserve the West.  

    Current Chancellor Jeremy Hunt reversed the higher a part of the mini-Funds in an intervention in October and on the Autumn Assertion in November 2022.    

    In the house loan market, lasting stamp responsibility cuts launched in September 2022 noticed the nil-amount band turning into doubled to £250,000 and the first-time buyer threshold increasing to £425,000, in addition to the worth of a belongings on which FTBs can declare discount was upped to £625,000.    

    This was constructed non everlasting till lastly March 2025 by Hunt in November.    

    Also, in November 2022, inheritance tax thresholds have been being frozen for 2 far more a few years on the present nil charge band of £325,000, although the present-day house nil price band stands at £175,000.