Tag: role

  • Johnson handed area director role at Broker Conveyancing – Mortgage Finance Gazette

    Broker Conveyancing has introduced the appointment of a brand new area director, masking the East Anglia and Essex areas.

    Steve-Johnson-Broker-Conveyancing-481x330.jpg

    Steve Johnson (pictured) will report back to managing director Keith Young, and can be working throughout his area to assist present customers of Broker Conveyancing in addition to serving to to drive new advisers to the portal.

    Johnson joins the enterprise following over 20 years working in enterprise improvement roles, primarily inside the mortgage lending sector, primarily throughout the East of England.

    His most up-to-date role was as a relationship supervisor with Aldermore Bank, and he has held senior BDM roles with different lenders comparable to Bank of Ireland, Bluestone, plus the Skipton and Norwich & Peterborough Building Societies.

    Broker Conveyancing mentioned it could proceed so as to add additional useful resource to the enterprise with the intention to meet rising demand for its proposition inside each the mortgage recommendation and property company sectors.

  • Pagan will take product director role at April Mortgages – House loan Finance Gazette

    For an extended period-phrase monetary establishment April Mortgages has appointed James Pagan as director of product or service & portfolio administration.

    James-Pagan-620x330.jpg

    Pagan has performed a central role within the launch of April Home loans and in accordance to the company has sizeable information of effectively constructing and dealing with mortgage loan propositions. He will oversee the development of 5-15-calendar yr set fee house loans.

    Commenting on the appointment acknowledged: “I’m thrilled to be heading up answer enhancement at April Mortgages, and persevering with to construct consciousness of the constructive points that certainty and total flexibility can produce to mortgage loan advisers and debtors.”

    He further: “My information so significantly within the house loan market has given me a superb notion into why we so badly require these merchandise, and the way they’ll provide reputable stability and comfort to all people concerned. For too very lengthy it has been sophisticated for debtors to achieve from for an extended time phrase mounted premiums within the Uk, however we’re established to regulate that.”

  • April Mortgages appoints Eaton to COO role – Mortgage Finance Gazette

    April Mortgages has appointed Mark Eaton as chief working officer.

    Mark-Eaton-New-v1-560x330.jpeg

    Eaton has performed a central role to date in April Mortgages’ launch, bringing 5-15 yr fastened charge mortgages into the UK market, and offering new ranges of safety and certainty to each advisers and shoppers.

    In the brand new place, he’ll utilise his expertise within the business in steering April Mortgages’ operations, in addition to its gross sales and advertising and marketing exercise, because it builds relationships with advisers throughout the UK.

    Commenting on the appointment Eaton mentioned: “My 25 years in wealth and mortgages can be invaluable in informing the conversations we have now with advisers and distributors throughout the sector as we unfold the April Mortgages message, which has already struck a chord with so many.

    He added: “The volatility of the previous couple of years has highlighted the advantages that mortgage advisers and their shoppers can get pleasure from by longer-term fastened charge mortgages, and we have now already seen substantial curiosity in our revolutionary vary of merchandise.”

  • FHFA request for input eyes Federal Home Loan banks’ role

    A proper public request for suggestions on the Federal Home Loan Bank system launched Thursday, following a 12 months when it each supported establishments in a disaster and got here underneath scrutiny on numerous fronts.

    The request seeks input on how the regulatory assertion governing the FHLBanks’ mission may higher replicate their “acceptable role” in housing finance.

    The RFI the Federal Housing Finance Agency put forth additionally calls for ideas on what yardsticks needs to be used to measure how effectively it fulfills its mission and what incentives is likely to be utilized to that finish.

    “The mission of the FHLBanks to supply liquidity and help housing and neighborhood growth needs to be clearly articulated,” FHFA Director Sandra Thompson mentioned in a press launch.

    The RFI additionally poses questions similar to whether or not some mission objectives needs to be weighted extra closely than others and if there are objects that needs to be added to or faraway from the present iteration.

    Thompson indicated in a latest Senate listening to that she thinks inexpensive housing objectives needs to be extra aggressive, and the share of web earnings the 11 member establishments allot to them needs to be increased given their profitability.

    However, broader opinions on the system and its goals have been combined. While Thompson want to see it double-down on its exercise, others like former Fed Governor Daniel Tarullo have questioned its relevance and public bills linked to it.

    A latest Congressional Budget Office report just lately estimated the system’s value to be within the $7 billion vary. Most of that value is linked to an implied authorities assure on its debt.

    The FHLBank system bars nondepositories that represent an rising share of the mortgage market and as a substitute work extra prominently with different government-sponsored enterprises the FHFA regulates, Fannie Mae and Freddie Mac.

    Nonbank mortgage liquidity additionally has been present process regulatory overview, with a latest Financial Stability Oversight Council report suggesting that the supply of public amenities to bolster it needs to be improved.

    While the 2023 disaster examined depositories’ liquidity and out there assets, the pandemic initially raised questions on nonbanks by making them accountable for client cost suspensions they usually bear some duty for protecting to make sure investor funds.

    (A subsequent rate of interest drop provided as a type of pandemic aid returned money to nonbanks by means of refinancing to resolve the problem for the time being, however the FSOC report asks whether or not the problem would possibly re-emerge sooner or later.)

    Fannie and Freddie purchase loans from nonbanks, whereas the FHLB operates extra like a bunch of regional cooperatives with a public coverage mission. Each of those cooperatives receives lower-rate financing collateralized by mortgage portfolios by means of the system.

    A central Federal Home Loan financial institution workplace points debt that bondholders purchase to supply that financing. In return, the Federal Home Loan banks present low-cost liquidity to their members to put money into a spread of neighborhood lending.

    FHLB borrowing exercise soared throughout the 2023 banking disaster however critics be aware it wasn’t the only real useful resource out there to distressed banks, which additionally had the low cost window. The low cost window permits for borrowing secured by a broader vary of collateral than the FHLBanks however could provide a much less enticing charge. 

    Feedback in response to the request for input could be submitted by means of July 15 through the FHFA’s web site or mailed to the company’s Division of Bank Regulation at 400 seventh Street, S.W., Washington, DC 20219.

  • The role of brokers in closing the gender property gap

    The role of brokers in closing the gender property gap | Australian Broker News

    News

    The role of brokers in closing the gender property gap

    Solutions to the 24.3% Gen Z gender property gap
    The role of brokers in closing the gender property gap

    You’ve in all probability heard about the gender pay gap and the superannuation gap, however there’s one other essential gap that usually goes unnoticed: the gender property gap.

    CoreLogic’s newest Women and Property report sheds mild on this ignored situation, revealing some placing revelations.

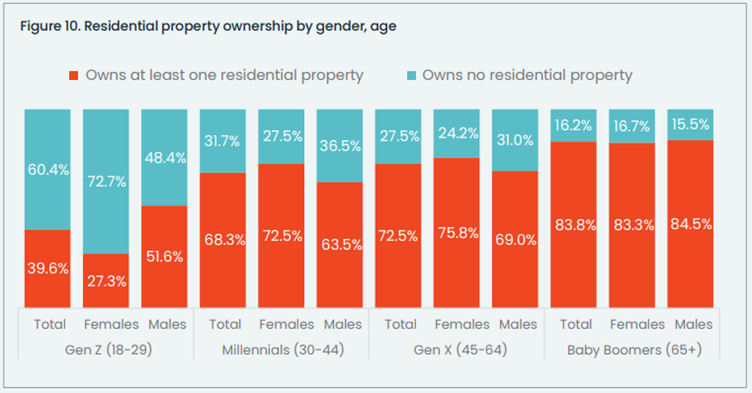
    Initially, it might seem to be progress when contemplating general property possession charges: ladies barely surpass males, with a 68.7% possession fee in comparison with males’s 67.4%. However, a more in-depth look reveals a special story, particularly amongst youthful generations.

    Mortgage dealer Alex Veljancevski (pictured above) emphasised the significance of understanding these tendencies, significantly when serving younger feminine purchasers.

    “All brokers, regardless of gender, ought to study this gap and think about find out how to modify our providers to higher meet our purchasers’ wants and slim the divide,” Veljancevski stated.
    Unveiling the gender property gap

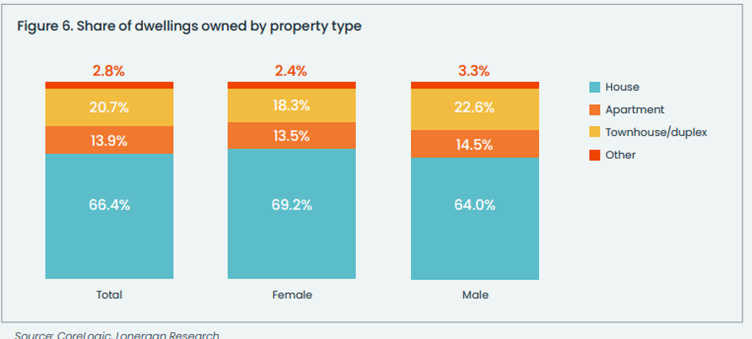
    Delving deeper, CoreLogic’s analysis highlights disparities in funding patterns. Males preserve a better fee of funding in residential dwellings, with 14.1% proudly owning a minimum of one residential funding property in comparison with 12.5% of females.

    The survey additionally requested about different kinds of property funding, offering the examples of business property, industrial property, or vacant land. Just 2.2% of males reported having a minimum of one different type of funding property, barely larger than 1.2% of females.

    Moreover, the report touches on the valuation and debt dynamics, revealing intriguing insights.

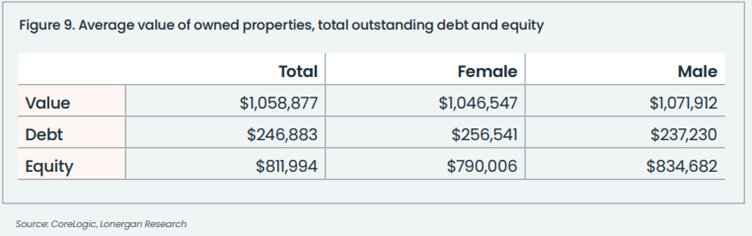
    Despite ladies proudly owning a better proportion of homes, sometimes extra precious than items, their common reported worth is barely decrease than that of males ($1,046,547 for ladies in comparison with $1,071,912 for males).

    Female-owned property values are inclined to cluster between $500,000 and $1,499,999, whereas males’s properties present a flatter distribution.

    Despite this, ladies report barely larger common excellent debt, ensuing in a decrease general house fairness place.
    The role of joint possession

    The means ladies purchase property additionally contributes to the gender property gap.

    Joint possession emerges as a prevalent avenue for ladies to entry the property market, with extra ladies than males utilizing this association.

    For ladies on decrease revenue, this may be an efficient solution to get onto the property ladder sooner via sharing of housing prices. However, this has its personal complexities probably creating conditions of monetary dependence and monetary abuse.

    This can also pose some vulnerability for ladies who’re single, or those who expertise a relationship breakdown.

    Affordability constraints amongst Gen Z ladies

    Affordability constraints considerably contribute to the gender property gap, significantly amongst youthful generations. While ladies could aspire to homeownership, restricted monetary sources usually pose a big barrier.

    Respondents incomes lower than $100,000 yearly exhibit a house possession fee of 61.4%, in comparison with 86.6% amongst these incomes greater than $100,000.

    Various elements contribute to this gap. Age performs a vital role, as each house possession and better incomes are sometimes achieved later in life. Additionally, socio-economic background influences entry to property possession, with higher-income people usually benefiting from household wealth or inheritance.

    Interestingly, ladies preserve a better fee of property possession when revenue is taken into account. For ladies incomes lower than $100,000, the possession fee was 62.1% (in comparison with 60.6% for males), rising to 91.0% for these incomes over $100,000 (83.2% for males).

    However, the notable gap that persists amongst Gen Z respondents (51.6% of males personal a property in comparison with solely 27.3% of ladies) can partly be chalked right down to variations in revenue.

    Gen Z ladies, on common, have decrease incomes and are more likely to have interaction in part-time or informal employment.

    This discovering is intriguing as a result of discussions about earnings for women and men usually centre on the well-documented gap ensuing from older ladies assuming unpaid parental or caregiver tasks.

    “Clearly, affordability constraints exacerbate the gender property gap amongst younger individuals, underscoring the want for focused interventions to handle this systemic situation,” Veljancevski stated.
    Other causes for the gender property gap

    While affordability constraints play a role, they don’t totally clarify the gap’s persistence. Veljancevski identifies three foremost elements.

    First, the common man earns greater than the common girl – for each $1 earned by males, 88c is earned by ladies, in line with the Workplace Gender Equality Agency.

    How brokers can deal with the gender property gap

    Addressing these disparities requires a multifaceted strategy.

    How to handle the pay gap

    Part of the motive the gender pay gap exists is as a result of males usually tend to be in positions of authority than ladies.

    “Because people usually tend to favour (usually unconsciously) individuals like them, it means, all issues being equal, that males usually tend to rent and promote males than ladies,” Veljancevski stated.  “That would apply as a lot to the mortgage broking trade as society in basic.

    “So if the trade made a acutely aware effort to extend the share of feminine illustration – solely 26.9% of brokers are ladies, in line with the MFAA – we’d be capable of slim the pay gap, a minimum of in our trade.”

    How to handle the danger tolerance gap

    “Brokers – particularly male brokers – must recognise that the common girl requires extra reassurance round shopping for property and taking over debt than the common man,” stated Veljancevski.

    “That means we’ve to offer the common feminine shopper with extra training.”

    How to handle the monetary literacy gap

    “We additionally must recognise that the common girl has much less monetary literacy than the common man. Again, that requires extra training – but it surely needs to be delivered in a means that feels empathetic fairly than patronising.”

    The backside line

    Ultimately, closing the gender property gap isn’t just a matter of equality; it is about empowering people to realize monetary safety and well-being.

    Brokers, as key gamers in the monetary panorama, have a pivotal role in driving this transformation.

    How do you service your younger feminine purchasers? Comment beneath.

    Related Stories

    Keep up with the newest information and occasions

    Join our mailing record, it’s free!
