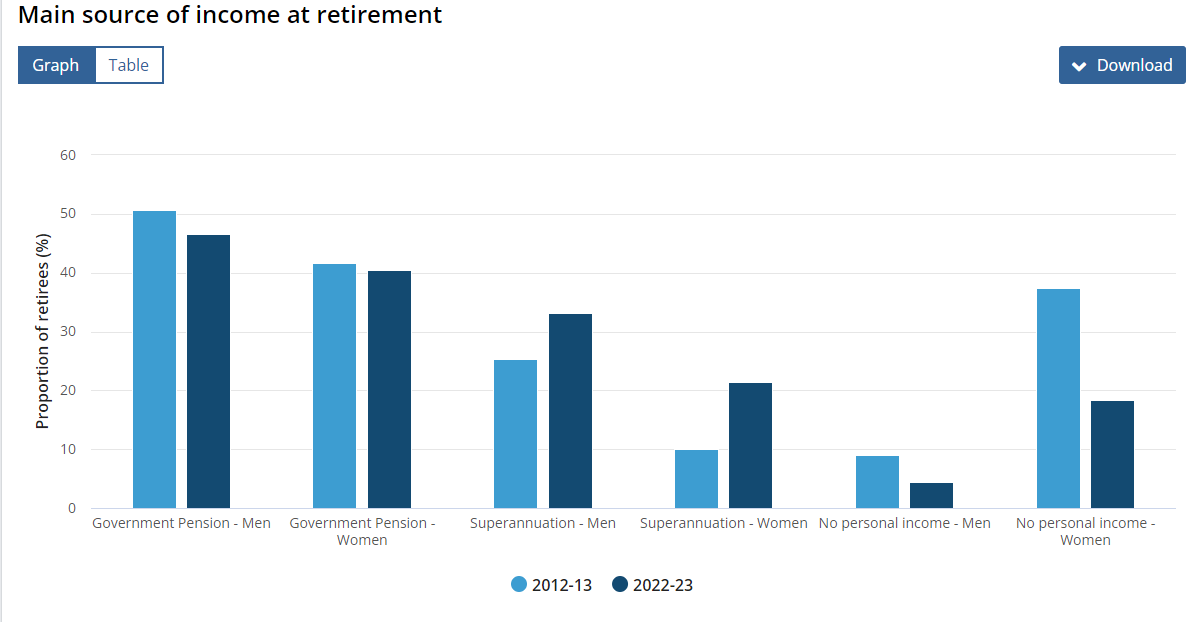Tag: retire

  • Dave Miller to phase down as MD of sourcing at Iress to retire – Home finance loan Approach

    Iress working director of sourcing Dave Miller has introduced he shall be stepping down from his half to retire.

    Miller retires quickly after a 35-calendar yr career in roles throughout the British isles financial providers and mortgage loan enterprise.

    He joined Avelo in 2002 and assumed his current function heading up the sourcing firm in 2013 pursuing its acquisition by Iress.

    Underneath his management, Iress’ sourcing small enterprise has developed and arrange with essential options The Trade, Trigold and Xplan Mortgage.

    Succeeding Miller is Jennifer Rafferty, who has held senior roles at Iress for 12 yrs. These embrace head of engineering and transport for the previous 10 a very long time.

    She has collectively managed Iress’ sourcing group together with Miller as a result of the beginning out of this 12 months.

    Iress’ group authorities prosperity and United kingdom Harry Mitchell states: “Jennifer assumes the administration half for sourcing at a time of appreciable alter and probability for the 2 Iress and the enterprise as an entire, bringing together with her appreciable know-how administration information and sector know-how.”

    “On behalf of the Iress Leadership Workforce, I’d like to fork out tribute to Dave’s appreciable contribution to Iress over many a number of years. We want him all of the most interesting on his retirement.”

  • Aussies’ retirement plans stay constant

    Aussies’ retirement designs proceed being steady | Australian Broker Information

    Information

    Aussies’ retirement choices proceed to be regular

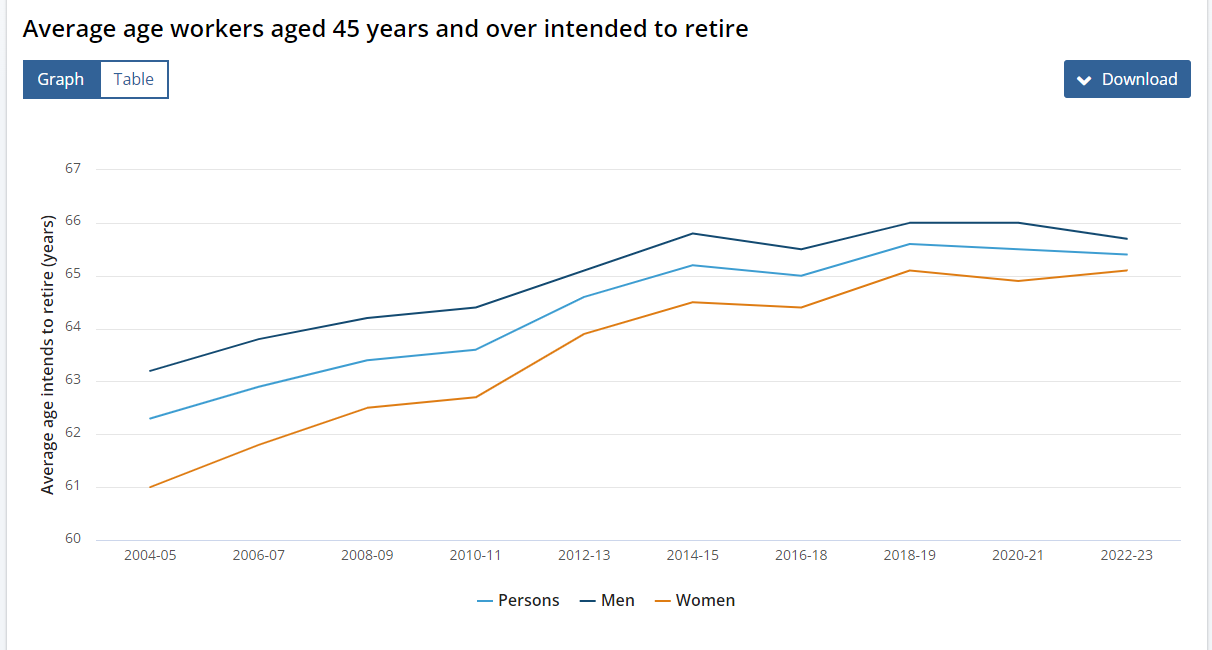
    Retirement age proceed to amongst 65-66

    Aussies' retirement plans remain steady

    Australians are nonetheless meaning to retire in between 65 and 66, in accordance to contemporary new figures from Ab muscle tissue.

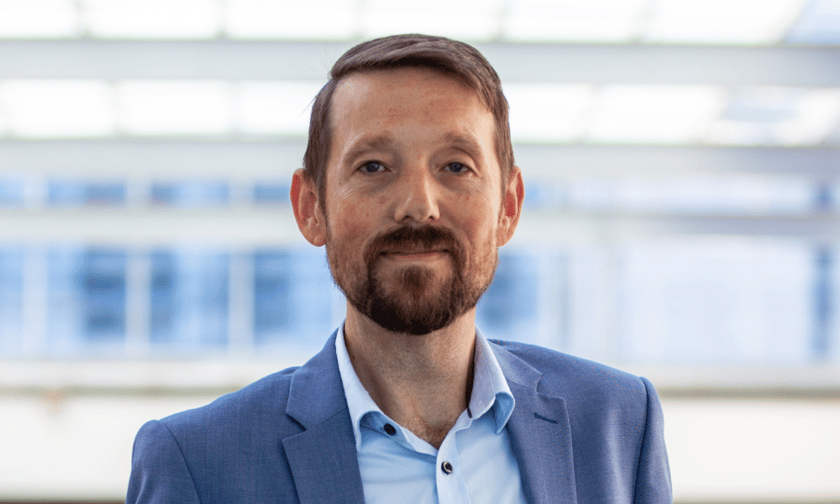
    “While the typical age that folks as we speak intend to retire has risen above time, it hasn’t adjusted a lot within the earlier 10 a few years,” reported Bjorn Jarvis (pictured above), Ab muscle tissue head of labour research. “This bizarre has been amongst 65 many years and 65.6 a few years for shut to a ten years, contemplating that 2014-15.”

    Gender dissimilarities narrowing

    Adult males generally tend to retire barely afterward than females, however the gap is closing.

    “In 2022-23, there was round 50 % a calendar yr variation amongst guys and girls, in distinction to a yr huge distinction a decade in the past, and a two-calendar yr variance all-around 10 a number of years simply earlier than that.” Jarvis defined in a media launch.

    Sector-specific tendencies

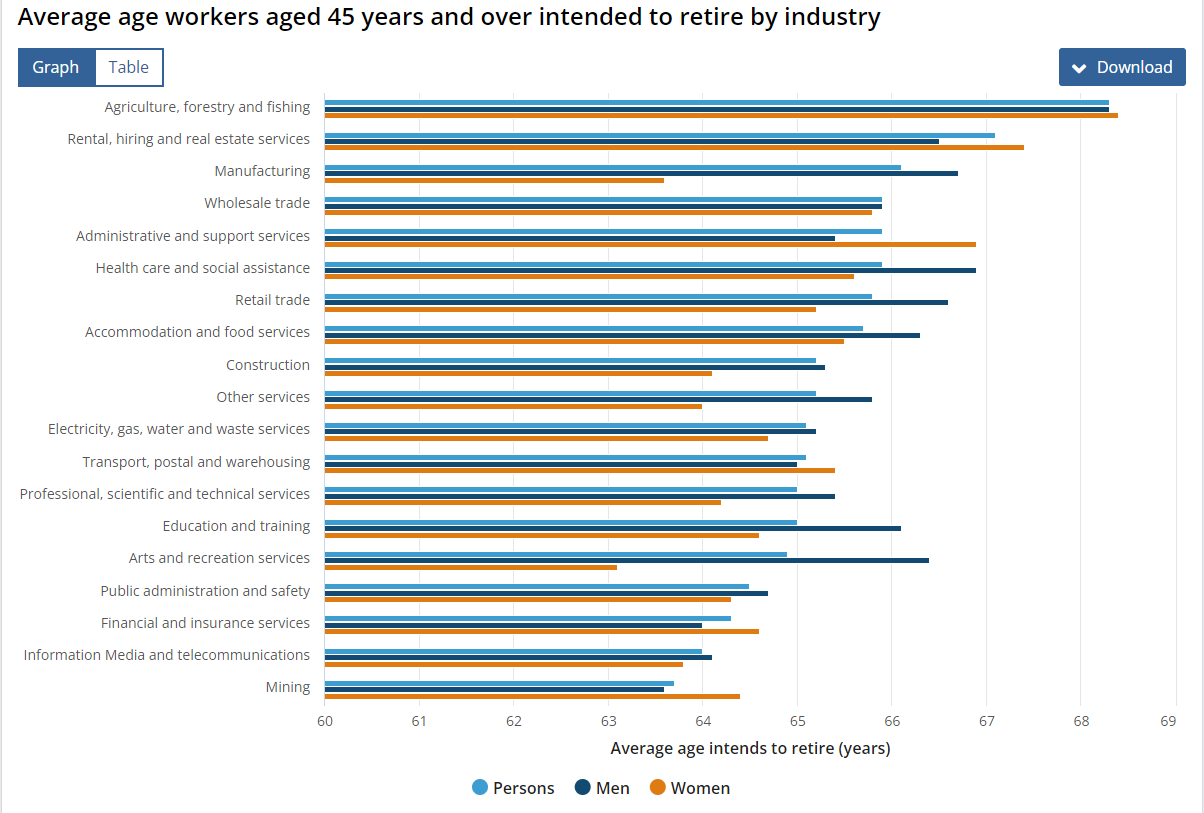
    Folks in agriculture, forestry, and fishing intend to retire at 68.3 years, the utmost common, despite the fact that people in mining method to retire at 63.7 years, the least costly.

    Age at retirement

    The Stomach muscle tissue data additionally confirmed the true age when retirees stopped working, with folks retiring afterwards on common.

    “In 2022-23, folks as we speak who retired within the earlier 20 many years did so, on typical, at 61.4 yrs,” Jarvis reported. “This common has risen from 58.5 a very long time in 2014-15 and 57.4 a few years in 2004-05.

    Retirees from the humanities and recreation services and products enterprise retired afterwards than all these in some other enterprise, at 64.4 a few years. The youngest frequent retirement age was in lodging and meals objects providers, at 58.5 years.

    Retirement income sources

    Govt pensions carry on being the first income useful resource for 43% of retirees, adopted by superannuation at 27%, Abdominal muscle tissue described.

    The amount of individuals as we speak with no non-public money circulation at retirement has fallen from 25% in 2012-13 to 12% in 2022-23.

    “In particular person, the share of ladies reporting no particular person money circulation has dropped considerably, down from 37% to 18%,” Jarvis claimed. 

    “The amount of ladies who relied on their companion’s revenue as their key useful resource of money for assembly residing expenditures at retirement has fallen by excess of 10 share particulars in regards to the 10 years, dropping from 44% in 2012-13 to 31 for every cent in 2022-23.”

    Things influencing retirement

    Financial security (36%) and particular person well being (22%) are probably the most frequent variables influencing retirement picks. One specific in 8 retirees cited reaching the eligibility age for a pension as a vital issue, Ab muscle tissue claimed.

    Get the most effective and freshest mortgage mortgage data shipped supreme into your inbox. Subscribe now to our FREE day-after-day e-newsletter.

    Similar Tales

    Hold up with the latest data and events

    Join our mailing record, it’s cost-free!

  • Men and women want to retire early, but aren’t preserving adequate to do it: study

    The home mortgage charge pendulum swings nonetheless as soon as extra

    By Didier Malagies
    •
    18 Apr, 2024

    Be anticipating 2024 to be mildly superior than 2023 with mortgage expenses slipping within the second fifty % of the calendar yr, housing gurus opined in their forecasts on the end of the calendar yr. Cuts to the Federal funds price (and subsequently to mortgage prices) are imminent, merchants enthused instantly after December’s assembly of the Federal Open up Sector Committee during which committee customers predicted just a few stage cuts in 2024. Some trade specialists forecasted as fairly just a few as six cost cuts within the calendar yr depending on this data. Fee cuts are however coming, simply not in March , merchants and market gurus reasoned way more just lately because the financial system ongoing to function scorching. And now on the heels of research of extra highly effective than anticipated work progress and stickier than anticipated inflation , the market’s change from optimism to pessimism about quantity cuts is full. Some even hope price hikes proper earlier than cost cuts. The pessimism is noticeable in mortgage mortgage costs. Freddie Mac‘s weekly Most essential Home finance mortgage Market Survey is climbing again once more in direction of 7%. HousingWire’s Mortgage Charge Center , which depends on knowledge from Polly, is by now above 7.2%. Rates had been as very low as 6.91% for Polly and 6.64% for Freddie as currently as February. On Tuesday, they arrived at 7.50% on Mortgage News Each day, a major for this yr. Mortgage mortgage expenses maintain principal energy within the housing trade most significantly, excessive charges exacerbate the current affordability disaster by walloping the acquiring electrical energy of would-be potential consumers and discouraging some would-be sellers – these individuals with very low, preset-amount residence loans – from itemizing their properties, a drain on accessible inventories. All this leaves housing specialists the second once more battling for his or her share of shrinking pies – as we’ve got noticed with simply currently launched residence finance mortgage data and RealTrends Verified’s brokerage data , as very nicely as deeper dives on the brokerage landscapes in Jacksonville and San Diego . It is unsurprising, then, that real property shares have suffered because the FOMC’s March assembly and the present occupation and inflation tales. That consists of the nation’s prime homebuilders (DR Horton and Lennar), residence mortgage originators (United Wholesale Mortgage and Rocket Mortgage), brokerages (Any place and Compass) and family search for portals (Zillow and CoStar, which owns Households.com). There are different dynamics at interact in for a few of these companies, however. The brokerages are additionally contending with the rule alterations built-in in a proposed settlement by the Countrywide Affiliation of Realtors some merchants additionally consider individuals rule adjustments edge CoStar on the expenditure of Zillow . UWM, within the meantime, is contending with a scathing investigative report by a hedge-fund-affiliated information group whose hedge fund shorted UWM and went intensive on Rocket it’s also working with pending litigation . UWM denies the allegations created within the report.  Large home mortgage charges, much less property finance mortgage functions and a lot much less dwelling earnings are sadly not the one results housing specialists might see from a extra extended significant-charge setting. There are additionally spillover outcomes from different industries, particularly enterprise critical property. Regional banking corporations – which traditionally have been important family residence finance mortgage originators – went important on industrial true property monetary loans as larger banking establishments scaled once more on this location in new a few years. That elevated their publicity to downtown workplace towers, which have noticed an exodus of tenants and a bottoming out of appraised values simply as a report $2.2 trillion in enterprise genuine property private debt arrives due to in regards to the subsequent variety of years. That ties up cash that might normally motion to family residence loans and in some situations stresses monetary establishments like New York Neighborhood Lender, father or mom of Flagstar Financial establishment — the Seventh-premier lender originator of residential mortgages, Fifth-largest sub-servicer of home mortgage monetary loans and the 2nd-major residence mortgage warehouse lender within the area. Homebuilders, as nicely, come to really feel the results of extended excessive charges. Whilst homebuilder self worth continues to be up considerably as a result of closing slide, new housing commences are slowing . The dim potential shoppers for homebuyers have turned some traders to the nascent develop-to-rent sector , successfully a wager that prime charges are on this article to keep for extended sufficient that would-be potential consumers at the moment are would-be renters.

  • Ginnie Mae President Alanna McCargo to retire

    Ginnie Mae President Alanna McCargo launched plans to retire Friday, contacting it a “deeply personal choice to return to personal each day life.”

    Her impending departure will finish the tenure of Ginnie’s to begin with girl president, who introduced stability to the half quickly after a interval wherein there hadn’t been a Senate-verified holder in virtually 5 a number of years.

    McCargo stabilized the corporate at a essential time as she served navigate it by every a pandemic and subsequent dramatic interest-amount cycle alter that put strain on some house mortgage companies that had been Ginnie’s counterparties.

    “We commend President McCargo and her employees members for his or her contributions on many difficulties, which embody supporting house finance mortgage servicers of their dedication to serving to battling owners enter and exit COVID-19 forbearance applications,” Bob Broeksmit, president and CEO of the Property finance mortgage Bankers Association, talked about in a press release responding to her departure.

    Broeksmit additionally credited McCargo for her work “investing in engineering to increase the working expertise for issuers, and enhancing liquidity for Ginnie Mae mortgage loan-backed securities” as well as to normally “advancing cheap housing initiatives and bettering the carry out of cash markets throughout her tenure.”

    Between Ginnie’s accomplishments throughout her time there was standing up an surprising emergency liquidity facility all by means of the pandemic and likewise afterward coordinating with the Federal Housing Finance Company within the progress of a sequence of modernized counterparty conditions.

    When Ginnie drew some criticism for acquiring to seize servicing from a single of these counterparties within the specialised reverse property finance mortgage market place, wherever there are confined gamers, it appears to have or else minimized issuer failures in a pressured setting.

    A nonbank risk-based funds rule proposed beneath McCargo’s watch drew some area criticism however relations with house mortgage firms turned further conciliatory simply after Ginnie prolonged its deadline and promised to carry out with issuers.

    Throughout McCargo’s time at Ginnie, the company took some strategies within the wake of its data with the Reverse Mortgage mortgage Funding particular person chapter to decrease liquidity strain in that sector.

    It additionally has drawn up insurance policies to take care of far more current hazards which have flip into apparent shut to cybersecurity fears and managed to proceed to hold its funding intact amid a federal spending price range catastrophe, sustaining liquidity for a massive governing administration-guaranteed housing sector.

    Ginnie ensures securitizations of mortgages backed on the mortgage-level by different authorities organizations just like the Federal Housing Administration and the Division of Veterans Affairs, and it’ll assist fund a essential number of loans made to initial-time dwelling potential patrons.

    “The previous 3.5 a very long time in group firm with the Biden-Harris Administration has been essentially the most important and fulfilling carry out of my 25-year occupation in housing finance,” defined McCargo, who designs to go away the company Might 3.

    “I’m deeply grateful for the choice to serve my nation and progress a daring housing agenda all through the world,” she included, alluding to the worldwide investor basis for the securities Ginnie assures. Ginnie enhanced outreach to Latin The usa all through her tenure.

    McCargo’s deliberate departure will happen not lengthy instantly after that of Marcia Fudge, the Section of Housing and Urban Development’s secretary, who introduced closing month she would step down. Ginnie is an arm of HUD. Adrianne Todman, beforehand a deputy secretary at HUD, is now serving in Fudge’s earlier goal on an appearing foundation.

    Todman referred to as McCargo, who introduced experience in areas like little-bank mortgage funding difficulties and servicing from her earlier half on the Urban Institute to Ginnie, “a zealous advocate for housing affordability and guaranteeing a much more equitable housing finance method.

    “As president of Ginnie Mae, Alanna has helped develop Ginnie Mae’s get to in serving traditionally underserved communities and has been a winner for advancing sector-driven initiatives that help property finance mortgage purposes all through the federal government,” Todman added.

    Sam Valverde, principal authorities vp at Ginnie, will tackle McCargo’s position on an appearing basis quickly after she leaves. Laura Kenney, Ginnie’s senior advisor for strategic operations and interim chief functioning officer, additionally will think about on a few of McCargo’s former duties.