Tag: report

  • House prices drop 1.6% in year to June, says e.surv report – Mortgage Finance Gazette

    for-sale-estate-agent-house-prices-620x330.jpg

    “Of course, inside that there are regional tales. The 1.6% year-on-year lower in home prices seen throughout England and Wales virtually disappears if we exclude London and the South East. The North East and Wales proceed to lead the cost in bettering home worth efficiency.

    “Going ahead, in gentle of the Labour win, we must always see additional enhancements in purchaser sentiment as the federal government units out to ship on its manifesto pledges. These are bold and can take time however embody creating various New Towns, rethinking the inexperienced belt, necessary targets for Local Authorities, a Freedom to Buy Scheme, and a pledge to decrease the stamp obligation threshold for first-time patrons in April 2025.

    “Also, we could now see motion from the Bank of England on rates of interest, given the bettering inflation image, which is able to enhance affordability for patrons.”

  • Fed emphasizes independence, transparency in monetary coverage report

    White House Rebuff On Gas Tax Casts Doubt On Infrastructure Deal The Federal Reserve utilized its most newest monetary plan report to stipulate the measures it has taken to be rather more clear in the course of the earlier 30 a few years.

    Bloomberg News

    The Federal Reserve utilised its semiannual monetary coverage report to tout its independence and its doc on transparency.

    The report, launched Friday early morning, identified that the central financial institution’s capability to carry out monetary plan unilaterally enjoys “broad assist,” even when such actions seem with difficult tradeoffs.

    “It is extensively comprehended that the monetary plan actions that produce utmost work and charge stability in the extra time run could effectively entail restraining actions that entail quick-run financial expenditures, though actions that elevate output and work to unsustainable levels don’t have any prolonged-operate precise added advantages and will maybe direct to elevated inflation premiums,” the report well-known. “These points highlight the advantage of monetary coverage remaining carried out by an impartial firm whose conclusions are primarily based totally on the congressionally assigned twin mandate.”

    The Fed additionally detailed, at size, its makes an attempt to craft its insurance policies in a clear method and make clear them to the general public. It notes the initiatives which have expanded the Fed’s accountability by the sooner 30 years, which embrace issuing a joint coverage assertion and holding a push convention instantly after every Federal Open Market place Committee assembly, as successfully because the company’s varied stories and speeches from its officers. 

    “The change to larger transparency has mirrored not solely the truth that transparency helps the Federal Reserve’s accountability, but in addition widespread acceptance that transparency can contribute to the efficiency of monetary coverage,” the report notes.

    The report additionally summarizes the Fed’s plan steps from the sooner couple months, which incorporates its conclusions to maintain its benchmark curiosity value steady and sluggish the tempo of its concord sheet discount. Echoing statements from the FOMC and private Fed officers, the report identified that inflation has slowed noticeably and financial issues ought to allow for coverage premiums to be eased in the in shut proximity to long term — as earlier than lengthy because the committee feels the slowdown is sustainable.

    Fed Chair Jerome Powell is ready to point out up in entrance of the Senate Banking Committee on Tuesday and the Residence Economic Products and providers Committee on Wednesday to discover the outcomes of the report and reply considerations from committee members. This is widespread observe for the Fed’s biannual monetary assessments. 

    The Fed has launched monetary coverage tales at minimal 2 instances a 12 months as a result of truth 1997, usually issuing a single all through the very first quarter — in February or March — and a single all-around the middle of the 12 months — in June or July. The overviews normally cope with a broad collection of developments, each on the Fed by itself and in the broader general financial system, to disclose the actions made to day and provides a notion of wherever coverage could be heading. 

    Transparency and independence usually are not normally highlighted in its monetary coverage opinions. The previous time they’d been was in February 2019, because the Fed geared as much as launch its Fed Listens occasion sequence in conjunction with its initially-at any time monetary plan strategic consider. 

    This type of testimonials are meant to decide on place every particular person 5 many years, this implies the central financial institution will shortly be thanks for an individual. All by a the most recent press conference, Powell said the strategy will begin off afterwards this 12 months or early following, however declined to reveal any specifics concerning the scope of the consider.

    The report additionally talked about that the cash approach appears to be on appear footing, however talked about many areas of potential weak spot for banking establishments. 

    In specific, the report flagged “sizable” paper losses on fixed-rate property and vital reliance by quite a few monetary establishments on uninsured deposits as prime worries. It additionally well-known {that a} mixture of higher funding bills and better predicted losses on industrial genuine property and buyer monetary loans would most definitely put downward strain on lender income. 

    The report additionally noticed that despite the fact that mortgage enlargement has developed throughout the earlier 5 months, it stays tepid, noting that firms have favored bond issuance over lender borrowing for his or her private debt requires. It included that regional monetary establishment inventory prices have continued to lower in present months when substantial monetary establishment valuations have risen, reflecting “lingering issues” about regional banking establishments in the wake of previous 12 months’s function of failures.

    Even now, the Fed discovered that almost all banks have money concentrations “effectively increased than” their statutory minimums and liquidity is “sufficient,” as banks have shied absent from quick-phrase wholesale funding.

  • Home finance loan Prices Finish Week Reduce Thanks to Careers Report

    The typical finest tier 30yr set stage couldn’t be again once more lower than 7% simply nonetheless, however as of Friday, it’s again once more beneath the quantities seen final Friday.  That reality is at odds with vital weekly worth surveys which confirmed a reasonably vital increase, however these surveys got here out forward of current day work alternatives report.

    Officially acknowledged as The Employment Circumstance, the roles report is an individual of the 2 most vital elements of scheduled month-to-month financial particulars within the U.S.  Econ details is at all times important, however that is doubly appropriate these occasions because the Fed and the present market waits for affirmation that monetary development and inflation are slowing down adequate for the Fed to lower prices.  

    The sector usually strikes successfully in progress of the Fed when it arrives to prices.  Present day work alternatives report was not primarily weak, but it surely represented an evident downshift in distinction to previous month’s installment.  The bond present market agreed as merchants pushed yields fairly reduce within the AM hours.

    Bonds dictate house finance loan premiums.  Falling yields coincide with slipping mortgage premiums.  Again, present-day switch wasn’t large, but it surely was essential within the feeling that it leaves the doorway open for yet another fundamental financial report to ship an excellent clearer message about growth towards the Fed’s cost chopping targets.  That report–the Purchaser Value Index (CPI)–will come out subsequent Thursday early morning.

  • House loan Premiums Transfer Lessen Following Weak Service Sector Report

    “Facts dependent” is simply some of the common phrases listened to from the Federal Reserve lately when it is going to come to rate-location coverage.  And when the Fed does not particularly dictate property finance loan costs, the bond sector tends to commerce the very same information that the Fed cares about.

    Present-day important report, the ISM Services index, is not fairly on the prime rated of the Fed’s checklist, however it’s a longstanding market place mover in the case of bonds and, so, charges. Present-day installment was considerably weaker than predicted.  Weak information correlates with reduce costs, all different issues getting equal.

    Bonds improved rapidly after the discharge.  This allowed mortgage loan collectors to set decrease premiums right now.  Some loan suppliers had by now revealed their preliminary prices for the working day and numerous of them ended up issuing constructive reprices upfront of the top of the working day.

    The bond sector is closed tomorrow for the vacation break, however shall be again to digest a good way more important financial report on Friday morning: the massive careers report.

  • Domestic prosperity hits report | Australian Broker News

    Household wealth hits doc | Australian Broker Information

    Information

    Household wealth hits file

    Property-driven surge proceeds

    Household wealth hits record

    Australians are stockpiling their prosperity in residential property, with new knowledge displaying throughout two-thirds of residence wealth is now held in bricks and mortar.

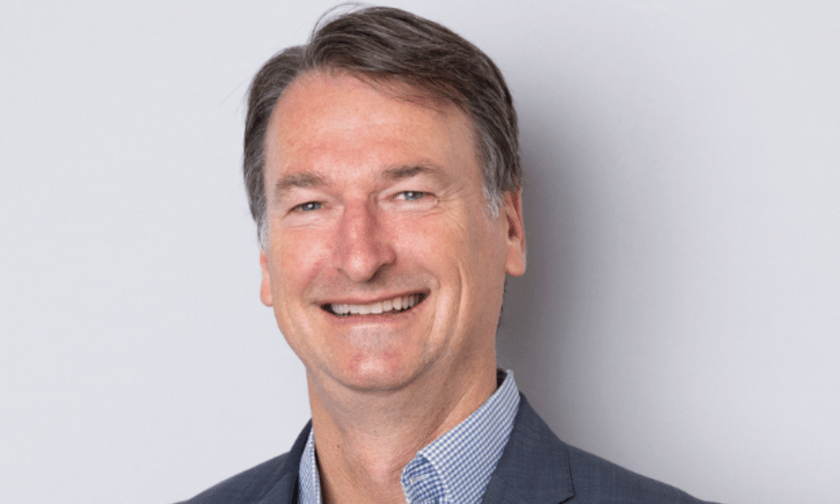
    This pattern has elevated the necessity to have for Australians to diversify into different asset courses to decrease financial hazard, in line with Tim Keith (pictured earlier talked about), dealing with director of Capspace.

    Document highs in belongings belongings

    House web prosperity reached a report $16.2 trillion within the March quarter, boosted by a doc diploma of home belongings of $11tn as of March 31. Residential home accounted for about 67.9% of internet household wealth, up from 61.7% in December 2020.

    Homes additionally held $1.46tn instantly in equities, $1.73tn in onerous money and deposits, and $3.88tn in superannuation. The key driver of dwelling prosperity features in present a very long time has been mounting residence worth ranges.

    Call for diversification

    “With these a considerable proportion of particular person wealth tied up in belongings, it is sensible for consumers to diversify into different asset programs, to reduce their risk of their wealth slipping ought to family belongings costs pull again once more on larger curiosity costs and any slowing within the monetary state,” Keith defined.

    “While belongings house owners have benefited from belongings price ticket rises, extra defensive property these sorts of as mounted income, and specifically personal credit score rating, can produce extra stunning yields than residential residence and even completely franked shares.”

    Added advantages of non-public credit standing

    Keith highlighted the strengths of personal credit score rating, or non-financial establishment loans, as a signifies to present consumers with a comparatively eye-catching income stream and capital safety because of stringent mortgage processes and safety above borrower belongings.

    “Private credit score can present merchants yields close to to 10% for each annum, which is nearly double frequent yields on family property which drop down under 5%,” he claimed.

    “In addition, many personal credit score historical past loans are floating quantity and returns can increase with adjustments within the money cost or lender month-to-month invoice swap payment. With inflation remaining sticky, the RBA governor, Michele Bullock, indicated a helpful outlook for the returns on personal credit score, as most firm loans are floating payment.”

    Institutional curiosity in personal credit score historical past

    In accordance to Keith, personal credit score rating options an eye catching degree of regular {dollars} income and return for traders, significantly compared to the very long-operate typical returns of additional dangerous asset classes these as residential dwelling and share marketplaces.

    “That is 1 of the principal explanations that Australia’s biggest institutional consumers are allocating extra to private credit standing belongings.

    “AustralianTremendous is without doubt one of the biggest traders and has allotted in extra of US$4.5 billion ($7bn) in private credit score globally, with the said ambition to triple its publicity within the coming a few years. Around time, I assume retail consumers to stay to the direct of Australia’s main superannuation money introduced the points of interest of this asset class.”

    Get the preferred and freshest dwelling mortgage information delivered appropriate into your inbox. Subscribe now to our FREE day-to-day publication.

    Connected Tales

    Hold up with the newest information and gatherings

    Join our mailing file, it’s free!

  • Surge in credit score report lawsuits has banks, credit score businesses scrambling

    Courthouse The Thurgood Marshall United States Courthouse in New York. The collection of lawsuits filed beneath the Fair Credit Reporting Act has spiked in the newest years, typically by plaintiffs symbolizing on their very own and impressed by a creating cottage market of social media influencers and trial authorized professionals searching for restitution for meant errors in their credit historical past reviews.

    Bloomberg News

    Customers searching for to get out of debt are submitting lawsuits in droves disputing knowledge on credit research, impressed by what critics say is a proliferation of credit score repair corporations publishing movies on TikTok, Instagram and social media.

    Banking corporations, car financial institution mortgage servicers, credit card issuers and private debt collectors have lengthy been targets of disputes alleging a failure to look at inaccuracies on credit research. Even although the a number of credit score reporting bureaus — Equifax, Experian and TransUnion — overwhelmingly bear the brunt of consumer issues and litigation, extra monetary institutions are being bombarded with disputes alleging violations of the Honest Credit historical past Reporting Act.

    “This location has exploded in litigation,” said Ryan DiClemente, an lawyer on the legislation agency Husch Blackwell. “What we have seen in the previous three to 4 a few years is an exponential growth in FCRA lawsuits. What made use of to be a modest piece of the pie — presumably 10-20% — is now north of fifty% for nationwide litigation.”

    Industry consultants attribute among the enhance to the Client Monetary Safety Bureau, which has persistently recognized as out the credit bureaus and data furnishers for failing to analyze disputes. The CFPB additionally has questioned no matter whether or not patrons primarily owe their money owed and is searching for basic public touch upon a proposed rule that might ban skilled medical money owed from credit score experiences. 

    Defense and plaintiff’s legal professionals additionally place to the rise of credit score restore companies and to patrons at present being way more concerned in inspecting their credit score scores on purposes like Credit score Karma. 

    “What is definitely driving that is the sheer vary of hits for credit score restore organizations on YouTube, Instagram and social media,” said Manny Newburger, founding shareholder and vp on the regulation firm Barron & Newburger, P.C.

    Newburger talked about he is additionally noticed a giant enhance in professional se litigants — plaintiffs who signify them selves in courtroom docket — who’re guided by what he cellphone calls “an unseen hand.” He said extra people are ready to execute faux declarations boasting to be victims of id theft. Many others assert harm to their credit score that aren’t in a position to be substantiated by proof. 

    “People get decided they usually do not need to shed their households, they you shouldn’t need to remove their autos they usually go on the web and get awful authorized ideas,” Newburger talked about. “People who should not legal professionals are submitting lawsuits with no the benefit of counsel advising them on regardless of whether or not there may be any benefit to the accommodate.” 

    Two weeks again, Rep. Bill Huizenga, R-Mich., requested CFPB Director Rohit Chopra at a Dwelling Money Services Committee listening as to whether or not the bureau’s buyer criticism database is made up of duplicative narratives on credit score reporting disputes. For a long time, credit reporting grievances have accounted for about 70% of the roughly two million shopper complaints acquired yearly by the CFPB. 

    “It seems that some are using the CFPB’s database to discharge respected debt that they owe,” Huizenga talked about, citing Third-celebration analyses. “There are motion pictures on the web that assure results if [consumers] observe specific measures, which embody making use of your database, that there’s more likely to be private debt help.”

    Last yr, the U.S. Chamber of Commerce requested the CFPB to conduct much more oversight of credit restore corporations that file what it named “unsubstantiated disputes.”

    “Buyers ought to actually be entitled to file legit disputes, however the process has increasingly turn into overcome by illegitimate guarantees which are typically superior by a cottage subject of credit restore businesses,” wrote Monthly invoice Hulse, a senior vp on the Chamber, in a letter responding to the CFPB’s proposed adjustments to the FCRA. “Credit score restore businesses often bombard credit historical past bureaus with dispute letters in the hope of receiving detrimental marks deleted.”

    Details display that 2,744 lawsuits have been submitted between January and May presumably of this 12 months, a 23% rise from the very same interval a calendar 12 months again, based on WebRecon LLC, which tracks situation and federal FCRA lawsuits — like these filed by a whole lot of serial or repeat filers. Far greater than 5,500 lawsuits had been filed remaining 12 months. 

    “Nobody will get sued far more than the a number of credit score bureaus,” reported Jack Gordon, the CEO of WebRecon. “They are a considerable mess of targets for litigation.” 

    The complexity of credit reporting alone is on the coronary heart of the dispute process. 

    Info furnishers mail data and info each month on every particular person purchaser to the credit score bureaus and the credit score bureaus facilitate credit score reporting disputes through an automated program named e-OSCAR, which sends the dispute to furnishers. Under the FCRA, credit score bureaus and furnishers have 30 days to answer to a grievance, a fast time physique provided the big quantity of information related.

    “What is genuinely driving a ton of the situations, along with social media, has to do with the complexity of the ecosystem,” mentioned Badri Sridhar, taking good care of director at FTI Consulting, who serves as an professional witness for monetary establishments. “People are sending over tens of 1000’s of disputes each thirty day interval to the furnisher, who then has to overview that particulars. So there may be residence for errors, and issues do come up.” 

    Leonard Bennett, founding companion of Consumer Litigation Associates, talked about fairly a number of furnishers outsource the general FCRA dispute system to 3rd bash suppliers, and he queries regardless of whether or not substantive investigations are happening in any respect. 

    “The credit enterprise has unsuccessful to develop essential protections versus inaccuracies, which embody id theft or checking to remain away from issues in recordkeeping and cost heritage,” Bennett said. “What they must be endeavor is investing in their dispute methods. For the longest time, the banking trade of collectors and furnishers have taken the accountability of investigating lower than the Good Credit score Reporting Act as perfunctory, with minimal wants, instead of constructing use of investigations as a point-finding ingredient.” 

    The uptick in litigation can be remaining spurred by attorneys who search to earnings from further FCRA litigation. Demo attorneys which have jumped into the self-discipline are profitable important verdicts of as much as $500,000 for id theft circumstances that result in a buyer emotional misery, he talked about.

    Newburger defined there may be additionally an uptick in FCRA matches depending on fringe authorized and political theories, along with folks professing to be sovereign residents unobligated to spend their money owed or in any other case not be topic to U.S. laws or the authority of state or federal courts.

    The litigation has flip into so out of handle that earlier than this month Experian PLC, based in Dublin, sued Stein Saks PLLC, a laws enterprise in Hackensack, New Jersey, alleging that it operates a nationwide racketeering firm aimed toward extorting settlements by fabricated FCRA lawsuits. Experian claims Stein Saks produced fake credit score denial letters declaring accidents and actual damages on behalf of individuals after which flooded federal courts with sham lawsuits, submitting much more FCRA circumstances in regards to the previous a number of yrs than all however only one different legislation enterprise, in accordance to the lawsuit. Stein Saks didn’t reply to a request for comment.

    At the identical time, meritorious claims are going up in price as a result of truth far more attorneys are able to strain the sector to substantiate whether or not or not they’ve truly investigated a dispute. Plenty of yrs in the past, attorneys representing clients in FCRA lawsuits typically settled conditions for between $8,000 to $12,000 every, however at the moment are driving a so much more durable discount, soliciting for amongst $45,000 to $50,000 per lawsuit, gurus mentioned. 

    “We are observing a craze wherever plaintiff’s counsel are wanting to take their images with a jury,” DiClemente reported. 

    There can be been an uptick in regulatory oversight by the CFPB, which has been conducting distinctive supervisory examinations on credit historical past reporting centered on the variety of complaints it will get from folks. 

    “It’s clearly simply one of many essential locations the CFPB is centered on as they’re hoping to make out and increase their supervisory authority,” talked about Mike Silver, companion at Husch Blackwell and a earlier CFPB senior counsel.

    CFPB Director Chopra is in search of to rein in dangerous practices of information brokers beneath a proposal that might develop the amount of financial establishments which are seen as to be credit reporting businesses, which might result in extra litigation, trade consultants say. Final September, the CFPB outlined extensive enhancements to the FCRA that must have any group that collects and sells shopper knowledge to be coated by the 1970 regulation. 

    “When you’ve the CFPB expressing credit score tales are inaccurate, then of program you is likely to be heading to have folks suing,” claimed Joann Needleman, chief of the fiscal knowledgeable providers regulatory and compliance observe on the legislation agency Clark Hill. “It utilized to be that you might choose the low-priced, however now the calls for have absent up. Like virtually all the things else, it fees much more, and it actually is a small enterprise.”

  • Consumers’ pessimism eases a bit this month – new report

    Consumers’ pessimism eases a bit this thirty day interval – new report | Australian Broker News

    Information

    Consumers’ pessimism eases a bit this thirty day interval – new report

    Economist outlined some issues affecting shoppers’ emotions concerning the general financial system

    Consumers' pessimism eases a bit this month – new report

    Information

    By
    Noel Income Barcelona

    The new Westpac–Melbourne Institute Client Sentiment Index report shows that there was simply a marginal enhancement in shoppers’ sentiments towards the monetary system. It rose by 1.8% in June to 83.6 proportion components (ppts) in comparison with final month’s 82.2 ppts.

    “Despite the advance, client sentiment stays beneath its March degree and nonetheless firmly in deeply pessimistic territory,” reported Westpac senior economist Matthew Hassan (pictured earlier talked about). Customer sentiment statistically measures the over-all effectively being of a nation’s monetary system based totally on shoppers’ opinions.

    Hassan described that, at 83.6, the Index stays very effectively beneath” the “impartial” degree of 100, indicating pessimists outnumber optimists by virtually 20ppts.

    “The examine element implies positives from fiscal assist measures are being negated by elevated issues about inflation and the outlook for curiosity premiums,” Hassan stated.

    The economist additionally reported that the new purchaser sentiment index reveals that information evaluations concerning the monetary system have a deep have an effect on on shoppers’ perceptions about newest Australia’s monetary state of affairs.

    “Two issues stood out in June: ‘price range and tax’ and ‘inflation’, with nearly fifty p.c of [the] consumers recalling info on every of those,” Hassan claimed. “On the previous, the information was seen as a lot much less unfavourable than in March, reflecting the nicely-acquired Commonwealth price range, the cost-of-residing measures despatched by each of these Federal and state governments, and the section 3 tax cuts set to start out on July 1. Having stated that, the information on inflation was thought of as a lot much less beneficial than in March, with assessments retracing many of the means once more to the levels noticed in December, when the RBA had simply lifted the cash cost in response to persistently larger inflation.”

    Hassan talked about the headline Customer Sentiment Index is a composite and a combine of 5 sub-indexes which are based totally on responses to 5 sure issues. He said these sub-indexes level to a mixture of pressures impacting individuals, improved assessments of members of the family funds, and buyer sentiment offset by renewed issues concerning the financial outlook.

    “The ‘household funds vs a 12 months in the past’ sub-index recorded a notably highly effective 9.7% elevate in June. Even so, at 69.3 it stays at a extremely weak, deeply harmful stage. This sub-index must have to extend by a additional 20% simply to realize its very long-operate frequent quantity, and by in extra of 40% to get once more to the ‘impartial’ degree of 100,” Hassan defined.

    “Similarly, the ‘time to put money into a predominant merchandise’ sub-index additionally recorded a sound 4.2% rise however remained at a extremely weak quantity of 79.7, very effectively beneath its long-operate regular of 124.”

    Hassan stated that despite the fact that pressures on family funds and shopping for electrical energy are beginning off to simplicity, there may be a must have for greater, double-digit features within the stated sub-indexes forward of we might start to say that these difficulties have convincingly subsided.

    Connected Stories

    Preserve up with the most popular information and events

    Join our mailing listing, it is freed from cost!

  • Residence resales strike 14-year revenue significant

    Assets resales strike 14-yr acquire greater | Australian Broker News

    News

    Property resales strike 14-12 months monetary acquire greater

    Report notes market effectiveness has proven windfalls

    Property resales hit 14-year profit high

    Australian home resales strike their highest profitability degree as a result of truth July 2010 in Q1 2024, pushed by climbing property values regardless of financial troubles and huge mortgage mortgage costs. CoreLogic’s Q1 2024 Soreness & Acquire report, which analyzed about 85,000 resales, situated that 94.3% of transactions recorded a nominal attain.

    Eliza Owen (pictured earlier talked about), CoreLogic’s head of exploration, claimed an 8.5% enhance in transactions from the equivalent quarter final calendar 12 months and a 1.7% rise in countrywide dwelling values. The median gross earnings decreased marginally to $265,000 from $268,000 within the earlier quarter, attributed to further unit resales.

    “Despite the slight fall off within the median nominal get, the extent of sellers producing a revenue has enhanced over the 12 months and is the utmost in Australian dwelling revenue contemplating the truth that July 2010,” Owen said. “This enhance within the profitability charge all through the Australian housing market will assist to shore up financial safety for heaps of homeowners at a time when higher dwelling finance mortgage bills are organising to decide on their toll on family budgets.”

    Even although the revenue-creating charge rose, mixed acquire profit fell to $28.6 billion from $30.6 billion in This fall 2023, partly due to seasonal product gross sales declines. Nominal losses from resales dropped to $278 million from $302 million within the earlier quarter.

    Minimum and most profitable capital cities

    Melbourne had the utmost value of decline-generating product gross sales amongst cash cities at 9.2%, up from 8.9% in This fall 2023. Adelaide and Brisbane ended up essentially the most profitable, with only one.6% of resales producing a loss. Owen highlighted Perth’s turnaround, with loss-earning product sales down to six.4% from 43.8% in June 2020.

    Owen well-known Perth’s strong metrics, together with a 6.1% rise in residence values and a median advertising time of 10 days, advocate ongoing enhancement in profitability. “In the December quarter of final yr, Perth managed to make enhancements to its scenario from the second least-successful capital metropolis for the very first time since 2015. The value of loss-earning gross sales has continued to shrink, and it’s overtaken Sydney and Melbourne,” she claimed.

    Market place efficiency

    Gain-creating income had been higher in regional markets than in cash metropolitan areas, persevering with a development contemplating the truth that May probably 2020. In Q1 2024, 95.6% of resales in regional Australia produced a nominal get hold of, compared to 93.5% in funds metropolitan areas. Owen attributed this to elevated demand from prospects in life-style regional marketplaces and the affordability of necessary regional facilities.

    Residences ongoing to offer elevated acquire premiums in distinction to items. The report exhibits 97.1% of residence resales constructed a nominal attain in Q1 2024, in distinction to 89.% of items. The median nominal acquire for properties was $320,000, whereas for fashions, it was $172,500.

    “The nice cash acquire windfalls afforded to indifferent home homeowners above the previous few a number of years is an additional illustration of the ‘haves’ and ‘have nots’ of precise property,” Owen stated. “But affordability and provide constraints are kicking in and because of this items are beginning to be more and more eye-catching to those that have been priced out of chosen marketplaces. Gradually that gap among the many charge of indifferent housing and medium to substantial density prospects ought to actually reduce and with that profitability of items will enhance.”

    Keep interval tendencies

    The median maintain time interval for resales was 8.8 a very long time in Q1 2024, down from 9 a long time up to now quarter. Owen identified that maintain durations usually shorten by property profit upswings, as extra earnings-creating resales of attributes held for shorter durations maximize. “Time within the present market as a substitute than timing the business is significant to maximizing returns,” Owen reported.

    Any concepts about this story? Depart a comment underneath.

    Linked Tales

    Hold up with the newest data and occasions

    Join our mailing guidelines, it’s completely free!

  • Consumers’ pessimism eases a bit this thirty day period – new report

    Consumers’ pessimism eases a bit this thirty day period – new report | Australian Broker Information

    SME

    Consumers’ pessimism eases a bit this thirty day period – new report

    Economist described some components affecting customers’ ideas concerning the general financial system

    Consumers' pessimism eases a bit this month – new report

    SME

    By
    Noel Gross gross sales Barcelona

    The new Westpac–Melbourne Institute Client Sentiment Index report reveals that there was minimal development in customers’ sentiments towards the financial system, because it rose to 1.8% this June, or 83.6 proportion particulars (ppts) when in comparison with final month’s 82.2 ppts.

    “Despite the enhancement, shopper sentiment stays down under its March stage and nonetheless firmly in deeply pessimistic territory,” claimed Westpac senior economist Matthew Hassan (pictured beforehand talked about). Client sentiment statistically steps the final effectively being of a nation’s financial system primarily based on customers’ viewpoints.

    Hassan defined that, at 83.6, the Index stays successfully under” the “impartial” stage of 100, that means pessimists outnumber optimists by roughly 20ppts.

    “The research component implies positives from fiscal steering measures are remaining negated by elevated worries about inflation and the outlook for curiosity costs,” Hassan claimed.

    The economist additionally mentioned that the new buyer sentiment index exhibits that data tales concerning the financial system have a deep results on customers’ perceptions referring to current Australia’s financial circumstance.

    “Two topic areas stood out in June: ‘funds and tax’ and ‘inflation’, with practically 50 % of [the] customers recalling data on every particular person of those,” Hassan mentioned. “On the previous, the knowledge was seen as considerably much less unfavourable than in March, reflecting the very well-received Commonwealth funds, the value-of-dwelling actions despatched by each of these Federal and state governments, and the section 3 tax cuts set to start on July 1. Even so, the knowledge on inflation was seen as a lot much less beneficial than in March, with assessments retracing a lot of the method once more to the quantities observed in December, when the RBA skilled simply raised the {dollars} cost in response to persistently increased inflation.”

    Hassan talked about the headline Client Sentiment Index is a composite and a mixture of 5 sub-indexes which might be based totally on responses to 5 exact issues. He defined these sub-indexes stage to a mix of pressures impacting consumers, improved assessments of relations funds, and purchaser sentiment offset by renewed issues concerning the financial outlook.

    “The ‘household funds vs a calendar yr in the past’ sub-index recorded a particularly highly effective 9.7% carry in June. Nevertheless, at 69.3 it stays at a extremely weak, deeply damaging stage. This sub-index would might want to rise by one more 20% simply to reach at its extended-run frequent stage, and by above 40% to get again to the ‘impartial’ diploma of 100,” Hassan acknowledged.

    “Similarly, the ‘time to acquire a key merchandise’ sub-index additionally recorded a steady 4.2% rise however remained at a very weak quantity of 79.7, effectively beneath its long-run frequent of 124.”

    Hassan reported that when pressures on partner and youngsters funds and shopping for potential are setting as much as simplicity, there’s a require for larger, double-digit positive aspects within the mentioned sub-indexes previous to we may begin off to say that these issues have convincingly subsided.

    Relevant Stories

    Hold up with probably the most up-to-date data and conditions

    Join our mailing guidelines, it’s completely free!

  • CoreLogic releases new building report

    CoreLogic releases new improvement report | Australian Broker Information

    Expense Loans

    CoreLogic releases new development report

    More than 1,300 assignments are within the pipeline

    CoreLogic releases new construction report

    Expense Financial loans

    By
    Noel Product gross sales Barcelona

    CoreLogic has launched its Cordell Design Regular month-to-month report for June, with 1,375 new duties in its pipeline, unfold all all through Australia, with $24.3bn in complete worth. This is whatever the acceleration of design charges, which in line with CoreLogic is only a “return to improvement.”

    According to the report, 29.7% of its ongoing jobs involved civil engineering, adopted by neighborhood jobs, comprising 23.3% of the total. Virtually 19% of the constructions staying constructed are flats and different housing models, although 15% are industrial infrastructure. Meanwhile, 2.8% of the new duties are linked to mining.

    When it is going to come to the challenge’s profit for each classification, civil engineering contains a lot of the pie – 69.3% of the $24.3bn. Flats and fashions got here 2nd, with an 11.8% share of the entire price range neighborhood duties accounted for 10.9% skilled 3.8% industrial 2.8% and mining 1.4%.

    “Nationally, 577 assignments moved into the design part in Could, up from 528 in April. The complete approximated advantage of these duties is $3.4 billion. The amount of duties shifting into design above the previous 3 months is 23.1% larger than the previous 3-month interval. New South Wales made up 27.6% of duties shifting into building in Might, adopted by Victoria (26.5%) and Queensland (19.6%),” the report acknowledged.

    Western Australia has 67 ongoing jobs, additionally in its improvement part. There are 20 ongoing initiatives within the Northern Territory, although Tasmania and the Australian Capital Territory (ACT) boast 18 and three ongoing duties, respectively.

    Some of the roles embody renewable power, which has been booming within the earlier two a number of years. Permits have presently been given to Neoen, Iberdrola Australia, TagEnergy and Mainstream Renewables Electric energy, and Someva Renewables joint ventures for the feasibility analyze of acquiring wind farms in some pine plantations within the Central West and Southern Inland places.

    Also, the building of the new Eurobodalla Regional Healthcare facility has been provided the inexperienced mild, with the State Considerable Development Software (SSDA) accredited for the challenge, with the monetary funding allocation of $260m by the NSW authorities. The draft thought system has additionally by now been produced for the preliminary interval of the University of NSW Canberra campus development, on governing administration-owned land in simply the Parliamentary Triangle, the report stated.

    With regards to mining, Castile Assets has been awarded a necessary enterprise place on the Rover Challenge by the Northern Territory Government, in accordance to the new report. In addition, Classic Minerals been given Mining Lease approval for the Forrestania Gold Job positioned 120 km South of Southern Cross in Western Australia.

    “Mining proposals and mine closure plans are to be submitted. The firm is hoping to start mining capabilities by 2024 – 2025 contingent on finishing the negotiation of the Mining Arrangement with Indigenous Title claimants, securing a lover with the requisite competencies and experience to optimise mining efficiency, the completion of replace from scoping evaluate to pre-feasibility analysis and getting all wanted governing administration approvals,” the report claimed.

    Harmony Gold skilled been awarded Prescribed Project Position at Eva Copper/Gold Job by the Queensland Govt, while Reward Minerals has withdrawn its bid to acquire the Beyondie Lakes Sulphate of Potash, the report acknowledged.

    Relevant Stories

    Maintain up with the latest data and events

    Sign up for our mailing checklist, it’s no value!