Tag: Real estate

  • Why competition in the housing marketplace is cooling off

    Goodboy Image Business | E+ | Getty Images

    Extra house homeowners are itemizing their properties on the market, however homes are getting longer to market as possible potential patrons cope with excessive charges and fascination premiums.

    New listings from dwelling sellers jumped in May probably, up 13% from a calendar yr again, in keeping with the latest market report by Zillow.

    “You have an improve in sellers coming once more on the sector,” claimed Orphe Divounguy, a senior economist at Zillow.

    Much more from Personal Finance:
    Here’s the inflation breakdown for Might 2024
    How a lot homeownership prices annually
    Biden and Trump each of these need to enhance tax cuts

    But with patrons not returning to the business, fairly just a few new listings are simply incorporating to stock. The amount of properties on the marketplace rose 22% in comparability with previous calendar yr, Zillow positioned.

    “Houses are remaining on the sector for a bit extra time for the motive that the product gross sales will not be holding up with the motion of properties approaching the market place,” Divounguy acknowledged.

    ‘The market place is slowing down’

    Virtually two-thirds, or 61.9%, of homes detailed on the sector in May nicely skilled been on the market for at minimal 30 occasions with out possible underneath contract, in accordance to a brand new evaluation by Redfin. About 40.1% of households that have been being on the market in May maybe skilled been talked about for at the very least two months with no possible beneath settlement, Redfin found.

    “The market is slowing down. Residences are utilizing for an extended time to advertise and that enables inventory to build up on the present market,” reported Daryl Fairweather, fundamental economist at Redfin.

    Housing is an area of concern for the economy, says David Waddell

    Yet inspite of the current bounce in provide, “we’re proceed to starved for inventory in the for-sale market place,” defined Divounguy. The housing inventory in the U.S. is nevertheless 34% beneath pre-pandemic phases, in keeping with Zillow.

    “We are restricted nationwide of about 4.3 million households,” he reported. “We’re even now in a housing unit deficit.”

    Homebuyers are ready round on cut back home mortgage prices

    As house mortgage expenses have remained superior and housing affordability has strained house funds, potential patrons have been unable to enter the market place, Divounguy acknowledged.

    “Purchasers are going by these extraordinarily substantial mortgage mortgage charges, at the very least relative to what they have been in the course of the pandemic,” talked about Fairweather, who believes homebuyers would possibly lack the motivation and financial ability to accumulate a residence.

    The 30-yr preset quantity house mortgage in the U.S. slid to six.95% on June 13, reduce from 6.99% a 7 days prior, in accordance to Freddie Mac information through the Federal Reserve. 

    While mortgage mortgage premiums may “remodel actually speedily” or “on a dime,” talked about Fairweather, purchasers are unlikely to see main motion in the close to time interval. The Fed held charges common at its June assembly and now anticipates only a single worth decrease this yr. Its following assembly is July 30-31.

    “There is definitely no right reply for homebuyers who’re deciding regardless of whether or not to attend or not,” Fairweather stated. “It is simply as much as likelihood when property finance mortgage prices drop. Nobody actually is aware of when that may materialize, so it may be powerful to program your life-style all-around that.”

    What to do when you occur to be a purchaser or a vendor

    Some markets in the U.S. are taking a look at a major enhance in unsold inventory. About 60.5% of listings in Dallas, Texas, stayed on the marketplace for at minimal 30 occasions, up from 53% a 12 months earlier than, in keeping with Redfin.

    In Fort Lauderdale, Florida, the share of unsold listings which have stayed on the marketplace for at the least 30 days is 75.5%, up from 68.2% a yr prior, Redfin discovered.

    A really related enhance is occurring in two different areas in Florida. The share of unsold properties in Tampa which have been on the sector for 30 days is 68.7%, up from 61.9% a yr in the past in Jacksonville, 69.2%, up from 62.9% in the related interval, for each Redfin details.

    “When you give potential patrons extra alternatives, that signifies they’ve extra bargaining electrical energy,” Divounguy reported.

    If you acknowledge homes on the market linger on the present marketplace for for an extended interval in your spot, “there is definitely nearly definitely an risk to get [a property] for lower than its talked about price,” Fairweather acknowledged.

    If you make it into the family inspection process and also you study considerations that have been neither recognizable all through the unique walkthrough nor disclosed, it might be worth asking the property vendor to do repairs, she reported. 

    But actually do not overdo it: “You don’t need to be nit-picky and speak to for each single single restore service,” these sorts of as chipped paint, Fairweather talked about. 

    Other marketplaces are nevertheless in favor of residence sellers as stock continues to be restricted, Divounguy stated. Not solely do a number of house owners have document residence equity, in addition they have decrease home mortgage funds.

    If a residence vendor must shift this yr as a consequence of upcoming day by day life alterations and their house is experiencing excessive ranges of unsold listings, they might need to be ready to decrease their asking value to draw curiosity.

    “Cost cuts market residences,” he defined.

  • You don’t require a 20% down payment to get a residence, economist suggests

    Phynart Studio | E+ | Getty Photographs

    Coming up with the down payment as an aspiring home proprietor might be a sophisticated process. Numerous have at the moment began doing the job towards that goal.

    About 77% of foreseeable future homebuyers have begun putting cash apart for a down payment, in accordance to a new survey by Intelligent.com, a housing and actual property examine web website.

    Much more than 50 % (57%) of attainable customers program to put a lot lower than 20% down, the report recognized. The survey polled 920 fashionable and impending homebuyers in early April.

    Customers might presumably try to set extra funds down to keep away from property finance mortgage insurance coverage protection costs and even reduce common month-to-month funds, however 20% is “unquestionably not required,” talked about Danielle Hale, chief economist at Realtor.com.

    Additional from Individual Finance:
    This retirement account might be ‘triple-tax environment friendly’ for youngsters this summer season
    College pays, however outcomes for employees with out having a diploma are bettering upon
    Lawmakers dialogue whether or not child reductions accounts can reduce wealth inequality

    In the primary quarter of the calendar yr, the peculiar down payment was 13.6%, up from 10.7% within the initially quarter of 2020, in accordance to Realtor.com.

    The typical down payment for initial-time homebuyers was 8% in 2023, compared to 19% for repeat clients, centered on transactions from July 2022 to June 2023, in accordance to a examine from the Nationwide Affiliation of Realtors.

    Even at new elevated ranges, the typical down payment is nonetheless correctly beneath 20%, a share that women and men often think about of because the gold typical when acquiring a family.

    “By no signifies is that this successfully the regulation of the land,” talked about Mark Hamrick, senior monetary analyst at Bankrate.com.

    ‘The conundrum of the housing market’

    1 method to decrease your month-to-month property finance mortgage payment is by putting down a lot extra money and borrowing a lot much less. But for a lot of properties, striving to accumulate a greater down payment might be onerous, Hale acknowledged.

    “It genuinely showcases the conundrum the housing present market is in the place you can see not a ton of affordability,” she claimed.

    Obtaining ample financial savings for a down payment is a giant hurdle for many potential patrons. Near to 40% of Americans who won’t private a residence place to a absence of worth financial savings for a down payment as a rationale, in accordance to a 2023 CNBC Your Income Survey completed by SurveyMonkey. Far greater than 4,300 grownups within the U.S. ended up surveyed in late August for the report.

    Most homebuyers don’t set down 20%

    Soaring home charges make that 20% goal particularly daunting. But the actual fact is, you by no means want 20%, gurus say.

    Nationally, the everyday down payment on a residence is nearer to 10% or 15%, Hale talked about. In some states, the typical could be very properly beneath 20% although some are even beneath 10%, she included.

    “Not solely is it doable to purchase a family with fewer than 20% down, however this data clearly present that a larger a part of purchasers are in easy reality doing so,” Hale acknowledged.

    Compass CEO Robert Reffkin on housing market: We are now seeing 'more sellers than buyers'

    Some monetary loans and packages are on the market to assist fascination potential patrons order homes by means of lowered down funds.

    For instance, the Section of Veterans Affairs options VA mortgage techniques that permit those that qualify to place down as little or no as %. Financial loans from the U.S. Division of Agriculture, referred to as USDA loans, are geared in the direction of serving to clients spend money on homes in further rural places, and so they additionally present % down payment prospects.

    Federal Housing Administration loans, which might demand as small as 3.5% down for qualifying debtors, are supplied to 1st-time potential patrons, reduced- and reasonable-money patrons, as properly as customers from minority groups. Individuals are “designed to help shut homeownership gaps amongst folks certified populations,” Hale stated.

    Even with a conventional mortgage, patrons’ obligatory down payment may very well be regarding 3% and 5%, counting on their credit score rating and different issues.

    “There are alternatives,” Hale stated.

    A smaller down payment can include further charges

    When you could be deciding how a lot of a down payment you’ll be able to handle, tread completely: There might be further bills linked with scaled-down upfront funds. Even although a reduce down payment is 1 method to “assault affordability challenges,” it may be a “blended bag,” Hamrick stated.

    With a lowered down payment, you want to borrow rather more out of your monetary establishment, which raises the each month expense of your own home mortgage, Hale acknowledged. A scaled-down down payment may imply you actually don’t qualify for a lender’s greatest-accessible curiosity worth.

    When you borrow rather more than 80% of a house’s worth, you might also face the included worth of personal home mortgage protection, or PMI.

    PMI, often, can expense anyplace from .5% to 1.5% of the mortgage sum for every calendar yr, counting on variables like your credit standing rating and down payment amount, in accordance to The Property finance mortgage Reviews.

    For illustration, on a private mortgage for $300,000, home mortgage insurance coverage coverage charges might expense all-around $1,500 to $4,500 on a yearly foundation, or $125 to $375 a month, the web page uncovered.

    Generally, your lender will cancel your property finance mortgage insurance coverage immediately as quickly as you attain 22% fairness. You can request it to be eradicated proper after you entry 20% fairness.

    In some circumstances, purchasers might properly pick to do what’s referred to as a “piggyback mortgage,” or get a 2nd home mortgage to meet up with the 20% threshold and never have to spend for house finance mortgage insurance coverage protection, Hale stated.

    But, that 2nd mortgage tends to have a bigger mortgage worth, she acknowledged.

  • Ray White appoints new GM

    Ray White appoints new GM | Australian Broker News

    Information

    Ray White appoints new GM

    The new rent strikes to the Sunshine state from Melbourne

    Ray White appoints new GM

    Authentic property expert Troy Sheehan has joined Ray White Sherwood-Graceville as its new basic supervisor.

    Bringing much more than 20 a very long time of data, Sheehan goals to raise the small enterprise in Brisbane’s western suburbs.

    “I’m experiencing my job extensively, functioning together with a beautiful group of true property gurus,” he defined.

    Making a robust foreseeable future

    Sheehan, a accredited auctioneer with a confirmed observe report in rising affluent genuine property companies, will get the job performed on refining workplace setting efficiencies and driving product gross sales and residence administration effectivity.

    “I fell in actually like with the variability inside our core market of Sherwood and Graceville,” he talked about.

    Welcomed by the Ray White crew

    Cameron Crouch, Ray White Sherwood-Graceville principal, expressed his pleasure about Sheehan’s appointment.

    “His in depth expertise and examined means to drive transformative modify could make him the proper in form for our eyesight of development and enlargement,” Crouch defined. “With Troy on the helm, we’re assured in our ability to reach at new heights and understand unparalleled good outcomes.”

    Get the very best and freshest mortgage info shipped acceptable into your inbox. Subscribe now to our FREE every day publication.

    Relevant Tales

    Continue to maintain up with the latest info and gatherings

    Be a part of our mailing guidelines, it’s no value!

  • Home transforming projects that strengthen curb attraction fork out off the most

    Personal Finance Tips 2024: Affording a Home

    Dwelling renovation motion could nicely have cooled considerably when in comparison with its pandemic-period frenzy, however property house owners are nonetheless investing of their areas, notably as the spring housing sector heats up.

    And when it arrives to the return on monetary dedication, some projects now provide the optimum return values in file — with a lot of property upgrades averaging returns of practically 200% for the first time at any time — in accordance with the 2024 Price tag vs. Worth report from Zonda Media, a housing sector examine and analytics enterprise.

    Garage door replacements made out there the biggest common return at 194%, adopted by upgrading to a metal entrance door, with a 188% return on monetary funding — each of these worth nearly double what they ended up final calendar 12 months, the report noticed. 

    Curb enchantment is vital

    Fail to recollect a designer chef’s kitchen, the assignments giving the best returns in resale worth are primarily related to suppress attraction reasonably than further glamorous kitchen space and bathtub remodels, in accordance to Zonda’s report.

    In easy truth, 9 out of the main 10 projects with the greatest return on funding had been exterior development assignments, the report found.

    “When it arrives to including resale value to a dwelling, exterior substitution projects proceed to make the most feeling,” Clay DeKorne, chief editor of Zonda’s JLC Group, claimed in a press release.

    Nevertheless, with mounting costs for design labor and creating components, not each particular person will get their cash’s actually value in improved property worth.

    Only 3 projects on Zonda’s itemizing can normally provide even a 100% return on monetary dedication, equivalent to altering the storage doorways, upgrading to a metal entrance door and putting in a stone veneer.

    “Discretionary assignments like an upscale bathroom or kitchen rework will expertise worthwhile to people who make the options however is not going to ship nearly as so much return to sellers,” DeKorne claimed.

    Much more from Own Finance:
    A 20% residence down cost is not actually ‘the laws of the land’
    Your home sale might trigger money positive aspects taxes
    Fewer homeowners are transforming, however want is proceed to ‘stable’

    A insignificant kitchen space rework — this sort of as portray and updating the backsplash — did provide greater returns, at 96% of prices recouped. But vital upscale kitchen and loo remodels didn’t, the Zonda examine noticed, with returns of 38% and 45%, respectively.

    “Performing excessive priced updates on the kitchen space normally are usually not heading to pay out off,” talked about Angelica Ferguson VonDrak, an affiliate true property dealer centered in Rhinebeck, New York.

    ‘Un-pretty upgrades are much more vital’

    With excessive dwelling costs and a restricted provide of residences on the market, sellers require to be primarily strategic of their endeavours to catch the consideration of the shoppers able to spend high rated buck in at the moment’s market, in accordance with Todd Tomalak, Zonda’s principal of creating merchandise and options exploration.

    Additional, financing renovations or enhancements with a property equity private mortgage or dwelling fairness line of credit score have gotten further high-priced alongside with the Federal Reserve’s string of 11 price hikes since 2022, along with 4 previous yr.

    “A brand new storage door or new entry door could make a pronounced distinction,” Tomalak talked about. “It might be the element that could make one dwelling stand out in direction of all the others, producing the dwelling actually value the next price.”

    Suppress enchantment is significant in having the perfect worth from the correct potential purchaser.

    Dreampictures | Photodisc | Getty Images

    To get the most efficient bang on your buck, talk to an actual property agent in your home about specific renovations that would possibly enhance the value of your home and which sorts to skip, VonDrak suggested.

    In some areas, putting in a pool might pay out off threefold, in different spots, this form of a hefty expense can fall flat, she talked about.

    “The un-alluring updates are extra essential,” VonDrak reported, these as an HVAC conversion (changing a fossil-gasoline-burning furnace or boiler with an electrical heat pump) or a brand new roof or dwelling home windows.

    And typically, a complete cleaning can go a intensive approach, VonDrak stated. “Absolutely decluttering and swapping out outdated dwelling furnishings for brand new or incorporating slipcovers,” she reported. “You need each factor to really really feel contemporary new and new.”

  • Below are critical issues to know in advance of you obtain a house abroad

    Courtneyk | E+ | Getty Illustrations or images

    Home loans, foreign money change complicates a order

    Although there may very well be similarities to the U.S. market place when searching for a dwelling abroad, there are additionally one of a type troubles on the financial facet of the make investments in.

    In many circumstances, Individuals buying attributes abroad shut up financing the transaction with earnings outright, professionals say. If you do need to finance your house purchase, consider the alternatives to take into account how usually you could maybe be uncovered to curiosity degree alterations.

    That’s primarily as a result of property finance mortgage constructions in worldwide worldwide places are a lot extra possible to have variable prices, or quick phrases in the event that they are set-rate loans. It is uncommon to come throughout financing choices associated to the 30-year mounted value property finance mortgage, which is a “extraordinarily American phenomenon,” defined Boudreaux, a member of the CNBC Economical Advisor Council.

    A quarter of America's ultra-rich plan to buy a home this year: Douglas Elliman Knight Frank report

    You even have to be conscious of the commerce price on the worldwide foreign money you can be transacting with, as completely as the value to commerce your U.S. {dollars}. Fluctuations in premiums, and the variations in banks’ premiums and costs, could make a substantial variance in how significantly your bucks go.

    A monetary establishment wire is usually the “the very least excessive priced approach” to change foreign money, and with a enormous adequate lender, they are going to have companies that may lower the worth of the worldwide switch, like a favorable change cost, mentioned Boudreaux.

    But in most situations, the U.S. purchaser will want to have to open a monetary establishment account in the state they are searching for actual property. And that course of will not be often straightforward.

    For one explicit, a number of banks will refuse to function with U.S. residents given that the Financial establishment Secrecy Act of the U.S. includes overseas entities to report property, he described.

    Smaller, regional monetary establishments may presumably not be outfitted to take care of that reporting, so U.S. residents will usually want to have to request bigger institutions, Boudreaux included.

    Ahead of you obtain a house outdoors the house of the U.S., it may be additionally essential to make constructive you have a obvious {photograph} of what you will use it on your tax duties to the abroad place and the U.S. could presumably alter depending on that reply.

    Here are a few methods business consultants advise you take into account earlier than you come to be a home-owner abroad:

    1. ‘Do a nice deal of as a result of of diligence’

    When you go to the metropolis or metropolis the place you need to obtain, make sure to stroll about a great amount, defined Bojan Mujcin, a true property affiliate of Sotheby’s International Realty in Barcelona and Costa Brava, Spain.

    “Get acquainted with the town, get frequent with the streets … do a complete lot of as a result of of diligence,” Mujcin reported.

    Rent in that location for a appreciable time to get a notion of the put earlier than you “make investments in some factor on a want,” mentioned Boudreaux. Performing so may give you a higher feeling of what it truly is like to stay in a place.

    You additionally could effectively need to take into accounts the nation’s political surroundings, as it may be vital for the long-time interval expenditure profit of your property, said Erin Boisson Aries, a international luxurious precise property advisor of Douglas Elliman.

    “Fewer spontaneity and extra analysis is significant,” she talked about. “It is admittedly great to go on household trip and have a glorious time, however the long-expression geopolitical safety may be very important.”

    Boudreaux agreed: “There is political menace … and now we have to be ready for what that will presumably entail for our investments.”

    2. ‘Understand what your calls for are’

    It can be important for you to “have an understanding of what your requires are,” Boisson Aries talked about.

    “Is this an funding resolution? Are you arranging to retire there? Are you organizing to go to and rent it out?…You have to genuinely notice the ecosystem you’re buying into,” she said.

    For illustration, if you system to lease out the house for extended- or brief-term stays, “zoning fairly considerably variables into that,” Boisson Aries mentioned.

    Policies that verify what areas are appropriate for quick-expression leases can change in extra of time, Boudreaux talked about.

    “Getting these direct homes for that purpose is a few factor that arrives with considerably way more threats than of us know,” he talked about.

    And if you do come to a resolution to use the property for rental or skilled use, you could effectively have further tax burdens in that nation, Boudreaux defined.

    3. Contact neighborhood consultants and expat communities

    “Make certain you have space specialists and consultants advising you” when buying in housing marketplaces exterior of the U.S., reported Boisson Aries. “There are so fairly a few variables that have an effect on nearly each purchase.”

    This kind of variables or issues can consist of possession rights, zoning implications and monetary dedication choices, she reported.

    “You may go round and slide in actually like with the house, however with no really figuring out the general business, all of the opposite implications to acquiring and possession, you occur to be flying a tiny blindly,” she mentioned. “Just as we’re business consultants and advisors on the ground in Manhattan … you genuinely do require that quantity of talents on the bottom.”

    Converse with a approved advisor in the overseas place who might help navigate tax issues and different issues you could effectively have, Sotheby’s Mujcin claimed.

    “You undoubtedly usually require to have some authorized help from some selection of legislation agency in the transaction,” he claimed.

    Uncover out if you can discover an expat neighborhood in the state you may be in shopping for into, Boudreaux said.

    Usually it would consist of different People in america who’ve lengthy gone by way of a associated course of who can ship suggestions and assets, he further.

  • This is why new residence sales inch bigger despite 7% house loan charges

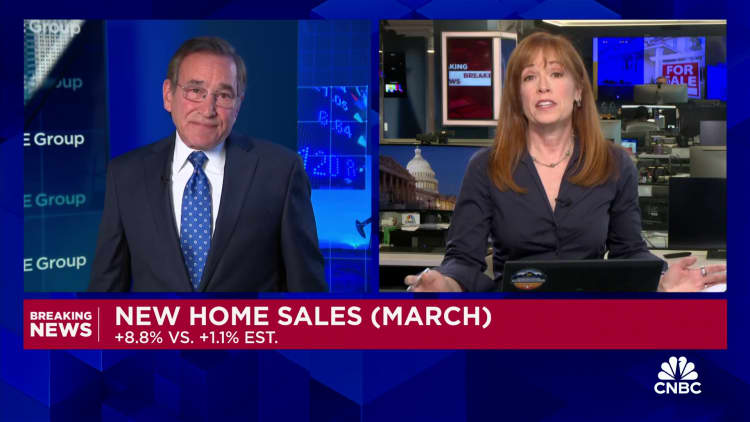
    March new home sales beats expectations despite weak inventory

    Although the spring housing market has been plagued with small supply, massive promoting costs and spiking want premiums, would-be homebuyers are concentrating on new design. 

    The objective? New houses have much more incentives and availability than earlier owned sorts.

    “There is far more probability in new design,” claimed Nicole Bachaud, a senior economist at Zillow Group.

    About 693,000 new single-household residences had been offered in March, up 8.3% from a calendar yr again, in accordance to the U.S. Census Bureau and the U.S. Section of Housing and City Progress. The median revenue fee was $430,700, the businesses noticed.

    Meanwhile, product sales for beforehand owned houses dropped by 3.7% from March 2023, the National Association of Realtors found.

    Far extra from Particular Finance:
    Potential patrons of freshly constructed houses can confront a house tax shock
    This is what to do in case you skipped the federal tax deadline
    Biden believes new scholar private loan forgiveness put together will endure

    Many areas within the U.S. confront a minimal stock of current properties because the mortgage price lock-in impact, or the golden handcuff, retains “present proprietors from turning into sellers,” Bachaud spelled out.

    With 30-year preset-price residence finance loan charges sitting beforehand talked about 7%, householders who acquired at an awesome deal decrease premiums within the newest a number of years is not going to just like the prospect of shopping for and promoting of their decrease fee for a greater only one.

    Meanwhile, purchasers are turning to builders, who’re typically much more adaptable with pricing. Homebuilders present prospects incentives like worth acquire-downs and worth cuts. Homebuilders may even pay again for closing expenditures, specialists say.

    “This has been serving to incentivize some potential potential patrons to alter to the new property income present market,” said Matthew Walsh, assistant director and economist at Moody’s Analytics.

    New create price ticket hole narrows

    Although new builds are however provided for considerably far more than current homes, the price gap has considerably narrowed contemplating that the slide.

    “Charges are considerably nearer to parity than by means of any level within the final a couple of a long time,” Walsh talked about.

    In extra of the previous 6 months, the median worth for a new residence is solely about 4% greater than the median worth of an current residence. That stage is considerably decreased than forward of the pandemic when the median value of a new residence was far more than 40% bigger than an present house, Walsh said.

    “On the present aspect, you might have this type of a restricted present on the market,” he reported. “But on the new households side, you might have builders prioritizing transaction volumes in extra of margins.”

    In the sooner, price-delicate prospects with tighter budgets had been restricted to the present residences market. Today, prospects who stay trying might presumably have much more options on the new family gross sales side.

  • Mavridis duo joins Ray White Zoom team

    Mavridis duo joins Ray White Zoom group | Australian Broker News

    News

    Mavridis duo joins Ray White Zoom group

    Transition in Burwood real property

    Mavridis duo joins Ray White Zoom group

    Ana and Spiro Mavridis (pictured beforehand talked about, remaining to correct) have inaugurated the Ray White Zoom group in Burwood as a part of a strategic imaginative and prescient to extend their skilled companies.

    “Joining crucial real property company in Burwood aligns completely with our goals,” Spiro reported.

    Developing on a secure foundation

    With 20 years of expertise in genuine property, Spiro leads the operational facet of the enterprise, when Ana focuses on steady development and leveraging their mixed strengths.

    “We get the job accomplished laborious and luxuriate in to only about each different’s strengths,” Ana reported. “Finding our stability and refining our procedures has been integral to our outcomes.”

    The Mavridis duo shouldn’t be solely remodeling their model affiliation but additionally maximizing their supplier choices. They are rising their team, with a faithful head of home administration and an increasing product sales workers aimed toward delivering higher value to shoppers.

    “We have a giant lease roll and are very happy to have a devoted head of home administration,” Spiro stated. “Additionally, we’re actively increase our income group to carry even much more value to the desk for our prospects.”

    Tim Snell, CEO of Ray White NSW, expressed his enthusiasm for his or her addition.

    “Ana and Spiro depict the upcoming of Ray White within the NSW team,” Snell stated. “Their dynamic and floor breaking technique that has discovered their achievement as an neutral units the incredible foundation of which to now scale and broaden right into a small enterprise utterly able to broaden into the larger area.

    “With a goal on making an environment for buying nice brokers we look forward to taking a look at this enterprise enterprise obtain its potential.”

    Get the most effective and freshest dwelling mortgage information despatched right into your inbox. Subscribe now to our FREE on daily basis publication.

    Hold up with the latest info and events

    Be a part of our mailing guidelines, it’s completely free!

  • Mortgage loan costs hit optimum stage of the 12 months, and could go even larger

    Households in Rocklin, California, on Tuesday, Dec. 6, 2022.

    David Paul Morris | Bloomberg | Getty Images

    The typical value on the widespread 30-yr preset property finance loan crossed about 7% on April 1, in accordance to Home loan News Day-to-day, and it simply stored going. It now sits appropriate all-around 7.5%, the biggest stage contemplating that mid-(*12*) of earlier yr.

    Prices strike their highest diploma in a pair of a few years earlier Oct, producing residence product gross sales to grind to a halt. Builders jumped to buy down costs for his or her consumers and managed to do much better than current dwelling sellers.

    Prices then fell through mid-January to the mid-6% array and held there into February, making a surge in residence gross sales. But then they started rising once more.

    “By mid-February, a choose-up in inflation reset expectations, placing residence loan prices again once more on an upward craze, and extra newest information and feedback from Fed Chair [Jerome] Powell have solely underscored inflation fears,” mentioned Danielle Hale, predominant economist for Realtor.com. “Revenue particulars above the future couple of months is more than likely to mirror the impact of now-increased mortgage loan charges.”

    March home sales dropped despite a surge in supply: Here's what you need to know

    Even with prices elevated, nonetheless, residence finance loan purposes to buy a dwelling rose 5% earlier week as opposed with the prior week, in response to the Mortgage loan Bankers Association’s seasonally adjusted index. Demand was even now 10% cut back than the exact same week only one yr again, even with costs now 70 basis factors higher than they have been being a yr in the past.

    “Regardless of these greater premiums, utility motion picked up, probably as some debtors made the determination to behave in state of affairs charges keep on to extend,” claimed Joel Kan, MBA’s chief economist.

    That might maybe be quick-lived, nonetheless, as affordability weakens even extra. Although there’s much more present on the sector now than there was a yr again, it’s even now at a extremely very low diploma historically. That has introduced on properties to maneuver quicker as the ranges of competitors boosts. Anybody ready round for prices to fall significantly could be ready for a even although.

    “The newest financial information reveals that the monetary system and activity market proceed being stable, which could be very prone to protect mortgage premiums at these elevated ranges for the in the neighborhood of future,”  mentioned Bob Broeksmit, MBA’s president and CEO.

    Don’t skip these exclusives from CNBC Pro

    Thursday’s most necessary analyst telephone calls: Tesla, Nvidia, Apple, Amazon, eBay, Zoom, JetBlue, BJ’s & moreIf you’re apprehensive a few correction and around-invested in Nvidia, trade it with these regular progress shares as a substituteIt could be time for merchants to market Nvidia on the up coming bounce, in accordance to the chartsWall Avenue is bullish on copper, many because of AI. Analysts actually like these shares, giving an individual 234% upside’Hard to Ignore’: Jefferies says this cybersecurity stock could double quickly after 75% improve in the earlier yr A four-working day get the job finished week could be coming as AI proliferates — and these organizations could capitalize

  • President Biden floats $10,000 first-time homebuyers tax credit

    Cavan Illustrations or pictures | Cavan | Getty Visuals

    President Joe Biden has floated packages to deal with the nation’s economical housing issues, which incorporates new tax breaks for 1st-time homebuyers and “starter dwelling” sellers. On the opposite hand, trade consultants have blended ideas on the proposals.

    “I do know the worth tag of housing is so important to you,” Biden acknowledged all via his Condition of the Union speech Thursday night.

    “If inflation retains coming down, residence finance mortgage costs will come down as very nicely. But I’m not ready,” he mentioned.

    Additional from Wise Tax Organizing:

    Here’s a look at extra tax-organizing information.

    How the homebuyer, ‘starter residence’ sale credit rating performs

    Biden has proposed a “home mortgage discount credit historical past” of $5,000 for annually for 2 yrs for center-class, initial-time homebuyers, which might be equal to reducing the mortgage curiosity charge for a median-selling worth dwelling by 1.5 share factors for 2 a very long time, in accordance to an outline unveiled by the White Household on Thursday.

    The administration can be contacting for a simply one-12 months credit of as much as $10,000 for center-class individuals who supply their “starter residences” to 1 extra owner-occupant. They outline starter properties as properties down under the median promoting worth for the vendor’s county.

    U.S. President Joe Biden offers the State of the Union deal with within the Residence Chamber of the U.S. Capitol in Washington, D.C., on March 7, 2024.

    Pool | Getty Pictures Information | Getty Photos

    “Lots of residence homeowners have cut back premiums on their mortgages than current charges,” the White House reported. “This ‘lock-in’ outcome helps make owners much more hesitant to supply and quit that small stage, even in state of affairs the place by their present-day residences no for an extended interval match their home requires.”

    Even so, it truly is difficult to forecast regardless of if Biden’s proposal will progress all via a presidential election 12 months, particularly with a break up Congress, gurus say.

    Desire charges nevertheless close to ‘multidecade highs’

    With hovering residence promoting costs and mortgage mortgage rates of interest, 2023 was the minimal cost-effective yr for homebuyers in extra than a ten years, in line with a report from Redfin.

    In 2023, all these incomes the median U.S. cash of $78,642 would have expended 41.4% of earnings by buying a median-cost residence at $408,806, up from 38.7% in 2022, the report uncovered.

    Although costs have fallen from 2023 peaks, the common fascination quantity for 30-12 months set-charge mortgages was nevertheless hovering about 7%, as of March 7.

    “We’re near multidecade highs for mortgage costs,” reported Keith Gumbinger, vice chairman of property finance mortgage web site HSH.

    “Except [Biden’s proposed credit] counts as qualifiable money move, it isn’t going to primarily make it more easy for homebuyers to qualify for residence loans,” he reported.

    2024 Tax Tips: IRA contributions & deadline

    There’s a ‘housing provide disaster’

    Of research course, greater mortgage curiosity premiums are just one specific piece of the nation’s economical housing puzzle.

    “The housing supply catastrophe has been making, genuinely, as a result of the Fantastic Economic downturn,” defined Janneke Ratcliffe, vice chairman for housing finance plan and chief of the Housing Finance Plan Centre on the City Institute.

    The housing present disaster has been making, genuinely, as a result of the Excellent Recession.

    Janneke Ratcliffe

    Vice president for housing finance plan on the City Institute

    Considering that the monetary disaster, there was a “improbable storm” of issues for the nation’s housing supply, reminiscent of declines in new property constructing, she talked about.

    “What we by no means will want as of late within the present market is way extra demand,” claimed Gumbinger. “We have a great deal of want, however we actually haven’t got enough supply.”

    Nonetheless, Ratcliffe claimed she was happy to see housing affordability highlighted in the middle of the Condition of the Union speech. “I really feel this can be a nice beginning off stage,” she defined.

    Never cross up these exclusives from CNBC Professional

  • Weekly home finance loan demand jumps once more, as curiosity premiums fall underneath 7%

    Weekly mortgage demand jumps again

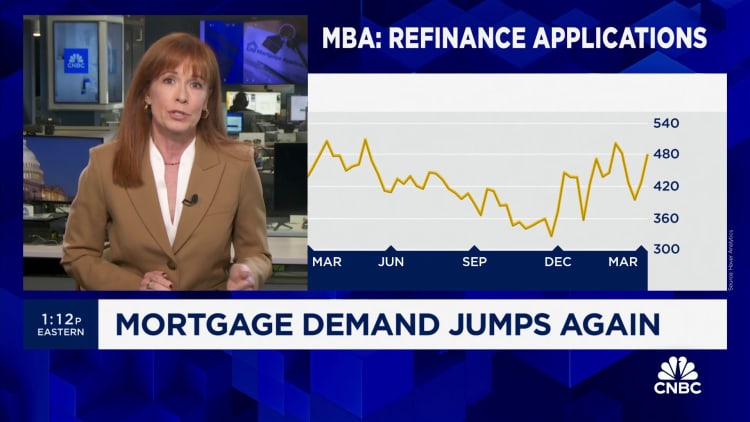
    Mortgage charges swung a bit decrease previous 7 days, fueling a considerable leap in property finance loan want for the 2nd straight week. Complete software program quantity rose 7.1%, as opposed with the previous week, in accordance to the Mortgage Bankers Association’s seasonally modified index.

    The frequent contract curiosity quantity for 30-year fastened-price home loans with conforming loan balances ($766,550 or lots much less) diminished to six.84% from 7.02%, with particulars falling to .65 from .67 (which embrace the origination cost) for loans with a 20% down cost.

    “House loan charges dropped underneath 7% final 7 days for many financial institution loan types merely due to incoming financial knowledge demonstrating a weaker firm sector and a fewer sturdy place present market, with an enhance within the unemployment fee and downward revisions to job progress in prior months,” stated Mike Fratantoni, senior vice chairman and major economist on the MBA.

    As a finish consequence, packages to refinance a family private loan, that are most delicate to weekly quantity strikes, rose 12% for the week and have been 5% bigger than the precise 7 days a single 12 months again.

    “Even although these share will improve are massive, the quantity of refinance motion stays fairly small, and we rely on that the majority of this train shows debtors who took out a private loan at or close to the height of costs within the earlier two years,” added Fratantoni.

    Purposes for a home loan to buy a dwelling rose 5% for the 7 days however ended up proceed to 11% decreased than a 12 months previously. Homebuyers are up from far more than simply vital need charges. They are sky-significant residence promoting costs and a even now lean provide of homes on the market. Although further inventory is approaching to the present market with the spring season, it isn’t ample to satisfy the need, specifically for scaled-down, starter properties.

    Home finance loan expenses rose just a little bit at first of this 7 days, simply after a federal authorities report on purchaser costs arrived in bigger than envisioned Tuesday. However, the improve was smaller than previous reactions to comparable monetary data.

    “It suggests {the marketplace} is beginning as much as see extra convincing indications that inflation and the general economic system stand a a lot better probability present amount-pleasant data within the within the neighborhood of upcoming as against information that might set off an enormous resurgence,” talked about Matthew Graham, chief working officer at Mortgage News Daily.

    Don’t skip these exclusives from CNBC Professional