Tag: program

  • FHA makes long-awaited changes to 203(ok) program

    A long-awaited improve for the Federal Housing Administration’s 203(ok) program has lastly hit the books, as its mother or father company issued a mortgagee letter detailing changes designed to improve use.

    “The changes we’re saying right now for the 203(ok) program are lengthy overdue and can help higher use of this program the place it’s wanted most – in neighborhoods the place houses are inexpensive however want restore,” stated Federal Housing Commissioner Julia Gordon in a press launch “Increased use of 203(ok) mortgages will assist modernize and revitalize houses, which helps inexpensive housing provide and strengthens neighborhoods.”

    Gordon was talking throughout a Philadelphia occasion at a house rehabbed utilizing the mortgage.

    Mortgage and actual property trade teams had requested changes to the program so as to make it extra possible to put it to use.

    In July 2022, the Department of Housing and Urban Development held a background briefing with the media promising to make updates to the 203(ok) program.

    While it is an necessary product for housing rehabilitation and renovation, it hasn’t been modernized in fairly a while, and its makes use of have remained slim, an official elaborated through the briefing.

    Originations had been shut to $4 billion in 2011, however fell to $1.31 billion by 2022.

    However, when it’s used, the 401(ok) has helped create homeownership alternatives, similar to this case in San Diego the place two unrelated and never romantically concerned folks had been in a position to collectively buy a home that they had been renting, in some of the costly markets within the nation.

    Some of those changes had been proposed in November 2023.

    The revisions have an effect on each the restricted 203(ok) and the usual model.

    Among different changes, FHA elevated the restricted 203(ok) complete rehabilitation price to a most of $75,000 from $35,000.

    It additionally created an annual evaluate course of for updating the utmost complete rehabilitation price for the restricted product.

    The rehabilitation interval was prolonged to 12 months for the usual 203(ok) and 9 months for the restricted.

    Mortgagees are actually in a position to improve the variety of months of financeable Mortgage Payment Reserves for the usual model.

    Early response from the mortgage trade has been constructive.

    “We help FHA’s enhancements to its 203(ok) program and commend them for together with most of the suggestions we highlighted in our January 2024 letter, together with growing the rehabilitation disbursement cap to $75,000 on a nationwide foundation for the Limited program, and increasing completion timelines to higher replicate present market circumstances and guarantee initiatives are accomplished,” stated Pete Mills, senior vp of residential coverage for the Mortgage Bankers Association, in an announcement. 

    “These changes will assist return older, dilapidated houses into owner-occupied housing inventory, and assist first-time consumers compete with fix-and-flip traders,” he added.

    The Community Home Lenders of America additionally was supportive of the changes, “as it’ll drastically strengthen housing affordability measures, particularly amongst first-time and low to average revenue debtors,” stated Scott Olson, government director, in an announcement.

    “CHLA has been a robust advocate for increasing the FHA program’s scope to consider price advances,” Olson continued. “We are inspired to see such enhancement initiatives, which make the program extra enticing for homebuyers utilizing FHA loans and contractors.”

    National Mortgage News reached out to HUD and a few 203(ok) lenders however these requests had not been answered by publication time.

  • FHFA approves controversial Freddie next lien program

    The controversial Freddie Mac next lien receive pilot has obtained conditional acceptance by the Federal Housing Finance Company.

    This proposal, which Freddie Mac officers posited as an choice to income-out refinancings in the next want value environment, created concern from opponents that it places the federal government-sponsored group in an location served by the personal market place.

    In the course of the comment interval, which ended on May nicely 22, the FHFA acquired 150 letters.

    “The thoughtful engagement from basic public stakeholders verified the advantage of a transparent course of for analyzing possible new Business merchandise and educated the parameters of the conditional approval,” reported Sandra Thompson, the FHFA’s director, in a press launch and accompanying assertion.

    “The restricted pilot will permit for FHFA to analyze regardless of whether or not this closed-finish 2nd property finance mortgage merchandise proficiently improvements Freddie Mac’s statutory purposes and advantages debtors, notably in rural and underserved communities.”

    Among the the boundaries FHFA confirmed are a $2.5 billion biggest in private mortgage buys, greater than an 18-thirty day interval interval. The particular person mortgage prohibit is $78,277, which FHFA reported corresponds to subordinate lien thresholds confirmed within the licensed residence mortgage definition.

    The 1st residence finance mortgage must have 24 months’ seasoning and it needs to be for the borrower’s most vital residence.

    Just after the 18-month time interval ends, the FHFA will consider the knowledge to determine regardless of whether or not the targets of the pilot have been fulfilled. Any possible maximize to the amount restrict or extension of the interval, or conversion to programmatic exercise could be handled as a brand new resolution that’s matter to basic public observe and remark and FHFA approval.  

    The accompanying assertion reaffirmed a perception that even quite a few opponents held, that Freddie Mac is in a position to do that beneath its structure.

    Furthermore, the restrictions be sure that personal money is just not crowded out. It additionally extends the means to accumulate next residence loans to underserved markets.

    The early response has been blended. Christopher Whalen, whose Whalen International Advisors, submitted a comment letter opposing the plan, reported most people within the subject envisioned the Biden Administration to go ahead inspite of the substantial neighborhood opposition.

    “Like the modifications created by the FHFA to the [loan level pricing adjustments] grid, the impression of this modify can be modest for the enterprises and unfavorable for people,” Whalen talked about in an emailed remark. “Reduced-money debtors are significantly significantly better served within the FHA/VA/USDA market place,” referring to the three authorities-guaranteed residence mortgage methods.

    The U.S. Home finance mortgage Insurers additionally opposed acceptance of the pilot, however took a conciliatory tone in its assertion.

    “Even although right now’s announcement contains vital limitations to the pilot, extra clarifications should be provided like on how mortgage-to-price ratios can be calculated, knowledge about relevant monetary debt-to-profits restrictions, a selected exclusion for ‘piggyback loans,’ and supplemental information on funds and pricing treatment,” the assertion from Seth Appleton, president, mentioned. “USMI advisable that any potential enlargement of an permitted resolution be concern to extra basic public discover and comment, and we’re happy that Director Thompson built-in this plan as portion of FHFA’s conditional approval.”

    On the opposite hand, the Local neighborhood Dwelling Lenders of The usa, welcomed the switch.

    “CHLA thinks that is an essential merchandise offered that skyrocketing curiosity costs have made buying a refinance unaffordable,” Scott Olson, its authorities director, talked about in an announcement.

  • CBI, MRI Program greatly enhance rental payments

    CBI, MRI Computer software program improve rental payments | Australian Broker News

    News

    CBI, MRI Computer software program enrich rental payments

    Streamlining precise property transactions

    CBI, MRI Software enhance rental payments

    The Commonwealth Bank (CBA) and MRI Computer software program have launched a partnership to streamline fee procedures within the family genuine property sector.

    This collaboration goals to enhance the fee processes for Australian actual property brokers, property supervisors, and tenants by integrating CBA’s Smart Serious Estate Payments answer with MRI’s Assets Tree software program program.

    Enhancing the rental fee data

    The initiative will ship tenants with a much more economical solution to management their rental payments.

    Functions include versatile fee workflows, the capability to regulate fee approaches very simply, and visibility into fee historic previous and approaching expenditures.

    This method goals to reduce the time and vitality used on operating rental payments for all events related.

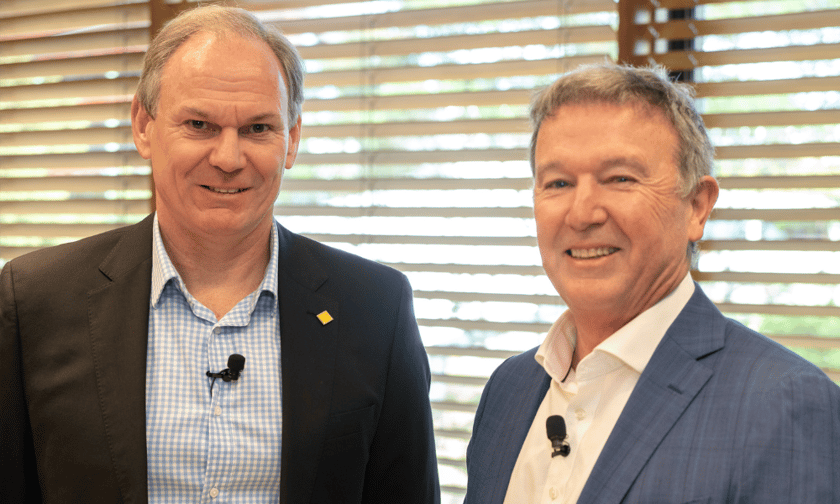
    “This digitised reply will make it uncomplicated and easy for each individual within the rental ecosystem to make and purchase rental payments,” stated Mike Vacy-Lyle (pictured beforehand talked about left), CBA group govt of group banking, in a media launch.

    Prioritising fundamental security and safety

    With the combination of predominant digital fee selections like BPAY, fast debit, PayTo, and playing cards, the Good True Estate Payments reply not solely simplifies the transaction technique but additionally boosts stability, based on CBA.

    “The safety of payments continues to be one in every of our core priorities and the brand new answer will provide a safer and extra safe digital data for tenants, actual property brokers, and residence professionals,” Vacy-Lyle claimed.

    The “announcement is a significant leap forward to addressing friction factors and fee safety for our Home Tree clientele,” stated David Bowie (pictured larger than appropriate), Asia Pacific senior vp and govt controlling director for MRI Computer software program. 

    Supporting development in critical property

    Outside of the fee answer, CBA can be devoted to supporting critical property brokers in rising their corporations. This comprises funding options for hire roll acquisitions and, for a confined time, waiving valuation charges to lower operational costs. These initiatives are designed to facilitate improvement and lower down financial strains on actual property organizations.

    Get the most well liked and freshest home mortgage data delivered correct into your inbox. Subscribe now to our FREE day-to-day e-newsletter.

    Similar Stories

    Maintain up with the latest information and gatherings

    Be part of our mailing guidelines, it’s no value!

  • FHFA seeks input on Home Financial loan banks’ economical housing program

    FHFA seal The Federal Housing Finance Company is on the lookout for comment from the general public on strategies that the Federal Household Bank loan banks’ cost-effective housing applications might be made far more profitable and inspire greater participation.

    Bloomberg Information

    The Federal Housing Finance Agency issued a official request for public enter on methods to strengthen the Federal Residence Mortgage banks’ reasonably priced housing software, an considerably pressing problem because the state grapples with a persistent housing lack.

    The Residence Personal loan monetary establishments have very lengthy billed on their very own as amongst the most important firms of financing for fairly priced housing however the process provides solely a smaller a part of its over-all funding in direction of the design of reasonably priced housing duties, sometimes by the Minimal-Revenue Housing Tax Credit score. Nonprofits have criticized the aggressive fairly priced housing software program as far too subtle and time-consuming for the compact quantity of funding. 

    A essential discovering of the FHFA’s 100-year evaluate of the Federal Dwelling Personal loan Lender Procedure was that the banks want to spice up their steering for housing and neighborhood progress. A whole lot of commenters in the midst of the evaluate claimed the cheap family system, or AHP, software plan of action is extraordinarily advanced.

    “Stakeholders inspired FHFA to strengthen the effectiveness of the software program procedures, which they talked about want main commitments of time and work for a relatively small amount of AHP subsidy relative to different endeavor funding sources,” FHFA defined in its ask for for input.  

    Ryan Donovan, president and CEO of the Council of Federal House Bank loan Banks, a commerce group for the system, claimed the banks are supportive of “an a lot simpler route” for accessing AHP funding.

    “1 of the most important issues coping with neighborhood and fairly priced housing teams desperately in the hunt for funding is how most interesting to navigate the complexity of the AHP grant program software process,” mentioned Donovan. “We hope that is the start of a technique to meaningfully streamline AHP legal guidelines to drastically improve get hold of use and, importantly, the have an effect on of the program.”

    Each and each of the 11 regional Property Personal loan banking firms are anticipated by statute to present 10% of earnings to very reasonably priced housing, which amounted to roughly $350 million final calendar yr. Numerous authorities have been prodding the banking firms to raise their funding for AHP to twenty%, which some have completed voluntarily. 

    In its request for enter, the FHFA supplied a group of points concerning the AHP, together with regardless of if some documentation necessities are wanted and the way the system might be extra productive. FHFA is also looking at how the AHP strategy compares to different firms of hole funding, which is usually the last word piece of funding bridging the opening amongst loans and a development mission’s complete costs. FHFA is also inquiring what objective consultants play in making use of for AHP cash. 

    The AHP subsidies sometimes purchase the number of grants or decreased curiosity fees for the get hold of, growth or rehabilitation of rental housing through which on the very least 20% of the models can be occupied by houses with incomes at or beneath 50% of the placement median earnings. The FHFA is soliciting responses solely on the system’s aggressive software plans for the expansion of multifamily rental housing.

    Every Residence Financial loan monetary establishment has discretion concerning the software program system to deal with the economical housing requires in its district.

    FHFA is demanded by statute to prioritize initiatives that use federal federal authorities houses or that  are sponsored by a nonprofit company or state federal authorities. It additionally need to make sure {that a} the overwhelming majority of the assistance is in the long term gained by low- and average-earnings households.

    The Household Financial loan banking establishments are a minor-recognized government-sponsored group created in 1932 to steering home loan lending after the Excellent Despair. The banking establishments have been criticized for receiving billions in subsidies and making sizable earnings for its member banking firms when offering considerably much less assist for its mission of cheap housing. 

    Commenters have till lastly August 19 to current feedback. Between the questions introduced, FHFA defined it needs to know the one most vital modify to spice up the AHP software plan of action. 

  • Trump Mortgage Relief Program, should i make my mortgage cost?

    U.S. mortgage holders put up file ranges of residence fairness: ICE

    By Didier Malagies

    15 May, 2024

    U.S. residence costs continued to climb in March as a persistent scarcity of houses on the market helped to buoy the housing market, in keeping with the Intercontinental Exchange (ICE) Home Price Index. And whereas potential homebuyers deal with the challenges of rising housing unaffordability, current householders are reaping the advantages of traditionally sturdy value good points. Nationwide fairness on mortgaged houses soared to a file $16.9 trillion within the first quarter of 2024, with $11 trillion accessible for leverage whereas sustaining a 20% fairness cushion — additionally an all-time excessive. The ICE index confirmed that residence costs elevated by a seasonally adjusted 0.42% month over month in March, marking the third consecutive month of above-average value good points, though this was a slight pullback from February’s 0.58% enhance. On an annual foundation, residence value development eased barely in March to five.6%, under the upwardly revised achieve of 6% in February. “The latest pattern of rising rates of interest has dampened homebuyer demand and allowed the stock of houses on the market to enhance,” Andy Walden, ICE’s vp of enterprise analysis technique, stated in an announcement.  “We’re nonetheless very a lot in a gap from a list perspective, however that deficit has fallen from 50% a yr in the past to 38% in March. Today, with 3.3 months of provide, stock remains to be traditionally low and indicative of a vendor’s market. This helps to maintain residence value development resilient despite the fact that

  • Trump Relief Program, what is happening


    Mortgage Forbearance Requests Jump Nearly 2,000% As Borrowers Seek Relief During Coronavirus Outbreak

    Source: CNBC

    Written by: Diana Olick

    Mortgage funds for the month of April are usually not even formally late till the fifteenth, however debtors are flooding into the federal government’s mortgage forbearance program.

    Forbearance requests grew by 1,270% between the week March 2 and the week of March 16, and one other 1,896% between the week of March 16 and the week of March 30, in line with numbers launched Tuesday by the Mortgage Bankers Association. It consists of information on 22.4 million loans serviced as of April 1, virtually 45% of the primary lien mortgage servicing market.

    The Cares Act, which President Donald Trump signed March 27, seeks to restrict the financial injury from COVID-19. The authorities applied the mortgage reduction measures earlier than Trump signed the invoice. It mandates that every one debtors with government-backed mortgages — about 62% of all first lien mortgages in line with Urban Institute — be allowed to delay not less than 90 days of month-to-month funds and presumably as much as a 12 months’s price. Those funds should finally be remitted both on the finish of the mortgage time period or in a structured modification plan.

    For the week of March 23 by March 29, caller requests numbered 218,718. That quantity jumped to 717,577 requests within the following week, in line with a Mortgage Bankers Association calculation. Mortgage servicers are required to grant forbearance to any borrower who requests it with no documentation of hardship vital.

    Among the loans sampled, from March 2 to April 1, whole loans in forbearance grew from 0.25% to 2.66% of whole servicing portfolios. Ginnie Mae loans in forbearance had the very best quantity and grew most importantly from 0.19% to 4.25%. These loans, which symbolize FHA and VA loans, typically have decrease down funds and are granted to debtors with decrease credit score scores.

    It is additionally getting harder for debtors to get by to their mortgage servicers to make these forbearance requests. Call middle common pace to reply reached 17.5 minutes from beneath 2 minutes three weeks in the past. About 25% of debtors are abandoning the calls in contrast with 5% three weeks in the past.

  • Florida UWM 0% Down Homebuyer Program

    The model new Florida UWM 0% Down Homebuyer Program affords as much as $15,000 in down-payment help that can assist you obtain homeownership within the Sunshine State.

    This program lets you purchase a house while not having cash for a down fee.

    In this text, we’ll clarify how this system works, who qualifies, and how you can apply.

    Program Overview

    The Florida UWM 0% Down Homebuyer Program helps folks purchase their first house with out a huge preliminary price. It affords as much as $15,000 in assist for the down fee, making it simpler to purchase a house while not having cash upfront.

    The two distinct methods to qualify for this program are by assembly earnings limits or being a first-time homebuyer.

    The Florida UWM 0% Down Homebuyer Program comes as a second mortgage that has no curiosity and doesn’t want month-to-month funds.

    This program is designed that can assist you purchase a house and handle your cash throughout buy.

    A potential homebuyers interacting with mortgage advisor about UWM zero down program

    Benefits

    The Florida UWM 0% Down Homebuyer Program offers important benefits to ease home-buying and scale back monetary pressure.

    Here are the important thing advantages that make this program a superb selection for eligible homebuyers:

    Zero Down Payment: This lets you buy a house with out an upfront down fee, eradicating a significant monetary barrier.

    Up to $15,000 Assistance: Receive as a lot as $15,000 to cowl your down fee, considerably lowering the quantity it’s worthwhile to save earlier than shopping for.

    No Interest: The down fee help comes within the type of a second mortgage with no curiosity, which suggests you don’t pay greater than you borrow.

    Deferred Payments: You would not have to make month-to-month funds on the second mortgage till you refinance or repay the primary mortgage, providing monetary flexibility.

    Enhanced Home Affordability: By lowering upfront prices, this system makes homeownership extra accessible for first-time consumers and people with restricted financial savings.

    Support for First-Time Buyers: Specifically targets first-time homebuyers, offering them with a better pathway to proudly owning their first house.

    Credit Flexibility: Accepts candidates with a minimal 620 credit score rating, making it accessible to a wider vary of debtors.

    High Loan-to-Value Ratio: You can qualify with loan-to-value ratios as excessive as 97%, maximizing the buying energy of your property mortgage.

    How to Qualify

    To be eligible for the Florida UWM 0% Down Homebuyer Program, you’ll be able to qualify by one in every of two paths relying in your monetary state of affairs and home-buying historical past:

    Path 1: For Low to Moderate-Income Homebuyers

    Meet Income Limits: Your yearly earnings must be 80% or much less of the Area Median Income (AMI) the place you wish to purchase your property.

    Extra Help for Lower Incomes: If your earnings are at or beneath 50% of the AMI, you additionally get a $2,500 credit score to assist much more, and also you don’t must pay this again.

    Credit Score and Home Loan Details: You want a credit score rating of at the least 620. The mortgage for the house should cowl between 95% and 97% of the house’s worth.

    Path 2: For First-Time Homebuyers

    If you do not match into both of those paths, don’t fret! There are numerous methods to attain homeownership with 0% down in Florida.

    There are 25 extra first-time homebuyer grants and packages within the state of Florida, notably the Florida Hometown Heroes Program, which has much less strict necessities.

    FAQ: UWM 0% Down Purchase Program

    Down fee help packages proceed to be a useful useful resource for homebuyers nationwide. To assist our companions develop their enterprise and higher serve debtors, we provide an unique 0% Down Purchase program.

    Simply put, certified debtors obtain a 3% down fee help mortgage, as much as $15,000, from UWM. This permits our companions to assist extra debtors get into a house proper now with no down fee.

    What is the UWM 0% Down Purchase Program?

    The UWM 0% Down Purchase Program is an unique providing the place certified debtors obtain a 3% down fee help mortgage, as much as $15,000, with no curiosity and no month-to-month funds required on the second lien mortgage.

    How does the down fee help work?

    UWM offers a second lien mortgage for 3% of the acquisition worth, as much as $15,000. This second lien has no month-to-month fee requirement and no curiosity. The steadiness is due when the primary lien mortgage is refinanced or paid off.

    Who is eligible for this system?

    Borrowers have to be at or beneath 80% of the Area Median Income (AMI) for the property’s handle and meet Home Possible® guideline necessities. Alternatively, first-time homebuyers who meet HomeOne® and UWM tips can qualify.

    What defines a first-time homebuyer?

    A primary-time homebuyer is outlined as somebody who has not had an possession curiosity in a house within the final three years.

    What are the credit score rating necessities?

    A minimal credit score rating of 620 is required for debtors assembly the AMI necessities, and a minimal credit score rating of 700 is required for first-time homebuyers.

    Are there any extra advantages for very low-income debtors?

    Yes, debtors with qualifying incomes at or beneath 50% AMI will obtain a $2,500 credit score for the three% help. This credit score doesn’t should be repaid and lowers their debt obligation from the second lien.

    What loan-to-value (LTV) ratios are accepted?

    The mortgage ought to cowl between 95% and 97% of the house’s worth for each paths.

    Are there any restrictions on the second lien mortgage?

    The second lien bears a 0% rate of interest, has no minimal month-to-month fee necessities, and is absolutely due as a balloon fee upon the refinance or payoff of the primary lien, or the ultimate fee of the primary lien’s amortization schedule.

    How can I apply for the UWM 0% Down Purchase Program?

    Visit MakeFloridaYourHome.com to examine eligibility, collect obligatory paperwork, and submit the web utility type. Once verified, you’ll be able to obtain as much as $15,000 to your down fee.

    What ought to I do if I’ve extra questions or want help?

    For extra data or help, contact UWM by their web site or join with them on social media. You may use the assets and instruments accessible on their platform to handle your utility and get assist.

    How to Apply

    Follow these steps to start out your journey towards homeownership with zero down fee.

    Verify Eligibility with MakeFloridaYourHome: Fill out our type to confirm eligibility for the Florida UWM 0% Down Homebuyer Program.

    Gather Documents: Prepare obligatory paperwork, together with earnings verification, credit score rating experiences, and identification.

    Submit Application: Complete and submit the appliance type with MakeFloridaYourHome.

    Get Verified: Await verification of your eligibility.

    Receive Assistance: If authorised, obtain as much as $15,000 to your down fee with no curiosity and deferred funds.

    With over 50 years of mortgage business expertise, we’re right here that can assist you obtain the American dream of proudly owning a house. We attempt to offer the perfect training earlier than, throughout, and after you purchase a house. Our recommendation relies on expertise with Phil Ganz and Team closing over One billion {dollars} and serving to numerous households.

  • United Wholesale Mortgage program eliminates need for title insurers

    Mortgage chief United Wholesale Mortgage is rolling out a device to permit brokers to bypass title insurers altogether on refinances, an enlargement of its earlier program. 

    Brokers utilizing Title Review and Closing plus, or TRAC+, can let UWM deal with title evaluations, closing and disbursement for a flat $1,850 charge. It upgrades its earlier program through which transactions nonetheless required a settlement agent, and is now obtainable for authorities loans. I

    “Title might be one of many least understood elements of the mortgage course of,” mentioned Melinda Wilner, chief working officer at UWM. “With TRAC+, it isn’t solely creating numerous financial savings however taking out a friction level that exists immediately that can save debtors numerous time.”

    The program, obtainable Thursday, was introduced by president and CEO Mat Ishbia on the UWM Live occasion Thursday on the agency’s headquarters in Pontiac, Michigan. 

    Further particulars round TRAC+ have been scheduled to be launched Thursday afternoon. The present program carries a $1,600 charge plus the price of a settlement agent. Brokers who had a most well-liked settlement agent join paid a $500 charge, in keeping with UWM. Those who use two chosen businesses pay a $350 flat charge. 

    The lender is providing scaling pricing incentives as much as 60 foundation factors for a mortgage as much as $150,000, 40 bps for a mortgage between $150,000 to $300,000, and 25 bps for loans between $300,000 to $450,000. 

    The agency upfront of the discharge employed attorneys and abstractors for title work in every state, Wilner mentioned. 

    The device comes at a tense time for the title business, which has urged warning round lawyer opinion letters and slammed a proposal for the government-sponsored enterprises for a title waiver pilot. 

    Wilner acknowledged that TRAC’s earlier incarnation “ruffled some feathers,” and cautioned that it will not be the best choice for each purchaser. 

    “Anything to offer choices normally provides good competitors,” she mentioned. “We imagine this product is a good motion ahead to vary one thing that is been stagnant for years.” 

  • Fannie Mae launches hire payment reporting pilot system Program allows renters in multifamily attributes to make improvements to credit score scores

    Fannie Mae on Tuesday launched a pilot program to allow renters of multifamily properties develop their credit score histories and strengthen their credit ranking scores.

    Productive Sept. 27, appropriate multifamily property entrepreneurs can share lease payment information by a vendor group to TransUnion, Equifax, and Experian in the renter’s credit ranking profile.

    “Around 20% of the U.S. inhabitants has minor to no confirmed credit ranking heritage, a gaggle in which Black and Latino/Hispanic of us are disproportionately represented. Of the patrons who do have a credit historical past ranking, a disproportionate vary of Black shoppers have a subprime credit ranking ranking. These imbalances improve racial disparities in entry to credit and glorious inexpensive housing between renters and homeowners,” talked about Michele Evans, Govt Vice President and Head of Multifamily at Fannie Mae.

    “The absence of sufficient credit historical past minimizes a renter’s talent to accessibility housing in greater-possibility neighborhoods, receive a house mortgage, and obtain reduce-cost credit score, this kind of as auto monetary loans and instruction financing.”

    Renters who overlook a payment are robotically unenrolled to shield their credit ranking ranking. They may choose out of the system. Fannie Mae suggests it
    Fannie Mae on Tuesday launched a pilot software to help renters of multifamily attributes construct their credit histories and improve their credit ranking scores.

    Successful Sept. 27, eligible multifamily property owners can share hire payment data by a vendor community to TransUnion, Equifax, and Experian in the renter’s credit score profile.

    “Around 20% of the U.S. inhabitants has small to no acknowledged credit score heritage, a workforce in which Black and Latino/Hispanic persons are disproportionately represented. Of the shoppers who do have a credit historical past score, a disproportionate amount of Black people have a subprime credit ranking. These imbalances fortify racial disparities in receive to credit and good high quality fairly priced housing among the many renters and property homeowners,” claimed Michele Evans, Govt Vice President and Head of Multifamily at Fannie Mae.

    “The absence of enough credit score historical past lessens a renter’s potential to accessibility housing in better-opportunity neighborhoods, pay money for a home mortgage, and attain decreased-expense credit score, equivalent to car loans and coaching funding.”

    Renters who skip a payment are routinely unenrolled to shield their credit ranking ranking. They may choose out of the appliance. Fannie Mae claims it’ll go over the expenditures of amassing and disseminating lease payment info for a 12-month time period for multifamily debtors who use an individual of the three approved sellers to accumulate the info.

    In September of 2021, Fannie Mae started to incorporate prospects’ hire funds into its underwriting method, acknowledged as Desktop Underwriter.

    The job of client transaction particulars in growing homeownership entry

    Productive all-natural language processing applied sciences extract deeper which implies from unstructured info to make a giant distinction in the lives of a large number of would-be homebuyers who’re credit invisible or haven’t had the potential to obtain entry to cost-effective housing finance.

    Freddie Mac, the lesser of the 2 governing administration sponsored enterprises, introduced in late June that it far too can be incorporating lease funds into its danger analysis. It additionally has impressed multifamily landlords to report constructive rental funds to the credit bureaus to enhance tenants’ shot at qualifying for a mortgage mortgage. The GSE defined in November that it had 70,000 properties all through 816 multifamily qualities enrolled in the plan.

    In a exploration research revealed final 12 months, Fannie Mae mentioned that in a pattern of property finance mortgage candidates who had been being denied a mortgage, 17% might have obtained an approval if their rental payment heritage skilled been considered.

    will go over the prices of accumulating and disseminating hire payment data for a 12-month interval for multifamily debtors who use a single of the a couple of authorised sellers to receive the small print.

    In September of 2021, Fannie Mae commenced to incorporate prospects’ hire funds into its underwriting program, recognised as Desktop Underwriter.

    The job of purchaser transaction info in rising homeownership accessibility

    Successful natural language processing programs extract deeper which implies from unstructured information to make a variance in the lifetime of innumerable would-be homebuyers who’re credit score invisible or haven’t had the potential to get entry to fairly priced housing finance.

    Freddie Mac, the extra compact of the 2 authorities sponsored enterprises, declared in late June that it as properly can be incorporating lease funds into its likelihood analysis. It additionally has impressed multifamily landlords to report useful rental funds to the credit bureaus to improve tenants’ shot at qualifying for a property finance mortgage. The GSE defined in November that it had 70,000 properties all through 816 multifamily qualities enrolled in the software program.

    In a evaluation analyze posted final yr, Fannie Mae talked about that in a pattern of mortgage  candidates who’ve been denied a home mortgage, 17% might have been given an approval if their rental payment heritage had been thought of.

  • Florida Produced Dwelling Bank loan Program

    Florida Created Residence Personal loan Plan Overview

    The Florida Produced Home Bank loan Plan gives cost-effective monetary loans to individuals immediately who need to purchase made households in Florida.

    It permits endorse economical housing by supplying nice loan alternatives to all those that qualify.

    Purpose of the System

    The Florida Manufactured Dwelling Bank loan Plan was developed to help decrease—and center-income individuals personal residences. This plan began given that genuine property prices are rising, and cost-effective housing is required.

    It makes an attempt to make it a lot simpler to personal a residence by offering minimal-interest premiums and versatile monetary loans for made properties in Florida.
    An illustration symbolizing the accessibility of homeownership through Manufactured Home Loan Program

    What is a Florida Manufactured Dwelling Financial loan?

    A Florida made dwelling mortgage is a selected type of mortgage for purchasing a produced or cell dwelling in Florida. These residences, constructed in factories and moved to a locale, are often about 30% to 80% inexpensive than on-website homes.

    You often must have a superior credit score historical past ranking, a steady cash, and a down cost to get this financial institution loan. Distinctive monetary loans are supplied, like FHA, VA, and USDA monetary loans, which frequently have scale back down funds and versatile credit score historical past insurance policies.

    Eligibility Necessities

    Listed listed here are the important eligibility necessities for acquiring a manufactured home financial institution loan, with estimated figures based on the common price of a manufactured property:

    Credit historical past Rating and Cash stream

    Usually, a credit standing rating of 580 or bigger is critical. You ought to reveal a safe earnings sufficient to guard month-to-month funds and different obligations.

    Down Payment

    Assuming the common promoting worth of a produced house is about $100,000, the down cost would vary from $3,000 to $20,000, depending on the distinctive loan utility (3% to twenty%). Having stated that, quite a few initial-time homebuyer grants in Florida can support you buy a created dwelling with zero down cost.

    Advantages of the Software

    This system interprets the will of homeownership right into a conveniently achievable reality, many because of an array of added advantages uniquely personalized for potential homebuyers and severe property buyers.

    Low-fascination charges that appreciably lower each month funds.

    Adaptable compensation phrases as much as 30 yrs.

    Availability of each of these preset and variable cost monetary loans.

    Chance to finance as much as 100% of the house’s profit.

    No prepayment penalties.

    Relevant for every new and made use of manufactured homes.

    Eligibility to residents regardless of their income quantity.

    Key Modifications in 2024

    Advancement in Manufacturing and Shipment

    The manufacturing and cargo of created properties have seen a necessary elevate, with a talked about 27.2% rise in shipments in February 2024 in comparison with the earlier yr.

    This suggests a increasing sector and availability of manufactured properties.

    Luxury and High high quality Advancements

    There has been a obvious change in path of upper good high quality and luxurious in produced houses. These properties at the moment are staying created with large-quality parts and comprise plentiful facilities.

    The trendy luxurious created residence emphasizes prime quality building and progressive patterns, aligning with evolving purchaser calls for.

    2024 Government Initiatives and Funding

    The Biden-Harris Administration has launched new actions beneath HUD to steerage the affordability and availability of created homes.

    This incorporates a brand new federal funding alternative termed the Value Application, which goals to keep up and revitalize produced housing and communities with a $225 million grant.

    Furthermore, FHA Title I Made Property Loan Application updates are supposed to make funding rather more obtainable and in step with current present market pricing.

    Developing Attraction To Young Customers

    The attractiveness of created residences is broadening all through all age groups.

    The out-of-date stigma that made properties are primarily for retirees is switching. Far extra youthful individuals and relations are pondering of them as a sensible housing selection owing to their affordability and total flexibility.

    Bank loan Types

    FHA Made Dwelling Financial loan

    With an FHA loan, the highest rated revenue is the small down cost necessity of simply 3.5%, making homeownership additional achievable for lots of consumers.

    You usually must have a continuing earnings and a down cost of at the very least 3.5% for an FHA mortgage. The minimal quantity credit standing ranking necessity is often throughout 580, however debtors with decreased scores could nonetheless qualify with a greater down cost.

    VA Made Residence Bank loan

    VA monetary loans stand out just because they name for no down cost. They are fully available to veterans, energetic-obligation help clients, and their households.

    Whilst you will see that no formal minimal credit score rating necessity, most loan suppliers need a rating of on the very least 620 for VA monetary loans.

    USDA Created Dwelling Personal loan

    The important achieve of USDA monetary loans is their zero down cost choice and the likelihood to purchase homes in certified rural areas, which boosts accessibility to homeownership for minimal-to-average-profits relations.

    The least credit score historical past ranking want for USDA monetary loans is often throughout 640, however some collectors could nicely settle for decreased scores with compensating elements.

    How to Utilize for a Produced Dwelling Mortgage in Florida

    Commence by amassing the paperwork you want, this form of as proof of earnings, your credit score historical past report, and data in regards to the created family.

    Then, submit your software program on the web and maintain out for acceptance from MakeFloridaYourHome. To improve your potentialities of accomplishment, make optimistic your software program is full and correct.

    As a to start out with-time applicant, select fringe of help from loan specialists and ponder having pre-approved. Knowing how an important deal you’ll be able to borrow early on can help you make much better decisions.

    Also, look for monetary loan packages supposed for initially-time shoppers that present unbelievable situations. This can improve your odds of buying an important monetary loan in 2024.

    Essential Documentation

    Applicants ought to actually seem ready with proof for the Florida Produced House Financial loan utility.

    Proof of Identification: Driver’s license or governing administration-issued ID.

    Employment Verification: Get maintain of details to your employer or proof of self-employment cash.

    Credit Historical previous: Check out your credit standing rating and obtain a credit score rating report.

    Manufactured Home Aspects: Simple details in regards to the residence you is likely to be buying.

    These paperwork must be the least wanted for a potential purchaser to start out out making use of for a produced dwelling mortgage in Florida.

    Try to recollect, a effectively-documented utility tells a convincing story of your creditworthiness. Seek the recommendation of with a private loan officer for distinct doc wants.

    Financial loan Application Course of motion

    Embarking on the Florida Created Dwelling Loan software program method may presumably seem like refined, however it may be uncomplicated when you have got an understanding of the sequence of strategies.

    Here are 5 very important methods potential debtors require to adjust to in 2024.

    Pre-application preparations: MakeFloridaYourHome will put together all required paperwork and consider your monetary standing and readiness.

    Personal loan pre-approval: If pre-acceptance is made out there, make the most of to grasp your potential borrowing limitations.

    House Collection: Choose a suited manufactured home that meets software program specs.

    Software submission: Fill out the formal system software program fully and embody all demanded paperwork.

    Await approval: After submitting your utility, await formal interplay about your software program standing.

    Strategies for a Successful Application

    Right listed here are three important concepts for a affluent utility for a made residence monetary loan in Florida:

    Before making use of for a private loan, study your credit standing ranking and overview your funds. MakeFloridaYourHome will use this data and details to find out your eligibility and need cost. If your credit score historical past ranking calls for enchancment, think about measures to deal with any points proper earlier than making use of.

    Acquire all very important documentation, some of these as proof of earnings, employment verification, and identification, as early as attainable. Possessing these paperwork prepared will streamline the software program system and reveal your preparedness to the loan firm.

    Acquire the time to know the a number of private loan situations and alternatives out there to you. Make sure you perceive the phrases of the mortgage you occur to be making use of for and go for the selection that biggest matches your financial circumstance and extended-expression plans.

    FAQs about Florida’s Manufactured Residence Personal loan Program

    Aiding you navigate the ins and outs of Florida’s Produced House Financial loan Application.

    Can I exploit the loan for each of these new and utilized manufactured houses?

    Certainly! Florida’s Produced Household Financial loan Software handles every new and utilised houses. Whether or not you occur to be eyeing a brand-new product or a pre-owned an individual, this system’s purchased you included.

    Recall, all employed properties must be inspected rigorously to satisfy HUD code pointers.

    What expenses are affiliated with the mortgage?

    Count on typical charges like origination service charges and appraisal costs and extras like recording charges and state taxes. To get a crystal clear picture, query your loan firm for a breakdown of all prices, from processing service charges to inspection charges.

    Are there any down cost requirements?

    Indeed, a down cost is critical. The whole depends upon issues like the kind of residence and your fiscal circumstance. A better down cost may indicate improved monetary loan phrases, so it actually is value planning strategically.

    Can I get pre-accredited for a produced residence private loan?

    Absolutely! Pre-approval is accessible, offering you a head begin off within the aggressive financing earth. It assists loan corporations comprehend your economical monitor report, dashing up the method while you receive the right property.

    How lengthy does it think about to method the loan utility?

    It usually usually takes 60-90 days from software program to ultimate approval. The timeline can vary primarily based totally on the completeness of your paperwork and market illnesses.

    Staying organized and responding instantly to any requests out of your monetary establishment can support velocity points up.

    What transpires if I default on the monetary loan?

    Defaulting on the non-public loan means not assembly compensation situations, which may information to foreclosures and hurt your credit score historical past rating. But don’t stress!

    Open up interplay together with your loan supplier is crucial. They could nicely give strategies like private loan modifications or compensation plans to allow you get again on monitor.

    Can I encompass renovation expenditures within the mortgage?

    In some situations, sure. If you occur to be getting a made family that wants renovations, you might be able to encompass the renovation charges within the loan sum.

    Nonetheless, it will depend on the loan firm and the extent of the renovations essential. Be assured to deal with this different together with your loan firm via the applying system.

    What are the revenue calls for for the financial institution loan?

    Earnings calls for fluctuate depending on the monetary establishment and the particular private loan software program. Frequently, collectors need to see that you’ve got a gradual supply of revenue satisfactory to cowl your common month-to-month property finance loan funds. This can embody revenue from employment, self-work, retirement advantages, or different sources.

    Throughout the software program plan of action, be organized to current documentation of your cash, these sorts of as shell out stubs, tax returns, and monetary establishment statements.

    Are there any distinctive financing alternatives supplied for very first-time homebuyers?

    Exclusive financing choices are obtainable for to start out with-time homebuyers by MakeFloridaYourHome. These choices may comprise reduce down cost requirements, diminished fascination charges, or different incentives to help initially-time purchasers understand their homeownership goals.

    Be assured to speak to us about any available packages for 1st-time homebuyers and no matter whether or not you qualify.

    Bottom Line

    The Florida Created House Personal loan Application makes it potential for probably homebuyers to acquire inexpensive financing solutions for manufactured homes in simply the situation.

    Key benefits of the tactic embody small-interest prices, adaptability in reimbursement phrases, and the chance to finance as much as the house’s full value.

    Ready to make Florida your property? Take a take a look at your financing potentialities now with MakeFloridaYourHome.