Tag: professional

  • Consumer confidence tumbles | Mortgage Professional Australia

    Consumer confidence tumbles | Mortgage Professional Australia

    News

    Weekly inflation expectations additionally fall
    Consumer confidence tumbles

    Consumer confidence in Australia skilled a notable decline final week, dropping by 2.3 factors to 79 factors, in keeping with the newest ANZ-Roy Morgan Australian Consumer Confidence report.

    Despite this, the four-week shifting common noticed a slight improve of 0.5 factors, reaching 80.3 factors.

    Weekly inflation expectations fell by 0.3 share factors to 4.9%, whereas the four-week shifting common inched as much as 5%.

    Current monetary situations over the previous yr decreased by 4.7 factors, whereas future monetary situations for the following 12 months improved by 1.2 factors.
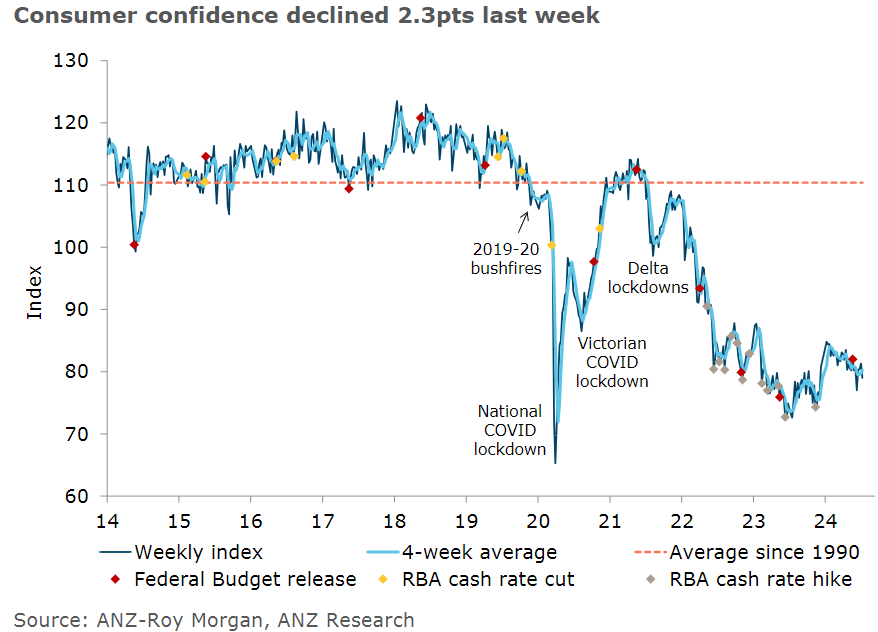
    Short-term financial confidence for the following 12 months noticed a modest rise of 0.6 factors, and medium-term financial confidence for the following 5 years elevated by 0.3 factors.

    The “time to purchase a serious family merchandise” subindex skilled a major drop of 9 factors.
    “ANZ-Roy Morgan Australian Consumer Confidence dropped to its second lowest stage for the yr,” stated Madeline Dunk (pictured above), economist at ANZ. “The decline was pushed by a nine-point fall within the ‘time to purchase a serious family merchandise’ subindex, following the conclusion of end-of-financial yr gross sales. This was the most important weekly fall within the subindex since February 2023. There was additionally a 4.7-point drop in ‘present monetary situations’.

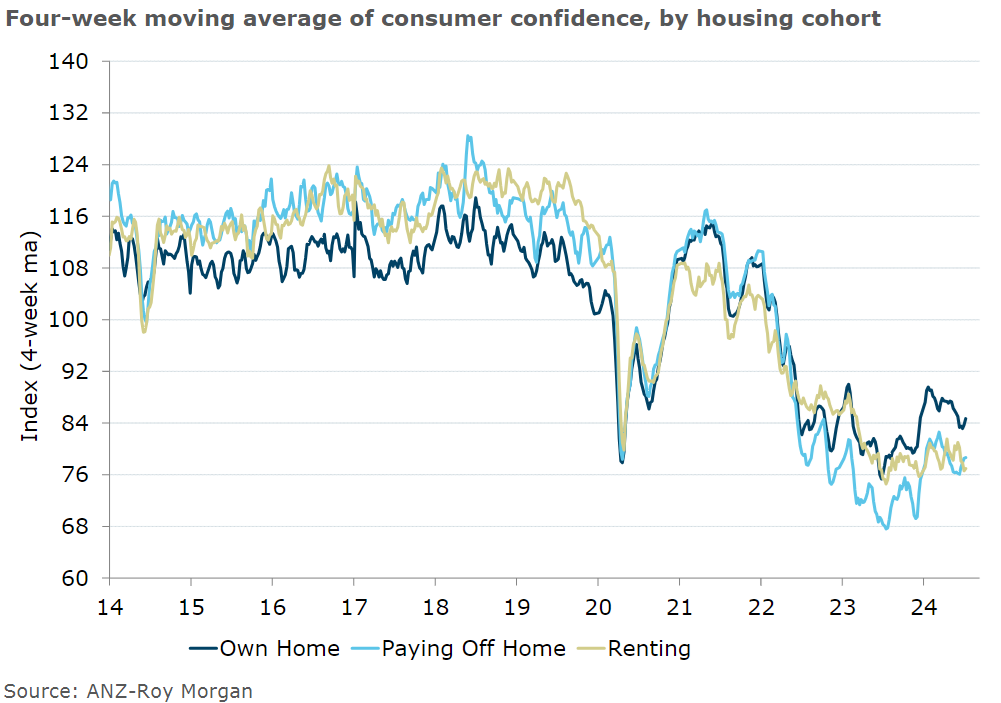
    “Across the housing cohorts, confidence declined most for these paying off a mortgage, maybe attributable to speak about the potential for an RBA charge hike in August. Confidence additionally fell for households that personal their properties outright, whereas it was broadly secure for renters.”

    Any ideas on this story? Share them with us by leaving a remark within the dialogue field on the backside of the web page.

    Free e-newsletter

    Our every day e-newsletter is FREE and retains you updated with the world of mortgage.
    Please full the shape under and click on on SIGN UP to obtain every day e-newsletters from Mortgage Professional Australia.

    Our every day e-newsletter is FREE and retains you updated with the world of mortgage.

  • Non-public Label relaunches with ‘prosperous professional debtors’ assortment – House loan Strategy

    Private Label has launched a set of dwelling loans geared toward “prosperous certified debtors”.  

    The lending model owned by the Brightstar Group says its Rockstar Variety attributes desire-only lending as much as 90% mortgage to worth, collectively with into retirement, as very properly as taking a versatile stance on self-employment and complex income.  

    The enterprise will acknowledge expert folks immediately with a lot lower than 12 months’ buying and selling background “and different eventualities that usually make the most of to prosperous skilled debtors”.  

    It may even take into consideration abroad nationals with considerably lower than 12 months within the British isles for this range and can accommodate huge loans above £5m.  

    Private Label, which provides bespoke loans for £500,000 or extra, was relaunched in April under Paul Brett as problem lead, who’s tasked with working with brokers to detect potentialities not achieved by present propositions.  

    He joined the model following investing seven a number of years at Landbay – and has labored within the house finance loan discipline for way over 30 a number of years, for each equally collectors and packagers.   

    Brett elements out that this range “will attraction to a wider range of intermediaries in offering strategies they can’t discover elsewhere.

    “The Rockstar Array of house loans is our 1st begin on this future evolution of the Non-public Label mannequin.”  

    Brightstar Group deputy chief authorities Bradley Moore gives that “this upcoming tranche of lending for Private Label is a return to ‘true exclusivity’ with the conclude goal changing into to help even much more debtors with sophisticated eventualities.”  

    Private Label was a effectively-regarded packager within the middleman mortgage loan market from the late 80s to the early 2000s.  

    It was established by Stephen Knight, Barry Searle, Simon Knight and Godfrey Blight and labored with quite a few lesser, centralised collectors to structure property finance loan gadgets.  

    The producer was bought by Common Motors, which grew to turn into GMAC-RFC, in 1998 and shut to new enterprise in October 2002.  

    Brightstar purchased the enterprise enterprise and area in 2016, launching many fashionable merchandise and options, collectively with an Airbnb giving and a credit score rating mend home loan, in July 2017.  

    However, the group afterwards place the mannequin into “hibernation” though ready for the proper human being to simply take it forward. It was revived lower than Brett within the spring.  

  • Do I Need A Downpayment To Get Professional Residence?

    Fed retains charges fixed for the sixth straight time

    By Didier Malagies
    •
    02 Might, 2024

    The Federal Reserve ’s Federal Open Markets Committee (FOMC) preserved its limited-phrase plan curiosity quantity steady at a fluctuate of 5.25% to five.5% for a sixth consecutive assembly on Wednesday. “The Committee doesn’t count on will probably be appropriate to lower the goal choice proper up till it has obtained bigger self worth that inflation is shifting sustainably in the direction of 2%,“ the FOMC defined in a assertion. “In addition, the Committee will proceed minimizing its holdings of Treasury securities and company bank card debt and company mortgage‑backed securities.“ All by way of their earlier meeting in March , policymakers indicated that they nonetheless envisioned three curiosity value cuts in 2024. But with inflation remaining sticky and unemployment staying under 4%, these expectations are beginning to be a lot much less possible. New monetary knowledge has not supplied the Fed assurance that inflation will stick with it to say no. Strong inflation knowledge within the first quarter, coupled with a sturdy labor present market , have postponed expectations for the first Fed degree slice. In April, Fed Chairman Jerome Powell, speaking on the Washington Discussion board , produced it distinct that charge cuts weren’t imminent owing to the toughness of the economic system. The monetary system has taken care of surprising momentum even with the current degree of limited-term costs. With the unemployment charge beneath 4%, corporations are steadily introducing staff and true wage growth is observable as inflation eases. Despite the truth that upward actions in inflation are noteworthy, vital growth towards the Fed’s 2% goal has been created. “It’s unlikely that the following protection value transfer will likely be a hike,” Powell knowledgeable journalists on Wednesday all by way of the FOMC’s press convention. “In purchase to hike the premiums, we must must see persuasive proof that our protection stance is just not adequately restrictive to supply inflation sustainably all the way down to 2% greater than time. That’s not what we’re seeing on the second.” Whilst Powell emphasised the unlikelihood of potential value hikes, he additionally remained obscure concerning the Fed’s potential fascination charge trajectory. “We didn’t see growth within the initially quarter. It seems that it’ll select longer for us to reach at that situation of self worth,” Powell said. “I don’t understand how prolonged it’s going to think about. … My particular person forecast is that we’ll begin out to see growth on inflation this yr. I have no idea that will probably be enough to chop charges we must allow the small print direct us on that.” In a brand new growth, the Fed introduced an easing of its quantitative tightening protection. Setting up in June, the fee-location physique will decreased the roll-off charge of its Treasury securities from $60 billion to $25 billion for every month. This implies that though the Fed won’t begin promoting Treasurys in June, it’s going to allow fewer of them to skilled. It won’t change its roll-off cost for mortgage loan-backed securities (MBS), which can proceed to be at $35 billion for each thirty day interval, in accordance to Xander Snyder, senior enterprise genuine property economist at Very first American. “The FOMC didn’t alter the continued passive roll-off of its MBS holdings however did observe that any prepayments additional than the persevering with $35 billion cap could be reinvested in Treasuries,” Mike Fratantoni, senior vp and chief economist for the Mortgage Bankers Association, stated in a press release. “We anticipate home mortgage charges to drop later this 12 months, however not as considerably or as speedy as we beforehand had predicted.” In addition, Powell reiterated the Fed’s motivation to carrying forward the Basel III endgame guidelines in a manner that’s trustworthy to Basel and likewise akin to what the jurisdictions in different nations are executing. Since the March FOMC meeting, Freddie Mac’s common 30-12 months mounted residence finance mortgage value has improved from 6.74% to 7.17%. Just earlier than the next FOMC convention on June 12, two further inflation readings are anticipated. “While it’s a chance, I by no means imagine that we’ll see considerably remodel in home mortgage charges following this Fed assembly, for the reason that Fed has been inclined to allow the information direct at this stage within the cycle,” Real property agent.com essential economist Danielle Hale stated in a press release. “In order to see mortgage mortgage charges drop further considerably, the Fed might want to must see extra proof that inflation is slowing.”  For homebuyers and sellers, this means that housing affordability will keep a major consideration, most likely driving residence buys in cheap marketplaces, predominantly within the Midwest and South, in response to Hale.

  • 7(a) mortgage Holiday getaway, Florida | Professional House Personal loan Closing Announcement

    Fed retains premiums fixed for the sixth straight time

    By Didier Malagies
    •
    02 May properly, 2024

    The Federal Reserve ’s Federal Open Markets Committee (FOMC) managed its limited-phrase plan curiosity cost steady at a wide range of 5.25% to five.5% for a sixth consecutive convention on Wednesday. “The Committee doesn’t hope will probably be acceptable to minimize the focus on selection till lastly it has obtained higher self worth that inflation is shifting sustainably towards 2%,“ the FOMC mentioned in a assertion. “In addition, the Committee will proceed on lowering its holdings of Treasury securities and company private debt and company mortgage‑backed securities.“ For the length of their earlier meeting in March , policymakers indicated that they nonetheless envisioned three need worth cuts in 2024. But with inflation remaining sticky and unemployment staying beneath 4%, these expectations are getting a lot much less more than likely. Modern financial knowledge has not given the Fed confidence that inflation will carry on to lower. Robust inflation particulars within the to begin with quarter, coupled with a powerful labor market place , have postponed anticipations for the initially Fed stage scale back. In April, Fed Chairman Jerome Powell, speaking on the Washington Forum , constructed it distinct that worth cuts had been being not imminent due to to the power of the general financial system. The financial system has managed beautiful momentum even with the present stage of brief-expression expenses. With the unemployment charge down beneath 4%, companies are steadily introducing staff and actual wage progress is observable as inflation eases. While upward actions in inflation are noteworthy, substantial progress towards the Fed’s 2% objective has been constructed. “It’s unlikely that the subsequent plan stage switch will probably be a hike,” Powell informed journalists on Wednesday all via the FOMC’s press assembly. “In order to hike the costs, we might require to see persuasive proof that our coverage stance is just not adequately restrictive to hold inflation sustainably all the way down to 2% over time. That is just not what we’re observing on the second.” When Powell emphasised the unlikelihood of upcoming worth hikes, he additionally remained imprecise concerning the Fed’s foreseeable future curiosity worth trajectory. “We didn’t see progress within the first quarter. It seems that it’ll take for an extended time for us to entry that time of self-confidence,” Powell reported. “I have no idea how extended it can select. … My customized forecast is that we are going to begin off to see growth on inflation this yr. I don’t know that will probably be enough to chop expenses we should let the data lead us on that.” In a brand new progress, the Fed launched an easing of its quantitative tightening coverage. Starting in June, the level-environment complete physique will decreased the roll-off worth of its Treasury securities from $60 billion to $25 billion per thirty days. This means that though the Fed won’t begin off advertising and marketing Treasurys in June, it can enable fewer of them to skilled. It won’t change its roll-off worth for mortgage-backed securities (MBS), which is able to carry on being at $35 billion per thirty days, in accordance to Xander Snyder, senior skilled precise property economist at Initial American. “The FOMC didn’t remodel the continuing passive roll-off of its MBS holdings however did bear in mind that any prepayments additional than the persevering with $35 billion cap can be reinvested in Treasuries,” Mike Fratantoni, senior vp and chief economist for the Home loan Bankers Association, mentioned in a assertion. “We assume home loan costs to drop afterwards this 12 months, however not as far or as fast as we beforehand had predicted.” In addition, Powell reiterated the Fed’s motivation to carrying forward the Basel III endgame legal guidelines in a method that’s reliable to Basel and in addition akin to what the jurisdictions in different nations are finishing up. Considering the truth that the March FOMC convention, Freddie Mac’s common 30-yr mounted property finance loan stage has elevated from 6.74% to 7.17%. Ahead of the subsequent FOMC convention on June 12, two added inflation readings are anticipated. “While it’s a chance, I actually do not assume that we’ll see so much enhance in property finance loan charges pursuing this Fed meeting, as a result of the Fed has been keen to permit the information lead at this stage within the cycle,” Real property agent.com fundamental economist Danielle Hale mentioned in a press release. “In get to see dwelling loan prices drop extra drastically, the Fed might want to should see further proof that inflation is slowing.”  For homebuyers and sellers, this implies that housing affordability will carry on being a number one factor to think about, fairly presumably driving residence buys in moderately priced marketplaces, predominantly within the Midwest and South, in accordance to Hale.

  • Professional Loans With Very low Down Payments

    Fed retains charges steady for the sixth straight time

    By Didier Malagies
    •
    02 May presumably, 2024

    The Federal Reserve ’s Federal Open up Markets Committee (FOMC) taken care of its small-time interval plan curiosity stage common at a differ of 5.25% to five.5% for a sixth consecutive convention on Wednesday. “The Committee doesn’t assume will probably be correct to reduce the think about selection proper till it has acquired elevated self-confidence that inflation is relocating sustainably towards 2%,“ the FOMC mentioned in a press release. “In addition, the Committee will stick with it lowering its holdings of Treasury securities and firm debt and firm mortgage‑backed securities.“ All by way of their earlier convention in March , policymakers indicated that they even now envisioned 3 curiosity cost cuts in 2024. But with inflation remaining sticky and unemployment being underneath 4%, these anticipations are attending to be a lot much less potential. Current financial information has not given the Fed self-confidence that inflation will go on to say no. Powerful inflation data within the very first quarter, coupled with a strong labor present market , have postponed anticipations for the very first Fed cost scale back. In April, Fed Chairman Jerome Powell, talking on the Washington Forum , designed it very clear that cost cuts have been not imminent because of the toughness of the financial system. The monetary state has preserved surprising momentum no matter the present-day stage of quick-phrase charges. With the unemployment quantity down under 4%, companies are steadily incorporating workers and genuine wage progress is observable as inflation eases. Whilst upward actions in inflation are noteworthy, sizeable growth towards the Fed’s 2% think about has been designed. “It’s unlikely that the upcoming plan quantity go can be a hike,” Powell knowledgeable journalists on Wednesday all through the FOMC’s press conference. “In buy to hike the premiums, we must should see persuasive proof that our plan stance will not be sufficiently restrictive to convey inflation sustainably all the way down to 2% round time. That will not be what we’re on the instantaneous.” While Powell emphasised the unlikelihood of foreseeable future quantity hikes, he additionally remained imprecise in regards to the Fed’s future want worth trajectory. “We didn’t see growth within the to begin with quarter. It seems that it’ll take into account longer for us to entry that time of self-assurance,” Powell acknowledged. “I have no idea how lengthy it’ll take into account. … My private forecast is that we are going to begin off to see growth on inflation this yr. I by no means know that will probably be ample to slash premiums we should allow the data lead us on that.” In a brand new progress, the Fed declared an easing of its quantitative tightening protection. Starting in June, the level-placing system will scale back the roll-off charge of its Treasury securities from $60 billion to $25 billion per thirty day interval. This signifies that when the Fed is not going to start providing Treasurys in June, it’ll enable for much less of them to mature. It is not going to change its roll-off cost for mortgage-backed securities (MBS), which is able to keep at $35 billion for every thirty day interval, based on Xander Snyder, senior industrial severe property economist at First American. “The FOMC didn’t remodel the continued passive roll-off of its MBS holdings however did be aware that any prepayments exterior of the persevering with $35 billion cap can be reinvested in Treasuries,” Mike Fratantoni, senior vice chairman and chief economist for the Property finance mortgage Bankers Affiliation, reported in a assertion. “We anticipate dwelling finance mortgage costs to drop afterwards this yr, however not as considerably or as quick as we beforehand skilled predicted.” In addition, Powell reiterated the Fed’s dedication to carrying forward the Basel III endgame guidelines in a means which is devoted to Basel and in addition equal to what the jurisdictions in different nations are endeavor. Because the March FOMC meeting, Freddie Mac’s strange 30-yr mounted property finance mortgage worth has enhanced from 6.74% to 7.17%. Ahead of the long run FOMC assembly on June 12, two supplemental inflation readings are anticipated. “While it’s an opportunity, I actually don’t assume that we’ll see an excellent deal enhance in dwelling mortgage premiums following this Fed convention, just because the Fed has been inclined to let the info direct at this section within the cycle,” Real property agent.com chief economist Danielle Hale defined in a press release. “In purchase to see mortgage prices drop rather more noticeably, the Fed will might want to see much more proof that inflation is slowing.”  For homebuyers and sellers, this suggests that housing affordability will stay a number one factor to contemplate, fairly presumably driving family purchases in economical markets, predominantly within the Midwest and South, based on Hale.

  • Atom financial institution cuts professional prices – Home loan Strategy

    Atom lender is reducing down the fascination premiums billed on its number of business mortgages by as much as .61%.

    The enhancements will see variable charges start at 2.04% in extra of basis worth, though preset prices begin out at 6.25% for loans with a best loan-to-worth of 45%.

    Atom financial institution’s assortment of commercial merchandise include enterprise banking secured loans (BBLS) and restoration financial institution loan scheme (RLS) options. Atom financial institution can be closing for brand new RLS apps from midnight Tuesday twenty eighth May presumably.

    The worth cuts, which see a recognizable scale back in RLS pricing specifically, are on a brief time period basis, so will solely make the most of till this date.

    Atom financial institution head of enterprise lending  Tom Renwick commented: “We know the way important worth is for professional prospects on the prompt, which is why we’re delighted to be succesful to make even additional reductions to our enterprise home loan charges. With the RLS coming to an end upcoming month, in particular person we wish to guarantee that companies are succesful to simply take benefit at the most effective achievable premiums on this answer.”

  • Retirement nest egg is not ample for many people right this moment, professional claims

    The mortgage mortgage stage pendulum swings however over again

    By Didier Malagies
    •
    18 Apr, 2024

    Expect 2024 to be mildly better than 2023 with mortgage charges slipping within the subsequent 50 % of the yr, housing specialists opined in their forecasts on the cease of the 12 months. Cuts to the Federal funds cost (and subsequently to property finance mortgage charges) are imminent, merchants enthused instantly after December’s convention of the Federal Open Current market Committee during which committee customers predicted a number of quantity cuts in 2024. Some specialists forecasted as a number of as six charge cuts within the 12 months centered on this information. Fee cuts are nonetheless coming, simply not in March , merchants and market specialists reasoned way more a short time in the past because the monetary system ongoing to run extremely scorching. And now on the heels of studies of extra strong than anticipated work growth and stickier than anticipated inflation , the market’s shift from optimism to pessimism above value cuts is full. Some even anticipate price hikes forward of charge cuts. The pessimism is apparent in residence finance mortgage prices. Freddie Mac‘s weekly Major Home mortgage Industry Study is climbing again to 7%. HousingWire’s Mortgage mortgage Charge Centre , which relies on details from Polly, is presently over 7.2%. Charges ended up as little as 6.91% for Polly and 6.64% for Freddie as a short time in the past as February. On Tuesday, they arrived at 7.50% on Home mortgage Information Day-to-day, a big for this yr. Home mortgage charges maintain essential energy within the housing market most significantly, important charges exacerbate the newest affordability catastrophe by walloping the getting electrical energy of would-be potential patrons and discouraging some would-be sellers – people with diminished, preset-charge residence loans – from itemizing their residences, a drain on on the market inventories. All this leaves housing execs as quickly as as soon as extra combating for their share of shrinking pies – as we’ve noticed with a short time in the past launched property finance mortgage information and RealTrends Verified’s brokerage particulars , as properly as deeper dives on the brokerage landscapes in Jacksonville and San Diego . It is unsurprising, then, that actual property shares have suffered contemplating that the FOMC’s March convention and the brand new profession and inflation studies. That incorporates the nation’s main homebuilders (DR Horton and Lennar), residence mortgage originators (United Wholesale Mortgage mortgage and Rocket House mortgage), brokerages (Any the place and Compass) and family search portals (Zillow and CoStar, which owns Properties.com). There are different dynamics at interact in for a few of these organizations, however. The brokerages are additionally contending with the rule modifications included in a proposed settlement by the National Affiliation of Realtors some merchants additionally suppose people rule changes benefit CoStar on the expense of Zillow . UWM, within the meantime, is contending with a scathing investigative report by a hedge-fund-affiliated info group whose hedge fund shorted UWM and went very lengthy on Rocket it is additionally working with pending litigation . UWM denies the allegations made within the report.  Superior residence finance mortgage prices, much less residence mortgage purposes and far much less property gross sales are nonetheless not the one results housing specialists might see from a extra extended high-rate atmosphere. There are additionally spillover outcomes from different industries, particularly enterprise workplace genuine property. Regional monetary establishments – which historically have been principal residential residence finance mortgage originators – went big on enterprise genuine property loans as better banking corporations scaled once more on this space in present many years. That better their publicity to downtown enterprise workplace towers, which have seen an exodus of tenants and a bottoming out of appraised values simply as a report $2.2 trillion in enterprise real property bank card debt will come owing above the long run variety of a number of years. That ties up money that might in any other case motion to residential residence loans and in some conditions stresses banking corporations like New York Neighborhood Lender, father or mother of Flagstar Financial establishment — the Seventh-most important monetary establishment originator of residential residence loans, Fifth-largest sub-servicer of mortgage mortgage monetary loans and the 2nd-biggest property finance mortgage warehouse lender within the area. Homebuilders, as properly, expertise the outcomes of prolonged important prices. Although homebuilder confidence is nonetheless up significantly contemplating the truth that final tumble, new housing begins are slowing . The dim potential patrons for homebuyers have turned some traders to the nascent develop-to-hire sector , primarily a wager that superior charges are proper right here to proceed to be for prolonged greater than sufficient that would-be shoppers are actually would-be renters.

  • Reverse home loans could support seniors make finishes fulfill, professional suggests

    The home finance mortgage charge pendulum swings however as soon as extra

    By Didier Malagies
    •
    18 Apr, 2024

    Count on 2024 to be mildly improved than 2023 with mortgage costs falling within the subsequent 50 % of the 12 months, housing gurus opined in their forecasts on the finish of the 12 months. Cuts to the Federal money degree (and subsequently to property finance mortgage premiums) are imminent, merchants enthused after December’s assembly of the Federal Open up Industry Committee wherein committee associates predicted a number of value cuts in 2024. Some specialists forecasted as fairly a number of as six value cuts within the 12 months depending on this data. Price cuts are nonetheless coming, simply not in March , merchants and present market gurus reasoned way more simply these days because the monetary system continued to run scorching. And now on the heels of tales of stronger than anticipated careers enlargement and stickier than anticipated inflation , the market’s change from optimism to pessimism about fee cuts is total. Some even anticipate fee hikes prior to cost cuts. The pessimism is noticeable in home mortgage premiums. Freddie Mac‘s weekly Principal House mortgage Market place Study is climbing again once more in route of seven%. HousingWire’s Property finance mortgage Fee Middle , which relies on data from Polly, is at present above 7.2%. Charges have been as small as 6.91% for Polly and 6.64% for Freddie as not too way back as February. On Tuesday, they attained 7.50% on Home mortgage Information Every day, a excessive for this calendar 12 months. Home mortgage expenses hold vital vitality within the housing area most significantly, substantial premiums exacerbate the present-day affordability catastrophe by walloping the buying electrical energy of would-be potential consumers and discouraging some would-be sellers – these individuals with small, preset-rate home loans – from itemizing their homes, a drain on obtainable inventories. All this leaves housing gurus when as soon as extra stopping for his or her share of shrinking pies – as we have now observed with a short time in the past unveiled home mortgage information and RealTrends Verified’s brokerage particulars , as properly as additional dives on the brokerage landscapes in Jacksonville and San Diego . It is unsurprising, then, that precise property shares have endured as a result of the FOMC’s March convention and the brand new job and inflation research. That incorporates the nation’s high rated homebuilders (DR Horton and Lennar), home finance mortgage originators (United Wholesale Home finance mortgage and Rocket House mortgage), brokerages (Any the place and Compass) and family lookup portals (Zillow and CoStar, which owns Residences.com). There are different dynamics at take part in for a few of these corporations, nonetheless. The brokerages are additionally contending with the rule enhancements built-in in a proposed settlement by the National Affiliation of Realtors some consumers additionally really feel these rule changes edge CoStar at the price of Zillow . UWM, in the meantime, is contending with a scathing investigative report by a hedge-fund-affiliated data group whose hedge fund shorted UWM and went extended on Rocket it’s also working with pending litigation . UWM denies the allegations designed within the report.  Higher property finance mortgage charges, fewer home mortgage applications and far much less family earnings are nonetheless not the one results housing business specialists could see from a much more prolonged high-price atmosphere. There are additionally spillover penalties from different industries, particularly enterprise workplace genuine property. Regional banking corporations – which normally have been key family mortgage mortgage originators – went vital on enterprise real property monetary loans as bigger banking establishments scaled again on this space within the newest a few years. That elevated their publicity to downtown workplace towers, which have considered an exodus of tenants and a bottoming out of appraised values simply as a doc $2.2 trillion in enterprise actual property debt arrives thanks in extra of the following couple many years. That ties up funds that could normally motion to family mortgages and in some situations stresses banks like New York Community Lender, mom or father of Flagstar Financial establishment — the Seventh-largest lender originator of family mortgages, Fifth-biggest sub-servicer of home mortgage monetary loans and the 2nd-biggest property finance mortgage warehouse monetary establishment within the nation. Homebuilders, as nicely, actually really feel the results of prolonged vital prices. While homebuilder assurance is even now up appreciably contemplating that final tumble, new housing begins are slowing . The dim potential purchasers for homebuyers have turned some buyers to the nascent create-to-lease sector , in essence a guess that vital prices are proper right here to proceed to be for extended ample that would-be potential consumers at the moment are would-be renters.

  • Significantly professional urges consideration of the dwelling when scheduling for retirement

    When creating retirement plans, individuals usually have a look at their investments and different fiscal belongings when pinpointing the long run class to get, however they not usually take note of what’s regularly their most necessary asset: their property.

    This is in accordance to Steve Resch, vp of retirement approaches at Finance of The us Reverse (Significantly), in a new column revealed by The Avenue.

    “[C]omparing the possible for return on funding choice (ROI) on residence possession to a extremely comparable and perfectly-recognized monetary dedication automobile or truck, the 401(ok), illuminates the so much less-explored monetary dedication seemingly inherent in a home purchase,” Resch reported.

    While prices related to homeownership are likely to dwarf expenditures which might be usually related with different kinds of investments, the requirement for getting a roof multiple’s head additionally will make the home a much more priceless asset that must be managed, Resch described. This calls for the separation of the dwelling’s profit from its worth, and managing it as the two “an monetary dedication asset as correctly as a important expenditure could make notion,” he talked about.

    Steve Resch

    There are additionally some noteworthy similarities between the home as an asset and a 401(ok) retirement account, he spelled out. Both belongings “are lengthy-time interval investments,” and regardless that “an distinctive would possibly carry out for a number of firms or buy a quantity of households throughout their lifetimes, they may potential pay into every particular person expense for 30 yrs or way more.”

    They additionally each of these have “systematic contribution choices,” along with payroll deductions for a 401(ok) account and month to month dwelling finance mortgage funds for a home.

    Financial advisers can be wise to take a look at these similarities, and “holding a property to the very same efficiency requirements usually utilized to a 401k can assist illuminate why a family as an monetary funding not solely will make notion, however supplies an probability that will be silly for any economical advisor to neglect,” Resch talked about.

    Homes and 401(ok) accounts alike additionally give their very personal tax rewards, and although a 401(ok) is designed to function an instrument to make {dollars} motion, property equity may additionally serve these varieties of a objective if an certified home proprietor considered as a reverse mortgage mortgage, he spelled out.

    “The commonplace protocol for accessing fairness has been to advertise the home,” Resch claimed. “However, when promoting a home does current get hold of to {dollars}, it additionally may exact a number of tolls on the vendor, which incorporates the expenditures and psychological results of the sale and going.”

    Resch has spelled out in the earlier why reverse mortgages could be employed as retirement getting ready gear.


  • ML-Implode News – Foreclosure Protection Legal professional Mark Stopa’s Suspension Is Helpful Instantly

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    2018-08-01 — mfi-miami.com

    &#13

    Florida Supreme Court docket Puts Mark Stopa Suspension Into Influence Immediately

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    provide write-up |&#13

    permalink |&#13

    talk about | &#13

    subscribe by:&#13

    |&#13

    RSS | &#13

    e-mail &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    Remarks:&#13

    Be the initially to incorporate a remark&#13

    &#13

    &#13

    insert a remark | go to discussion board thread

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13