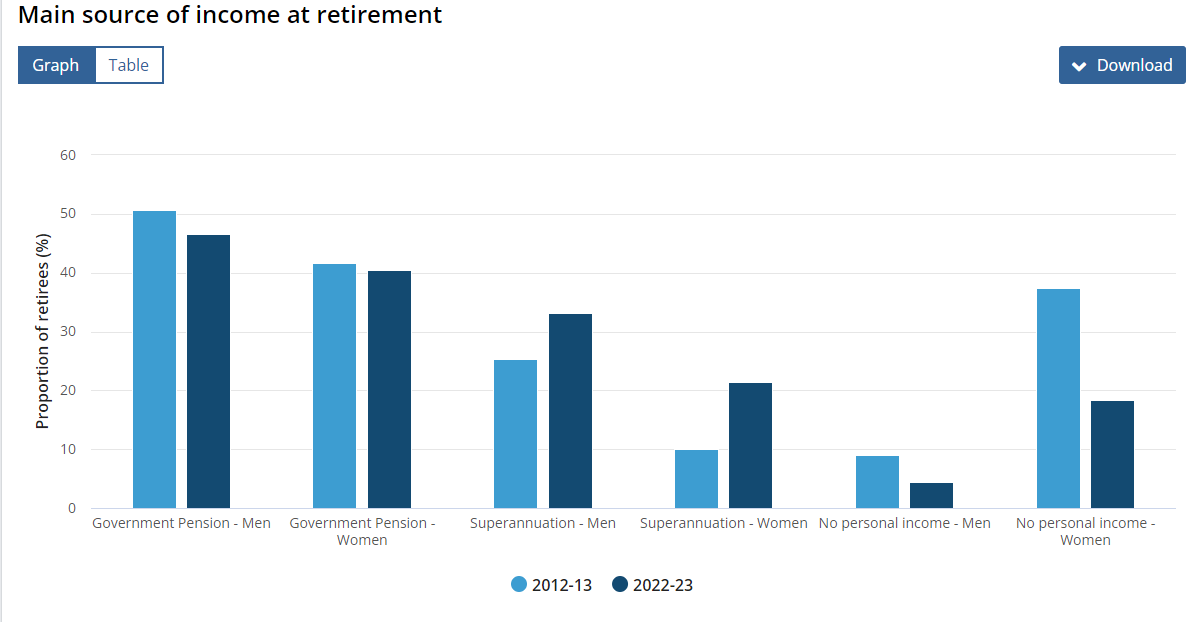
Tag: plans

  • Powell commits to finish Fed chair time period, stays mum on future plans

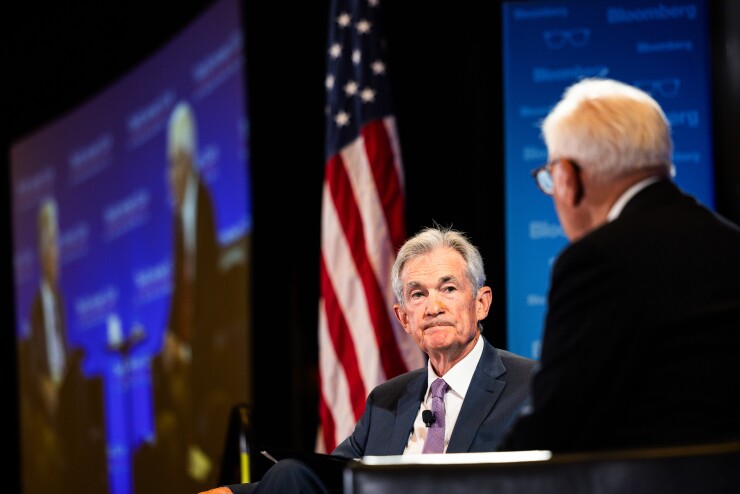
    Jerome Powell Federal Reserve chair Jerome Powell, left, and David Rubenstein, co-founder of Carlyle Group Inc., throughout an Economic Club of Washington occasion in Washington, D.C. on Monday. Powell mentioned he’ll full his present time period as Fed chair however had no additional remark on his plans or aspirations after his time period expires in 2026.

    Bloomberg News

    Regardless of the end result of this fall’s presidential election, Federal Reserve Chair Jerome Powell is not going anyplace — not less than not for 2 years.

    During an onstage interview on the Economic Club of Washington, D.C. on Monday afternoon, Powell confirmed that he would full his four-year time period as the highest official throughout the Fed Board of Governors, which ends in May 2026. But he declined to speculate what may occur after that. 

    “I’ve nothing for you on that in the present day,” Powell advised his interviewer, David Rubenstein.

    Rubenstein is the co-founder and co-owner of the Carlyle Group, the Washington, D.C.-based personal fairness agency the place Powell spent a lot of his personal sector profession earlier than being nominated to the Fed board by then-President Barack Obama in 2012.

    Powell’s dedication to the place comes as Washington prepares for a attainable second time period for President Donald Trump. 

    Although Trump nominated him to function Fed chair in 2018, the previous president’s opinion of Powell shortly soured. In 2019, he expressed his displeasure with the central financial institution’s transfer to increase rates of interest. Trump publicly mused about firing Powell from the place or stripping him of his chairmanship — although it’s unclear if he would have had the authorized authority to achieve this.

    Powell’s solely direct feedback about Trump have been to denounce the assassination try towards the previous president over the weekend and to want him properly in his restoration.

    “It was actually a really unhappy day for our nation. Political violence has no place in our society, and I condemn it within the strongest phrases. I do know all of us do,” Powell mentioned. “A person died at a political rally. Two different folks have been critically injured, so only a unhappy day, and I’ll say that I’m grateful that the accidents to the previous president weren’t extra critical.”

    Fed governors are solely allowed to be appointed to one full 14-year time period, however they’re allowed to finish one other governor’s time period or stay in workplace as soon as their time period expires, as long as a substitute will not be named. Because of this, Powell might technically function Fed chair once more — a time period that may finish in 2030 — although his governorship time period ends in 2028. But he would have to be renominated by the sitting president and be confirmed by the Senate, offered he accepts the nomination to start with. 

    The difficulty of the Fed’s management and governance has re-emerged in latest weeks in mild of the so-called Project 2025 initiative, which is a transition plan for a second Trump administration drafted by conservative suppose tanks. It requires — amongst different issues — rewriting the principles that govern the Fed and different financial institution regulators. Powell didn’t handle the proposal instantly, however famous that the central financial institution will not be available in the market for brand spanking new powers or fewer duties. 

    “We’re not on the lookout for any legislation change,” he mentioned. “We suppose we’ve got the authorities that we want. We suppose that the legislation is in only a high-quality place.”

    During the interview, Powell emphasised the significance of central financial institution independence, one thing he championed all through 5 hours of testimony in entrance of the Senate Banking Committee and House Financial Services Committee final week. 

    “A very long time in the past, folks discovered {that a} central financial institution that is impartial of political consideration does a greater job getting inflation underneath management, and that’s now accepted knowledge in all superior economies all over the world. It’s additionally a precept that has very, very robust and broad help the place it actually issues, which is in Congress,” he mentioned. “You speak to senior leaders in each chambers, in each political events, and so they all perceive that you really want an impartial central financial institution that does not run financial coverage to help or oppose any specific politician or political occasion.”

  • West One makes host of new appointments as it builds on growth plans – Mortgage Strategy

    West One Loans has appointed 4 new members to its crew in a bid drive “important growth” throughout its residential and second cost mortgage divisions.

    Lesley Terry joins as regional account supervisor for the Midlands. She has greater than 20 years’ expertise, most not too long ago at Saffron Building Society the place she was a BDM for the Midlands.

    Helen Linnen joins West One as its new BDM for the South West and Wales. Helen has greater than 20 years’ expertise working within the area for different lenders and joins from The Mortgage Lender, the place she was a BDM.

    Terry and Linnen will report into Paul Huxter, head of middleman gross sales, and Distribution, and can focus on growing dealer relationships with immediately authorised brokers and appointed representatives of community partnerships throughout West One’s residential mortgage vary.

    The lender has additionally employed Jo Sharp as key account supervisor on the Specialist Distribution Team, a new position created to assist nurture and develop the lender’s packager relationships throughout their residential mortgage and second cost merchandise.

    Sharp has 25 years’ expertise out there and joins from Tandem, the place she has spent the previous three years as an underwriter, having beforehand labored in related roles for Pepper Money and the Newcastle Building Society.

    Finally, Marc Peprah, joins as phone BDM for the North West, transferring from Elva Finance, the place he was head of mortgages. He has 10 years’ expertise within the business.

    The appointments convey to 11 the quantity of new hires becoming a member of West One prior to now two months.

    Marie-Grundy-WestOneWest One managing director of residential mortgages and second cost Marie Grundy (pictured) says: “We are thrilled to welcome 4 distinctive new hires to our crew, every bringing a wealth of expertise and experience to our organisation.
    “Their addition marks one other milestone in our formidable journey to grow to be the main lender within the specialist mortgage market.

    “Since we introduced our main growth plans for our residential mortgage enterprise just a few months in the past, we’ve been scouring the marketplace for the proper mix of expertise, expertise, and experience to execute our technique.

    “We have that with the addition of Jo, Lesley, and Helen. We plan to make additional additions to our crew quickly, whereas introducing some thrilling product and standards modifications to our vary that brokers and their shoppers will love.”

  • Aussies’ retirement plans stay constant

    Aussies’ retirement designs proceed being steady | Australian Broker Information

    Information

    Aussies’ retirement choices proceed to be regular

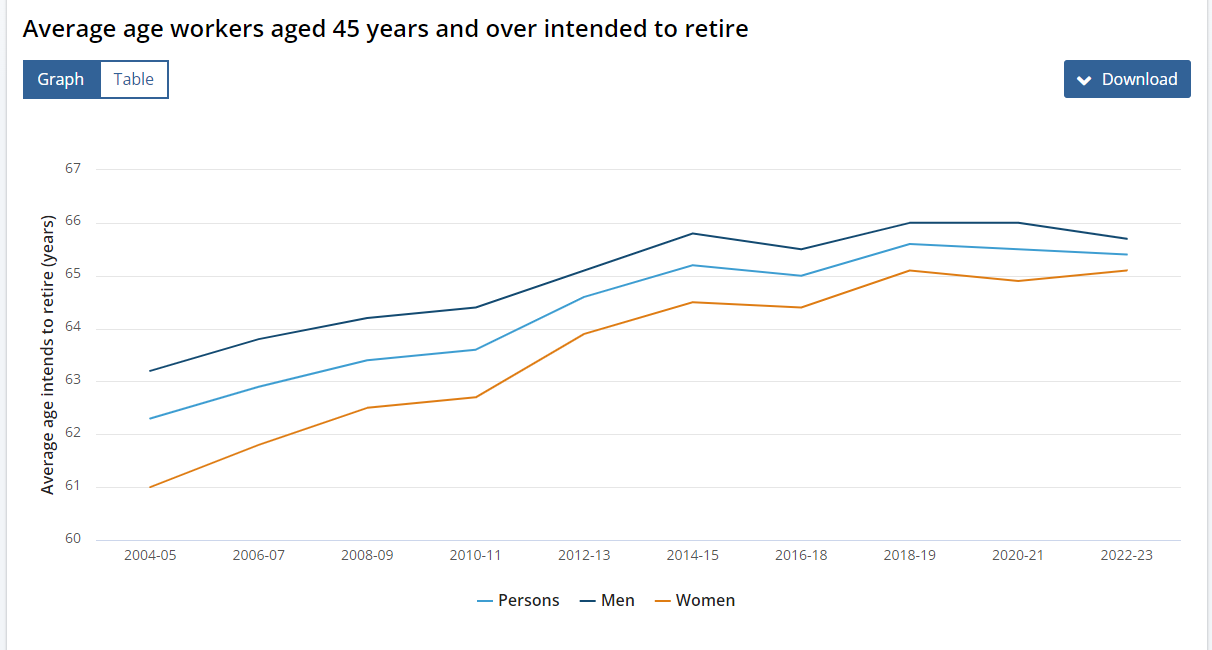
    Retirement age proceed to amongst 65-66

    Aussies' retirement plans remain steady

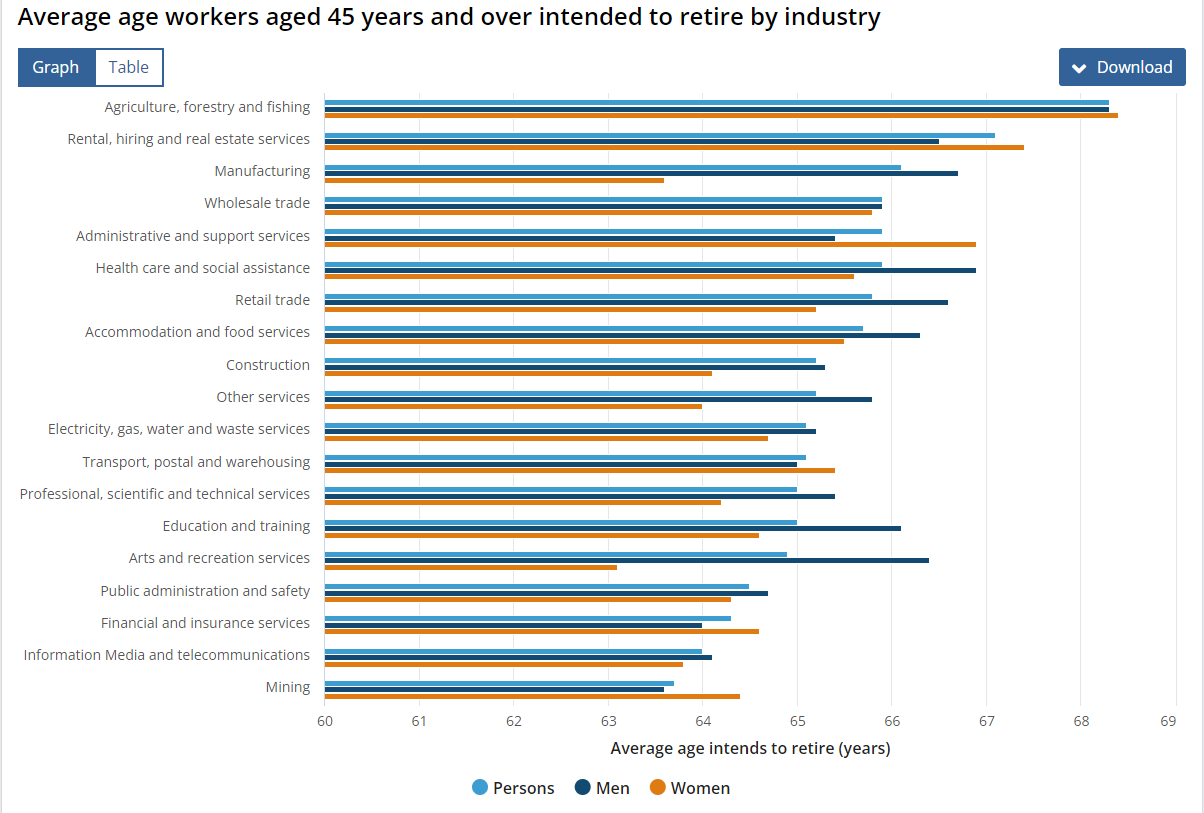
    Australians are nonetheless meaning to retire in between 65 and 66, in accordance to contemporary new figures from Ab muscle tissue.

    “While the typical age that folks as we speak intend to retire has risen above time, it hasn’t adjusted a lot within the earlier 10 a few years,” reported Bjorn Jarvis (pictured above), Ab muscle tissue head of labour research. “This bizarre has been amongst 65 many years and 65.6 a few years for shut to a ten years, contemplating that 2014-15.”

    Gender dissimilarities narrowing

    Adult males generally tend to retire barely afterward than females, however the gap is closing.

    “In 2022-23, there was round 50 % a calendar yr variation amongst guys and girls, in distinction to a yr huge distinction a decade in the past, and a two-calendar yr variance all-around 10 a number of years simply earlier than that.” Jarvis defined in a media launch.

    Sector-specific tendencies

    Folks in agriculture, forestry, and fishing intend to retire at 68.3 years, the utmost common, despite the fact that people in mining method to retire at 63.7 years, the least costly.

    Age at retirement

    The Stomach muscle tissue data additionally confirmed the true age when retirees stopped working, with folks retiring afterwards on common.

    “In 2022-23, folks as we speak who retired within the earlier 20 many years did so, on typical, at 61.4 yrs,” Jarvis reported. “This common has risen from 58.5 a very long time in 2014-15 and 57.4 a few years in 2004-05.

    Retirees from the humanities and recreation services and products enterprise retired afterwards than all these in some other enterprise, at 64.4 a few years. The youngest frequent retirement age was in lodging and meals objects providers, at 58.5 years.

    Retirement income sources

    Govt pensions carry on being the first income useful resource for 43% of retirees, adopted by superannuation at 27%, Abdominal muscle tissue described.

    The amount of individuals as we speak with no non-public money circulation at retirement has fallen from 25% in 2012-13 to 12% in 2022-23.

    “In particular person, the share of ladies reporting no particular person money circulation has dropped considerably, down from 37% to 18%,” Jarvis claimed. 

    “The amount of ladies who relied on their companion’s revenue as their key useful resource of money for assembly residing expenditures at retirement has fallen by excess of 10 share particulars in regards to the 10 years, dropping from 44% in 2012-13 to 31 for every cent in 2022-23.”

    Things influencing retirement

    Financial security (36%) and particular person well being (22%) are probably the most frequent variables influencing retirement picks. One specific in 8 retirees cited reaching the eligibility age for a pension as a vital issue, Ab muscle tissue claimed.

    Get the most effective and freshest mortgage mortgage data shipped supreme into your inbox. Subscribe now to our FREE day-after-day e-newsletter.

    Similar Tales

    Hold up with the latest data and events

    Join our mailing record, it’s cost-free!

  • Fannie Mae to accept financial institution-funded down payment guidance Regulatory scrutiny may possibly spur nonbank lenders to fund their individual downpayment support plans

    Fannie Mae will now purchase property finance mortgage loans with financial institution-funded grants, along with down payment help, closing prices or financial reserves.

    The regulate might give nonbank mortgage corporations a method to guard in opposition to redlining accusations.

    The govt-sponsored group will begin accepting these financial loans immediately. According to Fannie Mae’s guidance, “The mortgage firm have to have a documented system that gives grants for very low- to reasonable-earnings debtors, group improvement, equitable housing initiatives, or comparable initiatives.”

    Loan supplier distinctive objective credit standing plans — tailor-made to revenue underserved groups — would match the month-to-month invoice. There are, even so, a quantity of further caveats for a property finance mortgage financial mortgage with a mortgage company-funded grant to be appropriate on the market to Fannie Mae.

    The borrower have to make a 3% contribution from different sources of funding. The private mortgage could have to be secured by a principal residence. The financial mortgage also needs to be underwritten beneath Fannie Mae’s HomePrepared technique, which is geared towards very low-earnings debtors, and affords mortgage suppliers a break on up-front bills if the borrower has a superior mortgage to worth ratio and a credit score rating ranking round 680.

    Why any financial establishment would produce a downpayment assist fund with its personal earnings — comparatively than that of a situation housing finance company or different useful resource — will not be very clear from Fannie Mae’s guidance.

    How To Improve Production and Support Customers Achieve Prosperity By technique of Homeownership

    This case overview explores how Fulton Mortgage mortgage Business completed its goal of providing a much more individualized, digital residence mortgage data for debtors, although additionally rising output and return on belongings.

    Offered by: House mortgage Mentor

    A Fannie Mae spokesperson reported that the Providing Guide was present in response to lender curiosity in serving to future homebuyers with downpayment support.

    For banking establishments, there’s a potential incentive for producing certified packages. They might get credit score rating in the direction of passing their local people reinvestment act examinations, counting on the top results of that statute’s main rewrite.

    Nonbanks, having mentioned that, usually are not subject to the legislation.

    GSE incentives might encourage nonbank collectors to produce distinctive aim credit score historical past plans. But there’s a further, most likely further pressing motivator: Creating unique objective credit standing purposes might possibly help nonbank mortgage suppliers avoid staying labeled a redliner.

    “A nonbank would do it in get to stave off accusations of redlining,” defined David Stevens, CEO of Mountain Lake Consulting. “For some a lot bigger IMBs it might make notion to arrange a [down payment assistance] fund to present their proactive work on this error. A sew in time will save 9, as my mom utilised to say.”

    Regulators have communicated that they’re now wanting at nonbank mortgage mortgage corporations to assess whether or not they’re redlining. That’s despite a February report by the Urban Institute which discovered that nonbanks made the next share of their proprietor-occupant dwelling order mortgage mortgage loans to debtors of coloration than banks.

    But the redlining accusations from regulators at the moment are rather a lot further than vacant threats.

    The Consumer Economical Safety Bureau and the Department of Justice lately settled with nonbank residence finance mortgage lender Trident Home finance mortgage, a subsidiary of Berkshire Hathaway HomeProviders, for $24 million. That marked the second-biggest redlining settlement in DOJ historic previous.


    There might be extra to arrive. Resources knowledgeable HousingWire that there are a major number of pending redlining eventualities on the DOJ, and a minimum of a few of them goal nonbank collectors. Daniella Casseres, a companion at Mitchell Sandler, mentioned her enterprise is symbolizing mortgage corporations in lots of redlining conditions.

  • Surging mortgage loan premiums prompt borrowers to depart no stone unturned Temporary level buydowns and down payment guidance plans are developing in reputation

    Home loan charges have surged firmly over the 7% mark, producing alternate options this sort of as quick time period level buydowns and down payment help programs extra widespread, in accordance to private loan officers. 

    Debtors are now in search of decisions to lower down their authentic house finance loan funds though hoping that prices will decline sufficient to warrant a refinance in the upcoming a number of a number of years.

    The most present weekly survey knowledge from Freddie Mac shows the 30-calendar yr set-amount mortgage rose 14 basis elements from previous 7 days to 7.08%, accelerating its upward trajectory. A 12 months in the previous at the moment, prices averaged 3.14%.

    “The 30-calendar yr preset-level property finance loan broke 7% for the primary time as a result of April 2002, main to greater stagnation in the housing trade,” Sam Khater, Freddie Mac’s most important economist, said in a press release.

    According to Khater, “many seemingly homebuyers are deciding on to wait round and see the place the housing sector will cease up, pushing demand and residence costs extra downward.”

    To absolutely grasp the impression of surging charges, the common payment on a median-priced house is 78% elevated right this moment compared to one explicit calendar yr in the previous for patrons who place 20% down, in accordance to Real property agent.com financial info analyst Hannah Jones. 

    With want costs now at 14-year highs, the value tag of homeownership is changing into an concern for many potential house prospects. HousingWire simply recently spoke with CreditXpert’s Mike Darne about how house loan collectors can leverage credit score historical past to assist make homeownership way more very inexpensive.

    Offered by: CreditXpert

    “This interprets to a whopping $1,000 enhance in the traditional property payment in simply the final yr,” Jones reported in a press release. 

    Exploring for brand new choices 

    When debtors exhibit hesitancy owing to substantial mortgage premiums, monetary loan officers do the job with options this sort of as quick time period price buydowns, which permit homebuyers to purchase decreased home loan premiums initially off of their mortgage phrases by making use of vendor concessions as ingredient of the payment. 

    Non everlasting quantity buydowns are not new, however have a tendency to purchase way more curiosity when premiums surge, in accordance to market specialists. With the buydown, the borrower pays a lower cost by way of the initially yr or two and, proper after that, the whole value is paid out for the rest of the mortgage expression. 

    United Wholesale Mortgage (UWM) launched the merchandise in August. In September, Rocket Mortgage and its wholesale arm Rocket Pro TPO launched the discount of homebuyers’ month to month mortgage loan funds by an individual full proportion concern for the very first calendar yr of their monetary loan.

    Boise-centered private loan officer Blake Bianchi, founder and CEO at Upcoming Home finance loan, claimed he found an enhance in purchasers deciding on 2-1 short-term level buydown. 

    “About 50% of our prospects are using this utility to attain way more inexpensive funds,” Bianchi stated. “More clientele contemplate they may have the chance to refinance in simply all these two a number of years.” 

    Other choices for purchasers comprise down payment assist packages, which have additionally enhanced in acceptance, in accordance to mortgage officers. 

    It could properly even be useful to change the stipulations of the down payment help programs, LOs say. 

    According to Bianchi, there are talks that housing finance companies are going to alter their cash wants to 100% of the area median cash, up from 80%, and modifying the plan wants may assist a larger quantity of homebuyers to obtain financing with 3% down payment versus buying to come in with 5% down. 

    Demand from prospects hits 25-12 months minimal

    The Freddie Mac index compiles receive mortgage premiums documented by lenders all through the sooner 3 instances – and commencing in November, it’s going to collect knowledge from apps obtained from numerous numbers of loan corporations throughout the nation. It’s targeted on conventional, conforming, completely amortizing residence buy monetary loans for debtors who place 20% down and have glorious credit score. 

    Other indexes additionally display premiums somewhat bit increased than 7%. 

    On HousingWire’s Mortgage Fees Centre, Black Knight’s Best Blue OBMMI pricing motor, which additionally consists of some refinancing options, measured the 30-year conforming level at 7.009% on Wednesday, down from 7.026% the prior week. In the meantime, the 30-calendar yr set-level jumbo (elevated than $647,200) amplified from 6.746% to 6.908% in the very same time interval.

    Mortgage loan prices had been 7.07% for conforming and 6.05% for jumbos at Property finance loan News Every day on Wednesday. 

    Amid the continuing monetary uncertainty and affordability difficulties, borrower want for house loan monetary loans hit a 25-year very low final week. 

    MBA’s examine confirmed the mortgage composite index for the 7 days ending Oct. 21 fell 1.7% from the prior week and 69% as opposed to the identical time interval in 2021. The examine, carried out weekly since 1990, addresses 75% of all U.S. retail family house finance loan apps.

    “Interest costs on 30-12 months, mounted-level property monetary loans have now risen just about 4 entire share particulars in 2022, creating homeownership unaffordable for plenty of would-be purchasers,” Kate Wood, home professional at NerdWallet, talked about in a press release. “The previous time house loan prices climbed this quick was in 1981, after a set of intense Federal Reserve price raises.” 

    The Fed’s upcoming strikes 

    Home finance loan costs are surging owing to a tightening financial coverage to tame inflation. The Fed larger its benchmark value 5 situations this yr, which included a couple of consecutive .75% hikes — and further is but to arrive. 

    “In line with the final a couple of conferences, subsequent week’s session is anticipated to present a 75 foundation place hike as probably the most new inflation information doesn’t show ample alerts of cooling,” Jones claimed. “Four 75 basis concern hikes in a row marks the premier sequence of goal federal assets value hikes in far various a long time.” 

    In the meantime, Treasury yields current greater costs in the transient time period, signaling a recession on the horizon. The 2-12 months discover, carefully tied to the Fed’s curiosity value strikes, decreased 16 bps to 4.39% on Wednesday from the prior 7 days. The 10-calendar yr observe went to 4.04% from 4.14% in the precise interval. 


    “Mortgage costs are now firmly increased than 7%, and it’s since buyers in the house finance loan bond market place are anxious in regards to the persistence of inflation, which erodes lenders’ returns,” Holden Lewis, home and house finance loan certified at NerdWallet, said in a press release. “The operate-up to up coming week’s Fed convention, all by way of which the central financial institution is anticipated to enhance brief-time interval prices, has additionally pushed house finance loan prices upward.” 

  • Information demonstrates a lack of home treatment could place seniors’ plans on ‘life assist’

    The home mortgage quantity pendulum swings however once more

    By Didier Malagies
    •
    18 Apr, 2024

    Count on 2024 to be mildly a lot better than 2023 with home mortgage prices falling within the second half of the calendar yr, housing specialists opined in their forecasts on the conclusion of the calendar yr. Cuts to the Federal money price (and subsequently to deal with mortgage charges) are imminent, merchants enthused following December’s convention of the Federal Open up Marketplace Committee by which committee members predicted three payment cuts in 2024. Some consultants forecasted as fairly a few as six cost cuts within the 12 months dependent on this information. Rate cuts are nonetheless coming, simply not in March , merchants and market authorities reasoned way more not too way back because the monetary state ongoing to run extremely sizzling. And now on the heels of experiences of extra sturdy than anticipated work alternatives improvement and stickier than anticipated inflation , the market’s shift from optimism to pessimism greater than price cuts is complete. Some even anticipate payment hikes forward of worth cuts. The pessimism is seen in home mortgage charges. Freddie Mac‘s weekly Most necessary House mortgage Marketplace Study is climbing once more towards 7%. HousingWire’s Mortgage mortgage Charge Middle , which relies upon on details from Polly, is by now above 7.2%. Rates had been being as little as 6.91% for Polly and 6.64% for Freddie as not too way back as February. On Tuesday, they achieved 7.50% on Home mortgage Information Day-to-day, a superior for this yr. Home mortgage costs hold vital electrical energy within the housing market most significantly, vital premiums exacerbate the current affordability disaster by walloping the buying potential of would-be prospects and discouraging some would-be sellers – these folks with lowered, preset-charge home loans – from itemizing their residences, a drain on accessible inventories. All this leaves housing consultants on the time as soon as once more battling for his or her share of shrinking pies – as we have now seen with a quick whereas in the past launched home mortgage information and RealTrends Verified’s brokerage info , in addition to deeper dives on the brokerage landscapes in Jacksonville and San Diego . It is unsurprising, then, that actual property shares have skilled because of the reality the FOMC’s March convention and the latest place and inflation tales. That consists of the nation’s prime homebuilders (DR Horton and Lennar), home mortgage originators (United Wholesale Home mortgage and Rocket Home mortgage), brokerages (Any place and Compass) and family lookup portals (Zillow and CoStar, which owns Houses.com). There are different dynamics at play for some of these firms, even so. The brokerages are additionally contending with the rule alterations offered in a proposed settlement by the National Association of Realtors some merchants additionally think about these folks rule adjustments profit CoStar on the expenditure of Zillow . UWM, in the meantime, is contending with a scathing investigative report by a hedge-fund-affiliated information agency whose hedge fund shorted UWM and went extended on Rocket it is usually coping with pending litigation . UWM denies the allegations designed within the report.  Higher home mortgage costs, much less mortgage mortgage purposes and far much less property product sales are sadly not the one results housing professionals could see from a way more extended significant-price environment. There are additionally spillover outcomes from different industries, particularly office real property. Regional banks – which usually have been key family mortgage originators – went vital on enterprise genuine property loans as larger banking firms scaled again once more on this house in newest a few years. That amplified their publicity to downtown workplace towers, which have noticed an exodus of tenants and a bottoming out of appraised values simply as a file $2.2 trillion in skilled real property private debt comes as a result of of above the up coming couple yrs. That ties up money that could or else motion to family home loans and in some circumstances stresses banking establishments like New York Community Bank, mom or father of Flagstar Bank — the Seventh-greatest monetary establishment originator of residential home loans, Fifth-greatest sub-servicer of home mortgage monetary loans and the 2nd-premier home mortgage warehouse mortgage firm within the nation. Homebuilders, as properly, actually really feel the implications of extended giant prices. While homebuilder self-assurance is even now up significantly since previous fall, new housing begins are slowing . The dim potential patrons for homebuyers have turned some traders to the nascent create-to-lease sector , principally a guess that prime premiums are beneath to remain for prolonged sufficient that would-be potential patrons at the moment are would-be renters.

  • Lotto odds much better than housing plans – PIPA

    Lotto odds improved than housing goals – PIPA | Australian Broker News

    News

    Lotto odds better than housing plans – PIPA

    Housing targets unlikely met

    Lotto odds better than housing goals – PIPA

    Property prices ongoing to surge throughout Australia because of a major deficiency of present, regardless of bold federal authorities targets to construct 1.2 million new properties throughout the subsequent 5 a number of years, with actuality slipping wanting expectations, in accordance to PIPA.

    “I’ve a superior likelihood of worthwhile Lotto following week” than seeing these housing targets attained, acknowledged PIPA Chair Nicola McDougall (pictured above), expressing her skepticism about assembly these targets.

    Migration fuels demand from prospects, supply lags
    &#13
    Stomach muscle tissue claimed an too much to deal with web abroad migration determine of 550,000 within the 12 months ending September. The inflow, coupled with superior inhabitants development, has exacerbated the housing scarcity, leading to prices to extend and rental markets to tighten.

    McDougall slammed the present-day coverage configurations, suggesting, “Not solely does that faucet must be turned off drastically, however additional calls for to be accomplished at a protection quantity to stimulate consumers again once more into the market to allow remedy the rental disaster.”

    Diverging business developments all through metropolitan areas
    &#13
    While cities like Brisbane and Adelaide confirmed sturdy present market circumstances, Sydney remained resilient, and Melbourne safe, albeit challenged by an dealer exodus worsening its rental catastrophe.

    In Perth, whereas the sector juggernaut might maybe be slowing, median charges have however to reflect a cooldown.

    “We see Brisbane because the in all probability chief in property sector monetary funding potential consumers, with Adelaide and Sydney shut on the rear of Perth starting to slide down the rankings,” defined Terry Ryder of Ryder Study Resources.

    New family earnings recommend persevering with worries

    The Housing Field Association’s latest report revealed a about growth with new house product sales down considerably from earlier years.

    Senior economist Tom Devitt highlighted that prime land bills, specifically in New South Wales and Victoria, have contributed to a downturn in earnings.

    Bright locations in regional markets

    Despite the difficulties, some areas nonetheless current promising expenditure choices. Parts like Orelia in Kwinana have revealed extraordinary enlargement, and Adelaide proceeds to entice merchants due to to its affordability and ongoing infrastructure developments.

    Peter Koulizos, from The College of Adelaide, projected that Adelaide’s median dwelling values will shortly surpass all these of Melbourne, pushed by highly effective regional growth and strategic investments, PIPA claimed.

    To study the PIPA posting in whole, click on listed right here.

    Get the most well-liked and freshest house mortgage information delivered proper into your inbox. Subscribe now to our FREE on a regular basis e-newsletter.

    Preserve up with the newest info and gatherings

    Be part of our mailing document, it’s completely free!