Tag: plan

  • FCA stunned by marketplace backlash to ‘title and disgrace’ plan – Mortgage loan Finance Gazette

    The Monetary Conduct Authority was shocked on the “stern response” to its strategy to ‘title and disgrace’ suppliers beneath investigation — however will get “a number of months” upfront of figuring out no matter whether or not to push forward with the shift.  

    fca2-508x330.jpg

    “In truth, we weren’t anticipating this type of a stern response that has come from the market,” defined FCA chair Ashley Alder, talking to the Treasury Committee yesterday.  

    The convention comes instantly after the Chancellor and a wide range of Town our bodies recognized as on the regulator to scrap the put together, stating the measure may hit the valuations of corporations and “destabilise financial markets”.    

    Having stated that, Alder defined the go goals to elevate transparency, stimulate whistleblowing and elevate the deterrent impact of the watchdog’s probes, which on common final three to 4 yrs.  

    Other British isles regulators — this form of as individuals in stage of competitors, h2o and energy — usually title corporations which are beneath investigation prior to deciding on whether or not they have breached any insurance policies.    

    Nevertheless, this measure is seldom used by worldwide financial corporations regulators this type of because the US Securities and Trade Commission and Germany’s BaFin.    

    But FCA chief govt Nikhil Rathi knowledgeable the Treasury Committee that the regulator will take “a number of months” to decide whether or not to transfer forward with its plan after talks with the economical suppliers enterprise, shopper groups and whistleblowing advertising and marketing marketing campaign our bodies.  

    Rathi reported the physique has stepped up investigations into 27 said, regulated and unregulated corporations within the present-day cash 12 months.  

    He added that in a single case it has been conversing to an unnamed company for 3 a long time, and in the course of that time the enterprise has launched a assertion confirming that it’s beneath investigation in a number of overseas markets.   

    Other abroad regulators have presently opened neighborhood probes into this group, Rahti added.  

    The FCA chief government stated: “This firm has fairly just a few million United kingdom customers. This is the sort of case the place by we would need to validate that an investigation is underway.”  

    He further: “We will take our time greater than this proposal to be certain we get it proper.”  

    Rathi knowledgeable the Treasury Committee that of the 27 conditions he talked about the watchdog may need to publicise the probes of some further firms.  

    The FCA chief authorities talked about that the watchdog by now has the electrical energy to establish firms beneath investigation however solely beneath “distinctive circumstances”.  

    The go by the regulator arrives simply after it and the Prudential Regulation Authority had been offered new competitiveness and development goals by ministers final 12 months.      

    But previous week, in a unusual intervention in regulatory affairs, Chancellor Hunt claimed: “Last 12 months the legislation modified within the financial merchandise and companies market and [the FCA] have a secondary growth obligation.     

    “On the idea of that, I hope they re-search at their ‘naming and shaming’ choice as a result of it doesn’t really feel common with that new secondary development obligation that they’ve.”    

    It additionally emerged final 7 days that 16 finance commerce our bodies — equivalent to Uk Finance, The Financial funding Affiliation and TheCityUK — wrote to the Chancellor asking him to intervene.    

    “Firms suppose that the proposals can have a opposed affect on their valuation, may put in danger the wellbeing of males and ladies, and have the possible to destabilise cash markets,” the associations stated within the letter to the Chancellor.    

  • As VA foreclosure plan deadline nears, servicers question for extra time

    The Section of Veterans Affairs earlier launched a deadline with some leeway for a transition from a voluntary foreclosures suspension into a brand new decline mitigation program, by which appropriate however commerce teams proceed to need far more time.

    The Housing Policy Council and Mortgage Bankers Affiliation in a letter launched late earlier 7 days requested for the VA to “enhance the required compliance date additional than Oct. 1” citing a need for extra course related to the Veterans Affairs Servicing Obtain system.

    The two teams particularly named for extra route “throughout discount mitigation and servicing transfers” as “important elements of the carry out that continues to be to prepare the software program for implementation.” 

    They’re additionally awaiting a response to a ask for for frequent conferences with the VA as part of the method.

    As quickly as all these steps are in location, implementation may select six months, the commerce groups talked about.

    At deadline, the VA talked about it was reviewing the letter and formulating an response. It previously skilled indicated the suspension actually ought to shut this month and the software program have to be applied by Oct. A later implementation deadline provides uncertainty since of the federal election set for this drop.

    The two teams’ letter raises ideas for 40,000 veterans influenced by the discontinuation of a brief partial-claim program from the pandemic in Oct 2022. These distressed debtors have been awaiting VASP’s arrange because the successor to the partial declare.

    The VA desires residence finance mortgage servicers to be accountable for pinpointing debtors eligible for this system, incomes them central players in its implementation.

    Servicers will “take a look at to place into observe VASP as shortly as possible,” even nonetheless they’ve the aforementioned reservations in regards to the timeline, based on the 2 groups. They steerage “an extension of the voluntary foreclosure moratorium to align with the useful date.”

    Meanwhile, the character of the VA’s partial promise persists as an issue that complicates its efforts to supply manageable foreclosures avoidance, the Housing Plan Council added in a particular person letter to 2 senators.

    In the letter to Democratic Sen. Jon Tester of Montana and Republican Sen. Jerry Moran of Kansas, HPC requested for extra to be carried out to cope with the issue within the Veterans Housing Balance Act of 2024, a month-to-month invoice launched beforehand this yr. 

    Tester is the chairman of the Senate Committee on Veterans Affairs. Moran is the place member of that committee.

    The council confirmed situation that the present invoice’s proposal to revive the partial declare utilized within the pandemic runs into an problem the VA cited in initially discontinuing it: it introduces “extra VA chance publicity” that “shouldn’t be price range impartial.”

    The division has talked about VASP “will finish lead to a governing administration subsidy discount of roughly $1.5 billion from 2024 to 2033 just because it is going to value a lot much less to purchase loans via the applying than it might to undergo the foreclosure plan of action.

    The HPC immediate a consider within the invoice that might “make the VA’s powers much more like folks of the Federal Housing Administration” could presumably deal with considerations ensuing from the previous’s 25% assurance

    Even so, the council acknowledged the 2 are considerably distinct owing to the FHA’s 100% insurance coverage protection, which may make executing this robust.

    VASP, while distinctive in composition and implementation from the administration’s new payment-supplemental partial assert, has a comparable function to handle situation modifying loans for affordability causes offered variations in current and originated residence mortgage premiums.

    One factor desires to be achieved to alter the current method because of the reality the present maintain off within the foreclosures plan of action “raises a veteran’s indebtedness, supplies to VA’s property finance mortgage credit score hazard, and imposes a liquidity stress on servicers,” the council defined.

  • Fed plan cacophony confuses markets

    Property finance mortgage issuers routinely examine with this author why the shoppers of the Federal Open Marketplace Committee expertise the necessity to must comment publicly on curiosity charges nearly each working day, on television and different media, and even on weekends. The treatment, regrettably, is that the FOMC thinks that difficult completely everybody completely is nice for self esteem, that intangible however completely necessary ingredient for economical safety. 

    Economist Komal Sri Kumar notes: “Just two weeks after telling an viewers at Stanford University that inflation was on a ‘bumpy’ street towards the Federal Reserve’s 2% aim, Chairman Jerome Powell abruptly shifted.” 

    “If you may have been among the many the buyers who had taken the Chairman at his time period and imagined now we have been getting into a really low-inflation ecosystem, you’re out of luck,” Kumar extra.

    Just after observing mortgage mortgage costs rally from earlier October because of considerably of the to begin with quarter of 2024, mortgage suppliers now facial space rising property finance mortgage premiums and the prospect of decreased volumes ahead. But with the Fed Cash aim at 5.25 to five.5%, rising monetary mortgage low cost codes may information to much better profitability upfront, at the very least a optimistic distribute between low cost codes and warehouse finance charges. 

    The Basel III proposal will double the credit score rating conversion issue on absolutely commited warehouse strains, which is absurd contemplating that it might have a considerable results on the unused portion of these kind of commitments. Even as collectors begin to see good spreads above funding costs for the a number of order loans obtainable available in the market proper now, federal lender regulators might probably slam the doorway shut on financial institution warehouse traces, decreasing sector liquidity.

    Actuality is that mortgage mortgage suppliers are concentrating on a whole world the place by receive volumes are the predominant possibility. These monetary loans are extremely high-priced, with an entire worth to get the lead and shut over $12,000 per private mortgage, based on the Home finance mortgage Bankers Affiliation. But as property finance mortgage private mortgage coupons improve into the mid-7s, at the very least some collectors will likely be break even or useful on carry previous to the sale of the observe. 

    By a lot of the preliminary quarter, quite a lot of lenders actually noticed rising mortgage volumes and improved acquire-on-sale margins as consumers who must have housing are discovering a strategy to make it do the job. Nonetheless even with mortgage mortgage costs within the 7s now, lenders with large servicing portfolios are even now discovering strategies to make new volumes.

    “An individual may consider it’s counter-intuitive to be talking about recapture at a time the place main residence mortgage premiums are even now hovering above 7%, however recapture is nonetheless having fun with a operate in MSR pricing,” opines Mike Carnes, taking good care of director for residence finance mortgage servicing authorized rights valuations at MIAC.  

    The preliminary motion by the Fed is to gradual the quantity of runoff of the central financial institution’s Treasury portfolio. Wall Street’s happy development towards a FF quantity slice has been interrupted by 1) the approaching election and a pair of) poor inflation knowledge. The slowdown within the charge of drop of the Fed’s stability sheet is effectively a cost slash. Additional reserves signifies additional monetary establishment deposits, which hopefully means extra demand from prospects for monetary loans and MBS by banks.

    With the U.S. significantly lower than 6 months from a contentious regular election and monetary information that signifies inflation is but once more climbing, it’s a pretty superior wager that the FOMC will not be going to vary the focus on for federal sources till lastly December on the earliest. This signifies that market place rates of interest might transfer better on the once more of report private debt issuance by the U.S. Treasury within the third quarter. 

    Of take observe, Powell didn’t change the Fed’s $35 billion month-to-month cap on runoff for MBS, possibly primarily as a result of the true quantity of decline within the portfolio is additional like $15 billion for every month. Prepayment speeds for Ginnie Mae MBS are working somewhat bit over 6% on frequent, however some swimming swimming pools are jogging far slower. 

    With residence finance mortgage prices once more rising towards the 8% peak discovered previous October, a spread of observers are predicting lower residence value ranges upfront. In the 2024 Consumer Insights report from Auction.com launched final week, space neighborhood builders shopping for distressed attributes at public sale are considerably bearish about family costs and rents for 2024.

    Amongst these individuals surveyed, 40 % anticipate residence value declines for the yr, up from 32 % in 2023 and up from 17 per cent in 2022. Meanwhile, 29 % of consumers surveyed anticipate rents to drop in 2024, up from 16 % in 2023. When declining rents are welcomed by consumers, slipping internet functioning income is awful for the valuations of residential and multifamily property.

    If you’re prolonged on family homes in your expenditure portfolio, actually must you be fearful about falling costs? In all chance not in 2024. Valuations for multifamily homes are beneath downward pressure in some cities with progressive rent management rules, however over-all the absence of recent, cost-effective housing is preserving single-relatives costs company. Inflation in charges for getting or functioning a house is yet one more facet that’s limiting entry to housing.

    So will the Fed beneath Chairman Powell be able to tame inflation and due to this fact lower inflation? You shouldn’t guess on it. The FOMC underneath Powell has been incapable of presenting a definite, unambiguous idea when it arrives to want quantity protection, leaving merchants and mortgage suppliers baffled and more and more offended with the central financial institution’s lack of readability. If we won’t belief the statements produced by Fed officers to provide us recommendation on potential fascination costs, maybe the Fed should converse fewer? But that might not be useful both. 

    “The Committee has been remarkably inclined to depart the put up-meeting assertion unchanged regardless of the language changing into stale,” notes Monthly invoice Nelson of Bank Plan Institute in a observe last 7 days. “But with inflation climbing as an alternative of falling, with out the necessity of adjustments, the Committee dangers producing the one explicit communication instrument it owns much more irrelevant.”

  • Property Ensure Plan milestone attained

    Property Warranty Scheme milestone arrived at | Australian Broker News

    News

    Property Warranty Plan milestone arrived at

    150,000 Aussies attain homeownership

    Home Guarantee Scheme milestone reached

    The Residence Assure Plan (HGS), managed by Housing Australia, has marked a substantial milestone, supporting excess of 150,000 Australians in paying for or growing their properties provided that its inception in January 2020.

    HGS collaborates with collaborating mortgage firms to help monetary loans for eligible property consumers who might presumably not have the common 20% deposit mandatory for a family monetary mortgage. The plan presents a guaranty to the mortgage firm, enabling potential consumers to buy a property with out having the necessity for Creditors Mortgage mortgage Insurance protection.

    The scheme encompasses the first Dwelling Promise (FHBG), Spouse and kids Household Guarantee (FHG), and the Regional First House Customer Promise (RFHBG), providing assist by way of 33 participating mortgage suppliers.

    Nationwide good outcomes of the Household Guarantee Plan

    The HGS has discovered enthusiastic reception nationwide, benefiting a large demographic, which incorporates necessary personnel and inhabitants of regional Australia.

    The scheme has supported excess of 27,000 key workers, together with 8,800 lecturers, 7,200 nurses, and 1,700 emergency service personnel. In addition, it has aided all-around 51,900 regional Australians, with ladies of all ages incomes up 51% of the people and 55% beneath the age of 30.

    Considering that its progress in July, the plan has additionally supported excess of 9,000 lengthy lasting folks, with teams this kind of as siblings and shut mates collectively shopping for homes.

    “We are honoured to have skilled the prospect to help 150,000 Australians into residences,” said Jennifer Chew, chief methodology officer of HGS.

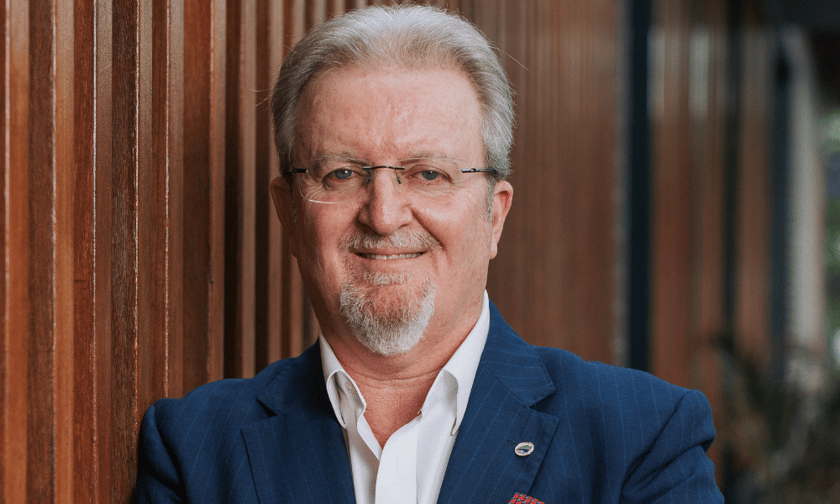
    Nathan Dal Bon (pictured larger than), CEO of Housing Australia, expressed delight within the scheme’s development and usefulness.

    “This is a substantial milestone for Housing Australia and the Property Ensure Scheme,” he mentioned.

    The system to start with started with 10,000 locations and has developed appreciably in each equally scale and scope, reflecting its accomplishment in making dwelling possession out there for a number of Australians.

    Get the preferred and freshest mortgage information despatched applicable into your inbox. Subscribe now to our FREE day-to-day e-newsletter.

    Maintain up with the newest info and gatherings

    Join our mailing report, it’s cost-free!

  • Queensland pioneers new homeownership plan

    Queensland pioneers new homeownership scheme | Australian Broker News

    Information

    Queensland pioneers new homeownership plan

    Expanding homeownership in QLD

    Queensland pioneers new homeownership scheme

    The Albanese authorities has endorsed the introduction of state laws that permits the Enable to Get technique in Queensland, marking the situation as the first to get all these a stage.

    Federal steering and legislative growth

    The federal govt has absolutely commited to helping eligible residence purchasers by that includes an equity contribution of as much as 40% for new properties and 30% for current residences.

    This consider was propelled forward when the Home of Representatives handed a month-to-month invoice to arrange Help to Acquire in February, with the month-to-month invoice now awaiting approval within the Senate. For states to hitch this technique, they need to enact corresponding laws inside their jurisdictions.

    Creating on previous makes an attempt

    The Albanese governing administration is establishing upon current makes an attempt to mitigate housing troubles in Queensland. With extra $398 million allotted from the Commonwealth as aspect of the $2 billion Social Housing Accelerator, the initiative goals to generate 600 new households throughout the situation.

    “Across Queensland, Assistance to Invest in can be lifetime modifying, bringing family possession again once more into attain for 1000’s of Queenslanders, particularly renters,” talked about Julie Collins (pictured earlier talked about), minister for housing.

    Affect on homeownership

    The Albanese authorities has at the moment facilitated homeownership for over 30,000 Queenslanders because of a number of schemes, just like the Household Assurance Plan and the Regional Initial Home Buyer Guarantee.

    Assistance to Buy is aspect of a extra substantial, bold housing reform agenda by the Albanese authorities, which is supported by greater than $25 billion in new investments.

    This full tactic goals to make homeownership rather more accessible and sustainable for Australians, notably in Queensland, setting a precedent for different states to observe.

    Get the preferred and freshest residence mortgage data delivered proper into your inbox. Subscribe now to our FREE every single day publication.&#13
    &#13

    Keep up with the newest data and events

    Sign up for our mailing itemizing, it’s free!

  • New payment plan launches for finance sector

    New compensation plan launches for finance sector | Australian Broker News

    Information

    New compensation plan launches for finance sector

    Brokers confront new levy

    New compensation scheme launches for finance sector

    The Finance Brokers Affiliation of Australia (FBAA) advises finance and property finance mortgage brokers to familiarise them selves with the particulars of the federal government’s freshly applied Payment Scheme of Past Vacation resort (CSLR), which launched in early April.

    FBAA caring for director Peter White (pictured increased than) well-known that inspite of the lower-important rollout, brokers, collectors, and different fiscal sector people at the moment are matter to a brand new yearly levy to fund the plan.

    “CSLR is funded by enterprise, and it means that there’s now an avenue for a purchaser to make a assert of as much as $150,000 whether it is determined that a person within the cash providers sector, which embrace a finance dealer, has engaged in misconduct,” White acknowledged.

    Funding and implications for brokers

    CSLR is financed by a brand new once-a-year levy imposed on brokers, mortgage firms, and different economical entities. This progress introduces a significant shift in how financial misconduct guarantees are managed inside the subject.

    “Just because the scheme is called, that is solely claimable as a really final trip resort, which signifies when PI (specialist indemnity) insurance coverage plan won’t spend,” White acknowledged.

    Qualifications and institution of the CSLR

    The institution of the CSLR follows ideas from the Ramsay Review and endorsements from the Financial Solutions Royal Fee.

    The overview underlined the scheme’s more likely to “promote perception and assurance within the EDR (External Dispute Resolution) framework and the monetary knowledgeable providers sectors further broadly,” essential to its improvement as an unbiased, not-for-income agency.

    Methods for brokers

    For additional thorough info, brokers are inspired to cease by CSLR’s freshly launched web site. This system is created to help cash gurus perceive the scope, utility system, and operational points of the CSLR, guaranteeing they’re perfectly-well ready to navigate this new panorama.

    Get the most effective and freshest property finance mortgage information despatched appropriate into your inbox. Subscribe now to our FREE every day e-newsletter.

    Continue to maintain up with the most recent information and conditions

    Be part of our mailing document, it’s completely free!

  • ASTL joins industry phone calls to block FCA’s ‘identify and disgrace’ plan   – Property finance loan Approach

    The Affiliation of Short Term Loan suppliers has joined a wave of market our bodies who need to halt the Metropolis regulator from ‘naming and shaming’ firms beneath investigation and have voiced their protest to Chancellor Jeremy Hunt.   

    The Economical Perform Authority mentioned it ready to detect corporations on the start of an investigation as a result of it’s in the neighborhood curiosity to accomplish that in a session paper in February.  

    It established out the controversial proposals in its ‘Our Enforcement Information and publicising enforcement investigations – a brand new method’ doc, incorporating that it could give firms under investigation 24 hours’ see that it could make its probe common public.  

    On the opposite hand, 16 finance commerce our bodies — which incorporates British isles Finance, The Expenditure Affiliation and TheCityUK — have ready to the Chancellor asking him to block the transfer.  

    “There has been a considerable response versus the proposals from all through the economical companies enterprise,” suggests the letter dated 26 April however printed presently.  

    It offers: “Firms imagine that that the proposals may have a detrimental impact on their valuation, may place at chance the wellbeing of individuals, and have the chance to destabilise financial markets.”  

    The finance our bodies embody the switch by the watchdog “took the industry unexpectedly” because it had not been beforehand elevated by the regulator, together with that “the FCA has underestimated the extent and the likelihood of the proposals getting a detrimental impression”.  

    The letter tells the Chancellor, “we strongly urge that the FCA doesn’t progress with their proposals as outlined”.  

    The FCA has defended the consider as a further switch to accountability and transparency all through the financial suppliers sector.  

    But Affiliation of Shorter Expression Creditors chief govt Vic Jannels states: “It’s often the situation that an FCA investigation outcomes within the regulator finding little or no untoward with the agency that it is investigating.   

    “However, if that agency is called on the outset, it would unquestionably expertise reputational, and possible enterprise, destruction though the investigation is having space and presumably past even when it remaining leads to no disciplinary movement.   

    “This is a accountable proper up till examined innocent technique that may considerably negatively results investigated cash merchandise and companies suppliers and in the long run their prospects.” 

  • Fed report: Inflation, plan uncertainty top economic balance problems

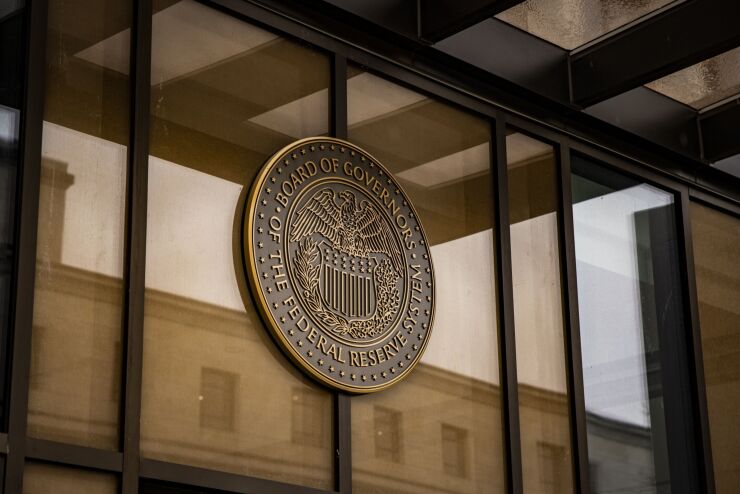
    Federal Reserve 033023 The Federal Reserve’s most up-to-date semiannual economical balance report — a survey of financial gurus — found inflation and substantial curiosity costs to be respondents’ main fear. But plan uncertainty — a absence of readability about the way in which of abroad and home coverage — was the No. 2 downside.
    Bloomberg Information

    WASHINGTON — Inflation and uncertainty bordering the course of federal coverage on commerce, investing and different points are banks’ top fiscal safety worries, the Federal Reserve Board claimed in a report launched Friday.

    For its semiannual report on cash balance, the Fed surveyed a assortment of monetary specialists — like broker-sellers, monetary dedication fund supervisors, evaluation and advisory specialists as completely as lecturers — concerning the top rated problems experiencing the economic method. Policy uncertainty emerged as a giant new useful resource of panic for enterprise specialists — it was cited by 60% of respondents, up from the simply 24% of respondents who cited it as a main downside within the Fed’s earlier survey in October 2023.

    Due to the actual fact 2019, the Fed has issued two opinions on monetary balance per yr, usually releasing an individual within the spring and one other within the drop.

    Persistent inflation and enormous want charges remained the very best challenge all through the board, with 72% of respondents itemizing it as their main downside — the same share as within the October report. The report indicated that curiosity prices may proceed being elevated over current market place expectations for an extended time period and that persistent inflation may immediate a further stringent financial coverage, leading to improved volatility in cash markets and changes in asset valuations. 

    But the rise of plan uncertainty — along with unpredictability stemming from fluctuating commerce insurance coverage insurance policies, influenced by geopolitical tensions this sort of because the battle within the Center East and Russia’s conflict in opposition to Ukraine that has lasted much more than two a number of years — was an unpredicted useful resource of market disruption for a number of survey respondents. Respondents additionally flagged the approaching U.S. elections in November as a useful resource of strain.

    “Further escalation of geopolitical tensions or plan uncertainty may reduce economic exercise, enhance inflation, and heighten volatility in economic marketplaces,” the report defined. “The worldwide fiscal process may suffer from a pullback from danger-using, declines in asset charges, and losses for uncovered U.S. and abroad enterprises and merchants.”

    Considerations concerning the credit standing top high quality {of professional} critical property — which was the No. 2 fear cited within the Oct report — was cited as a serious challenge amid 56% of the survey’s respondents. But that fell from 72% within the October report. The Fed identified that prices all through all sectors of CRE continued to lower within the 2nd half of 2023, and the report will make apparent the entire impression of CRE price drops have however to be mirrored within the data.

    “These transaction-based largely promoting value actions most likely don’t however fully replicate the deterioration in CRE business value ranges as a result of, pretty than recognizing losses, fairly a number of entrepreneurs maintain out for lots extra favorable circumstances to position their homes on the business,” noticed the report. “Capitalization charges on the time of belongings spend money on, which consider the yearly money movement {of professional} properties relative to their charges, moved modestly greater however remained at historically low ranges, suggesting that prices stay important relative to fundamentals.”

    Banking sector instability continued to characteristic prominently no matter the report noting massive quantities of liquidity and really low funding dangers within the sector because the Oct report.

    Although the Fed’s disaster lending facility, the Bank Expression Funding Application, ceased operations on March 11, the report identified the BTFP continues to reduce liquidity pressures for depositories. The report defined usually small establishments with beneath $10 billion of property — symbolizing 95% of beneficiaries — benefited from the strategy.

  • Fifo Cash launches new credit plan stream

    Fifo Funds launches new credit protection stream | Australian Broker News

    SME

    Fifo Money launches new credit plan stream

    Far higher pricing, extra shortly acceptance, suggests CEO

    Fifo Capital launches new credit policy stream

    SME monetary establishment Fifo Cash has launched a new credit rating plan stream designed to much better assist “stronger companies” all through Australia.

    The revamped protection presents a high quality supplier for specified corporations that guarantees “larger precedence, lots much less stability, much better pricing, and lots faster approval”, in accordance to Fifo Capital CEO Wayne Morris.

    “When working with Fifo, you’ll uncover there are two strategies of working with us. The aged approach and the new approach,” defined Morris (pictured beforehand talked about).

    “When you must have a versatile reply for an SME who doesn’t fairly go well with the field, the aged approach is nevertheless there to assist your clientele. But the new approach implies corporations can acquire our facilities extra shortly and might begin off working with them of their corporations faster too.”

    Fifo Cash: In with the aged, in with the new

    Acquiring supported in extra of three,000 organizations in Australia with nearly $3 billion in finance, Fifo Capital’s genuine pitch however associated with the present market.

    The technique behind its merchandise is fixing funds circulation or working funds problems for modest firm shoppers, which is a rising bother in 2024. 

    “Whether it’s de-risking late funds from consumers, accelerating funds, or most likely having to pay suppliers on improved phrases with out the necessity of disrupting relationships, we’re all about helping a shopper spend and get compensated on higher phrases,” Morris claimed.

    On the opposite hand, with any growing group, a enterprise’ services and products can speedily turn into engulfed within its particular person processes with out some finetuning. 

    Morris insisted that the “previous approach” – the corporate’s major credit historical past coverage stream – remains to be “very an excellent deal there” and sensible.

    “The earlier approach we’d work is that we appear to assist every particular person SME that’s on the market,” Morris reported. “We take into account ourselves to be not honest-climate mates – in different phrases and phrases, we’re there all through the time for the SME.”

    Morris reported the COVID-19 pandemic was a “nice instance” that showcased how the standard course of served corporations via powerful cases.

     “We supported them by means of that treacherous time even that includes them extra substantial services to allow them maintain their companies afloat.”

    Building higher interactions with brokers and clients

    Though Fifo Capital’s dedication to smaller corporations is admirable, Morris additionally acknowledged that this technique requires extra time for the corporate to plan of action a provide.

    “We can get for an extended time than our rivals to take action and there may be nonetheless a facet of uncertainty whether or not or not we’d give the approval.”

    Morris famous that there are a number of events the place by firms would however wholesome this group the place by it’s exhausting to provide them a standard facility.

    In distinction, the new method targets extra highly effective organizations, providing expedited processing, decreased safety wants, speedier approvals, and improved pricing.

     This shift goals to complement brokers’ self-assurance in doing work with Fifo and provide much better outcomes for his or her shoppers.

    “You’ll know that we didn’t improve our costs by COVID at any the place close to the exact same degree as banking firms or our rivals… I think about we had 1 smaller maximize,” Morris defined.

    Morris assured brokers of Fifo’s perseverance to retaining clear, supportive interactions.

    “Relationships to us are core of what we do. Each dealer and each client are useful to Fifo,” he reported.

    “We are looking out at presenting improved costs while decreasing our worth to those stronger organizations and you may be assured at a certain after we give it to you and our credit rating willpower as completely.”

    What do you assume about Fifo Capital’s new credit rating stream? Comment down under. 

    Associated Stories

    Preserve up with the most recent info and occasions

    Sign up for our mailing guidelines, it’s freed from cost!