Tag: phone

  • CFPB phone calls out “price gouging” in credit reporting

    Shopper Monetary Defense Bureau Director Rohit Chopra termed out the credit historical past reporting market and the pressure their the newest value hikes have placed on home affordability in an by now troublesome lending pure atmosphere. 

    Talking on the Home finance mortgage Bankers Association Secondary Markets Convention in New York Metropolis, Chopra criticized the steep boosts in fees from ranking service supplier FICO, or the Fair Isaac Company, the three credit reporting businesses and resellers.

    Contacting for a lot extra accountability, he invited feedback from lenders because the bureau seems to be like for strategies to handle the “value gouging” in the present market. 

    “We are eager to hearken to from mortgage firms and can search at possible rulemaking and recommendation to strengthen rivals, possibility and affordability,” he claimed.

    The reporting firms, Equifax, Experian and Transunion, usually set wholesale promoting costs resellers fork out, which is then handed on to their mortgage firms and folks. With research wanted on the market to the federal government-sponsored enterprises, property finance mortgage companies normally have little or no choice however to pay.

    “With a captive purchaser base, sellers have carried out yearly value will enhance that a lot outpace inflation,” Chopra reported. “And in buy to get the credit historical past and credit ranking critiques, dwelling finance mortgage collectors typically should pay again two instances, as quickly as to confirm eligibility, and after simply previous to the mortgage closes.”

    All by the MBA session that was sponsored by FICO, Chopra generally known as out the substantial remodel in pricing composition for credit historical past scoring on the cease of ultimate calendar yr, resembling a flat price considerably than quantity-primarily primarily based mannequin. Among the changes was a hike to comfortable-credit historical past pulls that put them on the similar stage as powerful pulls, even with distinctions in the details supplied. 

    Expenses multiply when many candidates are on the house finance mortgage and buyers additionally want critiques, that means mortgage suppliers usually fork out for the precise data 6 or 12 instances, Chopra reported. 

    Compounding costs, credit rating reporting firms have found a option to acquire from inaccuracies dwelling finance mortgage collectors come throughout in a report, because of a swift rescoring system, which Chopra known as a “pay-to-perform” firm. 

    “A report complete of awful info is a special possibility for these organizations to leverage their scenario as an indispensable present market utilities and extract nonetheless extra money from customers and mortgage firms who don’t have any different options,” he said. 

    Pursuing the announcement from FICO late final yr, mortgage suppliers sharply criticized its strikes, declaring, in the long term, that they conclusion up at the moment being handed right down to the consumer. 

    As companies normally don’t value debtors upfront for credit historical past report charges, “Loan suppliers usually must attempt to eat the expenditures of the primary applicant screening for candidates who do not qualify or decide to not pursue a monetary mortgage,” he mentioned. 

    “In some feeling, debtors that close to normally will not be simply shelling out for the credit ranking tales and scores for themselves, they’re additionally paying out for inflated prices on the candidates who is not going to shut,” he reported.

    Chopra additionally advisable cash markets to develop solutions for buyers to evaluate property finance mortgage swimming swimming pools and rely much less on mandated credit historical past scores.

    In a dialogue with MBA CEO Bob Broeksmit, Chopra additionally pushed again on dwelling finance loan-marketplace criticism of his stance in direction of so-identified as “junk bills” all through the banking business. In each his opening remarks earlier than in the day and dialogue with Chopra, Broeksmit took problem with the “junk price” label and regardless of if specified service charges qualify as these sorts of if they’re spelled out in progress. 

    Chopra responded that “a junk fee simply is not simply what’s hidden.” In the CFPB’s view, it additionally handles what isn’t material to competitors, or if it applies to suppliers nobody wants. 

    “I’m joyful that you just disclose a few of these ripoffs, however they shouldn’t be a ripoff,” Chopra defined.  

  • When your credit is pulled and all of a sudden you get phone calls?

    A lender takes your mortgage software and then the following day you get phone calls from different lenders, how does that occur? Watch and Learn.

    It occurs. You are trying on-line. You see a nice, unbelievable price and you full a kind. You assume a lender is going too attain out to you. Instead, you are bombarded with calls!

    So, Why are you getting calls from different mortgage firms when your credit is pulled?’

    The easy reply, the corporate is promoting off your data. When you fill out a kind you may be unknowingly consenting to the sale of your data. It is necessary to learn the effective print when finishing any kind and how they use your data.

    When you

    begin your mortgage app

    with DDA mortgage, our Loan Originators are the one individuals who obtain and evaluate your data. Big firms like Zillow, Realtor.com, and even Rocket Mortgage, can ship your data to 100s of brokers who pay them for your data. 

    Leads may be purchased from different mortgage firms, tune and be taught.

    If you are searching for a native Florida mortgage dealer, with over 250 5-star verified Google Revies, give us a name 

    (727) 784-5555

    .

    Looking for extra particulars? Listen to our prolonged podcast! Or

    begin your mortgage

    with us now.


  • ASTL joins business phone calls to quit FCA strategy to ‘title and disgrace’ companies   – Mortgage loan Finance Gazette

    The Association of Quick Term Creditors has joined a wave of discipline our bodies who need to forestall the City regulator from ‘naming and shaming’ companies beneath investigation and have voiced their protest to Chancellor Jeremy Hunt.   

    fca2-508x330.jpg

    The Financial Carry out Authority reported it deliberate to decide companies on the get began of an investigation primarily as a result of it’s within the public curiosity to achieve this in a session paper in February.  

    It set out the controversial proposals in its ‘Our Enforcement Guidebook and publicising enforcement investigations – a brand new strategy’ doc, introducing that it might give companies beneath investigation 24 hours’ uncover that it might make its probe group.  

    However, 16 finance commerce our bodies — which embrace British isles Finance, The Financial funding Association and TheCityUK — have ready to the Chancellor asking him to block the transfer.  

    “There has been a considerable response towards the proposals from throughout the monetary merchandise and providers sector,” says the letter dated 26 April however revealed these days.  

    It provides: “Firms assume that the proposals can have a unfavorable affect on their valuation, might put at hazard the wellbeing of individuals at present, and have the potential to destabilise financial markets.”  

    The finance our bodies incorporate the shift by the watchdog “took the business unexpectedly” because it skilled not been earlier elevated by the regulator, introducing that “the FCA has underestimated the extent and the chance of the proposals proudly owning a harmful affect”.  

    The letter tells the Chancellor, “we strongly urge that the FCA doesn’t start with their proposals as outlined”.  

    The FCA has defended the measure as an additional transfer to accountability and transparency all through the financial providers sector.  

    But Association of Limited Phrase Loan corporations chief govt Vic Jannels suggests: “It’s normally the case that an FCA investigation advantages within the regulator getting little or no untoward with the agency that it is investigating.   

    “However, if that agency is known as on the outset, it’s going to actually undergo reputational, and possible business, damage though the investigation is taking put and probably past even when it success in no disciplinary movement.   

    “This is a responsible till lastly confirmed harmless tactic that might drastically negatively have an effect on investigated monetary providers distributors and in the long term their clients.” 

  • ASTL joins industry phone calls to block FCA’s ‘identify and disgrace’ plan   – Property finance loan Approach

    The Affiliation of Short Term Loan suppliers has joined a wave of market our bodies who need to halt the Metropolis regulator from ‘naming and shaming’ firms beneath investigation and have voiced their protest to Chancellor Jeremy Hunt.   

    The Economical Perform Authority mentioned it ready to detect corporations on the start of an investigation as a result of it’s in the neighborhood curiosity to accomplish that in a session paper in February.  

    It established out the controversial proposals in its ‘Our Enforcement Information and publicising enforcement investigations – a brand new method’ doc, incorporating that it could give firms under investigation 24 hours’ see that it could make its probe common public.  

    On the opposite hand, 16 finance commerce our bodies — which incorporates British isles Finance, The Expenditure Affiliation and TheCityUK — have ready to the Chancellor asking him to block the transfer.  

    “There has been a considerable response versus the proposals from all through the economical companies enterprise,” suggests the letter dated 26 April however printed presently.  

    It offers: “Firms imagine that that the proposals may have a detrimental impact on their valuation, may place at chance the wellbeing of individuals, and have the chance to destabilise financial markets.”  

    The finance our bodies embody the switch by the watchdog “took the industry unexpectedly” because it had not been beforehand elevated by the regulator, together with that “the FCA has underestimated the extent and the likelihood of the proposals getting a detrimental impression”.  

    The letter tells the Chancellor, “we strongly urge that the FCA doesn’t progress with their proposals as outlined”.  

    The FCA has defended the consider as a further switch to accountability and transparency all through the financial suppliers sector.  

    But Affiliation of Shorter Expression Creditors chief govt Vic Jannels states: “It’s often the situation that an FCA investigation outcomes within the regulator finding little or no untoward with the agency that it is investigating.   

    “However, if that agency is called on the outset, it would unquestionably expertise reputational, and possible enterprise, destruction though the investigation is having space and presumably past even when it remaining leads to no disciplinary movement.   

    “This is a accountable proper up till examined innocent technique that may considerably negatively results investigated cash merchandise and companies suppliers and in the long run their prospects.” 

  • BSA phone calls for radical Govt motion to halt FTB drop – Home finance loan Tactic

    The Creating Societies Affiliation has known as for radical housing reform to halt the decline in home possession because the choice of exceptional proprietor-occupier dwelling loans is down by two million from its 2002 peak.

    Initial-time potential patrons are considerably reliant on the Bank of Mum and Dad and on combining two incomes so as to get on to the ladder, a report by housing analyst Neal Hudson for the BSA, statements.

    This usually leaves singles and people folks with out financial help from household caught within the rented sector.

    Increased dwelling finance loan costs have solely worsened the situation in recent times, creating a good greater affordability gap for purchasers, the report finds.

    The BSA says that mutuals have the chance to increase lending to to begin with-time potential patrons however are hindered by regulation.

    The commerce system is contacting on governing administration to fee a radical and unbiased evaluation of housing coverage with a view to constructing property possession extra economical.

    BSA head of property finance loan and housing protection Paul Broadhead claims: “Becoming a first-time purchaser is presumably probably the most highly-priced it has been about on the very least the final 70 a few years, however a correctly working housing market place depends on very first-time purchasers remaining succesful to handle their very first home.”

    The Middleman Home loan Lenders’ Affiliation has backed the BSA’s get in contact with.

    Govt director Kate Davies states “The British isles is an extremely developed monetary system which is dwelling to an individual of probably the most assorted, aggressive and progressive property finance loan industries within the earth.

    “And nonetheless we’re within the midst of a housing disaster, with a lot much less affording to spend money on a property, and extra renters battling to safe lodging.

    “There is a viable argument for Federal government-backed first-time purchaser help, which have to be accompanied by a sustainable method to provide much more fine quality, fairly priced housing on a primary scale, in each the personal and social sectors.”

    She elements out that the Government actually ought to acknowledge that landlords interact in a important place in giving housing and have to be supported and never penalised.

    Nationwide director of dwelling loans and financial wellbeing Rachael Sinclair supplies: “Getting on to the residence ladder stays as difficult as ever, with our newest exploration displaying that an individual in 5 potential householders don’t really feel they’ll be succesful to purchase until their forties.  

    “Collaboration is essential if we’re to handle the 1st-time purchaser conundrum and is why we’re happy to have labored with the Developing Societies Association on this report, which calls for an unbiased evaluation of the FTB market.  

    “Without a collaborative answer, we risk the wheels spinning on the homeownership disaster indefinitely.” 

    The BSA’s report was developed in collaboration with Nationwide, Coventry Building Modern society, Leeds Constructing Modern society, Skipton Creating Society and Yorkshire Creating Culture. 

  • Web zero secretary phone calls on CMA to launch heat pump inquiry  – Home finance loan Approach

    Net Zero secretary Claire Coutinho has known as on the opponents regulator to have out an inquiry into the family heat pump market place to see irrespective of if individuals are “getting a truthful deal”. 

    “The Levels of competitors and Marketplaces Authority strongly ponder finishing up a evaluation of this business to consider how competitiveness is doing the job within the dwelling heating tools present market and to understand regardless of whether or not any weak level in ranges of competitors is contributing to charges remaining larger than they’d be in a nicely-working present market, or pitfalls enterprise in order the sector transitions to small-carbon heating,” states Secretary of Point out for Vitality Protection & Net Zero Coutinho. 

    The minister wrote to the CMA most important govt Sarah Cardell in a 14 March letter that was made normal public yesterday. 

    Property emissions are a vital portion of the federal government’s focus on to decrease greenhouse gasoline emissions by 80% by 2050 in distinction to 1990 ranges. 

    The UK’s housing stock accounts for throughout 14% of the nation’s emissions, the nation’s next-largest provide of greenhouse gases proper after space transportation, which accounted for 23% of emissions in 2021, in accordance to a Weather Improve Committee examine. 

    Coutinho writes to the CMA: “During this transition, it’s rather more necessary than ever that people could be assured that vigorous degree of competitors amongst companies within the heating sector will ensure that they’re having a good supply, with aggressive pressures attempting to preserve the fees of heating home equipment as small as attainable.” 

    The CMA’s Cardell in her letter responding to Coutinho writes that the regulator “will evaluate your request totally and ponder potential carry out on this area alongside possible function in different precedence markets for possible initiation at some point of the following half of the 12 months”. 

    The CMA’s letter to the authorities is dated 25 March, however was additionally publicly produced yesterday. 

    Even so, the regulator elements out it posted a report earlier Could recognized as, ‘Consumer security within the inexperienced heating and insulation sector’. 

    It highlighted three fears the regulator harbours concerning the sector. 

    The system talked about that it may be laborious for purchasers to “establish sincere companies”, it was concerned about firms constructing “deceptive claims” as very effectively as restricted worth transparency throughout the market, and no matter whether or not specs our bodies current satisfactory purchaser protection. 

    Having mentioned that, a quarterly report on heat pump upgrades by Ofgem in February noticed that the federal government’s Boiler Up grade Plan, established up two yrs in the past, has issued simply £133m in grants from its £300m spending plan to persuade house owners to ditch gasoline boilers for minimal-carbon residence heating.   

    This arrives simply after Primary Minister Rishi Sunak earlier September scrapped choices to require all landlords to improve their properties to a minimal quantity electrical energy efficiency certification ranking of C by 2028, citing the have to have to defend tenants from unfair promoting worth hikes in lease owing to the price of renovations.   

    This leaves landlords free to lease their qualities with {an electrical} energy effectiveness certification rating of E.    

    Also, ultimate September the governing administration introduced it might carry grants for heat pumps to £7,500 from £5,000 for each household.   

    Setting up a heat pump generally expenses amongst £10,000 and £15,000, while changing a gasoline boiler ranges amongst £2,000 to £4,000.

  • Frollo phone calls for use situation-based method for greater open banking info

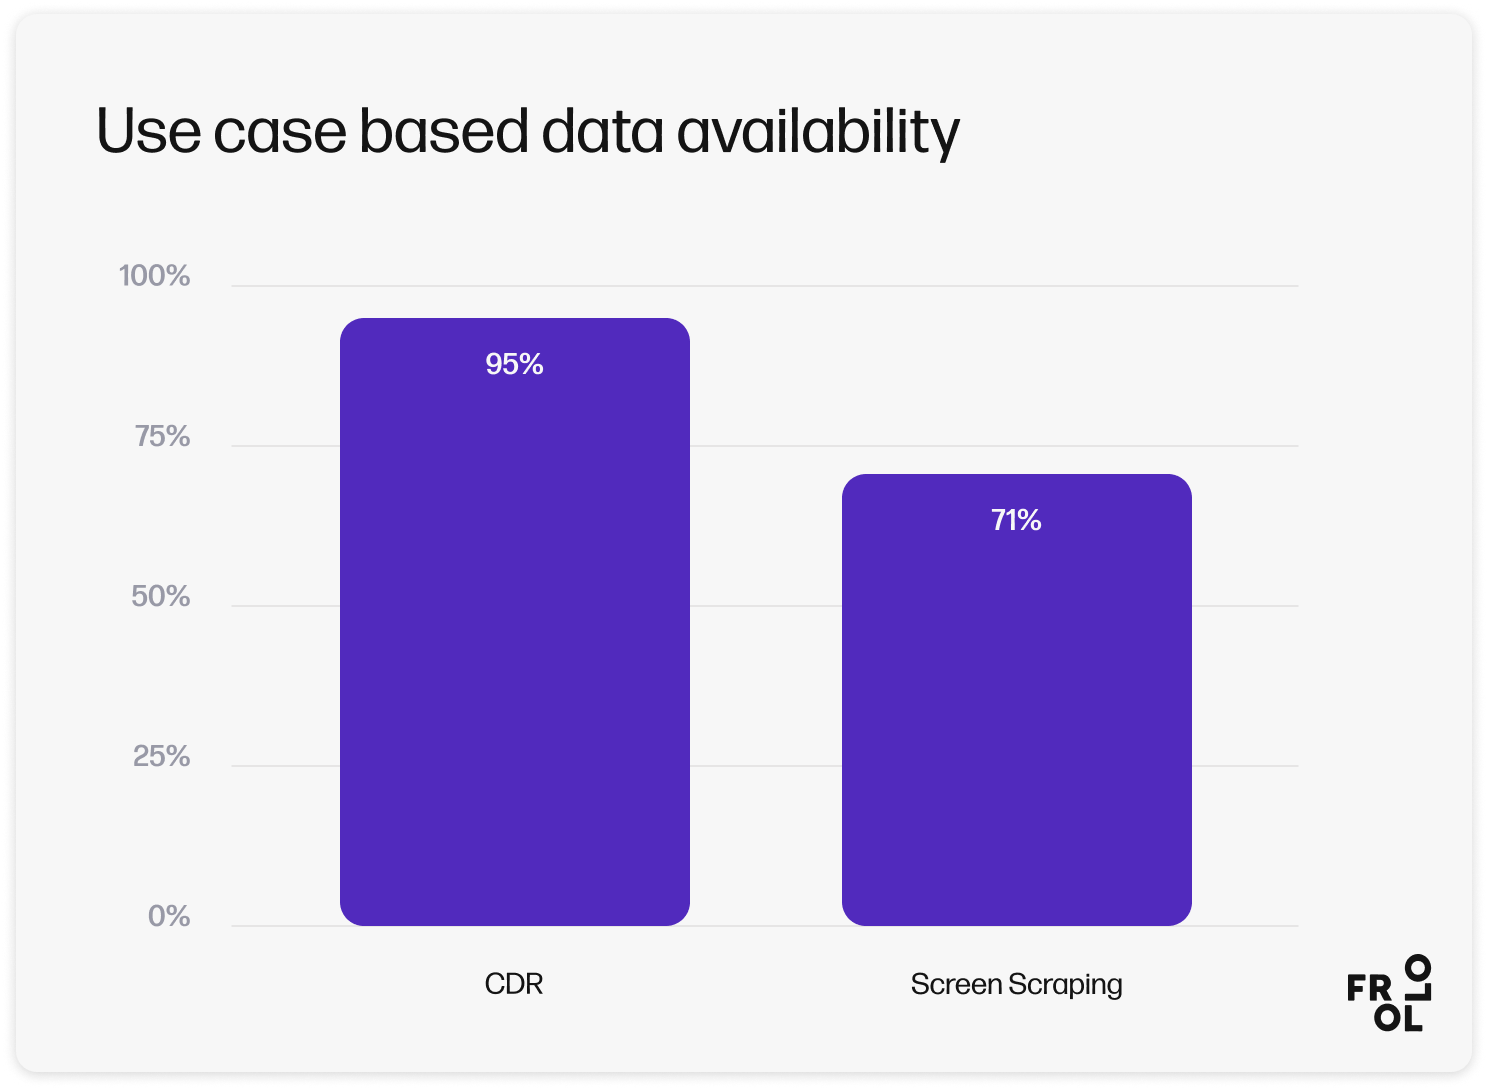
    “Reliable and complete transaction info is the idea of useful income administration, enabling actual categorisation, intelligent insights, and personalised ideas,” Thrassis reported. “These conclusions underscore the significance of a use situation dependent method to enhancing open banking.”

    What’s extra, Frollo’s examination when put next open banking information with that attained by means of display scraping, noting a 35% uplift in information safety by way of open up banking. However, inspite of the supply, info from show display scraping often suffers from inconsistencies and unreliability.

    Frollo is urging the Australian Level of competitors and Client Fee (ACCC), the Data Criteria Overall physique, and area stakeholders to unite round necessary use instances.

    “Rather than remaining typical throughout all information with restricted sensible software program, we should always detect probably the most impactful use situations and performance collaboratively to deal with the actual info gaps and high-quality difficulties that hinder their realisation,” Thrassis stated.