Tag: more

  • Land Registry aims for more accurate timescales – Mortgage Finance Gazette

    The Land Registry has up to date its portal to provide more accurate estimated timescales for customers looking for to register a property title.

    Land-Registry-620x330.jpg

    It says it’s now calculating the estimated completion dates in another way with a view to give more readability to customers, following suggestions.

    The Land Registry says: “The date displayed will probably be more particular to the applying sort that was submitted.”

    In additional updates to the portal, it is going to be simpler for customers to filter functions to indicate instances the place more info has been requested earlier than they’ll proceed.

    It must also be simpler to identify functions which might be susceptible to being cancelled as a result of requested info has not been equipped but. 

    The portal will now permit customers to submit bigger information when requested to add paperwork.

  • More lenders cut rates including Barclays, Perenna and others – Mortgage Strategy

    A bunch of lenders have introduced charge cuts right this moment including Barclays, Perenna, Hodge, Buy to Let by Foundation and Spring Finance.

    Barclays is reducing rates throughout a number of residential merchandise on Friday, by as a lot as 33 foundation factors.

    The cuts embody a five-year repair for buy at 75% LTV which is down from 4.57% to 4.24% with no charge.

    Barclays can be reducing the speed on a two-year mounted for remortgage at 60% LTV which is down from 5.01% to 4.7% with a £999 charge, amongst many different reductions.

    Perenna has cut rates on its residential buy and retirement curiosity solely offers by as much as 59 foundation factors.

    Its 40-year mounted charge product at 95% LTV has been diminished by 34 foundation factors to six.61% with a £1,999 charge and an early compensation cost in place for the primary 5 years solely.

    The lender’s RIO remortgage offers now begin at 5.88% for a 60% LTV mortgage with a £1,999 charge.

    Meanwhile, Hodge is decreasing rates throughout a number of its 50+ and RIO mortgages.

    Among the largest worth cuts is to its five-year mounted RIO Mortgage at 75% LTV, which is down from 6.25% to five.99% with a £995 charge.  

    Buy to Let by Foundation has cut rates by 15 foundation factors on its F1 vary for debtors with an almost-clean credit score historical past and its F2 vary for purchasers with blips on their credit score file or these shopping for non-standard properties.

    Rates on these offers now begin from 6.49% with a 1.5% charge.

    The lender has additionally cut rates by as much as 10 bps on its pound-for-pound F1 and F2 remortgage merchandise, which now begin from 6.64% with a 1.5% charge.

    Bridging lender Spring Finance has diminished rates on its residential, semi-commercial and industrial bridging loans. 

    First cost residential bridging finance is now obtainable from 0.89% monthly and second cost residential lending, industrial and semi-commercial from 1.04%.

  • More lenders cut rates including Barclays, Perenna and others – Mortgage Finance Gazette

    A bunch of lenders have introduced fee cuts right this moment including Barclays, Perenna, Hodge, Buy to Let by Foundation and Spring Finance.

    Barclays-branch-620x330.jpg

    Barclays is reducing rates throughout a number of residential merchandise on Friday, by as a lot as 33 foundation factors.

    The cuts embody a five-year repair for buy at 75% LTV which is down from 4.57% to 4.24% with no price.

    Barclays can be reducing the speed on a two-year fastened for remortgage at 60% LTV which is down from 5.01% to 4.7% with a £999 price, amongst many different reductions.

    Perenna has cut rates on its residential buy and retirement curiosity solely offers by as much as 59 foundation factors.

    Its 40-year fastened fee product at 95% LTV has been lowered by 34 foundation factors to six.61% with a £1,999 price and an early compensation cost in place for the primary 5 years solely.

    The lender’s RIO remortgage offers now begin at 5.88% for a 60% LTV mortgage with a £1,999 price.

    Meanwhile, Hodge is decreasing rates throughout a choice of its 50+ and RIO mortgages.

    Among the most important worth cuts is to its five-year fastened RIO Mortgage at 75% LTV, which is down from 6.25% to five.99% with a £995 price.  

    Buy to Let by Foundation has cut rates by 15 foundation factors on its F1 vary for debtors with an almost-clean credit score historical past and its F2 vary for shoppers with blips on their credit score file or these shopping for non-standard properties.

    Rates on these offers now begin from 6.49% with a 1.5% price.

    The lender has additionally cut rates by as much as 10 bps on its pound-for-pound F1 and F2 remortgage merchandise, which now begin from 6.64% with a 1.5% price.

    Bridging lender Spring Finance has lowered rates on its residential, semi-commercial and industrial bridging loans. 

    First cost residential bridging finance is now obtainable from 0.89% per thirty days and second cost residential lending, industrial and semi-commercial from 1.04%.

  • More than 25% of retired investors are paying down mortgage, credit card debt

    Experts share suggestions for starting to age in place

    By Didier Malagies
    •
    08 Jul, 2024

    As these in or close to retirement proceed to proclaim a choice for getting old in place , there could also be challenges for individuals who aren’t positive about how or when they need to get began on planning. A collection of dwelling healthcare, renovation and senior care specialists supply tips about methods to start in a column printed by U.S. News & World Report . For reverse mortgage purchasers wanting to make use of their mortgage proceeds to fund the aim of getting old in place, dwelling renovations and different preparations could also be requested from the reverse mortgage mortgage officer as a result of high-touch nature of reverse mortgage origination. LOs usually occupy a spot of belief amongst their borrower purchasers. For facilitating the aim of getting old in place, planning forward is vital. One skilled defined that it ought to begin as quickly as potential. “Making small modifications now will help you keep away from scrambling to make massive modifications in a while when you’ve restricted capability,” based on James Bowdler, a house healthcare skilled. Connecting with a specialised geriatric care supervisor can even permit a fuller evaluation of potential hazards for getting old in place that may be rectified with a retrofit or renovation of some variety, added Texas -based senior care skilled Stacey Eisenberg to the outlet. What was regular for a house with youngsters or youthful adults may show to be hazards in later life, notably as larger mobility challenges come from extra superior age. Widening doorways, eradicating litter (together with rugs, which may trigger tripping) and enhancing the lighting in a house could be difference-makers based on architect Diana Melichar. “Seniors sometimes have much less mobility and bodily agility, and their senses could be diminished,” she mentioned within the column. Another potential hazard is the presence of stairs, notably if a most important bed room or different residing house is situated on a second flooring, she added. “Adding a major bed room suite to the primary flooring of your property is good,” she mentioned. “If that’s not potential, then including a chairlift or elevator is a second selection.” Other components that would support the aim of getting old in place embrace changing door knobs with lever handles, which are simpler to function for individuals who have or might develop arthritis. Bathrooms are a standard goal for renovations since it may be straightforward to slide and injure your self if in case you have restricted mobility; nonstick mats and extra rails and handles will help mitigate some of this threat.  Smart dwelling expertise can be an more and more widespread device for outfitting a house for getting old in place. In addition to digital assistants and audio system that are voice-operated , movement sensors that may mechanically activate lights and internet-enabled home equipment that may permit a consumer to watch activation states can help aging-in-place targets, sure specialists say.

  • Gender inequality: More than just pay

    Gender inequality: More than just pay | Australian Broker News

    News

    Gender inequality: More than just pay

    Finance entry neglected in gender inequality

    Gender inequality: More than just pay

    Westpac’s Rachael McKenzie (pictured above), government supervisor of life operations and CX, emphasises that gender inequality extends past pay disparities.

    “Access to finance is a matter that usually will get neglected within the dialog about gender inequality,” McKenzie stated.

    The persistent pay hole

    The international gender pay hole stays vital, with the World Economic Forum reporting it was 68.4% closed in 2023. At the present tempo, full pay parity will not be achieved for 131 years.

    “Public debate tends to deal with the gender pay hole – and with good purpose,” McKenzie stated.

    Financial obstacles for girls entrepreneurs

    At the latest Financial Alliance for Women Summit in London, the highlight was on ladies’s entry to capital.

    “Over 400 million ladies entrepreneurs all over the world have huge potential to develop their companies … however they lack the financing to realize their targets,” McKenzie stated.

    The potential financial influence

    Female entrepreneurs characterize a $1.7 trillion development alternative for monetary service suppliers and will add $5-6tn to the worldwide economic system. However, feminine founders at the moment obtain much less than 2% of enterprise capital globally.

    Collaborative efforts and options

    The FAW Summit noticed participation from extra than 250 folks representing 149 establishments throughout 58 international locations, discussing help mechanisms for girls entrepreneurs. Non-financial providers reminiscent of schooling, mentoring, and recognition applications had been additionally highlighted as essential for development.

    Westpac’s initiatives

    Westpac, a founding member of the Financial Alliance for Women, is actively working to shut the finance hole.

    In 2023, Westpac Business Lending introduced new measures, together with devoted loans for small companies and a $500 million dedication to help ladies in enterprise.

    Westpac’s collaboration with the University of New South Wales Founders’ 10X Accelerator Program affords three $20,000 scholarships for girls balancing work and private commitments.

    Additionally, their partnership with Fishburners, a group hub for early-stage startups, consists of the Ascent Project geared toward growing feminine founder illustration.

    “There’s nonetheless a protracted approach to go, however applications reminiscent of these are serving to many ladies realise their potential within the enterprise world,” McKenzie stated, highlighting the continued efforts to handle gender inequality in entry to finance.

    Get the most well liked and freshest mortgage information delivered proper into your inbox. Subscribe now to our FREE every day e-newsletter.

    Related Stories

    LATEST NEWS

    Perth market surges

    Keep up with the most recent information and occasions

    Join our mailing record, it’s free!

  • California sets $20B of state bond steps Bay Area adds $20B a lot more

    California’s presidential election poll in November will embody $20 billion bucks of statewide bond measures, with $20 billion extra in only one regional bond election.

    At the purpose out diploma, lawmakers reached agreements earlier week on two $10 billion customary obligation bond actions that had been heading towards acceptance in flooring votes this 7 days.

    The actions have been being set forward as Senate Bill 867, a $10 billion statewide Ok-14 school constructing bond measure, and Assembly Invoice 247, a $10 billion climate bond measure.
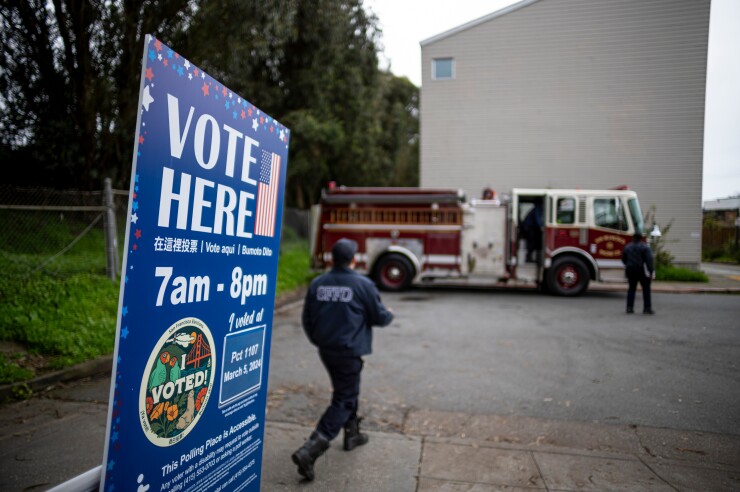
    Signage outside a polling station in San Francisco A indicator outdoors a polling station in San Francisco in March. Voters there’ll take into consideration a $20 billion regional housing bond in November, in addition to $20 billion of situation GO bonds.

    Bloomberg News

    All these steps will compete for consideration on the poll in what some predict might be a doc 12 months for varsity district bond measures, in an election by now juiced with a $20 billion regional housing bond measure within the San Francisco Bay Spot.

    The statewide actions have been place forward as Senate Bill 867, a $10 billion statewide Ok-14 school development bond measure, and Assembly Monthly invoice 247, a $10 billion climate bond consider.

    Supporters say the college bond would strengthen the lives of tens of thousands and thousands of children and modernize normal public colleges, regardless that the climate bond would fund clear up h2o, wildfire avoidance and restoration initiatives.

    “These bond actions are very important to the long run of this level out, and commit in our youngsters, their neighborhood universities, they usually make certain communities large and modest have accessibility to wash ingesting h2o and are wildfire protected,” stated Sen. President Pro Tempore Mike McGuire, D-Healdsburg.

    The Senate chief included that he ran for the college board on the age of 19 after observing his excessive school tumble into disrepair.

    “Our learners, lecturers and crew ought to have superior, particularly folks in underserved universities precisely the place sources are restricted and services are outdated, and at conditions, hazardous,” McGuire stated.

    Proposition 51, the ultimate statewide bond consider to help school design, was permitted by voters in November 2016 and has extended been depleted.

    If the statewide college bond measure passes, space districts will need matching money to protected state money.

    “I really feel we’re going to see a doc selection of GO school bond actions on the poll in 2024,” claimed Adam Bauer, president and principal authorities officer of municipal advisory company Fieldman, Rolapp & Associates.

    In 2020 and 2022, the choice of college bond measures on the poll was light, and the require for school development funding has remained, Bauer claimed.

    “In 2024, school districts have been ramping as much as make up for the absence of bond measures floated in extra of the earlier cycles,” he stated.

    He verified that college districts are working into circumstances precisely the place they won’t have sufficient money for initiatives as a result of truth they have not handed a bond in a while.

    “That is especially perfect, and they’re hopeful the state would set a measure on the poll to assist with matching money,” he talked about.

    Of the statewide climate bond consider, McGuire defined the communities he represents have been devastated by wildfires. Making certain that the state’s communities have the sources to defend themselves from wildfires, drought and floods is “vital to the prolonged-phrase success of the purpose out,” he talked about.

    “Our historically underserved communities on the doorway strains of the native local weather disaster couldn’t have enough money to attend any lengthier, requiring us to switch with urgency to strengthen California native climate resiliency,” reported Assemblymember Eduardo Garcia, D-Coachella, who co-lead the Assembly native local weather bond doing work group with Assemblymember Lori Wilson, D-Suisun Town.

    SB 867 would commit a naked minimal of 40% of the bond funds towards disadvantaged communities.

    The cash can be divided seven means: $3.8 billion for protected ingesting ingesting water, drought and flood protection $1.5 billion for wildfire and forest resilience $1.2 billion to cope with sea stage rise $1.2 billion to guard biodiversity $1.55 billion for park growth and out of doors recreation areas $450 million for excessive warmth mitigation and $300 million for climate-friendly and resilient ranches and farms.

    The climate bond would make investments in “our potential by prioritizing important calls for these varieties of as protected and fairly priced ingesting water entry, wildfire prevention, extreme heat mitigation, sustainable agriculture, and totally clear, renewable energy,” Wilson stated.
    Adam Bauer, president and chief executive officer of financial advisory firm Fieldman, Rolapp & Associates “I think about we’re heading to see a historical past quantity of GO school bond measures on the poll in 2024,” stated Adam Bauer, president and principal govt officer of Fieldman, Rolapp & Associates.

    Fieldman, Rolapp & Associates

    The $20 billion regional primary obligation bond measure within the San Francisco Bay Location would help assemble or preserve 90,000 reasonably priced households all through the 9-county location, supporters say.

    The Bay Location Housing Financing Authority Board, a regional board comprised of neighborhood elected officers, unanimously agreed at their June 26 convention to place the Bay Area’s first regional housing bond on the standard election poll.

    Only 17% of the state’s homebuyers can have enough money the state’s $814,280 median-priced single partner and youngsters home, with 24% able to afford to pay for a $655,000 median-priced condominium or townhome, in accordance to a California Affiliation of Realtors housing affordability report revealed Might 9.

    To afford to pay for a solitary-family members home, in accordance to the CAR’s calculation, potential consumers need to need to make $208,400 yearly to make month-to-month funds of $5,120, like principal, curiosity and taxes on a 30-year preset-level mortgage with a 6.86% curiosity quantity.

    San Mateo and Santa Clara — two counties within the BAHFA location — are the initially and subsequent most expensive components to acquire a residence, in accordance to Automobile.

    If authorized, $10.4 billion would go to assemble 36,000 very reasonably priced properties, $3 billion would go to guard 14,000 present moderately priced residences and $6.6 billion can be utilized as versatile funding to take care of and current homebuyer assist for 22,000 properties, in line with a report.

    Below current laws, the BAHFA measure must have approval by a minimum of two-thirds of voters to go. The bonds can be repaid with the advert valorem residence tax levy within the nine-county location.

    But the state’s voters may even be pondering of Assembly Constitutional Amendment 1, which might established the voter threshold at 55% for voter approval of bond actions for cost-effective housing and infrastructure. In accordance to BAHFA, if ACA1 passes, the authority’s bond consider would solely need a 55% vote threshold.

    “Today’s vote is the fruits of so quite a few a very long time of effort by so many of us all throughout our space,” BAHFA chair Alfredo Pedroza, a Napa County supervisor, acknowledged in a June 26 assertion. “The Bay Area’s longstanding housing affordability challenges affect all of us, our mates, our neighbors and our members of the family associates.”

    The bond consider would break up 80% of the money between the 9 counties (and the cities of San Jose, Oakland, Santa Rosa and Napa, each single of which carries a lot more than 30% of their county’s reduced-profits housing will want), in proportion to every county’s tax contribution to the bond. The remaining 20%, or $4 billion, can be made use of by BAHFA to construct a new regional system to fund economical housing growth and preservation assignments throughout the space.

    The measure additionally would develop a citizen’s oversight committee and bond proceeds account. The committee would report back to BAHFA and the Association of Bay Location Governments authorities boards. There would even be an once-a-year neutral audit.

    It stays to be witnessed if voters could have the precise enthusiasm to approve bond steps because the authors have for the techniques they might assist.

    Sonoma Point out University political science professor David McCuan identified that Gov. Gavin Newsom and lawmakers beforehand designed efforts to lighten the stress placed on voter’s discover by dealing with some initiatives legislatively, considerably than positioning them simply earlier than voters.

    “There might have been 22 to 24 statewide initiatives on the poll quite there might be 9 to 11,” McCuan claimed.

    “There is a lot weighing on voter’s pocketbooks by now, together with it staying a contentious election yr,” he stated.

    Take into consideration all the attention changing into equipped to the battle amongst earlier President Donald Trump and President Joe Biden, he defined.

    “Bond steps have accomplished pretty properly on the neighborhood quantity prior to now 10 or 15 a number of years, however California has been approaching the bond indebtedness ceiling,” he talked about. “When that affliction takes place, it’s actually simpler to get a ‘no’ than a ‘sure’ vote.”

    Regional poll actions, along with however not confined to tax and college bonds have notched a 70% approval quantity, and statewide actions have skilled a from 33% to 38% approval payment within the earlier 10 a few years, he reported.

    McCuan anticipates that fiscal measures, bond steps and steps to rework voter thresholds won’t fare in addition to they’ve within the earlier. If they have been being grabbing 70% of the vote beforehand, he’s predicting the standard acceptance value to fall as very low as 50%.

  • Concerns elevated more than Stockland, Supalai acquisition

    Fears raised over Stockland, Supalai acquisition | Australian Broker Information

    News

    Fears lifted in extra of Stockland, Supalai acquisition

    ACCC flags competitiveness issues

    Concerns raised over Stockland, Supalai acquisition

    The Australian Competitiveness and Shopper Fee (ACCC) has posted a Statement of Challenges outlining preliminary ranges of competitors fears pertaining to Stockland and Supalai’s proposed acquisition of 12 Lendlease residential masterplanned neighborhood initiatives through a joint enterprise.

    Lendlease, Stockland, and Supalai are builders of masterplanned neighborhood initiatives, and the acquisition consists of Lendlease promoting 12 out of its 16 initiatives in NSW, Queensland, Victoria, and Western Australia.

    “We are involved that the proposed acquisition would eliminate an individual of Stockland’s closest and main competitors within the provide of family masterplanned group housing heaps in 4 areas – the Illawarra, North West Perth, Ipswich, and Moreton Bay,” ACCC Commissioner Liza Carver (pictured earlier talked about) mentioned.

    Opportunity results on costs and prime quality

    ACCC’s preliminary points recommend that the acquisition might effectively maximize Stockland’s incentive to boost charges, maintain off present, or lower the wonderful of housing masses within the impacted areas, maybe harming potential house homeowners.

    Market feedback indicated that Stockland and Lendlease are close to competitors with sturdy reputations and the flexibility to dedicate in high-excellent facilities, which embrace coaching, parks, and metropolis centres.

    “We are involved that different builders of masterplanned group tasks might maybe not be succesful to compete adequately with Stockland proper after the acquisition in some areas,” Carver reported.

    Certain points in Illawarra

    “These preliminary fears are strongest within the Illawarra space of New South Wales the place the proposed acquisition would carry collectively the 2 premier masterplanned area people duties in an already remarkably concentrated business,” Carver added.

    The ACCC invites submissions in response to the Assertion of Problems by July 18.

    Get one of the best and freshest mortgage information despatched applicable into your inbox. Subscribe now to our FREE every day publication.

    Related Stories

    Maintain up with the latest information and conditions

    Be part of our mailing listing, it’s completely free!

  • Vida-operator Belmont Eco-friendly lending falls a lot more than threefold to £190m   – Mortgage loan System

    Vida-owner Belmont Eco-friendly claimed that gross lending fell far more than threefold to £190m final 12 months, in accordance to its yearly report.  

    New residential monetary loans tumbled from £683m in 2022.  

    The small enterprise operated with “a obvious think about creating new house loan group with sustainable returns pretty than chasing amount in what was a fairly aggressive market, gross new lending in 2023 was consciously restricted,” suggests Belmont Environmentally pleasant chief authorities Anth Mooney within the report.  

    Its report supplies: “The increase in Financial establishment of England base charge throughout 2022 and early 2023 resulted in higher house loan prices, considerably impacting on affordability, which was additional exacerbated by substantial levels of inflation escalating the price of dwelling for fairly a few shoppers.”  

    Uk Finance figures clearly present that general gross lending all through the mortgage sector fell 29% to £223bn remaining yr, with remortgages 23% cut back and the make investments in-to-enable market place down 50%.  

    Belmont Green elements out that its new digital retention platform, seen 62% of maturing shoppers take into account out a new supply with the corporate, allowing it to prohibit redemptions to £0.2bn final yr.  

    This enabled it to finish 2023 with web mortgage loan belongings principally unchanged at £1.7bn.   

    It additionally completed two family property finance loan-backed stability transactions in 2023 elevating £750m, with a additional £300m raised in January 2024.  

    The company posted a income prematurely of tax of £6m, up from £1.4m in 2022.

    The report provides: “In December 2023, Uk Finance forecast a additional more 5% contraction within the gross house loan market place in 2024, reflecting the larger charge pure atmosphere and ongoing minimal client self-assurance.   

    “Our very personal view is a little bit far more optimistic, reflecting new enhancing financial data and early proof of charge reductions driving amplified motion ranges.   

    “Anticipated fascination degree reductions all through 2024, and a gradual enchancment in affordability and purchaser self-confidence together with pent-up want is probably going to restrict any additional discount in house costs, with a probably for them to keep broadly flat 12 months on yr.”  

  • LendInvest introduces twin representation for more quickly bridging bargains – Home loan Strategy

    LendInvest Mortgages has launched twin illustration for bridging jobs, now supplied throughout its merchandise range.

    According to LendInvest, the characteristic, run by its Mortgages Portal, gives prospects higher adaptability and efficiency in operating their bridging specials.

    With twin representation, shoppers have the freedom to select a one legislation company to behave on behalf of the 2 on their very own and LendInvest. This streamlines the licensed course of, accelerates deal completion, and lessens costs by eliminating the necessity to have for plenty of licensed associates.

    Commenting on the beginning LendInvest director of bridging Leanne Ardron defined: “Our twin illustration choice is meant to produce our buyers with enhanced profit and expense worth financial savings.

    By utilising twin representation we will drastically pace up the bridging course of, enabling our prospects to complete their initiatives faster and more proficiently. This is an additional occasion of how our Mortgages Portal is driving innovation and strengthening the general purchaser encounter.”

  • House affordability decreases in Q2 as charges surge once more

    On prime rated of pre-present homeownership-relevant stressors these as superior rates of interest and rising residence taxes, median dwelling charges have shot once more up and want more of 1’s wage to proceed being economical, in keeping with Attom. 

    The genuine property info curator situated median dwelling costs soared to a unique file excessive in its second quarter affordability report. Main homeownership bills now account for 35.1% of the peculiar American’s wages, the very best portion provided that 2007, the report defined. The share stands correctly beforehand talked about the prevalent 28% lending guideline that’s regarded as economical. 

    In the subsequent quarter of 2024, median-priced solitary-household households and condos remained considerably much less inexpensive in distinction to historic averages. The latest craze continued a sample that commenced in early 2022, in which homeownership demanded large elements of Americans’ wages amid ongoing substantial dwelling finance mortgage costs and promoting costs, in accordance to Attom. 

    There was a short lived interval of enchancment in affordability in late 2023 probably into early 2024. For the length of the spring shopping for time, the median family price ticket shot as much as a brand new massive of $360,000, with the increasing worth of possessing a family outpacing wage enlargement. The most up-to-date determine is up from $335,500 in the primary quarter this yr. At the county diploma, median dwelling value ranges rose from Q1 to Q2 in 87.3% of the 589 U.S. counties Attom researched. 

    In the subsequent quarter, the portion of regular wages required for normal home mortgage funds, belongings taxes and insurance coverage rose by 3 proportion particulars each quarterly and yearly. 

    “The most up-to-date affordability data affords a apparent downside for home purchasers. When residence value ranges are rising and property finance mortgage charges proceed being pretty substantial, these variables are creating households considerably much less cost-effective,” defined Attom CEO Rob Barber. 

    “It may be widespread for these developments to accentuate in the course of the spring buying time when purchaser want raises. Even so, the tendencies this 12 months are considerably robust for residence hunters, further so than at any level contemplating the truth that the housing business increase began in 2012.”

    The kinds discovered from April to June produced as the nationwide median dwelling worth rose 7.3% quarterly and 4.7% yearly, the report concluded. Regular 30-year dwelling finance mortgage charges carry on to generate away prospects as successfully, as they completed the preliminary quarter at 6.9%, further than double the place they had been being in 2021. 

    Individuals discouraging parts boosted homeownership prices by throughout 10% in the second quarter subsequent earlier quarterly declines, Attom found. 

    The a part of widespread neighborhood wages contributing to important dwelling expenditures was deemed unaffordable in about 80% of the counties examined nationally all through the subsequent quarter, based on the 28% lending guideline. 

    A variety of areas with superior populations have managed affordability, which embrace Houston, Detroit, Philadelphia, Cleveland and Pittsburgh.  

    Dwelling price development is mounting more shortly than wages in fifty p.c of American counties. Calendar year-more than-12 months family worth variations outpaced weekly annualized wage boosts all by Q2 in 47.9% of the counties analyzed, worsening affordability on prime of upper curiosity charges and hovering dwelling taxes. 

    The earnings required to handle a normal dwelling in the U.S. this quarter is 25% far more than peculiar, in accordance to the report. Key homeownership payments on commonplace homes provided in Q2 demanded an once-a-year earnings of $90,598 to be inexpensive, 25.2% further than essentially the most up-to-date regular nationwide wage of $72,358.

    Affordability stays most out of attain in the Northeast and collectively the West Coast. Nineteen of the main 20 counties the place large expenditures took essentially the most important proportion out of normal group wages all through the quarter had been being in folks places, these kinds of as Brooklyn, New York, in which 111.8% of the annualized neighborhood wage was important to get a house, Attom said.