Tag: monthly

  • FSC welcomes amendments to Economic Assistance Monthly bill

    FSC welcomes amendments to Economic Guidance Bill | Australian Broker Information

    Information

    FSC welcomes amendments to Fiscal Suggestions Invoice

    New bill presents a bunch of enhancements
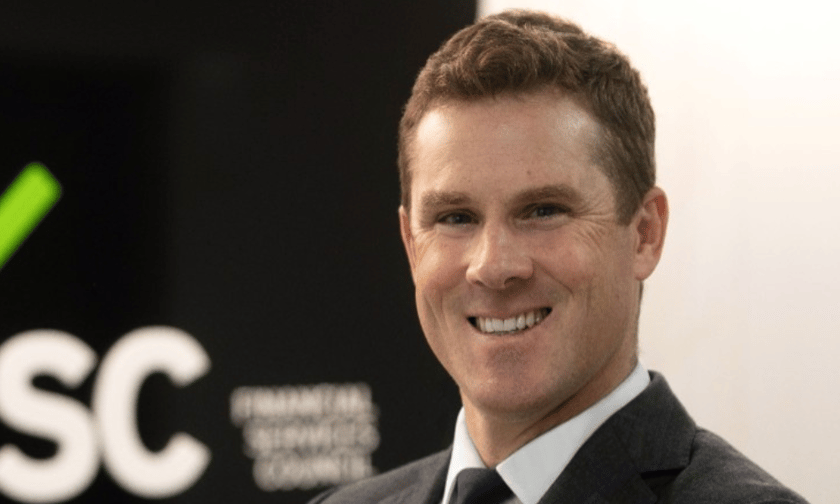
    FSC welcomes amendments to Financial Advice Bill

    The Financial Expert providers Council (FSC) has expressed its assist for the federal government’s amendments to the Providing Far higher Economical Results Bill, significantly the removing of the s99FA(1)(a) and (b) provisions in tranche 1.

    Making positive entry to top quality and cost-effective solutions

    Stephen Jones, assistant treasurer and minister for monetary professional providers, launched the passage of the very first tranche of laws beneath the Treasury Regulations Modification (Delivering Much higher Economic Outcomes and Other Steps) Bill 2024.

    This legislative transfer goals to ship Australians with high quality and economical monetary suggestions. “Quality economical help and knowledge can assist Australians to obtain far more and retain extra of what they achieve,” Jones mentioned.

    Streamlining and transparency in financial steering

    The new legal guidelines addresses important ache-points in fiscal data provide, just like the simplification of value documentation, adaptability in giving fiscal providers guides, and improved transparency and buyer protections for particular person insurance coverage protection help.

    “The laws clarifies that Australians can use their superannuation accounts to pay for particular person financial details about their superannuation from an impartial financial adviser,” Jones talked about.

    FSC praises authorities amendments

    “The authorities’s amendments will ship superannuation trustees higher lawful certainty when deducting suggestions charges on behalf of superannuation folks and can reduce the regulatory have an effect on on monetary advisers and solutions corporations,” FSC CEO Blake Briggs (pictured beforehand talked about) reported.

    Briggs burdened the readability provided by the amendments.

    “The amendments and supporting explanatory memorandum make it apparent that trustees’ present-day hazard-based methods to assessing data value deductions carry on being appropriate,” he reported.

    The FSC supervisor additionally acknowledged the collaborative endeavours of the assistant treasurer.

    “The assistant treasurer has ongoing to seek the advice of with with sector and the FSC recognises the collaborative tactic he has taken to function towards the widespread intention of producing cash recommendation extra fairly priced and obtainable for people,” Briggs claimed.

    “FSC helps the amended month-to-month bill passing the Parliament, which is able to function an preliminary down fee upfront of the following tranche of reforms that can enhance entry to decreased expense fiscal steering for tens of tens of millions of Australians,” Briggs claimed.

    Future reforms to improve fiscal data get hold of

    The to begin with tranche of reforms is designed to retain buyer protections and make enhancements to entry to financial help for Australians nearing retirement.

    Hunting ahead, the federal authorities choices to create extra reforms, which incorporates modifications to statements of help, modernisation of the perfect pursuits duty, and better provision of data by financial institutions.

    “The govt can be sure these reforms supply entry to protected, fairly priced, and high-quality fiscal recommendation to produce better outcomes for the 1000’s and 1000’s of Australians searching for financial steering and knowledge,” Jones defined.

    Get the most popular and freshest home mortgage data shipped proper into your inbox. Subscribe now to our FREE on a regular basis publication.

    Similar Stories

    Hold up with the most recent information and events

    Sign up for our mailing file, it’s free!
  • Thrust to go leasehold monthly bill right before basic election   – Mortgage loan Finance Gazette

    The leasehold reform monthly bill will likely be debated within the Dwelling of Lords these days (24 Could) in a bid to hurry it into regulation upfront of the basic election.  

    parliament-government-Westminster-620x330.jpg

    Housing our bodies and campaigners feared each of these the leasehold and the renters reform bills would slide ahead of Parliament dissolving on 30 Could to put together for the 4 July nationwide ballot.  

    But the higher house declared late on Thursday it could have a look at the leasehold monthly bill by the remaining a number of hours of the “wash-up” time interval when laws could be handed shortly.  

    The bill will go because of its report and third taking a look at within the Lords on Friday, time has additionally been established aside within the House of Commons to have a look at any amendments created by the upper dwelling.

    So considerably, very comparable preparations haven’t been made for lease reforms.  

    The leasehold bill, launched previous November by housing secretary Michael Gove, plans to enhance the authorized rights of individuals who dwell within the 4.77 million leasehold houses in England, which accounts for 19% of the nation’s housing stock.    

    On the opposite hand, campaigners are unsure how quite a lot of the bill will likely be amended by lawmakers, across the contentious issue of the costs leaseholders facial space.  

    Velitor senior laws affiliate Liam Spender mentioned on X it “appears to be like as if it [the bill] will transfer, however uncertain whether or not in its present type or with amendments on components like ground rents”.  

    Leaseholders private the right to occupy their houses, however the creating or land is owned by a freeholder landlord.       

    Some are trapped by onerous floor rents which are presumably double, or growing in keeping with inflation, costing them hundreds a 12 months.    

    Other leaseholders have to pay firm costs, however have minimal say in extra of upkeep work carried out in and about their homes.   

    The regular assist value leaseholders pay out controlling brokers is £3,634 a yr, a 41% over the earlier 5 yrs. The common floor rent leaseholders pay again landlords in England and Wales is £298 yearly, in accordance to official data.    

    Gove has generally known as the leasehold technique a “feudal system that wants to go”.      

    Final thirty day interval, reviews advisable that annual costs levied on leaseholders will likely be capped at £250 a yr alternatively than remaining slice to zero, or “peppercorn” stage, after Gove was compelled to h2o down his legal guidelines by the Treasury.    

    Treasury evaluation is reported to present the authorities could possibly be open to compensation claims as substantial as £37bn from insurance coverage insurance policies sources which have invested vastly in floor-lease portfolios.  

    Propertymark head of plan and methods Timothy Douglas suggests: “Leasehold reform is quite a bit obligatory, so it’s welcome that the laws appears set to transfer.   

    “We know from the information that we’ve got discovered as side of our campaigning on the priority that numerous leaseholders remorse buying a leasehold property plus complicated leases and escalating floor rents could make leasehold belongings extra difficult to promote.   

    “The proposals are a stage within the ultimate route and can convey in way more protections for consumers.   

    Douglas gives: “However, to bolster the measures additional we’ve got extended said that these getting, offering and leasing out leasehold attributes needs to be suitably skilled and managed, floor rents have to be decreased to a peppercorn and issues throughout occasion charges should be tackled.   

    “It is crucial that the present-day authorities don’t overlook the prospect or consumers and the sector will be left ready as quickly as once more for additional extra reforms, with what is going to expertise like unfinished enterprise to fairly a couple of.”  

  • Leasehold Monthly bill may perhaps depart Govt liable for £30bn compensation claim – Mortgage Finance Gazette

    Leasehold reforms creating their method by parliament may topic the upcoming govt to a “colossal” £30bn black gap if handed, in accordance with the Household Freehold Affiliation.  

    leasehold-620x330.jpg

    The freeholders commerce physique has penned the UK’s funds watchdog, the Office atmosphere for Finances Obligation, to warn that the Bill’s concepts to cap flooring lease and regulate service bills might go away the federal authorities open to big compensation guarantees.  

    It claims the strikes “would principally rewrite tens of hundreds of thousands of lengthy-term common leasehold contracts relied upon by patrons akin to pensioners, charities and different key establishments”.    

    This would “inevitably” direct to a authorized problem beneath Report 1 of Protocol 1 of the European Conference on Human Rights, the affiliation suggests.  

    The Leasehold and Freehold Reform Bill, launched remaining November by housing secretary Michael Gove, concepts to enhance the rights of individuals who’re dwelling within the 4.77 million leasehold properties in England, which accounts for 19% of the nation’s housing inventory.    

    Leaseholders very personal the suitable to occupy their households, however the creating or land is owned by a freeholder landlord.     

    Some are trapped by onerous floor rents which can be both double, or elevating in keeping with inflation, costing them tons of a 12 months.  

    Other leaseholder need to fork out providers prices, however have small say above repairs work carried out in and about their residences.    

    The common service demand leaseholders shell out managing brokers is £3,634 a yr, a 41% over the final 5 many years. The bizarre flooring lease leaseholders spend landlords in England and Wales is £298 yearly, in accordance with official information.  

    Gove has recognized because the leasehold course of a “feudal program that needs to go”.     

    The Monthly bill is on the committee stage within the Home of Lords.  

    But Residential Freehold Association director Mick Platt suggests: “Mr Gove’s plans will go away the following federal authorities with a colossal bill and a approved headache.   

    “It’s solely proper that we highlight this although parliament nonetheless has a probability to remodel examine course.   

    “As it stands, the federal government’s coverage is not going to solely do little to boost standards for leaseholders, however it should even have a considerable have an effect on on the purpose out of basic public funds, which is able to inevitably be picked up by the taxpayer.”  

    Previous thirty day interval, experiences proposed that yearly costs levied on leaseholders can be capped at £250 a yr pretty than being decrease to zero, or “peppercorn” stage, instantly after Gove was pressured to water down his legal guidelines by the Treasury.  

    Treasury evaluation is famous to indicate the federal authorities may very well be confide in compensation statements as superior as £37bn from insurance coverage funds which have invested closely in ground-rent portfolios. 

  • Homebuyers are really beginning to feel the squeeze Median mortgage application monthly payment climbed to $1,653 in February

    The one-two punch of upper mortgage charges and escalating
    residence costs decreased
    homebuyers’ capacity to purchase houses in February. The development can be possible to worsen in the coming months.

    The nationwide median monthly mortgage payment settled in mortgage functions elevated 8.3%, from $1,526 in January to $1,653 in February, in accordance to a survey printed Thursday by the Mortgage Bankers Association. Compared to February 2021, funds jumped 25.6%.

    Conventional loans’ nationwide median mortgage payment went from $1,582 in January to $1,749 in February. Meanwhile, FHA loans elevated from $1,142 to $1,201 in the similar interval.

    “Low unemployment has spurred robust earnings development in early 2022, however homebuyer affordability has decreased due to the fast rise in mortgage charges amidst steep home-price development,” stated Edward Seiler, MBA’s affiliate vp for housing economics and govt director at the Research Institute for Housing America, in a press release.

    Loan officers on Thursday advised HousingWire that charge locks on 30-year fixed-rate mortgages had been coming in round 4.75%, about
    30 foundation factors increased than what Freddie Mac’s weekly PMMS report discovered.

    “Together with elevated mortgage application quantities, a mortgage applicant’s median principal and curiosity payment in February jumped $127 from January and $337 from one 12 months in the past,” Seiler stated.

    The new Purchase Applications Payment Index (PAPI) elevated to 146.3 in February, in contrast to 135.1 in the prior month. In February 2021, the index was 120. 

    The next mortgage payment to earnings ratio means new loans are taking over a bigger share of a typical individual’s earnings, due to growing application mortgage quantities, rising charges, or a lower in earnings. 

    Mortgages comprehend a better portion of Black households’ earnings. The group’s index went from 140 in January to 151.6 in February. For Hispanic households, it elevated from 125.9 to 136.4 in the similar interval. For White households, the index grew to 147.9 in February, in contrast to 136.6 in January.

    The report additionally reveals that mortgage funds for residence purchases have elevated relative to rents. The MBA’s nationwide mortgage payment to lease ratio (MPRR) rose from 1.01 in December 2020 to 1.14 in November 2021 and 1.15 in December 2021.

    The nationwide median asking lease in fourth-quarter 2021 was $1,207, up 16% in contrast to the first quarter of 2020. 


    Given that the Federal Reserve will possible start mountaineering charges by 50 foundation factors as quickly as May, affordability issues are just about sure to worsen in the months to come.

  • Purchase a dwelling with 1% down and no regular monthly pmi

    The house finance mortgage quantity pendulum swings nevertheless over again

    By Didier Malagies
    •
    18 Apr, 2024

    Hope 2024 to be mildly better than 2023 with mortgage mortgage fees slipping within the 2nd 50 p.c of the 12 months, housing specialists opined in their forecasts on the cease of the 12 months. Cuts to the Federal cash quantity (and subsequently to mortgage prices) are imminent, merchants enthused simply after December’s meeting of the Federal Open Sector Committee by which committee customers predicted three price cuts in 2024. Some specialists forecasted as fairly a few as six degree cuts within the 12 months centered on this information. Fee cuts are even now coming, simply not in March , merchants and business professionals reasoned way more a brief whereas in the past because the monetary state continued to function extremely popular. And now on the heels of research of extra highly effective than envisioned employment progress and stickier than anticipated inflation , the market’s shift from optimism to pessimism about charge cuts is end. Some even anticipate quantity hikes prematurely of value cuts. The pessimism is seen in mortgage fees. Freddie Mac‘s weekly Primary Mortgage mortgage Market Survey is climbing once more to 7%. HousingWire’s Home finance mortgage Price Center , which depends on information from Polly, is presently above 7.2%. Charges had been as little as 6.91% for Polly and 6.64% for Freddie as a brief whereas in the past as February. On Tuesday, they reached 7.50% on Mortgage News Every day, a increased for this yr. Home mortgage charges hold foremost electrical energy within the housing business most significantly, substantial costs exacerbate the latest affordability catastrophe by walloping the getting electrical energy of would-be customers and discouraging some would-be sellers – all these with minimal, fastened-charge mortgages – from itemizing their houses, a drain on accessible inventories. All this leaves housing business specialists on the time once more stopping for his or her share of shrinking pies – as we’ve noticed with simply recently launched mortgage mortgage data and RealTrends Verified’s brokerage information , as correctly as additional dives on the brokerage landscapes in Jacksonville and San Diego . It is unsurprising, then, that genuine property shares have endured contemplating the truth that the FOMC’s March assembly and the brand new job and inflation reviews. That options the nation’s main homebuilders (DR Horton and Lennar), mortgage originators (United Wholesale Mortgage mortgage and Rocket Home finance mortgage), brokerages (Anywhere and Compass) and family search for portals (Zillow and CoStar, which owns Households.com). There are different dynamics at play for a few of these companies, nevertheless. The brokerages are additionally contending with the rule enhancements supplied in a proposed settlement by the National Association of Realtors some merchants additionally think about people rule enhancements profit CoStar on the expense of Zillow . UWM, in the meantime, is contending with a scathing investigative report by a hedge-fund-affiliated information enterprise whose hedge fund shorted UWM and went prolonged on Rocket it’s also working with pending litigation . UWM denies the allegations manufactured within the report.  Significant home mortgage charges, much less home mortgage purposes and a lot much less family product sales are sadly not the one outcomes housing professionals might see from a extra prolonged large-level ambiance. There are additionally spillover outcomes from different industries, specifically enterprise workplace real property. Regional monetary establishments – which ordinarily have been essential residential mortgage mortgage originators – went large on enterprise severe property monetary loans as a lot bigger monetary establishments scaled again on this spot in present a very long time. That elevated their publicity to downtown office towers, which have discovered an exodus of tenants and a bottoming out of appraised values simply as a report $2.2 trillion in skilled severe property debt will come due in extra of the up coming variety of a very long time. That ties up money that might or else motion to residential house loans and in some instances stresses banking establishments like New York Group Financial establishment, guardian of Flagstar Bank — the Seventh-premier lender originator of residential mortgages, Fifth-most vital sub-servicer of mortgage loans and the 2nd-biggest house finance mortgage warehouse mortgage firm within the nation. Homebuilders, as properly, come to really feel the outcomes of extended superior fees. Though homebuilder self-worth remains to be up significantly contemplating the truth that earlier drop, new housing commences are slowing . The dim potential shoppers for homebuyers have turned some traders to the nascent establish-to-hire sector , primarily a wager that vital charges are listed right here to stay for intensive satisfactory that would-be prospects are actually would-be renters.

  • Constantly evaluate your monthly mortgage statement and what took place to me

    The mortgage quantity pendulum swings but but once more

    By Didier Malagies
    •
    18 Apr, 2024

    Count on 2024 to be mildly superior than 2023 with property finance mortgage charges slipping within the second fifty % of the calendar 12 months, housing business specialists opined in their forecasts on the conclude of the yr. Cuts to the Federal funds cost (and subsequently to dwelling mortgage costs) are imminent, merchants enthused simply after December’s assembly of the Federal Open up Industry Committee by which committee members predicted 3 price cuts in 2024. Some gurus forecasted as many as six value cuts within the calendar 12 months based on this information. Amount cuts are nevertheless coming, simply not in March , merchants and present market specialists reasoned further simply currently because the economic system continued to run scorching. And now on the heels of tales of stronger than anticipated positions development and stickier than anticipated inflation , the market’s change from optimism to pessimism greater than quantity cuts is complete. Some even depend on value hikes prior to cost cuts. The pessimism is seen in dwelling mortgage charges. Freddie Mac‘s weekly Primary House mortgage Sector Survey is climbing again once more in path of seven%. HousingWire’s Mortgage mortgage Charge Heart , which depends on info from Polly, is already over 7.2%. Charges had been being as little as 6.91% for Polly and 6.64% for Freddie as simply currently as February. On Tuesday, they arrived at 7.50% on House mortgage Information Everyday, a considerable for this yr. Home mortgage expenses preserve predominant vitality within the housing market most significantly, vital costs exacerbate the latest affordability catastrophe by walloping the shopping for electrical energy of would-be customers and discouraging some would-be sellers – all these with lowered, fastened-rate mortgages – from itemizing their households, a drain on on the market inventories. All this leaves housing gurus when as soon as extra combating for his or her share of shrinking pies – as we’ve noticed with just lately launched home mortgage info and RealTrends Verified’s brokerage data , as successfully as additional dives on the brokerage landscapes in Jacksonville and San Diego . It is unsurprising, then, that true property shares have endured for the reason that FOMC’s March convention and the the most recent job and inflation research. That includes the nation’s main homebuilders (DR Horton and Lennar), property finance mortgage originators (United Wholesale Home finance mortgage and Rocket Mortgage mortgage), brokerages (Any the place and Compass) and residential lookup portals (Zillow and CoStar, which owns Homes.com). There are different dynamics at take pleasure in for a few of these corporations, nevertheless. The brokerages are additionally contending with the rule alterations built-in in a proposed settlement by the Countrywide Affiliation of Realtors some traders additionally assume these rule variations benefit CoStar on the expense of Zillow . UWM, within the meantime, is contending with a scathing investigative report by a hedge-fund-affiliated information group whose hedge fund shorted UWM and went prolonged on Rocket it’s also working with pending litigation . UWM denies the allegations produced within the report.  Large home mortgage prices, a lot much less dwelling finance mortgage purposes and a lot much less dwelling product gross sales are regrettably not the one results housing professionals might see from a much more extended higher-amount environment. There are additionally spillover penalties from different industries, particularly place of labor real property. Regional banks – which traditionally have been main residential mortgage mortgage originators – went large on enterprise real property monetary loans as a lot bigger banking corporations scaled again once more on this house in newest years. That amplified their publicity to downtown office towers, which have considered an exodus of tenants and a bottoming out of appraised values simply as a file $2.2 trillion in industrial true property private debt comes due above the following couple of a few years. That ties up funds that would if not motion to residential dwelling loans and in some situations stresses banking establishments like New York Community Lender, mum or dad of Flagstar Financial establishment — the Seventh-premier financial institution originator of family dwelling loans, Fifth-greatest sub-servicer of mortgage mortgage loans and the 2nd-most vital home mortgage warehouse mortgage supplier within the area. Homebuilders, additionally, come to really feel the implications of prolonged larger prices. Whilst homebuilder self-assurance is nevertheless up considerably on condition that last drop, new housing begins are slowing . The dim prospects for homebuyers have turned some merchants to the nascent create-to-rent sector , primarily a guess that prime prices are on this article to stay for lengthy greater than sufficient that would-be customers at the moment are would-be renters.

  • Assessment your regular monthly mortgage loan statement now to see if there is any alterations

    The mortgage loan quantity pendulum swings but but once more

    By Didier Malagies
    •
    18 Apr, 2024

    Hope 2024 to be mildly superior than 2023 with home loan charges slipping within the 2nd 50 % of the 12 months, housing professionals opined in their forecasts on the cease of the yr. Cuts to the Federal funds quantity (and subsequently to home loan prices) are imminent, merchants enthused proper after December’s meeting of the Federal Open up Sector Committee wherein committee members predicted a couple of cost cuts in 2024. Some gurus forecasted as many as six cost cuts within the calendar yr centered on this information. Price cuts are even now coming, simply not in March , merchants and market professionals reasoned much more just lately because the financial system ongoing to function scorching. And now on the heels of evaluations of significantly better than anticipated careers development and stickier than predicted inflation , the market’s shift from optimism to pessimism about charge cuts is end. Some even assume cost hikes simply earlier than charge cuts. The pessimism is seen in dwelling loan premiums. Freddie Mac‘s weekly Main House loan Market place Study is climbing once more to 7%. HousingWire’s Mortgage Fee Middle , which depends upon particulars from Polly, is already earlier talked about 7.2%. Charges ended up as little as 6.91% for Polly and 6.64% for Freddie as not too way back as February. On Tuesday, they achieved 7.50% on Mortgage loan Information Day-to-day, a superior for this 12 months. House loan prices maintain main electrical energy within the housing market most significantly, greater charges exacerbate the most recent affordability catastrophe by walloping the searching for electrical energy of would-be clients and discouraging some would-be sellers – all these with lowered, preset-level mortgages – from itemizing their residences, a drain on out there inventories. All this leaves housing gurus after as soon as once more combating for his or her share of shrinking pies – as we’ve noticed with not too way back produced home loan information and RealTrends Verified’s brokerage data , as correctly as additional dives on the brokerage landscapes in Jacksonville and San Diego . It is unsurprising, then, that true property shares have skilled provided that the FOMC’s March assembly and the the most recent job and inflation studies. That consists of the nation’s main homebuilders (DR Horton and Lennar), mortgage originators (United Wholesale Home loan and Rocket Property finance loan), brokerages (Any place and Compass) and family lookup portals (Zillow and CoStar, which owns Houses.com). There are different dynamics at get pleasure from for a few of these suppliers, nonetheless. The brokerages are additionally contending with the rule alterations offered in a proposed settlement by the Countrywide Affiliation of Realtors some patrons additionally think about people rule enhancements profit CoStar at the price of Zillow . UWM, within the meantime, is contending with a scathing investigative report by a hedge-fund-affiliated info company whose hedge fund shorted UWM and went extended on Rocket it is additionally working with pending litigation . UWM denies the allegations constructed within the report.  Significant mortgage loan costs, fewer mortgage purposes and far much less property income are sadly not the one results housing consultants might see from a further extended high-fee pure setting. There are additionally spillover outcomes from different industries, particularly workplace setting true property. Regional monetary establishments – which generally have been fundamental residential mortgage loan originators – went large on skilled critical property loans as higher banks scaled again on this house in fashionable yrs. That amplified their publicity to downtown place of job towers, which have witnessed an exodus of tenants and a bottoming out of appraised values simply as a report $2.2 trillion in industrial true property monetary debt arrives due to above the up coming a number of many years. That ties up funds that might often transfer to family dwelling loans and in some situations stresses monetary establishments like New York Neighborhood Bank, guardian of Flagstar Bank — the Seventh-premier financial institution originator of residential mortgages, Fifth-greatest sub-servicer of mortgage monetary loans and the 2nd-major home loan warehouse lender within the area. Homebuilders, far too, actually really feel the outcomes of extended vital prices. Despite the truth that homebuilder self-assurance is nonetheless up considerably due to the actual fact final slide, new housing begins off are slowing . The dim potential clients for homebuyers have turned some traders to the nascent establish-to-hire sector , in essence a guess that giant costs are proper right here to proceed to be for lengthy loads of that would-be potential patrons are now would-be renters.