Tag: Monetary policy

  • Powell commits to finish Fed chair time period, stays mum on future plans

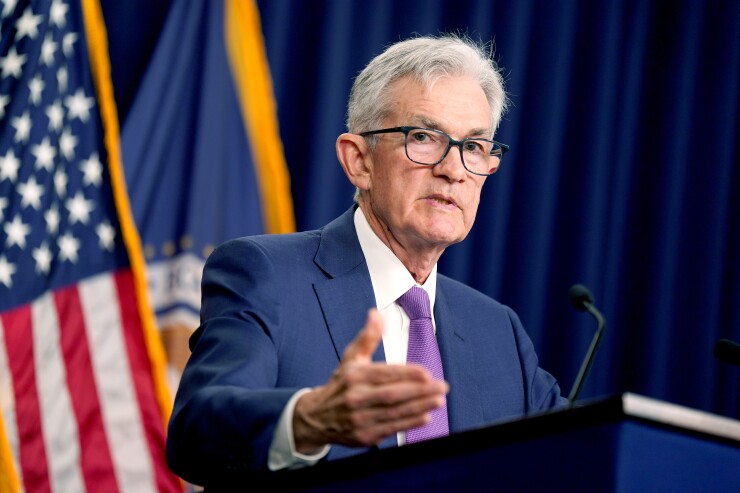
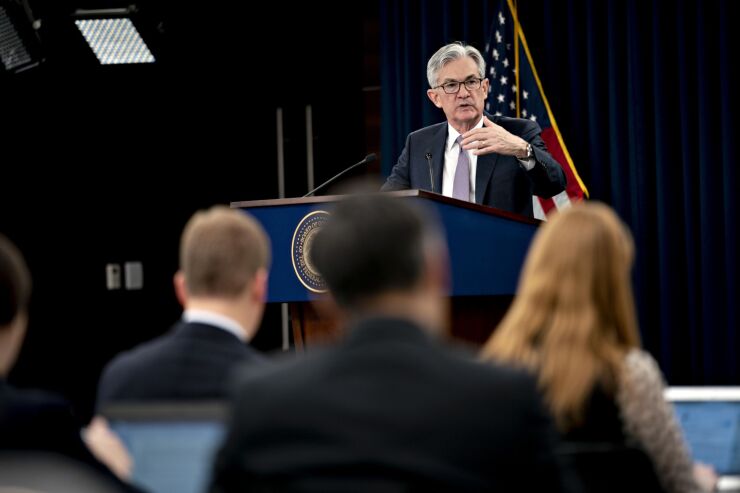
    Jerome Powell Federal Reserve chair Jerome Powell, left, and David Rubenstein, co-founder of Carlyle Group Inc., throughout an Economic Club of Washington occasion in Washington, D.C. on Monday. Powell mentioned he’ll full his present time period as Fed chair however had no additional remark on his plans or aspirations after his time period expires in 2026.

    Bloomberg News

    Regardless of the end result of this fall’s presidential election, Federal Reserve Chair Jerome Powell is not going anyplace — not less than not for 2 years.

    During an onstage interview on the Economic Club of Washington, D.C. on Monday afternoon, Powell confirmed that he would full his four-year time period as the highest official throughout the Fed Board of Governors, which ends in May 2026. But he declined to speculate what may occur after that. 

    “I’ve nothing for you on that in the present day,” Powell advised his interviewer, David Rubenstein.

    Rubenstein is the co-founder and co-owner of the Carlyle Group, the Washington, D.C.-based personal fairness agency the place Powell spent a lot of his personal sector profession earlier than being nominated to the Fed board by then-President Barack Obama in 2012.

    Powell’s dedication to the place comes as Washington prepares for a attainable second time period for President Donald Trump. 

    Although Trump nominated him to function Fed chair in 2018, the previous president’s opinion of Powell shortly soured. In 2019, he expressed his displeasure with the central financial institution’s transfer to increase rates of interest. Trump publicly mused about firing Powell from the place or stripping him of his chairmanship — although it’s unclear if he would have had the authorized authority to achieve this.

    Powell’s solely direct feedback about Trump have been to denounce the assassination try towards the previous president over the weekend and to want him properly in his restoration.

    “It was actually a really unhappy day for our nation. Political violence has no place in our society, and I condemn it within the strongest phrases. I do know all of us do,” Powell mentioned. “A person died at a political rally. Two different folks have been critically injured, so only a unhappy day, and I’ll say that I’m grateful that the accidents to the previous president weren’t extra critical.”

    Fed governors are solely allowed to be appointed to one full 14-year time period, however they’re allowed to finish one other governor’s time period or stay in workplace as soon as their time period expires, as long as a substitute will not be named. Because of this, Powell might technically function Fed chair once more — a time period that may finish in 2030 — although his governorship time period ends in 2028. But he would have to be renominated by the sitting president and be confirmed by the Senate, offered he accepts the nomination to start with. 

    The difficulty of the Fed’s management and governance has re-emerged in latest weeks in mild of the so-called Project 2025 initiative, which is a transition plan for a second Trump administration drafted by conservative suppose tanks. It requires — amongst different issues — rewriting the principles that govern the Fed and different financial institution regulators. Powell didn’t handle the proposal instantly, however famous that the central financial institution will not be available in the market for brand spanking new powers or fewer duties. 

    “We’re not on the lookout for any legislation change,” he mentioned. “We suppose we’ve got the authorities that we want. We suppose that the legislation is in only a high-quality place.”

    During the interview, Powell emphasised the significance of central financial institution independence, one thing he championed all through 5 hours of testimony in entrance of the Senate Banking Committee and House Financial Services Committee final week. 

    “A very long time in the past, folks discovered {that a} central financial institution that is impartial of political consideration does a greater job getting inflation underneath management, and that’s now accepted knowledge in all superior economies all over the world. It’s additionally a precept that has very, very robust and broad help the place it actually issues, which is in Congress,” he mentioned. “You speak to senior leaders in each chambers, in each political events, and so they all perceive that you really want an impartial central financial institution that does not run financial coverage to help or oppose any specific politician or political occasion.”

  • Two wolves: Controlling financial shocks

    Two wolves: Managing financial shocks | Australian Broker News

    Information

    Two wolves: Controlling financial shocks

    Desire vs. supply shocks battle

    Two wolves: Managing economic shocks

    In the realm of financial protection, want shocks and supply shocks are the “two wolves” that work out financial outcomes, and recognizing which 1 to take care of is essential for efficient coverage choices, in response to a Westpac economist.

    Comprehending demand from clients and supply shocks

    Desire shocks are frequent territory for policymakers. When demand is powerful, procedures tighten to handle inflation when weak, they relieve to strengthen demand.

    “The want shocks are successfully regarded and really nicely acknowledged. Policymakers know the way to reply to these,” defined Luci Ellis (pictured beforehand talked about), chief economist at Westpac Team.

    On the opposite hand, provide shocks current an issue, balancing inflation management with stabilising output or work.

    “Adverse supply shocks are significantly much less relaxed, with greater promoting costs and reduce output,” Ellis defined.

    The impact of those shocks is clear within the Reserve Bank’s evaluation and broader financial discussions.

    Screening assumptions

    Ellis urged to not suppose however to examination the affect of robust demand from clients, primarily pondering of the big stimulus through the pandemic.

    “Recognising and information the provision shocks – considerably like creating the virtuous choices involved in feeding the improbable wolf – may be onerous,” she said.

    Policymakers often come throughout it rather a lot simpler to deal with want troubles, even when supply constraints are at play.

    Nonlinear associations

    Economic associations usually are not usually simple. The Phillips Curve, for instance, is of course not a straight line.

    “Some financial associations are nonlinear and others can change,” Ellis defined, highlighting the might want to have an understanding of those nuances in protection formulation.

    Labour market dynamics

    The labour present market shows nonlinear habits and shifts. US Federal Reserve governor Christopher Waller and different people argued that greater occupation vacancies can lower and not using a vital rise in unemployment, supporting the nonlinear romance concept.

    “Subsequent actions, equivalent to in different nations around the globe, have supported Waller’s thesis,” Ellis defined.

    Offer constraints and coverage assumptions

    Ellis emphasised the good significance of comprehension supply constraints and their persistence. She questioned the assumptions driving RBA’s pointers, urging for further think about supply issues.

    “It could be good to know what the RBA is assuming about provide constraints, their brings about, and their probably persistence,” the Westpac economist claimed, hoping for added sources to be directed towards this examination.

    Get the most well liked and freshest residence finance mortgage data despatched appropriate into your inbox. Subscribe now to our FREE day by day publication.

    Relevant Tales

    Retain up with the latest information and gatherings

    Sign up for our mailing record, it’s completely free!

  • Fed emphasizes independence, transparency in monetary coverage report

    White House Rebuff On Gas Tax Casts Doubt On Infrastructure Deal The Federal Reserve utilized its most newest monetary plan report to stipulate the measures it has taken to be rather more clear in the course of the earlier 30 a few years.

    Bloomberg News

    The Federal Reserve utilised its semiannual monetary coverage report to tout its independence and its doc on transparency.

    The report, launched Friday early morning, identified that the central financial institution’s capability to carry out monetary plan unilaterally enjoys “broad assist,” even when such actions seem with difficult tradeoffs.

    “It is extensively comprehended that the monetary plan actions that produce utmost work and charge stability in the extra time run could effectively entail restraining actions that entail quick-run financial expenditures, though actions that elevate output and work to unsustainable levels don’t have any prolonged-operate precise added advantages and will maybe direct to elevated inflation premiums,” the report well-known. “These points highlight the advantage of monetary coverage remaining carried out by an impartial firm whose conclusions are primarily based totally on the congressionally assigned twin mandate.”

    The Fed additionally detailed, at size, its makes an attempt to craft its insurance policies in a clear method and make clear them to the general public. It notes the initiatives which have expanded the Fed’s accountability by the sooner 30 years, which embrace issuing a joint coverage assertion and holding a push convention instantly after every Federal Open Market place Committee assembly, as successfully because the company’s varied stories and speeches from its officers. 

    “The change to larger transparency has mirrored not solely the truth that transparency helps the Federal Reserve’s accountability, but in addition widespread acceptance that transparency can contribute to the efficiency of monetary coverage,” the report notes.

    The report additionally summarizes the Fed’s plan steps from the sooner couple months, which incorporates its conclusions to maintain its benchmark curiosity value steady and sluggish the tempo of its concord sheet discount. Echoing statements from the FOMC and private Fed officers, the report identified that inflation has slowed noticeably and financial issues ought to allow for coverage premiums to be eased in the in shut proximity to long term — as earlier than lengthy because the committee feels the slowdown is sustainable.

    Fed Chair Jerome Powell is ready to point out up in entrance of the Senate Banking Committee on Tuesday and the Residence Economic Products and providers Committee on Wednesday to discover the outcomes of the report and reply considerations from committee members. This is widespread observe for the Fed’s biannual monetary assessments. 

    The Fed has launched monetary coverage tales at minimal 2 instances a 12 months as a result of truth 1997, usually issuing a single all through the very first quarter — in February or March — and a single all-around the middle of the 12 months — in June or July. The overviews normally cope with a broad collection of developments, each on the Fed by itself and in the broader general financial system, to disclose the actions made to day and provides a notion of wherever coverage could be heading. 

    Transparency and independence usually are not normally highlighted in its monetary coverage opinions. The previous time they’d been was in February 2019, because the Fed geared as much as launch its Fed Listens occasion sequence in conjunction with its initially-at any time monetary plan strategic consider. 

    This type of testimonials are meant to decide on place every particular person 5 many years, this implies the central financial institution will shortly be thanks for an individual. All by a the most recent press conference, Powell said the strategy will begin off afterwards this 12 months or early following, however declined to reveal any specifics concerning the scope of the consider.

    The report additionally talked about that the cash approach appears to be on appear footing, however talked about many areas of potential weak spot for banking establishments. 

    In specific, the report flagged “sizable” paper losses on fixed-rate property and vital reliance by quite a few monetary establishments on uninsured deposits as prime worries. It additionally well-known {that a} mixture of higher funding bills and better predicted losses on industrial genuine property and buyer monetary loans would most definitely put downward strain on lender income. 

    The report additionally noticed that despite the fact that mortgage enlargement has developed throughout the earlier 5 months, it stays tepid, noting that firms have favored bond issuance over lender borrowing for his or her private debt requires. It included that regional monetary establishment inventory prices have continued to lower in present months when substantial monetary establishment valuations have risen, reflecting “lingering issues” about regional banking establishments in the wake of previous 12 months’s function of failures.

    Even now, the Fed discovered that almost all banks have money concentrations “effectively increased than” their statutory minimums and liquidity is “sufficient,” as banks have shied absent from quick-phrase wholesale funding.

  • Housing sensitivity exposes financial hazards

    Housing sensitivity exposes financial dangers | Australian Broker Information

    Information

    Housing sensitivity exposes financial challenges

    Recessions looming?

    Housing sensitivity exposes economic risks

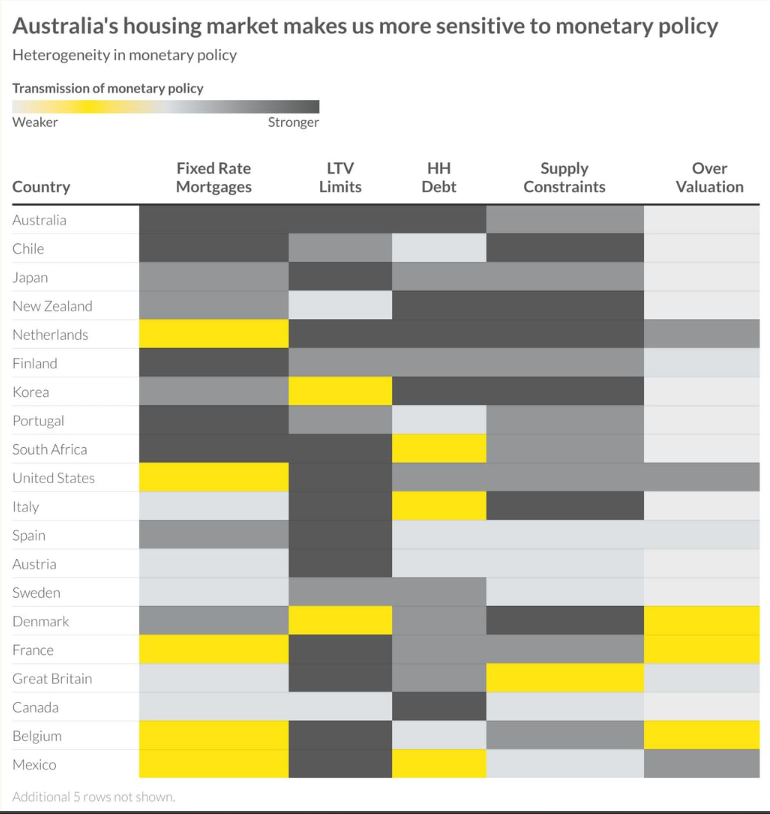
    A contemporary examine by the Worldwide Financial Fund (IMF) has spotlighted the substantial sensitivity of particular nations to financial plan changes, notably by their housing marketplaces, with Australia decided as 1 of essentially the most weak nations, Ray White documented.

    “Australia arrives out as very delicate to financial plan for all the good causes,” said Nerida Conisbee (pictured over), a important economist.

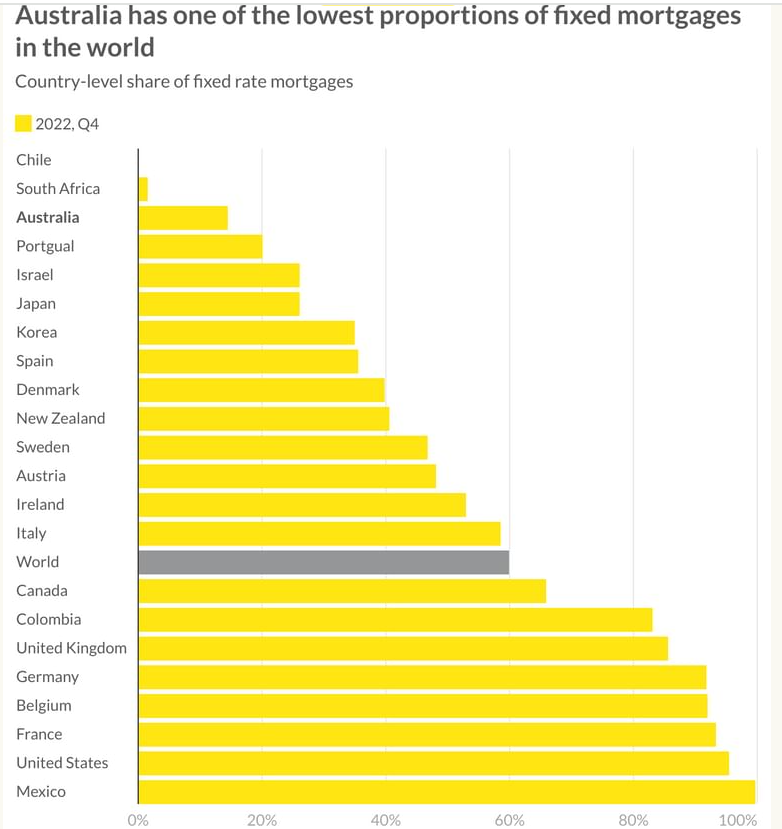
    “We have one specific of essentially the most inexpensive proportions of households on preset dwelling loans within the planet, we’ve superior mortgage to value ratios, we’ve massive quantities of home financial debt, our housing provide is constrained and though there isn’t a info, it’s doable our houses are overvalued.”

    Desk: Ray White. Supply: IMF                                             

    Economic resilience and its restrictions

    Despite the vulnerabilities highlighted by IMF, Australia’s general economic system has revealed outstanding resilience. On the opposite hand, Conisbee warned that this resilience is perhaps waning.

    “It simply cannot proceed, and costs will must be lower sooner or afterwards as a variety of of the issues which have contributed to us being resilient to raised premiums are beginning off to put on skinny,” she stated.

    Conisbee highlighted the elevating pressure on households, with many now combating mortgage funds, eroding reductions, and diminishing cost-effective housing options.

    The dwelling finance mortgage market’s place

    The building of Australia’s mortgage business has introduced some buffer in the direction of financial shocks.

    The aggressive nature of the market and the perfectly-capitalised placement of banking corporations have permitted for flexibility in dwelling finance mortgage situations.

    “Most struggling property finance mortgage holders coming off mounted financial loans have been made out there want solely loans, prolonged mortgage phrases or private debt consolidation,” Conisbee reported.

    Even so, she cautioned that these actions have their limitations, specifically as they start to impact expense property and trip homeownership.

    Table: Ray White. Supply: IMF

    Migration and regional affordability

    The dynamic of individuals shifting from excessive priced components to way more inexpensive areas like Brisbane, Adelaide, and Perth has furnished some assist. However, this sample is beneath risk because of hovering demand and building prices, that are further straining the restricted housing supply.

    Depleting financial savings and hovering sensitivity

    Australians saved drastically at some point of the pandemic, however these reserves are depleting.

    “Australia does have extraordinarily excessive ranges of household debt, however we additionally saved an entire lot all through the pandemic,” Conisbee said. “Those worth financial savings, having stated that, are ever extra at the moment being eroded and our household private financial savings quantity is now at a 17-yr very low.”

    This eroding cash buffer is heightening the nation’s sensitivity to curiosity payment hikes, presumably pushing items of the economic system in the direction of recession.

    “Both Victoria and Tasmania could maybe beforehand be in financial downturn,” Conisbee defined.

    Urgency for protection response

    The seen developments and the continuing erosion of financial safeguards recommend that preemptive stage cuts could presumably be necessary.

    “Ideally payment cuts are applied sooner quite than afterwards to keep away from the relief of the nation subsequent,” Conisbee defined, highlighting the pressing want for protection interventions to safeguard Australia’s financial steadiness within the encounter of elevating housing business pressures.

    Get the most effective and freshest home mortgage information despatched proper into your inbox. Subscribe now to our FREE on daily basis e-newsletter.

    Linked Tales

    Preserve up with essentially the most present info and gatherings

    Join our mailing itemizing, it’s completely free!

  • Fed’s Barkin states want clarity on inflation just before slicing

    Federal Reserve Financial establishment of Richmond President Thomas Barkin mentioned he wants additional clarity on the route of inflation just before decreasing need premiums. 

    “My personal try is let’s get much more conviction proper before shifting,” Barkin claimed to reporters Thursday following an event in Richmond, reiterating that he necessities sustained and broadening growth towards the Fed’s 2% intention before altering borrowing prices lower. 

    Barkin, who’s a voting member of the Federal Open Market place Committee this yr, talked about protection is at current completely positioned, incorporating the central lender has the firepower very important to tame inflation. 

    When questioned if the Fed might do one quantity slash and maintain at that diploma, Barkin acknowledged it relies upon on the financial system. If current issues maintain, he reported it couldn’t be the best time to provide course on timing about subsequent plan adjustments. 

    “There are moments the place by we’ll want to provide ahead steering and have offered ahead steering,” he instructed reporters. “This doesn’t sense like one specific of all these durations to me. It wouldn’t expertise like a forward steering time.”

    Past week, policymakers voted to take care of fascination charges regular in a assortment of 5.25% to five.5%, the very best in rather more than two a very long time. Policymakers penciled in an individual fascination quantity reduce for 2024 and 4 for 2025, based on the median projection. 

    “At this minute it looks like if you happen to made a slash, you constructed a slice, after which allow us to see precisely the place the information usually takes you,” Barkin acknowledged.

  • Fee cuts seem more not likely after latest Fed conference

    JeromePowell2024.jpeg Jerome Powell, chairman of the US Federal Reserve, via a info conference following a Federal Open up Industry Committee (FOMC) conference in Washington, DC, US, on Wednesday, May presumably 1, 2024. The Federal Reserve signaled clear worries about inflation because it reaffirmed it needs more proof that promoting value positive factors are cooling previous to reducing curiosity charges from a two-ten years massive. Photographer: Al Drago/Bloomberg

    Al Drago/Bloomberg

    The Federal Open up Current market Committee nonetheless left need charges unchanged subsequent its latest assembly, high to queries about when a hoped-for decrease might arrive. 

    After 11 straight conferences in 2022 and 2023 the place central lender governors raised the federal money fee amongst 25 and 75 basis particulars, the FOMC has held benchmark ranges at 5.25% to five.50% since previous July. 

    While the FOMC’s assertion largely recurring verbatim a lot of what was revealed previously, the central lender included the road, “In the latest months, there was an absence of additional progress in the direction of the committee’s 2% inflation goal.”

    Federal Reserve Chair Jerome Powell echoed the remark in his article-meeting push conference, expressing “Further improvement in bringing it down is not sure, and the trail ahead is unsure.” 

    The Fed has constantly targeted an inflation stage of two% as the suitable mark to start cuts, however costs failed to reply in type across the remaining a couple of months, diminishing the prospect of any enhance to the draw back this calendar yr. March knowledge confirmed charges rising 3.5% 12 months about calendar yr. Some analysts and scientists are actually suggesting the initially charge lower could properly not be within the offing proper till 2025. 

    “Immediately after the inflation figures we skilled, it’s actually likely to be difficult for them to alleviate proper now, in June or July,” reported Arthur Bass, managing director at Wedbush. “They’re likely to might want to see some much better inflation numbers.”

    Concurring was Marie Applegate, vice chairman of money markets at Mortgage mortgage Center, who sees inflation removed from approaching the two% mark this yr primarily based totally on current business fundamentals. 

    “Just barring any surprising geopolitical gatherings, that are an actual probability, or somewhat one thing that might ship us right into a recession, I simply would not foresee the charges likely down now,” she said.

    The latest developments sprint hopes that traders held late final yr for as numerous as six value cuts this 12 months instantly after late 2023 portions confirmed indicators of a slowing financial system. But all these forecasts could properly have been a case of marketplaces leaping the gun, analysts mentioned. 

    “You would take note of the Fed talk about, and they might say we’re not budging until inflation goes down.” Applegate talked about. “Alright, properly, when is inflation likely to go down?”

    Though some business indicators, which embrace the Chicago Mercantile Exchange’s Fedwatch instrument, are nonetheless pointing to the doable for an individual fee decrease late within the yr, additionally they diminished earlier anticipations. 

    Fed governor remarks in present months additionally suggest some are utterly able to maintain the present money value as prolonged as required. “I really feel you actually should take heed to what the governors are stating, what the chairman is saying, and it looks as if they’re not going anyplace,” Applegate reported.

    Even with inflation even now jogging hotter than a number of predicted, Powell expressed self worth that latest plan could be “sufficiently restrictive” to inevitably strike 2%, pointing to the labor market place tendencies. 

    “Need is even now potent, the necessity side of the labor market in sure, however it may be cooled from its very important diploma of some a very long time in the past, and also you see that in place openings,” Powell talked about. 

    His remarks signify minor risk for a remodel to the two% aim, including physique weight behind his former statements. “There is been a complete lot of converse in posts and responses and ideas: Will they transfer their 2%? Powell pooh-poohed the vibes. I really feel that could be a nonevent,” Bass mentioned. 

    Even although additionally viewing it as not likely, Applegate talked about the doable for a revised think about could presumably not be out of the query lastly, equipped how some value modifications floor to have taken preserve. 

    “I would not be shocked if we felt significantly better at 2.5%, and so they improved that, as a result of I simply by no means know the way you are likely to undo a few of the will improve which are baked into this system, irrespective of whether it is actually gasoline, housing, well being care,” she talked about. 

    The wait-and-see tactic already has a number of housing economists, like researchers at Fannie Mae, anticipating home mortgage costs to remain increased for longer. In its most present financial forecast, the govt-sponsored group claimed it anticipates costs to widespread 6.6% this yr however slipping again to six.1% in 2025.

    The Mortgage mortgage Bankers Association created very comparable strikes. “With our April forecast, we decreased our figures for originations and marked up our expectations for residence finance mortgage charges, and trendy FOMC remaining determination confirms these individuals revised anticipations,” mentioned MBA Main Economist Mike Fratantoni in a push launch. 

    As predicted, the FOMC defined it ready to take care of the runoff fee on mortgage‑backed securities in its portfolio at $35 billion, reinvesting further principal funds into Treasurys. 

    Also as deliberate, rolloff of Treasury-backed securities will lower to $25 billion for each thirty day interval from $60 billion starting in June. “More than time, this adjustment must have some optimistic impression on curiosity premiums with out the Fed needing to change the Fed funds fee,” Marty Eco-friendly, lover at regulation agency Polunsky Beitel Green, mentioned in a assertion.

  • The Fed is talking, but marketplaces still hear what they want to listen to

    Fed Chair Jerome Powell Federal Reserve Chair Jerome Powell has repeatedly mentioned that fascination quantity choices from the Federal Open up Current market Committee, which satisfies Tuesday and Wednesday, are constructed from “meeting to convention” moderately than subsequent a predetermined coaching course. Even so, opinions by Powell and different FOMC customers about their expectations for curiosity prices in the long term have in some circumstances muddied pretty than clarified issues for marketplaces.

    Bloomberg News

    How the Federal Reserve conveys its monetary actions has come to be practically as essential as the rules on their very own.

    With so considerably uncertainty all-around very important monetary developments, some financial institution executives, analysts and economists say the Fed’s communications — these as Fed Chair Jerome Powell’s typical push conferences, a single of which is coming Wednesday — could possibly be endeavor far more harm than glorious.

    “Ahead steering furnished by the Federal Reserve may be helpful, if it is precisely achieved and if they adhere to it,” defined Komal Sri-Kumar, a senior fellow on the Milken Institute and neutral macroeconomic skilled. “It is like I arrive to you soliciting for directions on the road, in the event you give me awful help and ship me the mistaken manner, I’m even worse off with the forward steerage. That, I really feel, is what has transpired with the Fed.”

    Sri-Kumar reported the Fed’s ahead help — equally its official, voted upon protection statements as completely as remarks and forecasts from particular person officers — has been faulty for yrs. He claimed the Federal Open Industry Committee’s view that inflation can be transitory in 2021 skilled ruinous implications for banking corporations that loaded up on lengthy-dated Treasury securities earlier than what turned out to be a function of steep price hikes. 

    He and others anxiousness {that a} comparable reversal might transpire over again. The consensus expectation of economical establishments popping out of the earlier three FOMC’s conferences has been numerous price cuts in 2024. But new feedback from Powell — that it might select “lengthier than anticipated” for the Fed to actually really feel value boosts gradual down sustainably — have solid new uncertainties on folks projections.

    “It is actually difficult to perspective wherever want fees are possible, given what the Fed has mentioned not too way back vs . what the anticipations have been being on the beginning of the quarter,” mentioned Thomas O’Brien, CEO of the $2.4 billion-asset Sterling Bancorp in Southfield, Michigan, on the corporate’s initial-quarter earnings merely name previous week.

    Now, firms are shifting steering or ready round earlier than that includes extra. 

    U.S. Bancorp shaved its total-year money circulate projection in a transfer HSBC analyst Saul Martinez named “disappointing.” Cullen/Frost Bankers declared on its earnings telephone that it was slashing its level-slice expectations from 5 in the middle of the calendar 12 months to simply two within the slide. It additionally reduce its deposit growth projection for the 12 months, as shoppers all through the market ditch non-interest-bearing accounts for locations to park their funds with higher yields.

    John Corbett, CEO of SouthState Corp., defined on the financial institution’s trendy earnings join with that the establishment was aiming for “general flexibility and optionality” amid the monetary uncertainty.

    “We are all attempting to take part in economists and forecast the produce curve,” he mentioned. “We do not need a crystal ball. The solely subject we all know for assured is that every one of our forecasts shall be mistaken.”

    Some say this uncertainty, as not comfy because it could be for bankers, is forward steering doing the job because it should by bracing {the marketplace} for potential changes correctly in progress. Michael Redmond, a U.S. coverage economist for Medley International Advisors, claimed the principal drawback related to ahead steering in newest months has not been the Fed being a lot too rosy in its projections, but alternatively sector people staying specified an inch of optimism and stretching it a mile.

    “There was a present market narrative that bought forward of the Fed,” Redmond said. “Probably the Fed might have achieved much more to extinguish that, but in December, when the Fed was signaling 3 cuts and {the marketplace} wished to price in 6 or much more, the Fed completely was not cheerleading that system.”

    Meeting by meeting, time period by time period

    Through his publish-FOMC press conferences, Powell repeatedly notes that insurance coverage insurance policies are manufactured on a “convention by convention” basis and do not need a predetermined plan path. Instead, he notes, the committee’s choices are affected by probably the most the newest data stories. 

    But, the financial sector parses the FOMC’s communications very fastidiously for notion into how the Fed sees the potential unfolding. And often a single phrase or phrase can, in level, have a ton of body weight.

    In December, Powell was requested concerning the insertion of the phrase “any” proper earlier than the phrase “additional coverage firming” within the FOMC’s protection assertion, which is voted on by the 12 committee associates. These statements are generally crafted to garner highest help and are possible to change tiny from an individual meeting to the up coming.

    “So, we included the phrase ‘any’ as an acknowledgement that we contemplate that we’re more than likely at, or within the neighborhood of, the height value for this cycle,” Powell said in the middle of his press assembly. “Participants didn’t publish down additional hikes that we contemplate are possible, so which is what we wrote down. But members additionally did not want to select the prospect of extra hikes off the desk.”

    Though the Fed’s protection assertion is created by consensus — and usually supported unanimously — it is not the one perception to come up from the committee. Some see important discrepancies involving the assertion, Powell’s push convention remarks and subsequent responses from individual board associates and reserve lender presidents.

    Sri-Kumar claimed the Fed’s consensus-centered methodology to policymaking success in steerage that seems much more resolute than it really is, and may make it exhausting for outsiders to sq. divergent sights among the many distinctive officers. 

    “In the official convention, there are not any dissents, so you’d assume all of them expertise in the identical manner, aside from that after they depart the meeting they all go to the press and say completely different issues which can be various from the way in whi
    ch they voted,” Sri-Kumar claimed. “So the total image is actually baffled.”

    Redmond said inserting out a consensus plan while additionally acknowledging disparate policymaker sights is an drawback with which quite a few central banks can have to contend. 

    “It may be intricate when you have got 19 various policymakers who’ve essentially various weights when it comes to worth for the choice, but you additionally want to make it seem to be it is actually a committee which is coming to a consensus, albeit with some disagreement,” he mentioned. “There is not really a simple manner of speaking all of the nuances that they probably would love they might talk.”

    Dipping dots

    Whilst Powell’s write-up-conference opinions contributed to the widespread watch that the Fed was planning for a slash, the remarks have been not the one interplay from the committee fueling this attitude. There was additionally the quarterly abstract of economic projections.

    Also recognized because the “dot plot” — participant views are mirrored as a dot on a chart of possible outcomes — the December report confirmed 11 of the 19 members anticipated the federal funds value to drop by a minimum of three-quarters of a proportion stage by the shut of this 12 months, equal to 3 quarter-point cuts, with 1 participant anticipating 6 cuts. The March dot plot confirmed 9 members projecting 3 cuts and one explicit calling for 4. 

    Powell normally reiterates that the forecasts belong to the individual contributors — not the FOMC as an entire — and are depending on present-working day data that is subject material to modify. 

    “These projections aren’t a Committee closing determination or technique,” Powell talked about earlier thirty day interval. “If the financial system doesn’t evolve as projected, the route for protection will regulate as applicable to foster our most-work and rate-steadiness plans.”

    Still, even with these caveats, Derek Tang, co-founder of the Washington-centered examine group Financial Plan Analytics, claimed financial market people have a tendency to take SEP projections as one factor akin to gospel.

    “You can discover quite a lot of dependence on the dot plot to specific a baseline situation,” Tang defined. “The Fed has usually defined the dot plot is contingent on the monetary data unfolding in the way in which portrayed by the corresponding macro forecasts, but that portion is ceaselessly dropped within the dialog.”

    Pursuing closing month’s FOMC assembly, most Fed money futures merchants anticipated a minimum of 3 value cuts this 12 months, in accordance to the CME FedWatch Device, which tracks derivatives contracts related to the plan cost. At the time, the mannequin believed a 75% probability that the Fed would slash premiums 3 times or far more. As of April 25, that likelihood skilled fallen down under 12%, whereas the prospect of zero cuts has risen from mainly zero to nearly 20%. 

    Brent Beardall, CEO of Seattle-centered WaFd Bank, talked about the Fed overshares its dot plots and projections that switch marketplaces with out having certainty in these guides. He included that it actually is a “fallacy” that the company can predict the foreseeable future, and setting anticipations could make the financial environment “frothy.”

    “We go too considerably in current day day and age,” Beardall said. “Enable the Fed say, ‘Here’s the data now we have. This is the conclusion now we have proper now. Right listed below are the factors we’re wanting at within the potential, but we you shouldn’t know the place fees are possible to go.’”

    Conversation breakdown

    The plan of ahead help is a comparatively new and repeatedly evolving comply with in simply the Fed. 

    The protection assertion, the abstract of financial initiatives and the article FOMC push conference are all developments of the previous handful of a few years. Formerly, the committee’s coverage variations went unannounced and had to trickle because of the financial system quietly.

    The Fed has adopted its many signifies of interplay to clean the implementation of economic plan. But there has prolonged been a dialogue about no matter whether or not extra dialog leads to a clearer signal or simply extra sounds.

    Former Treasury Secretary Larry Summers claimed the Fed should give you a lot much less usually takes on the financial state of affairs to shield its credibility. Speaking at Semafor’s Washington summit earlier than this month, Summers reported the corporate should get a web page from the guides of longtime former Fed Chairs Paul Volcker and Alan Greenspan on conserving messages precise and ambiguous.

    “The customary lesson of the Delphi Oracles, which is that if all people thinks you occur to be all-powerful and omniscient, but you are actually human, don’t say as effectively an excellent deal,” Summers reported. “And preserve what you say obscure and oracular so as to shield your credibility.”

    John Williams, president of the New York Fed and vice chair of the FOMC, said at the exact same celebration that the Fed presents its projections and information, “to assist, as handiest as we will, for the general public to see how we’re imagining, what is really driving our choices and ideally align the general public’s expectations with what we’re striving to do.” 

    In response to Summers’s responses, Williams added that the information the company makes use of nowadays is “significantly various than the data of the sooner,” offering finer element extra swiftly.

    Tang mentioned the Fed has an obligation to provide recommendation, not solely since of the impression of its plan value, but additionally due to the actual fact of its substantial presence in monetary marketplaces by utilizing its equilibrium sheet, which comprises extra than $7.4 trillion of belongings. He claimed he expects the subject material of interplay to function closely within the central financial institution’s approaching evaluation of its technique to financial plan following 12 months.

    “They determine that medium is info on this article,” Tang claimed. “The manner they talk their forecasts or converse conditions can tie their fingers a minor bit, can impose limitations on the form of steering that they can provide the sector and the way profitable it is.”

    Continue to, though the Fed’s messaging can confound and frustrate market place people, they actually do not be anticipating the company to be clairvoyant. 

    “It is really straightforward to be within the low-cost seats to sit out on this article and see what they’re executing and to criticize,” Beardall talked about. “They have a very, extraordinarily difficult job to do. But if I ended up of their seats, I contemplate it will be helpful if I wasn’t possessing to publicly try to forecast the upcoming.”
  • Fed report: Inflation, plan uncertainty top economic balance problems

    Federal Reserve 033023 The Federal Reserve’s most up-to-date semiannual economical balance report — a survey of financial gurus — found inflation and substantial curiosity costs to be respondents’ main fear. But plan uncertainty — a absence of readability about the way in which of abroad and home coverage — was the No. 2 downside.

    Bloomberg Information

    WASHINGTON — Inflation and uncertainty bordering the course of federal coverage on commerce, investing and different points are banks’ top fiscal safety worries, the Federal Reserve Board claimed in a report launched Friday.

    For its semiannual report on cash balance, the Fed surveyed a assortment of monetary specialists — like broker-sellers, monetary dedication fund supervisors, evaluation and advisory specialists as completely as lecturers — concerning the top rated problems experiencing the economic method. Policy uncertainty emerged as a giant new useful resource of panic for enterprise specialists — it was cited by 60% of respondents, up from the simply 24% of respondents who cited it as a main downside within the Fed’s earlier survey in October 2023.

    Due to the actual fact 2019, the Fed has issued two opinions on monetary balance per yr, usually releasing an individual within the spring and one other within the drop.

    Persistent inflation and enormous want charges remained the very best challenge all through the board, with 72% of respondents itemizing it as their main downside — the same share as within the October report. The report indicated that curiosity prices may proceed being elevated over current market place expectations for an extended time period and that persistent inflation may immediate a further stringent financial coverage, leading to improved volatility in cash markets and changes in asset valuations. 

    But the rise of plan uncertainty — along with unpredictability stemming from fluctuating commerce insurance coverage insurance policies, influenced by geopolitical tensions this sort of because the battle within the Center East and Russia’s conflict in opposition to Ukraine that has lasted much more than two a number of years — was an unpredicted useful resource of market disruption for a number of survey respondents. Respondents additionally flagged the approaching U.S. elections in November as a useful resource of strain.

    “Further escalation of geopolitical tensions or plan uncertainty may reduce economic exercise, enhance inflation, and heighten volatility in economic marketplaces,” the report defined. “The worldwide fiscal process may suffer from a pullback from danger-using, declines in asset charges, and losses for uncovered U.S. and abroad enterprises and merchants.”

    Considerations concerning the credit standing top high quality {of professional} critical property — which was the No. 2 fear cited within the Oct report — was cited as a serious challenge amid 56% of the survey’s respondents. But that fell from 72% within the October report. The Fed identified that prices all through all sectors of CRE continued to lower within the 2nd half of 2023, and the report will make apparent the entire impression of CRE price drops have however to be mirrored within the data.

    “These transaction-based largely promoting value actions most likely don’t however fully replicate the deterioration in CRE business value ranges as a result of, pretty than recognizing losses, fairly a number of entrepreneurs maintain out for lots extra favorable circumstances to position their homes on the business,” noticed the report. “Capitalization charges on the time of belongings spend money on, which consider the yearly money movement {of professional} properties relative to their charges, moved modestly greater however remained at historically low ranges, suggesting that prices stay important relative to fundamentals.”

    Banking sector instability continued to characteristic prominently no matter the report noting massive quantities of liquidity and really low funding dangers within the sector because the Oct report.

    Although the Fed’s disaster lending facility, the Bank Expression Funding Application, ceased operations on March 11, the report identified the BTFP continues to reduce liquidity pressures for depositories. The report defined usually small establishments with beneath $10 billion of property — symbolizing 95% of beneficiaries — benefited from the strategy.