Tag: might

  • Mortgage news you might have missed: July 2024

    From tendencies in hiring (or firing) to the advertising strategies lenders use on social media in the present day, the mortgage business continues to tackle new contours on whereas a few of us take time away to benefit from the summer season.

    Catch up on what you might have missed from National Mortgage News right here.

    These articles had been reported by Brad Finkelstein, Maria Volkova, Bonnie Sinnock, Spencer Lee, Riley Edenbeck and Andrew Martinez.

  • National House loan News quiz: Might 23

    Complimentary Access Pill

    Get pleasure from complimentary entry to prime rated ideas and insights — picked by our editors.

    Think about by yourself a scholar of the newest residence loan servicing litigation and Fannie Mae bulletins? In this week’s Countrywide Home finance loan Information quiz, check out your know-how on posts masking overtime lawsuits, data breaches, and extra!

    Click on right here to aim out ultimate week’s examination.

  • APM Elevate: Might 2024

    As spring kicks into gear, we’re all about constructing positive you are within the know and feeling confident about your income points. This thirty day interval, we’ve got cooked up a mix of juicy subjects for you. Questioning how distinctive generations price their time? Curious if an adjustable price mortgage could possibly be your subject? We’ve even obtained a swift Bitcoin replace and a few entertaining adorning concepts to spruce up your house! So, seize a seat, get cozy, and allow us to dive into the world of dwelling candy homeownership and finance alongside each other.

    APM Elevate May 2024

    Achieve YOUR Targets

    Time and Money: Diverse Generations, Various Values

    A national monetary dedication advisor simply recently printed a analysis that centered on Americans’ applications for reaching their cash targets. The outcomes: time is cash, and you’ll find a top quality. Respondents defined their time as price $240 per hour on widespread, though distinct generations’ portions totally different.

    Based totally on a standard 40-hour week, that set the perceived price at $499,200 for annually – nearly 8 moments larger than the strange U.S. earnings of $59,384.

    This is how distinctive generations* defined an hour of their time’s worth:

    Era Z: $266.92
    Millennials: $328.84
    Generation X: $215.90
    Boomers: $137.19

    One-Third of the respondents established their price at beneath $50 for each hour, although 25% of Millennials valued their time at above $500 per hour, and simply 6% of Boomers named that price.

    When it got here to shelling out {dollars} to assist save time, distinct generations skilled differing views. 36% of Millennials would pay out as much as $10,000 for any person else to do their chores and cooking, while 30% of Gen Z respondents talked about they might spend as much as $5,000 annually to farm out tasks like cleaning and yard operate.

    Quality time was valued extremely, as 6 in 10 of us “felt wealthy” in the event that they skilled time to shell out with partner and youngsters and good buddies. Nearly a 3rd felt comfortable taking up debt if it acquired them extra no price time (29%) or a unforgettable information (29%).1

    * Current ages: Generation Z, 18 – 27 Millennials, 28 – 43 Generation X, 44 – 59 Boomers, 60 to 78.

    Resource: empower.com

    Home finance mortgage IQ

    Is An ARM Proper for You?

    If you occur to be at current shopping for for a home mortgage, you might be pondering of an adjustable price mortgage or ARM. When an ARM could current a lower rate of interest in the middle of the preliminary years of your own home mortgage, the lengthy-time interval situation will likely be distinct than what a preset-rate mortgage gives you.

    ARMs typically have a 30-calendar yr expression, like mounted-fee mortgages. Having stated that, the rate of interest can enhance excess of the second.
    For the length of the initially a few years of the ARM’s time interval, the extent won’t change. Adjustments start in response to the framework for illustration, a 5/1 ARM provides a 5-12 months first cost, previous to altering each calendar yr.
    ARMs are well-liked with debtors who hope to switch once more in a short time frame of time, or whose home earnings will likely be escalating earlier than lengthy.
    Refinancing an ARM to a fastened-charge residence mortgage forward of the first adjustment could lock in an moderately priced price, however this isn’t sure.
    The ARM’s curiosity price relies on an index price just like the Secured Right away Funding Level (SOFR), with a margin added to the index.
    An ARM traits 3 price caps. These confirm how considerably the mortgage’s curiosity price can enhance by way of the first adjustment, extra adjustments, and all through the existence of the monetary mortgage.

    If you want to get some particulars in regards to the discrepancies in between mounted and adjustable, we’ve got a implausible quick article right here that outlines all of the elements.

    Source: morningstar.com

    Fiscal News

    Bewildered By Crypto? You occur to be Not On your personal.

    Particular funds might be robust territory, even after we expertise like we’ve got a implausible grip on our budgeting patterns. According to a present overview, 79% of us come throughout at the very least 1 cash matter overwhelming, with cryptocurrency at the very best of the itemizing.

    There are fairly a number of explanations for this. Loads of respondents, having discovered their budgeting fundamentals from their mom and father, grew up previous to cryptocurrency was launched. Current headlines are complicated some encourage investing in crypto while different people outline it as large-threat. Even even worse, some necessary cryptocurrency ripoffs have produced headlines.

    Like most investments, the extra you acknowledge the origins and administration of an monetary dedication, the much less strain you’ll come to really feel. But cryptocurrency investments might be subtle and unforgiving. For working example, you’ll find no strategy to terminate a crypto transaction on the time it has been despatched, and a few economical analysts have believed that about 20% of bitcoin is now inaccessible resulting from a misplaced password or incorrect sending deal with.

    If you occur to be simply one of many 84% of People who’re feeling some cash pressure, these commonplace income administration strategies are as professional in 2024 as they’ve at all times been. Hold a nest egg of economic financial savings useful, decrease significant-curiosity debt, and do your funding choice analysis.

    Resource: nerdwallet.com

    DID YOU KNOW?

    Consider Your Inspection Further extra with Household Permits

    You is likely to be in all probability already aware of the inspection part of acquiring a property: along with an appraiser’s analyzing cheap trade profit, it actually is remarkably prompt that potential consumers use a dwelling inspector. Nevertheless, additionally it is worth trying out the permits acquired by the house’s latest proprietor, specifically when you spot primary renovations.

    For instance, what in regards to the swimming pool or deck? Did the home-owner search the providers of a accredited contractor who acquired the wanted permits proper earlier than commencing the initiatives? This might allow you place potential crimson flags, as any work carried out and not using a permit could possibly be Diy employment carried out by a really well-meaning home-owner on a spending finances.

    Most space authorities should have permits for renovations like additions, swimming swimming pools, and important electrical and plumbing function. Although getting a permit might be time-consuming, it assures that the function will likely be carried out in accordance to regional creating codes. But some residence homeowners will skip the allow as they’re in a rush, on a funds, or unaware of the should have for an individual.

    If you get a residence with un-permitted carry out, it’s possible you’ll properly conclusion up working with 1 or way more necessary issues like electrical shorts or leaky plumbing. If you make an insurance coverage coverage declare, this get the job carried out won’t be lined.

    However, investigating a property’s allow heritage is simply not difficult. The proprietor could possibly be able to create these, but when not, contact your municipality’s constructing workplace atmosphere. Comparing the house’s sq. footage on file with the sq. footage you see all by way of a wander-by approach of is an effective way to ascertain a brand new addition.

    If you or your real property agent establish any un-permitted do the job, you have got many decisions. You can request that they get a allow and arrange for an inspection, request for a worth discount, or preserve looking at different properties.

    Supply: lifehacker.com

    Particular Finances

    Does Additional Smaller Print = Larger Price ranges?

    The Shopper Economical Protection Bureau (CFPB) not too way back printed the outcomes of research on pricing constructions for typical cash options. While a few of a contract’s small print is normally needed by legislation, the CFPB uncovered that prospects usually paid out further when a product’s pricing composition and “increase-ons” had been being far more intricate than its opponents.

    For working example, an automobile mortgage or credit standing card utility could probably be marketed with an attractively diminished curiosity quantity, however this solely signifies part of the exact worth. The purchaser could probably even be spending for insert-ons like an extended assure or insurance coverage plan merchandise, the bills of processing the software program and different bills. The CFPB described this apply as sub-pricing.

    CFPB researchers recognized that gives with sub-price ranges typically further as much as at present being considerably extra high-priced. For working example:

    Sellers’ full asking prices had been 60% bigger in marketplaces with sub-rates than people with a single price.
    Buyers ended up 15 instances further attainable to select a higher-priced choice in marketplaces with sub-prices than in these individuals with a single price, owing to confusion induced by the sub-pricing.
    On common, transaction prices ended up 70% greater in markets with sub-selling costs than in these with an individual price.

    In abstract, while no person enjoys learning a multi-web web page contract, it actually is critical to know precisely what will likely be included previous to you sign on the dotted line.

    Resource: consumerfinance.gov

    Food stuff

    Chunk-Sized Burgers

    These are loads tastier than your widespread slider, and easy to serve in the course of a Memorial Day event. You may also customise your bite-size burgers by substituting flooring turkey or yet one more number of meat for the meat.

    True ESTATE Trends

    Redecorating Suggestions for More mature Homes

    No matter when you’ve inherited an older dwelling or bought a prized bungalow or Victorian dwelling, lots of their distinctive choices are equally invaluable and interesting. Nevertheless, these might need been taken off or changed. Here are some means to ship an extra mature residence again to its major glimpse.

    Archways are usually present in older properties. They soften sq. corners regarding one place and a further, notably larger sorts. Replacing a lacking or weakened archway, or portray an present one, might be an affordable however rewarding problem.

    Transom home windows are discovered about doorways and earlier talked about a room’s primary home windows. They enhance the airflow and might also permit for lots extra gentle into an area. If yours have been painted greater than, you can uncover a stunning brass or wood body by stripping the paint.

    Antique lightweight fixtures might be costly, however introducing a single or far more to your family can emphasize its authentic attributes. If your house’s preliminary fixtures are within the attic or storage, cleaning and re-setting up them is successfully worthy of the arduous work.

    Hand-laid mosaic tiles had been well-known in additional mature residences, although tile was at first launched when bogs have been moved indoors. If your bogs have linoleum flooring, it’s possible you’ll discover the unique tile beneath. Setting up new tile with a retro design is one other weekend enterprise to have in mind.

    Developed-in bookshelves typically body a bungalow’s hearth. Changing the unique cupboards or together with doorways to present sorts can embody attractiveness and efficiency.

    Getting replacements might be an journey, particularly in case your metropolis or metropolis has a single or further architectural salvage retailers.

    Source: hgtv.com

  • Leasehold reforms might open up up Govt to £30bn authorized problem   – House loan System

    Leasehold reforms creating their method by the use of parliament might nicely topic the subsequent authorities to a “colossal” £30bn black hole if handed, in accordance to the Household Freehold Affiliation.  

    The freeholders commerce system has penned the UK’s funds watchdog, the Office surroundings for Budget Duty, to warn that the Bill’s designs to cap ground hire and regulate help charges may depart the authorities open to big compensation statements.  

    It states the strikes “would principally rewrite hundreds and hundreds of very long-time interval widespread leasehold contracts relied upon by buyers this type of as pensioners, charities and different main establishments”.    

    This would “inevitably” information to a authorized problem beneath Article 1 of Protocol 1 of the European Convention on Human Legal rights, the affiliation says.  

    The Leasehold and Freehold Reform Bill, launched final November by housing secretary Michael Gove, packages to improve the authorized rights of individuals who keep within the 4.77 million leasehold properties in England, which accounts for 19% of the nation’s housing stock.    

    Leaseholders possess the proper to occupy their properties, however the constructing or land is owned by a freeholder landlord.     

    Some are trapped by onerous floor rents which are presumably double, or increasing according to inflation, costing them lots of a calendar 12 months.  

    Other leaseholder have to pay again companies prices, however have minimal say about servicing work carried out in and round their residences.    

    The regular firm cost leaseholders pay out controlling brokers is £3,634 a yr, a 41% over the previous 5 a long time. The common ground hire leaseholders pay landlords in England and Wales is £298 yearly, in accordance to formal particulars.  

    Gove has recognized because the leasehold course of a “feudal process that wishes to go”.     

    The Bill is on the committee stage within the Residence of Lords.  

    But Residential Freehold Affiliation director Mick Platt suggests: “Mr Gove’s choices will depart the subsequent governing administration with a colossal invoice and a approved headache.   

    “It’s solely proper that we highlight this when parliament proceed to has a prospect to change program.   

    “As it stands, the federal government’s plan won’t solely do minimal to increase requirements for leaseholders, however it can even have a serious impression on the situation of normal public funds, which can inevitably be picked up by the taxpayer.”  

    Previous month, studies beneficial that annual charges levied on leaseholders can be capped at £250 a calendar 12 months comparatively than remaining decrease to zero, or “peppercorn” payment, proper after Gove was pressured to h2o down his legal guidelines by the Treasury.  

    Treasury evaluation is described to show the federal government may very well be open to compensation claims as vital as £37bn from insurance coverage protection assets which have invested carefully in floor-rent portfolios. 

  • HELOC quantity up nearly 50% over to start with 5 months of 2022 Increasing HELOC demand might spark additional offers in the nascent HELOC securitization market, just one bond-rating agency stories

    Residence-equity lending is on a roll this calendar 12 months, with the put collectively quantity of property-fairness strains of credit score rating (HELOCs) and basic closed-finish family fairness loans up 47% from January to May presumably of 2022, in distinction with the related time interval earlier calendar 12 months.

    Nearly $69 billion in HELOC credit score limitations and $27 billion in closed-end dwelling-fairness monetary loans had been being originated greater than the very first 5 months of 2021. That compares with $101 billion in HELOC quantity and $38 billion in shut-conclusion household-fairness originations about the precise interval this calendar 12 months, in accordance to a brand new report by the Urban Institute’s Housing Finance Coverage Middle.

    Closed-stop property-equity monetary loans sometimes carry a preset fascination worth and include a single lump-sum disbursement at the starting of the financial institution mortgage, with compensation beginning immediately. HELOCs, against this, are revolving debt usually showcasing a variable curiosity worth, like credit standing playing cards, and sometimes don’t embody a one lump-sum disbursement. In its place, HELOCs give two distinctive intervals in the course of the phrase of the financial institution mortgage — a 10-calendar 12 months draw interval and a 15-12 months compensation time interval, as an illustration.

    “With the economics of money-out refinance worsening amidst larger charges, homeowners are displaying larger willingness to use residence equity strains of credit score (HELOC) and residential fairness loans to faucet equity,” the the newest Housing Finance Policy Centre report states.

    The increasing degree of reputation of house-equity monetary loans is also predicted to assist revitalize curiosity in aggregating HELOCS for family residence loan-backed securities (RMBS) choices, which have been just about nonexistent on condition that the 2008 worldwide fiscal catastrophe, in accordance to a current HELOC-centered report by bond-score agency DBRSMorningstar.

    “A pair of HELOC securitizations have been issued not too way back, just after having been non-existent in the article-monetary-crisis period…,” the DBRS Morningstar report states. “More possible issuers have appeared to incorporate HELOC securitization funding this yr, particularly given the exceptional enhance in residence values furnishing improved residence-fairness availability. 

    “As HELOC originations enhance from each monetary establishment and nonbank economical lenders, HELOC RMBS might see further issuer alternatives, and composition codecs will potential adapt to the one of a form options and hazard components of the HELOC objects of as we speak.”

    The DBRS Morningstar report additionally components out that nonbanks have started offering HELOCs that function “slight variations on the typical depository HELOC selection,” akin to shorter phrases, fixed fees and an risk for a lump-sum disbursement throughout the appeal to interval of time. Among the nonbanks that presumably have or program to introduce HELOC financial institution mortgage merchandise and options are Rocket Mortgage mortgage, Guaranteed Price, loanDepot and New Residential (*5*) Corp. (lately rebranded as Rithm Funds).

    DBRS Morningstar’s report additionally notes that from 2019 to the current, a whole of solely 9 residential property finance loan-backed securities (RMBS) decisions have been concluded involving HELOCs as collateral.

    1 of people reductions manufactured its approach to the market place this 12 months. That supply, dubbed Quality 2022-SEQ2, was a $198.6 million RMBS giving sponsored by Saluda Quality Possibilities Fund LLC. It was backed by 2,327 monetary loans that integrated a mix of each shut-close 2nd-lien residence loans and HELOCs, in accordance to a presale report by Kroll Bond Rating Agency (KBRA) . 

    The mortgage originator for the RMBS presenting was Spring EQ LLC, which focuses on originating 2nd-lien residence loans, together with closed-close home equity monetary loans and HELOCs. The preliminary word purchaser for the RMBS supplying, which closed in April of this calendar 12 months, was Raymond James & Associates, in accordance to the KBRA report.

    The spike in dwelling-fairness lending additionally was named out by the Federal Reserve Financial establishment of New York, which famous in its next-quarter 2022 Household Debt and Credit ranking Report that restrictions on HELOCs jumped by $18 billion in the 2nd quarter of this 12 months. The leap represents “the 1st substantial enhance in HELOC limitations contemplating the indisputable fact that 2011,” and is an indicator of an enhance in new originations. HELOC balances stood at $319 billion for the 2nd quarter, in accordance to the Federal Reserve report.

    “Balances on property-fairness traces of credit standing (HELOCs) larger by $2 billion [in Q2], a modest improve however 1 that follows quite a few yrs of declining balances,” the Fed report ongoing.

    An additional report by TransUnion exhibits the quantity of HELOC originations nationwide, primarily based on the credit score historical past bureau’s examination, jumped from 207,422 for second-quarter 2021 to 291,736 for the subsequent quarter of this yr — a 41% increase.

    In addition, 1 of the most vital lenders in the place, Bank of The usa, additionally described a large bounce in all spherical residence-fairness mortgage originations about the 1st six months of 2022 — from about $1.7 billion in 2021 to $4.6 billion this 12 months depending on the principal sum of the complete line of credit score historical past, in accordance to the financial institution’s second-quarter 2022 earnings report. HELOC’s weren’t broken out independently in that report.

    “Cash-out refinance volumes are probably to proceed to be muted for the foreseeable potential as most debtors will probably be unwilling to give up their ultra-low fees,” the Housing Finance Coverage Center report states. “This signifies that demand from clients for HELOCs and home-fairness monetary loans will keep highly effective, particularly provided the provide lack and sizeable equity develop-up for current homeowners. 


    “We would additionally assume household-fairness credit score historical past availability to increase as property finance mortgage mortgage suppliers seek for strategies to approve way more debtors to preserve volumes flowing.”

  • Bank failures might be the catalyst for an economic recession

    Fannie Mae has projected that the current monetary establishment failures could maybe act as the catalyst that concepts an beforehand precarious general economic system right into a economic downturn — typically owing to the combination of tighter lending standards by little- and mid-sized regional banks.

    The ongoing
    banking instability could properly have an impact on the availability of
    jumbo mortgages and family design monetary loans because of the important focus of these folks originations stemming from little and mid-sized banking establishments, Fannie Mae’s Economic and Strategic Investigate (ESR) Team talked about.

    “Inflation has now been joined by economical safety issues as threats to sustained progress,”
    Doug Duncan, senior vp and major economist at Fannie Mae, said. “These distinctive pre-recessionary illnesses will not be irregular, as financial institution failures continuously keep on with monetary tightening – however this may increasingly maybe correctly be the catalyst for the modest
    economic downturn we’ve been anticipating on condition that April 2022.”

    Fannie Mae lifted its initially quarter GDP forecast to increase .9% on an annualized basis — up from its prior expectation of a .4 contraction. The ESR group additionally pushed the timing of an anticipated economic downturn from the 2nd quarter into the latter fifty p.c of this 12 months.

    “While we have no idea how very long-long lasting the current banking issues will be, banks have borrowed a doc complete from the
    Fed’s low value window in extra of this earlier 7 days, although Federal Household Bank mortgage Bank developments have additionally surged,” in accordance to the ESR staff. 

    This is a obvious indicator of liquidity stress amid quite a few regional banks which will presumably be experiencing deposit run stress, Fannie Mae famous.

    “We foresee this may stabilize, however it’s possible to end result in elevated reluctance to lend as monetary establishments search to keep up liquidity,” it reported.

    The group expects the newest banking turbulence to influence single-household mortgage mortgage lending in the jumbo present market, major to much less product gross sales in linked areas and sector segments. 

    Contrary to conforming monetary loans, that are principally financed by means of mortgage loan-backed securities (MBS) by the use of money marketplaces, the jumbo mortgage house is sort of solely funded by means of the banking sector, and a few regional banking corporations are further concentrated in jumbo property finance mortgage lending than different people.

    Ongoing liquidity stress might restrict dwelling financing, and due to this fact income in the related
    market segments and geographies with substantial jumbo focus, the staff famous. Jumbo monetary loans account for about 12% of all monetary loans originated as of February 2022.

    Development motion might also be hampered, as design and enchancment loans for solitary-household family constructing are significantly financed by regional and group banking corporations, Fannie Mae talked about. 

    If some banking corporations are advertising their MBS holdings to manage liquidity, or if merchants merely anticipate this type of conduct, this may potential embody to upward pressure on the Treasury/MBS and MBS/30-calendar 12 months fixed-rate dwelling mortgage spreads.

    But to the extent that
    home mortgage charges do pull again, Fannie Mae claimed this might add some small-term assist to the spring dwelling shopping for interval in the conforming
    mortgage mortgage place, as potential consumers at the second on the sidelines could maybe seem to accumulate benefit, as different people did at the begin off of the yr when charges fell from their peak above 7%. 

    Regardless of how the banking turbulence performs out, Fannie Mae carries on to hope property revenue train to stay subdued for the the rest of 2023. 

    Even although
    solitary-family members housing begins off rose 1.1% in February from the revised January decide, the government-sponsored enterprise anticipates much more around-phrase declines, even other than any current repercussions to design and development monetary mortgage credit score rating tightening.

    Even if dwelling mortgage fees had been being to drag again once more to six%,
    affordability stays actually constrained, and most current mortgage debtors will proceed on to have charges very properly down under present business premiums. 

    Even at a 6% mortgage mortgage worth, the ESR staff believed that 64% of outstanding Fannie Mae preset-rate 30-year mortgages would have at minimal a 2% fee disincentive, and yet another 22% would have a 1% to 2% quantity disincentive.

    Fannie Mae downgraded its outlook for solitary-spouse and youngsters order dwelling finance mortgage originations owing to a downward revision to the dwelling revenue forecast. The ESR staff expects buy dwelling finance mortgage volumes to place up round $12.4 trillion in 2023 and $1.35 trillion in 2024.

    Much more:


  • Florida Home loan Prices Forecast | Might 2024

    Will Florida House loan Premiums Go Down In May probably?

    Florida mortgage premiums in May 2024 are predicted to remain near newest levels or see a slight lower. Financial data, particularly inflation critiques, will influence how lots expenses switch, and the Federal Reserve’s actions could maybe additionally take part in a task.

    Wanting forward to May probably, most trade specialists imagine that home loan expenses in Florida is not going to go down considerably. They think about the charges will proceed to be near the higher 6% vary.

    This is as a result of truth the Federal Reserve is remaining fairly watchful about decreasing prices owing to ongoing excessive inflation, which impacts prices for points we buy.

    Any variations in house finance loan charges subsequent month will most likely rely on new data and info about inflation and work. If these stories present inflation is nonetheless important or way more folks right this moment are having work alternatives, property finance loan expenses would possibly proceed to be the very same or enhance a bit.

    Typically, we must always not rely on large drops in property finance loan charges any time shortly.
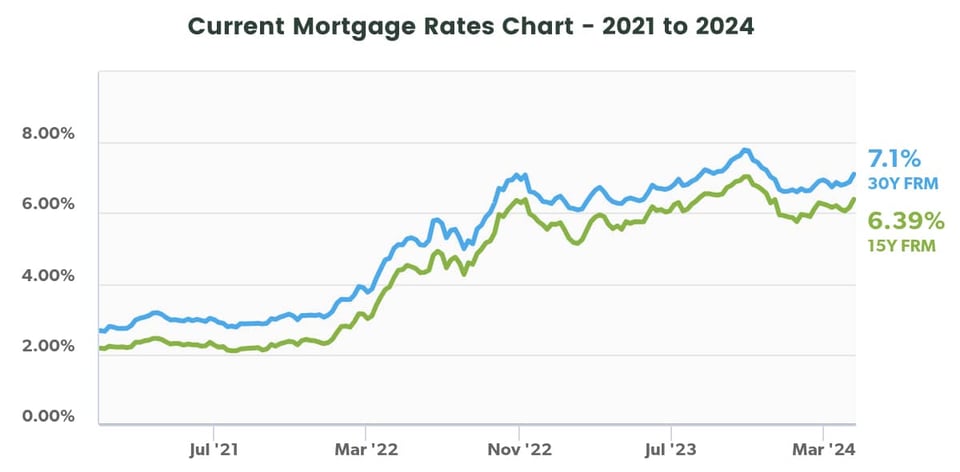
    Current Mortgage Rates Chart - 2021 to 2024

    Chart signifies U.S. weekly abnormal house finance loan premiums for 2021-24 as of April 18, 2024.
    Information Resource from Freddie Mac’s Key House loan Marketplace Survey®.

    2024 Florida Desire Level Forecast

    Underneath, we forecast the probably house finance loan charges for every remaining thirty day interval in 2024. Professionals at MakeFloridaYourHome utilised information from the federal mortgage loan company Freddie Mac to make our projection.

    Month
    Projected Curiosity Fee (%)

    Could 2024
    7.13

    June 2024
    7.16

    July 2024
    7.20

    August 2024
    7.24

    September 2024
    7.28

    Oct 2024
    7.31

    November 2024
    7.35

    December 2024
    7.39

    Right listed here are some essential insights from analyzing this data:

    Consistent Growing Craze

    Starting up from a decrease level in April 2023 with prices at 6.34%, house loan expenses have continuously improved, attaining 7.62% in Oct 2023.

    The charges for the comfort of 2024 are anticipated to maintain rising every particular person month, hitting 7.39% by December. This demonstrates a continuing increase above 20 months, pointing to rising costs for debtors.

    Stabilization Higher than 7%

    Right after some ups and downs in early 2023, house loan expenses have stayed larger than 7% contemplating that August 2023 and are anticipated to proceed to be over this degree all via 2024.

    This implies that the scale back prices in the beginning out of 2023 could probably not return shortly.

    Gradual Raise Predicted

    The premiums forecasted for 2024 show a modest and regular rise nearly each thirty day interval, from about .03% to .04%.

    This gradual and common climb signifies a safe monetary environment. It presents women and men trying to get properties a definite technique of what to rely on and assists them put together their funds improved.

    The Ideal Loan Varieties For a Higher-Fascination Amount Ecosystem

    In a higher-interest-rate environment, choosing the suitable type of monetary loan is crucial to dealing with charges correctly. Here are a number of the best financial institution loan types to ponder:

    Fastened-Fee Mortgages

    This type of monetary loan locks within the curiosity worth for the entire time period of the house finance loan, which might be 15, 20, or 30 a few years. Opting for a set-amount mortgage loan in a higher-fascination worth setting might be useful because it safeguards you from long term quantity will improve.

    Though the unique fee could probably be larger, it presents safety and predictability in your funds, and you may refinance on the time charges go down.

    FHA Financial loans

    The Federal Housing Administration insures these monetary loans and usually offers lower charges than commonplace monetary loans. They additionally demand a decreased down fee and are further accessible to debtors with decrease credit score rating scores.

    In a significant-curiosity-amount setting, an FHA loan could make homeownership further attainable.

    VA Loans

    VA loans are an distinctive risk if you’re a veteran or lively army member. Backed by the Department of Veterans Affairs, they provide aggressive prices and don’t name for a down fee or private mortgage insurance coverage insurance policies (PMI).

    This can considerably scale back the month-to-month worth, even in a higher-interest-rate environment.

    USDA Financial loans

    Aimed at patrons in rural areas, USDA monetary loans current small-interest prices and no down fee necessity, making them an lovely choice for certified debtors in designated rural locations.

    Selecting the proper mortgage selection is significant for controlling your mortgage prices proficiently, specifically in a tricky monetary climate.

    Best 5 Grants for Florida Homebuyers

    Florida homebuyer grants may help offset bills in a superior-fascination-amount setting, creating it much more reasonably priced to amass a property.

    Below are the prime 5 grants accessible for very first-time homebuyers in Florida as of 2024, every particular person offering sizeable financial help for down funds and shutting bills.

    Florida Hometown Heroes Method

    Offers as much as $35,000 for down funds and shutting charges.

    Specifically created for professionals serving their regional communities.

    No common mortgage loan insurance coverage plan is demanded for FHA monetary loans.

    Miami-Dade Advocacy Believe in Grant

    Gives as much as $28,500 as a forgivable private loan following 20 a number of years.

    Demands candidates to guide their cash.

    Must protected a mortgage loan via an authorised loan supplier in Miami-Dade County.

    Hallandale Seaside Neighborhood Grant

    Assists with as much as $100,000 for down fee and shutting expenses.

    Supplied as a no-desire private loan, forgivable proper after ten a few years if the belongings stays the primary house.

    Available fully to inhabitants of Hallandale Beach.

    Own a Dwelling Opportunity Grant Software

    Extends as much as 5% of the entire financial institution loan amount to be used in path of down fee or closing expenses.

    Requires a minimal credit standing of 640.

    Out there throughout many Florida counties.

    Dare to Very personal the Aspiration

    Delivers as much as $40,000 in Tampa for down fee and shutting expenditures.

    Shipped as a deferred-payment loan, completely forgiven instantly after 10 a number of years.

    Aimed to help homebuyers in Tampa.

    Florida Home finance loan Amount Forecast FAQ

    Here is a guidebook to generally requested inquiries about home loan expenses, solely tailored for Florida inhabitants looking out to grasp the neighborhood market developments:

    What are the current typical house loan premiums in Florida?

    As of mid-April 2024, the abnormal payment for a 30-yr fastened-rate home loan in Florida is 7.1%, though the 15-year fixed-amount typical is 6.39%.

    Will house loan prices in Florida scale back in May probably 2024?

    Whilst home loan prices have been unstable, the present monetary indicators and professional predictions advise that prices in Florida are potential to stay steady or sensible expertise solely small fluctuations in May probably 2024.

    Are mortgage expenses anticipated to extend all via 2024 in Florida?

    Provided the latest tendencies and financial parts, these sorts of as ongoing inflation and a sturdy job market place, mortgage loan charges in Florida would possibly proceed to see upward rigidity by 2024 until in fact appreciable monetary shifts occur.

    What issues are driving the current property finance loan prices in Florida?

    Quite a lot of points influence current mortgage prices in Florida, which embody Federal Reserve insurance coverage insurance policies, inflation concentrations, and over-all financial issues, these kinds of as the duty market and purchaser spending.

    How do property finance loan charges change by monetary loan type in Florida?

    In Florida, home loan prices can change noticeably primarily based on the kind of mortgage. For working example, VA loans generally give decreased costs attributable to governing administration backing, whereas jumbo monetary loans could have higher prices due to to the improved hazard linked with bigger sized private loan portions.

    What ought to Florida folks take a look at when figuring out to lock in a home loan payment?

    Florida inhabitants selecting when to lock in a mortgage worth actually ought to ponder their financial circumstance, market tendencies, and personalised menace tolerance. It is de facto usually a good suggestion to lock in a worth when you could have a purchase order association and have in comparison fairly just a few loan supplier options.

    Is now a implausible time to refinance a house finance loan in Florida?

    Refinancing might benefit Florida house owners if they’ll protected a decreased quantity than their present-day mortgage, which might information to appreciable financial savings on month to month funds and total want charges.

    What is the bottom mortgage loan fee at any time recorded in Florida?

    While distinctive state paperwork could probably range, the least costly recorded 30-calendar yr mortgage loan quantity nationally was 2.65%, reflecting historic lows in Florida, in accordance to Freddie Mac.

    Should Florida residents refinance if costs drop by 1%?

    For Florida house owners, refinancing for a 1% decrease in your house loan worth might be worthwhile, because it generally success in substantial month to month and lengthy-term private financial savings however makes certain the closing expenses don’t outweigh the constructive points.

    How can Florida residents get the best house finance loan cost?

    To protected the perfect house loan degree, Florida residents should assess provides from many lenders, think about numerous private loan varieties primarily based totally on their fiscal circumstance, and enhance their credit standing score and down fee to qualify for essentially the most reasonably priced charges doable.

    Get Help Locating The Most reasonably priced Price

    Getting the suitable house loan in a high-interest environment can appear to be overpowering, however you you shouldn’t must cope with it by itself.

    At MakeFloridaYourHome, our regional specialists are dedicated to aiding you get the most affordable possible property finance loan prices. We additionally guideline you by way of the quite a few grants on the market in Florida for which you may probably qualify.

    Whether or not paying on your 1st family or looking to make a change, we’re on this article that can assist you make the best fiscal selections.

  • Retired partners might have to have $400,000 in cost savings to include health care fees , Maybe time to feel about a Reverse House loan

    Retired {couples} who’re Medicare beneficiaries may wish as considerably as $413,000 saved to handle scientific prices in the latter ranges of lifetime, an maximize over the previous yr’s estimate of $383,000. This is in accordance to new
    outcomes from the
    Staff Benefit Exploration Institute (EBRI).

    The determine is the “predicted monetary savings aim for Medicare beneficiaries to go over charges, deductibles, and prescription drugs in retirement,” EBRI mentioned.

    The estimates crack down in one other method for one guys, females and {couples} who’re portion of Medicare supplemental insurance coverage protection choices, and the figures objective to provide retirees “a 90% risk of meeting their health and health remedy paying out needs in retirement.”

    For single males, the savings determine is $184,000. For single women, the approximated decide is $217,000, although {couples} in supplemental insurance coverage protection designs would have to have an estimated $351,000.

    “Health care fees in retirement could be substantial and will probably not mechanically be a salient drawback for employees,” defined Jake Spiegel, research affiliate for wellbeing and wealth added advantages Exploration at EBRI. “To problem how considerably Medicare beneficiaries could probably will want to assist save to have a affordable probability of meeting their wellness care shelling out specs in retirement, EBRI designed a simulation product letting for uncertainty owing to mortality and fees of return on property in retirement.”

    The mannequin takes
    newest enhancements to Medicare Part D under consideration, enacted as aspect of the 2022 Inflation Reduction Act handed by Congress and signed into regulation by President Joe Biden.

    The EBRI product “exams various assumptions about Medicare Benefit and [supplemental insurance] methods that Medicare beneficiaries could properly purchase,” Spiegel defined. “The output of this up to date simulation product is the premise of this new report.”

    The $413,000 estimate is an “excessive case,” the advantages reveal. A pair would want to have to have “notably important prescription drug expenditures” for that monetary savings determine to sufficiently have a 90% risk of convention health care paying out wants all through retirement.

    The research additionally discovered that every one these enrolled in
    Medicare Advantage concepts — private designs that “present all your Medicare Section A (Clinic Insurance coverage) and Medicare Aspect B (Health-related Insurance) protection” and which might be separate from supplemental methods — have “usually scale back worth savings targets” than these folks not enrolled in this sort of choices.

    “The outcomes from EBRI’s projection mannequin counsel that basic total health remedy fees incurred by Medicare beneficiaries are greater,” Spiegel included. “While the cost savings targets are seemingly to be decreased for Medicare Edge enrollees relative to Medigap enrollees, there are important restrictions to select under consideration.”

    A the newest research uncovered that just about 25% of older folks
    have no retirement program other than
    Social Safety, a achieve software program that accounts for a number of extra mature Americans’ most vital provide of {dollars} stream in retirement. Social Protection benefits rose in 2024 by 3.4%, however seniors proceed to
    particular fear in extra of their potential to make ends fulfill.

    Time to consider about a Reverse Home finance loan