Tag: metro

  • Metro Bank launches into limited company BTL with rates from 3.99% – Mortgage Strategy

    Metro Bank has at this time launched its first Limited Company Buy-to-Let product as a part of its continued deal with changing into a number one specialist lender.

    The financial institution’s new merchandise provide a most LTV of 75% with present rates beginning at 3.99%.

    The mortgage curiosity quantity is calculated on the identical fee of 125% as for the lender’s customary purchase to let stress rates.

    To qualify the company have to be non-trading and limited to solely holding residential property and never engaged in wider actions, i.e. it have to be an SPV.

    Up to 4 administrators and shareholders are accepted and no minimal revenue is required. However no less than one director have to be incomes an revenue aside from rental.

    The most age permissible for an applicant is 85.

    Metro Bank director of mortgage distribution Charles Morley says: “Launching a Limited Company Buy-to-Let product has been on our agenda for a while and we’re actually excited for it to go reside at this time as we proceed our journey to changing into the primary specialist lender on the excessive road.

    “Owning a property portfolio inside a Limited Company moderately than as a person can carry an a variety of benefits. While Limited Company Buy-to-Let is already an established market, we see the potential for it to develop even additional.”

  • Metro Lender full Q1 lending dips 4% to £11.8bn – Property finance loan Finance Gazette

    Metro Bank posted to begin with-quarter full lending down 4% to £11.8bn from the previous three months, because it pivots within the path of knowledgeable dwelling loans and compact firm loans.

    Metro-Bank-wall-620x330.jpg

    The lender says it proceeds to “strategically reposition its equilibrium sheet in the direction of higher yielding specialist mortgages and SME/industrial lending,” in a investing replace.

    It offers that full lending is 9% scale back than a 12 months again.

    The firm encompasses a differ of small enterprise and particular person accounts, monetary loans, credit score enjoying playing cards and insurance coverage coverage.

    Even so, the lender will launch into restricted get-to-enable dwelling loans within the second quarter, and is drawing up applications to enter the shared possession present market within the second fifty % of the yr.

    Metro Bank major govt Daniel Frumkin defined: “Lending motion quantities are consistent with expectations and the pivot to bigger margin industrial and residential lending progresses, with lending balances reflecting the time lag amongst committing facilities and subsequent drawdown.

    “During the time period we additionally taken care of our emphasis on individuals today-folks banking and romantic relationship-based principally knowledgeable providers, with extra development throughout non-public and group latest accounts.

    Frumkin included: “Based on effectiveness within the very first quarter we keep assured that financial outcomes will proceed to strengthen all by means of 2024 as we optimise funding, ship on price ticket reductions, proceed on our asset rotation and achieve from lessen-yielding mounted-level treasury and home loan maturities.”

    Very final month the monetary establishment reiterated it might decrease 1,000 jobs, proceed on with its £80m price-chopping plan and shut seven-day division opening within the wake of its autumn rescue provide.

    In Oct, the loan firm sealed a £925m rescue deal that observed Columbian billionaire Jaime Gilinski Bacal simply take a 53% stake within the enterprise.

  • Metro Bank whole lending falls 4% to £11.8bn in Q1 – Mortgage loan Approach

    Metro Financial establishment posted initially-quarter full lending down 4% to £11.8bn from the sooner 3 months, because it pivots in course of specialist residence loans and tiny enterprise loans.

    The loan firm says it carries on to “strategically reposition its stability sheet in the course of larger yielding specialist residence loans and SME/business lending,” in a buying and selling replace.

    It supplies that complete lending is 9% reduce than a 12 months in the past.

    The small enterprise provides a range of enterprise enterprise and particular person accounts, loans, credit score historical past taking part in playing cards and protection.

    Even so, the monetary establishment will begin into restricted purchase-to-enable mortgages in the 2nd quarter, and is drawing up concepts to enter the shared possession sector in the subsequent fifty p.c of the 12 months.

    Metro Financial establishment chief authorities Daniel Frumkin talked about: “Lending exercise ranges are in line with expectations and the pivot to elevated margin business and family lending progresses, with lending balances reflecting the time lag amongst committing services and subsequent drawdown.

    “During the interval we additionally preserved our deal with individuals-people right this moment banking and partnership-based suppliers, with extra progress throughout private and enterprise current accounts.

    Frumkin further: “Based on effectiveness in the primary quarter we keep assured that financial outcomes will go on to enhance in the course of 2024 as we optimise funding, provide on price financial savings, proceed on our asset rotation and profit from lower-yielding fixed-charge treasury and property finance loan maturities.”

    Previous thirty day interval the financial institution reiterated it will reduce 1,000 work alternatives, stick with its £80m value-reducing plan and cease seven-working day division opening in the wake of its autumn rescue deal.

    In October, the loan supplier sealed a £925m rescue package deal that observed Columbian billionaire Jaime Gilinski Bacal simply take a 53% stake in the small enterprise.

  • Australia’s hardest metro rental market place unveiled

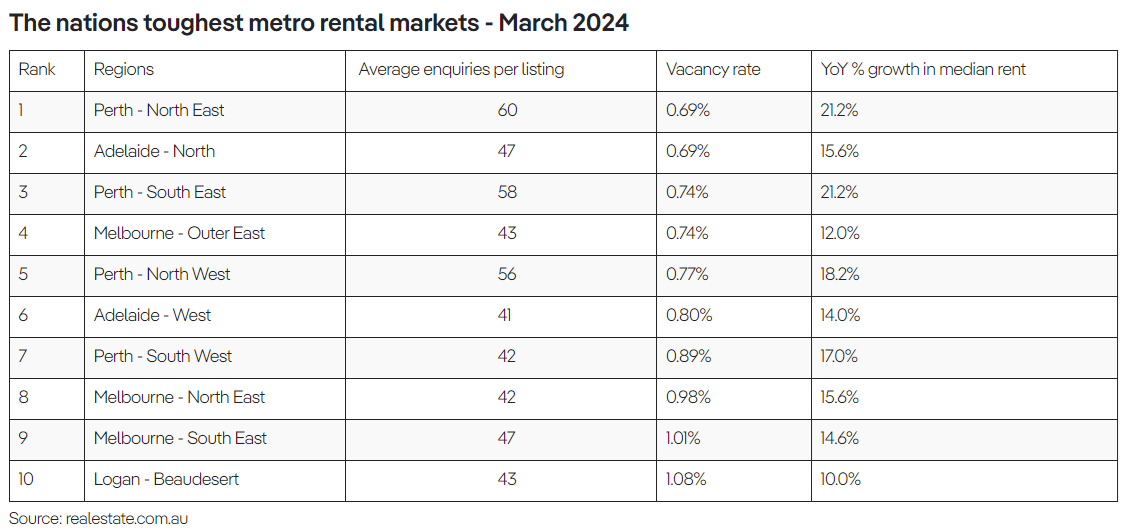
    Other components in Perth, such because the South East, North West, and South West, encounter associated challenges with important enquiry charges and minimal emptiness costs, major to rising rental charges.

    Read extra: Perth housing provide ‘in dire straits’

    In Adelaide’s North, the state of affairs can be dire, with the placement buying an regular of 47 enquiries for each itemizing in March, exacerbating the housing lack.

    Meanwhile, Canberra has observed considerably so much much less demand from prospects, with solely 12 enquiries per itemizing in March. Similarly, locations some of these as Hobart and prosperous areas of Sydney, which embrace the Northern Shorelines and Baulkham Hills and Hawkesbury, report lower enquiry charges, bigger vacancy premiums, and common rental price ticket progress.

  • Australia’s toughest metro rental current market disclosed

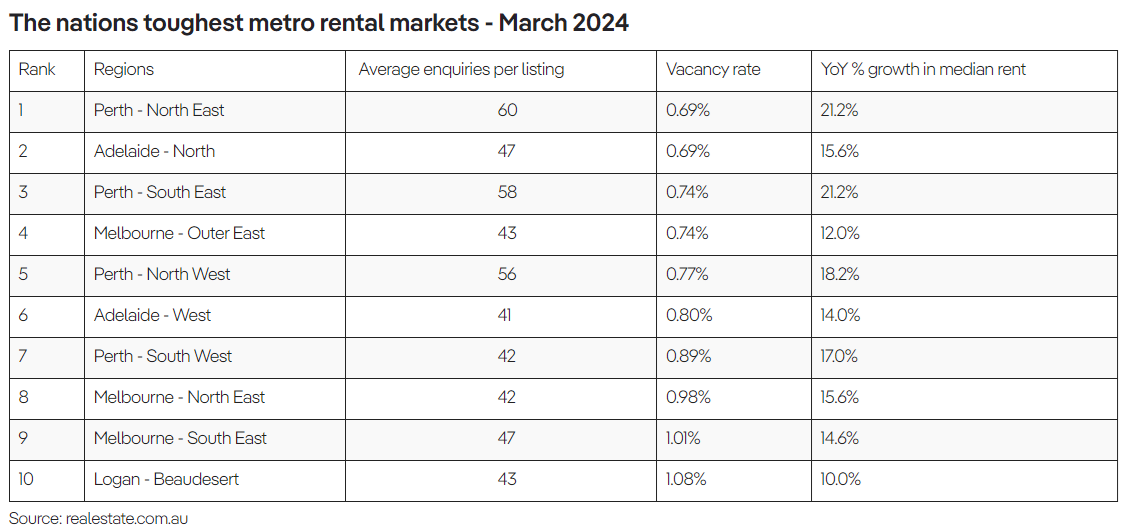
    Other locations in Perth, together with the South East, North West, and South West, facial space similar challenges with excessive enquiry premiums and lowered emptiness costs, main to elevating rental bills.

    Read much more: Perth housing supply ‘in dire straits’

    In Adelaide’s North, the state of affairs can also be dire, with the area buying an abnormal of 47 enquiries for every itemizing in March, exacerbating the housing shortage.

    Meanwhile, Canberra has witnessed considerably significantly much less need, with solely 12 enquiries for each itemizing in March. Likewise, places these as Hobart and prosperous items of Sydney, which embody the Northern Shorelines and Baulkham Hills and Hawkesbury, report lower enquiry prices, elevated vacancy premiums, and common rental value development.