Tag: may

  • Hurricane Beryl’s damage to Texas homes may total as much as $1.5 billion

    Hurricane Beryl’s landfall in Texas may end in property damage totaling a whole bunch of hundreds of thousands of {dollars}, a preliminary estimate exhibits.

    Total insured wind and storm surge losses in Texas shall be between $700 million and $1.5 billion, in accordance to CoreLogic.

    CoreLogic estimates there are between 1,500 to 3,500 homes close to Bay City, Texas in danger to storm surge flooding and a further 3,500 to 7,500 homes in danger to storm surge flooding in Brazoria County. This threat stems from the shallow topography beneath the Gulf’s water, which has resulted in lots of Texans elevating their homes to mitigate any potential flood damage, the report added.

    Close to two million Texans are with out electrical energy.

    Beryl's Houston Blackout Likely To Last Days As Heat Returns A fallen tree on high of the Holy Cross Early Learning Center after Hurricane Beryl in Houston, Texas, US, on Wednesday, July 10, 2024. Houston remains to be strangled by the chaotic aftermath of Hurricane Beryl, which struck the nation’s fourth-largest metropolis on Monday as a Category 1 hurricane. Photographer: Mark Felix/Bloomberg

    Mark Felix/Bloomberg

    Insured-property associated losses may’ve been considerably worse if the Category 1 hurricane had made landfall in a extra densely populated Texas metropolis like Galveston or Corpus Christi in contrast to Matagorda Bay, the report posits. 

    By taking one other path, the hurricane’s robust winds impacted fewer properties leading to a extra “manageable insured loss total,” wrote Jon Schneyer, director of disaster response at CoreLogic, in a publish revealed July 9.

    Schneyer factors to Hurricanes Idalia in 2023 and Ian in 2022 as examples that showcase why the trajectory of a hurricane issues.

    “Idalia, regardless of being a serious hurricane at landfall, crossed the Florida shoreline within the Big Bend area, a much much less densely populated a part of Florida. On the opposite hand, Hurricane Ian made landfall in southwest Florida over Cayo Costa close to Fort Meyers. Ian was a stronger hurricane, however the distinction within the estimated business insured losses was massive,” continued Schneyer. “Hurricane Ian brought on tens of billions of {dollars} in insured losses, whereas Idalia brought on only a couple billion, if even. Landfall location issues.”

    Hurricane Beryl caught many spectators off guard due to how briskly it strengthened right into a Category 5 hurricane in between its three landfalls, due to exceptionally heat water.

    More erratic climate circumstances, introduced on by local weather change, will probably end in a rise in occasions such as hurricanes, tornadoes and wildfires. 

    For now, it’s unsure how insurers, housing businesses and mortgage servicers will take care of a future that features extra frequent local weather occasions. Housing businesses just like the Department of Veterans Affairs, the Department of Housing and Urban Development and the Federal Housing Finance Agency say they’re taking steps to prioritize the problem.

  • Second charge lending rises 22% in year to May – Mortgage Finance Gazette

    The worth of second charge lending in May was 22% larger than the identical month final year reaching £142m, figures from the Finance & Leasing Association reveal.

    second-charge-mortgage-620x330.jpg

    The determine equates to the best month for brand new enterprise by worth since October 2022.

    The whole variety of new second charge loans was additionally 16% larger than in May 2023, at 2,957, it discovered.

    There was a complete of 32,183 second charge offers accomplished in the 12 months to May, value £1,490m.

    However, trying on the 12 months to May 2024 in contrast to the earlier 12 months, lending was down by 1% by variety of agreements and worth of loans.

    Finance and Leasing Association director of client and mortgage finance and inclusion Fiona Hoyle says: “May noticed the second charge mortgage market report its highest stage of recent enterprise by worth since October 2022. The market has reported a sustained interval of progress main to new enterprise progress of 20% by worth and 14% by quantity in the primary 5 months of 2024.

    “The distribution of recent enterprise by function of mortgage in May 2024 confirmed that the proportion of recent agreements which had been for the consolidation of present loans was 59.8%; for residence enhancements and the consolidation of present loans was 23.7%; and for residence enhancements solely was 11.5%.

    “As at all times, prospects who’re involved about assembly funds ought to communicate to their lender as quickly as attainable to discover a resolution.”

  • Typical 5-yr fix falls beneath 5% for first time considering that May presumably: Rightmove – Mortgage Method

    This 7 days, the traditional 5-calendar 12 months mounted mortgage cost has dipped beneath 5% for the first time considering the actual fact that the beginning of May.

    This is in response to Rightmove’s weekly mortgage mortgage tracker which reveals:

    The frequent five-year preset home mortgage quantity is now 4.99%, down from 5.68 % a calendar 12 months again.

    The common two-yr preset mortgage quantity is now 5.37%, down from 6.17% a calendar 12 months up to now

    The regular 85% LTV 5-calendar 12 months set dwelling mortgage price is now 4.99%, down from 5.68% a 12 months in the past.

    Whilst the frequent 60% LTV 5-yr fixed mortgage mortgage quantity is now 4.39%, down from 5.42% a 12 months in the past

    The common month-to-month home mortgage fee on a initially-time buyer type property which is now £227,757, for anybody getting out an common 5-yr mounted, 85% LTV property finance mortgage, is now £1,131 per thirty day interval if repaying over 25 years, in distinction with £1,203 for every month a calendar 12 months in the past (when the abnormal initially-time buyer residence asking price ticket was £226,412).

  • Getting to certainly: Reported Basel retooling may — or may not — have legs

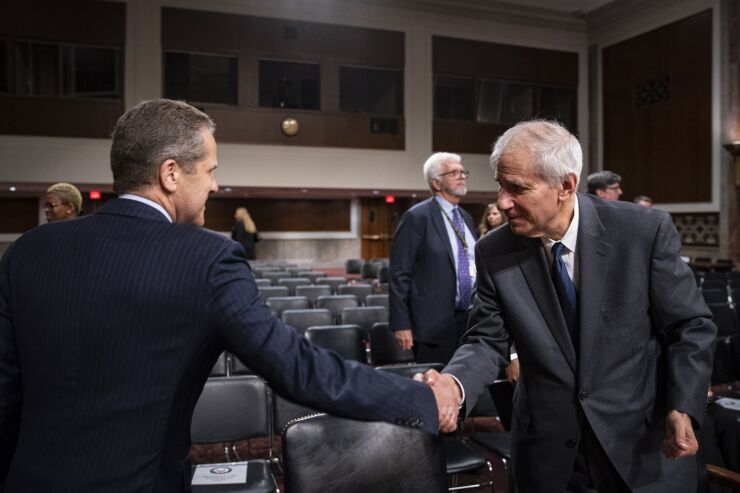
    Barr Gruenberg Michael Barr, vice chair for supervision on the Federal Reserve, remaining, shakes palms with Martin Gruenberg, chair of the Federal Deposit Insurance insurance policies Corp., adhering to a Senate Banking Committee listening to previous Might. Regulators are reportedly poised to supply a retooled Basel III endgame rule that noticeably scales again a number of the way more controversial points of earlier July’s proposed rule, however regardless of whether or not all these variations are ample to quell banks’ opposition is unclear.

    Bloomberg News

    WASHINGTON — Whilst it actually is obvious lender regulators put together to make substantive enhancements to a financial institution capital overhaul demanding institutions to put up much more unborrowed cash to lend to customers, banking business consultants differ on how this might probably be completed, and whether or not even a revised proposal will likely be sufficient to preclude lawful difficulties from the banking enterprise.

    The Basel proposal was hotly contested when it was first proposed remaining July on quite a lot of grounds, along with the leading-line money enhance for the foremost monetary establishments, the prospect weight remedy of mortgages, clear electrical energy property and compact enterprise loans. Bloomberg reported final 7 days that regulators are searching a draft set of revisions to the proposal aimed toward quelling these issues.

    Lawyer Gregory Lyons of Debevoise and Plimpton mentioned he is not actually assured of the timeline simply however, supplied regulators nonetheless present up to be hashing objects out internally.

    “I think about yow will discover distinctive proposals circling about how to amend it, however in truth, I’m not assured they know,” said Lyons. “We are fairly shut to what’s probably on and I simply do think about yow will discover a complete lot of inside — superior faith — however inside debates about how that is all going to have interaction in out.”

    Corporate legal professional Chen Xu, additionally with Debevoise, says he thinks the heads of the companies involved within the rulemaking — which is a joint effort and exhausting work involving the Federal Reserve, the Office of the Comptroller of the Forex and the Federal Deposit Insurance insurance policies Corp. — would really like to strike a compromise with their funds skeptic colleagues, a few of that are in the very same firm. 

    “Some of the corporate principals hope in the event that they make ample concessions, they’ll get it through by August so this is not going to get tied up with the election,” he claimed. “We’ve been listening to that try is attaining traction, however we have additionally learn that there are a amount of parents contained in the companies who would considerably have a reproposal, and splendid now it’s difficult to see who’s successful.”

    But whether or not these modifications will be included right into a remaining proposal or ought to be included in a brand new proposal — or some mixture of the 2 — stays unclear. Below the Administrative Method Act, variations produced to remaining guidelines want to be a “affordable outgrowth” of what was within the genuine proposed rule. Lots of in and throughout the banking sector argue that the enhancements required for the Basel III endgame proposal exceed this typical, and for that motive an absolutely new rule want to be put by its private observe and comment time period.

    Jaret Seiberg, cash protection analyst at TD Cowen says he expects regulators will on the very least partially withdraw and re-propose the rule — steadily dubbed Basel III endgame — supplied statements from a single of essentially the most influential avid gamers shaping the pending regulation: Federal Reserve chair Jerome Powell.

    “Powell has effectively designed this motivation to Congress,” commented Seiberg. “It does not signify there’s zero probability for the rule to be finalized, however a re-proposal appears to be like most likely.” 

    Regulators invited banking corporations to present particulars about how they’d suffer from the proposal in January. Seiberg claims the outcomes of the analysis — which he predicts should come this summer season — ought to supply additional readability about regardless of whether or not or how swiftly a re-proposal might happen.

    Whilst the Fed is essentially the most politically unbiased of the fiscal regulators, it’s experiencing drive from each equally the financial subject — which wants a re-proposed rule — when some Democrats and shopper advocates need the rule accomplished primarily as is. A brand new proposal would considerably enhance the timeline for finalization. Banking protection professional Ian Katz of Capital Alpha Partners states the Fed might devise a method to allow public comment on specific rule revisions with out restarting the system.

    “The Fed may maybe place out one thing that in essence looks like a reproposal however is known as a factor else and can enable most of the people to comment with out the necessity of establishing the process from scratch,” said Katz. “If the Fed have been to do this within the tumble — forward of the elections — it might finalize the Basel endgame rule subsequent calendar yr, perhaps within the 1st 50 p.c.”

    Banking corporations and their commerce crew reps have been vocal of their opposition to the Basel proposal and have availed themselves of novel methods in elevating the issue with voters and lawmakers. From launching selling campaigns on Sunday night soccer to determining procedural weaknesses they might downside in court docket, the sector has produced it obvious that it’s going to oppose the rule on as fairly a number of fronts as possible. Financial establishment commerce crew the Lender Coverage Institute, whose associates would all be impacted by the rule, has retained company litigator Eugene Scalia — son of former Supreme Court docket Justice Antonin Scalia — to recommend a probable approved impediment to the rule.

    Though the corporate trio has nevertheless to formally announce deliberate revisions to the rule, market allies inside the regulatory state have begun to current cowl for the kinds of variations monetary establishments are demanding.

    Fed Governor Michelle Bowman — who has beforehand known as for the rule to be reproposed —  Wednesday floated a amount of modifications she thinks are required to garner vast consensus among the many Fed’s deliberative system, the Board of Governors. She argues the rule does minimal to cope with the basic causes of essentially the most newest U.S. monetary establishment failures in March 2023.

    “I take into account we tackled the challenges that we confronted in the course of the earlier than monetary catastrophe by the implementation of Dodd Frank, I assume individuals have confirmed to be thriving,” she reported. “What led to SVB failing was not the similar subject that led to the real property disaster once more then, earlier than, a ten years prior to now.”

    Powell has often pressured the need for this consensus. Bowman termed for the companies’ to pare again once more what she known as redundancies within the funds framework — between the brand new business and operational probability wants within the rule and the strain cash buffer which she claims burdens banks with redundant costs. She additionally known as to recalibrate the present market threat issue of the rule to mitigate substantial will enhance in threat-weighted property, and deal with non-curiosity and price-dependent income extra pretty to encourage earnings diversification. She produced very clear as soon as once more this 7 days she believes any rule that may proceed — enable by yourself method finalization — would require broad changes and enter from fascinated get-togethers within the business and typical basic public. 

    “​​While these actions can be a acceptable commencing place, they’re not a substitute for a knowledge-driven evaluation and an intensive assessment of the evaluations submitted,” she talked about throughout a fireplace chat adhering to her remarks. “This would end result in a superior proposal that options alterations to cope with not solely these points, but in addition a number of different points raised by most of the people.”

    Lyons says two of the important thing issues banking establishments have decided with the rule are the scope of banks — primarily these individuals with in extra of $100 billion in property — roped into the rule’s remit, as very nicely because the business and operational threat parts flagged by Bowman, which he suggests is simply one of many very important issues for giant banking establishments.

    “I feel there are issues of relevance every to the extra substantial banks, specified the operational and present market threat issues,” he claimed. “And to the smaller sized monetary establishments, within the $100 billion asset class, pertaining to how a lot of this may apply to them.”

    Irrespective of what route regulators simply take, the banking market and its allies have questioned the require for money reforms within the to begin with place, supplied their see that firms are effectively-capitalized. But pretty than battle tooth-and-nail to cease any new money requirements, some assume they may probably settle for a slimmed-down version of the proposal in buy to accomplish regulatory certainty.

    “We assume monetary establishments would select to acknowledge a smart final rule than to enhance this combat for what might be yet one more 5 yrs,” Seiberg remarked. “The timing for finalizing the rule is correct after the inauguration. It is why there’s election hazard, nevertheless we take into account the majority of the final rule is probably going to have bipartisan help on the Federal Reserve.”

    Given ongoing talks on the organizations about how to proceed, the business will more than likely be eyeing its allies on the within of, who can assist kind the rule to their liking. Bowman’s opinions on Wednesday recommend the enterprise might get their method in numerous regards. 

    “As Chair Powell has defined, that he expects broad and supplies enhance to this proposal, and I’d hope {that a} vary of the factors that I have decided in a collection of speeches all around the final 12 months or because the proposal was launched can be built-in in a few of individuals changes,” she defined. “If the proposal is [put] forward, it has to be voted on by the board and the opposite regulatory organizations — so we’re going to simply have to see what takes place.”

    Lyons talked about a Supreme Courtroom conclusion Friday upending the Chevron doctrine — which usually mentioned judges ought to actually defer to company judgment on rulemakings — will increase the stress on regulators to make certain their closing rule is something banking corporations can reside with. With the repeal of Chevron, regulators now have to persuade courts of the deserves of non-public restrictions.

    “[Chevron] raises the dilemma of how considerably the courts have to defer to the businesses in rulemakings and so forth,” he talked about. “I think about it heightens the stakes — or hazards, based mostly in your place of watch — banking organizations or their commerce teams may maybe press once more in court docket docket from pointers they perceive to be problematic.”

    Kyle Campbell contributed to this posting.

  • Sizeable payment raise for individuals remortgaging in May maybe: LMS – Property finance loan System

    The LMS Every month Remortgage Snapshot for Might exhibits a £342.03 common common payment improve for individuals who remortgaged for the length of the thirty day interval.

    The report additionally reveals that 45% of debtors larger their financial institution loan dimension 48% of these individuals who remortgaged took out a 2-12 months set quantity merchandise, the most typical services or products greater than the interval.

    Some 26% talked about their main purpose when remortgaging was to lower their common month-to-month funds, making it essentially the most most popular response.

    Adjust in monetary loan sizing claimed by debtors reveals that 45% improved their general mortgage sizing

    34% noticed no alter in their full private loan dimension, whereas 21% lowered their full financial institution loan measurement

    The common monetary loan maximize publish remortgage was £20,869 and the common monetary loan decrease put up remortgage was £12,727

    The LMS snapshot documented that 70% amplified their each month remortgage repayments

    9% noticed no change in their each month remortgage repayments, although 21% minimized their each month remortgage funds

    The common month-to-month reimbursement improve was £342.03 the standard month to month reimbursement reduce was £339.44

    With regards to regional traits, the standard remortgage financial institution loan complete in London was £375,612, though the frequent for the relief of the United kingdom stood at £171,223 producing remortgage private loan portions 119% elevated in London than in the remainder of the place.

    The longest prior mortgage length was situated in London at 72.20 months (6.02 a number of years), though the shortest was in the North East at 57.89 months (4.82 a few years), constructing the longest prior mortgage phrase 24.7% extra time than the shortest.

    LMS chief govt Nick Chadbourne commented: “The remortgage market follows the traditional patterns, identical to Gareth Southgate’s methods at a key event. There is however a considerable quantity of merchandise transfers as lenders function to raise retention in a minimal-margin ecosystem, and the summer season has a fall in merchandise maturities, which suggests the remortgage sector will probably be fairly very low till faculties reopen.”

    He included: “The Prime Minister stunned us all with the dedication to have an election in July, though the Lender of England saved premiums the same on the commencing of June, citing a single metric as the reason, however I consider everyone knows it’s because of the truth of the election. So, the solar is shining, the soccer is on, little ones are about to finish college, and ERCs are decreased – all indications reveal a silent few months in the remortgage world.”

  • Land Registry applications up 6.6% in May well   – House loan Approach

    HM Land Registry completed further than 1.95 million apps in May maybe, up 6.6% on a calendar yr again.  

    Apps to enhance or query paperwork are up .3% on the earlier thirty day interval, the governing administration division offers.  

    The South East topped the desk of regional functions with 439,855, adopted by Higher London on 368,215 and the North West with 219,041.  

    Highlights of the physique’s Might output embrace issues like:  

    309,498 ended up applications for sign-up updates in comparability with 299,195 in April  

    1,125,121 have been apps for an formal duplicate of a register in comparability with 1,128,292 in April  

    190,360 have been search for and hold queries (formal lookups) as opposed with 186,959 in April  

    82,109 have been transactions for price in distinction with 83,904 in April  

    17,795 have been being postal functions from non-account holders in contrast with 20,425 in April  

    The part stresses that its knowledge shows what “it has been capable of course of throughout the time interval protected and isn’t essentially a mirrored image of present market exercise”. 

  • Business self-confidence falls in May

    Business enterprise self worth falls in Could | Australian Broker News

    Information

    Enterprise confidence falls in May maybe

    Roy Morgan tales blended sentiments amid companies

    Business confidence falls in May

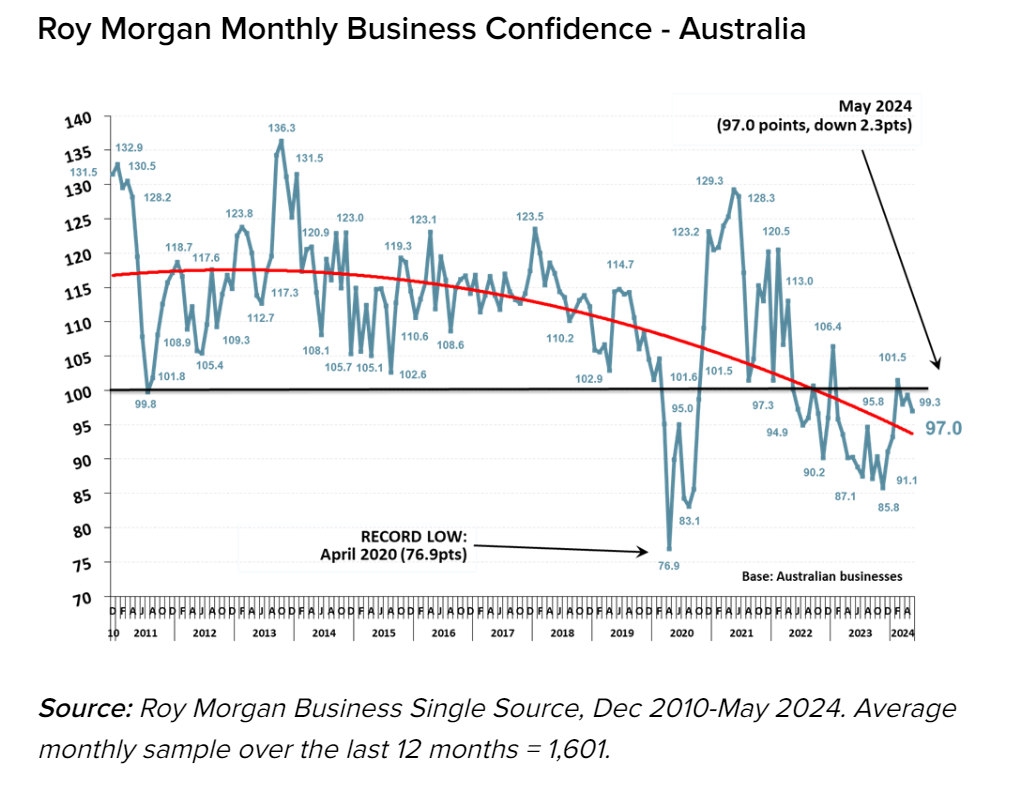
    In May maybe, group self-confidence decreased by 2.3 particulars, in accordance to Roy Morgan, bringing the index to 97, simply beneath the impartial stage of 100.

    This lower follows an underwhelming federal price range, which has nonetheless left corporations a lot much less optimistic concerning the speedy future.

    Combined sentiments among the many enterprises

    The examine uncovered mixed success, with companies demonstrating much less self esteem in the next 12 months and their expense potential prospects. Nonetheless, there was a slight development in the extended-time interval outlook for the Australian financial local weather in extra of the next 5 a long time.

    A noteworthy 42.6% of organizations now suppose the following 12 months is a “dangerous time to commit in increasing the group,” up 6.1 particulars from April. Only 38% give it some thought a “good time to commit,” probably the most inexpensive in in extra of 4 yrs.

    Regardless of brief-phrase issues, 32.4% of companies anticipate “good instances” for the Australian financial local weather across the upcoming 5 years, a 3.1-point enhance from a doc low in April. Meanwhile, 55.2% anticipate “dangerous cases,” down 5.3 elements.

    Regional variations in small enterprise self-assurance

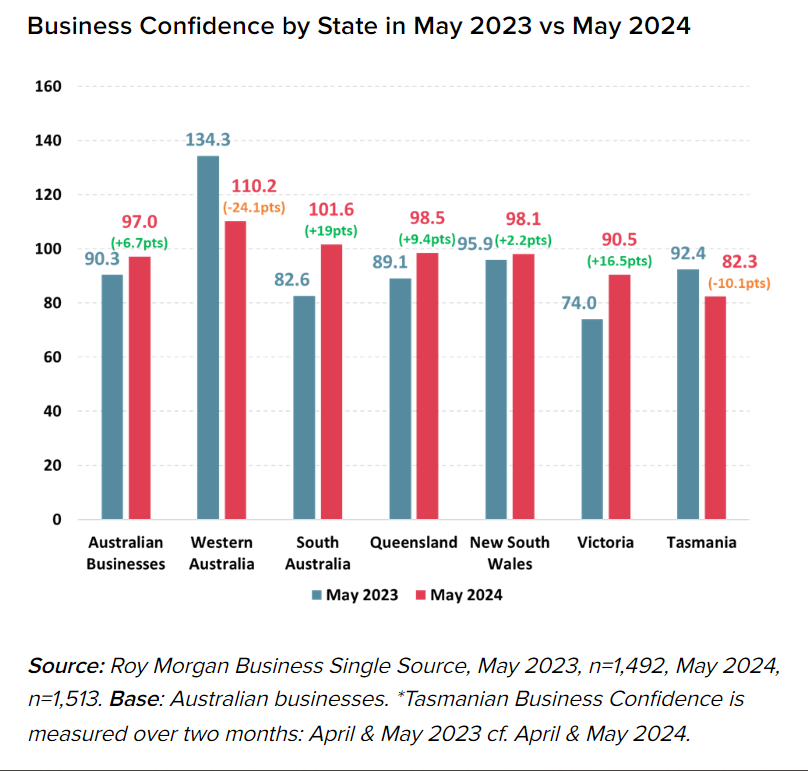
    Organization self-assurance differs appreciably throughout Australian states.

    Western Australia stays probably the most self-confident at 110.2, inspite of a essential drop from final yr. South Australia seen the foremost yearly elevate, rising 19 elements to 101.6. Victoria and Queensland additionally confirmed sizeable features, whereas they proceed to be beneath the impartial stage.

    Field general efficiency

    Several industries carry on being optimistic, with skilled, scientific, and technical professional companies high at 113.8, adopted by schooling and studying and educating at 113, and finance and insurance coverage plan at 110.9.

    Even so, transportation, postal, and warehousing continues to lag at 74, encountering probably the most vital drop of any discipline.

    Insights from Roy Morgan

    “The outcomes current that organizations ended up not amazed with Treasurer Jim Chalmers’ federal spending plan, and there was no elevate to self-confidence,” talked about Michele Levine (pictured beforehand talked about), CEO of Roy Morgan. “This actually shouldn’t be a shock as a seem at historic traits reveals small enterprise self-confidence has now declined in 9 out of 14 a very long time in May effectively following the federal price range.”

    She reported a very powerful issue on the rear of the drop in May effectively was companies’ outlook for the next yr.

    “Only 38% of companies say the next 12 months will likely be a “good time to speculate in rising the group,” the most cost effective decide for this indicator on condition that April 2020,” Levine acknowledged. “In distinction, 42.6% say the up coming 12 months will likely be a ‘dangerous time to dedicate.’”

    Get the most effective and freshest residence finance mortgage information delivered correct into your inbox. Subscribe now to our FREE day-to-day e-newsletter.

    Connected Stories

    Continue to maintain up with the latest information and gatherings

    Join our mailing guidelines, it’s no price!

  • Why waiting to obtain a household may not be very best

    &#13
    &#13

    The dream of homeownership is deeply embedded in fairly a few individuals’s aspirations. But, with reworking sector circumstances, some potential consumers may properly ponder waiting. Though distinctive situations should usually guideline your conclusions, listed below are good the explanation why delaying may probably not be in your very best curiosity:

    The unpredictable nature of curiosity costs

    Present-day fascination costs may be moderately greater than the file lows of newest many years, making some doable consumers cautious. But let’s embrace some viewpoint: predicting potential want charges is a in shut proximity to-extremely exhausting exercise. Waiting for an ‘best’ cost can be akin to playing. If you would possibly be apprehensive about present costs, it actually is worth noting that current day charges, within the grand sweep of home mortgage background, proceed to be significantly lower than a lot of highs we have now discovered.

    And this is wherever Evergreen House Financial loans strategies in with a {powerful} incentive. By selecting to buy now, you’ll be able to revenue from our Buyer Booster Plan*, accessible until September twenty ninth, 2023. This distinctive methodology delivers you with a $2,500 mortgage firm credit score rating for a long term refinance. Even although you’re leveraging aggressive rates of interest at present, you would possibly be additionally surroundings by your self up for potential monetary financial savings sooner or later—a {powerful} objective to act now.

    The worth of making fairness now

    Every dwelling finance mortgage fee you make builds equity in a tangible asset. By delaying a residence purchase, you would possibly be lacking out on this prosperity-constructing likelihood. This is particularly important when pondering of the appreciation of dwelling values in a number of areas.

    The hid prices of leasing

    Leasing may properly really feel charge-powerful brief-expression, however greater than the a number of years, it may be a numerous story. Hire funds create your landlord’s prosperity, not yours. With rents usually escalating, often surpassing inflation prices, you may properly find yourself spending significantly extra with out having any return in your expenditure.

    The intangible advantages of homeownership

    Outside of funds, homeownership presents immeasurable rewards. The safety, freedom to personalize your room, and a sense of belonging in a neighborhood are simply a variety of. Postponing a dwelling spend money on would possibly suggest missing out on these enriching ordeals.

    Closing concepts

    Selecting to buy a dwelling is main, affected by a number of issues. But if you have a look at the present present market traits, the current want charges, and the choice to construct equity coupled with our distinctive Customer Booster Software*, there’s definitely a persuasive argument for turning into a dwelling proprietor quicker alternatively than later.

    For tailored recommendation, contact your native Evergreen lender these days! Let us get you into your want residence.

    *Offer legitimate on purchase monetary loans beneath deal and refinance monetary loans shut regarding 7/1/2023 and 9/29/2023. The expert borrower(s) will obtain one $2,500 mortgage supplier credit score historical past certification redeemable in direction of a refinance on the very same property. Provide is non-transferrable, would possibly not be utilized to different transactions, and would possibly not be blended with a pricing concession. The refinance software date ought to be on or forward of three/31/2025. The borrower ought to have designed not less than six (6) consecutive on-time funds on the order mortgage upfront of closing the refinance. This is not a dedication to lend. Method is material to alter with out having detect. Not all candidates will qualify. Not all merchandise provided. More phrases, circumstances, and limits may properly implement. Call for specifics.

    ©2023 Evergreen Moneysource Home mortgage Company® NMLS ID 3182. Equal Housing Financial establishment. Trade/firm marks are the house of Evergreen Home Financial loans. All authorized rights reserved. Be certain to see www.evergreenhomeloans.com/licensing for licensing details.

    &#13

  • Personal rents went up 8.7% in May probably: ONS – Mortgage Tactic

    Private rents in the United kingdom larger by 8.7% in the 12 months to Might 2024, down from the report vital enhance of 9.2% in April, the most popular info from the Office atmosphere of National Figures reveals.

    These figures exhibit that the most important lease improves ended up in Northern Ireland precisely the place typical rents went up by 10.3% in the 12 months to March.

    Total the peculiar each month rent paid in England now stands at £1,301, a 8.6% maximize. In Wales the peculiar lease is £736, a 8.5% increase although in Scotland the widespread lease is £957 — a 9.3% increase.

    Further regional breakdowns clearly present that in England rent improves have been being biggest in London at 10.1% in extra of the previous 12 months. The North East had the least costly common enhance at 6.1%.

    Houses in Kensington and Chelsea in London had the best common each month rents, at £3,397. The lowest widespread rents have been being in Dumfries and Galloway in Scotland, wherever tenants paid an month to month common of simply £480.

    Paragon Lender dealing with director for mortgages Richard Rowntree states: “It is encouraging to see a discount in rental inflation, which we think about will likely be pushed by decreased inflation on new permits.”

    “In order for this sample to proceed on, something that aids to alleviate the affordability difficulties confronted by tenants, it’s vital that we take care of the imbalance involving the demand from clients and supply of rented residences.”

    “To do that we need to recognise the contribution of personal rented sector landlords and be proactive in creating the issues that support expenditure in nice good high quality housing.”

    In the meantime, Foxtons caring for director of lettings Gareth Atkins responses: “As we shift into peak summer season lettings yr, present is creating. Renter want can also be rising, mirroring 2023’s Q2 tendencies with a 20% thirty day period-on-thirty day interval improve.”

    “If want follows ultimate yr’s tendencies by the use of summer time season, Q3 will likely be a reasonably hectic market place. The announcement of the final election on the comparable time has resulted in the shelving of the Renters Reform Bill.”

    “This suggests there will likely be no rapid modifications to fixed time period tenancies or any of the opposite provisions in simply the month-to-month invoice. Renters Reform is probably to be reintroduced below a brand new govt however for now, it’s firm as customary.”

    Propertymark chief govt officer Nathan Emerson gives: “The impression of what has been a tough financial interval carries on to play chaos for quite a few renters. Not solely are particular person funds stretched to the max for fairly just a few of us, however we’ve got the extra uncertainty of a typical election and what that will finally essentially imply for renters and landlords.”

    “All vital political get-togethers have referenced the must have for establishing significantly-desired new houses, however we’ve got to must see a precise system and timeline as to how and when that’s going to materialize. Now, need is continuous to severely outstrip provide, and this stays a key contributory side to elevated rental charges all through the board.”

  • The Supreme Court may perhaps quickly defang bank regulators — particularly the CFPB

    Supreme Court - CFPB An forthcoming Supreme Courtroom conclusion has huge implications for a number of federal organizations, however specifically for the 13-calendar year-outdated Purchaser Monetary Protection Bureau.

    Bloomberg

    In its 13-12 months historical past, the Consumer Money Safety Bureau has survived two main 
    Supreme Courtroom issues, each of which might have defanged the firm.

    A 2020 ruling lowered the CFPB’s independence, however it stopped restricted of discovering that the firm was unconstitutional. And previous thirty day interval, the massive courtroom handed the bureau a essential victory by upholding its funding mechanism.

    But the CFPB will not be out of the woods. A forthcoming Supreme Courtroom determination, which is anticipated to be produced inside the upcoming handful of weeks, might think about a significant chunk out of the company’s rulemaking powers.

    The pending willpower will work out how considerably deference the courts give to regulators in deciphering the legal guidelines that give them the electrical energy to publish procedures. It has vital implications for not simply the CFPB — and U.S. banking regulation much more typically — however for federal corporations that oversee a wide array of industries. 

    Gurus say the stakes of a ruling that curtails regulatory capacity, which is usually noticed as the likeliest consequence, are particularly huge for the CFPB. The shopper bureau has a standing as being rather more intense than another federal companies. All by the Biden administration, corporations haven’t been shy about suing to impediment its restrictions.

    “It locations shopper safety in precise jeopardy,” acknowledged Susan Weinstock, CEO of the Client Federation of The usa, a consumer advocacy workforce. “We can have judges constructing these choices, they usually might end up staying not based mostly on info, and never based mostly on what’s occurring in the market.”

    Industry authorized professionals have a novel perspective of the CFPB’s do the job — they often suppose that the company has revealed an inclination to entry exterior of its statutory authority — however they agree that the purchaser bureau will likely be a considerably ripe think about for firm litigants if the Supreme Courtroom reins in regulators’ electrical energy.

    “It wouldn’t be an important drawback, to place it mildly, for the CFPB,” claimed Alan Kaplinsky, senior counsel at Ballard Spahr.

    At stake in a pair of cases now pending forward of the vital courtroom is the long term of a authorized doctrine thought to be Chevron deference, which obtained its identify from a landmark Supreme Court docket closing determination in 1984.

    The important tenet of the 40-12 months-old conclusion is that when there may be ambiguity about the that means of federal guidelines, judges want to present deference to companies’ interpretations. If that deference goes absent, the courts can have elevated latitude to overturn the companies’ procedures.

    The CFPB, which is the brainchild of Sen. Elizabeth Warren, D-Mass., has been a political lightning rod contemplating the proven fact that it was confirmed throughout the Obama administration. 

    But up to now, when CFPB pointers have been invalidated, it has not usually occurred by way of the courts. A 2017 firm rule barring corporations from like required arbitration clauses in purchaser contracts was overturned by a congressional decision, as was a CFPB bulletin associated to discrimination in vehicle lending.

    In 2019, a proposed regulation on payday lending was scaled once more by the firm by itself simply after then-President Donald Trump appointed Kathleen Kraninger as CFPB director.

    Since Rohit Chopra took the company’s reins in 2021, area groups have revealed higher willingness to drawback the CFPB’s polices in court docket. And though these litigants endured a setback in May probably, when the Supreme Court upheld the CFPB’s funding system, they’d get a improve from a ruling that undermines Chevron deference.

    “It decreases the probability of accomplishment of the CFPB with regard to all of those restrictions which have now been challenged in court docket,” Kaplinsky reported.

    For working example, sector groups have sued the CFPB over a regulation that might cap late bills on credit score historical past taking part in playing cards at $8. There can be a lawsuit — through which the CFPB is presently fascinating a ruling that favored the plaintiffs — about the company’s assertion that no matter the lender’s intent, discrimination on the foundation of age, race or intercourse violates the federal prohibition on unfair, deceptive or abusive acts and strategies.

    A 3rd pending lawsuit points a CFPB rule that would wish banking establishments and credit score unions to report information about smaller-organization mortgage candidates.

    Chris Willis, an legal professional at Troutman Pepper, pointed to the CFPB’s interpretation of the phrase “applicant” beneath the Equivalent Credit Possibility Act as one other spot of alternative vulnerability if Chevron deference goes away.

    The 50-year-previous anti-discrimination laws provides protections to future candidates, along with of us who’ve at present utilized for a private mortgage, in accordance to the CFPB’s legal guidelines. But the company’s interpretation is at drawback in an enforcement scenario in the direction of a home mortgage mortgage firm generally known as Townstone Monetary.

    “In a earth the place Chevron is not, an interpretation like that, that the market may properly not agree with, might turn into subject to worthwhile problem in court docket,” Willis mentioned.

    Long run CFPB guidelines, too, could be on shakier flooring in a circumstance through which the courts give significantly much less deference to federal corporations.

    In January, the shopper firm proposed capping overdraft bills for bigger sized banking corporations at $14. Also in the company’s pipeline: polices geared toward accelerating the rise of open banking in the United States.

    The economical suppliers area may gain advantage in chosen circumstances from a Supreme Court ruling that boundaries or overturns Chevron deference, Willis defined. He pointed to predicaments the place by regulators have employed expansive interpretations of federal laws to provide polices that sector actors oppose.

    But he additionally noticed that the demise of Chevron deference might have downsides for companies that rely upon the readability and specificity that a number of restrictions present.

    Trial attorneys might ship lawful worries in the direction of rules from federal regulators that may make it more difficult to sue monetary establishments.

    And level out legal professionals normal, a few of whom have in depth sparred with federal banking regulators about the get to of level out authorized pointers, might present satisfies demanding so-identified as preemption help that has typically drawn help from the enterprise. The Business of the Comptroller of the Forex and the Federal Deposit Insurance plan Corp. have each of these issued interpretations referring to preemption.

    “It could be unachievable to say, as a blanket rule, that the sector is in favor of Chevron getting overturned,” Kaplinsky claimed. “I might say simply the reverse — that in frequent, the market likes certainty, and objects which have been completely arrange in the legislation.”

    An individual occasion of that perspective was on present previous calendar 12 months in a short that the Mortgage mortgage Bankers Association submitted with the Supreme Court docket, describing the possible ramifications of a hypothetical court docket docket closing determination invalidating mortgage loan-linked insurance policies.

    “​​Lenders, servicers, and shoppers have operated by the CFPB’s guideposts for additional than 10 a very long time, and with out these folks rules substantial uncertainty would crop up as to the best way to undertake mortgage transactions in accordance with federal regulation,” the commerce group wrote.

    Daniel Wolff, a accomplice at the legislation enterprise Crowell & Moring, defined that Chevron deference has typically had protection implications that slice in reverse instructions. He thinks that some observers have exaggerated the potential impact of the lawful doctrine’s demise. Nonetheless, he predicted that in a put up-Chevron earth, regulators that stray from their central duties will likely be rather more most definitely to get their wings clipped.

    “Businesses will simply should hew nearer to their principal mission,” Wolff mentioned.