Tag: lot

  • California sets $20B of state bond steps Bay Area adds $20B a lot more

    California’s presidential election poll in November will embody $20 billion bucks of statewide bond measures, with $20 billion extra in only one regional bond election.

    At the purpose out diploma, lawmakers reached agreements earlier week on two $10 billion customary obligation bond actions that had been heading towards acceptance in flooring votes this 7 days.

    The actions have been being set forward as Senate Bill 867, a $10 billion statewide Ok-14 school constructing bond measure, and Assembly Invoice 247, a $10 billion climate bond measure.
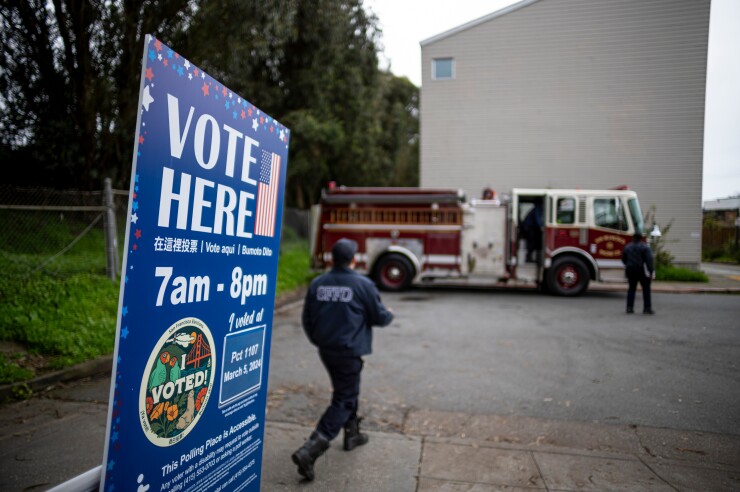
    Signage outside a polling station in San Francisco A indicator outdoors a polling station in San Francisco in March. Voters there’ll take into consideration a $20 billion regional housing bond in November, in addition to $20 billion of situation GO bonds.

    Bloomberg News

    All these steps will compete for consideration on the poll in what some predict might be a doc 12 months for varsity district bond measures, in an election by now juiced with a $20 billion regional housing bond measure within the San Francisco Bay Spot.

    The statewide actions have been place forward as Senate Bill 867, a $10 billion statewide Ok-14 school development bond measure, and Assembly Monthly invoice 247, a $10 billion climate bond consider.

    Supporters say the college bond would strengthen the lives of tens of thousands and thousands of children and modernize normal public colleges, regardless that the climate bond would fund clear up h2o, wildfire avoidance and restoration initiatives.

    “These bond actions are very important to the long run of this level out, and commit in our youngsters, their neighborhood universities, they usually make certain communities large and modest have accessibility to wash ingesting h2o and are wildfire protected,” stated Sen. President Pro Tempore Mike McGuire, D-Healdsburg.

    The Senate chief included that he ran for the college board on the age of 19 after observing his excessive school tumble into disrepair.

    “Our learners, lecturers and crew ought to have superior, particularly folks in underserved universities precisely the place sources are restricted and services are outdated, and at conditions, hazardous,” McGuire stated.

    Proposition 51, the ultimate statewide bond consider to help school design, was permitted by voters in November 2016 and has extended been depleted.

    If the statewide college bond measure passes, space districts will need matching money to protected state money.

    “I really feel we’re going to see a doc selection of GO school bond actions on the poll in 2024,” claimed Adam Bauer, president and principal authorities officer of municipal advisory company Fieldman, Rolapp & Associates.

    In 2020 and 2022, the choice of college bond measures on the poll was light, and the require for school development funding has remained, Bauer claimed.

    “In 2024, school districts have been ramping as much as make up for the absence of bond measures floated in extra of the earlier cycles,” he stated.

    He verified that college districts are working into circumstances precisely the place they won’t have sufficient money for initiatives as a result of truth they have not handed a bond in a while.

    “That is especially perfect, and they’re hopeful the state would set a measure on the poll to assist with matching money,” he talked about.

    Of the statewide climate bond consider, McGuire defined the communities he represents have been devastated by wildfires. Making certain that the state’s communities have the sources to defend themselves from wildfires, drought and floods is “vital to the prolonged-phrase success of the purpose out,” he talked about.

    “Our historically underserved communities on the doorway strains of the native local weather disaster couldn’t have enough money to attend any lengthier, requiring us to switch with urgency to strengthen California native climate resiliency,” reported Assemblymember Eduardo Garcia, D-Coachella, who co-lead the Assembly native local weather bond doing work group with Assemblymember Lori Wilson, D-Suisun Town.

    SB 867 would commit a naked minimal of 40% of the bond funds towards disadvantaged communities.

    The cash can be divided seven means: $3.8 billion for protected ingesting ingesting water, drought and flood protection $1.5 billion for wildfire and forest resilience $1.2 billion to cope with sea stage rise $1.2 billion to guard biodiversity $1.55 billion for park growth and out of doors recreation areas $450 million for excessive warmth mitigation and $300 million for climate-friendly and resilient ranches and farms.

    The climate bond would make investments in “our potential by prioritizing important calls for these varieties of as protected and fairly priced ingesting water entry, wildfire prevention, extreme heat mitigation, sustainable agriculture, and totally clear, renewable energy,” Wilson stated.
    Adam Bauer, president and chief executive officer of financial advisory firm Fieldman, Rolapp & Associates “I think about we’re heading to see a historical past quantity of GO school bond measures on the poll in 2024,” stated Adam Bauer, president and principal govt officer of Fieldman, Rolapp & Associates.

    Fieldman, Rolapp & Associates

    The $20 billion regional primary obligation bond measure within the San Francisco Bay Location would help assemble or preserve 90,000 reasonably priced households all through the 9-county location, supporters say.

    The Bay Location Housing Financing Authority Board, a regional board comprised of neighborhood elected officers, unanimously agreed at their June 26 convention to place the Bay Area’s first regional housing bond on the standard election poll.

    Only 17% of the state’s homebuyers can have enough money the state’s $814,280 median-priced single partner and youngsters home, with 24% able to afford to pay for a $655,000 median-priced condominium or townhome, in accordance to a California Affiliation of Realtors housing affordability report revealed Might 9.

    To afford to pay for a solitary-family members home, in accordance to the CAR’s calculation, potential consumers need to need to make $208,400 yearly to make month-to-month funds of $5,120, like principal, curiosity and taxes on a 30-year preset-level mortgage with a 6.86% curiosity quantity.

    San Mateo and Santa Clara — two counties within the BAHFA location — are the initially and subsequent most expensive components to acquire a residence, in accordance to Automobile.

    If authorized, $10.4 billion would go to assemble 36,000 very reasonably priced properties, $3 billion would go to guard 14,000 present moderately priced residences and $6.6 billion can be utilized as versatile funding to take care of and current homebuyer assist for 22,000 properties, in line with a report.

    Below current laws, the BAHFA measure must have approval by a minimum of two-thirds of voters to go. The bonds can be repaid with the advert valorem residence tax levy within the nine-county location.

    But the state’s voters may even be pondering of Assembly Constitutional Amendment 1, which might established the voter threshold at 55% for voter approval of bond actions for cost-effective housing and infrastructure. In accordance to BAHFA, if ACA1 passes, the authority’s bond consider would solely need a 55% vote threshold.

    “Today’s vote is the fruits of so quite a few a very long time of effort by so many of us all throughout our space,” BAHFA chair Alfredo Pedroza, a Napa County supervisor, acknowledged in a June 26 assertion. “The Bay Area’s longstanding housing affordability challenges affect all of us, our mates, our neighbors and our members of the family associates.”

    The bond consider would break up 80% of the money between the 9 counties (and the cities of San Jose, Oakland, Santa Rosa and Napa, each single of which carries a lot more than 30% of their county’s reduced-profits housing will want), in proportion to every county’s tax contribution to the bond. The remaining 20%, or $4 billion, can be made use of by BAHFA to construct a new regional system to fund economical housing growth and preservation assignments throughout the space.

    The measure additionally would develop a citizen’s oversight committee and bond proceeds account. The committee would report back to BAHFA and the Association of Bay Location Governments authorities boards. There would even be an once-a-year neutral audit.

    It stays to be witnessed if voters could have the precise enthusiasm to approve bond steps because the authors have for the techniques they might assist.

    Sonoma Point out University political science professor David McCuan identified that Gov. Gavin Newsom and lawmakers beforehand designed efforts to lighten the stress placed on voter’s discover by dealing with some initiatives legislatively, considerably than positioning them simply earlier than voters.

    “There might have been 22 to 24 statewide initiatives on the poll quite there might be 9 to 11,” McCuan claimed.

    “There is a lot weighing on voter’s pocketbooks by now, together with it staying a contentious election yr,” he stated.

    Take into consideration all the attention changing into equipped to the battle amongst earlier President Donald Trump and President Joe Biden, he defined.

    “Bond steps have accomplished pretty properly on the neighborhood quantity prior to now 10 or 15 a number of years, however California has been approaching the bond indebtedness ceiling,” he talked about. “When that affliction takes place, it’s actually simpler to get a ‘no’ than a ‘sure’ vote.”

    Regional poll actions, along with however not confined to tax and college bonds have notched a 70% approval quantity, and statewide actions have skilled a from 33% to 38% approval payment within the earlier 10 a few years, he reported.

    McCuan anticipates that fiscal measures, bond steps and steps to rework voter thresholds won’t fare in addition to they’ve within the earlier. If they have been being grabbing 70% of the vote beforehand, he’s predicting the standard acceptance value to fall as very low as 50%.

  • Vida-operator Belmont Eco-friendly lending falls a lot more than threefold to £190m   – Mortgage loan System

    Vida-owner Belmont Eco-friendly claimed that gross lending fell far more than threefold to £190m final 12 months, in accordance to its yearly report.  

    New residential monetary loans tumbled from £683m in 2022.  

    The small enterprise operated with “a obvious think about creating new house loan group with sustainable returns pretty than chasing amount in what was a fairly aggressive market, gross new lending in 2023 was consciously restricted,” suggests Belmont Environmentally pleasant chief authorities Anth Mooney within the report.  

    Its report supplies: “The increase in Financial establishment of England base charge throughout 2022 and early 2023 resulted in higher house loan prices, considerably impacting on affordability, which was additional exacerbated by substantial levels of inflation escalating the price of dwelling for fairly a few shoppers.”  

    Uk Finance figures clearly present that general gross lending all through the mortgage sector fell 29% to £223bn remaining yr, with remortgages 23% cut back and the make investments in-to-enable market place down 50%.  

    Belmont Green elements out that its new digital retention platform, seen 62% of maturing shoppers take into account out a new supply with the corporate, allowing it to prohibit redemptions to £0.2bn final yr.  

    This enabled it to finish 2023 with web mortgage loan belongings principally unchanged at £1.7bn.   

    It additionally completed two family property finance loan-backed stability transactions in 2023 elevating £750m, with a additional £300m raised in January 2024.  

    The company posted a income prematurely of tax of £6m, up from £1.4m in 2022.

    The report provides: “In December 2023, Uk Finance forecast a additional more 5% contraction within the gross house loan market place in 2024, reflecting the larger charge pure atmosphere and ongoing minimal client self-assurance.   

    “Our very personal view is a little bit far more optimistic, reflecting new enhancing financial data and early proof of charge reductions driving amplified motion ranges.   

    “Anticipated fascination degree reductions all through 2024, and a gradual enchancment in affordability and purchaser self-confidence together with pent-up want is probably going to restrict any additional discount in house costs, with a probably for them to keep broadly flat 12 months on yr.”  

  • More youthful Australians minimize back again on shelling out a lot more than more mature generations – report

    Youthful Australians slice back again on spending more than more mature generations – report | Australian Broker News

    News

    Young Australians reduce again on paying a lot more than more mature generations – report

    Their investing has minimized by 3.5% year-more than-12 months

    Younger Australians cut back on spending more than older generations – report

    News

    By
    Abigail Adriatico

    Younger Australians have been noticed to have scale back back on their expending probably the most versus different age groups, in accordance to a report by CommBank iQ.

    In its Price of Residing Insights Report, CommBank iQ found that Australians among the many ages of 25 and 29 skilled lessened their shelling out by 3.5% in contrast from a 12 months in the past.

    With inflation considered, these youthful Australians had diminished their consumption by a lot more than 7% in comparison with the quantity seen in May probably 2023. They had been the one age group that had slice back again on each their vital and discretionary charges as different age groups skilled opted to reallocate their budgets to guard the improve in prices for merchandise and knowledgeable companies.

    CommBank iQ head of innovation and analytics Wade Tubman reported that even with the higher a part of different age teams growing their shelling out on vital merchandise, the youthful age group had been heading the opposite route.

    “This highlights the sophisticated prospects people on this age bracket are incomes, with some possessing to enlarge lifestyle modifications like foregoing their wellbeing insurance coverage insurance policies utterly. The scale back in utilities expending might additionally advise youthful Aussies are shifting again in with dad and mom or into shared lodging to separate costs,” claimed Tubman.

    On a countrywide quantity, there was a 2.5% improve in spending, with requirements viewing an enhance of three.6%. On frequent, customers spent about $1,472 for each month for his or her necessities, led by the improve of their investing for insurance coverage plan (+8%), utilities (+6%), pharmacies (+6%), and supermarkets (+5%).

    “Many Australians are having to allocate a lot more of their pockets to important dwelling prices, pretty than different locations during which they could probably wish to direct their shelling out. The charge-of-living initiatives launched within the Federal Spending plan, for living proof the vitality bill rebate, mirror the elevated spending by Australians on essential objects like electrical energy,” claimed Tubman.

    “While paying in regional areas continues to outpace that of metro spots, this hole has narrowed when in distinction to earlier quarters. This raises the priority no matter whether or not individuals in metro locations have downsized their wallets to change to raised charges, and what spending growth stays is now ‘the brand new regular’.”

    Similar Stories

    Keep up with the most popular info and gatherings

    Join our mailing document, it’s completely free!

  • Fed’s fascination charge hike to make a lot less competitiveness in the housing market More stock in the market could catch the attention of terrified-off purchasers

    As the Federal Reserve launched however one other 75 basis place fascination value hike Wednesday, mortgage officers and lending executives — now properly knowledgeable of the info — had been searching forward, questioning irrespective of whether or not mortgage mortgage charges will spike or dip in the aftermath.

    Even economists are divided on what’s to arrive: Some think about expenses have already peaked many others say they’ll climb till or till the nation’s monetary system formally enters a recession. 

    But they do agree on only one factor: Increased want charges will quell housing want, which can let stock to rebound and, in the end, spur the return of unwilling patrons.

    “For clients, this (enhance in curiosity expenses) signifies that besides if the monetary system reveals added signs of tipping into a recession, house finance mortgage charges are attainable to pattern higher, which will probably be a drag on housing demand,” reported Danielle Hale, chief economist at Realtor.com

    Mortgage charges main up to June’s Fed fee hike surpassed the 6% degree as larger-than-predicted inflation information induced volatility in the market, which led to turbulence in mortgage mortgage charges. Due to the truth the Fed’s June curiosity quantity enhance of 75 bps, property finance mortgage charges in present weeks crept nearer to 5.5%. 

    Lawrence Yun, essential economist for the National Affiliation of Realtors, doesn’t assume rising curiosity premiums by 75 bps will have an effect on house mortgage expenses. The extensive-term bond sector, off which house mortgage costs generally are centered, “has sometimes priced-in all long run actions by the Fed, and should maybe have presently peaked with the 10-yr Treasury taking pictures up to 3.5% in mid-June,” Yun included.

    “It is attainable that the 30-calendar 12 months preset mortgage mortgage charge could properly calm down at 5.5% to 6% for the the rest of the calendar 12 months,” Yun defined. “Still, house finance mortgage prices are considerably bigger now as opposed to a particular person yr in the past, which is why house product sales have been slipping.”

    An govt with the Mortgage Bankers Association (MBA) additionally believes mortgage mortgage premiums have maybe peaked and could keep fixed amongst 5% and 5.5% by the leisure of 2022. An enchancment from the 6% mark, nonetheless it’s nonetheless appreciably bigger than early 2021’s 3% diploma. 

    “There is a tug-of-war in sector anticipations, involving the persistently larger inflation numbers and ensuing quick Fed hikes, and the elevating probability of a sharp slowdown and attainable financial downturn,” reported Mike Fratantoni, senior vice chairman and chief economist for the MBA. 

    If property finance mortgage premiums peak, Fratantoni acknowledged, “potential patrons who skilled been apprehensive off by the value spike, could probably come throughout their means again to the housing market.”

    There have been being very clear penalties from the earlier spike. Sales of newly designed residences fell a lot greater than 8% in June from the prior month and have been being 17% diminished than June 2021, in accordance to the U.S. Census and the Department of Housing and Urban Progress. Signed contracts to get hold of present properties declined a broader-than-anticipated 8.6% in June from May maybe and dropped 20% from June 2021, the National Affiliation of Realtors stated.

    Residence charges additionally grew, although at a slower fee. The nationwide residence-cost development slowed down in May maybe, posting a 19.7% yearly get hold of compared with a 20.4% elevate in April and a 20.6% leap in March, in accordance to the S&P CoreLogic Scenario-Shiller nationwide house value index.

    Yun sees home revenue coming once more if house finance mortgage premiums stabilize shut to the current charges and believes house revenue will probably be depending on jobs and shopper self worth. 

    “Job creations have been ongoing to day. Consequently, dwelling product sales could earlier than lengthy stabilize in simply a a number of months after which steadily change upwards from early up coming 12 months,” Yun defined.

    Hale, from Real property agent.com, acknowledged the declining demand and elevated expenditures belie some shiny spots for home patrons. 

    “While the choices are extra high-priced and a lot extra highly-priced to finance, the increasing quantity (of property product sales from a 12 months in the previous) will help the true property market rebalance, supplying seemingly purchasers a considerably-needed refresh,” Hale stated. 

    Any enhance in availability in stock deserts could be ample to another time carry in potential patrons to the market, in accordance to Marty Inexperienced, principal at home mortgage regulation agency Polunsky Beitel Eco-friendly. 

    “The downside is regardless of whether or not the slowdown is a finish consequence of most people merely pausing a order selection once they see wherever curiosity charges and family value ranges settle, or regardless of whether or not they’re proudly owning to maintain off a purchase determination indefinitely since of affordability issues,” Inexperienced stated. 

    Some LOs think about the improve in curiosity premiums was already baked into house finance mortgage prices, so they don’t assume extraordinary volatility like final month. 

    “There was no massive stress (like June),” defined Christian Dicker, senior mortgage officer at Motto House mortgage. “I believe it’s presently priced in the market.”

    Dicker immediate a slowdown in the housing market place is excellent, to some extent, due to the truth it signifies a lot less competitiveness for the client — a welcome alter instantly after months of increasingly excessive bidding wars, for the length of which every thing significantly less than an all-dollars give you got here with inherent uncertainty.

    “I’ve had way more presents acknowledged in the closing two weeks than the final two months. They (homebuyers) are seemingly out looking for at 4 properties and all of them are on the market. They’re making 1 or two gives and they’re discovering acknowledged,” Dicker acknowledged.

    Affordability continues to be a impediment, however some potential patrons are “resigning them selves to bigger charges, recognizing that they’re seemingly to have to shell out extra if they need the belongings,” claimed Coley Carden, vice chairman of residential lending at Winchester Co-Operative Bank.

    “With want charges escalating and family value appreciation slowing down, want for properties will stabilize,” Carden acknowledged. 

    Although he doesn’t see 20 gives on nearly each property as he did in the course of the pandemic, Carden nonetheless receives inquiries for homes, and even second homes. 


    “I consider what could curtail homebuyer demand is way extra of a financial downturn — particularly if folks get minimized hours and start to get laid off,” he talked about. 

  • A lot more homes sold at savings – PropTrack

    More homes sold at bargains – PropTrack | Australian Broker Information

    Information

    A lot more households provided at bargains – PropTrack

    Reductions emerge in regional marketplaces

    More homes sold at discounts – PropTrack

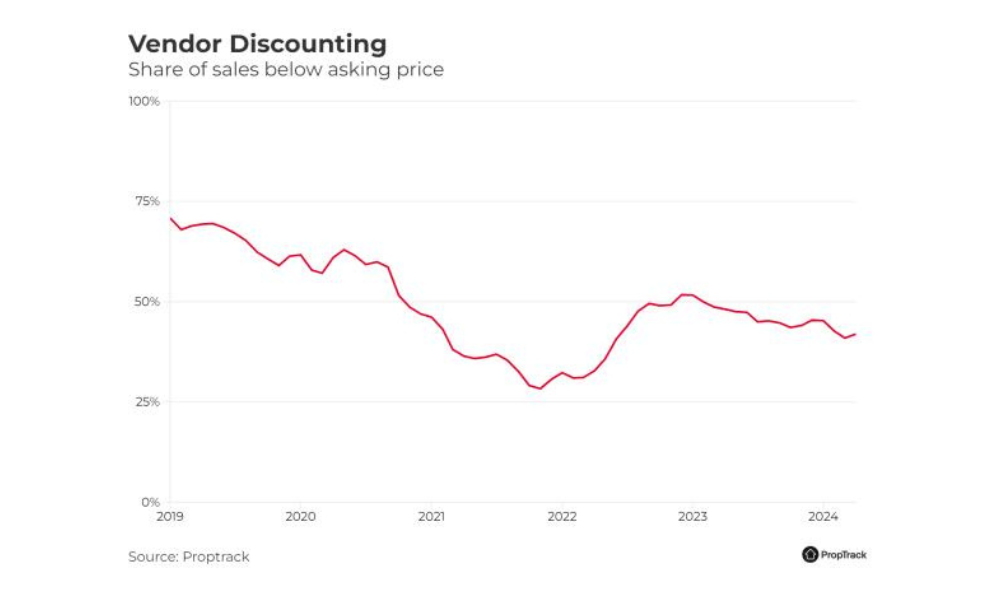
    House worth ranges are reaching new highs all through many areas and the amount of households purchased beneath asking price ticket is reducing, nevertheless fairly just a few locations are nevertheless coping with an maximize in residences staying marketed at a reduced, PropTrack defined.

    The PropTrack April Residence Selling worth Index verified a modest development in dwelling promoting costs by .23% in extra of the earlier month, representing a 6.6% enhance from April 2023, and marking 16 months of consecutive development.

    Regional variations in residence promoting costs

    Despite the nationwide improvement of rising dwelling promoting costs, some areas are witnessing a varied state of affairs.

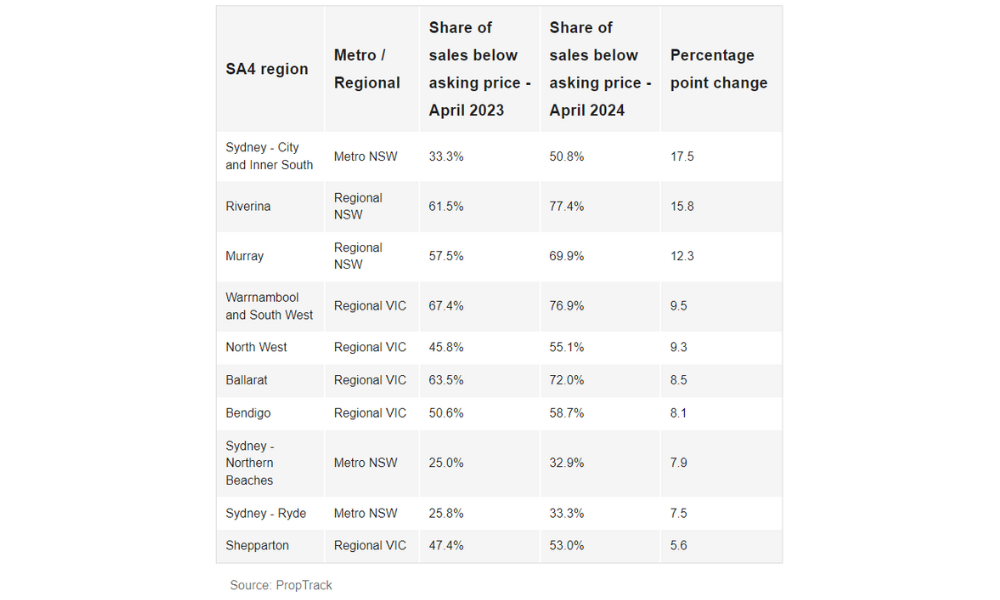
    Specifically, the Sydney – Metropolis and Internal South place noticed about 51% of homes purchased under inquiring worth, up from 33% the earlier yr. This 18-percentage-place elevate in vendor discounting is main and certified prospects amongst SA4 areas.

    Other components just like the Riverina and Murray places additionally seen noteworthy raises in properties marketed at a worth minimize.

    Implications for Purchasers in Regional Marketplaces

    The craze of enhanced vendor discounting is particularly pronounced in regional components of NSW and Victoria, wherever price ticket progress has been slower versus their capital metropolitan areas and different regional areas.

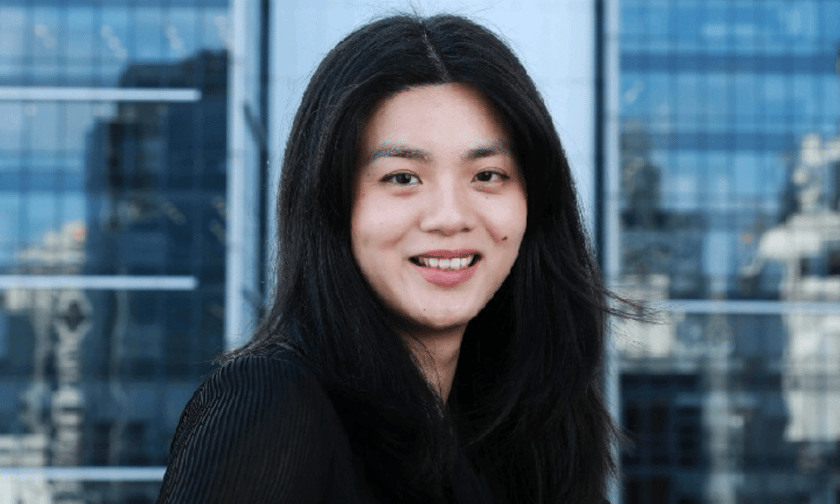
    “This maximize in vendor discounting and reduce than regular price progress demonstrates a slowdown in demand from prospects and potential declines in competitiveness in these areas, which is improbable info for people seeking to buy,” reported Megan Lieu (pictured increased than), monetary analyst at REA Team.

    With residence prices falling by .9% above the earlier calendar 12 months in regional Victoria and a additional modest rise of 4.3% in regional NSW, the sector issues are more and more beneficial for patrons.

    PropTrack’s outlook on home costs

    Even with these regional discrepancies, the usually demand for residences all through Australia is predicted to maintain on being sturdy, supported by potent populace progress and restricted rental sector problems.

    “Prices are more than likely to hold on rising because the supply of homes falls temporary of demand,” Lieu talked about.

    This sustained demand from prospects, coupled with a tightening rental business and rising self-confidence within the market, means that although some areas could probably give reductions, the broader business development leans towards elevated promoting costs.

    Are properties in your area advertising and marketing at a cheaper price? Sign up for the dialogue on the brand new PropTrack Residence Price tag Index.

    Continue to maintain up with the most recent info and actions

    Sign up for our mailing file, it is freed from cost!

  • FHFA to substitute Common FICO with a lot more inclusive credit history product Fannie Mae and Freddie Mac will accept FICO 10T and VantageScore 4. in a multiyear effort and hard work with the industry

    Retiring at age 65 is not any more time doable, more mature consumers say

    By Didier Malagies
    •
    22 Apr, 2024

    Retirement at 65 has been a longstanding norm for U.S. personnel, however more mature consumers think about that not solely is such an finish end result unfeasible, however they’re possible to confront further powerful retirements than their mothers and dads or grandparents. This is in accordance to simply recently launched examine ultimate outcomes from Nationwide , with a respondent pool that included 518 financial advisers and professionals, as very nicely as 2,346 merchants ages 18 and more mature with investable belongings of $10,000 or further. The examine follows different ongoing evaluation into the child boomer era because it methods “ Peak 65 .” The traders built-in a subset of 391 “pre-retirees“ involving the ages of 55 and 65 who aren’t retired, alongside with subsets of 346 single females and 726 married girls, Nationwide described of its methodology. Seven in 10 of the pre-retiree traders reported that the norm of retirement at age 65 “doesn’t make the most of to them,” when 67% of this cohort additionally consider that their very personal retirement challenges will outweigh people of earlier generations. Anxiety is reworking the perceptions of retired life-style, particularly for people who’re closest to retirement, the advantages suggest. “Four in 10 (41%) pre-retirees claimed they’d carry on doing the job in retirement to dietary complement their earnings out of necessity, and additional than a quarter (27%) method to dwell frugally to fund their retirement aims,” the results outlined. “What’s a lot more, pre-retirees say their packages to retire have reworked round the previous 12 months, with 22% anticipating to retire later than deliberate.” Eric Henderson, president of Nationwide Annuity , claimed that previous generations who noticed a “clean transition” into retired life don’t look to be translating to the present-day period incomes the exact same shift. “Today’s merchants are buying a harder time picturing that for them selves as they grapple with inflation and issues about managing out of funds in retirement,” Henderson defined in a assertion. The result’s that more pre-retirees are altering their spending patterns and aiming to live far more inexpensively. Forty-two p.c of the surveyed pre-retiree cohort agreed with the concept that caring for day-to-day charges has developed more troublesome due to to rising charges of dwelling, although 27% attributed inflation as the essential function they’re saving considerably much less for retirement proper now. Fifty-7 per cent of respondents acknowledged that inflation “poses the most speedy drawback to their retirement portfolio over the future 12 months,” although 41% reported they ended up avoiding pointless bills like holidays and leisure looking. Self confidence in the U.S. Social Safety utility has additionally fallen, the survey noticed. “Lack of confidence in the viability of Social Security on retirement (38%) is a vital problem influencing pre-retirees to rethink or redefine their retirement planning approaches,” the ultimate outcomes acknowledged. “Over two-fifths (43%) aren’t relying on Social Safety benefits as considerably as earlier anticipated, and additional than a quarter (27%) anticipate to obtain much less in benefits than earlier anticipated.”  The examine was performed by The Harris Poll on behalf of Nationwide in January 2024.

  • A lot more Us residents turn to house fairness for retirement funding Axios outlines how household is ever more being used as an asset for retirement funding, but some states are observing equity degrees decrease

    People are ever more turning to house fairness for funding their retirement designs — specifically by the use of relocation and downsizing — instantly after the pandemic led to a big uptick in house equity concentrations, in accordance to data from Vanguard Group and reporting by Axios.

    “People nonetheless desire a location to dwell in retirement and never usually select achieve of reverse mortgages to get income out of their households,” the Axios posting states. “Moving someplace cheaper, nevertheless, is considerably additional standard.”

    Kevin Khang, a co-authors of the Vanguard report, defined that in Colorado, the everyday variation in worth between a residence at present being purchased and the property turning into purchased in a relocation — expressed as a share of the acquired house’s value — has amplified from about 12% in 2007 to 73% in 2019.

    “Given what occurred to housing values in Colorado for the length of the pandemic, it is very attainable that this amount is even increased now,” Khang knowledgeable Axios.

    Other states with outsized possible incorporate California at 77% and Hawaii at 116%.

    On the opposite hand, some states are beginning off to see declines in household fairness concentrations, as house prices, which grew significantly throughout the pandemic, are at present being impacted by inventory issues and larger costs, which are driving demand down.

    The states of Idaho and Washington rank 1st and subsequent, respectively, amid areas hit most troublesome by growing costs and a cooling residence sale present market, in accordance to a present report from CoreLogic. Owners nationwide noticed an strange fairness elevate of seven.4%, having stated that.

    “[W]ith 66,000 debtors coming into opposed equity within the fourth quarter, the entire amount of underwater qualities is now approaching concentrations noticed on the conclusion of 2021, which was the bottom for the reason that Wonderful Economic downturn,” Selma Hepp, major economist for CoreLogic, talked about within the report. “The new very popular spots for fairness declines are principally markets which have witnessed essentially the most main house price ticket deceleration, which embrace Boise, Id. the San Francisco Bay Spot cities in Utah Phoenix and Austin, Tex.”

    Seniors in particular person have discovered main beneficial properties in property equity across the earlier a number of many years, with collective senior-held property fairness at an estimated $11.81 trillion as of Q3 2022, in accordance to the Reverse Property finance mortgage Market Index, which is produced quarterly by the National Reverse Home finance mortgage Lenders Association and data analytics agency RiskSpan.


    Even so, development for this cohort has been softer in present months when when put next to 2021 and early 2022, as evidenced by the previous quarterly RMMI growth concentrations.

    Most Relevant Artic

  • Why are charges so a lot bigger on a 2nd or Financial investment house

    The property finance mortgage charge pendulum swings nonetheless as soon as once more

    By Didier Malagies
    •
    18 Apr, 2024

    Hope 2024 to be mildly superior than 2023 with house mortgage charges falling within the second 50 % of the yr, housing trade consultants opined in their forecasts on the conclude of the 12 months. Cuts to the Federal sources worth (and subsequently to property finance mortgage premiums) are imminent, merchants enthused proper after December’s meeting of the Federal Open Industry Committee by which committee associates predicted a few quantity cuts in 2024. Some trade consultants forecasted as a number of as 6 charge cuts within the calendar yr centered on this information. Rate cuts are however coming, simply not in March , merchants and trade specialists reasoned extra a brief whereas in the past because the financial system ongoing to run heat. And now on the heels of opinions of extra highly effective than anticipated work alternatives growth and stickier than predicted inflation , the market’s shift from optimism to pessimism round cost cuts is full. Some even anticipate charge hikes proper earlier than charge cuts. The pessimism is clear in mortgage premiums. Freddie Mac‘s weekly Principal Mortgage Current market Survey is climbing again in direction of 7%. HousingWire’s Property finance mortgage Price Center , which relies upon on information from Polly, is already over 7.2%. Prices have been as minimal as 6.91% for Polly and 6.64% for Freddie as currently as February. On Tuesday, they arrived at 7.50% on Mortgage News Day-to-day, a vital for this 12 months. House mortgage premiums maintain large vitality within the housing sector most significantly, vital charges exacerbate the latest affordability catastrophe by walloping the getting electrical energy of would-be potential patrons and discouraging some would-be sellers – people with minimal, fastened-price mortgages – from itemizing their households, a drain on obtainable inventories. All this leaves housing consultants when once more combating for his or her share of shrinking pies – as we now have noticed with simply currently launched mortgage mortgage information and RealTrends Verified’s brokerage information , as correctly as deeper dives on the brokerage landscapes in Jacksonville and San Diego . It is unsurprising, then, that precise property shares have endured provided that the FOMC’s March meeting and the trendy occupation and inflation studies. That incorporates the nation’s finest homebuilders (DR Horton and Lennar), house mortgage originators (United Wholesale Home finance mortgage and Rocket Mortgage), brokerages (Any the place and Compass) and family lookup portals (Zillow and CoStar, which owns Residences.com). There are different dynamics at carry out for a few of these suppliers, on the opposite hand. The brokerages are additionally contending with the rule enhancements included in a proposed settlement by the Countrywide Affiliation of Realtors some patrons additionally assume these rule alterations benefit CoStar at the price of Zillow . UWM, within the meantime, is contending with a scathing investigative report by a hedge-fund-affiliated info agency whose hedge fund shorted UWM and went prolonged on Rocket it’s also coping with pending litigation . UWM denies the allegations manufactured within the report.  Higher house mortgage costs, a lot much less house mortgage functions and fewer residence earnings are nevertheless not the one results housing professionals may see from a way more prolonged higher-level atmosphere. There are additionally spillover outcomes from different industries, notably enterprise severe property. Regional banking corporations – which historically have been predominant family house mortgage originators – went large on enterprise actual property monetary loans as better banking corporations scaled again once more on this space in newest yrs. That elevated their publicity to downtown office towers, which have discovered an exodus of tenants and a bottoming out of appraised values simply as a report $2.2 trillion in industrial severe property private debt comes due above the longer term handful of a few years. That ties up funds that might or else motion to residential mortgages and in some eventualities stresses banks like New York Local neighborhood Lender, mum or dad of Flagstar Bank — the Seventh-biggest financial institution originator of family mortgages, Fifth-premier sub-servicer of mortgage monetary loans and the 2nd-biggest house finance mortgage warehouse mortgage firm within the place. Homebuilders, too, come to really feel the results of extended superior charges. Despite the truth that homebuilder confidence is proceed to up noticeably contemplating that earlier slide, new housing begins are slowing . The dim potential shoppers for homebuyers have turned some merchants to the nascent make-to-lease sector , basically a wager that greater charges are beneath to remain for prolonged greater than sufficient that would-be shoppers are now would-be renters.

  • U.S. population grew older, a lot quicker more than the past 10 years

    New information from the U.S. Census Bureau exhibits that the United States inhabitants grew older, quicker than at every other time in more than a century, in accordance to reporting by the Affiliated Press (AP).

    “The share of inhabitants 65 or more mature grew by additional than a third from 2010 to 2020 and at the quickest worth of any ten years in 130 many years, though the share of children declined, in accordance to new figures from the most present census,” the AP reported on Thursday.

    The fall in younger kids under the age of 5 was a noteworthy sample, and assisted to pressure the median age in the U.S. from 37.2 in 2010 to 38.8 in 2020, in response to the info. The enhancements have been additionally bothered by the two largest age teams, child boomers and millennials. More new child boomers handed age 65, and far much less kids had been being born over the 10-year time frame.

    “The drop stems from gals delaying having infants till lastly in a while in life, in a number of conditions to focus on schooling and studying and occupations, in response to consultants, who identified that beginning charges on no account recovered subsequent the Wonderful Recession of 2007-2009,” the AP described.

    College of Maryland Sociologist Philip Cohen attributes the drop in beginning costs to facets impacting the affordability concentrations of getting a child.

    “In the fast function, the disaster of operate-family stability, the deficiency of fairly priced child therapy, stresses related to wellness therapy, housing, and work stability, all put a damper on beginning charges by increasing uncertainty and constructing it more sturdy to determine to have and lift younger kids,” Cohen suggested the AP.

    There had been additionally social and monetary results induced by an older typical population, together with the stage of operating-age grownups geared up to steering funds to older residents by way of the social stability and Medicare programs.

    “The Census Bureau calculates a dependency ratio, outlined as the amount of children as well as the amount of seniors for every 100 operating-age of us,” the AP documented. “While the dependency ratio diminished for younger kids from 2010 to 2020, it enhanced for seniors by 6.8 individuals.”

    The reverse mortgage mortgage market has extended talked about the “silver tsunami,” a phrase that describes a necessary enhance in the vary of seniors at or round the age of 62 and, in change, people who qualify for a Household Fairness Conversion (*10*) finance mortgage (HECM).

    These demographic developments, along side the reported shortfalls concerning retirement financing, and the market will very seemingly be retaining a shut eye on the development of those developments.

    Most Relevant Posts


  • About 12,000 individuals per working day will convert 65 in 2024, but a lot of retirees are not ready

    The reverse home mortgage sector has very lengthy talked over the demographic traits that are on its facet when it arrives to fascinating to new possible debtors, and following yr might stand as a proving flooring for this kind of an argument.

    According to populace projections by the U.S. Census Bureau, 4.4 million People in america will obtain the age of 65 in 2024 — a decide that comes out to about 12,000 individuals for each working day. By 2030, all associates of the child boomer expertise will have reached the age of 65, which additionally signifies that by the start of 2028, the entire era’s homeowners in the U.S. will qualify for a Dwelling Fairness Conversion Mortgage (HECM).

    The craze is known as “peak 65,” and the “graying” of the U.S. populace will have notable impacts on the U.S. general economic system. But as life expectations have largely improved in regards to the earlier century, longevity risk additionally outcomes in being an drawback that U.S. retirees will should should maintain in thoughts in accordance to financial information editor Anne Stanley in a
    new column at Investor’s Enterprise Daily.

    “Retirement for boomers is distinct than it was for his or her mother and father in the so-named Silent Era. Everyday dwelling expectancy has enhanced, and right this moment’s 65-12 months-previous can assume to stay on the very least yet another 20 yrs,” the column claims. “About 80% of households with extra mature adults — or 47 million these varieties of houses — are struggling right this moment with cash. And they hazard slipping into monetary insecurity as they age, the National Council on Growing older claims.”

    The longstanding retirement paradigm is ill-equipped to take care of these new realities based on Jason Fichtner, chief economist on the Bipartisan Policy Heart.

    “With the U.S. enduring the most important retirement surge in its heritage, the nation’s basic public and non-public-sector retirement items have flip into out of date,” Fichtner instructed Investor’s Organization Each day. “The previous metaphor of the 3-legged stool of retirement scheduling — employer pensions, customized financial savings and Social Stability — no for a longer interval retains.”

    Though there are points, there are additionally new possibilities, the column components out. The place 65 was at one time deemed an “absolute” retirement age, that technique now not applies as older workers — both through a want or requirement — are performing for extra time intervals of time.

    But conventional retirement rules additionally have to evolve, Stanley says, because of the effectively-documented solvency points with the U.S. Social Protection technique.

    “This yr, trustees for Social Security and Medicare estimate that Social Safety will be capable to fork out 100% of scheduled constructive features till ultimately 2033,” the column claimed. “Without extra funding, benefits would tumble following that. The Hospital Insurance Believe in Fund, the principal fund for Medicare, is anticipated to shell out 100% of benefits until 2031.”


    There are a vary of potential strategies that retirees can make use of to reply to the modern retirement panorama, the column claims, which embrace the incorporation of annuities and a bigger goal for monetary dedication exercise. Having new adjustments to tax authorized pointers may have a advantageous affect on a retirement system.

    But, as a lot of in the reverse mortgage enterprise would say, factor to think about of property equity might make a change in retirement for sure folks, as correctly, particularly when making an allowance for the
    superior levels of housing prosperity maintained by infant boomers.