Tag: legal

  • DOJ loses legal dispute with Nutter Home Loans

    A Missouri district court docket choose dominated towards the federal government in a legal dispute with the now-defunct Nutter Home Loans over alleged violations within the underwriting of Home Equity Conversion Mortgages.

    In a abstract judgment favoring the Kansas City-based mortgage agency, also referred to as James B. Nutter & Co., the court docket prevented the U.S. Department of Justice from recovering potential damages beneath the False Claims Act, limiting it to looking for civil penalties. 

    In 2020, the DOJ filed its grievance, which alleged Nutter’s underwriting of over 1,500 government-guaranteed reverse mortgages, or HECMs, one decade earlier ran afoul of U.S. Department of Housing and Urban Development rules. In the allegation, the Justice Department claimed Nutter used unqualified underwriters, main HUD to insure loans that weren’t eligible and later went into default. The grievance additionally stated some signatures of licensed underwriters had been solid.

    The greatest takeaway from the ruling was “the federal government has developed no proof to indicate that any of these alleged underwriting deficiencies induced any hurt to HUD,” stated Edward “Ted” Kang, companion at Alston & Bird, who represented the lender in court docket. 

    The Justice Department’s failure to show causation means it will likely be restricted to looking for civil penalties towards Nutter. In addition, the choose eliminated roughly 1,000 of the loans cited by the federal government..  

    While an underwriting error or misconduct may play a consider any future issues with the mortgage, the choose stated there was no proof of proximate trigger or “enough connection between the conduct and the hurt,” in line with Kang. 

    The resolution made no judgment on the veracity of DOJ’s claims of Nutter’s alleged misconduct. The lender had beforehand paid penalties to each HUD and state regulators for infractions in its reverse-mortgage operations. 

    Nutter Home Loans ceased operations in late 2022 after being in enterprise for over 70 years, citing its DOJ battle as one of many causes behind its closure. Its shutdown additionally got here in the course of a protracted interval of enterprise contraction, main a number of different corporations to consolidate, shut or cut back employees. 

    In its 2020 submitting, the Department of Justice additionally claimed Nutter’s actions had violated the Financial Institutions Reform, Recovery and Enforcement Act of 1989. The abstract judgment wouldn’t have an effect on DOJ’s efforts to doubtlessly pursue damages associated to these allegations.

    The choose’s findings come simply weeks after pivotal Supreme Court rulings, together with within the case generally known as the Chevron deference, seem to level to quite a lot of legal opinions that will diminish powers of enforcement federal businesses have.  

    “It’s vital as a result of the federal government stated that it was harmed on this means, the court docket did not essentially simply rubber stamp that,” Kang stated relating to the Nutter resolution. 

    The choose “exercised impartial assessment of the circumstances and the proof and got here to a really effectively reasoned, in our view, resolution.” 

    A request for remark from the DOJ has not been returned by press time.

  • Firstmac breached distribution legal guidelines, court rules

    Firstmac breached distribution legal guidelines, court rules | Australian Broker News

    News

    Firstmac breached distribution legal guidelines, court rules

    First DDO case ends in ASIC win

    Firstmac breached distribution laws, court rules

    The Federal Court has discovered Firstmac in breach of the brand new design and distribution provisions, marking the primary court discovering of such a violation, ASIC reported.

    Firstmac didn’t take cheap steps to make sure the distribution of its High Livez funding product was in line with its goal market dedication (TMD).

    Cross-selling technique fails

    The court stated that Firstmac applied a “cross-selling technique” by advertising and marketing the High Livez funding product to 780 time period deposit holders between October 2021 and September 2022.

    ASIC’s stance on client safety

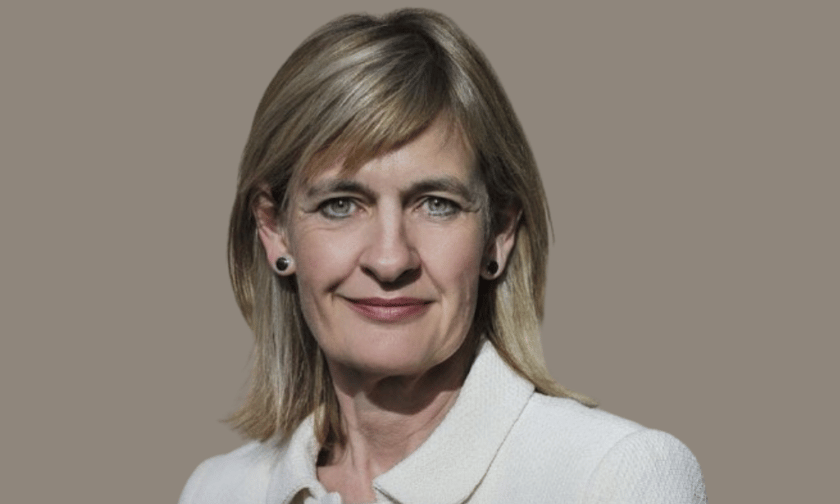
    ASIC deputy chair Sarah Court (pictured above) expressed considerations concerning the dangers to customers.

    “ASIC took this case as a result of we had been involved that clients had been uncovered to the danger they could get hold of a monetary product that was not acceptable to their wants and targets,” Court stated.

    “This ought to act as a deterrent to anybody engaged in cross-selling monetary merchandise who fails to contemplate their design and distribution obligations earlier than sending product disclosure statements.”

    Judgment particulars

    Justice Kylie Downes highlighted Firstmac’s insufficient steps in guaranteeing compliance with the DDO laws.

    “Firstmac didn’t take cheap steps to make sure the distribution of the High Livez PDS to time period deposit holders was in line with the goal market dedication,” Downes stated.

    “It is self-evident that [there] had been appropriate and out there methods to eradicate or minimise the probability that the High Livez PDS can be despatched to an individual who fell exterior the goal marketplace for High Livez.”

    Next steps for Firstmac

    ASIC will search pecuniary penalties towards Firstmac, with proceedings listed for a case administration listening to on July 19.

    Background on Firstmac and DDO regime

    Firstmac is a non-bank lender and the funding supervisor of High Livez, a registered managed funding scheme.

    ASIC commenced civil penalty proceedings towards Firstmac on Dec. 14, 2022, marking ASIC’s first DDO civil penalty motion towards a monetary product distributor.

    The DDO regime, efficient from Oct. 5, 2021, mandates issuers and distributors to undertake a consumer-centric focus in designing, advertising and marketing, and distributing monetary merchandise.

    Get the most well liked and freshest mortgage information delivered proper into your inbox. Subscribe now to our FREE each day e-newsletter.

    Related Stories

    LATEST NEWS

    Perth market surges

    Keep up with the most recent information and occasions

    Join our mailing record, it’s free!

  • Legal & Standard Retail hires Jefferies as industry growth director   – Property finance loan Technique

    Lawful & Standard Retail has employed Vikki Jefferies as its sector development director.   

    The small enterprise claims Jefferies will lead the development of its “presence and affect within the intermediated industry, doing the job carefully with companions, distributors, and advisers to ship floor breaking and shopper-centric choices throughout the enterprise”.   

    It gives that she’s going to goal on proposition developments together with the excessive profit, enterprise safety, and core distribution propositions.   

    Jefferies opinions to Authorized & Standard Retail controlling director, distribution, Ali Crossley.  

    She joins from LSL Financial Solutions, the place by she was a member of the federal government crew and was chargeable for the Primis neighborhood as very properly as relationship administration throughout mortgage, protection, and primary protection merchandise strains. She skilled labored at LSL for above 6 a number of years.   

    Jefferies has in extra of 25 yrs of sector working expertise, buying previously labored at Endsleigh Insurance plan in numerous roles throughout income administration, enterprise enterprise growth and merchandise type and design.  

    Her appointment at Lawful & Normal Retail follows the retirement announcement of the top of middleman development Jeff Woods.  

    Crossley claims: “Vikki’s appointment on this just lately created job arrives at a quick paced and thrilling time for the group, and I’m looking out forward to the bottom breaking techniques and management she’s going to convey to our workforce.  

    “She is a extraordinarily revered and seasoned chief with a deep being conversant in of the wants and problems with advisers and shoppers and, we’re assured that her experience will assist us to go on to succeed in good accomplishment.”  

    Jefferies gives that she is in search of forward to “enhancing their [Legal & General Retail’s] highly effective proposition and in addition main a proficient and devoted crew of sector growth managers”. 

  • Legal & General – Mortgage Strategy

    There has been a development of older first-time consumers, will increase in common mortgage sizes, and longer mortgage phrases being looked for, the newest knowledge from Legal & General Mortgage Services reveals. 

    It discovered there was a 13% enhance in 56 to 65-year-olds looking for their first property in Q1 2024 in comparison with the identical interval final yr suggesting {that a} rising variety of consumers are having to attend till their late 50s and past to take their first step onto the housing ladder.  

    Legal & General’s knowledge platform Ignite discovered within the 12 months to April 2024, 38% of potential consumers within the UK had been first-time consumers (FTBs), with a mean age of 33. 

    When evaluating Q1 2024 and This fall 2023, there was a 37% enhance in 18 to 30-year-old FTBs looking for a property, and a 33% enhance in 31 to 40-year-old FTBs.

    It explains that there was a pure decline in total market exercise within the lead-up to Christmas, so these will increase mark a return to exercise within the spring months.

    Elsewhere the info platform discovered that the typical mortgage worth looked for by advisers on behalf of FTBs during the last yr was £217,125. 

    When evaluating Q1 2024 to Q1 2023, the typical mortgage worth looked for elevated by 0.81% from £220,358 to £222,148. 

    However, when evaluating This fall 2023 to Q1 2024, the typical mortgage worth looked for by advisers elevated by 3.7% from £214,299 to £222,148.

    Legal & General says this highlights that purchaser affordability could possibly be beginning to ease as common month-to-month earnings enhance and inflation drops, that means consumers can afford bigger mortgage values.   

    Meanwhile, the most typical mortgage time period looked for by advisers on behalf of FTBs was 31 to 35 years (36%), adopted by 26 to 30 years (24%) and 36 to 40 years (17%).

    When trying on the broader market, the most typical mortgage time period searched on the platform was 31 to 35 years (28.5%), adopted by 26 to 30 years (22.4%) and 21 to 25 years (18.4%). 

    Legal & General Mortgage Services managing director Kevin Roberts says: “Our figures present that the need to personal a house stays sturdy, even for many who are ready longer to take these first steps onto the property ladder. As affordability begins to ease, we’ll probably see additional exercise within the first-time purchaser market, particularly if inflation continues to fall and the Bank of England reduces its base charge later within the yr.”

    “There are a lot of elements more likely to be impacting folks’s choices to purchase a property. High rental costs might encourage some clients towards homeownership. Equally, as mortgage charges decreased at first of the yr, clients who had been ready for the fitting time to purchase might have discovered merchandise that are extra inexpensive.”

    “While affordability has eased considerably, we all know the Bank of Family has nonetheless been enjoying a key function within the housing market, both by gifted deposits or through sensible assist to assist relations who’re making an attempt to avoid wasting for his or her first residence.”

    “This assist from mother and father, grandparents, and different relations reached report ranges in 2023, serving to 318,400 property purchases with an astonishing £8.1 billion price of lending. More than half (58%) of the worth of intergenerational assist goes to assist first-time consumers.”

    “However, if that housing possession dream goes to be achieved we’d nonetheless advocate consumers hunt down an expert mortgage adviser to provide them the most effective steering on their choices. ” 

  • On the hot seat: A banker testifies at Trump’s legal trial

    Trump - Michael Cohen - First Republic - trial montage Michael Cohen (main remaining) utilized a To begin with Republic Lender account that he based in Oct 2016 to ship $130,000 to the grownup movie star Stormy Daniels. Prosecutors allege that earlier President Donald Trump subsequently designed funds to Cohen that had been being reimbursement for a scheme to incorporate up a Trump sexual affair.

    Bloomberg

    If you occur to be a non-public banker, you’ve got received seemingly handled rapid-conversing purchasers who deal with each single transaction as an pressing make a distinction. Probably you may have even skilled purchasers who paint a phony or misleading image of their monetary actions.

    Gary Farro, a earlier senior managing director at To begin with Republic Bank, not too way back noticed himself beneath a highlight primarily due to 1 this kind of powerful buyer. On Tuesday, he concluded testifying at the first prison trial of a earlier president in U.S. background.

    Farro’s problematic shopper was Michael Cohen, the former Trump Corporation regulation agency who paid out $130,000 to grownup movie actress Stormy Daniels in the waning days of the 2016 presidential advertising and marketing marketing campaign.

    Manhattan prosecutors have charged earlier President Donald Trump with falsifying enterprise paperwork in hyperlink with funds that he afterwards created to Cohen, allegedly to reimburse the legal skilled for his power to cope with up a Trump sexual affair.

    Cohen, who pleaded responsible in 2018 to quite a lot of felony prices, like advertising and marketing marketing campaign finance violations and producing pretend statements to a federally insured financial institution, has morphed into a preferred nemesis of the earlier president. He is anticipated to testify afterwards in the trial.

    But first, the jury learn from Farro, a New Jersey resident who remaining yr joined Flagstar Financial establishment, a subsidiary of New York Community Bancorp, simply after 1st Republic collapsed. He was known as as a prosecution witness, and he said that he was testifying voluntarily. 

    Farro’s testimony was the two mundane and extraordinary. It centered on the type of again-business function that banking establishments do all the time in an effort and onerous work to know who their consumers are, however It additionally arrived in the midst of a presidential advertising and marketing marketing campaign during which the defendant is the presumptive Republican nominee.

    From the witness stand, Farro recalled being assigned Cohen as a buyer in 2015.

    “I can solely notify you what I used to be defined to,” he outlined. “I used to be picked since of my experience and my capability to deal with, um, people that may very well be a little or no onerous.”

    “Just about each time Michael Cohen spoke to me, he gave a sense of urgency,” Farro claimed, in line with formal transcripts of his testimony, which occurred about elements of two days. “He was a difficult shopper merely due to his motivation to get objects achieved so speedily.”

    The occasions that landed Farro in the witness seat started with a cellular phone merely name from Cohen on Oct. 26, 2016. That was 19 days simply after the emergence of the notorious “Access Hollywood” tape, during which then-candidate Trump bragged in vulgar circumstances about kissing and groping gals, and 13 occasions upfront of the election.

    Cohen wanted to arrange a checking account for a constrained legal accountability enterprise — Crucial Consultants LLC — that he had confirmed 9 days earlier than. And he wanted to take action speedily.

    “When Mr. Cohen referred to as me, I used to be on a golf course, I do know that is actually cliche for a banker,” Farro testified. “But I used to be on a golf course on a time off.”

    Of system, Cohen skilled to ship quite a lot of objects of data in order that the monetary establishment may do its owing diligence forward of the account may very well be opened.

    The financial institution’s know-your-purchaser type talked about the adhering to, based mostly totally on the data that Cohen offered to Initial Republic: “Michael Cohen is opening Crucial Consultants as a real property consulting agency to assemble charges for expenditure consulting do the job he does in genuine property reductions.”

    That assertion turned out to be pretend. The paperwork didn’t say all the things about the authentic function of the checking account.

    If Cohen had specified any indicator of the grownup amusement angle, “Nicely, we will surely query additional questions,” Farro mentioned. “It may be not our money to determine the place it goes. Having mentioned that, it’s an enterprise that we don’t perform with.”

    The paperwork additionally didn’t include any suggestion that the account could be used to assist a political prospect. If there skilled been these a disclosure, Farro mentioned, “There could be added scrutiny.”

    It took solely 5 or 6 a number of hours to get the Essential Consultants account permitted and utterly able to fund. “Shifting in and opening an account in a singular working day is taken into account extremely fast,” Farro mentioned.

    Just 4 minutes earlier than the 3 p.m. cutoff for wire transfers, Cohen moved $131,000 from a residence fairness line of credit standing that he beforehand had at To begin with Republic to the just lately based Vital Consultants account.

    The up coming morning, on Oct, 27, 2016, Cohen licensed a $130,000 wire switch from the Essential Consultants account to an account for purchasers of Daniels’ lawyer, Keith Davidson. The perform of the fee was characterised in paperwork as a “retainer.”

    During Farro’s testimony on Tuesday, Assistant District Attorney Rebecca Mangold questioned: “Would the financial institution’s plan of action for approving the wire be distinct if Mr. Cohen skilled indicated that the wire switch was a fee to an grownup film star?”

    “Of course,” Farro responded. “There would undoubtedly be enhanced thanks diligence on that.”

    Farro additionally testified that it’s really not atypical for a real property transaction to be achieved in a compressed time frame. In between Cohen’s preliminary get in contact with to Farro on the {golfing} system and the wire switch to Daniels’ legal skilled, solely about 24 hrs elapsed.

    When it was Trump legal professional Todd Blanche’s convert to drawback Farro, he requested whether or not Initially Republic might maybe have unsuccessful to do appropriate due diligence. “I actually do not know if that may be a truthful assertion,” Farro replied.

    In January 2018, The Wall Avenue Journal claimed that Cohen employed Critical Consultants to pay $130,000 to Daniels.

    Initially Republic in the end determined to close chosen accounts managed by Cohen, Farro testified. “We selected to not be hooked as much as what we have in mind t
    o be detrimental push,” he mentioned.

    He additionally testified that media protection was what alerted the San Francisco-primarily based mostly lender to the correct character of the transactions Cohen skilled made once more in Oct 2016.

    “Perfectly, the second the consumer doesn’t be completely reliable with us, we resolve on to not do enterprise enterprise with them seemingly forward,” he reported.

  • ML-Implode News – Foreclosure Protection Legal professional Mark Stopa’s Suspension Is Helpful Instantly

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    2018-08-01 — mfi-miami.com

    &#13

    Florida Supreme Court docket Puts Mark Stopa Suspension Into Influence Immediately

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    provide write-up |&#13

    permalink |&#13

    talk about | &#13

    subscribe by:&#13

    |&#13

    RSS | &#13

    e-mail &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    Remarks:&#13

    Be the initially to incorporate a remark&#13

    &#13

    &#13

    insert a remark | go to discussion board thread

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13

    &#13