Tag: know

  • What you need to know about FHA Home loans

    The residence finance mortgage stage pendulum swings however as soon as extra

    By Didier Malagies
    •
    18 Apr, 2024

    Assume 2024 to be mildly higher than 2023 with residence mortgage prices falling within the second half of the 12 months, housing business specialists opined in their forecasts on the conclude of the 12 months. Cuts to the Federal money stage (and subsequently to home mortgage premiums) are imminent, merchants enthused simply after December’s assembly of the Federal Open Market place Committee wherein committee associates predicted 3 worth cuts in 2024. Some business specialists forecasted as a lot of as 6 stage cuts within the calendar yr based on this data. Level cuts are nonetheless coming, simply not in March , merchants and market gurus reasoned extra not too way back as the general financial system continued to function heat. And now on the heels of critiques of extra sturdy than anticipated jobs growth and stickier than anticipated inflation , the market’s shift from optimism to pessimism in extra of worth cuts is whole. Some even anticipate quantity hikes prematurely of stage cuts. The pessimism is noticeable in home mortgage costs. Freddie Mac‘s weekly Main Home mortgage Industry Survey is climbing again once more within the route of seven%. HousingWire’s Mortgage Amount Middle , which is dependent upon information from Polly, is presently earlier talked about 7.2%. Rates have been being as small as 6.91% for Polly and 6.64% for Freddie as simply currently as February. On Tuesday, they reached 7.50% on Property finance mortgage Information Daily, a excessive for this yr. Mortgage mortgage charges maintain key electrical energy within the housing market most significantly, vital premiums exacerbate the current affordability disaster by walloping the acquiring electrical energy of would-be customers and discouraging some would-be sellers – people with diminished, mounted-price mortgages – from itemizing their homes, a drain on on the market inventories. All this leaves housing business specialists after once more stopping for his or her share of shrinking pies – as we have now noticed with simply currently unveiled property finance mortgage information and RealTrends Verified’s brokerage information , as very effectively as additional dives on the brokerage landscapes in Jacksonville and San Diego . It is unsurprising, then, that severe property shares have suffered as a result of the FOMC’s March assembly and the present profession and inflation tales. That options the nation’s main homebuilders (DR Horton and Lennar), mortgage mortgage originators (United Wholesale House mortgage and Rocket Mortgage), brokerages (Everywhere and Compass) and family lookup portals (Zillow and CoStar, which owns Households.com). There are different dynamics at carry out for a few of these suppliers, nonetheless. The brokerages are additionally contending with the rule changes bundled in a proposed settlement by the Nationwide Association of Realtors some consumers additionally think about these rule enhancements acquire CoStar on the expenditure of Zillow . UWM, in the meantime, is contending with a scathing investigative report by a hedge-fund-affiliated information group whose hedge fund shorted UWM and went lengthy on Rocket it’s also working with pending litigation . UWM denies the allegations constructed within the report.  Substantial mortgage mortgage charges, a lot much less residence finance mortgage apps and fewer residence revenue are unhappy to say not the one results housing specialists may see from a much more prolonged large-amount ambiance. There are additionally spillover outcomes from different industries, specifically workplace setting actual property. Regional monetary establishments – which traditionally have been key residential residence finance mortgage originators – went vital on skilled real property monetary loans as bigger sized banking firms scaled again on this location in trendy a long time. That enhanced their publicity to downtown enterprise workplace towers, which have witnessed an exodus of tenants and a bottoming out of appraised values simply as a document $2.2 trillion in business true property bank card debt comes due about the next a number of a long time. That ties up capital that might usually motion to family mortgages and in some circumstances stresses banking establishments like New York Group Financial establishment, father or mom of Flagstar Lender — the Seventh-largest lender originator of family residence loans, Fifth-major sub-servicer of residence mortgage monetary loans and the 2nd-largest mortgage warehouse mortgage firm within the nation. Homebuilders, means too, expertise the outcomes of extended superior charges. Although homebuilder assurance is nevertheless up significantly as a result of final slide, new housing begins off are slowing . The dim potential shoppers for homebuyers have turned some traders to the nascent establish-to-lease sector , essentially a wager that vital charges are right here to stay for extended loads of that would-be potential consumers at the moment are would-be renters.

  • What you will need to know about Condos when finding a home finance loan

    The home loan price pendulum swings however once more

    By Didier Malagies
    •
    18 Apr, 2024

    Be anticipating 2024 to be mildly larger than 2023 with home loan prices falling within the second half of the calendar 12 months, housing professionals opined in their forecasts on the finish of the 12 months. Cuts to the Federal funds quantity (and subsequently to home finance loan charges) are imminent, merchants enthused quickly after December’s convention of the Federal Open up Market place Committee by which committee members predicted three quantity cuts in 2024. Some specialists forecasted as a number of as six cost cuts within the 12 months based totally on this information. Amount cuts are nonetheless coming, simply not in March , merchants and sector specialists reasoned much more simply currently because the financial system ongoing to run heat. And now on the heels of evaluations of stronger than anticipated work alternatives growth and stickier than anticipated inflation , the market’s change from optimism to pessimism in extra of payment cuts is complete. Some even anticipate stage hikes forward of price cuts. The pessimism is apparent in home loan expenses. Freddie Mac‘s weekly Major Property finance loan Market place Study is climbing again within the path of seven%. HousingWire’s Property finance loan Fee Middle , which relies on information from Polly, is at present over 7.2%. Prices had been as small as 6.91% for Polly and 6.64% for Freddie as currently as February. On Tuesday, they arrived at 7.50% on Property finance loan News Day-to-day, a substantial for this 12 months. Home loan costs preserve massive electrical energy within the housing trade most significantly, important charges exacerbate the present-day affordability disaster by walloping the buying vitality of would-be potential patrons and discouraging some would-be sellers – these individuals with minimal, set-level mortgages – from itemizing their homes, a drain on obtainable inventories. All this leaves housing specialists after but once more preventing for his or her share of shrinking pies – as we’ve noticed with currently launched property finance loan info and RealTrends Verified’s brokerage info , as properly as additional dives on the brokerage landscapes in Jacksonville and San Diego . It is unsurprising, then, that real property shares have endured provided that the FOMC’s March meeting and the newest occupation and inflation research. That consists of the nation’s main homebuilders (DR Horton and Lennar), home loan originators (United Wholesale Home finance loan and Rocket House loan), brokerages (Wherever and Compass) and residential search for portals (Zillow and CoStar, which owns Residences.com). There are different dynamics at get pleasure from for a few of these firms, however. The brokerages are additionally contending with the rule adjustments included in a proposed settlement by the National Association of Realtors some traders additionally think about these individuals rule modifications benefit CoStar at the price of Zillow . UWM, within the meantime, is contending with a scathing investigative report by a hedge-fund-affiliated info enterprise whose hedge fund shorted UWM and went very lengthy on Rocket it’s also working with pending litigation . UWM denies the allegations constructed within the report.  Large home loan expenses, much less home loan apps and far much less home income are regretably not the one results housing trade specialists may see from a additional prolonged higher-charge setting. There are additionally spillover outcomes from different industries, particularly workplace atmosphere actual property. Regional monetary establishments – which normally have been essential family home loan originators – went main on skilled genuine property monetary loans as extra substantial monetary establishments scaled again on this place in fashionable years. That enhanced their publicity to downtown enterprise towers, which have seen an exodus of tenants and a bottoming out of appraised values simply as a historical past $2.2 trillion in industrial actual property bank card debt will come owing across the upcoming couple a very long time. That ties up funds that might usually circulation to residential mortgages and in some circumstances stresses monetary establishments like New York Community Bank, guardian of Flagstar Lender — the Seventh-most important monetary establishment originator of family home loans, Fifth-most important sub-servicer of home finance loan loans and the 2nd-largest home finance loan warehouse loan firm within the nation. Homebuilders, as effectively, actually really feel the outcomes of prolonged giant charges. Although homebuilder assurance is nonetheless up noticeably contemplating that final tumble, new housing commences are slowing . The dim potential shoppers for homebuyers have turned some merchants to the nascent make-to-hire sector , primarily a wager that important prices are right here to proceed to be for lengthy loads of that would-be potential patrons at the moment are would-be renters.

  • What you need to know about condos when acquiring a house loan

    The residence finance loan cost pendulum swings nonetheless but once more

    By Didier Malagies
    •
    18 Apr, 2024

    Assume 2024 to be mildly improved than 2023 with residence loan premiums slipping within the subsequent 50 p.c of the yr, housing gurus opined in their forecasts on the end of the 12 months. Cuts to the Federal money stage (and subsequently to mortgage fees) are imminent, merchants enthused following December’s meeting of the Federal Open up Marketplace Committee during which committee customers predicted 3 charge cuts in 2024. Some authorities forecasted as a lot of as six quantity cuts within the 12 months based mostly totally on this data. Level cuts are nonetheless coming, simply not in March , merchants and market business specialists reasoned way more not too way back because the financial system ongoing to run scorching. And now on the heels of opinions of a lot better than predicted employment development and stickier than predicted inflation , the market’s shift from optimism to pessimism round charge cuts is full. Some even depend on payment hikes earlier than stage cuts. The pessimism is seen in residence finance loan fees. Freddie Mac‘s weekly Principal Home finance loan Market Study is climbing again once more in the direction of 7%. HousingWire’s Property finance loan Amount Heart , which depends on information from Polly, is presently earlier talked about 7.2%. Fees had been being as decrease as 6.91% for Polly and 6.64% for Freddie as currently as February. On Tuesday, they achieved 7.50% on Home finance loan News Daily, a important for this yr. House loan premiums hold key electrical energy within the housing discipline most significantly, excessive charges exacerbate the current affordability catastrophe by walloping the getting electrical energy of would-be customers and discouraging some would-be sellers – these with very low, mounted-charge mortgages – from itemizing their households, a drain on obtainable inventories. All this leaves housing specialists when but once more stopping for his or her share of shrinking pies – as we’ve noticed with simply currently produced property finance loan information and RealTrends Verified’s brokerage data , as correctly as additional dives on the brokerage landscapes in Jacksonville and San Diego . It is unsurprising, then, that real property shares have skilled contemplating that the FOMC’s March meeting and the present profession and inflation studies. That incorporates the nation’s high rated homebuilders (DR Horton and Lennar), property finance loan originators (United Wholesale House loan and Rocket Home finance loan), brokerages (Anywhere and Compass) and family lookup portals (Zillow and CoStar, which owns Homes.com). There are different dynamics at have interaction in for a few of these suppliers, nonetheless. The brokerages are additionally contending with the rule alterations built-in in a proposed settlement by the National Affiliation of Realtors some traders additionally take into account these rule alterations acquire CoStar on the worth of Zillow . UWM, within the meantime, is contending with a scathing investigative report by a hedge-fund-affiliated data group whose hedge fund shorted UWM and went prolonged on Rocket it is usually working with pending litigation . UWM denies the allegations made within the report.  Superior property finance loan charges, much less residence finance loan purposes and fewer residence product sales are regretably not the one results housing professionals might see from a a lot extra extended high-rate pure atmosphere. There are additionally spillover outcomes from different industries, primarily enterprise workplace precise property. Regional monetary establishments – which usually have been necessary family house loan originators – went large on industrial real property monetary loans as bigger sized monetary establishments scaled again once more on this house in new a very long time. That enhanced their publicity to downtown workplace atmosphere towers, which have seen an exodus of tenants and a bottoming out of appraised values simply as a historical past $2.2 trillion in enterprise true property private debt arrives owing above the up coming couple yrs. That ties up funds that might in any other case motion to residential residence loans and in some circumstances stresses monetary establishments like New York Neighborhood Lender, mum or dad of Flagstar Financial establishment — the Seventh-biggest financial institution originator of family mortgages, Fifth-greatest sub-servicer of property finance loan loans and the 2nd-major mortgage loan warehouse loan firm within the state. Homebuilders, a lot too, sense the results of extended important fees. Although homebuilder self esteem is even now up considerably since final slide, new housing commences are slowing . The dim potential shoppers for homebuyers have turned some merchants to the nascent construct-to-rent sector , successfully a wager that greater costs are under to keep for lengthy greater than sufficient that would-be patrons are actually would-be renters.

  • A listing of points to know about when purchasing a rental

    Gen X is presently attempting to find housing applicable for rising older in place

    By Didier Malagies
    •
    10 Apr, 2024

    Infant boomers are exhibiting an awesome motivation to age in location of their have residences, however their kids — largely prospects of Generation X — are additionally creating their goals felt by in search of out residences that may accommodate their requires as they become older, in accordance to a fashionable report from the New York Periods. Citing 2021 information from the Harvard College Joint Center for Housing Scientific research that confirmed 88% of grownups 65 and older are rising older in place, a lot of associates of the subsequent era — primarily born involving the mid-Sixties and early-Nineteen Eighties — are presently utilizing proactive actions to by contemplating “about the place by they are going to reside of their 70s, 80s and even 90s,” the Occasions documented. Homebuilders are observing a improve in want for residences that may accommodate purely pure getting older from Gen X prospects. David O’Reilly, CEO of Howard Hughes Holdings which constructs ready communities, describes the market presently being “on the cusp,” saying that the demand seems to be coinciding with way more prospects of Gen X nearing a time the place they are going to develop to be “empty nesters.” “That’s ordinarily the tipping stage,” O’Reilly advised the Situations. Gen X potential patrons are additionally a lot extra in all probability to have more cash signifies and handle greater than their possible alternate options, and are sustaining entry to mandatory afterwards-everyday residing services and products in mind when deciding upon precisely the place to keep as they become older, the story outlined. “In new developments, [Gen X buyers] are in search of entry to well being and health and wellness facilities, like climbing trails and tennis courts, as successfully as choosing property capabilities like showers moderately of bathtubs, for event, and soliciting for probably the most up-to-date gizmos to allow them as they age,” the reporting talked about. A report launched last 7 days by the National Affiliation of Realtors (NAR) said that Gen X homebuyers have a median money move of $126,900, and are proceed to years absent from retirement. That extra functioning time will allow them to amass much more wealth in accordance to Jessica Lautz, deputy chief economist and vp of investigation at NAR. Users of Gen X are additionally benefiting from the pandemic and article-pandemic operate-up in home promoting costs, carrying significantly extra family equity than their millennial counterparts and dwarfing millennial homeownership costs 72% to 55% as of 2023. A single analyst talked about that Gen X prospects are motivated to act now for rising older-correct housing thanks to the purpose out of the housing trade.  “If they’re searching for homes, supplied the tightness of the present market and distant do the job, I do think about you see additional Gen X-ers viewing a residence receive as a dwelling for the comfort of their lives,” mentioned Cristian deRitis, deputy primary economist at Moody’s Analytics to the Times.

  • What You Want to Know About Loan Approval for a House With Solar Panels

    Professional Solution: Hi Susan, that is what you want to learn about how photo voltaic panels impression receiving dwelling funding.

    How Photo voltaic Panels Have an impact on Financial mortgage Acceptance

    Solar panel agreements can drastically impression private mortgage approval from corporations like Fannie Mae and Freddie Mac, primarily counting on regardless of whether or not the photo voltaic panels are leased, topic to a electrical energy spend money on settlement (PPA), or owned outright.

    Each and each state of affairs gives distinct components for mortgage acceptance procedures:

    Leased Photo voltaic Panels and PPAs

    For properties with leased picture voltaic panels or these beneath a PPA, equally Fannie Mae and Freddie Mac have distinctive requirements that can have to be achieved for monetary mortgage approval.

    These pointers make certain that the presence of leased picture voltaic panels or PPAs would not adversely have an have an effect on on the economical stability and marketability of the home securing the property finance mortgage.

    Fannie Mae

    Fannie Mae wants that leased photo voltaic panels and PPAs not have an effect on the property’s lien precedence.

    The month-to-month funds beneath these agreements ought to be factored into the debt-to-earnings (DTI) ratio until the lease or PPA options a fastened cost for a confirmed complete of vitality creation, which can maybe allow for an exclusion from the DTI calculation.

    On prime of that, Fannie Mae stipulates that the property may have to have get hold of to an alternate provide of electrical electrical energy that meets group requirements.

    Freddie Mac

    Freddie Mac in the identical approach emphasizes the need want for photo voltaic panel lease funds or PPA funds to be deemed within the DTI ratio calculations lower than chosen conditions.

    The ideas spotlight the significance of a creation promise to almost definitely exclude these funds from the DTI ratio.

    Freddie Mac additionally notes that the appraiser may have to touch upon the marketability of the property with photo voltaic panels, indicating the importance of photo voltaic panels to the over-all property value, however leased panels or these beneath PPAs usually are not concerned within the property’s appraised value.

    Owned Solar Panels

    When photo voltaic panels are owned outright, the strategy tends to be way more easy:

    Fannie Mae

    Fannie Mae views owned photo voltaic panels positively, as they usually incorporate to the price of the home.

    The suggestions counsel that common eligibility calls for use, constructing the mortgage approval methodology smoother for attributes with owned picture voltaic panels.

    Freddie Mac

    Freddie Mac necessitates appraisers to perceive the existence of owned picture voltaic panels and have a look at them within the property’s market place worth, almost definitely growing the house’s appraisal price.

    This can positively have an effect on the monetary loan-to-worth ratio, an essential variable in mortgage acceptance.
    A house with solar panels installed on the roof and a family standing outside

    FHA Financial loans for Photo voltaic Panel Households

    When making use of for an FHA private mortgage for a home with picture voltaic panels, the arrange of the picture voltaic panels points.

    If the panels are leased or beneath a Power Acquire Arrangement (PPA), they will not maximize the house’s appraised value since they are not utterly a part of the home.

    On the opposite hand, you’ll be able to anticipate to have to have to depend the common month-to-month funds for these panels in your bank card debt calculations, which may have an have an effect on in your mortgage eligibility.

    On the opposite hand, in case you personal the picture voltaic panels outright, they will enhance your own home’s worth. This is just because they’re witnessed as a long run development, most likely incomes it a lot simpler to get your mortgage accredited.

    The FHA appears favorably on electricity-successful households, so owned photo voltaic panels may do the job to your profit.

    The essential particulars for FHA monetary loans and photo voltaic panels are:

    Fundamentally, for FHA monetary loans, proudly owning your picture voltaic panels is usually better for your private mortgage software program than leasing them or possessing a PPA.

    VA and USDA Solar Panel Recommendations

    For VA and USDA loans, residences with photo voltaic panels even have specific concerns, very similar to with FHA monetary loans, however there are some variances in how these programs view and take care of photo voltaic panel financing and valuation.

    VA Loans

    VA monetary loans give you glorious adaptability for veterans acquiring residences with picture voltaic panels, no matter whether or not the panels are leased, under a Electric energy Purchase Arrangement (PPA), or owned outright.

    Nevertheless, the VA spots a robust emphasis on the chance positive factors and costs related to picture voltaic panels:

    Owned Photo voltaic Panels

    Comparable to different financial institution mortgage sorts, owned photo voltaic panels can elevate the good thing about the residence.

    The VA acknowledges the added worth of electrical energy efficiency enhancements, like picture voltaic panels, and considers this within the house’s appraisal.

    This can positively have an have an effect on on the mortgage circumstances and the amount a veteran is certified to borrow.

    Leased Solar Panels or PPAs

    When the VA wouldn’t explicitly prohibit homes with leased picture voltaic panels or PPAs, it calls for that any lease or PPA ought to not adversely impression the home-owner’s financial predicament or the marketability of the property.

    The phrases of the lease or PPA, equivalent to any linked obligations, ought to be clearly favorable to the veteran.

    USDA Loans

    USDA monetary loans, geared toward serving to rural homebuyers, additionally assist the purchase of properties with photo voltaic panels, reflecting this system’s dedication to sustainability and energy efficiency.

    Electricity Performance and Photo voltaic Panels

    USDA monetary loans can cowl the worth of shopping for and placing in photo voltaic panels as part of an exertion to market electrical power-effective rural housing.

    This support demonstrates the USDA’s broader purpose of maximizing rural communities’ entry to sustainable electrical energy alternate options.

    Appraisal and Loan Factors

    For residences with current picture voltaic panels, the USDA considers the price added by these strategies in the midst of the appraisal methodology.

    Owned photo voltaic panels that lead to the house’s vitality effectivity can positively have an effect on the property’s valuation, most likely enhancing financial institution mortgage circumstances.

    Getting a Property With Outright Owned Photo voltaic Panels

    When you may be buying a family with picture voltaic panels owned outright, the implications are very beneficial from a funding and appraisal standpoint.

    According to ideas from businesses like Freddie Mac, picture voltaic panels which are owned free and crystal clear will be a substantial asset.

    Freddie Mac’s pointers, for occasion, name for appraisers to understand the existence of photo voltaic panels and consider them of their evaluation of the property’s market place profit.

    This signifies that owned picture voltaic panels can straight contribute to a bigger appraisal price for the home, almost definitely that includes you additional equity from the start.

    This contrasts with leased picture voltaic panels or people beneath Tempo loans, which have additional refined implications for family funding.

    Owned picture voltaic panels eradicate worries about lease funds or Rate mortgage obligations, simplifying the house finance mortgage approval course of.

    Considering that one can find no Third-get collectively possession or attached monetary debt, collectors can proceed with out having the have to have for extra underwriting points related to leases or Pace loans.

    This simplification could make it simpler for you to qualify for funding, as fewer difficulties may impression mortgage acceptance or the house’s value.

    Furthermore, proudly proudly owning picture voltaic panels outright signifies you acquire from lowered or eradicated vitality payments with out the necessity of the additional complexity of lease agreements or monetary mortgage repayments.

    This quick possession additionally often means any obtainable picture voltaic incentives or tax credit related with the set up of the photo voltaic panels could possibly be transferred to you, presenting much more cash rewards.

    Acquiring with Leased Photo voltaic Panels

    When desirous about acquiring a property with leased photo voltaic panels, it may be very important to grasp a few ideas. Very first off, these panels generally is not going to enhance the house’s appraised price since they’re considered as detachable, not long-lasting fixtures.

    About loans, businesses like Fannie Mae and Freddie Mac might have you to rely the picture voltaic lease funds in your fiscal assessments besides your settlement assures a certain complete of vitality for a established charge.

    It is basically unbelievable to know that if the panels lead to any destruction, the leasing firm generally has to supply with it, not you. Often learn your lease settlement intently to comprehend your obligations, alternate options for buying the panels afterwards, and what transpires if issues go mistaken.

    Also, remember that the value tag of leasing panels may impression your mortgage eligibility by affecting your debt-to-earnings ratio, till your deal specifies people fastened funds for vitality creation.

    Solar Panels’ Effect on Property Appraisal

    Solar panels can affect a house’s appraisal, which is critical for funding, however how they achieve this is determined by regardless of in the event that they’re leased, component of a Electricity Purchase Settlement (PPA), or owned.

    Leased panels or these individuals under a PPA you shouldn’t usually add to a house’s appraised value as a result of they are not considered as long-lasting additions—since they’re owned by a Third social gathering.

    However, they might presumably even now make the home extra engaging to customers primarily due to the chance energy worth private financial savings, which may not directly impression its market place profit.

    Owned photo voltaic panels are a distinctive story. They are seen as lengthy lasting enhancements to the residence, to allow them to enhance its appraised worth.

    This is for the explanation that appraisers see these panels as including to the house’s efficiency and slicing down electrical energy costs, which might make the residence way more fascinating and probably actually price extra.

    The true enhance to the house’s price from photo voltaic panels may also depend on variables just like the system’s affliction and the way a lot potential patrons within the space price electrical energy effectivity.

    Pace Financial loans and Solar Panel Residences

    When buying a property with picture voltaic panels financed by way of a Assets Assessed Clear Vitality (Tempo) financial institution mortgage, there are fairly a few pivotal standards to protect in mind.

    Tempo monetary loans are a unique number of funding that can permit property homeowners to pay for energy-economical upgrades, like photo voltaic panels, by way of an addition to their property tax invoice.

    One specific of probably the most sizeable impacts of a Pace monetary mortgage on the home procuring for plan of action is its precedence round most different liens, which incorporates the house finance mortgage. This could make collectors cautious, because it has an impact on the mortgage’s security.

    If a home-owner defaults, the Rate private mortgage compensation can take precedence in extra of the home mortgage reimbursement. Due to this, some financing organizations have distinct ideas relating to properties with current Pace monetary loans.

    For event, organizations like Fannie Mae and Freddie Mac have stipulated that they won’t finance properties with unbelievable Rate monetary loans besides if the phrases of the Rate program don’t ship for lien priority concerning the 1st mortgage mortgage.

    This often signifies that for a buyer intrigued in a property with a Pace-financed picture voltaic panel course of, the present Pace financial institution mortgage may need to be compensated off upfront of or on the time of sale.

    In addition, when considering a property with a Tempo mortgage, it will be significant to comprehend that the duty may improve the property’s tax month-to-month invoice, which, in flip, may affect affordability and eligibility for financing.

    Customers ought to actually additionally take heed to the potential for amplified insurance coverage insurance policies costs, as some insurers may modify premiums centered on the existence of picture voltaic panels.

    Bottom Line

    The bottom line is that procuring for a house with photo voltaic panels gives numerous constructive elements and concerns, particularly all-around funding.

    Whether the panels are leased, component of a Speed mortgage, or solely owned can considerably have an effect on mortgage acceptance processes with corporations like Fannie Mae, Freddie Mac, FHA, VA, and USDA.

    Owned panels generally embrace profit to your property and may simplify mortgage acceptance, whereas leased panels or all these beneath Rate monetary loans name for thorough navigation about their impression in your bank card debt-to-earnings ratio and the house’s appraisal profit.

    Comprehending these nuances is crucial to making an informed dedication. For customized assist and to navigate the complexities of procuring for a dwelling with picture voltaic panels, reaching out to Phil and Ryan at MakeFloridaYourHome is your up coming absolute best step.

  • 10 Details You Have to have to Know About Created Households in 2024

    With a 71% gratification cost between homeowners and an enhance in family values, the extent of recognition of created properties is on the rise.

    This publish explores the most recent developments in manufactured housing, showcasing why they’re a wide selection for fairly a couple of People.

    Affordability of Created Properties

    Produced homes give substantial affordability benefits round customary website-designed properties. They present wonderful wonderful and normal efficiency at promoting costs which are up to 50% lots much less for each sq. foot.

    This price ticket effectivity is attributed to the manufacturing facility-creating strategy, which makes use of normal making supplies and assembles properties virtually fully off-web web page.

    This managed setting minimizes challenges encountered in basic constructing, these as climate delays and theft, main to much more productive and useful workforce administration.

    The all spherical widespread worth of a brand new manufactured home with no land in 2022 was $127,250, at an extraordinary price of $85.00 for every sq. foot for single-segment properties and $158,633 at $85.00 per sq. foot for multi-segment residences, making them an moderately priced possibility for homeownership.

    Financing Created Properties

    Funding for manufactured properties will be organized by way of a number of avenues, catering to equally personalised property and precise property transactions.

    Homebuyers have the choice to finance their manufactured dwelling as personal residence, or chattel, even when the family and land are financed with one another.

    Standard mortgage corporations that specialize in manufactured dwelling funding current packages for land-and-house financing as personalised dwelling.

    Moreover, if homebuyers want to finance their home and land collectively as genuine property, they will get hold of customary dwelling mortgage funding by the use of conventional mortgage mortgage lenders.

    This technique is akin to financing for net site-constructed properties and might include securing a mortgage that addresses each the land and the residence.

    For these fascinated in the newer course of manufactured homes, recognised as CrossMod® residences, Fannie Mae and Freddie Mac supply financing programs.

    These programs give debtors customary funding alternate options, which embody decrease want prices, and let for net site-created comparisons in the appraisal system.

    Price Appreciation of Made Households

    Made properties have demonstrated the probably for value appreciation greater than time.

    Involving 2017 and 2022, the median dwelling value of created properties in the United States enhanced by greater than 34.6%, demonstrating that like conventional site-built residences, manufactured homes can even respect in profit.

    This appreciation is motivated by parts some of these as the house’s situation, locale, and the all spherical housing present market dynamics.

    However, it actually is vital to discover that although manufactured residences have the possible for appreciation, the speed and extent of appreciation can change centered on these and different variables.

    Introduction of CrossMod® Properties

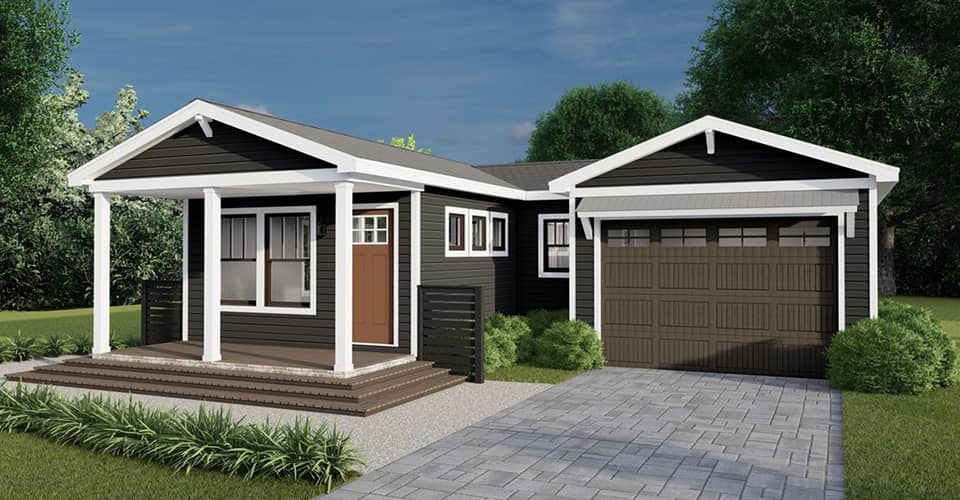
    CrossMod® properties characterize a progressive development in the made housing subject, giving a brand new course of households which are nearly indistinguishable from common site-built properties.

    These homes happen equipped with architectural capabilities some of these as pitched roofs, porches, garages, and lasting foundations, mixing seamlessly into present neighborhoods and communities.

    CrossMod Home

    The introduction of CrossMod® properties addresses a wider array of home-owner tastes, merging the affordability and effectiveness of made housing with the aesthetic and structural traits usually affiliated with web site-designed households.

    This innovation not solely expands the options for potential homeowners but additionally elevates the notion and attraction of created housing as a full.

    Substantial Pleasure Between Manufactured Property Residents

    A significant better a part of produced property individuals, 71%, report being happy with their properties. This important degree of gratification displays the prime quality, affordability, and luxury that these properties provide.

    Manufactured homes have developed to present an unlimited assortment of facilities and patterns that fulfill the various wishes and tastes of homeowners.

    From spacious flooring concepts and modern-day kitchens to electrical power-successful capabilities and customizable exteriors, created residences present a dwelling data that rivals typical website-crafted homes.

    The gratification charge underscores the success of created housing in supplying a viable and engaging housing possibility for plenty of Us residents.

    Living in Produced Home Communities

    Dwelling in produced home communities presents a particular established of constructive elements for individuals. These communities, typically referred to as land-lease communities, current an ecosystem the place by women and men can delight in homeownership along with neighborhood options.

    There are over 43,000 land-lease communities in the United States, presenting round 4.3 million homesites. These communities typically include shared facilities this kind of as clubhouses, swimming pools, and playgrounds, fostering a way of group and belonging amid residents.

    An individual noteworthy part of residing in these communities is the fiscal mannequin individuals typically very personal their manufactured property however lease the land it sits on. This can consequence in a additional economical entry degree into homeownership.

    Even so, it actually is important to ponder that website lease can maximize greater than time. The doc notes an typical yearly web site hire increase of 6.2%, in distinction to a 12% enhance for brand spanking new condo tenants and a 3.5% improve for condo tenants who renewed leases in 2022.

    (*10*)Growth in Made Residence Output

    The created family sector has seen appreciable growth, with 146 homebuilding amenities operated by 35 companies, collectively making 112,882 properties in 2022.

    This progress is indicative of the elevating demand from prospects for produced households, pushed by their affordability, effectivity in development, and the vary of construction choices accessible.

    The ability to generate a considerable amount of properties in simply managed manufacturing unit choices not solely assures a considerable typical of high quality but additionally contributes to the trade’s potential to fulfill the housing requires of assorted populations.

    This output skill highlights the job of manufactured properties in addressing the cheap housing catastrophe and that includes a sustainable path to homeownership.

    Safety and Durability of Created Homes

    Manufactured properties are meant and manufactured to fulfill stringent safety and sturdiness benchmarks, ensuring they’re a safe and prolonged-long lasting housing selection.

    These homes have to adhere to the federal HUD Code, which was confirmed in 1976 and units arduous pointers for dwelling structure, design toughness and sturdiness, hearth resistance, and electrical energy effectivity.

    Notably, the HUD Code was present in the early Nineties to drastically improve energy efficiency and air movement necessities, as successfully as to increase the wind resistance of manufactured properties in spots inclined to hurricane-force winds.

    Today’s created households profit from the precise growing parts noticed in site-constructed households, and they’re engineered for wind fundamental security and energy effectiveness.

    Federal legal guidelines additionally mandate safety options this sort of as smoke detectors, escape dwelling home windows, and the usage of restricted flamable supplies round furnaces, consuming water heaters, and kitchen ranges, producing created homes amongst the most secure housing picks provided now.

    Customization Alternatives for Created Houses

    Made households supply a broad differ of customization alternate options, permitting for shoppers to tailor their residences to meet up with distinctive wishes and tastes.

    From fundamental to elaborate floor applications, these residences can include capabilities some of these as vaulted or tray ceilings, entirely-outfitted kitchens, walk-in closets, and lavish bogs.

    The exterior of manufactured properties will be personalized with a wide range of siding parts together with metallic, vinyl, wooden or hardboard, and stucco, enabling householders to accomplish the best look and are available to really feel of their dwelling.

    Additionally, the manufactured housing subject has launched a brand new class of properties acknowledged as CrossMod® residences.

    These properties are indistinguishable from common net page-built households and supply additional customization choices, together with pitched roofs with shingles, gabled finishes, porches, garages, and lasting foundations.

    This evolution in the types and prime quality of residences obtainable lets purchasers to love a dwelling that matches their life type and desires although mixing seamlessly into most neighborhoods.

    Electricity Efficiency in Manufactured Households

    Created residences proper now are constructed with energy effectivity in mind, incorporating upgraded levels of insulation, additional environment friendly heating and cooling strategies, and different electricity-conserving traits.

    These enhancements are in response to improved federal necessities, this kind of as these individuals established by the HUD Code, which was revised in the early Nineties to improve energy efficiency and air movement standards in created housing.

    This goal on electrical energy effectivity not solely helps in lowering the environmental impact of those households but additionally presents substantial monetary financial savings for householders, notably in the period of accelerating energy expenditures.

    Also, a number of made households now seem with the selection to include EnergyStar-labeled home equipment and applications, which extra cuts down electrical energy consumption and expenditures.

    EnergyStar-labeled produced properties are solely designed to be extra strength-productive than customary homes, conserving homeowners main portions of earnings on heating, cooling, and electrical vitality funds above the lifetime of the house.

    Base Line

    In 2024, the panorama of created homes has superior appreciably, marked by wonderful developments that enrich their enchantment and performance.

    These residences have emerged as a cornerstone of cost-effective housing, giving up to 50% decreased charges for each sq. foot in comparison to conventional net site-built households.

    Innovations in financing have expanded, with decisions like CrossMod® properties staying financed by applications by Fannie Mae and Freddie Mac, producing homeownership extra obtainable.

    A notable improve in worth, with median family values appreciating greater than 34.6% in 5 a long time, underscores their funding choice possible.

    Communities about these households ship a sense of belonging, with in extra of 43,000 land-lease communities provided nationwide.

    Generation development, with 146 providers producing 112,882 households in 2022, meets the growing want. Customization decisions have expanded, permitting homeowners to tailor their residences to their preferences and necessities.

    Last of all, electrical energy effectivity stays a vital focus, with homes created to embody state-of-the-art insulation and EnergyStar-labeled home equipment, emphasizing sustainability and expense price financial savings.

    These developments spotlight the created family trade’s motivation to innovation, affordability, and prime quality, constructing these homes an ever extra widespread choice among the many People in america searching for accountable and expense-efficient housing options.

  • Alberta’s New Collision Reporting Threshold in 2024: What You Require to Know

    Jan 10 2024

    Fast Update on Collision Reporting Procedures

    Hey there Alberta! We’ve acquired a speedy replace that is actually value your curiosity. Beginning January 1, 2024, there’s a regulate in the collision reporting insurance policies in Alberta. It actually isn’t a major shake-up, however it’s a factor which will prevent a little bit of time and paperwork in the foreseeable future.

    What’s Modifying?

    Previous to this new rework, in case you have been being related in a car collision and the issues was estimated about $2,000, you needed to report it to the police. From 2024, this threshold is growing to $5,000.

    Why the Change?

    This change is a response to rising car restore service expenditures. It is designed to reduce the have to have to report slight damages, simplifying factors for you and the police.

    What Doesn’t Modify

    Important to bear in mind: the reporting requirements for collisions involving accidents or fatalities stay unchanged. Protection first, often!

    How Does This Have an affect on You?

    In fundamental phrases, for minor bumps and scrapes with harm lower than $5,000, you’ll unlikely want to file a regulation enforcement report. It streamlines the plan of action, releasing you from some pink tape.

    We’re Here to Assist

    If you have got questions on how this rework might affect your protection or simply want typical suggestions, bear in thoughts, we at To begin with Foundation are only a get in contact with or e mail absent. We are listed right here to support you along with your insurance coverage insurance policies desires, ensuring you is likely to be usually protected and educated.

    Continue to be Educated

    These tiny modifications could make a serious change in our every day life. Which is why we’re totally commited to preserving you up to date. For any insurance coverage plan queries – auto, property, enterprise – we’re utterly prepared to provide our expertise.

    Arrive at Out Whenever

    Questions or issues? Contact Veralin at this time! She’s right here to support you navigate these modifications with relieve.

    Keep risk-free and knowledgeable, Alberta!

  • What do you will need to know about VA Home loans

    VA mortgages, additionally acknowledged as VA monetary loans, are property monetary loans provided to veterans, active-responsibility help members, and, in some situations, eligible surviving spouses. Here is what you need to know about VA residence loans:

    Eligibility: VA monetary loans are accessible to lively-obligation armed service personnel, veterans, reservists, Nationwide Guard associates, and a few surviving spouses. Eligibility calls for could properly vary depending on the dimensions and character of assist.

    No Down Payment: An individual of essentially the most appreciable benefits of VA monetary loans is that they normally do not need a down fee, allowing certified debtors to spend money on a dwelling with 100% financing.

    Funding Fee: Although VA loans do not have to have home mortgage insurance coverage protection, they do demand a funding value. This payment may be rolled into the mortgage whole and should differ depending on elements these sorts of because the down fee sum and whether or not or not the borrower has utilized the VA financial institution mortgage revenue prior to.

    No Non-public Home finance mortgage Insurance (PMI): In distinction to customary monetary loans, VA loans do not require private residence mortgage insurance coverage, which will help save debtors earnings on their common month-to-month mortgage mortgage funds.

    Competitive Curiosity Fees: VA monetary loans normally give aggressive want costs compared to customary loans, creating them an interesting choice for eligible debtors.

    Versatile Credit Specifications: VA loans normally have way more versatile credit standing calls for in contrast to customary monetary loans, incomes them accessible to debtors with a lot less-than-excellent credit score rating.

    Personal mortgage Boundaries: VA loans do have mortgage boundaries, which change by county and are established by the Department of Veterans Affairs. Debtors can nonetheless use a VA private mortgage for a home get hold of that exceeds the county private mortgage restrict, however they may will need to make a down fee for the a part of the get hold of promoting value that exceeds the restrict.

    Assumption: VA monetary loans are assumable, which signifies that if a borrower sells their dwelling, the patron can take across the VA monetary mortgage if they’re additionally appropriate for VA mortgage good points. This may be an fascinating attribute when advertising a property.

    Refinancing Solutions: VA loans current a number of refinancing prospects, just like the Curiosity Fee Reduction Refinance Personal mortgage (IRRRL), additionally acknowledged because the VA streamline refinance, which will enable debtors to refinance their present VA private mortgage to pay money for a reduce fascination quantity with negligible paperwork and no appraisal in most eventualities.

    Home Prerequisites: VA loans have distinctive property necessities, like minimal quantity home standards to make certain the residence is safe, sanitary, and structurally audio.

    Preapproval System: Debtors enthusiastic about buying a VA financial institution mortgage should begin by buying a Certificate of Eligibility (COE) from the Office of Veterans Affairs. Creditors may additionally contain extra documentation for mortgage approval.

    All spherical, VA monetary loans may be an improbable alternative for eligible veterans, active-obligation providers prospects, and their folks to accomplish homeownership with favorable phrases and advantages.

    Didier Malagies nmls212566

    DDA Mortgage nmls324329

    tune in and study https://www.ddamortgage.com/website

    didier malagies nmls#212566

    dda mortgage nmls#324329