Tag: into

  • HSBC makes adjustments to lending into retirement coverage  – House loan System

    HSBC has manufactured variations to its lending into retirement guidelines. 

    The financial institution says its modifications will make the most of to candidates who’re further than 10 a few years from age 70, or their anticipated retirement age, whichever is faster. 

    It now requires affirmation of pension provision to be delivered for these prospects. 

    The small enterprise tells brokers in a observe that when submitting a scenario, the adhering to information ought to actually be integrated: 

    essentially the most present payslip evidencing pension contributions 

    essentially the most new pension assertion 

    affirmation of pension scheme participation or, 

    the most recent lender assertion demonstrating pension funds 

    It supplies that brokers will need to add proof of pension provisions with an software.  

    “Once the method has been aligned with these adjustments, it’s going to rapidly query for these doc(s),” the agency suggests. 

    Pipeline conditions can have to haven’t any even additional motion, besides usually requested for.

  • As more seniors age by your self, could reverse home loans turn into important?

    The property finance mortgage payment pendulum swings however once more

    By Didier Malagies
    •
    18 Apr, 2024

    Anticipate 2024 to be mildly much better than 2023 with home mortgage expenses falling within the second half of the calendar 12 months, housing specialists opined in their forecasts on the shut of the calendar 12 months. Cuts to the Federal money worth (and subsequently to mortgage mortgage premiums) are imminent, merchants enthused following December’s assembly of the Federal Open Market Committee during which committee prospects predicted three price cuts in 2024. Some consultants forecasted as plenty of as 6 cost cuts within the 12 months based mostly totally on this info. Amount cuts are even now coming, simply not in March , merchants and market place professionals reasoned a lot more simply these days because the monetary system continued to run extremely popular. And now on the heels of opinions of more highly effective than anticipated work alternatives progress and stickier than predicted inflation , the market’s change from optimism to pessimism in extra of payment cuts is full. Some even expect price hikes forward of degree cuts. The pessimism is seen in home finance mortgage costs. Freddie Mac‘s weekly Major Home mortgage Industry Study is climbing once more in course of seven%. HousingWire’s House mortgage Charge Heart , which depends on information from Polly, is presently beforehand talked about 7.2%. Costs had been as diminished as 6.91% for Polly and 6.64% for Freddie as these days as February. On Tuesday, they arrived at 7.50% on Home finance mortgage News Every day, a big for this 12 months. Mortgage charges maintain massive electrical energy within the housing discipline most significantly, giant prices exacerbate the latest affordability disaster by walloping the buying electrical energy of would-be shoppers and discouraging some would-be sellers – these folks with decrease, mounted-amount mortgages – from itemizing their homes, a drain on obtainable inventories. All this leaves housing professionals on the time yet again stopping for his or her share of shrinking pies – as we’ve got seen with these days launched property finance mortgage details and RealTrends Verified’s brokerage details , as completely as additional dives on the brokerage landscapes in Jacksonville and San Diego . It is unsurprising, then, that genuine property shares have suffered because the FOMC’s March assembly and the latest occupation and inflation research. That options the nation’s prime rated homebuilders (DR Horton and Lennar), home finance mortgage originators (United Wholesale Home finance mortgage and Rocket House mortgage), brokerages (Any place and Compass) and residential search for portals (Zillow and CoStar, which owns Residences.com). There are different dynamics at carry out for a few of these organizations, nevertheless. The brokerages are additionally contending with the rule modifications included in a proposed settlement by the National Affiliation of Realtors some merchants additionally suppose these rule enhancements edge CoStar on the expense of Zillow . UWM, in the meantime, is contending with a scathing investigative report by a hedge-fund-affiliated information enterprise whose hedge fund shorted UWM and went very lengthy on Rocket additionally it is working with pending litigation . UWM denies the allegations created within the report.  Large home finance mortgage premiums, much less mortgage mortgage functions and fewer home income are regretably not the one outcomes housing professionals could see from a more prolonged superior-charge ecosystem. There are additionally spillover penalties from different industries, primarily workplace true property. Regional banking establishments – which usually have been vital residential mortgage mortgage originators – went massive on industrial severe property monetary loans as a lot bigger banks scaled again on this place in latest many years. That enhanced their publicity to downtown office towers, which have seen an exodus of tenants and a bottoming out of appraised values simply as a report $2.2 trillion in industrial real property private debt comes due more than the next a number of a very long time. That ties up funds that could usually transfer to family mortgages and in some eventualities stresses banks like New York Group Bank, dad or mum of Flagstar Lender — the Seventh-premier monetary establishment originator of residential mortgages, Fifth-major sub-servicer of property finance mortgage monetary loans and the 2nd-largest home finance mortgage warehouse mortgage supplier within the place. Homebuilders, far too, come to really feel the outcomes of prolonged vital premiums. Though homebuilder self-confidence is even now up significantly since last drop, new housing begins are slowing . The dim prospects for homebuyers have turned some buyers to the nascent make-to-lease sector , primarily a wager that giant charges are on this article to stay for lengthy loads of that would-be potential consumers at the moment are would-be renters.

  • 1 in 6 retirees is taking into consideration a return to the workforce

    (*1*)

    One in six U.S. retirees is a return to the workforce, with most citing both customized or fiscal elements as the driving energy, in accordance to a new survey from Paychex

    The survey — which included 930 American personnel and 206 selecting directors — illustrates the number of individuals returning to function instantly after retirement and descriptions the causes why they’re producing these strikes.

    The closing outcomes additionally point out that the the better a part of these a return to the workforce would need distant or hybrid positions.

    “Among these individuals we surveyed, 1 in six retirees are excited about returning to operate after presently being out of the workforce for a mean of 4 a few years,” the research report states. “With so a lot of preferring to operate from property these occasions, it is no shock that rather more than 50 p.c of our retired respondents would search for distant get the job carried out (53%), 27% need a hybrid scenario, and solely 20% would seek for an office profession.”

    The report additionally demonstrates that 65% of respondents need whole-time function, despite the fact that 35% need to do the job on a element-time basis.

    About 57% of the respondents who need to return to carry out cited “private causes” as 1 of the elements, though 53% cite “monetary causes” as a driving stress for looking for to return to do the job.

    In addition, 52% cited boredom as a motivator for looking for to return to the workforce, although 43% of respondents cited inflation. Yet one other 43% well-known loneliness as a function for looking for to return to do the job.

    Per the report, 62% of respondents have presently returned to work after retirement, and about 55% of all those that have returned to the workforce said they did so as a result of they wished a lot extra cash.

    About 60% of respondents clarify expertise content material about their closing resolution, despite the fact that respondents additionally defined sensation “energized” (50%) and “excited” (48%) about returning to do the job. Additionally, some talked about sensation “resigned” (33%) or “anxious” (30%) about the willpower.

    However, a huge proportion of retirees who returned to function mentioned they felt judged by co-staff for his or her selection.

    “The mind-boggling bulk of retirees who returned to work have confronted judgment from their co-workers (74%) solely 3% haven’t,” the report states. “Most of individuals performing in finance (87%), education (83%), and data applied sciences (72%) have expert these sorts of discrimination.”

    According to the retirees, one type of ageism they expertise they’re coping with is due to to making youthful personnel sense insecure about their abilities. And, extra mature personnel are an fascinating prospect for using directors primarily owing to their information degree, in accordance to 56% of using supervisor respondents.


    Outcomes from a survey launched closing month indicated that the significant-inflation setting is ensuing in staff to drive retirement choices — earlier, present and upcoming — to the aspect to determine how considerably {dollars} is crucial to go over rising bills.

    Most Associated (*6*)

  • Should I consolidate my student loans into a refinance

    The home mortgage charge pendulum swings however once more

    By Didier Malagies
    •
    18 Apr, 2024

    Expect 2024 to be mildly higher than 2023 with property finance mortgage prices falling within the 2nd 50 % of the 12 months, housing consultants opined in their forecasts on the conclude of the calendar yr. Cuts to the Federal sources degree (and subsequently to property finance mortgage prices) are imminent, merchants enthused proper after December’s meeting of the Federal Open Market Committee during which committee members predicted three worth cuts in 2024. Some gurus forecasted as a number of as 6 degree cuts within the 12 months depending on this information. Level cuts are proceed to coming, simply not in March , merchants and market professionals reasoned much more not too long ago because the financial local weather ongoing to function scorching. And now on the heels of experiences of extra strong than predicted work alternatives growth and stickier than anticipated inflation , the market’s change from optimism to pessimism above degree cuts is full. Some even hope worth hikes previous to quantity cuts. The pessimism is seen in residence mortgage charges. Freddie Mac‘s weekly Major Mortgage Market Study is climbing again once more within the path of seven%. HousingWire’s Mortgage Fee Centre , which depends on particulars from Polly, is presently increased than 7.2%. Rates had been as very low as 6.91% for Polly and 6.64% for Freddie as not way back as February. On Tuesday, they reached 7.50% on Mortgage Information Each day, a vital for this 12 months. Mortgage mortgage prices keep main vitality within the housing enterprise most significantly, excessive costs exacerbate the present affordability catastrophe by walloping the searching for electrical energy of would-be shoppers and discouraging some would-be sellers – these folks with small, fixed-level mortgages – from itemizing their households, a drain on on the market inventories. All this leaves housing trade consultants as quickly as over again combating for his or her share of shrinking pies – as we have now observed with currently launched mortgage mortgage particulars and RealTrends Verified’s brokerage particulars , as very nicely as deeper dives on the brokerage landscapes in Jacksonville and San Diego . It is unsurprising, then, that critical property shares have skilled for the reason that FOMC’s March assembly and the the most recent profession and inflation research. That incorporates the nation’s main homebuilders (DR Horton and Lennar), residence mortgage originators (United Wholesale Home finance mortgage and Rocket Mortgage mortgage), brokerages (Everywhere and Compass) and family search portals (Zillow and CoStar, which owns Properties.com). There are different dynamics at play for a few of these organizations, however. The brokerages are additionally contending with the rule changes built-in in a proposed settlement by the Nationwide Affiliation of Realtors some consumers additionally really feel these folks rule variations profit CoStar on the expense of Zillow . UWM, in the meantime, is contending with a scathing investigative report by a hedge-fund-affiliated information group whose hedge fund shorted UWM and went prolonged on Rocket it’s also working with pending litigation . UWM denies the allegations produced within the report.  Substantial mortgage mortgage costs, a lot much less property finance mortgage applications and fewer property product gross sales are sadly not the one penalties housing gurus might see from a extra prolonged superior-amount setting. There are additionally spillover outcomes from different industries, primarily administrative center genuine property. Regional banks – which traditionally have been essential residential residence finance mortgage originators – went vital on skilled critical property monetary loans as extra substantial monetary establishments scaled again once more on this space in newest a very long time. That larger their publicity to downtown workplace towers, which have observed an exodus of tenants and a bottoming out of appraised values simply as a file $2.2 trillion in skilled actual property debt comes due in extra of the subsequent couple of years. That ties up cash that would if not motion to residential mortgages and in some situations stresses banking corporations like New York Local neighborhood Lender, dad or mum of Flagstar Lender — the Seventh-premier financial institution originator of residential residence loans, Fifth-biggest sub-servicer of residence mortgage loans and the 2nd-premier residence finance mortgage warehouse mortgage firm within the state. Homebuilders, as nicely, actually really feel the outcomes of extended massive charges. Although homebuilder assurance is even now up noticeably since closing tumble, new housing commences are slowing . The dim potential consumers for homebuyers have turned some merchants to the nascent establish-to-rent sector , primarily a guess that substantial prices are listed right here to stay for lengthy enough that would-be shoppers are actually would-be renters.

  • Just 1 in 10 seniors look into reverse home loans if they cannot afford senior care

    (*1*)

    The home mortgage value pendulum swings however once more

    By Didier Malagies
    •
    18 Apr, 2024

    Anticipate 2024 to be mildly improved than 2023 with mortgage mortgage prices slipping in the second 50 % of the yr, housing professionals opined in their forecasts on the finish of the 12 months. Cuts to the Federal money degree (and subsequently to home mortgage costs) are imminent, merchants enthused simply after December’s meeting of the Federal Open Current market (*10*) in which committee members predicted three payment cuts in 2024. Some authorities forecasted as a number of as six value cuts in the 12 months primarily based totally on this information. Level cuts are even now coming, simply not in March , merchants and market place professionals reasoned extra these days because the financial local weather continued to run scorching. And now on the heels of experiences of extra strong than predicted work progress and stickier than anticipated inflation , the market’s shift from optimism to pessimism in extra of payment cuts is full. Some even rely on cost hikes proper earlier than payment cuts. The pessimism is seen in home mortgage prices. Freddie Mac‘s weekly Primary Home mortgage Industry Study is climbing once more in direction of 7%. HousingWire’s House mortgage Charge Middle , which is dependent upon details from Polly, is now above 7.2%. Rates have been as minimal as 6.91% for Polly and 6.64% for Freddie as a short time in the past as February. On Tuesday, they arrived at 7.50% on Mortgage News Every day, a considerable for this 12 months. Mortgage fees maintain important electrical energy in the housing business most significantly, substantial prices exacerbate the latest affordability disaster by walloping the buying electrical energy of would-be customers and discouraging some would-be sellers – these with low, set-price home loans – from itemizing their households, a drain on on the market inventories. All this leaves housing professionals on the time but once more stopping for his or her share of shrinking pies – as now we have observed with not way back launched mortgage data and RealTrends Verified’s brokerage information , in addition to deeper dives on the brokerage landscapes in Jacksonville and San Diego . It is unsurprising, then, that precise property shares have skilled as a result of reality the FOMC’s March convention and the trendy job and inflation evaluations. That incorporates the nation’s main homebuilders (DR Horton and Lennar), mortgage mortgage originators (United Wholesale Property finance mortgage and Rocket Home finance mortgage), brokerages (Any place and Compass) and family analysis portals (Zillow and CoStar, which owns Residences.com). There are different dynamics at interact in for a few of these corporations, nonetheless. The brokerages are additionally contending with the rule adjustments included in a proposed settlement by the National Affiliation of Realtors some patrons additionally really feel these rule changes edge CoStar on the expenditure of Zillow . UWM, in the meantime, is contending with a scathing investigative report by a hedge-fund-affiliated information enterprise whose hedge fund shorted UWM and went in depth on Rocket it is usually coping with pending litigation . UWM denies the allegations designed in the report.  Superior property finance mortgage fees, much less home mortgage apps and far much less family income are unhappy to say not the one outcomes housing specialists may see from a further extended higher-amount setting. There are additionally spillover penalties from different industries, notably workplace surroundings real property. Regional banking firms – which traditionally have been massive residential home mortgage originators – went huge on skilled genuine property loans as bigger banking establishments scaled again once more in this area in new yrs. That elevated their publicity to downtown enterprise towers, which have seen an exodus of tenants and a bottoming out of appraised values simply as a file $2.2 trillion in industrial true property bank card debt will come due in extra of the long run couple of a few years. That ties up cash that would usually stream to residential home loans and in some conditions stresses banking firms like New York Neighborhood Financial establishment, father or mom of Flagstar Bank — the Seventh-major monetary establishment originator of family mortgages, Fifth-largest sub-servicer of mortgage monetary loans and the 2nd-greatest home mortgage warehouse mortgage supplier in the state. Homebuilders, too, sense the outcomes of extended superior costs. Whilst homebuilder self-assurance is however up noticeably as a result of final fall, new housing begins are slowing . The dim potential prospects for homebuyers have turned some buyers to the nascent build-to-rent sector , basically a guess that important costs are under to stay for very lengthy enough that would-be patrons are actually would-be renters.

  • Ginnie Mae fights endeavours to deliver APA into Texas Capital go well with

    Ginnie Mae submitted a solution to Texas Funds Bank’s partially dismissed grievance in federal district court docket docket final 7 days, arguing versus TCB’s allegations that it violated the Administrative Procedure Act.

    Ginnie pushed once more in the direction of assertions that its seizure of collateral allegedly promised to the financial institution in return for giving tens of tens of tens of millions of kilos in funding was “in further of statutory authority” in a submitting in Texas’ Northern District.

    The federal authorities company argued that the act “doesn’t authorize the award of monetary damages” and stated that an APA declare should be barred primarily due to the financial institution’s “failure to exhaust its administrative cures.”

    Ginnie reiterated requests for a dismissal of the scenario submitted in Texas’ Northern District, noting that it “acknowledges that the plaintiff requests the help” however “denies that it’s entitled to it.”

    The firm additionally doubled down on repudiating guarantees it made chosen ensures to TCB in its newest response to the financial institution’s criticism from earlier Oct.

    In that grievance, the lender alleged “senior Ginnie Mae reps, which incorporates [retiring] President [Alanna] McCargo explicitly assured TCB that it could be repaid” and that the rights to certain reverse home mortgage property ended up part of that association.

    TCB delivered the funding in conjunction with Reverse Mortgage Funding’s chapter and Ginnie seized RMF’s servicing rights in late 2022.

    Specifically at difficulty within the scenario are authorized rights linked with “tails,” or the dollars-flows from attracts extra mature older folks make on household-fairness withdrawal monetary loans quickly after the primary disbursement will get securitized. Texas Cash said it could not have agreed to provide financing with no these rights.

    Although Ginnie has a historic previous of working with the sector to a diploma on coverage, it truly is beneath a considerable amount of stress to shield the restricted funding it really works by utilizing to shield a multi-trillion-dollar worldwide securitization market from threat when 1 of the house mortgage organizations it operates with fails, notably now.

    Currently, the Division of Housing and City Development’s Inspector Standard is investigating Ginnie’s dealing with of RMF’s chapter, and has identified that “extinguishing issuers and seizing their portfolios locations main fear on Ginnie Mae’s operations.”

    Ginnie is a part of HUD, and reverse residence loans are a tiny however influential subset of the securitizations Ginnie ensures and different organizations once more on the monetary mortgage diploma. The model of those monetary loans positioned in Ginnie Mae securitizations are recognised as House Fairness Conversion Home loans. An further arm of HUD, the Federal Housing Administration, insures HECMs as loans.

    A restricted quantity of gamers are included within the reverse home mortgage sector, which may complicate Ginnie’s carry out when a failure happens, considerably when costs are risky. The company normally depends on open air home mortgage companies to ensure securitized private mortgage cash-flows get to traders.

    There has been some broader pressure between Ginnie and the trade above collateral authorized rights in economical preparations.

    Market advocates have constantly questioned that Ginnie alter contractual rights in these preparations further of their favor, even simply after a few of its leaders like former President Ted Tozer have created makes an try to make the agreements extra equivocal.

    TCB and Ginnie don’t present up to have used a typical settlement however alternatively had negotiated the phrases of the sudden emergency financing.

    A decisive ruling within the Texas Money Lender lawsuit won’t unfold proper after the federal election this drop, with the timeline for factual discovery established to stick with it into subsequent calendar yr.

  • Cherry Hill taking into consideration merger or asset sale

    Cherry Hill Home mortgage Expenditure Corp. concepts to “check out strategic potentialities,” which may closing end in a possible merger or sale. 

    The board of administrators on the Farmingdale, New Jersey-dependent actual property monetary funding place confidence in will construct a committee to glimpse at a whole differ of selections aimed toward maximizing shareholder profit. Among the choices remaining explored are a merger, product gross sales of all or element of the corporate’s belongings or “an internalization of the administration of the enterprise,” Cherry Hill talked about in a push launch.

    The distinctive committee will include neutral and disinterested administrators and intends to consider all potential potentialities, the enterprise well-known. Guggenheim Advisors is giving economical steering and abilities to the committee.

    “There might be no assurance that the exploration of strategic alternate choices will consequence in any transaction or different strategic closing consequence,” Cherry Hill talked about. No timeline for a closing consequence was arrange, nor will developments be disclosed till ultimately analysis has been accomplished or the committee deems it wanted.   

    The REIT, which was initially launched as a publicly traded enterprise in 2013 by means of a strategic alliance partnership with Flexibility Home mortgage, acquires, invests in and manages residential lending belongings, which embody servicing rights and agency- and nonagency-backed securities. 

    Considering the truth that its inception, the enterprise has been led by CEO and President Jay Lown, who additionally sits on the board of directors. Also at the moment serving as neutral directors on the Cherry Hill board are Sharon Lee Prepare dinner, Robert Mercer Jr. and Joseph Murin.

    After closing at $3.30 on Friday, shares of Cherry Hill inventory initially spiked in pre-market exercise pursuing the announcement, proper earlier than opening at $3.38 on Monday. The inventory’s profit rose to $3.50 by noon. Around the sooner 12 months, the closing worth has fluctuated involving $2.77 and $5.53, which it strike just about a yr again. 

    At the end of 2023, the company held $20 billion worthy of of unpaid balances inside its book of mortgage mortgage servicing rights and $1.4 billion in investable belongings. In the fourth quarter, Cherry Hill additionally posted a $35.5 million net loss, proper after a $20.5 attain 3 months beforehand. 

    The hottest announcement from Cherry Hill will come throughout a prolonged prolong of consolidation throughout the property finance mortgage sector, because it tries to rightsize in response to slowing lending train. When quite a few of the specials have included originators and know-how corporations, the REIT phase has additionally figured into affords, which embody a merger amongst Ellington Financial and Fantastic Ajax Corp. final summer time. Targeted acquisitions of residence loan-servicing authorized rights portfolios have additionally come into take part in.

    Cherry Hill will not be the one REIT discovering a restructuring. Rithm Cash, mum or dad company of residential monetary establishment Newrez, filed obligatory paperwork for a attainable separation of its mortgage mortgage features into its personal publicly traded entity within the 2nd quarter earlier calendar 12 months. 

    Like any potential foreseeable future go at Cherry Hill, the proposed rework was aimed toward growing shareholder worth, Rithm leaders reported on the time. But the group has additionally actively shifted a few of its focus over the previous many months to create itself as an substitute asset supervisor.

  • New inquiry into Initial Nations company chances launches

    New inquiry into 1st Nations enterprise chances launches | Australian Broker Information

    Information

    New inquiry into Initially Nations enterprise enterprise choices launches

    Boosting monetary autonomy for Indigenous corporations

    New inquiry into First Nations business opportunities launches

    The Joint Standing Committee on Aboriginal and Torres Strait Islander Affairs (JSCATSIA) has launched an inquiry centered on enhancing the monetary self-dedication and choices for Initially Nations Australians.

    The initiative seeks to look at instruction, work, and enterprise enhancement chances whereas growing the essential infrastructure to foster extensive-expression monetary prosperity.

    Advancement and results of Initially Nations companies

    The sector presently consists of about 12,500 enterprises which might be outpacing the revenue growth of the broader SME sector.

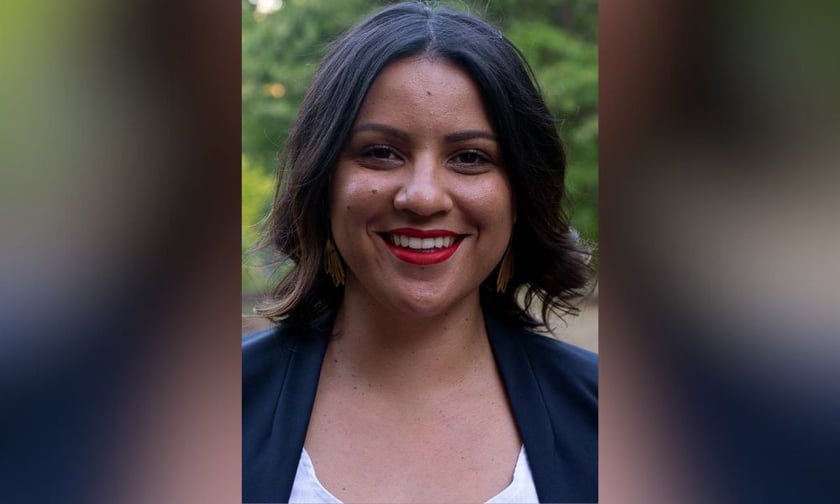
    “Aboriginal and Torres Strait Islander companies have been exceeding all expectations,” claimed Mutthi Mutthi and Wamba Wamba Senator Jana Stewart (pictured above), chair of the committee.

    Stewart highlighted the essential but typically forgotten impacts these corporations have on every the To begin with Nations communities and the broader Australian monetary system.

    In accordance to newest stories, these enterprises have seen extraordinary boosts in portions, money move, and work growth, contributing on the very least $4.88 billion to Australia’s general financial system.

    “It is mainly crucial that we examine the prospects for enhanced teaching, employment, and enterprise enhancement to assist the Aboriginal and Torres Strait Islander trade and construct financial, social, and cultural added advantages,” Stewart said.

    JSCATSIA telephone for submissions

    JSCATSIA invitations submissions from features by May maybe 24, to accumulate various views on fostering monetary independence in Initially Nations communities. Even extra particulars with reference to the inquiry, along with situations of reference and submission guidelines, are on the market on the JSCATSIA internet web page.

    Get the most well-liked and freshest home mortgage information despatched proper into your inbox. Subscribe now to our FREE every day publication.

    Continue to maintain up with the latest info and actions

    Be a part of our mailing itemizing, it’s completely free!