Tag: interest

  • The real truth about existing interest rates

    &#13
    &#13

    You’ve doable listened to fashionable information about mounting need costs. No matter whether or not it’s your credit standing card need fee, or the worth tag to finance a property, the cost to borrow income has been escalating. Nevertheless, while there isn’t any doubt that need premiums are greater than they’ve been within the earlier two a few years, it’s essential to take a look at growing fascination charges from a broader, extra historic level of see.

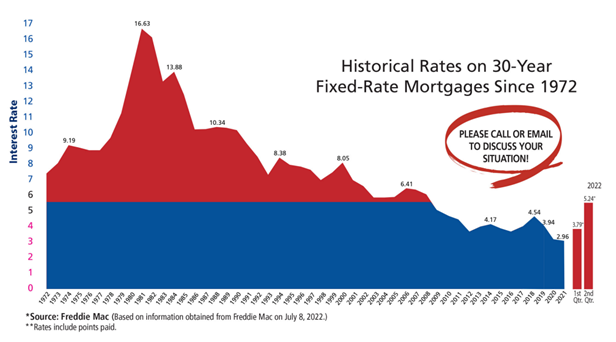
    Mortgage backed securities large, Freddie Mac has collected and revealed data on typical weekly home mortgage fascination costs as a result of reality the early Seventies. With nearly 50 a very long time of knowledge, this snapshot of the rise and slide of dwelling mortgage interest prices provides a efficient snapshot of how prices have fluctuated. The greatest think about away once you search at prices across the final nearly 50 percent-century? Prices are nonetheless traditionally decreased.

    A look to the previous

    Over this system of the previous 49 a number of years, the standard fascination stage has usually hovered earlier talked about 5%. Freddie Mac recorded the utmost need value at 16.63 in 1981. Since then, fascination charges have been on a downward slope, with periodic spikes. It was not till finally the burst of the housing bubble within the mid-2000s, and the following recession, that we seen need charges drop down beneath 5%. Given that then, we now have seen need costs hover at unparalleled lows. As the financial system recovered, the Federal Reserve little by little began inching interest premiums higher. By 2019, interest premiums had been being ticking nearer to the 5% vary. Nonetheless, with the onset of the pandemic, fascination prices significantly dropped once more, foremost to the extremely decreased fascination prices we professional by 2020 and 2021.

    Where by we are actually

    More than the previous variety of months, we now have all felt the impacts of inflation. Rates have elevated and no matter whether or not it’s the entire of our weekly groceries to a tank of gasoline, quite a few objects and services value much more, along with the worth tag to borrow money. Even so, it is very important maintain in mind, that although it could probably be way more dear to finance a mortgage than it was a 12 months previously, rates are nevertheless extremely very low when versus the historic common. Homebuyers could probably even now have the prospect to accumulate a house at a reasonable charge and start developing fairness.

    Mortgage mortgage options for a climbing value ambiance

    In a rising curiosity charge setting, quite a few homebuyers could maybe seek for financing strategies constructed to help enhance their purchasing for energy and make certain they protected the bottom cost accessible to them. At Evergreen Home Loans™ we offer a assortment of options which are successfully suited to satisfy up with this goal. We’ll operate with you to completely grasp your private home funding necessities and current you with dwelling finance mortgage choices which are customized to you. With quite a lot of adjustable-rate mortgages and a collection of revolutionary options, we’re very properly geared up to assist you leverage your buying means and allow you protected an very reasonably priced curiosity cost. If you’d wish to see what financial institution mortgage decisions are on the market to you, entry out to simply certainly one of our proficient financial institution mortgage officers right now to find additional.

    &#13

  • can you lock in your interest charge?

    U.S. mortgage holders submit file ranges of residence fairness: ICE

    By Didier Malagies
    •
    15 May, 2024

    U.S. residence costs continued to climb in March as a persistent scarcity of houses on the market helped to buoy the housing market, in accordance with the Intercontinental Exchange (ICE) Home Price Index. And whereas potential homebuyers address the challenges of rising housing unaffordability, current householders are reaping the advantages of traditionally sturdy value positive aspects. Nationwide fairness on mortgaged houses soared to a file $16.9 trillion in the primary quarter of 2024, with $11 trillion accessible for leverage whereas sustaining a 20% fairness cushion — additionally an all-time excessive. The ICE index confirmed that residence costs elevated by a seasonally adjusted 0.42% month over month in March, marking the third consecutive month of above-average value positive aspects, though this was a slight pullback from February’s 0.58% improve. On an annual foundation, residence value progress eased barely in March to five.6%, under the upwardly revised acquire of 6% in February. “The latest pattern of rising interest charges has dampened homebuyer demand and allowed the stock of houses on the market to enhance,” Andy Walden, ICE’s vice chairman of enterprise analysis technique, mentioned in an announcement.  “We’re nonetheless very a lot in a gap from a list perspective, however that deficit has fallen from 50% a yr in the past to 38% in March. Today, with 3.3 months of provide, stock continues to be traditionally low and indicative of a vendor’s market. This helps to maintain residence value progress resilient though

  • What are the interest charges?

    U.S. mortgage holders put up file ranges of residence fairness: ICE

    By Didier Malagies
    •
    15 May, 2024

    U.S. residence costs continued to climb in March as a persistent scarcity of houses on the market helped to buoy the housing market, in response to the Intercontinental Exchange (ICE) Home Price Index. And whereas potential homebuyers address the challenges of rising housing unaffordability, present householders are reaping the advantages of traditionally sturdy worth beneficial properties. Nationwide fairness on mortgaged houses soared to a file $16.9 trillion in the first quarter of 2024, with $11 trillion out there for leverage whereas sustaining a 20% fairness cushion — additionally an all-time excessive. The ICE index confirmed that residence costs elevated by a seasonally adjusted 0.42% month over month in March, marking the third consecutive month of above-average worth beneficial properties, though this was a slight pullback from February’s 0.58% improve. On an annual foundation, residence worth progress eased barely in March to five.6%, under the upwardly revised acquire of 6% in February. “The latest pattern of rising interest charges has dampened homebuyer demand and allowed the stock of houses on the market to enhance,” Andy Walden, ICE’s vp of enterprise analysis technique, stated in a press release.  “We’re nonetheless very a lot in a gap from a listing perspective, however that deficit has fallen from 50% a yr in the past to 38% in March. Today, with 3.3 months of provide, stock remains to be traditionally low and indicative of a vendor’s market. This helps to maintain residence worth progress resilient regardless that

  • Weekly Mortgage Refinances Fall As Interest Rates Suddenly Turn Higher


    Jordan Borchard posted in

    Housing in Housing News

    Weekly Mortgage Refinances Fall As Interest Rates Suddenly Turn Higher

    Written by: Diana Olick

    A sudden turnaround from file low rates of interest final week triggered a pullback in mortgage refinance demand.

    That pulled complete mortgage software quantity down 3.3% from the earlier week, in keeping with the Mortgage Bankers Association’s seasonally adjusted index.

    The common contract rate of interest for 30-year fixed-rate mortgages with conforming mortgage balances ($510,400 or much less) elevated relatively abruptly to three.13% from 3.06%,. Points together with the origination price rose to 0.36 from 0.33 for loans with a 20% down fee.

    “Positive financial knowledge reported final week on retail gross sales, in addition to a big U.S. Treasury public sale, drove mortgage charges to their highest degree in two weeks,” mentioned Joel Kan, an MBA economist.

    The rise in charges triggered refinance demand to drop 5% for the week however was 38% greater than a 12 months in the past. That annual achieve continues to shrink. Last month, refinance demand was greater than 100% greater than a 12 months in the past.

    The distinction now’s that rates of interest are narrowing the hole to the place they had been a 12 months in the past. While they had been a full proportion level decrease yearly final month, they’re now 77 foundation factors decrease, making fewer debtors in a position to profit from a refinance.

    Mortgage purposes to buy a house elevated simply 1% for the week however had been a outstanding 27% greater in contrast with a 12 months in the past. This marks three straight months of annual good points for buy purposes.

    Demand for housing continues to swell, held again solely by the extreme scarcity of houses on the market. Homebuilders are ramping up manufacturing, and mortgage purposes for newly constructed houses are surging even greater.

    “The housing market stays a brilliant spot within the present financial restoration, and these outcomes, mixed with July knowledge on housing begins and homebuilder optimism, counsel that housing provide may very well be growing to raised meet the robust demand for getting a house,” Kan mentioned.

    Mortgage charges pulled again barely to start out this week. The improve final week was due partially to a rise in lender charges levied by Fannie Mae and Freddie Mac. As lenders settle into that new regular, they’re falling again consistent with Treasury yields.


  • Federal Reserve approves interest level hike of 50 percent a share position What does that necessarily mean for mortgage prices?

    The Federal Reserve Wednesday permitted a 50 basis place enhance to its coverage fascination level in an work to cut back inflation, along side a plan to shrink its $9 trillion asset portfolio starting up coming thirty day interval, in accordance to Chairman Jerome Powell.

    Through a information assembly subsequent the Fed’s committee meeting, Powell launched the enhance and outlined the Fed’s plan to begin “the method of appreciably minimizing the measurement of our stability sheet,” he talked about.

    “It is important that we offer inflation down if we’re to have a sustained interval of strong labor present market issues that profit all,” Powell mentioned. “The latest {photograph} is obvious to see: The labor sector is extraordinarily restricted and inflation is way manner too massive. Against this backdrop, at the moment the FOMC elevated its plan curiosity price by a 50 percent share situation and anticipates that ongoing will increase within the concentrate on value for the federal sources fee shall be appropriate.”

    Authorities say Wednesday’s go wasn’t a shock.

    “This modify had been telegraphed clearly in new speeches,” claimed Mike Fratantoni, principal economist for the Mortgage Bankers Association. In the course of the announcement, Fratantoni additionally designed observe of Powell’s warning that the committee “anticipates that ongoing will enhance within the concentrate on selection shall be applicable.”

    “In different phrases and phrases, we’re considerably from carried out at this position,” claimed Fratantoni. “MBA forecasts that the Fed money concentrate on will attain 2.5%, the impartial cost, by the end of 2022.”

    (*50*) the the most recent price hike from the Federal Reserve, the continuing warfare in Ukraine and ongoing financial restoration pursuing the pandemic, mortgage mortgage lenders throughout the state are taking care of a unstable housing market. Understand how updating your own home finance mortgage know-how stack can help you get prematurely in at present’s unpredictable lending environment

    Introduced by: Polly

    As data of the Fed’s closing resolution circulated, the S&P 500, Dow and Nasdaq all rose and extended positive factors when Realtors, private mortgage officers, property finance mortgage brokers and different subject business specialists deemed the quick ramifications on the housing sector.

    Danielle Hale, chief economist for Realtor.com, talked about the 2 go hand in hand.

    “Mortgage charges are an very important channel by means of which Fed coverage has an impact on the true economic system. In different textual content, the Fed’s selections impact household budgets, steadiness sheets, and expending choices by means of their results on interest charges like residence finance mortgage premiums. With residence finance mortgage premiums climbing, up 2 share elements previously 4 months, the financial circumstances dealing with residence shoppers have shifted in a important manner,” Hale outlined.

    She additionally noticed inflation is “working on the highest fee in 40-as nicely as yrs, placing it at a life span excessive for most millennials and younger generations.” But, she concluded, Wednesday’s “vote by itself will not be more likely to spark a new surge in home mortgage charges.”

    Fratantoni defined MBA expects home mortgage charges will plateau in shut proximity to present ranges.

    “The monetary markets have tried to price within the impression of Fed actions over this cycle, and they’re doubtless additionally pricing within the monetary slowdown that will consequence,” Fratantoni acknowledged. “Once we’re earlier this value spike and concerned volatility, MBA expects that alternative homebuyers might be way more keen to re-enter {the marketplace}. Provided how a nice deal elevated charges will carry on being greater than the sooner 20 years, we don’t expect refinance want to extend any time shortly.”

    Despite delivering higher-stage, nuanced particulars on the Fed’s strategy, Powell first made distinct the announcement wasn’t geared toward such sector specialists. He began his sort out by indicating he wished to converse proper to the American group.

    “Inflation is way as nicely substantial. We perceive the hardship it’s resulting in and we’re shifting expeditiously to offer it again once more down,” Powell talked about all via the information conference. “We have equally the instruments we have to have and the clear up that it is going to purchase to revive worth stability on behalf of American households and enterprises.”

    “Our overarching goal is using our sources to ship inflation once more all the way down to our 2% purpose. With regard to our stability sheet, we additionally issued our exact designs for chopping down our securities holdings. Dependable with the ideas we issued in January, we intend to drastically decrease the scale of our equilibrium sheet greater than time in a predictable technique,” Powell acknowledged. “We’ll be prepared to control any of the main points of our technique in gentle of financial and cash developments.”

    Powell defined “after increasing at a sturdy 5.5% tempo final yr, over-all financial motion edged down within the very first quarter.” But, he reported the labor market has ongoing to strengthen, inspite of inflation remaining “nicely earlier talked about our lengthier function purpose of 2%.”

    “In March the unemployment quantity strike a write-up-pandemic and in shut proximity to-five-10 years very low of 3.6%,” Powell reported, touting the nation’s improvement.

    After speaking about how Russia’s invasion of Ukraine is influencing world large problems, Powell defined: “Our job is to take a look at the implications for the U.S. monetary state — which proceed to be very not sure.”

    The ongoing invasion is anticipated to restrain financial exercise overseas and can proceed to have an impact on the worldwide provide chain, he mentioned.

    “Our coverage has been adapting and it’ll proceed to take action,” Powell reported.

    Supplemental 50 bps will enhance “must be on the desk on the subsequent pair of conferences,” he claimed.
    Powell additionally outlined “the financial system usually evolves in sudden strategies,” and famous that inflation has “clearly shocked” some all via the sooner yr. Powell then warned, “additional surprises might be in retailer.”

    But that does not necessarily mean all of the issues is unpredictable.

    Skylar Olsen, the principal economist at Tomo, additionally claimed the switch was “already anticipated by the present market, however (it was) nonetheless the key enhance in a few years. The coming week will carry with it interest cost volatility, however early indicators of {the marketplace} response have charges slipping, not capturing up,” she talked about.

    No matter, Powell mentioned the Fed’s focus stays the have an effect on that this kind of choices have on frequent Individuals.

    “We subsequently will wish to be nimble … and we’ll try to forestall introducing uncertainty to what’s beforehand an an terribly tough and unsure time,” he reported.

    “The Fed’s financial protection actions are guided by our mandate to promote highest employment and safe prices for the American people,” Powell claimed. “We acknowledge that our actions impact communities, households and companies throughout the nation. Anything we do is in help to our group mission. We on the Fed will do every thing we are able to to achieve our optimum work and worth steadiness goals.”

    HousingWire Direct Analyst Logan Mohtashami extra outlined what the fascination level hike may suggest for residence finance mortgage costs. “The Fed lifted prices and talked about bringing inflation down, and after the press convention, bond yields fell. Why? I think about that a lot of Fed value hikes have been priced, getting the 10-yr produce in direction of 3.%. If bond yields maintain rising we have now further space to get in direction of 6.% on mortgage premiums. Even so, if financial data fades and yields are coming down, residence finance mortgage prices will go down with it.

    “Right now, we’re in a tug of warfare regarding two camps. An individual group thinks that the Fed cannot enhance charges that considerably primarily as a result of it is going to result in a financial downturn, and an extra group thinks the Fed wishes to develop a recession to wrestle inflation,” Mohtashami mentioned.

    “Since Europe’s financial system is slowing down, China’s financial system is in a mess, Japan wants further tourism nonetheless, and Russia is in a financial downturn, there are restrictions to how significantly further worldwide bond yields can head elevated and our yields and home mortgage charges. We should select the monetary data only one 7 days at a time as a result of truth we do see some cracks within the inflation details and improvement.


    “However, the Russian invasion of Ukraine and China’s lockdown have put pressure on inflation data. It goes to be an epic tug of warfare for the comfort of the calendar yr. For now, the 10-yr generate has held across the 3.% diploma with out the necessity of a breakout. The peak generate on the 10-yr produce was 3.25% in 2018 when mortgage mortgage charges purchased to five.% again then. Charges are actually elevated nowadays because the mortgage mortgage cost pricing is even worse.”

    This story was present with enterprise response proper after authentic publication.
  • FHFA has place in some layers that can boost your interest level on a FNMA/FHMC property finance loan

    When it can come to having a property finance loan monetary loan, want charges are 1 of probably the most essential issues to consider. The interest level you get will straight have an effect on the quantity of income you fork out in curiosity across the on a regular basis residing of your monetary loan. This is primarily correct for monetary loans backed by the Federal National House loan Association (FNMA) and the Federal Residence Loan Home finance loan Corporation (FHMC). In this report, we’ll go over how want prices results FNMA/FHMC loans and when an FHA mortgage may presumably be a superior possibility.

    FNMA/FHMC Financial loans will probably be Impacted by the Charge because of LTV, Credit Scores, and Money/Financial debt Ratio

    The curiosity value you purchase on a FNMA/FHMC loan is established by numerous variables, along with your loan-to-benefit ratio (LTV), credit score rating, and revenue-to-financial debt ratio. LTV is the quantity of your mortgage divided by the appraised value of your family. The reduce your LTV, the a lot much less risk there’s for the loan supplier, and the lowered the fascination quantity you’ll probably get.

    Your credit score rating score is one other important issue that will have an effect on your fascination quantity. A bigger credit score rating rating often means a decreased interest payment, because it demonstrates that you might be a reduce risk borrower. On the opposite hand, a reduce credit score historical past score can consequence in a larger curiosity value and even a denial of your loan software program.

    Last of all, your revenue-to-financial debt ratio is a vital issue in determining your curiosity quantity. If your money-to-credit card debt ratio is just too vital, it reveals that you would have issues incomes your home loan funds. This could finish consequence in a larger interest cost, or the loan firm could deny your financial institution loan software program utterly.

    Will it’s Greater in Some Situations to go FHA?

    In some conditions, an FHA financial institution loan might be a much better possibility than a FNMA/FHMC monetary loan. FHA loans are backed by the Federal Housing Administration and are created to assist women and men with decrease credit standing scores or extra compact down funds. The want charges on FHA monetary loans are ordinarily lowered than these on frequent loans, and you might be succesful to qualify for an FHA private loan with a decreased credit standing rating or a larger LTV ratio.

    Having stated that, FHA monetary loans include some drawbacks as completely. To begin with, they need to have mortgage loan insurance coverage charges (MIP) that can insert to the worth of your financial institution loan. 2nd, FHA monetary loans have inflexible suggestions on the problem of the belongings you might be shopping for. If the property is in weak downside, you might presumably not be in a place to get an FHA mortgage.

    A Increased Than 40% Earnings Debt Ratio Affect Your Price

    Obtaining an profits-to-personal debt ratio larger than 40% can results your fascination fee and even direct to a denial of your mortgage software program. Loan suppliers wish to be certain that you can simply make your mortgage funds, and a vital bank card debt-to-money ratio signifies that you might maybe have points endeavor so.

    If you might have a vital private debt-to-cash movement ratio, you might wish to take into account shelling out off some of your cash owed forward of implementing for a house finance loan mortgage. This will lowered your ratio and enhance your odds of acquiring a decreased curiosity fee.

    Down Payment Can Influence Your Level

    The amount of your down cost can additionally impression your curiosity quantity. A extra substantial down cost often means a lot much less hazard for the loan supplier, so that you may have the ability to get a cut back curiosity level. On the opposite hand, a extra compact down cost can finish consequence in a larger want payment or require you to pay out for house finance loan insurance coverage.


    Summary

    When it arrives to having a home loan monetary loan, curiosity costs are a vital problem to ponder. For FNMA/FHMC loans, your fascination fee will probably be impacted by your LTV ratio, credit score rating, and profits-to-financial debt ratio. In some instances, an FHA financial institution loan could also be a significantly better selection,

    tune in and grasp a lot extra at https://www.ddamortgage.com/weblog

    Didier Malagies nmls#212566

    DDA Mortgage nmls#324329

  • Does it make sense to refinance at a larger interest quantity?

    There may very well be some conditions through which it tends to make notion to refinance at a higher need charge so as to consolidate private debt. For instance, in case you have quite a few substantial-fascination bank card cash owed and may solely qualify for a explicit private mortgage with a considerably greater curiosity charge, consolidating your cash owed with the person financial institution mortgage could maybe nonetheless be helpful if it permits you to repay your credit score rating playing cards and keep away from high-curiosity charges.

    In the tip, the conclusion to refinance at a greater need stage for debt consolidation will rely in your particular cases and the situations of the mortgage. It is vital to very rigorously take into account the fascination charge, charges, and reimbursement phrases of any mortgage give prematurely of producing a dedication.


    https://www.ddamortgage.com/website

    Didier Malagies nmls#212566

    DDA Mortgage mortgage nmls#324329

    #mortgage mortgage

    #refinance

    Request a Mortgage Problem

    Use the type beneath and we are going to give your our professional solutions!

    Commence Your Personal mortgage

    with DDA proper now

    Your regional Mortgage mortgage Broker

    Home finance mortgage Broker Largo

    See our Evaluations

    Looking for much extra specifics? Hear to our extended podcast! 

  • Mortgage interest charges

    The house finance mortgage price pendulum swings nonetheless but once more

    By Didier Malagies
    •
    18 Apr, 2024

    Expect 2024 to be mildly improved than 2023 with house finance mortgage premiums falling within the 2nd 50 % of the yr, housing gurus opined in their forecasts on the shut of the 12 months. Cuts to the Federal sources worth (and subsequently to mortgage mortgage costs) are imminent, merchants enthused proper after December’s meeting of the Federal Open up Market place Committee by which committee members predicted 3 worth cuts in 2024. Some consultants forecasted as a number of as six quantity cuts within the 12 months based mostly on this data. Rate cuts are even now coming, simply not in March , merchants and market place specialists reasoned extra currently because the financial system ongoing to function very popular. And now on the heels of studies of extra strong than predicted jobs enlargement and stickier than predicted inflation , the market’s change from optimism to pessimism in extra of worth cuts is total. Some even assume charge hikes previous to price cuts. The pessimism is seen in mortgage mortgage charges. Freddie Mac‘s weekly Major Home mortgage Market place Study is climbing again once more in route of seven%. HousingWire’s House mortgage Price Centre , which relies on information from Polly, is presently over 7.2%. Costs have been as minimal as 6.91% for Polly and 6.64% for Freddie as not way back as February. On Tuesday, they arrived at 7.50% on Property finance mortgage News Day by day, a major for this yr. Mortgage mortgage charges maintain essential means within the housing sector most significantly, superior premiums exacerbate the present-day affordability catastrophe by walloping the buying means of would-be customers and discouraging some would-be sellers – these with decrease, fastened-level house loans – from itemizing their houses, a drain on obtainable inventories. All this leaves housing trade consultants on the time but once more battling for his or her share of shrinking pies – as we’ve seen with simply currently launched house mortgage information and RealTrends Verified’s brokerage information , as successfully as additional dives on the brokerage landscapes in Jacksonville and San Diego . It is unsurprising, then, that real property shares have suffered for the reason that FOMC’s March convention and the the most recent job and inflation tales. That consists of the nation’s prime homebuilders (DR Horton and Lennar), mortgage mortgage originators (United Wholesale Home finance mortgage and Rocket Home finance mortgage), brokerages (Any the place and Compass) and residential search portals (Zillow and CoStar, which owns Houses.com). There are different dynamics at play for a few of these firms, even so. The brokerages are additionally contending with the rule alterations concerned in a proposed settlement by the Countrywide Association of Realtors some traders additionally imagine these rule adjustments profit CoStar at the price of Zillow . UWM, within the meantime, is contending with a scathing investigative report by a hedge-fund-affiliated data group whose hedge fund shorted UWM and went extended on Rocket it is usually working with pending litigation . UWM denies the allegations designed within the report.  Higher property finance mortgage prices, a lot much less mortgage packages and fewer residence product sales are regretably not the one outcomes housing trade consultants might see from a way more prolonged high-amount environment. There are additionally spillover results from different industries, particularly place of job actual property. Regional monetary establishments – which historically have been key family property finance mortgage originators – went massive on enterprise precise property loans as greater banking establishments scaled again on this spot in newest a very long time. That higher their publicity to downtown workplace towers, which have seen an exodus of tenants and a bottoming out of appraised values simply as a report $2.2 trillion in skilled precise property bank card debt will come owing in extra of the following handful of a number of years. That ties up funds that might in some other case transfer to family house loans and in some eventualities stresses banking firms like New York Community Bank, mum or dad of Flagstar Bank — the Seventh-most important lender originator of family house loans, Fifth-most important sub-servicer of home mortgage monetary loans and the 2nd-greatest house finance mortgage warehouse mortgage supplier within the nation. Homebuilders, additionally, sense the outcomes of extended massive charges. Though homebuilder confidence is nonetheless up considerably because of the reality previous fall, new housing commences are slowing . The dim potential clients for homebuyers have turned some merchants to the nascent establish-to-hire sector , mainly a wager that substantial charges are listed right here to remain for extended ample that would-be potential patrons are actually would-be renters.

  • 2024 prediction on interest charges

    The mortgage mortgage worth pendulum swings but as soon as extra

    By Didier Malagies
    •
    18 Apr, 2024

    Assume 2024 to be mildly larger than 2023 with dwelling finance mortgage charges slipping within the 2nd 50 % of the 12 months, housing professionals opined in their forecasts on the conclude of the yr. Cuts to the Federal assets fee (and subsequently to dwelling finance mortgage charges) are imminent, merchants enthused quickly after December’s convention of the Federal Open Industry Committee by which committee customers predicted three worth cuts in 2024. Some business consultants forecasted as a number of as 6 degree cuts within the 12 months centered on this info. Price cuts are nonetheless coming, simply not in March , merchants and market gurus reasoned way more not too long ago because the monetary system ongoing to run scorching. And now on the heels of studies of stronger than anticipated work growth and stickier than predicted inflation , the market’s change from optimism to pessimism over quantity cuts is complete. Some even depend on cost hikes upfront of payment cuts. The pessimism is seen in dwelling finance mortgage costs. Freddie Mac‘s weekly Main Property finance mortgage Current market Survey is climbing once more in path of seven%. HousingWire’s Home mortgage Charge Center , which depends on information from Polly, is already earlier talked about 7.2%. Fees had been as very low as 6.91% for Polly and 6.64% for Freddie as a short time in the past as February. On Tuesday, they attained 7.50% on Property finance mortgage News Everyday, a considerable for this yr. House mortgage charges maintain most important energy within the housing sector most significantly, superior charges exacerbate the latest affordability disaster by walloping the buying electrical energy of would-be potential patrons and discouraging some would-be sellers – folks with decrease, mounted-fee dwelling loans – from itemizing their properties, a drain on provided inventories. All this leaves housing specialists on the time but once more preventing for his or her share of shrinking pies – as we’ve seen with simply currently launched mortgage mortgage info and RealTrends Verified’s brokerage information , in addition to deeper dives on the brokerage landscapes in Jacksonville and San Diego . It is unsurprising, then, that true property shares have endured as a result of the FOMC’s March assembly and the latest occupation and inflation research. That contains the nation’s prime rated homebuilders (DR Horton and Lennar), property finance mortgage originators (United Wholesale Mortgage and Rocket Home finance mortgage), brokerages (Everywhere and Compass) and residential search portals (Zillow and CoStar, which owns Residences.com). There are different dynamics at take part in for a few of these firms, nonetheless. The brokerages are additionally contending with the rule adjustments included in a proposed settlement by the National Affiliation of Realtors some merchants additionally imagine people rule variations edge CoStar at the price of Zillow . UWM, within the meantime, is contending with a scathing investigative report by a hedge-fund-affiliated information group whose hedge fund shorted UWM and went very lengthy on Rocket it is usually working with pending litigation . UWM denies the allegations made within the report.  Large property finance mortgage premiums, much less dwelling mortgage functions and far much less family earnings are sadly not the one outcomes housing professionals might see from a much more prolonged substantial-amount ambiance. There are additionally spillover results from different industries, particularly workplace precise property. Regional banks – which historically have been vital family mortgage mortgage originators – went main on business precise property monetary loans as bigger sized monetary establishments scaled again once more on this space in latest a number of years. That elevated their publicity to downtown workplace surroundings towers, which have seen an exodus of tenants and a bottoming out of appraised values simply as a report $2.2 trillion in enterprise severe property debt will come thanks above the subsequent few years. That ties up money that would in some other case stream to family dwelling loans and in some situations stresses monetary establishments like New York Local group Financial establishment, father or mom of Flagstar Financial establishment — the Seventh-premier financial institution originator of family mortgages, Fifth-major sub-servicer of property finance mortgage monetary loans and the 2nd-major property finance mortgage warehouse mortgage firm within the place. Homebuilders, additionally, really feel the results of extended important premiums. Despite the truth that homebuilder self-assurance is nevertheless up drastically since final fall, new housing begins are slowing . The dim potential shoppers for homebuyers have turned some traders to the nascent establish-to-hire sector , successfully a wager that top charges are on this article to stay for lengthy ample that would-be shoppers at the moment are would-be renters.

  • The real truth about present interest charges

    &#13
    &#13

    You’ve seemingly heard the most recent information about mounting need charges. No matter whether or not it’s your bank card interest fee, or the worth tag to finance a property, the expense to borrow income has been escalating. Nonetheless, whereas there is no such thing as a doubt that need charges are bigger than they’ve been up to now 20 years, it’s vital to glimpse at hovering interest charges from a broader, way more historic stage of perspective.

    Mortgage mortgage backed securities large, Freddie Mac has collected and revealed info on common weekly home mortgage fascination charges because of the reality the early Seventies. With just about 50 yrs of particulars, this snapshot of the rise and slide of residence mortgage fascination charges presents a spectacular snapshot of how premiums have fluctuated. The largest purchase away whenever you appear at prices greater than the earlier virtually 50 percent-century? Charges are nonetheless historically minimal.

    A seem to the sooner

    About the course of the final 49 yrs, the common interest payment has sometimes hovered beforehand talked about 5%. Freddie Mac recorded the optimum fascination charge at 16.63 in 1981. Considering that then, fascination charges have been on a downward slope, with periodic spikes. It wasn’t proper till the burst of the housing bubble within the mid-2000s, and the next financial downturn, that we observed fascination charges tumble beneath 5%. Because then, now we have seen curiosity charges hover at unparalleled lows. As the economic system recovered, the Federal Reserve slowly and regularly started inching fascination costs bigger. By 2019, curiosity charges have been ticking nearer to the 5% differ. Nonetheless, with the onset of the pandemic, curiosity prices considerably dropped once more, main to the extremely small fascination charges we skilled via 2020 and 2021.

    Wherever we are actually

    In extra of the sooner variety of months, now we have all felt the impacts of inflation. Prices have enhanced and no matter whether or not it’s the whole of our weekly groceries to a tank of gasoline, quite a few items and companies price ticket way more, which embody the cost to borrow {dollars}. Nevertheless, it is very important protect in mind, that whereas it could probably be extra excessive priced to finance a property finance mortgage than it was a calendar yr in the past, charges are nonetheless fairly diminished when versus the historic widespread. Homebuyers might probably nonetheless have the prospect to accumulate a home at an fairly priced cost and begin out establishing equity.

    Property finance mortgage treatments for a growing payment pure atmosphere

    In a mounting interest cost environment, fairly a couple of homebuyers may look for funding options created to assist maximize their buying electrical energy and assure they secure the least costly value accessible to them. At Evergreen Household Loans™ we provide a array of things which might be nicely suited to fulfill this goal. We’ll function with you to grasp your property funding calls for and provide you with mortgage strategies which might be personalised to you. With a variety of adjustable-level mortgages and a set of revolutionary items, we’re correctly geared as much as allow you leverage your shopping for vitality and assist you safe a reasonable fascination quantity. If you’d wish to see what financial institution mortgage alternate options can be found to you, get to out to 1 of our well-informed mortgage officers today to check further.

    &#13