Tag: instrument

  • Fannie Mae supplies free of charge access to income calculation instrument

    Fannie Mae is producing a important underwriting software made use of for sure types of residence loans no price of charge on its web site.

    The authorities-sponsored enterprise’s cash calculator, which serves mortgage corporations who originate monetary loans for self-used clientele with out the necessity of basic wage circulate, is now accessible on Fannie Mae’s web website by means of a brand new world extensive net interface. Released earlier calendar 12 months because of this of permitted Third-get collectively suppliers, the software goals to allow originators lower their financial institution mortgage defect payment although streamlining small enterprise capabilities. 

    “With the beginning of our new web site interface, originators now can determine on the choice that absolute best aligns with their processes and satisfies their wants, though preserving time and bettering certainty within the top quality of the private mortgage,” talked about Mark Fisher, president of solitary-household credit score risk solutions, in a push launch. 

    Consumers of Fannie Mae’s know-how vendor associates will proceed on to have entry to the income calculator by way of their suppliers’ platforms as effectively, Fisher reported.

    “No matter whether or not because of this of our new net-primarily based mostly individual interface or by way of an built-in engineering service firm, Fannie Mae’s earnings calculator simplifies the strategy of underwriting the qualifying money circulate of self-used debtors, which normally has been a difficult and time-consuming operation for lenders.”

    The self-utilized inhabitants signifies roughly 10% of the U.S. workforce, in accordance to U.S. authorities estimates, as correctly as a growing selection of Fannie Mae monetary mortgage deliveries. But the methods concerned in originating residence loans to this sort of debtors sometimes contain detailed scrutiny of lender statements and different sources, escalating the danger of private mortgage issues. 

    In April, Aces Quality Management found the loan-defect payment growing to its most cost-effective in about 3 a long time, in accordance to essentially the most present info provided. But difficulties with income and work arrived in as essentially the most frequent type of error, found in additional than 23% of loans.

    The money circulate calculator useful resource obtainable by Fannie Mae works through the use of tax return particulars to set up month-to-month wages when additionally using its present providing information conditions, prior to submission of the monetary mortgage. The supplier returns an everyday month-to-month qualifying money circulate quantity together with warnings to help originators steer clear of widespread issues.

    The most up-to-date announcement follows new modifications to Fannie Mae underwriting plan, like approval of one-supply validation of a debtors’ belongings, money circulate and work, which is meant to ease procedures for collectors. 

    The GSE additionally designed strikes this 12 months to deal with considerations in regards to the highly-priced results on mortgage firm small enterprise when they’re essential to repurchase faulty monetary loans. Notifications of potential flaws might enable mortgage suppliers to resolution a defect circumstance earlier than Fannie Mae strikes on to additional costly choices, enterprise leaders talked about.

  • Twenty7tec updates affordability instrument – Mortgage loan Method

    207tec has present its Supply utility to make its affordability useful resource way more right for debtors with intricate circumstances.

    Advisers will now be ready to encompass way more complete particulars about their clientele, which incorporates people with self-used or contractor revenue.

    The tech enterprise claims this can allow brokers to retrieve extra correct info on the best financial institution loan measurement available from distinctive loan firms.

    Twenty7Tec director Nathan Reillysays: “We’ve been doing work on this replace for a while, as we admire that affordability has grow to be an more and more subtle matter and a single that has intensified in extra of the final 12-18 months.

    “In change, we come to really feel applied sciences has a element to get pleasure from in encouraging {the marketplace} reply to this downside by furnishing solutions that guarantee an even bigger diploma of efficiency and accuracy.

    “We’re by pure means delighted to be rolling this included operation out to our finish customers at no extra worth and we’re additionally devoted to exploring how we are able to make additional extra enhancements.”

  • The 2-1 vendor-paid out buydown: A potent instrument for homebuyers and household sellers

    &#13
    &#13

    Today’s housing market is undeniably distinctive from what it was throughout 2021 and early 2022. Elevated need charges and residences sitting down in the marketplace place for extra time intervals of time have modified traditionally very low curiosity prices and a extremely popular present market characterised by bidding frenzies. Whether you might be at the moment a homebuyer, residence vendor, or each of these, you could shock what this suggests for you. It might signify that now’s a very good time to simply take fringe of a 2-1 vendor-paid out buydown.

    Buydown ideas

    What precisely is a buydown? It’s when factors—generally known as discounted elements, mortgage particulars, or pay as you go curiosity—are made use of to put money into down a mortgage’s curiosity value as a a single-time upfront fee. The worth of 1 explicit challenge equals a single % of the principal (unique mortgage quantity), that signifies that one level on a $100,000 mortgage would equal $1,000. When which is a gentle worth all through mortgage suppliers, the amount of cash that 1 degree will decrease a mortgage’s rate of interest can vary involving mortgage suppliers and relies on further parts similar to the private mortgage model and present prices. It’s additionally essential to bear in mind that there could possibly be buydown maximums.

    Then, there are numerous approaches for the cost of a buydown to be paid, together with borrower-compensated and seller-compensated. Just as they audio, debtors cowl the expense with a borrower-compensated buydown, and sellers shield the price with a seller-compensated buydown.

    The social gathering accountable for fee isn’t the one challenge that may differ—completely different buydown sorts are available. They might be eternal or momentary and make the most of to set-level and adjustable-rate mortgages. With a long run buydown, the fascination quantity will get bought down for your complete financial institution mortgage time period. In comparability, the curiosity quantity receives acquired down for distinct a long time of the mortgage phrase with a brief time period buydown. A 2-1 buydown is a well-liked brief time period software program.

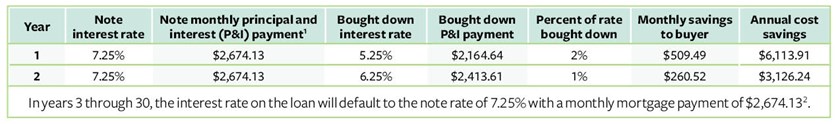
    Securing a home mortgage with a 2-1 buydown will enable for the curiosity payment to be diminished in the middle of the first 20 years of the private mortgage time period proper earlier than climbing to the lasting quantity, additionally acknowledged because the discover value, in calendar yr 3. The fascination degree is regularly diminished by 2% within the 1st yr, adopted by 1% within the 2nd 12 months.

    2-1 buydown illustration

    Here’s a 2-1 buydown instance for a 30-calendar yr fixed-fee mortgage phrase wherever the small print value $9,240.15:

    2-1 Buydown Chart

    Potential benefits of a 2-1 vendor-paid buydown

    Now that we now have coated some buydown necessities and reviewed an living proof, let’s simply take a more in-depth appear at how a 2-1 vendor-paid buydown could possibly be useful in a genuine property transaction proper now.

    For potential consumers, a 2-1 vendor-compensated buydown helps them ease into homeownership. First common funds are under their everlasting month-to-month fee, making the home mortgage cheaper upfront. And in consequence, they spend considerably much less curiosity across the way of life of the private mortgage, versus a mortgage devoid of a buydown that has the precise take be aware fascination payment and principal. A 2-1 seller-paid out buydown is often a risk-free method customers can make the most of shortly securing a cut back need payment and common month-to-month fee in a climbing degree setting.

    Sellers might revenue from a 2-1 buydown, a lot too. Presenting one on their dwelling itemizing could probably make it way more eye-catching to purchasers and assist it stand out in direction of different listings, primarily when need payment hikes are a reality. Or, if a purchaser requests for a vendor to produce only one and the seller accommodates the request, the shopper could possibly be way more very more likely to put money into the house. Numerous households are sitting on the sector for an extended time period of time, and a 2-1 vendor-paid out buydown could also be a unbelievable house-promoting method.

    Total, a 2-1 vendor-paid out buydown could possibly be a gain-earn for each equally homebuyers and property sellers. If you’re concerned about discovering way more about getting advantage of this robust instrument, join with an Evergreen monetary mortgage officer at the moment. We additionally give 1- and 3-2-1 buydowns. One explicit of our dwelling mortgage specialists can assist make clear the ins-and-outs so that you’re perfectly-informed and established up for good outcomes in your homeownership journey.

    Prices are as of 10/19/2022 and matter to change with out uncover, certain conditions apply. Not all customers will qualify for the phrases talked about. 1. Regular fee is principal and curiosity (P&I) solely, based mostly totally on order fee of $490,000 with a mortgage amount of cash of $392,000, 7.25% fastened degree, 30-yr expression, APR 7.551%, and 20% down fee. 2. Payment doesn’t embody taxes and insurance coverage coverage premiums. The exact fee quantity will likely be elevated. Some situation and county most financial institution mortgage quantity limitations may make the most of. The fee state of affairs is for instance capabilities solely. Talk to for current charges. Not all merchandise and options provided. Application is matter to enhance.

    &#13