Tag: Industry News

  • $5M settlement between shareholders and Property Place authorized

    A Michigan federal decide gave a final nod to a $5 million settlement, placing to relaxation a shareholder go properly with in opposition to Household Place Economical, three many years following it was first submitted.

    Of the sum, the information counsel will receive 30% of the proceeds, or $1.5 million, Shalina Kumar, U.S. District Choose in Michigan dominated June 28.

    The settlement was introduced in September of final yr however took close to to a 12 months to get the inexperienced mild.

    The course movement lawsuit, lodged by shareholders, accused House Level of creating misleading statements close to its firm approaches and how the unfolding lending setting might results it because it was established to go group.

    Exclusively, the category movement accused the now defunct lender of omitting information in its filings with the Securities and Exchange Commission regarding how its development of dealer companions might elevate the corporate’s prices and how an industry-huge scale back of gain-on-sale margins would impression it.

    This was “negligent” on behalf of Dwelling Stage and owing to it and “the precipitous lower within the {industry} worth of Dwelling Point’s securities, plaintiffs and different course prospects have endured vital losses and damages,” the first criticism filed June 21, 2021 claimed.

    Judge Kumar, the federal determine on the circumstance, wrote in her ruling that the settlement “delivered a good restoration for the course,” specifically with the looming uncertainty near Household Point’s cash viability final yr.

    House Point opted to unload its wholesale enterprise to The Bank mortgage Retail retailer, a national entity based in Tucson, Arizona, in April 2023. 4 months in a while, the corporate’s servicing operation was obtained by Mr. Cooper. The defunct dwelling mortgage lender was a casualty of deteriorating economics of the home mortgage market, which resulted in its demise, analysts have claimed.  

    In asserting the preliminary settlement earlier yr — previous to the decide’s current acceptance — in extra of 9,988 potential class prospects had been contacted, all of whom might almost definitely purchase a tiny chunk of the proceeds pie.

    The circumstance has been dismissed with prejudice, provided that the court docket retains jurisdiction greater than all points referring to the administration of the settlement, the decide wrote in her ruling.

    Other collectors that went group during this identical time interval, like Loandepot and Rocket Mortgage, have confronted similar accusations lodged by shareholders. 

    Loandepot settled one explicit such go properly with in Might, with a California determine granting closing approval to a $3.5 million settlement accusing the lender of misleading traders previous to its unique common public offering.

    Meanwhile, Rocket Property finance mortgage traders have pushed for a federal Michigan court docket to certify their class motion lawsuit, which accuses the house finance mortgage giant of deceptive shareholders pertaining to the corporate’s financial well being in 2021. The go properly with has been pending for over a number of a few years.

  • Multifamily-addled Texas lender lands $228 million cash infusion

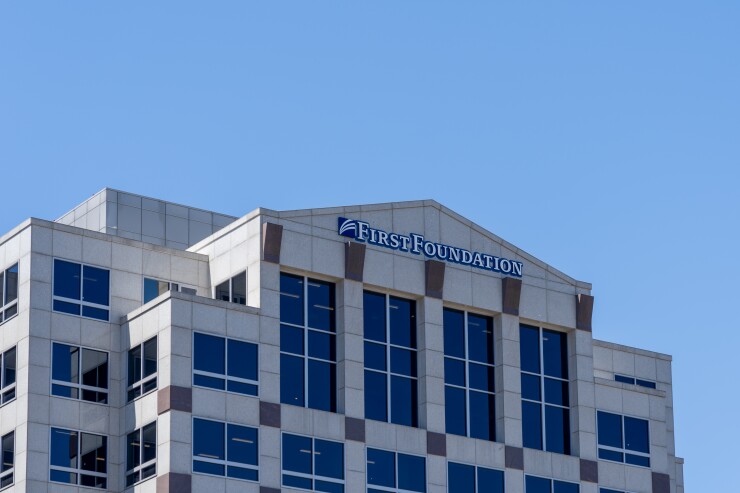
    First Foundation Bank building Dallas-centered Initial Foundation’s multifamily portfolio makes up extra than half of its loans, which have put rigidity on earnings for greater than a yr. The expenditure will give the monetary establishment some adaptability to get again once more to profitability, CEO Scott Kavanaugh claimed on an dealer contact.

    Adobe Inventory

    A gaggle of economic funding companies led by Fortress Financial funding Team is injecting $228 million into To begin with Foundation Inc., which has been grappling with a big multifamily severe property portfolio which is stressing its concord sheet amid a difficult curiosity cost environment.

    Dallas-dependent Initially Basis talked about Tuesday that the inflow of funds will give you flexibility to enhance its allowance for credit standing losses, decrease its multifamily focus over time and develop its skilled and industrial mortgage information.

    Canyon Associates, Strategic Worth Financial establishment Companions and North Reef Capital have been amongst the opposite monetary dedication corporations that participated within the capital improve. The financial institution’s stock price, which has been delicate to chatter concerning the route of curiosity premiums, sank 24% following the deal was introduced to $5.00 in proper after-hours investing. Its shares are down some 70% from two a number of years prior to now.

    To begin with Basis President and CEO Scott Kavanaugh mentioned on an dealer get in contact with that the monetary funding companies executed months of due to diligence previous to concluding that “with a vital strengthening of [the bank’s] stability sheet and funds placement,” 1st Foundation may “return to at the moment being a superior-general efficiency regional lender.”

    “The actuality that Fortress, Canyon and fairly a couple of different merchants arrived to this conclusion is an outstanding vote of self worth, not solely in our management crew and reconstituted board, but additionally in {our capability} to utterly remodel the monetary establishment in a modern difficult environment and simply take acquire of the numerous alternatives in our present market,” Kavanaugh talked about. “This funds infusion will current us the chance to return to a posture towards offense.”

    1st Basis promptly grew its publicity to multifamily in 2021 and 2022, when fascination charges have been close to zero, ballooning the asset class to extra than 50 p.c its financial institution mortgage portfolio. But the fastened-fee loans turned extra burdensome as charges rose, and the deposits to fund people loans grew further expensive. As a finish outcome, the $13.6 billion-asset financial institution’s web curiosity margin was crunched, shrinking from throughout 3% within the to start out with quarter of 2022 to 1.17% in the very same time interval this yr.

    1st Basis was scarcely worthwhile within the to start out with quarter of this 12 months, bringing in $793,000 in web revenue, down from $8.5 million in the identical interval of 2023.

    The cash injection, slated to close early subsequent week, will dole out frequent and desired shares to the monetary funding companies at $4.10 for every share. For the financial institution, the funds will purchase flexibility, Kavanaugh talked about. 

    “When you seem at FFWM’s stock worth, it truly is been battered for a while,” Kavanaugh defined. “As the earnings diminished, I used to be launched with the possibility to engage with some massive profile and exceptionally expert lender patrons. … .The risk to position ourselves again once more to strong profitability above a shorter interval of time — the board felt like that was a prudent difficulty to do.”

    1st Foundation will classify a few of its multifamily monetary loans as “obtainable on the market,” which may imply getting a discount, however may additionally give you wiggle place to evaluate the best approach to strengthen profitability, Kavanaugh mentioned. He included that the lender will launch a extra in-depth enterprise plan on its second-quarter earnings get in contact with in a handful of months.

    While Initially Basis is working to shrink its multifamily portfolio, lender executives doubled down Tuesday on their confidence within the lender’s credit score rating top quality. The lender operates in Texas, Florida, California, Hawaii and Nevada, with about three-quarters of its financial institution mortgage information within the Golden Condition. Kavanaugh said there’s been “no degradation” in credit score, however Very first Foundation is shoring up reserves because of the reality of rigidity from Wall Street.

    Industrial real property has been casting a pall on the banking enterprise for months, particularly as some banks’ stability sheets have taken main hits. 

    This calendar yr, New York Community Bank in Very lengthy Island noticed its inventory price tumble some 70% instantly after it astonished patrons with a key loss provision because of the price of its loans plummeting. The financial institution, which has an outsized publicity to hire-regulated multifamily houses in New York Town, wanted a $1 billion lifeline funding resolution led by Previous Treasury Secretary Steven Mnuchin to stabilize. Even pursuing a administration and methodology overhaul, New York Community  has not seen a massive stock-selling worth rebound.

    1st Foundation additionally introduced Tuesday that it’ll mix up its governance, tapping Simone Lagomarsino, the earlier CEO of two California monetary establishments, as the 2 its new president and a member of its board. Lagomarsino has served as CEO of Luther Burbank Discounts and Heritage Oaks Bancorp, and she or he can be the previous chair of the board of directors of the Federal Home Bank mortgage Financial establishment of San Francisco.

    Also predicted to be a part of First Foundation’s board are Henchy Enden of Fortress Investment Team, which can have the choice to insert a further board member Sam Edelson, who was specified by Canyon Associates and Ben Mackovak of Strategic Price Bank Companions. Regardless of the additions, the lender talked about that it’s actually decreasing the measurement of its board to 9 clients for now.

    “With the appointment of Simone Lagomarsino as President much more bolstering a robust administration crew, and the addition of exceptionally gifted of us to the agency’s Board of Administrators, we expect To begin with Basis could be very well-positioned to capitalize on potentialities for development and worth growth within the many years upfront,” claimed Drew McKnight, co-CEO of Fortress Financial funding Group, in a equipped assertion.

  • Guaranteed Amount shortens title to ‘Charge’

    Home lender Assured Amount has a brand new identify and search. 

    The Chicago-based principally property finance mortgage group launched on social media Monday it was shortening its determine to merely simply “Charge.” The announcement will come simply after a group of different strategic enterprise enterprise and web advertising and marketing strikes the mortgage group has created in regards to the previous many months. 

    “Just like our streamlined title, we’re devoted to producing the house finance mortgage plan of action smoother, extra quickly and smarter,” Level claimed in a Linkedin article. 

    An up to date website at the moment traits a brand new emblem. The rebrand arrives simply after the addition of quite a few new lending merchandise within the earlier two years, as the house finance mortgage market appeared to usher in customers amid slowing originations. The firm ramped up reverse-home finance mortgage features in 2023, whereas producing new application-application interfaces accessible as very properly that linked its shoppers to digital insurance coverage insurance policies suppliers. 

    In ventures exterior common property finance mortgage lending, the mortgage supplier unveiled a no price wellness app in partnership with famend self-support advocate Deepak Chopra previous tumble. At the time of rollout, the group solely termed the instrument the Level Application, which client success gurus stated may present as a valuable methodology of creating producer consciousness and a pipeline for brand spanking new shoppers.

    Elsewhere, the company additionally has naming authorized rights to the stadium often called Confirmed Fee Field, made use of by its hometown baseball workforce Chicago White Sox. The venue acquired the identify in 2016. 

    More simply currently, Confirmed Level, which ranks because the fourth premier retail lender in accordance to Scotsman Manual, noticed itself the problem of unwelcome headlines proper after an investigation of toxic-office allegations by the Chicago Tribune. The enterprise vehemently denied the statements, contacting the posting successful piece. 

    The house finance mortgage sector is not any stranger to model refreshes this 10 years. In June, private mortgage servicer Ocwen formally renamed alone to Onity, with the enhance additionally bringing a brand new stock ticker picture. 

    Two a few years again, precise property expenditure have faith in and guardian agency of Newrez, underwent its very personal rebranding from New Household Expense Corp. to Rithm Money. Newrez, by itself, was earlier referred to as New Penn Economical, relaunching with its current determine in 2019 following its acquisition by New Household.

  • Nexa’s 100% fee method spurs confusion, intrigues

    When Nexa Home mortgage rolled out its Nexa100 program, a 100% fee merchandise, in late May, social media exploded with emotions and confusion. 

    “Can any individual make clear this plan to me like I’m 5?,” quipped one dealer in a Facebook workforce for residence mortgage originators. Other commenters assumed the agency’s software was “additionally superb to be correct.”

    This could maybe have been in portion owing to the deficiency of specifics concerned in Nexa’s press launch asserting the system, or it might need stemmed from disbelief over how a group can begin these a software program and proceed to be in enterprise. 

    Regardless of what the state of affairs could maybe be, CEO Mike Kortas likes the eye the method is having – superior and perplexing – and hopes the hype will help his brokerage develop right into a 5,000 highly effective workforce by mid-2025. (There are presently 2,580 sponsored private mortgage officers, in keeping with the Nationwide Multistate Licensing Technique.)

    Prior to introduction of this system, out of the 275 basis particulars gained on a monetary mortgage, 220 basis components would go to the LO and 55 foundation factors would go to Nexa. The Nexa100 software program would make it in order that 220 foundation particulars goes to the LO, although 55 foundation factors goes to a separate account to deal with their expenditures, these sorts of as web advertising and marketing charges and rather more, Kortas factors out.

    “Bank mortgage officers purchase their normal comp after which we credit score historical past the remaining to a ledger for purposes of enterprise enterprise development,” stated Kortas. “Mortgage mortgage laws should be adopted with regard to financial institution mortgage officer cost.”

    Some brokers have recognized because the method “gimmicky,” primarily as a result of in actuality 100% of the fee doesn’t utterly land in an LOs pocket. Stakeholders have additionally been important about how Nexa can stay afloat with the roll out of this merchandise, particularly in such a troublesome lending environment. 

    To keep within the Nexa100 method, which is presently open to everybody proper till July 31, financial institution mortgage officers should recruit many others, or a minimum of make an endeavor to, states Kortas. “The state of affairs is that in buy to proceed on to get it, it’s essential to assist me develop. And the one problem that I demand is that you’ve got a single mortgage officer that you simply recruited to the group,” he stated.

    Kortas talked about he’s ready to decide on a number of the loss stemming from his program because of the reality his enterprise siphons from different cash sources, this form of as his protection small enterprise, which LOs use, and constitution jet enterprise enterprise, to retain components afloat. Nexa’s hangar enterprise has not way back gotten consideration because of a spat amongst Kortas and his earlier partner Mat Grella. 

    Kortas additionally notes his agency has an “intense tax tactic,” which saves the group funds. “I would not have to get nervous about that. I will pay my private mortgage officers extra. They’re going to conclude up shelling out taxes,” the Nexa CEO defined.

    But what’s simply not described concerning the Nexa100 system in its announcement, in keeping with a enterprise workers who requested for to be nameless, is that it’s only open to these LOs who do correspondent lending.

    The Nexa employee notes the brokerage is partnering with a couple of correspondent lenders: United Wholesale Home mortgage, Equity Primary House mortgage and MLB House mortgage for this software. And that therefore considerably, the roll out has been allegedly tumultuous.

    “Nexa has struggled with the teaching on it primarily as a result of relocating to correspondent lending is a various origination mannequin, you will see distinctive guidelines to it,” they defined. “The enterprise has struggled with instructing their LOs on learn how to do these kinds of loans, so you could find been an excessive amount of rising pains within the final month or so.”

    Kortas verified that the group is using the described corporations for non-delegated correspondent lending. 

    “There aren’t any rising pains to correspondent much more than rising pains for big growth. We handle the progress effectively however there’ll normally be speedbumps. We are quickly to reply to them,” he additional.

    Kortas defined responses from the usual public has been that the merchandise is “smoke and mirrors” and that he “must be patting the charges.”

    “My prices are the particular comparable charges as some other residence finance mortgage dealer at these mortgage corporations, we’ve tier an individual ranges. It really is the precise exact premiums as a pure dealer,” the Nexa CEO defined. “When you would not have an understanding of 1 factor, you assault it. And that is normal in human background. That is what you do.”

  • Americans’ personal debt reaches an all-time substantial, analyze finds

    The burden of debt has reached an all-time giant for American houses, in accordance to a examine by The Kaplan Group.  

    The assortment company analyzed the evolution of house loans as very properly as car, bank card and pupil loans since 2003 and located full debt grew by 81.5% greater than the previous 20 yrs. 

    Although the general sum of money of bank card debt decreased briefly simply after the 2008 cash catastrophe, the examine positioned the quantity owed has been growing shortly contemplating that, outpacing inflation. 

    With in extra of $100,000 in debt, residents of Washington, D.C., battle with the best sum of money, adopted by houses in Hawaii and Washington, the study talked about. Conversely, with all-around $35,000, residents of West Virginia, Mississippi and Arkansas stick with the least sum of debt. 

    Property finance mortgage bank card debt is eighteen% larger than on the peak of the subprime catastrophe. It has been rising steadily given {that a} decrease level in 2015 however grew minimally in between 2023 and 2024. Mortgages carry on being the principal debt useful resource for American households, symbolizing a few-quarters of the total, or 74%.

    Whilst credit score rating card personal debt has demonstrated minimal progress provided that 2023 and observed probably the most inexpensive share enhance of the noticed varieties of monetary debt, it’s at an all-time giant and has spiked exponentially because the pandemic. 

    In the route of the end of 2023, credit standing card stability delinquencies rose to 9%, a charge not present in excess of a ten years, in line with the Federal Reserve Bank of New York. 

    As of May properly, important card issuing banks held the idea that credit standing good high quality is slowly returning to pre-pandemic levels, getting under consideration inflation and unemployment. The assessment reveals bank card debt has elevated by 33% as a result of 2020 and doesn’t nonetheless counsel a possible decline. 

    The total diploma of personal debt enhance might differ drastically by state. The District of Columbia noticed the utmost enhance at 143%, excess of doubling contemplating that 2003. The highest will increase over time took place in Northern states like North Dakota, Montana, Utah and Idaho. 

  • Patrice Ficklin, CFPB’s head of reasonable lending, to leave for Fannie Mae

    CFPB's Patrice Ficklin.

    Patrice Ficklin, who has headed the Client Economical Defense Bureau’s good lending place of work as a result of its institution in 2011, has launched that she is leaving the bureau for a associated place at Fannie Mae.

    Patrice Ficklin, who has led the Buyer Financial Security Bureau’s truthful lending enterprise workplace because it opened its doorways in 2011, is leaving the corporate to rejoin Fannie Mae.

    Ficklin has been the CFPB’s solely truthful lending director through seven performing and long-lasting directors. She is the founding director who established up the company’s Business workplace of Fair Lending & Equal Prospect reliable for the oversight and enforcement of truthful lending laws. She has served coordinate makes an attempt with the Section of Justice to rein in redlining and launched new tips and guidelines geared toward curbing the impacts of racial bias on dwelling valuations. 

    Ficklin earlier served as Fannie Mae’s affiliate widespread counsel for virtually a dozen a very long time. She is rejoining the authorities-sponsored group to function its new good lending officer. In advance of signing up for the CFPB, Ficklin labored as an authorized skilled at Relman, Dane & Colfax PLCC.

    Underneath Ficklin’s administration, the CFPB has introduced historic truthful lending enforcement steps all through a spread of sectors of consumer finance and has assessed tons of of hundreds in penalties. Final 12 months, the CFPB fined Citibank $26 million for “intentional, illegal discrimination” from Armenian People in america making use of for credit score rating playing cards. The bureau additionally took motion towards Bank of The usa and Flexibility Home mortgage for reporting faux, misguided or incorrect data beneath the Home Home finance mortgage Disclosure Act. 

    In its most up-to-date sincere lending once-a-year report, the CFPB cited a document 189 financial institutions in 2023 for violations of the Equivalent Credit Possibility Act, up from 174 in 2022. ECOA prohibits discrimination from credit standing candidates based mostly totally on race, nationwide origin, gender or age. Very final 12 months, the CFPB referred 33 fiscal establishments to the Justice Division for suspected violations of truthful lending tips.

    Ficklin has had a nationwide impression by transferring the federal governing administration over and above its unique deal with redlining and reasonable lending enforcement of monetary establishments and property finance mortgage lenders. The CFPB’s reasonable lending oversight now encompasses a wide selection of financial merchandise — like bank cards and the use of artificial intelligence and machine learning in underwriting and lending originations. 

    CFPB Director Rohit Chopra, who has constructed superior and rising techniques a precedence, praised Ficklin’s administration. The bureau has nonetheless not named a successor.

    “Patrice’s administration has fashioned the CFPB’s good lending system from the company’s commencing,” Chopra talked about in an emailed assertion. “I’m grateful for all the things she has completed to battle discrimination and make our markets fairer.”

    In an interview, Ficklin defined it was bittersweet to cease her help as a senior authorities on the CFPB.

    The adhering to transcript is edited for size and readability.

    American Banker: You’re the one human being to direct the CFPB’s Fair Lending Office atmosphere. What are you probably the most comfortable of quickly after 13 a very long time on the company?

    Patrice Ficklin: My get the job executed concerned not solely establishing the reasonable lending objective, but additionally genuinely serving to to assemble the corporate within the supervision and enforcement capabilities, due to the actual fact I used to be half of the governance construction for the complete Bureau. It’s a factor else to assemble a governing administration startup. 1 of the first issues that Elizabeth Warren requested every of us to do as we ready to develop our workplaces was to sketch out a eyesight. I had remaining a personal sector job and I arrived onboard as a Treasury worker on a 30-thirty day interval appointment.

    And the eyesight that I sketched out was to in essence progress the Bureau’s obligation for truthful lending — primarily as a result of there had not been an awesome deal focus on nonbanks — after which additionally all through numerous enterprise enterprise traces to absolutely use all of the sources that Congress had given the corporate. [Those include] the laws beneath our jurisdiction, but additionally the full toolkit for training and regulation, help, supervision, exploration and enforcement. You can count on to bear in mind, again in 2011, reasonable lending was simply considered the province of dwelling finance mortgage origination, appropriate? And it was nearly fully targeting depositories. But inspecting the Equivalent Credit Prospect Act, there may be definitely a total breadth of authority and obligation proper right here. 

    I used to be a private sector authorized skilled and I can do not forget listening to at conferences this type of deep resistance to the plan of compliance administration techniques present outdoor of mortgage mortgage origination in different enterprise traces, corresponding to property finance mortgage servicing for automobile finance or credit score rating playing cards. I assume one of the gadgets I’m proudest of is that now all through stakeholders — irrespective of whether or not it actually is sector or consumers or advocates — there may be significantly additional consciousness of the Equal Credit Prospect Act and the protections that it claims. And so fairly just a few individuals in banks and nonbanks have invested appreciable belongings in reasonable lending compliance. We see sincere lending specialists considerably much more deeply embedded of their agency’s operations and all through distinctive enterprise enterprise strains. I’m fired up about that, and I’m hopeful that that may proceed to develop.

    The third area I’m more than happy of is that the bureau’s reasonable lending perform is definitely stable. It is absolutely deeply embedded throughout the whole CFPB. We have severely gifted, truly good, genuinely kind and humble colleagues. It is a strong plan that I’m forsaking.

    AB: How anxious are you the lawsuit the CFPB submitted from a Chicago mortgage mortgage monetary establishment Townstone Money might backfire and undermine the CFPB’s take a look at that it has broad authority to discourage discrimination?  

    PF: I actually can’t touch upon that. I’ve at all times thought-about that the complete laws is on place that the polices the Federal Reserve Board of Governors promulgated and the Bureau adopted have been on level. But I definitely are unable to forecast what the courts might presumably do. 

    AB: What are your fears or hopes for synthetic intelligence and the use of machine learning in lending and underwriting algorithms? 

    PF: One of the problems of the CFPB, as an company that was born out of a cash disaster, is to be at any time-vigilant with regard to rising troubles and threats. And so now we have unquestionably been targeting knowledge surveillance and the monetization of so lots shopper behavioral data, and the way they’re fueled by the use of these gear understanding and different intricate computational approaches. It was six a very long time in the past that the CFPB based our supervision applied sciences software with dedicated consultants, in order that we will get out in entrance and absolutely grasp what’s going on as a twenty first century company to actually be on high rated of these varieties of developments. 

    We have resident gurus with diversified technological innovation backgrounds, now we have knowledge scientists, designers and software program bundle engineers and different individuals, and they’re performing hand-in-glove with legal professionals and examiners to completely have an understanding of the corporations beneath our jurisdictions and their use of technological know-how to guarantee compliance with consumer cash regulation. These are collaborative teams that go additional of their engineering assessments, assessing these sophisticated last determination varieties, reviewing data safety techniques and exposing darkish designs that may trick consumers into earning money prospects that they’d not in any other case. In our bank card check work, we evaluated automated techniques and types which can be generally promoted as AI and gear understanding which can be remaining utilised by bank card issuers. 

    AB: Can you discuss in regards to the CFPB’s deal with what you are calling considerably much less discriminatory prospects?

    PF: It actually is a major focus. Testing for disparate process and disparate results are nuts and bolts in situations of compliance administration in situations of reasonable lending checks. Strong truthful lending screening actually does incorporate lookups for lots much less discriminatory choice variations. And only one of the issues that the bureau is finishing up is now we have created the complicated capability into our enforcement and supervision do the job. The capability to actually examine the use of open provide automated debiased procedures to lookup for substitute varieties — variations that protect comparable accuracy however reduce disparities. 

    AB: Racist e-mails have performed a perform in some reasonable lending instances which have been introduced by the Department of Justice. Is that one thing you have discovered much more normally?

    PF: It actually is a big provide, and it’s actually a bit of one thing I’m additionally proud of, due to the actual fact it truly is a process that we pioneered in phrases of asking establishments to perform key phrase searches. ECOA basically prohibits collectors from discriminating versus candidates in any issue of a credit score historical past transaction and in addition discouraging these candidates. And so this type of intentional discrimination and redlining from a singular group has at all times been a serious precedence for the bureau and proceeds to be. 

    Interior e-mail are 1 of many features that the CFPB considers when assessing a possible truthful lending violation. We appear at not solely e mail messages, but additionally textual content material messages and chats and other forms of digital communications that may incorporate discriminatory content material. The different variables that we look at contain the cost of functions that an establishment will get from numerous neighborhoods, precisely the place they’re finding their branches and locations of work and the place by they market. It may be all of these distinctive components collectively that allow us to affirm regardless of whether or not these are proof of a particular person perspective, and irrespective of whether or not or not the mortgage officers or different personnel could also be fostering a tradition that tolerates or embraces discrimination or stereotypes about individuals or neighborhoods on a prohibited basis. So they’re an individual ingredient of what we search at. 

  • Additional layoffs at Newrez, trimming 78 workers in Arizona

    Newrez let go of dozens of its Arizona workers in late June, extra trimming employees of acquired Computershare Mortgage Expert providers.

    The top-rated mortgage mortgage mortgage firm, owned by asset supervisor Rithm, let go of 78 former Computershare workers centered in Tempe, Arizona, for every a Alert acknowledge filed on June 28.

    Newrez made the choice to reduce a few of its freshly extra workforce in particular geographies because it was making redundancies, talked about a enterprise government. Employees impacted are entitled to a severance provide and Newrez will likely be supplying work changeover steerage, they additional Monday.

    Given that its acquisition of Computershare Home finance mortgage Providers and affiliate Specialized Mortgage Servicing LLC., lots of of personnel have been axed by the mortgage mortgage mortgage firm. It shouldn’t be uncommon for repetitive positions to be eliminated subsequent the completion of an acquisition, enterprise stakeholders have identified.  

    Consequently significantly, reductions have strike locations of labor in Florida, Colorado and now Arizona, with the entire tally of workers allow go lurching in extra of the five hundred mark.

    Roles impacted have concerned fairly just a few authorities positions, knowledge analysts, shopper relations associates and home mortgage mortgage processors. 

    The receive of Computershare price ticket Rithm near $720 million and was paid out for because of a mix of present earnings and on the market liquidity on the soundness sheet, as correctly as supplemental mortgage servicing rights financing. The deal was declared late final 12 months and closed in early May properly. 

    Integrating the enterprise and its affiliate provides $149 billion in unpaid principal stability of MSRs to Newrez. This entails $104 billion in Third-celebration servicing to Newrez’s portfolio, the company reported in a push launch.

    It additionally extra expands Newrez’s existence in servicing, a factor the house finance mortgage monetary establishment has been prioritizing. Servicing is considered to be the pure hedge to originations as curiosity prices rise, and the reverse is official once they tumble. 

    “SLS will much more develop our sturdy subservicing group and convey with it a unbelievable reputation in the sector – the workforce and Newrez share a willpower to delivering a most effective-in-class expertise to each of these purchasers and house owners,” claimed Baron Silverstein, president of Newrez, in a press launch in May probably. “The electrical energy of the put collectively platform will reinforce Newrez’s positioning in the present market.”

  • Nationwide Home finance loan Information quiz: July 1 2024

    (*1*)

    Love complimentary accessibility to prime concepts and insights — chosen by our editors.

    Think about oneself a scholar of the most well liked mortgage loan servicing litigation and Fannie Mae bulletins? In this week’s National Mortgage News quiz, verify your know-how on content material articles masking new executives, Venture 2025, and much more!

    Click on right here to check out out final week’s verify.

  • Sachem Funds cancels financial debt offer thanks to marketplace conditions

    Even as varied mortgage subject firms turned to the financial debt markets this week, Sachem Money Corp., a extremely laborious funds financial establishment, has canceled its that includes, citing present market circumstances.

    A prospectus filed with the Securities and Exchange Commission on June 17, together with a press launch from the precise day, doesn’t guidelines a greenback sum of money for the that includes, which might have had a five-calendar yr maturity.

    Sachem issued a second press launch 10 instances in a while canceling the transaction.

    “Our conclusion to withdraw our previously launched private debt presenting was primarily based solely on our willpower that the proposed pricing of the presenting was unfavorable to the prolonged-term pursuits of Sachem’s enterprise enterprise,” CEO John Villano mentioned in a press launch.

    Sachem is a severe property financial funding trust in that originates and firms short-time interval loans (just a few a few years or significantly much less) to actual property merchants to fund acquisition, renovation, enchancment, rehabilitation, or enchancment of family or industrial qualities.

    “We need to guarantee our shareholders and noteholders that Sachem has adequate liquidity by way of its current credit standing providers and liquid house mortgage portfolio to go on to execute on the group common with earlier apply,” Villano defined. “In addition, Sachem will go on its disciplined underwriting and private mortgage origination procedures to enhance probability adjusted returns for shareholders and to safe our capital.”

    When it would come to liquidity, Sachem has a $200 million grasp repurchase financing facility with a subsidiary of Churchill Genuine Estate a margin financial institution mortgage account with Wells Fargo that permits us to borrow towards our expense securities portfolio and a $65 million revolving credit score rating facility with Needham Lender, a Massachusetts co-operative financial establishment, the supplying prospectus talked about.

    At the conclusion of the preliminary quarter, Sachem skilled shut to $25.9 million incredible beneath the Churchill facility and $35 million from Needham’s. It additionally had revenue and revenue equivalents of about $18.4 million.

    During the earlier week, just a few suppliers, which incorporates another REIT, New York Financial dedication Believe in, priced financial debt transactions. That deal was for $60 million in 9.125% senior, unsecured notes owing to mature on July 1, 2029.

    Finance of The america, a reverse mortgage mortgage lender, did a offer on a complete of $350 million of financial debt that extended maturities from subsequent yr to 2026 and 2029.

    Then Essent Group priced $500 million of senior unsecured notes, making ready to use $425 million of proceeds to pay again off the borrowings of a time period mortgage in order that it may very well be refinanced.

  • Presidential debate skirts housing affordability

    Final night time’s presidential debate let down some commerce teams by solely briefly relating how the 2 contenders will deal with housing affordability, despite the fact that different indicators recommend there may very well be stark distinctions of their approach.

    Upon remaining questioned in regards to the stress of rising home prices, President Biden reported steps he is taking in keeping with that function embrace his efforts to scale back broader inflation, somewhat one thing earlier President Trump additionally stated he’d cope with.

    In addition to combating inflation, Biden acknowledged he applications to maximise housing present by “incomes assured we construct 2 million new fashions” and capping rents. 

    The candidates additionally confronted a subject in regards to the proceed to-huge homeownership divide amongst Black voters and white properties, with each candidates calling the priority a merchandise of inflation and Biden declaring he’ll proceed taking strategies to slim the hole.

    “For occasion, I offered the technique that any Black family members initially-time homebuyer should get a $10,000 tax credit standing,” Biden defined, additionally pointing to broad initiatives he’s created to keep away from discrimination. President Trump, in distinction, rolled once more honest lending insurance policies during his phrase.

    Despite the truth that Realtor.com famous that the scant level out of housing wasn’t totally astonishing because it was in keeping with previous debates between the 2 candidates, the omission was out of line with voter want. 

    A the most recent ballot from on-line real property brokerage Redfin uncovered that 53.2% of households talked about their election willpower will likely be influenced by housing affordability. The candidates did cope with some ideas about it, however solely President Biden addressed the subject material immediately.

    Also, a national examine from the College of Michigan and the Money Occasions recognized that Americans’ cash functionality to afford a house rated as a serious subject by a nearly equal 70% share of Democrats, Republicans and neutral voters alike. 

    In delicate of that, Ralph McLaughlin, a Realtor.com economist, talked about he skilled hoped for, “further dialogue about your dwelling, and far much less in regards to the White House.”

    Similarly, Carl Harris, chairman of the National Affiliation of House Builders, issued a comment pursuing the dialogue stressing a necessity for the presidential candidates to cope with the housing supply shortage and apply solutions. 

    “The housing affordability disaster is a serious nationwide fear and Americans will simply take acknowledge why the presidential candidates reported fairly minor on how one can make homeownership and renting much more very inexpensive,” Harris talked about in a press launch.

    Builders are looking for endeavours that will enhance inventory, Harris stated.

    “With a nationwide shortage of round 1.5 million housing items, the one approach to carry down mounting housing expenditures is to set in space insurance policies that may enable builders to enhance the housing present,” he further.

    Harris additionally immediate another strategies the presidential candidates ought to actually carry out with lawmakers on to alleviate stresses on housing constructing and affordability troubles for consumers. 

    “The administration and Congress should tackle excessive restrictions, help trades schooling to alleviate a intense labor scarcity within the constructing enterprise that’s delaying dwelling developing assignments, and oppose restrictive, necessary making codes that drastically elevate housing prices and provide little electrical energy value financial savings to customers,” he reported, referring to some gadgets in a established of solutions the NAHB has.