Tag: income

  • Fascination charges weigh on Wells Fargo’s income again

    This is a establishing story. Make certain you examine again again on this article for updates.

    Wells Fargo described its web need cash slid nonetheless throughout again within the 2nd quarter, as bigger payouts to depositors proceed on weighing on income.

    The financial institution’s makes an attempt to trim noninterest charges and improve its cost income served relieve a few of that stress, with its complete profitability growing to $4.9 billion between April and June, up from $4.6 billion within the to start out with quarter.

    But the megabank underperformed analyst anticipations on its web fascination income, which fell under $12 billion for the preliminary time since 2022.

    Wells Fargo’s stock worth was down excess of 5% in pre-market place shopping for and promoting, contemplating that an enchancment in need income was “element of the investor bull thesis” prematurely of the quarterly earnings time, Citi analyst Keith Horowitz wrote in a discover to consumers.

    1 driver was the “tepid” pace of financial institution mortgage growth that Wells Fargo executives talked about they have been observing, as that gave it a scaled-down pool of economic loans on which to acquire need. But the financial institution was additionally compelled to shell out much more curiosity to carry depositors content material, as individuals switched to increased-yielding certificates of deposit pretty than receives a commission tiny for his or her {dollars}.

    “We’ve discovered ongoing migration into bigger-yielding prospects within the buyer enterprise enterprise,” Mike Santomassimo, Wells Fargo’s fundamental financial officer, suggested reporters Friday.

    1 good is that the tempo of that migration “has slowed and continues to gradual,” Santomassimo reported. Fascination payments climbed 3.3% through the quarter, versus 5.4% within the very first quarter and 12% 1 / 4 simply earlier than.

    The lender trapped to its prior recommendation that web curiosity cash would fall amongst 7% to 9% in all of 2024, whereas it did say Friday it expects to be on the higher shut of that vary.

  • Tembo provides bonus cashback up to £300 to its income LISA – Property finance loan Tactic

    Tembo has added a cashback reward cost of up to £300 to its arduous money Lifetime ISA.

    Prospects transferring a Life time ISA of £5,000 or rather more to Tembo from one other provider will get the cashback. The provide is legitimate till lastly 31 July.

    The cashback bonus will likely be paid to the income Lifetime ISA account 6 months instantly after money are acquired by Tembo.

    The loan supplier requires patrons to preserve their {dollars} Life span ISA for a minimal quantity of 12 months for the present to be legitimate.

    The lender has an elementary need stage of 4.3% (AER variable), nonetheless, the cashback cost takes the AER variable to the equal of up to 5.07% primarily based on the worth of the switch.

    With the Monetary Coverage Committee (MPC) anticipated to reduce the muse price within the coming months, Tembo states customers at the moment are properly positioned to achieve from the last word days of better costs proper earlier than they start to slide.

    The FCA has uncovered that on typical, British isles monetary financial savings solely generate 1.25% need.

    Tembo says for quite a few 1st-time prospects (FTBs) incomes the best amount of need on their value financial savings will likely be an essential a part of their route to dwelling possession.

    The authorities’s Life time ISA permits 18-12 months-olds to protect to searching for very first residences that price ticket £450,000 or fewer.

    Savers can set in up to £4,000 yearly to the account up to a most of £20,000 within the 2024 to 2025 tax yr.

    The authorities will add a 25% reward to these monetary financial savings, up to a utmost of £1,000 for each yr.

    On the opposite hand, withdrawals from the account that aren’t utilised to buy a dwelling incur a 25% cost of the overall amount, effectively eliminating the federal government’s bonus.

    Tembo chief govt Richard Dana opinions: “Many FTBs could have been upset with the Bank of England’s last resolution earlier 7 days to maintain the bottom stage however another time. However, massive fascination costs are additionally a wonderful probability for deposit savers, who want to take into account this second to evaluation their financial savings costs and make sure they’re on the best possible deal.”

    “Average Uk value financial savings solely generate 1.25% need, which – specified the upper inflationary environment – is a extremely dangerous purchaser consequence. We’re delighted to present a even additional incentive for first time shoppers, by giving up to £300 cashback on high of our industry-major elementary charge of 4.3% AER (variable).”

  • Existing-residence income slide a 3rd thirty day period as prices established a file

    Revenue of current homes within the U.S. fell for a third straight thirty day period in May maybe although prices established a totally different historical past, underscoring persistent affordability worries that hobbled the very important spring advertising season.

    Agreement closings lessened .7% from a thirty day period earlier to a 4.11 million annualized charge, pushed totally by a drop within the South, in accordance to Countrywide Association of Realtors info launched Friday. The decide was in step with the median estimate in a Bloomberg examine of economists. 

    Meantime, the inventory of current households on the market has crept up a brief whereas in the past, partly as a result of women and men who’ve been ready for fees to drop earlier than itemizing their homes have decided they can’t wait round any for a longer time.

    The present of properties on the sector enhanced 18.5% from the very same month final 12 months to 1.28 million, however it may be nonetheless completely beneath the stage considered forward of the pandemic when dwelling finance mortgage prices had been a nice deal decrease.

    That explains why fees keep elevated — the median income promoting value higher 5.8% from a calendar 12 months previously to a historical past $419,300, reflecting additional product gross sales of large-priced properties as completely as many options, NAR’s info show.

    “Residence charges reaching new highs are producing a wider divide regarding all these proudly proudly owning attributes and people individuals who want to be initial-time clients,” NAR Chief Economist Lawrence Yun said in a assertion. “Finally, extra inventory will assist enhance dwelling income and tame dwelling price ticket good points sooner or later months.”

    Home finance mortgage prices have come down considerably not way back, however the Federal Reserve very probably won’t ever decrease fascination prices till later this 12 months. Yun claimed that could be delaying the restoration in residence gross sales, which have been trapped about a 4 million annualized charge for the previous 12 months.

    At the present tempo, selling all households on the sector would simply take 3.7 months, the most effective in 4 years. Even so, brokers see almost something under 5 months as indicative of a restricted present market.

    About 67% of the households offered ended up on the trade for a lot lower than a thirty day period in Might, roughly flat from the prior thirty day period, whereas 30% offered earlier talked about the guidelines charge. Properties remained on {the marketplace} for twenty-four occasions on typical in May properly, in distinction with 26 days in April, NAR’s report talked about.

    Current-dwelling earnings account for the higher a part of the U.S. full and are calculated when a contract closes. The federal authorities releases May presumably new-dwelling income figures on June 26.

  • I halved my income when I left London but purchased my to start with residence

    A Occasions Cash Mentor reader explains how she purchased a property whereas incomes essentially the most inexpensive wage of her on a regular basis residing.

    Lisa was incomes £31,500 a calendar 12 months as a nanny in London when she made the choice to shift to Manchester, chopping her wage in half.

    Now 27 and with an income of £16,000, she has managed to fulfil her targets of marrying retailer supervisor Steph, buying a family and even occurring getaway to New York.

    A happy-looking Lisa and her wife Steph on their wedding day, with their dog AlbieLisa and spouse Steph with doggy Albie on their bridal ceremony day | Credit: Andy Reeves

    Frugal residing

    “For a few years, I believed that if I wasn’t incomes tons of {dollars} then I wouldn’t have the option to buy a property, trip or have stunning issues – which is what tradition appeared to notify me about income,” Lisa states.

    “Although I have all the time been frugal and love a cut price, I begun to query why I wished to buy elements within the to start with location.”

    Lisa, initially from Harrogate, is studying for a PhD in digital well being and health examine at Manchester College. She receives £16,000 a 12 months: £8,000 from working on the college and £8,000 within the number of a mortgage.

    In August 2018, Lisa and Steph purchased a modern-day two-mattress residence within the centre of Bury with a backyard and photo voltaic panels. They paid out £100,000 with a £5,000 deposit and took out a 15-12 months residence finance mortgage.

    The least expensive comparable attributes in simply 20 miles of London would have worth £260,000, although that’s with out the necessity of the surplus bathroom, modern inside or photograph voltaic panels.

    Lisa doesn’t really feel that at the moment being on a worth vary suggests residing a disadvantaged existence.

    What I did

    In 2017 Steph and I had a joint income of £48,500 dwelling in London. But of program the value of residing in London is dear. In August 2017 we moved to Manchester, the place we now have a joint income of £36,000. We’d decided to rent for a calendar 12 months and see if we favored the house greater than sufficient to purchase a property in.Just after leaving London, I stepped up my frugal strategies and commenced to actually concern every particular person one purchase. It boosted my monetary financial savings.In August 2018 we purchased our dwelling, paying £100,000 with a £5,000 deposit and took out a 15-calendar 12 months mortgage mortgage. We bought married in Manchester in June 2019 proper after two a few years of arranging. There have been being 100 firm at our £2,400 wedding ceremony ceremony.I keep on to plan our worth financial savings throughout virtually every little thing we wish to do within the following handful of a number of years, which includes touring to Japan, buying and renovating a caravan, discovering out to horse journey and changing into foster carers.

    To have your personal wedding ceremony on a worth vary, learn our quick article with 22 wise pointers.

    What labored

    Learning from my mom – she has “hacks” for each little factor. She instilled in me that you simply spend for the branding more often than not. I show you how to save a fortune by buying worth producers. I portion them up and cling them within the freezer till lastly I want them.Tracking my payments. It was great to perceive I was throwing away in between £5 and £10 on lunch each single day at one subject. Find out how to select management of your funds by studying our guideline to budgeting.Providing off earlier furnishings when we moved. I produced £2,500 by acquiring rid of things we no prolonged desired or had residence for.Embracing minimalism. I donated and threw absent possessions when we moved. I skilled been holding on to them just because I assumed that they had been incorporating extra to my day by day life. Doing a ton of Diy. Laying the patio was significantly additional than my skillset but we managed to do a £500 place for £100 thanks to YouTube video clips, getting tiles in a sale, borrowing a spade, messing up the first try, leaving it for a number of months and going again to it with the spirit degree we initially forgot to use.Budget bridal ceremony. We weren’t involved to ditch bridal ceremony traditions that we didn’t remedy about. We opted out of acquiring a wedding automobile or truck, new bouquets {and professional} hair and make-up. Setting up prematurely. We booked our bridal ceremony photographer two years prematurely when he was new to bridal ceremony pictures (we compensated £450 for a deal that he now bills £1,290 for). Equally, if I get a fork out rise I’ve presently resolved I will overpay the home mortgage and expend some on driving classes.

    Lisa paperwork her paying out on her web site Residing Thrifty.

    What didn’t function

    Applying bank cards and an overdraft to purchase objects in an endeavor to present I was thriving and like all people else. I learnt instantly that this didn’t fulfil me.I nonetheless squander funds on meals even with meal arranging and making use of Tesco Clubcard vouchers strategically. We are all creatures of sample.

    We’d actually like to hear what you are feeling about Occasions Money Mentor. Make certain you converse to us with any concepts or concepts.

    Vital knowledge

    Some of the merchandise promoted are from our affiliate companions from whom we get compensation. Whilst we goal to attribute a number of the best options out there, we will not critique nearly each merchandise on the business.

    Read further

  • Homes have turn into unaffordable for usual earners

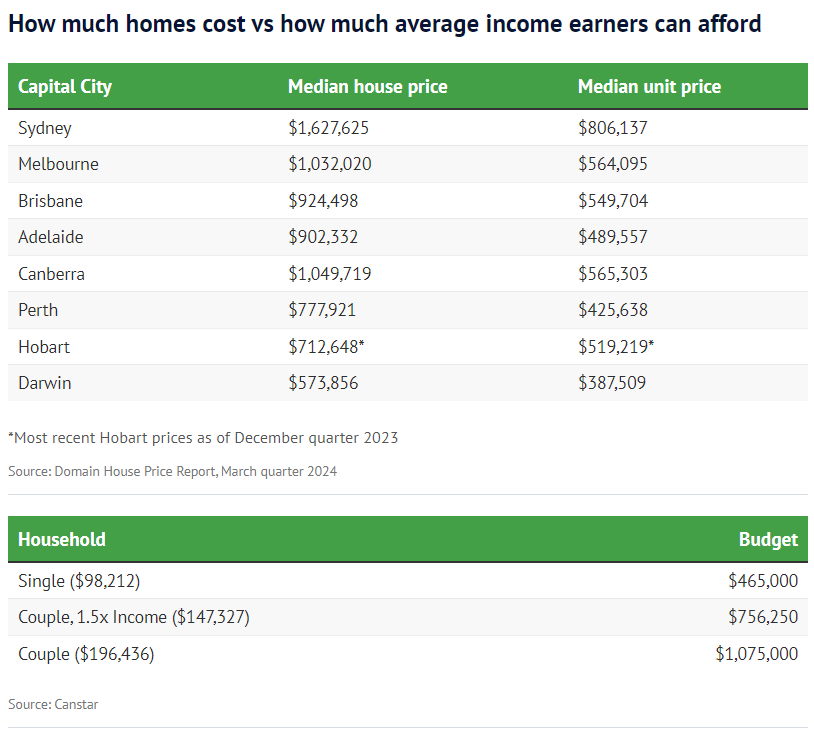
    For twin total-time earners, the funds improves to $1.08 million with a $215,000 deposit. This complete handles median family costs in most metropolitan areas, apart from Sydney, the place it’s fifty % one million {dollars} shorter.

    Solitary workers looking out to amass a unit have a funds of $465,000, which is insufficient for the median machine worth in any money metropolis, apart from Perth and Darwin.

    More than the sooner two a very long time, 13 fascination cost hikes have lowered borrowing capability, pushing as quickly as-reasonably priced suburbs out of arrive at as property charges keep greater.

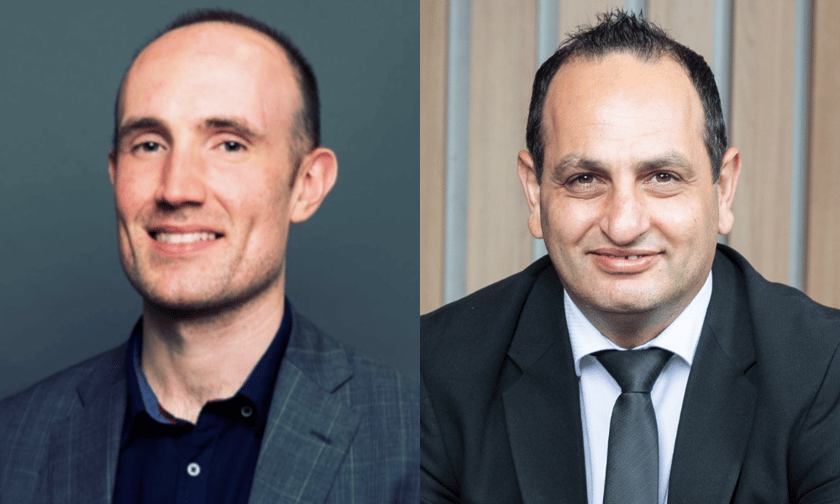
    “We accurately capitalised zero curiosity costs into property prices all via the expansion in extra of 2021,” mentioned Carlos Cacho (pictured left), principal economist at company finance and marketplaces enterprise Jarden. “Since then, we all know that borrowing electrical energy has absent again once more by roughly 30%, a tiny bit extra or considerably much less relying on the family. The one who might handle to buy when charges ended up zero can no extra time pay for to spend money on.”

  • Aussie and Pepper Income spouse on white label tech answer

    Aussie and Pepper Dollars affiliate on white label tech treatment | Australian Broker Information

    Know-how

    Aussie and Pepper Dollars affiliate on white label tech decision

    Item-matching tech delivers indicative approval in 5 minutes

    Aussie and Pepper Money partner on white label tech solution

    Technology

    By
    Ryan Johnson

    Aussie has strengthened its partnership with specialist mortgage firm Pepper Funds with the launch of ‘Aussie Activate Products Match’ – a digital decision now obtainable to all Aussie and Lendi brokers.

    Driven by Pepper Money’s distinctive technological innovation, the Pepper Item Selector (PPS), the Aussie Activate Solution Match treatment is built-in instantly into the Aussie Activate monetary mortgage journey and Lendi system.

    The dealer group defined the expertise matches a client with the best Aussie Activate dwelling financial institution mortgage resolution and gives an indicative acceptance in lower than 5 minutes, devoid of impacting the client’s credit score historical past ranking.

    Combining in depth credit score reporting and some important software data and info from the patron, the method immediately analyses a assortment of issues which incorporates credit score rating historic previous, LVR, dwelling space and work document to serve consumers with a product match and swift indicative approval.

    The power of mortgage supplier platform integrations

    Aussie’s offering permits the dealer and their purchaser to know through which they stand with only one enquiry, in opposition to the whole suite of Aussie Activate merchandise alternate options. 

    The decision demonstrates the non-financial establishment sector’s agility and elevated share of residential lending – which arrived at 16% market share in March this yr, and an approximated market place advantage of $74 billion.

    General supervisor, lending and third-occasion partnerships at Lendi Team, Shaun Lordan (pictured larger than nonetheless left) outlined: “There are a complete vary of circumstances that should should be considered when aiding our patrons. These differ from larger LVR’s to gifted deposits, non-normal revenue, self-work and so an excellent deal extra.”

    “Traditionally, these types of circumstances indicate longer processing and software events and much more do the job for our brokers in discovering the best product resolution.”

    The merchandise matching know-how now sits inside simply Lendi Group’s system, furnishing Aussie brokers with the suitable Aussie Activate monetary mortgage and indicative quantity to match their buyer’s calls for.

    “This can all take into account space in beneath 5 minutes, supporting extra shortly time to ‘sure’ and increasing the possibility of conversion,” Lordan further.

    “80% of our brokers are actually using mortgage supplier integrations on system to assist them publish loans every particular person week, and it’s empowering for our brokers to allow consumers with differing scenario so proficiently.”

    Aussie talked about its dealer neighborhood has warmly embraced the product, appreciating its effectivity, considerably the elimination of copy data entry, with the answer providing solitary technique enter.

    Brokers have favoured the user-friendly interface, considerably the instant merchandise matching attribute, which identifies the optimum family monetary mortgage choice, disposing of the guesswork of discovering probably the most appropriate Aussie Activate current significantly necessary for stylish residence financial institution mortgage eventualities.

    “We are often wanting for methods to make sure our lending merchandise are absolute best on system for each equally our brokers and shoppers and glimpse ahead to extra approaching enhancements to our Aussie Activate offering,” he claimed.

    Pepper Money’s typical supervisor mortgages and industrial lending, Barry Saoud (pictured over applicable) claimed the non-financial establishment stays centered on empowering their white label companions and dealer networks to fulfill their rising purchaser necessities.

    “With the beginning of Aussie Activate Product Match, we’re empowering the Aussie Lendi community to go on to emphasis on what points: the individuals at the moment on the rear of the financial institution mortgage.”

    “Pepper Dollars has created market place main programs and programs to assist our distribution companions aimed toward driving elevated conversion, an enhancement in dealer productiveness, and white label settlements whereas offering an excellent dealer and purchaser expertise,” he reported.

    The new Aussie Activate Item Match is built-in inside simply Lendi Group’s platform, which is now utilized by all Aussie brokers contemplating the truth that June 2023. At the second the companies’ brokers are attaining lodgement speeds as much as 4 cases sooner than the sector common.

    Associated Stories

    Keep up with the most popular data and events

    Sign up for our mailing checklist, it’s no price!

  • Virgin Income shareholders acknowledge Nationwide £2.9bn takeover provide   – Mortgage Strategy

    Virgin Funds shareholders have voted to just accept the £2.9bn takeover provide from Nationwide, which can generate the next-greatest residence finance mortgage monetary establishment within the Uk. 

    The homeowners of the excessive highway mortgage supplier handed the go along with an 89% the overwhelming majority in favour of the money give established out by the mutual.  

    The corporations function to finish the sale by the shut of the calendar yr.    

    Virgin Income chairman David Bennett says: “The board of Virgin Dollars welcomes the consequence of the shareholder conferences that took spot beforehand proper now, wherever shareholders voted strongly in favour of the suggested funds acquisition by Nationwide.   

    “We are hopeful that the transaction will full earlier than the shut of the yr, topic to the very good illnesses getting happy.”      

    The shock provide, introduced in March, will see Nationwide present the Virgin Cash shareholders 218p in cash and a 2p dividend to be paid on this monetary yr, or, if beforehand, quickly simply earlier than the completion of the takeover.    

    The give was a 38% high quality to Virgin Money’s 159.1p closing value of pence on 6 March, the day upfront of the deal was introduced.     

    Nationwide concepts to terminate the Virgin mannequin quickly after 4 a very long time and will rebrand the monetary establishment concerning the following two a number of years.    

    Nationwide customers is not going to vote on the provide.   

    Previously this thirty day interval, The Co-operative Bank claimed its £780m takeover talks with Coventry Making Modern society are at a “properly superior” stage.     

    Coventry Building Society’s proposed takeover of the Co-op Bank, declared in April, would develop a merged group with £89bn in belongings.   

  • No income restrictions?

    CFPB to Adopt Price-Based Approach for Qualified Mortgage Standards

    Source: Inman

    Written by: Marian McPherson

    The Consumer Financial Protection Bureau on Monday proposed the elimination of debt-to-income limits for certified mortgages processed by means of Fannie Mae and Freddie Mac, because the government-sponsored enterprises patch nears expiration in January 2021.

    Instead of utilizing DTI limits to foretell a borrower’s creditworthiness, the CFPB is suggesting a price-based method that considers annual and prime supply charges to bolster mortgage accessibility.

    “The GSE Patch’s expiration will facilitate a extra clear, stage taking part in subject that finally advantages shoppers by means of selling extra vigorous competitors in mortgage markets,” CFPB Director Kathleen L. Kraninger mentioned in a ready assertion. “The Bureau is proposing to interchange the Patch with a price-based method to QM loans to protect shopper entry to mortgage loans whereas additionally ensuring shoppers have the flexibility to repay them.”

    “The Bureau is dedicated to making sure a easy and orderly mortgage market all through its consideration of those points and any ensuing transition away from the GSE Patch,” Kraninger added.

    To approve a certified residential mortgage mortgage, lenders should use the Truth in Lending Act’s ability-to-repay necessities to calculate a borrower’s creditworthiness. Alongside the elimination of interest-only durations, unfavorable amortization, balloon funds, and prolonged mortgage phrases (30-plus years), TILA requires debtors to have a debt-to-income ratio of lower than 43 %.

    Under this rule, sure Fannie Mae and Freddie Mac assured loans have been given short-term certified mortgage standing, even when the DTI surpasses 43 %. According to the CFPB, short-term GSE QM loans “characterize a big and chronic share of mortgage originations” and put almost 1 million debtors in danger when the patch expires in January.

    “As famous above, the GSE Patch is scheduled to run out quickly, and absent regulatory motion the Bureau estimates that roughly 957,000 mortgage loans can be affected by the expiration of the GSE Patch,” CFBP’s announcement learn. “The Bureau estimates that, after the Patch expires, many of those loans would both not be made or can be made however at a better value.”

    To preserve mortgage availability and affordability, the CFPB is proposing two amendments to Regulation Z, which requires lenders to offer written disclosures explaining rates of interest, finance expenses, and extra mortgage phrases. It additionally requires lenders to reply debtors’ billing questions and prohibits unfair lending practices.

    The first modification would get rid of DTI limits in favor of a price-based approval, which the CFPB mentioned is a “extra holistic and versatile” methodology of figuring out a borrower’s creditworthiness.

    “The Bureau is proposing a price-based method as a result of it preliminarily concludes {that a} mortgage’s value, as measured by evaluating a mortgage’s annual share fee to the common prime supply fee for a comparable transaction, is a robust indicator and extra holistic and versatile measure of a shopper’s capacity to repay than DTI alone,” the announcement learn.

    With this methodology, lenders will nonetheless be inspired to “take note of a shopper’s income, debt, and DTI ratio or residual income and confirm the patron’s income and money owed.”

    The second modification to Regulation Z addresses the GSE Patch expiration date. Instead of permitting the Patch to run out January 2021, the CFPB is asking for it to be prolonged till the primary Regulation Z modification is permitted.

    “The Bureau is proposing to take this motion to make sure that accountable, reasonably priced credit score stays accessible to shoppers who could also be affected if the GSE Patch expires earlier than the amendments take impact as outlined within the first NPRM,” the modification learn.

    “Under the CFPB’s proposed rule change, an easy-to-understand quantity would get replaced by lenders’ judgment. The danger is that, over time, debtors and lenders would make more and more reckless selections below this proposed rule. After all, they’ve a observe report of irresponsibility from about 2005 to 2008.

    The National Association of Realtors helps CFPB’s proposals, with NAR President Vince Malta telling HousingWire the amendments would assist homebuyers obtain their homeownership targets amid a coronavirus-induced market shift.

    “America’s Realtors applaud the CFPB’s motion to offer a brief QM patch extension, and commend the bureau and Director Kraninger for performing on behalf of our nation’s shoppers and homebuyers at a time when market stability is so essential,” Malta mentioned. “Perhaps most significantly, we recognize the Bureau’s determination to get rid of a tough DTI commonplace, and we stay up for extra carefully analyzing the proposed replacements and their affect on homebuyers over the approaching months.”

    However, some consultants are involved lenders will exploit the brand new extra versatile necessities to approve high-rate loans for determined homebuyers.

    “Specifically, the proposal would do away with a rule that legally protects loans with a debt-to-income ratio of 43 % or much less,” NerdWallet Home and Mortgage Expert Holden Lewis mentioned in an emailed assertion to Inman. “It would get replaced by a rule that claims a lender is legally protected if the mortgage’s APR is lower than two share factors greater than the common APR that week for a chief mortgage.”

    “The CFPB argues that this wouldn’t make a giant change in mortgage danger or availability,” Holden added. “It must discover a strategy to forestall lenders from gaming the system with high-rate loans that simply barely match inside the tips.”

  • What will gas residence revenue? Subsequent yr will be a seller’s industry

    1st-time home shoppers will must know that that is obtainable

    By Didier Malagies

    09 May probably, 2024

    Just one utility that’s available for very first-time family prospects is in which you’ll be able to set 1% down and the mortgage supplier will provide the different 2% towards a down cost. A filled with a 3% down in your family. If you bought a 300,000 residence you’d set 3,000 down and in the event you acquired the seller to pay 3% of closing costs, you simply purchased a dwelling for $3,000. What would it not price ticket to maneuver into a additional rental? Very first, Past, and deposit? Now for the upcoming system. primarily based on the place by you keep, you may rise up to $5,250 for a down cost or closing prices. That is gigantic and with the vendor shelling out closing prices, Now you possibly can see how the alternate options of buying into a dwelling No liens, 2nd mortgages, or every part. This is a nice choice to not should do down cost help with a second lien out of your property with particular limits there aren’t any constraints with the 1% down or as much as $5,250 towards down cost or closing prices Be certain to allow me understand how I can help you tune in and grasp at https://www.ddamortgage.com/web page Didier Malagies nmls#212566 DDA House mortgage nmls#324329

  • No income /No asset on Primary/second homes

    No Doc Home Loans | No Income & No Asset Mortgages

    If you do not need to share your tax returns or doc your income, job, and property, don’t fret. You can nonetheless personal a house with a no-doc mortgage.

    What is a no-doc mortgage?

    The no doc mortgage is a sort of mortgage that enables debtors to get a mortgage with little or no documentation. This signifies that you need not doc your job, your income, or your property.

    What you do want is 2 issues:

    You have to have a down cost of 20% or extra

    You have to have a credit score rating of over 640

    Your charges will probably be greater than these on standard loans as a result of the lender has much less details about you and what they’re risking in the event that they approve your software. The rate of interest on a no doc mortgage is normally a degree or greater than on a conventional mortgage.

    Who would need a no-doc mortgage?

    If you reside within the north and are considering of transferring to Florida earlier than you get a job, this is likely to be one of the best mortgage for you!

    The no-doc mortgage is a good product people who’re in-between jobs, for the self-employed or 1099 staff with lower than 2 years employment, and people who might have a troublesome time exhibiting common income. This can be an incredible product for traders who might have a number of properties or different property and often reinvest.

    If you assume a no-doc mortgage is best for you, give us a name

    (727) 784-5555

    . We will crunch the numbers for you and decide what mortgage sort is likely to be finest for you.

    Or, join with us by finishing the shape under.

    Start Your Loan

    with DDA immediately

    Your native Mortgage Broker

    Mortgage Broker Largo

    See our Reviews

    Looking for extra particulars? Listen to our prolonged podcast!