“Scandalous assault”: Industry unites against “grossly inaccurate” columns on brokers | Australian Broker News
News
“Scandalous assault”: Industry unites against “grossly inaccurate” columns on brokers
FBAA writes letter requesting proper of reply
The mortgage trade has responded to 2 columns that referred to as Australian brokers “rich” and “brash”, criticising dealer renumeration, and implying that brokers are incentivised to encourage shoppers “to promote their present properties and to improve to new and dearer properties”.
The opinion articles, written by Australian Financial Review columnist Karen Maley, drew the ire of the trade, with brokers, aggregators, and peak trade our bodies alike posting their dissatisfaction on LinkedIn.
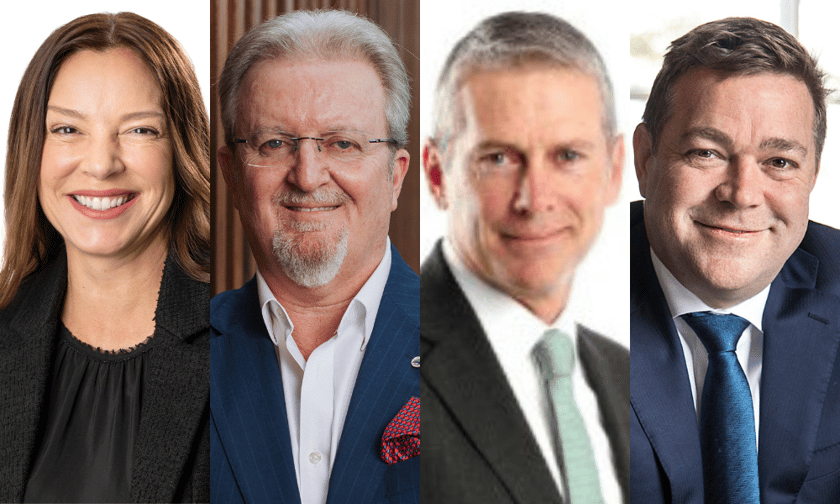
MFAA CEO Anja Pannek (pictured above far left) mentioned the “grossly inaccurate” opinion columns misrepresented the “work of brokers, how they’re remunerated and controlled”.
“Brokers carry alternative and competitors to the house lending market – so shoppers profit,” Pannek mentioned. “Consumers might be assured they’ve safety underneath regulation working with their dealer – underneath each accountable lending and the unrivalled mortgage dealer greatest curiosity obligation.”
“A dealer’s remuneration is very regulated and disclosed to their shoppers.”
FBAA managing director Peter White (pictured above centre left) agreed that the opinions expressed by a columnist have been inaccurate and displayed not solely “a misunderstanding of laws and the way in which our sector works, however a blatant bias against brokers”.
I’m upset that the AFR did not reality verify this dribble and have suggested the AFR of this,” White mentioned. “From the author’s claims round dealer common remuneration to many different false statements, the complete piece was garbage and doesn’t should be in a nationwide publication.”
What’s obtained the trade riled up?
With sturdy feedback coming from among the trade’s most recognisable figures, one could query what was printed to trigger such a vitriolic response.
In the opinion article, “The unstoppable rise of Australia’s mortgage brokers”, contemplate the opening sentences, for instance: “If you have been about to purchase a million-dollar residence, would you be ready to pay about $14,000 to a mortgage dealer for assist monitoring down the most effective deal?
“Many individuals would baulk on the prospect of forking out such a big quantity for the doubtful pleasure of an $800,000 residence mortgage.”
Tim Brown (pictured above centre proper), advisor at mortgage lender BC Invest, mentioned he wasn’t certain the place the calculations got here from.
“They quoted a fee of $14,000 for a mortgage of $800,000,” Brown mentioned.
“The common upfront fee on a mortgage that dimension is 0.65% which calculates to $5,200, even including path at $1,200 per yr, with the typical lifetime of mortgage now fortunate to be 36 months equates to $8,800. The common mortgage in Australia is $600,000 not $800,000.”
Mortgage dealer Max Harris, from Azura Financial, refuted such claims.
“This implies roughly $65 million in annual settlements, which is a major quantity,” Harris mentioned.
“To provide you with perspective, Azura Financial gained high non franchise brokerage in NSW in 2024. Out of our 12 brokers, solely six wrote greater than $65 million and we’re one of many high brokerages within the nation.
“Furthermore, the creator is implying that brokers shouldn’t have prices and that each greenback of income is revenue. I want. We are small companies identical to a restaurant or an actual property company. We have employees, lease, advertising and marketing prices and stuck over heads.
“Comparing high line income is a ridiculous argument.”
Perhaps essentially the most systematic response and evaluation of the articles was by LMG government chairperson Sam White (pictured above far proper).
In an open letter, White outlined the info to deal with “the entire inaccuracies with knowledge to help it”.
“I’m deeply enthusiastic about this. Brokers save shoppers cash by fostering asset competitors, lowering mortgage loyalty taxes, and advocating for truthful offers for his or her shoppers,” mentioned White.
“We’ll hold advocating for brokers to verify competitors, accuracy and equity prevail in our trade. I encourage you to learn the total letter and welcome your ideas on this to make sure we have now a balanced view of the mortgage broking trade.”
Advice to brokers: Don’t get labored up
Despite the adverse press, the mortgage broking trade stays extremely regarded by debtors.
While the trade is annoyed by the portrayal within the AFR articles, the overwhelming belief of Australian shoppers speaks volumes.
As Pannek mentioned, the trade has gone by way of important reform and the numbers inform the story.
“Almost 72% of shoppers select to make use of a dealer – greater than ever earlier than. And lower than 0.5% of all complaints throughout Australia’s financial institution and monetary providers sector are broker-related – which is negligible,” she mentioned.
The MFAA mentioned it could be utilizing “each avenue obtainable” to make sure the info are precisely represented.
Peter White mentioned it doesn’t deserve the eye and there was no level getting labored up about a few articles by somebody who’s “clearly misinformed”.
“My message to brokers is to focus as you at all times do on serving Australia’s debtors properly and guaranteeing you act of their greatest pursuits,” White mentioned. “The incontrovertible fact that mortgage brokers are trusted so extremely by our clients is all that issues.”
“The FBAA is frequently coping with all ranges of presidency, regulators and different stakeholders and these events all know the reality and worth our trade, as do thousands and thousands of Australian shoppers.”
Even so, Peter White despatched a letter to the Australian Financial Review (AFR) requesting a proper of reply. Here is the letter written by Peter White in full:
Letter to the AFR May 27
As the managing director of the Finance Brokers Association of Australia, I’m writing to request the chance to put in writing an opinion piece for the AFR in response to what was at worst a biased assault on our trade and at greatest inaccurate, deceptive and admittedly irresponsible articles in your publication immediately and over the weekend – “Banks gear as much as take again mortgage market from brokers” and “Inside the unstoppable rise of Australia’s mortgage brokers”, by your columnist Karen Maley.
Finance and mortgage brokers are liable for greater than 70% of Australia’s mortgages and each impartial survey taken has proven an exceptionally excessive degree of belief and satisfaction by shoppers of brokers (larger than that of direct financial institution clients).
While I perceive that this has been written underneath the title of “opinion” there may be nonetheless absolutely a duty for the AFR to verify the info and make sure that the article doesn’t mislead and defame 30,000 small enterprise individuals.
Our trade prides itself on our integrity, low criticism price and our work with authorities and regulators to at all times shield shoppers. We are legally obligated to behave within the buyer’s greatest curiosity and this text implies we don’t take that critically.
In the pursuits of balanced, moral journalism, I respectfully request a proper of reply that’s each in print and on-line and offers equal publicity.
Here are only a few of the falsehoods on this article introduced as reality:
“Customers who favour brokers are usually youthful and have a decrease revenue than those that begin their procuring with banks.” dealer clients are additionally extra more likely to be first-time residence consumers; in such instances, they work with brokers to bridge a data hole.”– This is wrong and our analysis exhibits this.
“According to mortgage broking trade sources, the typical Sydney mortgage dealer earns round $400,000 in upfront charges annually. Based on commonplace dealer fee charges, this implies that the typical Sydney dealer is pocketing $670,500 a yr when path commissions are included.” – This is just not solely false and absurd however irresponsible. The common earnings of a person finance dealer is nothing like these figures.
“The hefty value of commissions paid to mortgage brokers means residence consumers – those that undergo the banks’ department networks and people who use a dealer – are paying greater than they need to on their mortgages as a result of banks issue the commissions into the pricing of their residence loans.” – Totally unsuitable. If the banks didn’t pay fee these prices could be incurred by them internally. Clients pay no extra and this has been said by banks and governments.
“Because upfront commissions are a lot bigger than path commissions, mortgage brokers have an incentive to encourage their shoppers to promote their present properties and to improve to new and dearer properties.” – This is a scandalous assault on the integrity of mortgage brokers and fully unfaithful.
“But whereas the dealer pockets larger charges from the elevated mortgage dimension, their shoppers are saddled with bigger mortgages, and better residence mortgage repayments.” – Again, false.
“Earlier this yr, New Zealand Commerce Commission chairman John Small beneficial that the foundations round brokers’ disclosure of conflicts of curiosity needs to be tightened.” – He has since admitted that he had no data of the system and mustn’t have mentioned that.
“But the opaque nature of the upfront and path commissions paid to brokers – mixed with the truth that they’re paid by the banks reasonably than the precise debtors – imply that few debtors trouble to consider how a lot their dealer stands to earn.” – Commissions are clear and disclosed underneath regulation to all debtors (NCCP).
What do you concentrate on the AFR columns? Comment beneath.
Related Stories
Keep up with the most recent information and occasions
Join our mailing record, it’s free!

