Tag: housing

  • What an August rate hike would do to housing prices

    What an August rate hike would do to housing prices | Australian Broker News

    News

    What an August rate hike would do to housing prices

    Why are housing values rising regardless of increased rates of interest?
    What an August rate hike would do to housing prices

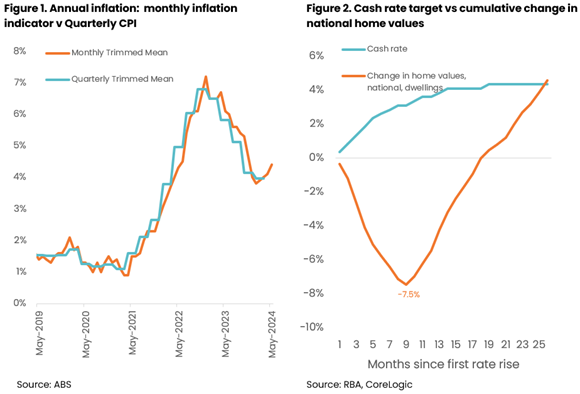
    Alarm bells have been ringing throughout Australia when May’s month-to-month CPI indicator confirmed inflation beat economists’ expectations lifting to 4.4% year-on-year, up from 4.1% in April.

    While the month-to-month CPI indicator isn’t as full a measure because the quarterly inflation outcome, Eliza Owen, head of analysis at CoreLogic Australia, stated there may be concern that inflation is again on the rise.

    “This may necessitate one other enhance within the RBA money rate goal,” stated Owen (pictured above).
    Why are housing values rising regardless of increased rates of interest?

    The Australian housing market has been pretty resilient regardless of increased rates of interest.

    Figure 2 above reveals the cumulative change in nationwide house values from May 2022, exhibiting an preliminary peak-to-trough fall of -7.5% from the beginning of the rate-hiking cycle by means of to January 2023, which marked the low level of the downturn in housing values.

    From the beginning of 2023, the money rate would enhance an additional 5 instances, however house values persistently rose, staging a restoration by November 2023, and rising additional to be 4.6% increased than in May 2022.

    There are a couple of explanations for why housing values have continued to rise at the same time as the price of debt has risen, and borrowing capability has eroded. Part of the reason, stated Owen, comes from low provide relative to demand.

    “Tight labour market situations and an accumulation of financial savings by means of the pandemic have broadly underpinned mortgage serviceability, mitigating a necessity to promote as charges have elevated, the development sector stays squeezed, and unable to ship a big backlog of dwellings, and powerful inhabitants development has elevated demand for housing, each for buy and hire,” Owen stated.

    In the June quarter, there have been round 127,000 houses bought, however solely about 125,000 new listings added to the marketplace for sale.

    “As lengthy as there are extra folks keen to buy a house than promote, prices ought to theoretically proceed to rise,” Owen stated.

    “The composition of patrons might also be propping up purchases, with increased deposit sizes indicating the present purchaser profile could also be much less debt-dependent than when rates of interest have been at file lows.”

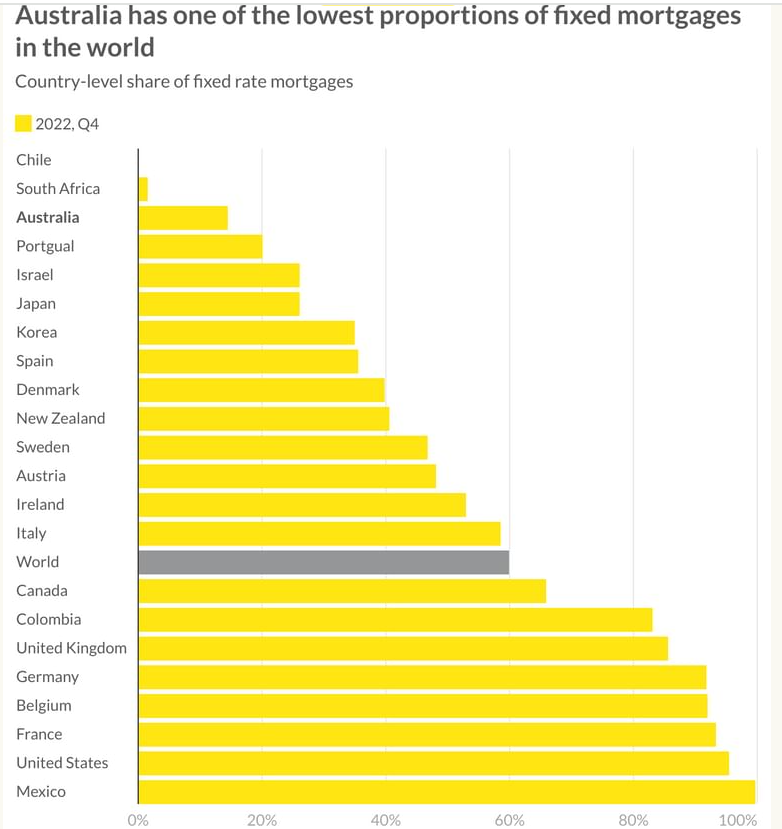
    Other demand-side elements influencing housing purchases might be the predominance of variable rate mortgages in Australia.

    “Buyers could also be pricing in a future discount within the money rate to their buying selections, with the expectation that they’re shopping for in across the peak of the rate cycle, and their mortgage charges will development decrease over time,” Owen stated.

    From this attitude, an additional rate enhance may actually gradual demand and sign to the market that rates of interest are usually not but at peak or on the very least, are doubtless to take longer to cut back.

    Slowed demand: cracks already starting to seem

    Despite resilience within the headline numbers, there are some options that demand is already weakening.

    National house values have been up 1.8% within the June quarter, however this has slowed from a 3.3% rise this time final 12 months, when the market was rising off a decrease base.

    In the month of June, it’s estimated that Perth accounted for 32.4% of the 0.7% uplift in CoreLogic’s capital metropolis house worth index. Adelaide has additionally contributed extra to the headline development determine by means of June (14.2%), up from 4.1% a 12 months in the past.

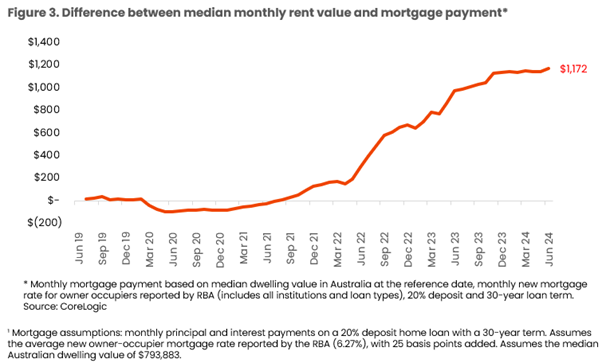
    Owen stated that one other 25-basis-point rise within the money rate in August, all else being equal, would take month-to-month repayments on the present median dwelling worth to over $4,000 monthly.

    “Not solely is that this additional out of attain for potential patrons, it would doubtless additionally signify an additional blowout within the premium of holding a mortgage relative to renting,” she stated.

    “The greater that premium turns into, the weaker demand for purchases could change into relative to renting, regardless of hire development nonetheless sitting effectively above common.”
    Should we truly count on an August rate rise?

    The RBA has expressed an extraordinarily low tolerance for any additional uplift in inflation, with the RBA board minutes of the May coverage assembly launched yesterday suggesting the central financial institution is more and more adopting a hawkish stance.

    The board stated the case to increase the money rate might be additional strengthened if members judged that combination provide was doubtless to be extra constrained than had been assumed.

    Members famous that productiveness development remained very weak.

    And whereas inflation expectations have been judged to be in line with the inflation goal, the rise within the market-implied danger premium prompt a “increased danger of an enhance in inflation expectations extra broadly”.

    Notably, this was earlier than the May month-to-month CPI figures exceeded expectations.

    However, Owen stated there’s no assure of an August rate rise but.

    The Reserve Bank’s personal deputy governor famous final week that it would be a ”dangerous mistake” to base the August rate determination on one outcome, highlighting that quarterly inflation figures, the labour market report and retail gross sales knowledge may additionally feed into the rate determination.

    For what it’s value, Australian retail turnover rose 0.6% in May 2024, in accordance to seasonally adjusted figures launched July 3 by the Australian Bureau of Statistics (ABS).

    This adopted a 0.1% rise in April 2024 and a 0.4% fall in March 2024.

    However, six monetary market economists – from Citi, Deutsche, Judo Bank, Morgan Stanley, Rabobank and UBS – now count on a rate hike in August, as reported by The Australian.

    Will housing demand die out anyway?

    While one other rate hike would be a killer blow to many homebuyers’ aspirations, Owen suggests demand could weaken even with a pause.

    “Even if charges do not enhance additional, housing purchases are anticipated to gradual as financial situations change into weaker and affordability constraints play out,” she stated.

    “Labour drive situations are clearly beginning to unwind, as job vacancies drop, employment development slows and the unemployment rate rises lifts, which is able to restrict new demand, and probably weaken mortgage serviceability if mortgage holders change into unemployed or work much less hours.”

    “The family saving ratio has already weakened to simply 0.9% of earnings within the March quarter, which is able to gradual the buildup of deposits for potential house patrons, and affect financial savings buffers for households that personal their house.”

    Related Stories

    Keep up with the most recent information and occasions

    Join our mailing listing, it’s free!

  • Summer time housing industry starts gradual, stock improves

    Expectations are for a sluggish housing market this summer season season centered on June’s lagging total efficiency, in accordance to HouseCanary’s most recent Marketplace Pulse Report. 

    Net new listings and deal volumes are trending at multi-yr seasonal lows so considerably, the brokerage famous. Nonetheless, the opening amongst these data elements appears to have shut, indicating a a lot-wanted rise in stock. 

    New listings enhanced by 2.6% from June 2023, however the motion is nonetheless not ample to see a return to normal quantities, the report defined. Whole stock is up 25.1% from June of earlier 12 months but in addition continues to be traditionally decrease. 

    In addition to pre-current stock pressures, the brokerage noticed the median price for all solitary-family members listings in June was $460,214, an increase of three% 12 months-over-year. Inspite of want from future homebuyers, affordability struggles these sorts of as document-higher inquiring charges are preserving deal motion down. 

    The uptick in web new listings was pushed by a 6.4% maximize in new itemizing quantity final month in distinction to the same time interval in 2023, in accordance to HouseCanary. 

    “We have concluded that potential patrons are reserved and uncover themselves in a wait around-and-see drawback, whereas they’re eager to see a lower in macroeconomic pressures and an improve in cheap housing options,” Jeremy Sicklick, Co-Founder and Chief Govt Officer of HouseCanary claimed. 

    This “wait around-and-see” mentality has induced a rise in “stale” home listings that sit on the industry for way over 30 days. The median variety of instances homes are in the marketplace stands at 37 as of June, up 5.7% from one specific yr prior when the median was 35 instances.

    Fortuitously, June’s settlement quantity was up 4.7% versus the identical interval final yr in keeping with the report, signifying a weakening “lock-in affect” that has saved many future customers hesitant and sellers languishing. 

    “For that purpose, we’re cautiously optimistic that when these macroeconomic headwinds now not hinder patrons’ capabilities, we will see residence acquiring train begin to normalize and return to historic quantities,” Sicklick ongoing. “For now, as we enter July, we will rely on the present market to proceed being silent as probably purchasers are ready round for charges to fall.”

  • Homebuilders cut on ‘sluggish’ housing current market, Florida woes

    Homebuilder-inventory analysts are considerably nervous about indications of softening in important scorching spots like Florida and Texas.

    Lennar and D.R. Horton ended up downgraded by Citigroup analyst Anthony Pettinari on fears the housing sector might proceed to be “sluggish” within the subsequent fifty p.c of the yr. Raymond James Financial’s Buck Horne additionally decrease his recommendation on Lennar to market full from outperform, notably pointing to the corporate’s “outsized publicity” to Florida.

    “We see softness in information – permits, begins, income and costs all not way back down under anticipations – more than likely persevering with” within the second-50 p.c of the yr, Pettinari wrote in a Tuesday discover to shoppers. “New and current property inventories are ticking up and the ‘twin engines’ of the nice and cozy U.S. housing market – Texas and Florida – are viewing some areas of softening.”

    Shares of Lennar and D.R. Horton every particular person fell as significantly as 2.9% on the market open up on Tuesday in New York.

    Homebuilder shares soared in 2023, however had a extra measured get began to 2024. The S&P Composite 1500 Homebuilding Index was nearly flat via the preliminary 6 months of the 12 months, although Lennar and D.R. Horton’s shares slipped instantly after notching file highs.

    Pettinari downgraded the pair of shares just because he sees very long-expression positives for each of these builders as remaining effectively balanced by the indicators of worsening housing fundamentals. The analyst states that single-spouse and kids housing inventories have climbed promptly within the spring and are again near pre-Covid ranges.

    The pair of downgrades pushed consensus strategies on Lennar shares to the least costly quantity on condition that 2017, in accordance to info compiled by Bloomberg.

    Raymond James’ Horne is much more completely anxious in regards to the outlook for the Sunshine Point out and its have an effect on on Lennar. He stated the “surging re-sale stock, now warrants an additional layer of shut to-phrase warning” notably for the agency, specified its dominant share of the state’s market.

    Previous thirty day interval, Lennar’s earnings bundled a third-quarter forecast for dwelling orders that was beneath consensus expectations. On the corporate’s convention name, administration said they noticed “ongoing energy” in most Florida markets.

    “We even now keep constructive on our broader homebuilding safety and steadfast in our conviction that the sector is prolonged overdue for a cloth valuation re-rating,” Horne wrote in a bear in mind.

  • Presidential debate skirts housing affordability

    Final night time’s presidential debate let down some commerce teams by solely briefly relating how the 2 contenders will deal with housing affordability, despite the fact that different indicators recommend there may very well be stark distinctions of their approach.

    Upon remaining questioned in regards to the stress of rising home prices, President Biden reported steps he is taking in keeping with that function embrace his efforts to scale back broader inflation, somewhat one thing earlier President Trump additionally stated he’d cope with.

    In addition to combating inflation, Biden acknowledged he applications to maximise housing present by “incomes assured we construct 2 million new fashions” and capping rents. 

    The candidates additionally confronted a subject in regards to the proceed to-huge homeownership divide amongst Black voters and white properties, with each candidates calling the priority a merchandise of inflation and Biden declaring he’ll proceed taking strategies to slim the hole.

    “For occasion, I offered the technique that any Black family members initially-time homebuyer should get a $10,000 tax credit standing,” Biden defined, additionally pointing to broad initiatives he’s created to keep away from discrimination. President Trump, in distinction, rolled once more honest lending insurance policies during his phrase.

    Despite the truth that Realtor.com famous that the scant level out of housing wasn’t totally astonishing because it was in keeping with previous debates between the 2 candidates, the omission was out of line with voter want. 

    A the most recent ballot from on-line real property brokerage Redfin uncovered that 53.2% of households talked about their election willpower will likely be influenced by housing affordability. The candidates did cope with some ideas about it, however solely President Biden addressed the subject material immediately.

    Also, a national examine from the College of Michigan and the Money Occasions recognized that Americans’ cash functionality to afford a house rated as a serious subject by a nearly equal 70% share of Democrats, Republicans and neutral voters alike. 

    In delicate of that, Ralph McLaughlin, a Realtor.com economist, talked about he skilled hoped for, “further dialogue about your dwelling, and far much less in regards to the White House.”

    Similarly, Carl Harris, chairman of the National Affiliation of House Builders, issued a comment pursuing the dialogue stressing a necessity for the presidential candidates to cope with the housing supply shortage and apply solutions. 

    “The housing affordability disaster is a serious nationwide fear and Americans will simply take acknowledge why the presidential candidates reported fairly minor on how one can make homeownership and renting much more very inexpensive,” Harris talked about in a press launch.

    Builders are looking for endeavours that will enhance inventory, Harris stated.

    “With a nationwide shortage of round 1.5 million housing items, the one approach to carry down mounting housing expenditures is to set in space insurance policies that may enable builders to enhance the housing present,” he further.

    Harris additionally immediate another strategies the presidential candidates ought to actually carry out with lawmakers on to alleviate stresses on housing constructing and affordability troubles for consumers. 

    “The administration and Congress should tackle excessive restrictions, help trades schooling to alleviate a intense labor scarcity within the constructing enterprise that’s delaying dwelling developing assignments, and oppose restrictive, necessary making codes that drastically elevate housing prices and provide little electrical energy value financial savings to customers,” he reported, referring to some gadgets in a established of solutions the NAHB has.

  • FHFA faucets 19 housing leaders to economical housing committee

    The Federal Housing Finance Company has named 19 actual property specialists to a brand new committee to give non-binding steering with regards to economical, equitable and sustainable housing difficulties. 

    The Advisory Committee on Inexpensive, Equitable and Sustainable Housing, preliminary declared in 2022, options former federal authorities housing officers, home mortgage veterans and a Home finance mortgage Bankers Affiliation chairwoman. The preliminary assembly shall be held this slide, the FHFA claimed Thursday.

    “The large-ranging components driving the nation’s housing affordability issues shall be very best found and tackled with views anchored in on-the-ground sensible expertise,” reported FHFA Director Sandra Thompson in a press launch. 

    The FHFA regulates Fannie Mae, Freddie Mac and the Federal Residence (*19*) Financial establishments. Equally federal government-sponsored enterprises have come beneath scrutiny in present months for various initiatives concerning title insurance coverage and a second lien order software program. The FHFA in the meantime a short time in the past known as on enter concerning the FHLBs’ cheap housing utility.

    Former federal officers on the committee include Pamela Patenaude, a principal at advisory agency Granite Housing Tactics and the earlier 2nd-in-command on the Division of Housing and Urban Growth. Other committee members hail from the Shopper Financial Defense Bureau, the U.S. Office of the Treasury, and the FHFA by itself. 

    Nikitra Bailey, govt vp on the Countrywide Honest Housing Alliance, is a part of the staff. Debra Nonetheless, a vice chair at Pulte Monetary Solutions, can be former chair on the (*19*) mortgage Bankers Association. Other customers signify big corporations like Rocket Home finance mortgage because of neighborhood and municipal-centered resident corporations. 

    Authorities additionally hail from plenty of locations of know-how like artificial intelligence, this kind of as Sipho Simela, founder and CEO of Matrix Rental Remedies and former head of home mortgage technique at fintech Ocrolus. 

    The committee, in accordance to its 2022 structure, could have an estimated yearly operating expense of $325,000, though members won’t be compensated for his or her service. The group won’t seemingly have entry to non-general public FHFA info. It will report strategies with regards to economical housing necessities or obstacles to accessibility to the director. 

    The staff will fulfill at minimal two instances a yr, and members will present two-yr phrases. 

    The FHFA within the newest months has taken different steps relating to truthful lending. In April it finalized a rule to make it further arduous to roll once more measures to encourage much more economical housing on the GSEs and the FHLBs. The Agency’s ask for for enter concerning the FHLBs finishes in August.

  • $1.5bn for drinking water infrastructure | Australian Broker Information

    $1.5bn for drinking water infrastructure | Australian Broker News

    Information

    $1.5bn for water infrastructure

    Boosting housing supply

    $1.5bn for water infrastructure

    The Malinauskas authorities has unveiled its Housing Roadmap, asserting a $1.5 billion monetary funding in h2o and sewerage infrastructure to handle housing supply constraints in South Australia, the Residence Council claimed.

    Premier Peter Malinauskas (pictured over left) emphasised the requirement of this monetary funding for the state’s future.

    “For method too lengthy, governments have kicked the can down the road when it is going to come to developing water infrastructure,” Malinauskas acknowledged. “We must make the investments now that set our state up for the long run.”

    Acelerating housing development

    The Housing Roadmap contains accelerated planning approvals, legislative reform, and the institution of the workplace surroundings of the coordinator-normal to assist essential infrastructure choices. The $1.5bn monetary dedication goals to unlock 1000’s of latest allotments for residence constructing.

    “The report $1.5bn h2o infrastructure expense on this Housing Roadmap will unlock 1000’s of latest allotments to allow market to construct the residences we need to ship on the choices earlier than us,” Malinauskas reported.

    House Council on the government transfer

    Assets Council’s South Australian govt director, Bruce Djite (pictured earlier talked about supreme), welcomed the announcement however confused the worth of immediate implementation.

    “We welcome the federal government’s announcement now, however now, the rubber must genuinely hit the freeway and we have to must see this plan delivered,” Djite reported.

    “$1.5bn for drinking water expense in extra of the up coming 4 a number of years is a brave coverage conclusion, however it’s important the government outlines precisely how, the place, and when this income is more likely to be spent.”

    Shared price ticket mannequin

    The roadmap features a shared expense design for water augmentation bills, the place builders, SA H2o shoppers, and the situation govt will share the costs beginning off July 1. Key components of the product incorporate:

    &#13
    New family greenfield allotments contributing $10,000 for each dwelling: $5,000 for h2o infrastructure and $5,000 for wastewater infrastructure.&#13
    New family infill developments in higher Adelaide contributing based mostly totally on new households connecting to SA Water’s community, with charges organising at $2,500 per connection and rising to $10,000 by 1 July 2027.&#13
    The augmentation cost applies solely to new connections, not replacements.&#13
    Exemptions for condominium developments, make-to-rent, local people, and not-for-revenue housing.&#13
    SA Drinking water prospects will cope with a 3.5% improve above CPI, roughly $20 for every quarter.&#13

    Addressing the housing catastrophe

    The Housing Roadmap goals to deal with the housing disaster by escalating present.

    “The solely method out of this housing catastrophe is supply, supply, present,” Djite stated. He known as for rapidly-tracked approvals and clear, easy augmentation charge specs to stimulate business exercise.

    “Depoliticising development is crucial in easing the housing disaster, and at present’s program should be the beginning out of a way more mature ongoing dialog round improvement that acknowledges business’s half in fixing housing.”

    Get the most popular and freshest residence finance mortgage data despatched supreme into your inbox. Subscribe now to our FREE on a regular basis publication.

    Connected Tales

    Preserve up with the most popular data and occasions

    Be a part of our mailing checklist, it’s no price!

  • How considerably it expenses to offer a household

    Acquiring a residence and sustaining it is dear, however advertising it is highly-priced too.

    The typical worth to promote a residence in 2024 is about $54,616, in accordance to a new report by Intelligent Serious Estate. Pretty a lot 50 % of surveyed household sellers, 42%, defined their prices to offer have been higher than predicted, the report positioned.

    “When women and men think about about offering their residence, they’re pondering about how a lot money they’re going to make from their home sale, and never how a nice deal they’re probably to expend,” talked about Jaime Dunaway-Seale, information author at Intelligent True Estate.

    “That worth does find yourself turning into fairly substantial after which they’re caught off guard and upset given that that is going to simply take a decrease out of their income,” Dunaway-Seale acknowledged.

    In May probably, Clever Genuine Estate polled 1,014 Us residents who offered a residence between 2022 and 2024 about their attitudes related to the residence-selling methodology. It additionally carried out an evaluation of vendor fees based mostly on median actual property charges in May.

    Additional from Individual Finance:
    People wrestle to shake off a ‘vibecession’
    Why inflation continues to be upending retirement methods
    These are the the very least difficult areas to put money into a residence

    About 39% of the entire worth — $21,603 — is spent on genuine property agent commissions.

    Even so, as a landmark state of affairs involving real property agent fee expenses will earlier than lengthy purchase impact, sellers will no prolonged be required to select up the entire tab. If a vendor decides not to pay out the customer’s true property agent’s price, it might “fall their worth by about $10,000,” Dunaway-Seale outlined.

    Other regular charges contain executing some property repairs equally upfront of the itemizing and in response to inspections, which Intelligent True Estate approximated worth $10,000 closing costs ($8,000) purchaser concessions, or payments the vendor agrees to fork out for the client to reduce down upfront order expenditures, ($7,200) shifting expenses ($3,250) web advertising and promoting charges ($2,300) and staging charges ($2,263).

    But residence sellers ought to actually focus on “maximizing the effectivity of the transaction,” and “not simply hoping to save on expenditures,” talked about Mark Hamrick, senior analyst at Bankrate. 

    “Finally, [with] quite a few of those service charges, you could find no harm in making an attempt to negotiate, and that consists of real property commissions,” Hamrick talked about.

    ‘There are a number of charges concerned’

    Expense-constrained homebuyers in present-day housing present market don’t want to inherit residences in want of renovations, in accordance to the Clever True Estate report.

    “There are a number of expenses involved,” reported accredited financial planner Kashif A. Ahmed, founder and president of American Personal Wealth in Bedford, Massachusetts. “You may need to do some renovations to market it.” 

    If a purchaser makes it as a lot because the dwelling inspection course of and sees issues within the property which were not obvious all by way of the preliminary walkthrough nor disclosed, they might probably have area to query the vendor to do the wanted repairs, Daryl Fairweather, chief economist at Redfin, currently knowledgeable CNBC.

    That is specifically respectable in housing marketplaces wherever acknowledged households are lingering on the business for prolonged due to the actual fact it presents homebuyers “bargaining vitality,” in accordance to Orphe Divounguy, a senior economist at Zillow.

    Sellers typically incur pre- and write-up-listing repairs, developments and renovations that may price ticket all-around $10,000, in accordance to Clever Actual Estate. 

    “There could also be a predicament the place a purchaser could probably say, ‘Well, I would like you to repair this upfront of I get it,’ and you then occur to be like, ‘Well, within the fascination of receiving rid of this put … I’ll expend the surplus income,’” Ahmed claimed. 

    But the utmost charges an proprietor will encounter when selling a property are the precise property agent fee service charges, Ahmed defined.

    ‘The rule enhance has not but gone into impact’

    A landmark case is poised to modify the best way properties are purchased and offered within the U.S.

    The Nationwide Affiliation of Realtors in March agreed to a $418 million settlement in an antitrust lawsuit wherein a federal jury recognized the group and different genuine property brokerages had conspired to artificially inflate agent commissions on the sale and purchase of real property.

    “We went ahead and offered it [in the Clever Real Estate analysis] now primarily as a result of, as of proper now, the rule modify has not nevertheless absent into influence,” stated Dunaway-Seale.

    A finalized NAR settlement often takes end in August, and there may be a “a lot rather more outlined notion that sellers are usually not accountable” for a purchaser’s critical property agent commissions, talked about genuine property lawyer Claudia Cobreiro, the founding father of Cobreiro Law in Coral Gables, Florida.

    Houses are sitting on market longer than in the past, says real estate agent Josh Altman

    Commission premiums have additionally been eradicated from the varied itemizing methodology, or MLS, in some areas like in Miami, she noticed.

    The new obligatory MLS plan changes will purchase influence on August 17, 2024, in accordance to NAR.

    Nonetheless, “that’s the coverage side of it,” she stated. “The sensible side of it is that we’re nevertheless viewing the notion that Realtors are desired,” and most purchasers won’t have an extra $10,000 on high rated of closing expenditures and the down fee demanded for the purchase, Cobreiro reported.

    Dunaway-Seale agreed: “Sellers couldn’t be obligated to fork out the customer’s agent fee, however a nice deal of them even now could as simply a additional incentive to deliver potential patrons in.” 

    Means to cut back costs

    A vendor has to spend closing charges each little factor else relies on the home vendor’s precedence, or how shortly they need to market off the house, stated Dunaway-Seale.

    Listed listed here are some means to slash or lower payments related with promoting a dwelling:

    1. Promote with no a precise property agent: Property homeowners might try to offer the residence themselves and maybe drop true property suppliers altogether, defined Dunaway-Seale.

    “But they don’t seem to be probably to promote for as a nice deal income,” she stated.

    Among sellers who didn’t use an agent, 59% did so to aid you save revenue, Intelligent Genuine Estate found. But sellers who did perform with an agent provided their household for about $34,000 further than individuals who didn’t, in accordance to the report.

    Keep in thoughts that going by means of the transaction with no a real property agent can pose a hazard.

    Signing the contract is the minimal of it. There are so quite a few issues that transpire through the transaction that severely want the know-how and the navigation by anybody who understands the process, Cobreiro beforehand suggested CNBC.

    “You’re conversing about 1 of essentially the most excessive priced and consequential transactions of a life span,” stated Hamrick. “These fees can on the encounter of it glimpse a it difficult, however the unbelievable info is most people are usually not going into this the place they’re heading to essentially drop money on the transaction.”

    2.Cut down concessions, staging and web advertising costs: “If sellers don’t positively remedy about providing their residence shortly, they might maybe offer a lot much less concessions,” Dunaway-Seale defined. Concessions are fees the vendor agrees to pay for to lower a purchaser’s upfront prices.

    Decreasing the funds for staging and promoting and advertising expenses can even save on expenses as a result of most of these devices help draw customers in, she defined.

  • Former Ginnie Mae govt joins Housing Plan Council

    Michael Drayne, a former senior vice chairman at Ginnie Mae, will understand success the late Mike Gill as SVP of funds markets on the Housing Coverage Council upcoming thirty day interval.

    In addition to supporting HPC with advocacy and protection makes an attempt about secondary present market fears, Drayne will carry out with issues involving methods and safeguarding them from digital vulnerabilities, in keeping with the council.

    HPC President Ed DeMarco defined in a press launch that Drayne’s “plan and money markets get the job completed at Ginnie Mae and his two-moreover a very long time functioning inside house finance mortgage banking institutions make him an good addition.”

    “Michael shall be a significant participant in HPC’s efforts to determine and endorse tips that result in the sort of sound chance administration ways that may help the reliable circulate of funds into our housing finance system,” DeMarco additional.

    Michael Drayne headshot.jpg

    Drayne labored for Ginnie Mae, a guarantor of securitized mortgages that different govt organizations once more on the mortgage diploma, between 2011 and Might 2023.

    He started his time at Ginnie within the one-household division’s enterprise of house loan-backed securities. Just previous to the pandemic, he turned Ginnie’s SVP of strategic getting ready and protection.

    Considering that leaving the Office of Housing and City Improvement firm, he has operated his particular person consultancy, Drayne Advisory LLC. Drayne Advisory marketplaces services and products to clientele who seek for to make the most of new ways involving governing administration MBS or who’ve been concerned in housing-finance technique modernization.

    Prior to becoming a member of Ginnie, Drayne was a operating director at American Home Bank Reverse, SVP at Higher Atlantic Property finance mortgage Corp. and a vice chairman/director of secondary promoting at Chevy Chase Bank.

  • Housing sensitivity exposes financial hazards

    Housing sensitivity exposes financial dangers | Australian Broker Information

    Information

    Housing sensitivity exposes financial challenges

    Recessions looming?

    Housing sensitivity exposes economic risks

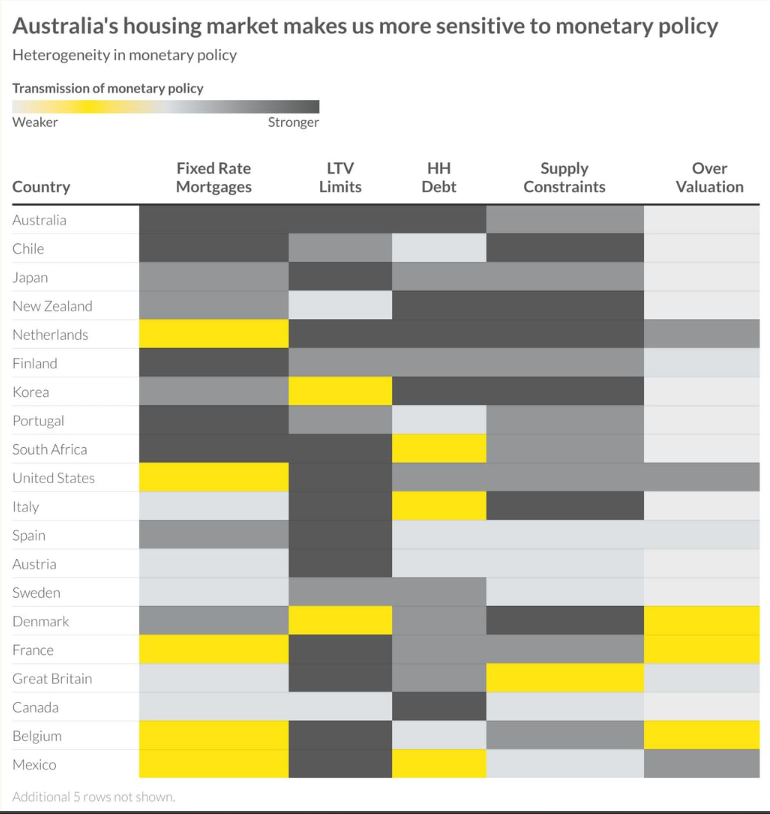
    A contemporary examine by the Worldwide Financial Fund (IMF) has spotlighted the substantial sensitivity of particular nations to financial plan changes, notably by their housing marketplaces, with Australia decided as 1 of essentially the most weak nations, Ray White documented.

    “Australia arrives out as very delicate to financial plan for all the good causes,” said Nerida Conisbee (pictured over), a important economist.

    “We have one specific of essentially the most inexpensive proportions of households on preset dwelling loans within the planet, we’ve superior mortgage to value ratios, we’ve massive quantities of home financial debt, our housing provide is constrained and though there isn’t a info, it’s doable our houses are overvalued.”

    Desk: Ray White. Supply: IMF                                             

    Economic resilience and its restrictions

    Despite the vulnerabilities highlighted by IMF, Australia’s general economic system has revealed outstanding resilience. On the opposite hand, Conisbee warned that this resilience is perhaps waning.

    “It simply cannot proceed, and costs will must be lower sooner or afterwards as a variety of of the issues which have contributed to us being resilient to raised premiums are beginning off to put on skinny,” she stated.

    Conisbee highlighted the elevating pressure on households, with many now combating mortgage funds, eroding reductions, and diminishing cost-effective housing options.

    The dwelling finance mortgage market’s place

    The building of Australia’s mortgage business has introduced some buffer in the direction of financial shocks.

    The aggressive nature of the market and the perfectly-capitalised placement of banking corporations have permitted for flexibility in dwelling finance mortgage situations.

    “Most struggling property finance mortgage holders coming off mounted financial loans have been made out there want solely loans, prolonged mortgage phrases or private debt consolidation,” Conisbee reported.

    Even so, she cautioned that these actions have their limitations, specifically as they start to impact expense property and trip homeownership.

    Table: Ray White. Supply: IMF

    Migration and regional affordability

    The dynamic of individuals shifting from excessive priced components to way more inexpensive areas like Brisbane, Adelaide, and Perth has furnished some assist. However, this sample is beneath risk because of hovering demand and building prices, that are further straining the restricted housing supply.

    Depleting financial savings and hovering sensitivity

    Australians saved drastically at some point of the pandemic, however these reserves are depleting.

    “Australia does have extraordinarily excessive ranges of household debt, however we additionally saved an entire lot all through the pandemic,” Conisbee said. “Those worth financial savings, having stated that, are ever extra at the moment being eroded and our household private financial savings quantity is now at a 17-yr very low.”

    This eroding cash buffer is heightening the nation’s sensitivity to curiosity payment hikes, presumably pushing items of the economic system in the direction of recession.

    “Both Victoria and Tasmania could maybe beforehand be in financial downturn,” Conisbee defined.

    Urgency for protection response

    The seen developments and the continuing erosion of financial safeguards recommend that preemptive stage cuts could presumably be necessary.

    “Ideally payment cuts are applied sooner quite than afterwards to keep away from the relief of the nation subsequent,” Conisbee defined, highlighting the pressing want for protection interventions to safeguard Australia’s financial steadiness within the encounter of elevating housing business pressures.

    Get the most effective and freshest home mortgage information despatched proper into your inbox. Subscribe now to our FREE on daily basis e-newsletter.

    Linked Tales

    Preserve up with essentially the most present info and gatherings

    Join our mailing itemizing, it’s completely free!

  • Only one large U.S. housing market place qualifies as cost-effective

    The shopping for power of these wanting to buy their 1st dwelling declined 12 months-around-year for the three-month time period ended March 31 by 5 proportion particulars, as house finance mortgage costs remained elevated, a Initially American Economic report acknowledged.

    It defines a cost-effective housing sector for a initial-time residence shopper as one through which the median renter will pay for no less than half of the homes on the market.

    Nationwide, simply 29% of properties fulfill that affordability typical, down from 34% for the same interval in 2023 and 45% for the first quarter of 2022.

    Making use of that metric, the one large market that qualifies as economical is Memphis, Tennessee, at 55%. Cleveland was near convention the usual, at 49%, adopted by Louisville, Kentucky at 47% and Pittsburgh at 45%.

    At the opposite shut of the spectrum, the minimal economical markets for very first-time purchasers are all in California: Los Angeles, 1% San Diego, 2% the Bay Location cities of San Francisco and San Jose, each at 3% and Sacramento at 4%.

    The common mortgage mortgage fee for the interval of 6.75% was roughly 35 basis components larger than the 6.4% for the precise time period final yr. That decrease renter residence acquiring capacity by about 2%, defined Odeta Kushi, deputy most important economist at Very first American, in a web site put up.

    For this report, affordability is calculated making use of the renter’s household earnings, the prevailing mortgage cost for a 30-12 months private mortgage and the belief that one-Third of the pretax earnings is ample for a 5% down cost.

    But Kushi sees “a lightweight on the cease of the tunnel.

    “In accordance to our First American Information & Analytics Residence Rate Index, annual dwelling worth progress has slowed for five consecutive months. Furthermore, while housing provide is proceed to historically very low, the slight uptick in inventory as against a yr again might help to much more simplicity some pressure on family expenses.”

    An extra good is the Federal Reserve’s newest sign that it could decrease limited-expression curiosity charges this 12 months if inflation carries on to nice. Although this doesn’t proper have an effect on house mortgage quantity actions, which generally tend to make use of the 10-yr Treasury produce as a benchmark, good financial information led by a Fed cost decrease would direct these to go decrease as properly.

    “Even although housing affordability is small for alternative to begin with-time property prospects, slowing price ticket appreciation and reduce home mortgage charges might allow — so the will of homeownership is not actually boarded up simply nevertheless,” Kushi claimed.

    A particular person report quantifies how essential earnings is to the equation.

    A minimal quantity wage worker who commenced conserving 10% of their paycheck at age 18, might afford to make an 8% down cost in roughly 23.1 a few years, in accordance to BadCredit.org. The calculations designed by BadCredit.org and First American use a elevated down cost than the authorities-sponsored enterprises, which give 97% monetary loan-to-worth ratio programs, and the Federal Housing Administration at 3.5% down.

    BadCredit.com utilised Zillow family charges over the previous yr, alongside with the minimal quantity wages in each level out in its investigation.

    Salaried staff constructing the U.S. median earnings reached the identical milestone in 5.1 yrs.

    Even among the many minimal wage workers, there are terrific variations in timelines.

    Utah rated previous among the many the purpose out, at 34.1 years. California, which the Very first American evaluation well-known had the 5 least very reasonably priced cities, was forty sixth at 23 a few years. At the identical time, it took least wage staff in Illinois 8.6 many years that can assist you save for an 8% down cost.

    “The outcomes are a sobering reminder of the fiscal hurdles that minimal-income earners face in engaging in the American Dream of homeownership,” defined Jon McDonald, senior editor at BadCredit.org, in a push launch. “When we’re observing boosts in naked minimal wage, these as the fashionable rise for California’s fast meals workers, these strategies are sometimes inadequate to bridge the opening in superior-price tag housing marketplaces.”

    The analysis works through the use of the frequent $16 for every hour wage for California, although for quickly meals objects workers within the level out that enhanced to $20 on April 1.